
 Sweden Wind Energy Market | 2026-2036
Sweden Wind Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Sweden Wind Energy Market Analytics
Buyer concentration among Swedish utilities is recalibrating procurement dynamics across the wind energy value chain. Vattenfall AB leverages its integrated utility-developer model to control project pipelines from origination to grid delivery. OX2 AB specializes in development services for institutional investors seeking operational wind assets without direct construction exposure. Nordex SE competes on turbine supply efficiency for medium-scale onshore clusters in forested terrain.
Sweden wind energy encompasses the conversion of kinetic atmospheric energy into electrical power through horizontal-axis turbines, typically sited at hub heights of 80-150 meters to capture stronger, more consistent wind regimes above forest canopies. The primary commercial purpose is bulk power generation for Nordic spot market participation and long-term corporate power purchase agreements. Onshore technology dominates installed capacity, though offshore installations represent the fastest-expanding segment as deeper-water foundation solutions mature. Extra-large turbine sizes anchor manufacturer R&D programs, while repowering activity concentrates margin pools among independent service providers replacing 1990s-era Danish units with modern drivetrains.
Svenska kraftnät shapes transmission access through its national grid planning process, while the Swedish Energy Agency administers electricity certificate obligations that sustain revenue stacking for new projects. EU Green Deal alignment pressures national permitting timelines, compressing environmental review windows for coastal offshore zones. Stakeholders must monitor how the proposed EU electricity market reform alters long-term contract structures before committing capital to multi-gigawatt Baltic Sea developments.
Market Dynamics
Swedish wind development hinges on Svenska kraftnät's grid reinforcement schedule, where transmission queue bottlenecks in northern Norrland determine which projects secure commercial operation dates before electricity certificate scheme deadlines expire.
Growth Catalysts
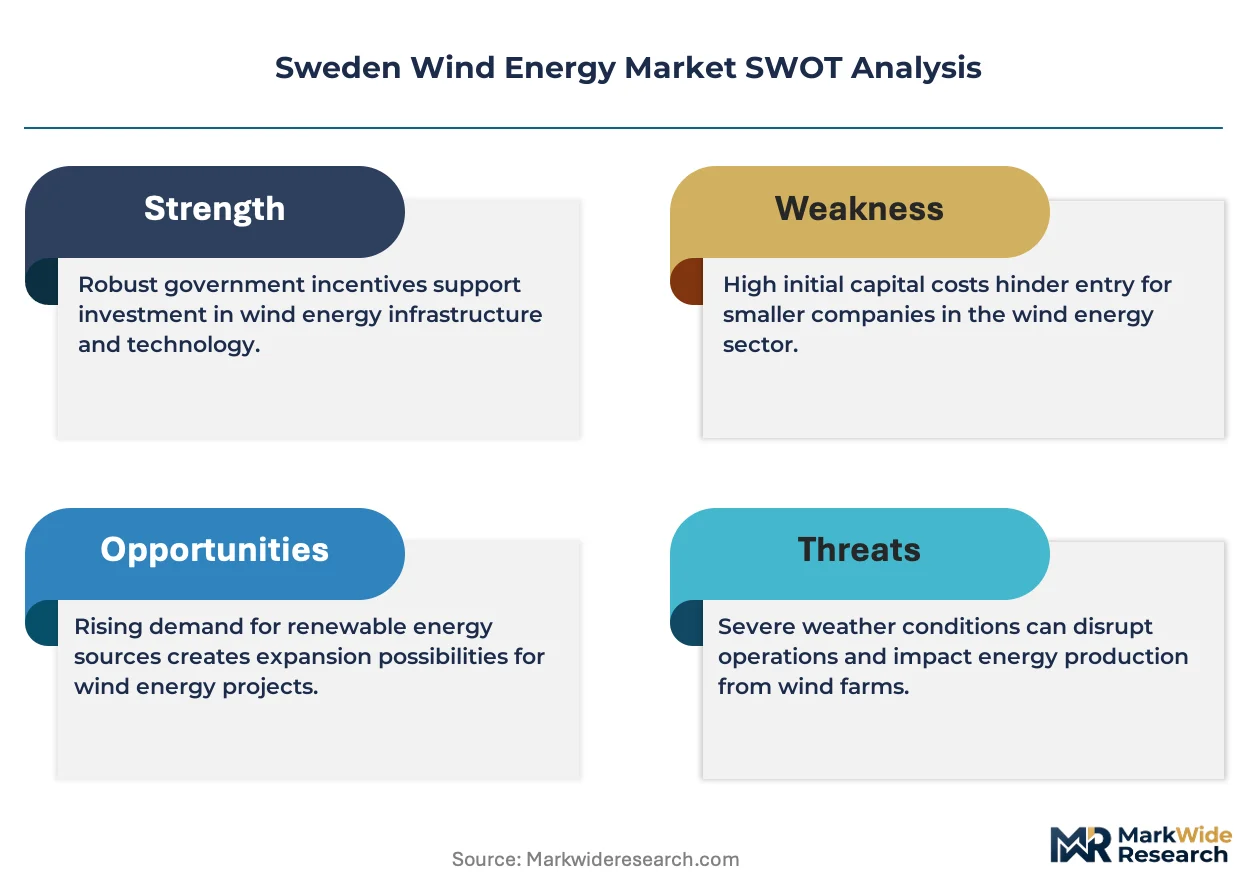
- EU Green Deal acceleration:Compressed permitting timelines for coastal offshore zones under national implementation directives reduce developer capital lock-up periods. Baltic Sea projects advance through streamlined environmental review.
- Norrland onshore resource quality:Forested terrain above the 62nd parallel delivers capacity factors exceeding southern Scandinavian benchmarks, attracting institutional capital seeking long-dated power purchase agreements.
- Corporate PPA appetite:Heavy industrial offtakers in pulp, paper, and steel sectors contract directly with wind farms to hedge Nordic spot market volatility and meet Scope 2 emissions targets.
Market Restraints
- Steel and rare earth input volatility:Turbine tower and permanent magnet supply chains expose project economics to commodity price swings beyond developer hedging capacity.
- Grid connection concentration:Svenska kraftnät's monopoly over transmission access creates queue dependencies that delay commercial operation regardless of construction completion.
- Aviation radar interference:Swedish Armed Forces restrictions on turbine heights near military installations cap hub elevations below optimal wind resource strata in southern counties.
Strategic Opportunities
- Gotland Basin floating foundations:Deeper-water offshore zones beyond fixed-bottom economic thresholds open multi-gigawatt development areas previously excluded from site screening.
- Power-to-X convergence:Co-location of electrolyzer capacity with high-capacity-factor wind farms enables hydrogen offtake contracts that stabilize revenue stacks beyond electricity certificates.
- Repowering 1990s Danish units:Aging onshore installations in Gävleborg and Västernorrland counties present brownfield sites with permitted grid access for modern drivetrain retrofits.
Industry Challenges
- Specialized technician scarcity:Offshore installation and high-voltage cable commissioning require certifications that Swedish technical institutes currently graduate at rates below pipeline demand.
- Environmental court backlogs:Land and Environmental Court appeals of municipal permits extend development timelines by 18-36 months, eroding electricity certificate eligibility windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sweden Wind Energy Market |
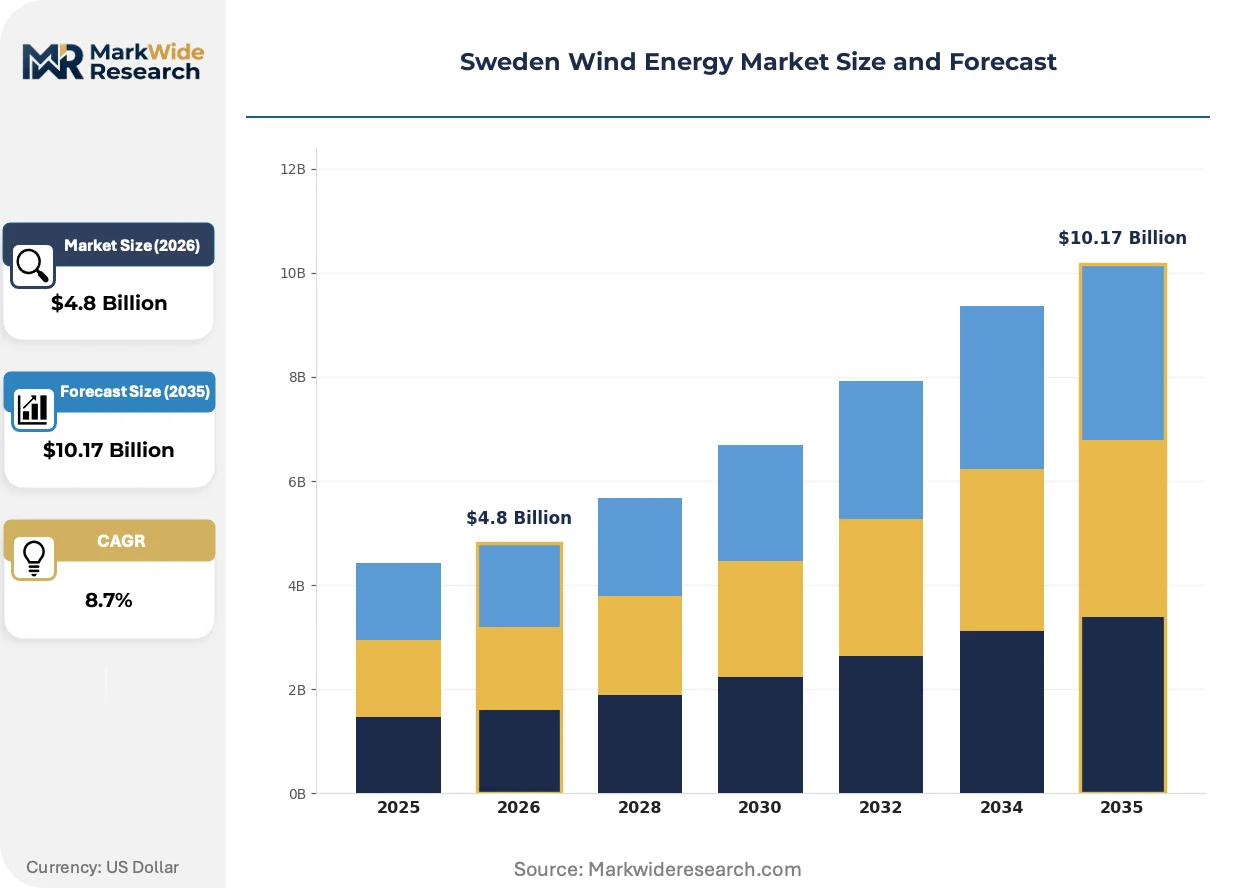
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Onshore, Offshore, Turbine Type, Hybrid End User: Utilities, Independent Power Producers, Government, Industrial Users Installation Type: New Installations, Repowering, Upgrades, Maintenance Turbine Size: Small, Medium, Large, Extra Large |
| Companies Covered | Nordex SE, Statkraft AS, Vattenfall AB, Fortum, OX2 AB, Vestas Wind Systems A/S, General Electric Renewable Energy, Ørsted A/S, Siemens Gamesa Renewable Energy SA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sweden Wind Energy Market Evolving Landscape
Technology trajectories in Swedish wind center on turbine scale escalation and foundation engineering advances that unlock deeper-water sites, while procurement structures evolve to allocate construction risk between developers and institutional capital.
Direct-drive permanent magnet generators are eliminating gearbox maintenance burdens in forested onshore sites with limited heavy-lift access. OX2 and independent power producers specify these units for remote Norrland clusters where gearbox replacement logistics inflate operational expenditures. The technology is integrating predictive maintenance platforms that compress unplanned outage durations through vibration monitoring and blade ice detection algorithms.
Sweden's implementation of the EU Renewable Energy Directive II tightens sustainability criteria for biomass co-firing, indirectly elevating wind's role in national renewable targets. The Swedish Energy Agency's administration of electricity certificate obligations now requires hourly matching proofs for green hydrogen claims, affecting offtake contract structuring. Offshore developers in Blekinge and Skåne counties respond by front-loading geotechnical survey investments to accelerate permitting submissions before 2026 scheme reviews.
Industrial offtakers now contract directly with wind farms through ten-to-fifteen-year fixed-price agreements, bypassing traditional utility intermediaries. This channel compression concentrates credit risk assessment burden on developer balance sheets rather than regulated utility tariffs. Pulp and paper mills in Västra Götaland demonstrate the most advanced adoption, with several facilities now sourcing over 60 percent of consumption from nominated wind assets.
Sweden Wind Energy Market Segmentation
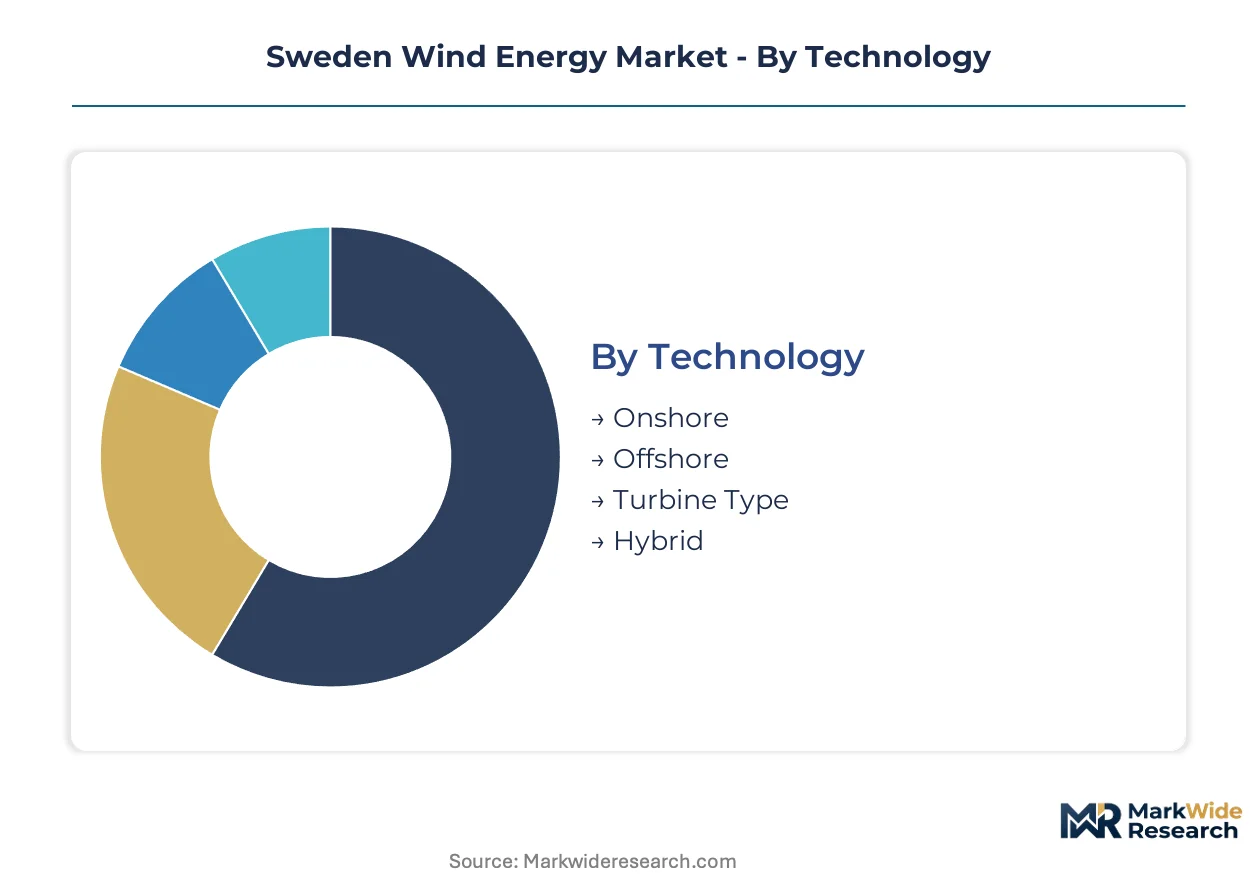
Swedish wind developers configure technology and procurement structures around grid access constraints in Norrland and the electricity certificate scheme timeline. Segmentation choices directly determine capital deployment horizons and offtake contract viability.
Technology:
Buyers differentiate by foundation engineering requirements and water depth economics, not turbine specifications alone.
- Onshore:Horizontal-axis turbines sited at 80-150 meter hub heights penetrate forest canopies to capture consistent wind regimes above tree lines. Demand clusters in Västernorrland and Jämtland counties where Svenska kraftnät transmission queues determine which projects secure commercial operation dates before certificate deadlines lapse.
- Offshore:Fixed-bottom and floating foundation systems target Baltic Sea zones with deeper-water economics now viable beyond 50-meter depths. Blekinge and Skåne developments accelerate through compressed EU Green Deal permitting timelines, though aviation radar restrictions cap hub elevations near military installations.
- Turbine Type:Direct-drive permanent magnet generators eliminate gearbox maintenance burdens in remote clusters with limited heavy-lift access.
- Hybrid:Co-located electrolyzer and battery storage configurations enable hydrogen offtake contracts that stabilize revenue stacks beyond electricity certificates.
Onshore leads volumes today; offshore is gaining share fastest.
End User:
Procurement authority concentrates among balance-sheet-heavy entities capable of absorbing construction risk and long-dated power purchase agreement exposure.
- Utilities:Vattenfall AB and municipal operators leverage integrated generation-grid models to control pipelines from origination through delivery. These entities dominate certificate-eligible capacity additions in Norrland.
- Independent Power Producers:OX2 AB and specialist developers originate projects for institutional capital seeking operational assets without direct construction exposure. IPPs concentrate development services in forested terrain where geotechnical complexity demands local expertise.
- Government:Svenska kraftnät and county administrative boards shape procurement through transmission planning and permitting authority rather than direct ownership.
- Industrial Users:Pulp, paper, and steel sector offtakers contract directly with wind farms through ten-to-fifteen-year fixed-price agreements, bypassing traditional utility intermediaries.
Utilities dominate installed base; industrial direct contracting is expanding most quickly.
Installation Type:
Capital allocation shifts between greenfield development and brownfield optimization based on grid connection scarcity and equipment depreciation schedules.
- New Installations:Greenfield projects in Norrland and Baltic Sea zones require fresh permitting, geotechnical surveys, and Svenska kraftnät queue positions. These installations absorb the majority of developer capital but face 18-36 month environmental court appeal risks.
- Repowering:Replacement of 1990s-era Danish units with modern drivetrains concentrates in Gävleborg and Västernorrland counties where permitted grid access already exists. Brownfield sites bypass transmission queue bottlenecks that delay new projects.
- Upgrades:Blade extensions and control system retrofits extend asset life without full turbine replacement.
- Maintenance:Predictive maintenance platforms compress unplanned outage durations through vibration monitoring and blade ice detection algorithms.
New installations command capital deployment today; repowering offers the steepest expansion trajectory as 1990s vintages reach end-of-life.
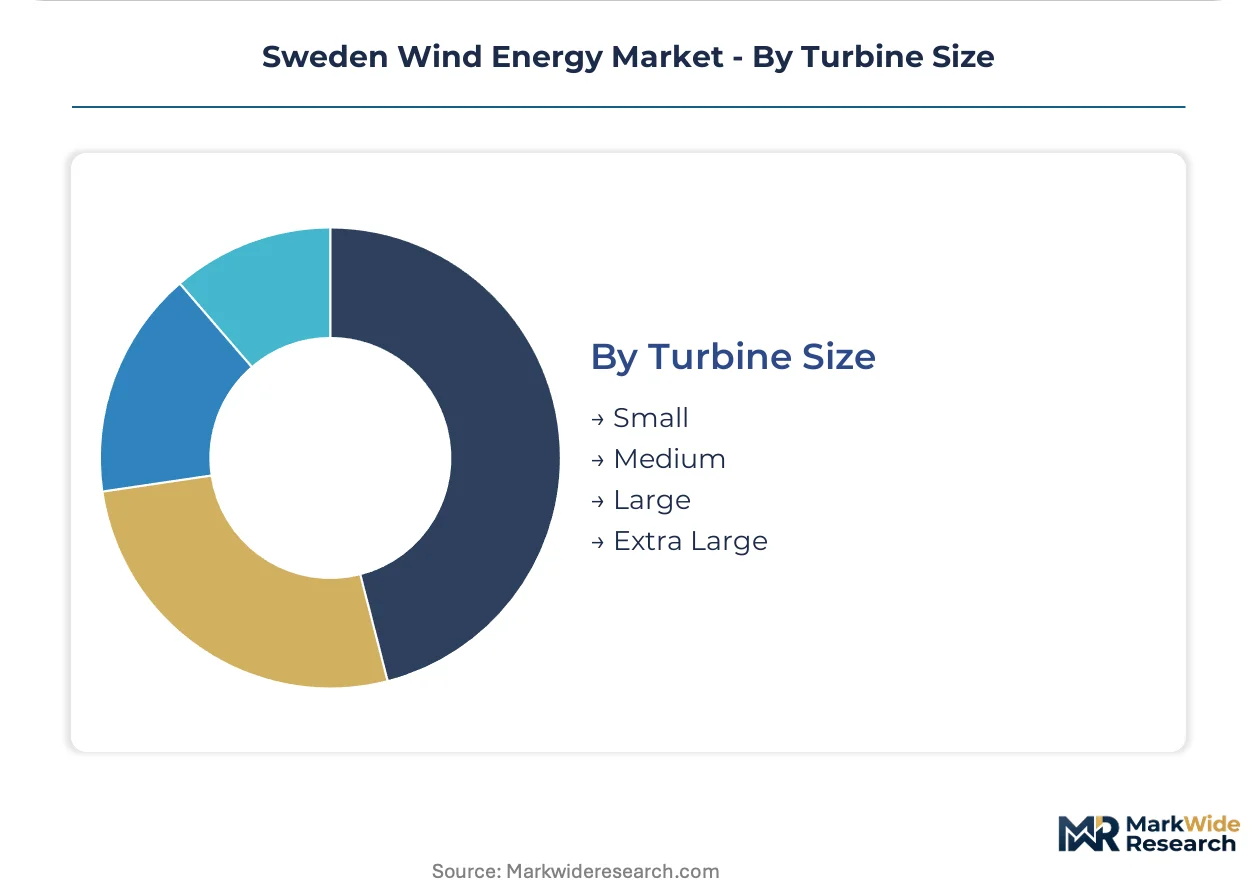
Turbine Size:
Hub height and rotor diameter choices trade off against aviation restrictions, forest canopy penetration, and logistics constraints in remote terrain.
- Small:Units below 2 MW capacity serve distributed applications and microgrids in archipelago communities with limited interconnection options.
- Medium:2-4 MW turbines balance transport logistics against energy yield in forested counties where road infrastructure limits component dimensions.
- Large:4-8 MW machines anchor manufacturer R&D programs and dominate new onshore installations in Norrland where capacity factors exceed southern Scandinavian benchmarks.
- Extra Large:8+ MW offshore units target Baltic Sea developments with deeper-water foundation solutions and higher capacity factors than onshore equivalents.
Large turbines dominate current procurement; extra-large units are climbing the fastest as floating foundation technology matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's offshore wind auction volumes exceed Sweden's pipeline by a factor of three, yet Swedish capacity factors in Norrland surpass German North Sea equivalents. Denmark bridges both markets through interconnector flows.
Norrland
Forested terrain above the 62nd parallel delivers capacity factors exceeding southern Scandinavian benchmarks, attracting institutional capital seeking long-dated power purchase agreements. Svenska kraftnät's transmission queue bottlenecks determine which projects secure commercial operation dates before electricity certificate scheme deadlines expire. Västernorrland and Jämtland counties concentrate development activity where grid reinforcement schedules dictate capital deployment timing.
Götaland
Industrial offtakers in pulp, paper, and steel sectors contract directly with wind farms to hedge Nordic spot market volatility and meet Scope 2 emissions targets. The Swedish Energy Agency administers electricity certificate obligations that sustain revenue stacking for new projects. Västra Götaland pulp and paper mills demonstrate the most advanced adoption, with several facilities now sourcing over 60 percent of consumption from nominated wind assets.
Svealand
Repowering activity concentrates on brownfield sites with permitted grid access for modern drivetrain retrofits. Gävleborg county hosts aging 1990s-era Danish units targeted for replacement. The Land and Environmental Court processes appeals of municipal permits, extending development timelines by 18-36 months in contested zones.
Baltic Sea Offshore Zones
Blekinge and Skåne developments accelerate through compressed EU Green Deal permitting timelines for coastal offshore zones. Deeper-water foundation solutions now unlock multi-gigawatt development areas previously excluded from site screening. Aviation radar restrictions cap hub elevations near military installations in southern counties.
Gotland Basin
Floating foundation technology matures in deeper-water zones beyond fixed-bottom economic thresholds. Geotechnical survey investments front-load capital to accelerate permitting submissions before 2026 scheme reviews. Hourly matching proofs for green hydrogen claims affect offtake contract structuring in this zone.
Sweden Wind Energy Market Competitive Landscape
Swedish producers anchor the integrated utility-developer tier; German and Danish turbine specialists hold equipment supply positions. The market structures around three distinct archetypes: state-backed utilities controlling pipelines from origination to grid delivery, independent power producers originating projects for institutional capital, and equipment manufacturers competing on turbine supply efficiency. Strategic moves concentrate on transmission queue positioning and long-term offtake contracting rather than manufacturing scale.
Within the integrated utility tier, Vattenfall AB exemplifies the state-backed model with generation-grid control. Among independent developers, OX2 AB represents the specialist archetype serving institutional investors seeking operational assets without direct construction exposure. On the equipment vector, Nordex SE anchors turbine supply for medium-scale onshore clusters in forested terrain. These three entities collectively illustrate how procurement authority concentrates among balance-sheet-heavy entities capable of absorbing construction risk and long-dated power purchase agreement exposure.
| Leading Market Players |
|---|
| Nordex SE |
| Statkraft AS |
| Vattenfall AB |
| Fortum |
| OX2 AB |
| Vestas Wind Systems A/S |
| General Electric Renewable Energy |
| Ørsted A/S |
| Siemens Gamesa Renewable Energy SA |
| Others |
Value Network & Pricing Analysis
Steel price indices on the London Metal Exchange cascade through turbine tower fabrication into project development cost tiers, compressing margins for developers locked into fixed-price EPC contracts while rewarding vertically integrated utilities with captive forging capacity.
Pricing Analysis
Capacity additions in Norrland are reshaping price floors for electricity certificate-eligible generation. Contract-based long-term offtake structures dominate, with price differentiation driven by capacity factor guarantees and green hydrogen bundling. Cost compression in standard-tier projects is intensifying because Svenska kraftnät transmission queue delays erode certificate window eligibility. Industrial offtakers in pulp and paper show least price sensitivity due to Scope 2 compliance premiums, while municipal utilities face acute budget constraints.
Supply Chain Analysis
Permanent magnet supply rests on Chinese rare earth processors and German magnetic alloy specialists. Turbine nacelles draw from Danish and Spanish assembly plants, while blade manufacturing concentrates in Poland and Turkey. Single-source vulnerability in neodymium-dysprosium supply chains exposes project timelines to export quota disruptions. Distribution runs through EPC contractors with Baltic Sea port access for offshore component staging.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Sweden wind energy market functions as a regulatory compounder where EU Green Deal implementation accelerates permitting velocity and compresses development timelines for Baltic Sea zones.
For Market Incumbents: Anchor transmission queue positions through early Svenska kraftnät engagement to defend against IPP entrants with faster municipal permitting pathways. Deepen backward integration into electrolyzer manufacturing to capture Power-to-X revenue stacks before certificate scheme reviews alter hydrogen claim structures.
For New Entrants and Emerging Players: The premium-to-economy price gap in corporate PPA contracting offers entry points for specialist developers with forestry terrain expertise. Repowering brownfield sites in Gävleborg bypasses greenfield grid bottlenecks. Lead with hourly matching certification capabilities to differentiate against utility intermediaries.
For Investors and Strategic Acquirers: Asymmetric upside sits with independent power producers holding permitted Norrland portfolios ready for institutional capital deployment. Long-term viability hinges on electricity certificate scheme continuity and hydrogen offtake contract depth. Watch Svenska kraftnät's grid reinforcement schedule as the critical inflection signal for commercial operation date certainty.
| Strategic Initiative | Industry Significance |
|---|---|
| Transmission Queue Positioning | Early Svenska kraftnät engagement secures commercial operation dates before certificate deadlines lapse. |
| Power Purchase Agreement Structuring | Direct corporate contracts with pulp and steel offtakers bypass utility intermediaries and stabilize revenue. |
| Floating Foundation Technology Licensing | Gotland Basin depth economics unlock multi-gigawatt zones previously excluded from development screening. |
| Repowering Asset Acquisition | Brownfield sites with permitted grid access eliminate transmission queue delays facing greenfield projects. |
| Electrolyzer Co-location Integration | Hourly matching proofs for green hydrogen claims satisfy Swedish Energy Agency certificate obligations. |
Research Methodology
Bottom-up project pipeline modeling reconciled against top-down electricity certificate tracking forms the analytical core. Primary interviews with utility planning officers, IPP project developers, EPC contractors, and grid operators at Svenska kraftnät combine with secondary validation from Swedish Energy Agency certificate registries, Svenska kraftnät grid planning documents, EU Renewable Energy Directive II implementation filings, and Nordic spot market price databases. Triangulation across these sources ensures demand-side and supply-side estimates converge.
Input-output matrices map turbine deployment by technology segment, capacity tier, and regional grid type across the projection horizon. CAGRs derive from project development velocity, interconnection queue progression, and certificate market clearing prices. Segmentation dimensions include onshore versus offshore foundation engineering, utility versus industrial offtake structures, and greenfield versus repowering installation types. Forecast inputs incorporate Svenska kraftnät reinforcement schedules and EU Green Deal permitting timeline compression.
Caveats apply where electricity certificate scheme revisions, rare earth export restrictions, or aviation radar regulation changes could materially shift the outlook. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wind Energy Systems
Europe Large Wind Turbine Market
Wind Energy Systems
Europe Wind Power Market
Wind Energy Systems
Wind Turbine Nacelle Market
Wind Energy Systems
Wind Turbine Shaft Market
Wind Energy Systems
Offshore Wind Tower Market
Wind Energy Systems
Medium-Speed Permanent Magnet Wind Turbine Generator System Market
Wind Energy Systems
Poland Wind Energy Market
Wind Energy Systems
Global Wind LIDAR Market
Wind Energy Systems
Greece Wind Energy Market
Wind Energy Systems
Onshore Wind Turbine (above 2.5MW) Market
Wind Energy Systems
Wind Tower Market
Wind Energy Systems
Global Small Wind Power Market
Wind Energy Systems
Iran Wind Energy Market
Wind Energy Systems
Offshore Wind Turbine Blade Leading-Edge Defect Inspection Equipment Market
Wind Energy Systems
Europe Wind Power Equipment Market
Wind Energy Systems
Offshore Wind Cable Market