
 Middle East and Africa Virtual Reality Market | 2026-2036
Middle East and Africa Virtual Reality Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Virtual Reality Market Foresight
Buyer concentration among Saudi healthcare consortiums is recalibrating procurement patterns across the Middle East and Africa Virtual Reality Market. Meta Platforms anchors its position through R&D intensity in immersive display architectures. Samsung Electronics leverages its semiconductor fabrication scale to control component costs for regional headset distributors. HTC Corporation specializes in enterprise-grade hardware that dominates industrial training deployments across Gulf Cooperation Council states.
Virtual reality denotes a computer-generated immersive environment rendered through stereoscopic displays with refresh rates typically exceeding 90 Hz to prevent motion sickness, serving industrial training, medical visualization, and interactive entertainment applications. Headsets capture the dominant share of hardware value as tethered and standalone devices penetrate oil-and-gas training centers. Cloud-based deployment expands fastest among education end users seeking to circumvent local compute infrastructure gaps. Training applications command premium pricing due to compliance requirements in aviation and heavy machinery sectors across the region.
The UAE's Telecommunications and Digital Government Regulatory Authority and South Africa's Independent Communications Authority shape market access through spectrum licensing for wireless VR streaming. Saudi Arabia's Communications, Space and Technology Commission enforces data-localization standards that redirect cloud-based deployment architectures toward domestic server infrastructure. Stakeholders must monitor evolving national content requirements that could fragment software licensing across multiple jurisdictions.
Market Dynamics
Saudi healthcare consortiums are consolidating procurement authority, forcing hardware vendors to restructure pricing and service architectures around volume-scale deployment contracts rather than unit sales.
Growth Catalysts
- Low-latency spectrum allocation:The UAE's telecommunications regulator has reserved millimeter-wave bands for wireless VR transmission, enabling untethered surgical training and industrial simulation without local compute infrastructure.
- Hazardous training substitution:South Africa's mining sector mandates VR-based safety certification for underground operations, replacing live exposure to rockfall and ventilation hazards with immersive scenario replication.
- Data-localization mandates:Saudi Arabia's Communications, Space and Technology Commission requires domestic server hosting for healthcare VR applications, accelerating sovereign cloud infrastructure investment.
Market Restraints
- Display panel supply concentration:Advanced micro-OLED fabrication capacity clusters in East Asian foundries, exposing regional headset assemblers to shipping delays and currency volatility.
- Import duty stacking:Gulf Cooperation Council customs frameworks layer electronics tariffs atop software licensing fees, inflating landed costs for enterprise training systems.
- Power infrastructure gaps:Rural Nigerian and Kenyan facilities lack reliable grid connectivity for high-fidelity VR compute, restricting deployment to urban training centers.
Strategic Opportunities
- Underpenetrated East African education:Kenyan technical institutes seek cloud-streamed VR labs to circumvent capital expenditure on local rendering hardware.
- Aviation maintenance convergence:Egyptian and Moroccan MRO facilities are piloting mixed-reality overlays combining VR visualization with haptic feedback for engine diagnostics.
- Sovereign wealth deployment:Saudi Arabia's Public Investment Fund is channeling capital toward domestic VR content studios, creating captive demand for Arabic-language industrial training modules.
Industry Challenges
- Immersive content production bottleneck:The region lacks sufficient 3D environment artists and motion-capture technicians, forcing enterprises to outsource scenario development to European studios.
- Biometric data governance:Eye-tracking and pupillometry sensors in enterprise headsets trigger unresolved compliance questions under Saudi and UAE data protection frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Virtual Reality Market |
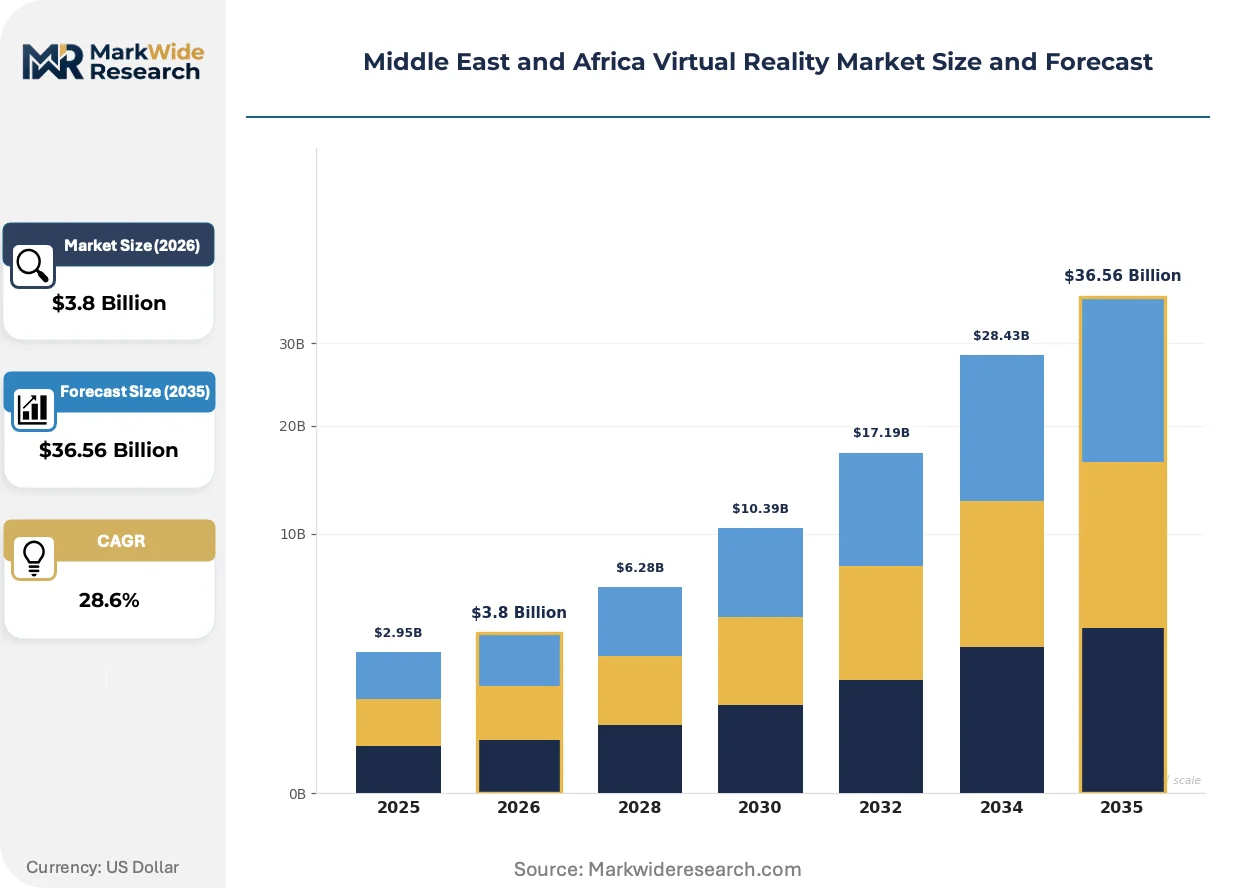
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $36.56 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Headsets, Software, Accessories, Haptic Devices End User: Gaming, Education, Healthcare, Real Estate Deployment: On-Premises, Cloud-Based, Hybrid, Mobile Application: Training, Entertainment, Simulation, Virtual Tours |
| Companies Covered | Microsoft Corporation, Samsung Electronics, Meta Platforms (Oculus VR), Pico Interactive, Lenovo Group Limited, HTC Corporation, Google LLC, Varjo Technologies, Sony Corporation, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Virtual Reality Market Shifts & Advancements
Wireless streaming architectures are compressing hardware requirements at the edge while cloud rendering farms expand capacity across Gulf data center zones. Three developments are restructuring competitive positioning.
Foveated rendering with dynamic resolution scaling is electrifying headset efficiency. The technology concentrates GPU workload only where the user's gaze lands, reducing pixel processing by up to 70 percent. Saudi surgical training centers are adopting this for high-fidelity anatomy visualization without tethered workstation bulk. The shift is compressing hardware procurement cycles from three-year replacement schedules to annual refresh programs.
The UAE's spectrum licensing framework for 6 GHz and 60 GHz bands is enabling millimeter-wave VR streaming with sub-20 millisecond latency. Industrial training providers in Abu Dhabi and Dubai are deploying these allocations for real-time remote equipment operation. Heavy machinery manufacturers are restructuring service contracts to include wireless VR maintenance support as a standard clause.
Consortium-led procurement is displacing fragmented purchasing across Saudi healthcare networks. King Faisal Specialist Hospital and Research Centre anchors a buying cooperative that aggregates demand from twelve tertiary facilities. Equipment vendors are responding with dedicated Arabic-language support desks and localized spare parts inventories in Riyadh.
Middle East and Africa Virtual Reality Market Segmentation
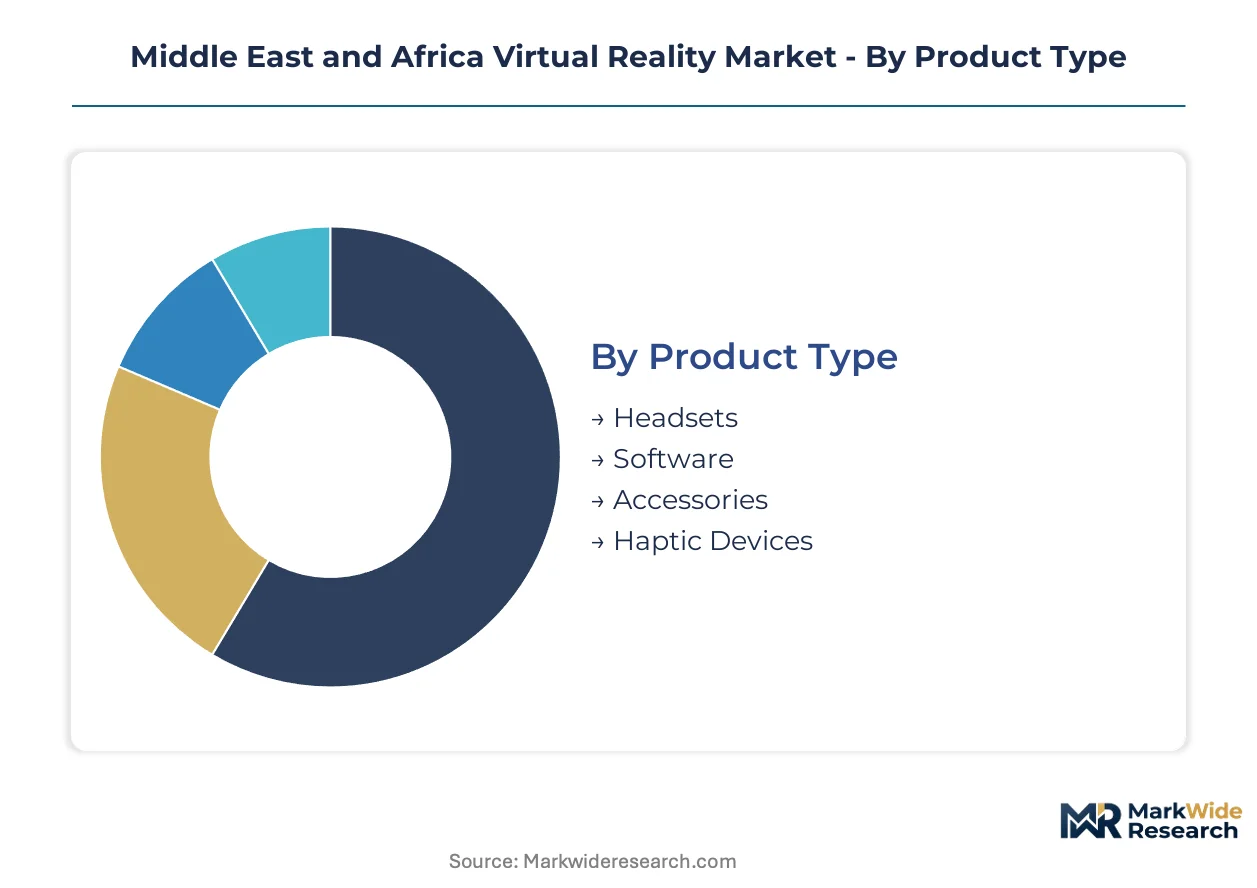
Segmentation in this market reveals how hardware procurement concentrates in industrial training while software and services fragment across education and healthcare verticals. Understanding these splits enables vendors to align pricing architectures with deployment scale and compliance requirements.
Product Type:
Headsets capture volume share through tethered enterprise deployments, while software commands premium pricing in regulated healthcare environments.
- Headsets:Stereoscopic displays with refresh rates exceeding 90 Hz dominate hardware procurement from Saudi oil-and-gas training centers and South African mining safety programs. Tethered configurations prevail in industrial settings demanding high-fidelity rendering, while standalone units penetrate education budgets with lower infrastructure requirements.
- Software:Immersive content licensing generates recurring revenue through scenario libraries for surgical training and heavy machinery operation. Saudi healthcare consortiums aggregate demand for Arabic-language modules, compressing per-seat costs through volume procurement.
- Accessories:Controller peripherals and tracking sensors extend headset functionality in Egyptian aviation maintenance facilities.
- Haptic Devices:Force-feedback gloves and vests penetrate Abu Dhabi industrial simulation centers requiring tactile response replication.
Mature deployment sits with Headsets. Newer deployment is concentrated in Haptic Devices.
End User:
Healthcare procurement aggregates through Saudi consortium structures, while education demand fragments across East African technical institutes seeking cloud-streamed alternatives.
- Gaming:Consumer entertainment drives headset volume through UAE retail channels and South African e-commerce platforms, though enterprise applications dominate absolute revenue.
- Education:Kenyan and Nigerian technical institutes deploy cloud-based VR labs to circumvent capital expenditure on local rendering hardware, with streaming architectures expanding fastest among budget-constrained institutions.
- Healthcare:Saudi Arabia's King Faisal Specialist Hospital anchors a twelve-facility buying cooperative demanding Arabic-language support and localized spare parts inventories in Riyadh.
- Real Estate:UAE property developers deploy virtual tours for off-plan sales to international investors, leveraging wireless streaming to reduce client onboarding friction.
Procurement maturity clusters in Healthcare. Volume expansion is accelerating in Education.
Deployment:
On-premises installations retain dominance where data-localization mandates apply, while cloud architectures gain traction where infrastructure gaps persist.
- On-Premises:Local rendering workstations serve Saudi surgical training centers subject to CSTC data-localization requirements, with domestic server hosting accelerating sovereign cloud investment.
- Cloud-Based:Streaming delivery expands fastest among education end users in Kenya and Nigeria lacking reliable grid connectivity for edge compute, compressing hardware requirements at the endpoint.
- Hybrid:Split architectures balance sensitive data processing locally with non-critical rendering remotely in Moroccan aviation MRO facilities.
- Mobile:Smartphone-dependent VR penetration remains limited by display quality constraints and thermal throttling in ambient Gulf temperatures.
Regulatory compliance anchors On-Premises deployment. Infrastructure scarcity is pushing adoption toward Cloud-Based models.
Application:
Training applications command premium pricing through compliance mandates, while entertainment competes on hardware cost minimization.
- Training:Safety certification scenarios for South African underground mining operations and Saudi surgical residencies generate the highest per-seat licensing fees due to regulatory validation requirements.
- Entertainment:Consumer gaming and cinematic experiences compete through hardware affordability and content library breadth rather than specialized scenario development.
- Simulation:Heavy machinery operation replication serves Abu Dhabi construction and logistics sectors with haptic feedback integration for equipment familiarization.
- Virtual Tours:Property visualization and cultural heritage preservation applications concentrate in UAE and Egyptian tourism marketing budgets.
Compliance-driven deployment centers on Training. Consumer accessibility defines Entertainment adoption patterns.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia's sovereign wealth deployment anchors capital formation across the Middle East and Africa Virtual Reality Market. Spectrum licensing frameworks in the UAE and data-localization mandates in Riyadh are redirecting cloud infrastructure investment toward domestic hosting. Industrial training demand concentrates in South African mining corridors and Egyptian aviation maintenance clusters.
Saudi Arabia
Healthcare consortium procurement aggregates demand from twelve tertiary facilities anchored by King Faisal Specialist Hospital. The Communications, Space and Technology Commission enforces data-localization standards that redirect cloud-based deployment architectures toward domestic server infrastructure. Riyadh concentrates hardware vendor support desks and localized spare parts inventories serving surgical training centers.
United Arab Emirates
Real estate developers deploy wireless virtual tours for off-plan sales to international investors, reducing client onboarding friction. The Telecommunications and Digital Government Regulatory Authority has reserved millimeter-wave bands for low-latency VR transmission, enabling untethered industrial simulation. Abu Dhabi and Dubai industrial training providers deploy these spectrum allocations for real-time remote equipment operation.
South Africa
Mining sector mandates require VR-based safety certification for underground operations, replacing live exposure to rockfall hazards with immersive scenario replication. The Independent Communications Authority shapes market access through spectrum licensing frameworks for wireless streaming. Johannesburg and Pretoria training centers concentrate procurement of enterprise-grade headsets for heavy machinery certification programs.
Egypt
Aviation maintenance, repair, and overhaul facilities in Cairo and Alexandria pilot mixed-reality overlays combining VR visualization with haptic feedback for engine diagnostics. The national civil aviation regulator validates immersive training modules for technical certification compliance. The Nile Delta corridor attracts regional content development studios serving Arabic-language industrial training demand.
Kenya
Technical institutes in Nairobi seek cloud-streamed VR labs to circumvent capital expenditure on local rendering hardware. National education policy frameworks prioritize digital skills infrastructure investment through public-private partnership models. The East African Rift Valley corridor concentrates pilot programs for streaming delivery among budget-constrained institutions lacking reliable grid connectivity.
Middle East and Africa Virtual Reality Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialized enterprise applications and regional content localization. The vendor base stratifies across three tiers: global technology conglomerates with integrated hardware-software stacks, specialized headset manufacturers focused on industrial-grade specifications, and regional system integrators assembling training deployment packages. Strategic archetypes include semiconductor-integrated conglomerates leveraging fabrication scale, immersive display specialists commanding premium pricing in regulated healthcare environments, and sovereign-backed content studios capturing domestic procurement preference. Dominant competitive moves encompass spectrum licensing partnerships with national regulators and backward integration into micro-OLED supply channels.
Within the enterprise hardware tier, HTC Corporation and Varjo Technologies exemplify industrial-grade specialization. Samsung Electronics anchors the semiconductor-integrated archetype through fabrication scale advantages. Meta Platforms occupies a position representing the consumer-to-enterprise transition vector, though its regional presence concentrates on developer ecosystem cultivation rather than direct procurement.
| Leading Market Players |
|---|
| Microsoft Corporation |
| Samsung Electronics |
| Meta Platforms (Oculus VR) |
| Pico Interactive |
| Lenovo Group Limited |
| HTC Corporation |
| Google LLC |
| Varjo Technologies |
| Sony Corporation |
| Others |
Supply & Pricing Matrix
Saudi healthcare consortium procurement aggregation is compressing per-unit hardware margins while forcing vendors to absorb localization costs for Arabic-language support and Riyadh-based spare parts inventories. This demand-side consolidation is reshaping supplier economics toward volume-scale service contracts and away from transactional headset sales.
Pricing Analysis
Warranty and service bundling separates enterprise-grade industrial deployments from education-sector hardware sales. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation for aviation and mining safety modules versus consumer entertainment headsets. Cost compression in the education tier is intensifying because Kenyan and Nigerian technical institutes prioritize cloud-streamed alternatives over capital-intensive local rendering infrastructure. Healthcare procurement through King Faisal Specialist Hospital's twelve-facility cooperative exhibits the lowest price sensitivity due to regulatory compliance mandates.
Supply Chain Analysis
Regional distribution centers in Dubai and Johannesburg anchor hub-and-spoke patterns serving Gulf Cooperation Council states and sub-Saharan African markets respectively. Advanced micro-OLED display fabrication concentrates in South Korea, Taiwan, and Japan, while semiconductor components source from Chinese and Malaysian foundries. Single-source vulnerability in East Asian display panel supply exposes regional assemblers to shipping delays and currency volatility. Distribution runs through authorized distributor networks with localized technical support capabilities rather than direct manufacturer-to-end-user channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around procurement scale advantages, with Saudi sovereign wealth deployment and healthcare consortium aggregation forcing sub-scale hardware vendors toward exit or acquisition.
For Market Incumbents: To counter emerging cloud-streaming substitutes, HTC Corporation and Varjo Technologies should deepen in-house production of Arabic-language content modules while securing millimeter-wave spectrum partnerships with UAE telecommunications regulators. Capacity addition in Riyadh-based support infrastructure will defend against procurement aggregation pressure from Saudi healthcare networks. For New Entrants and Emerging Players: Kenyan technical institutes represent the most penetrable channel partner type for cloud-based VR lab deployments, given infrastructure scarcity and public-private partnership policy alignment. White-space targets include haptic device integration for Egyptian aviation MRO facilities and sovereign-backed content studios serving Saudi industrial training demand. For Investors and Strategic Acquirers: The window for entry favors vertically integrated headset manufacturers with captive semiconductor supply. Long-term viability hinges on backward integration into micro-OLED fabrication or exclusive spectrum licensing arrangements. The signal to watch is CSTC enforcement intensity for data-localization mandates redirecting cloud infrastructure investment toward domestic Saudi hosting.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Micro-OLED Supply | Captive display sourcing insulates Saudi and UAE headset assemblers from East Asian foundry concentration risk. |
| Millimeter-Wave Spectrum Partnership | UAE Telecommunications and Digital Government Regulatory Authority allocations enable sub-20 millisecond wireless VR streaming latency. |
| Arabic-Language Content Studio Acquisition | Saudi Public Investment Fund capital deployment creates captive demand for localized industrial training modules. |
| Cloud Rendering Farm Expansion | Gulf data center zones circumvent Nigerian and Kenyan grid connectivity gaps for education-sector deployment. |
| Haptic Device Certification Investment | Egyptian civil aviation regulator validation unlocks mixed-reality maintenance training for Cairo and Alexandria MRO facilities. |
Research Methodology
Multi-period observation of procurement aggregation patterns, spectrum licensing frameworks, and data-localization enforcement anchored the trend analysis, supplemented by interviews with surgical training directors, mining safety officers, telecommunications regulators, VR hardware procurement managers, and cloud infrastructure specialists. Secondary validation drew from CSTC regulatory filings, UAE spectrum allocation notices, South African mining safety mandate documentation, hospital procurement databases, and hyperscaler Gulf data center capex disclosures. Bottom-up headset shipment tracking and top-down market sizing triangulated volume estimates.
Input-output matrices modeled hardware, software, and services segmentation across deployment modes, end-user verticals, and application types throughout the forecast period. CAGRs derived from logistic adoption curves fitted to healthcare consortium procurement cycles and education-sector cloud-streaming penetration trajectories. Industry-specific forecast inputs incorporated foveated rendering adoption rates in Saudi surgical centers and millimeter-wave infrastructure buildout timelines in Abu Dhabi and Dubai.
Caveats apply where CSTC enforcement intensity, East Asian display panel supply disruptions, or East African grid infrastructure investment delays could materially shift the outlook. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Virtual Reality (VR) and Augmented Reality (AR)
VR Ski Machines Market
Virtual Reality (VR) and Augmented Reality (AR)
Middle East Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
India Desktop Virtualization Market
Virtual Reality (VR) and Augmented Reality (AR)
Asia-Pacific Virtual Reality (VR) Health Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality (VR) and Augmented Reality (AR) Microdisplay Market
Virtual Reality (VR) and Augmented Reality (AR)
Immersive Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Augmented Learning Market
Virtual Reality (VR) and Augmented Reality (AR)
India Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
Europe Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
VR Headsets Market
Virtual Reality (VR) and Augmented Reality (AR)
AR in Education Market
Virtual Reality (VR) and Augmented Reality (AR)
Europe Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Smart Glasses for Augmented Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
UK Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
Immersive Simulator Market
Virtual Reality (VR) and Augmented Reality (AR)
Para-Virtualization Market