
 United Kingdom Gelatin Market | 2026-2036
United Kingdom Gelatin Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Gelatin Market Analytics
Contract formulation services is expanding as a distinct revenue layer in the UK gelatin value chain, shifting supplier relationships from commodity transactions to performance-based partnerships. GELITA AG leverages its Manchester technical center to sustain long-term supply agreements with British nutraceutical brands. Darling Ingredients Inc. competes through backward integration into rendering operations, securing raw material access across England's abattoir network. Rousselot SAS differentiates via specialized pharmaceutical-grade certifications that command premium positioning within the NHS procurement framework.
Gelatin comprises partially hydrolyzed collagen extracted from animal connective tissues, with bloom strength measured between 50 and 300 grams defining its gel-forming capacity and functional performance in industrial applications. Food grade gelatin dominates UK volume flows, serving confectionery manufacturers in Yorkshire and Lancashire with standardized viscosity profiles for gummy candy production. Pharmaceutical grade gelatin commands superior margins, driven by capsule shell demand from API formulation facilities clustered around the M11 corridor. Powder form leads distribution logistics, though sheet gelatin retains entrenched positions among artisan food producers and premium bakery operations in London and Bristol.
The Food Standards Agency enforces compositional standards under retained EU food law, while the Medicines and Healthcare products Regulatory Agency governs pharmaceutical excipient purity through British Pharmacopoeia monographs. Veterinary Medicines Directorate traceability requirements shape sourcing decisions, compelling suppliers to document species origin and BSE-related geographic restrictions across their supply bases. Stakeholders must monitor divergence between UK and EU regulatory frameworks post-Brexit, as future alignment decisions on gelatin-specific purity thresholds will determine cross-border market access conditions and domestic certification costs.
Market Dynamics
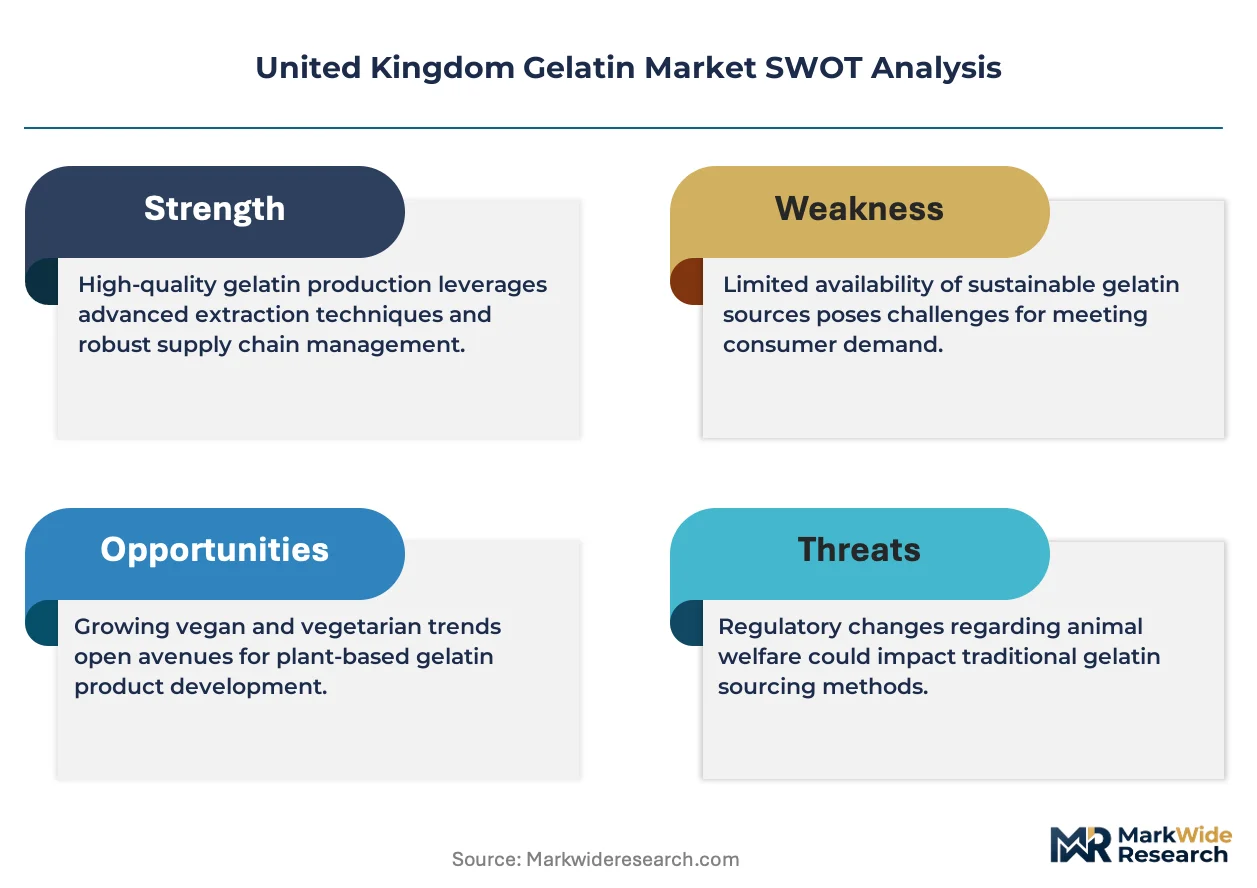
Post-Brexit regulatory divergence is forcing UK gelatin suppliers to maintain dual certification pathways for EU market access while the Medicines and Healthcare products Regulatory Agency tightens pharmaceutical-grade purity thresholds. This structural friction reshapes capital allocation across England's rendering and hydrolysis facilities.
Growth Catalysts
- Nutraceutical formulation expansion:Health-conscious consumers in England's urban centers are driving capsule and gummy supplement demand. The NHS procurement framework increasingly favors domestically certified excipients.
- REACH retention with UKCA alignment:The retained EU chemicals regime provides continuity for cross-border raw material flows. Suppliers leverage this stability to secure long-term pharmaceutical contracts.
- Cambridge-Stevenage pharmaceutical corridor concentration:API formulation facilities cluster along the M11 corridor. Gelatin capsule shell demand concentrates within this 40-mile manufacturing zone.
Market Restraints
- Bovine raw material volatility:Abattoir output fluctuations in England's Midlands and North create input cost instability. Rendering capacity constraints amplify price swings during livestock cycle downturns.
- Porcine sourcing geographic restrictions:BSE-related geographic restrictions under Veterinary Medicines Directorate rules limit eligible supply bases. Suppliers face documented traceability burdens across Commonwealth and EU origins.
- Plant-based hydrocolloid substitution:Pectin and carrageenan formulations displace gelatin in premium confectionery segments. Yorkshire and Lancashire manufacturers trial alternative gelling agents for vegetarian product lines.
Strategic Opportunities
- Scottish and Welsh manufacturing expansion:Underpenetrated regions outside England's core corridor offer greenfield facility potential. Devolved administration incentive schemes support food-grade production diversification.
- Halal and kosher certification tiers:Religious dietary compliance creates premium positioning for slaughterhouse-integrated suppliers. Manchester and Birmingham processors capture ethnic market segments.
- Veterinary medicine excipient demand:Pet pharmaceutical formulations require specialized bloom strength profiles. Companion animal health spending growth in Southeast England drives niche product development.
Industry Challenges
- Pharmaceutical-grade certification timelines:British Pharmacopoeia monograph compliance requires 18-24 month validation cycles. New entrants face capital lockup during regulatory review periods.
- Legacy rendering infrastructure modernization:Aging abattoir-linked facilities in Northern England require hydrogenation and filtration upgrades. Energy cost pressures complicate retrofit economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Gelatin Market |
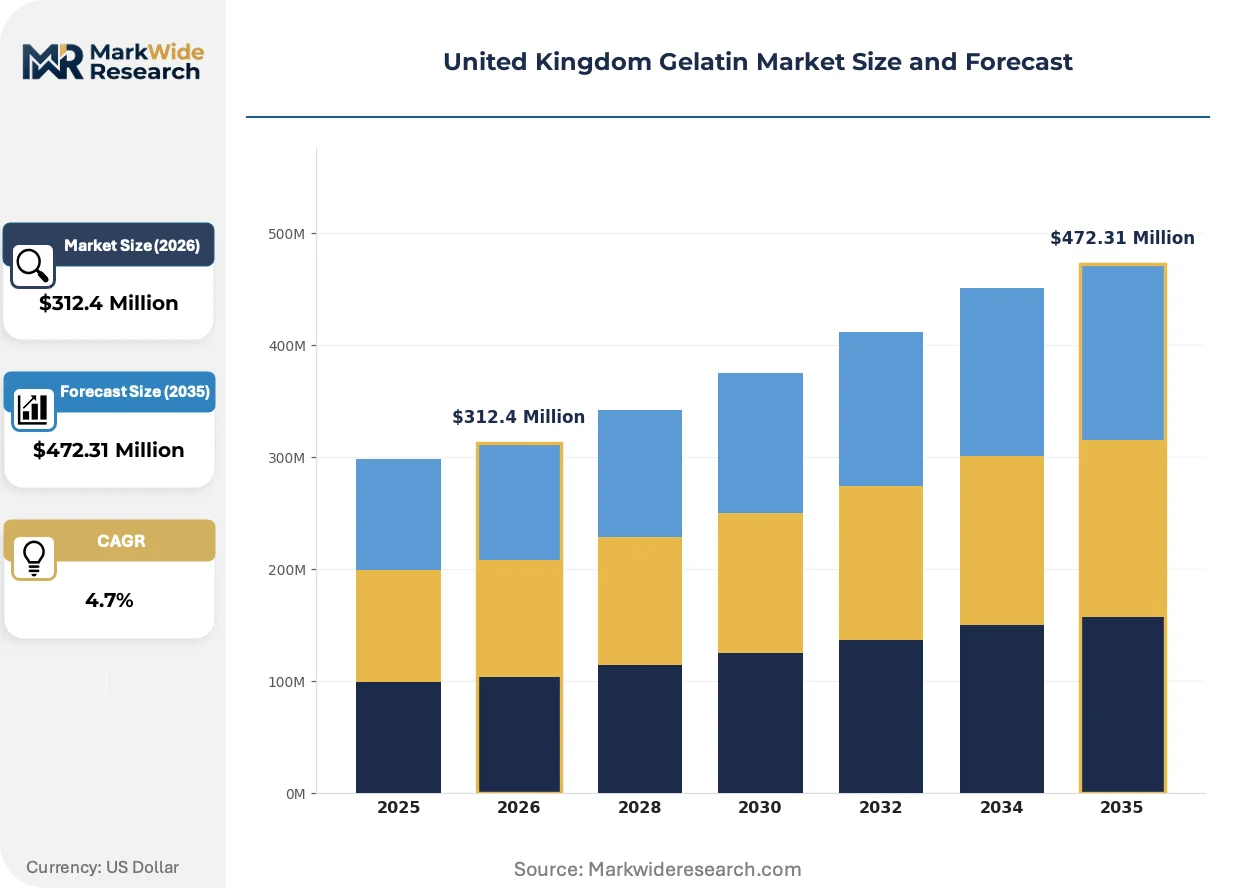
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $472.31 Million |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food Grade, Pharmaceutical Grade, Industrial Grade, Cosmetic Grade Application: Food & Beverage, Pharmaceuticals, Nutraceuticals, Personal Care Form: Powder, Granules, Sheets, Capsules End User: Food Manufacturers, Pharmaceutical Companies, Cosmetic Brands, Dietary Supplement Providers |
| Companies Covered | Darling Ingredients Inc., GELITA AG, LAPI GELATINE S.p.a., SAS Gelatines Weishardt, Trobas Gelatine BV, Ewald-Gelatine GmbH, Rousselot SAS, PB Leiner, Nitta Gelatin Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Gelatin Market Evolving Landscape
Enzymatic hydrolysis advances are compressing production cycles while the Food Standards Agency revises retained EU purity benchmarks. These parallel developments reshape technical investment priorities across the value chain.
Precision enzymatic hydrolysis is overtaking traditional acid-base processing in pharmaceutical-grade production. Facilities around Stevenage and Cambridge adopt immobilized enzyme systems to achieve tighter molecular weight distribution. This transition compresses batch-to-batch variability and reduces wastewater treatment burdens.
The Medicines and Healthcare products Regulatory Agency's updated British Pharmacopoeia monographs for gelatin excipients took effect in 2024. Pharmaceutical manufacturers must now demonstrate endotoxin levels below revised thresholds for parenteral applications. Capsule shell producers in the M11 corridor have reconfigured quality control protocols to meet these specifications.
Direct supplier relationships with artisan food producers are displacing traditional distributor intermediaries in London and Bristol. Premium bakery and confectionery operations now specify bloom strength and viscosity profiles directly with hydrolysis facilities. This channel compression rewards technical service capabilities over commodity logistics scale.
United Kingdom Gelatin Market Segmentation
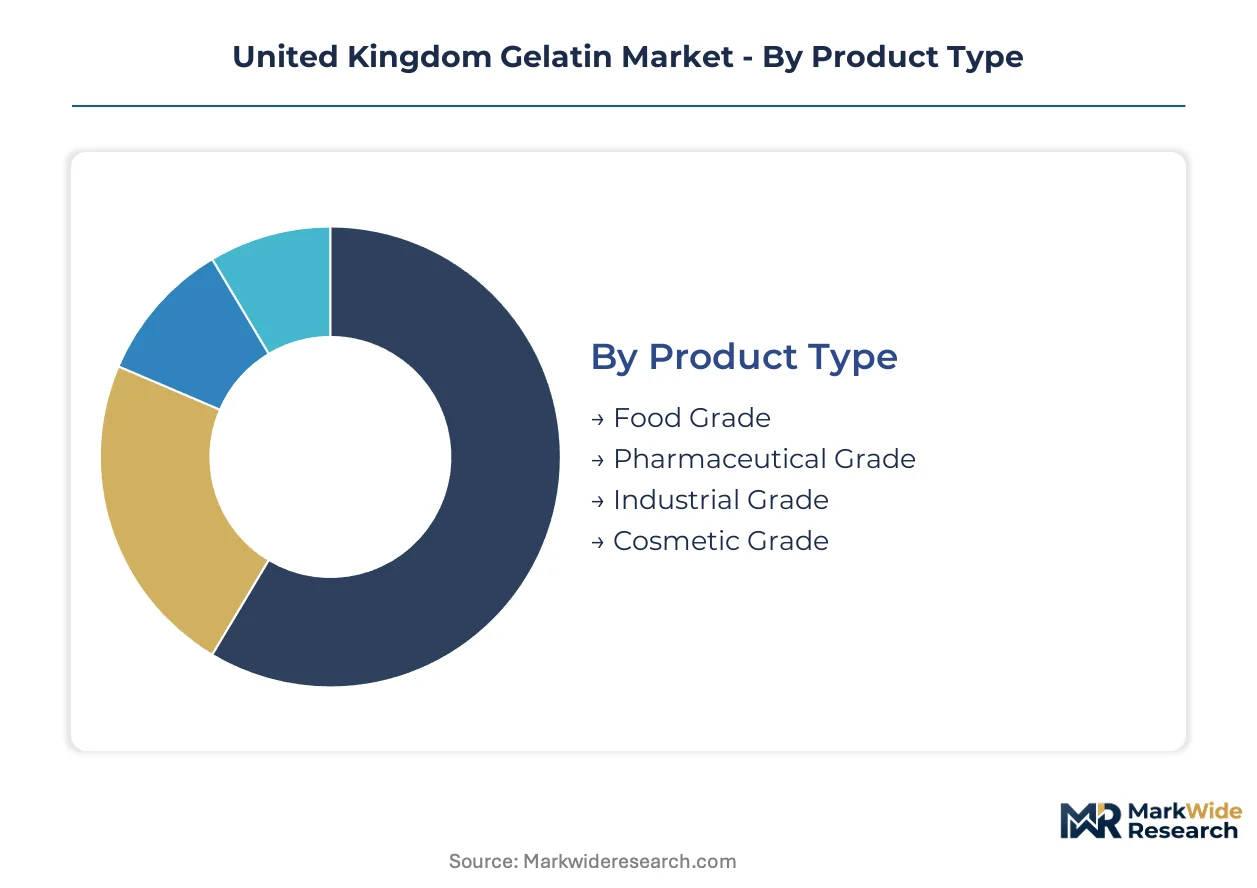
Segmentation reveals how capital deployment and regulatory compliance requirements diverge across the United Kingdom gelatin value chain. Pharmaceutical-grade specifications demand markedly different infrastructure investments than food-grade operations, shaping supplier specialization patterns.
Product Type:
Capital intensity peaks with pharmaceutical-grade hydrolysis facilities requiring endotoxin-controlled environments and British Pharmacopoeia validation infrastructure.
- Food Grade:Partially hydrolyzed collagen with bloom strength between 50 and 300 grams serves Yorkshire and Lancashire confectionery manufacturers. Standardized viscosity profiles for gummy candy production dominate volume flows, though margin compression from plant-based alternatives intensifies.
- Pharmaceutical Grade:Stringent British Pharmacopoeia monograph compliance governs capsule shell production for API formulation facilities along the M11 corridor. The Medicines and Healthcare products Regulatory Agency's tightened purity thresholds command premium positioning within NHS procurement frameworks.
- Industrial Grade:Lower-specification collagen derivatives supply photographic and adhesive applications with reduced hydrolysis investment requirements.
- Cosmetic Grade:Partially processed collagen fractions target skincare formulations with intermediate purity benchmarks between food and pharmaceutical tiers.
Most installed capacity flows through Food Grade. Expansion is steepest in Pharmaceutical Grade.
Application:
Customer procurement patterns separate commodity-scale food manufacturers from specification-driven pharmaceutical buyers with divergent technical service expectations.
- Food & Beverage:Confectionery applications in Yorkshire and Lancashire consume standardized bloom strength profiles. Gummy candy manufacturers prioritize batch-to-batch consistency over premium certifications.
- Pharmaceuticals:Capsule shell demand concentrates within the Cambridge-Stevenage corridor where API formulation facilities cluster. British Pharmacopoeia monograph compliance creates entry barriers that protect incumbent suppliers.
- Nutraceuticals:England's urban health-conscious consumers drive capsule and gummy supplement demand through dietary supplement providers specifying direct supplier relationships.
- Personal Care:Cosmetic brands in London and Bristol source specialized viscosity grades for topical formulations with reduced regulatory burden compared to pharmaceutical applications.
Volume leadership sits with Food & Beverage. Nutraceuticals climb the fastest as health-conscious consumption patterns deepen.
Form:
Logistics economics and end-use handling requirements determine processing investment allocation across physical presentation formats.
- Powder:Dominates distribution economics through bulk handling efficiency and extended shelf stability. Industrial-scale food manufacturers and pharmaceutical compounders prefer standardized particle size distributions.
- Capsules:Pre-formed gelatin shells eliminate downstream processing for pharmaceutical and nutraceutical fill-finish operations. Precise dimensional tolerances require dedicated molding infrastructure.
- Granules:Intermediate dissolution characteristics serve specialty food applications requiring controlled hydration rates.
- Sheets:Artisan food producers and premium bakery operations in London and Bristol retain entrenched positions for precise portion control and traditional preparation methods.
Most installed capacity flows through Powder. Capsules gain share fastest as pharmaceutical outsourcing expands.
End User:
Procurement sophistication tiers separate multinational pharmaceutical companies with dedicated supplier development programs from fragmented food manufacturing bases.
- Food Manufacturers:Yorkshire and Lancashire confectionery operations drive standardized volume demand with price-sensitive tender processes. Direct distributor relationships predominate.
- Pharmaceutical Companies:API formulation facilities along the M11 corridor enforce British Pharmacopoeia monograph compliance through long-term technical partnerships. The NHS procurement framework increasingly favors domestically certified excipients.
- Cosmetic Brands:London and Bristol premium skincare formulators specify intermediate purity grades with flexible batch sizing.
- Dietary Supplement Providers:England's urban centers generate capsule and gummy demand through brands specifying direct hydrolysis facility relationships, compressing traditional distribution channels.
Most installed capacity flows through Food Manufacturers. Dietary Supplement Providers expand most quickly as channel compression accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates pharmaceutical-grade gelatin capacity more densely than the United Kingdom, though England's M11 corridor narrows this gap through clustered API formulation demand. France and the Netherlands maintain strong food-grade positions. Belgium and Ireland compete on excipient certification density.
England
Pharmaceutical capsule shell demand from Stevenage and Cambridge API facilities drives premium-grade consumption. The Medicines and Healthcare products Regulatory Agency enforces British Pharmacopoeia monograph compliance through tightened endotoxin thresholds. Yorkshire and Lancashire confectionery manufacturers in Leeds and Manchester anchor food-grade volume flows.
Scotland
Underpenetrated pharmaceutical manufacturing creates greenfield facility opportunities for food-grade diversification. Scottish Enterprise incentive schemes support rendering and hydrolysis infrastructure investment. Glasgow and Edinburgh dietary supplement brands increasingly specify direct supplier relationships with hydrolysis facilities.
Wales
Devolved administration funding targets food-grade production expansion in underrepresented UK regions. The Welsh Government's Advanced Manufacturing Sector Strategy prioritizes collagen processing capabilities. Cardiff and Newport zones attract contract formulation services seeking lower operational costs than England's core corridor.
Northern Ireland
Post-Brexit regulatory alignment discussions with the Republic of Ireland create dual-market access complexity for gelatin suppliers. The Department of Agriculture, Environment and Rural Affairs maintains veterinary traceability requirements. Belfast rendering operations serve cross-border pharmaceutical and food manufacturers with specialized documentation protocols.
United Kingdom Gelatin Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with pharmaceutical-grade concentration favoring long-tenured incumbents and food-grade permitting fragmented regional competition. Three tiers emerge: multinational excipient suppliers with British Pharmacopoeia validation infrastructure, mid-scale European processors leveraging geographic proximity, and domestic contract manufacturers serving artisan food producers. Consolidation pressure concentrates among pharmaceutical-grade specialists seeking endotoxin-controlled capacity, while food-grade competition intensifies through plant-based substitution threats.
Among Germany-based gelatin specialists, GELITA AG occupies a position exemplifying technical center investment for sustained supply agreements. Darling Ingredients Inc. represents North American backward integration archetypes securing raw material access through rendering network control. Rousselot SAS anchors French pharmaceutical-grade positioning through specialized certification tiers commanding premium NHS procurement placement.
| Leading Market Players |
|---|
| Darling Ingredients Inc. |
| GELITA AG |
| LAPI GELATINE S.p.a. |
| SAS Gelatines Weishardt |
| Trobas Gelatine BV |
| Ewald-Gelatine GmbH |
| Rousselot SAS |
| PB Leiner |
| Nitta Gelatin Inc. |
| Others |
Value Network & Pricing Analysis
Bovine rendering costs cascade through three certification tiers, with pharmaceutical-grade British Pharmacopoeia compliance commanding premium positioning against food-grade commodity benchmarks. Abattoir-linked processors in England's Midlands translate raw material volatility into contract structures that shift margin risk downstream.
Pricing Analysis
Capacity additions in Wales and Scotland are reshaping price floors for food-grade gelatin, compressing spreads against pharmaceutical-grade tiers. Three-tier pricing structure across pharmaceutical, food, and industrial grades separates British Pharmacopoeia-certified excipients from standard confectionery inputs. Pricing pressure stems from plant-based hydrocolloid substitution in Yorkshire and Lancashire gummy manufacturing. Food manufacturers exhibit highest price sensitivity through tender-based procurement, while NHS framework buyers prioritize domestic certification over unit cost.
Supply Chain Analysis
Reverse-logistics flows for pharmaceutical-grade gelatin involve endotoxin-controlled returns and reprocessing protocols that extend batch documentation chains. Raw material sourcing draws from England's abattoir network, Irish rendering facilities, and Commonwealth bovine operations under Veterinary Medicines Directorate traceability rules. Supply chain risk centers on BSE-related geographic restrictions that limit eligible Commonwealth origins. Distribution runs through Manchester technical centers for pharmaceutical accounts and direct hydrolysis facility relationships for artisan food producers in London and Bristol.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United Kingdom gelatin market compounds steadily as pharmaceutical-grade capsule demand from the Cambridge-Stevenage corridor anchors long-term offtake. Nutraceutical formulation expansion reinforces volume growth independent of food-grade substitution pressures.
For Market Incumbents: Anticipate enzymatic hydrolysis capital cycles by securing immobilized enzyme system partnerships before British Pharmacopoeia monograph updates tighten purity thresholds. Defend NHS procurement positioning through Manchester technical center investment. Prioritize backward integration into rendering operations to buffer abattoir output volatility. For New Entrants and Emerging Players: Launch via direct supplier relationships with dietary supplement providers in England's urban centers, bypassing traditional distributor intermediaries. Target Scottish and Welsh greenfield food-grade production under devolved administration incentive schemes. Capture halal and kosher certification premiums through Manchester and Birmingham slaughterhouse integration. For Investors and Strategic Acquirers: Consolidation pressure builds where pharmaceutical-grade endotoxin-controlled capacity concentrates among long-tenured incumbents. Five-to-ten year viability favors British Pharmacopoeia-validated specialists with NHS framework placement. Monitor divergence between UK and EU regulatory alignment negotiations as inflection signal for cross-border certification cost structures.| Strategic Initiative | Industry Significance |
|---|---|
| Pharmaceutical-Grade Certification Investment | British Pharmacopoeia monograph compliance secures NHS procurement framework access against EU competitors. |
| Backward Integration into Rendering | Abattoir network control in England's Midlands buffers raw material cost volatility from livestock cycles. |
| Enzymatic Hydrolysis Technology Adoption | Immobilized enzyme systems around Stevenage compress batch variability for parenteral-grade excipient production. |
| Halal and Kosher Certification Tiers | Manchester and Birmingham processors capture premium positioning in ethnic market segments with religious dietary compliance. |
| Scottish and Welsh Manufacturing Expansion | Devolved administration incentive schemes support food-grade diversification outside England's core pharmaceutical corridor. |
Research Methodology
Coverage spans England, Scotland, Wales, and Northern Ireland, with primary inputs from each devolved regulatory jurisdiction. The approach combines interviews with pharmaceutical procurement managers at NHS trusts, technical directors at hydrolysis facilities, regulatory affairs leads at excipient suppliers, and category buyers at Yorkshire and Lancashire confectionery manufacturers. Secondary validation draws from British Pharmacopoeia monograph updates, Veterinary Medicines Directorate traceability guidance, Food Standards Agency compositional standards, and MHRA pharmaceutical excipient filings. Bottom-up facility capacity assessments triangulate against top-down demand modeling from end-use consumption patterns.
Segmentation granularity extends to pharmaceutical grade versus food grade versus industrial grade, powder versus capsule versus sheet form, and Cambridge-Stevenage corridor versus rest-of-England versus Celtic nations geography. CAGRs derive from regression analysis against pharmaceutical production indices, livestock cycle data, and nutraceutical consumption surveys. Forecast inputs incorporate NHS procurement framework shifts, post-Brexit regulatory divergence scenarios, and enzymatic hydrolysis adoption curves across the projection horizon.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt EU-UK regulatory misalignment or livestock disease outbreak conditions. Practitioners should monitor MHRA-European Medicines Agency divergence negotiations, abattoir capacity utilization in England's Midlands, and plant-based hydrocolloid substitution rates in premium confectionery for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Oak Extract Market
Ingredients
Botanical Extracts Market
Ingredients
Dry Blended Products Market
Ingredients
Vegetable Extract Market
Ingredients
Caramel Ingredient Market
Ingredients
Middle East Feed Palatability Enhancers Market
Ingredients
Philippines Edible Oils & Fats Market
Ingredients
Rose Hips Extract Market
Ingredients
Food Ingredients Market
Ingredients
North America Gluten Free Flour Market
Ingredients
Xylooligosaccharide Market
Ingredients
Cocoa Maker Market
Ingredients
Textured Milk Protein Market
Ingredients
Liquid Feed Market
Ingredients
Sunflower Protein Market
Ingredients
Amylase Market