
 Nigeria Used Car Market | 2026-2036
Nigeria Used Car Market Size, Share, and Industry Trends Forecast 2026-2036
Nigeria Used Car Market Insights
Nigeria's vehicle emissions and safety standards under SON oversight is rebalancing import flows toward newer used vehicle cohorts. Toyota leverages its spare parts density across West African corridors to sustain aftermarket loyalty among second-hand buyers. Autochek anchors digital financing penetration by embedding credit scoring into used vehicle transactions. Honda competes on fuel efficiency reputation within the informal transport sector.
A used car denotes a previously registered automobile transferred to a subsequent owner, typically assessed by odometer reading, service history, and structural integrity prior to resale; these vehicles serve price-sensitive mobility demand where new vehicle taxation and currency volatility inflate showroom costs beyond mass-market reach. Sedan and SUV categories dominate transaction volumes through Lagos ports, reflecting family transport and commercial fleet replacement cycles. Certified Pre-Owned and Non-Certified conditions split the market between warranty-backed dealership inventory and informal roadside transactions, with margin pools concentrating in refurbishment and documentation services. Online Platforms are displacing traditional auction yards by aggregating inspection data and payment escrow for distant buyers.
Nigeria's National Automotive Design and Development Council (NADDC) guidelines interact with SON import age restrictions to filter eligible vehicle vintages, while the Central Bank of Nigeria's foreign exchange policies shape dollar-denominated landing costs. The country's national automotive regulator enforces local content benchmarks that nibble at assembly incentives without yet displacing import dependency. Stakeholders must monitor how digital platform compliance with consumer protection frameworks evolves alongside physical inspection standards.
Market Dynamics
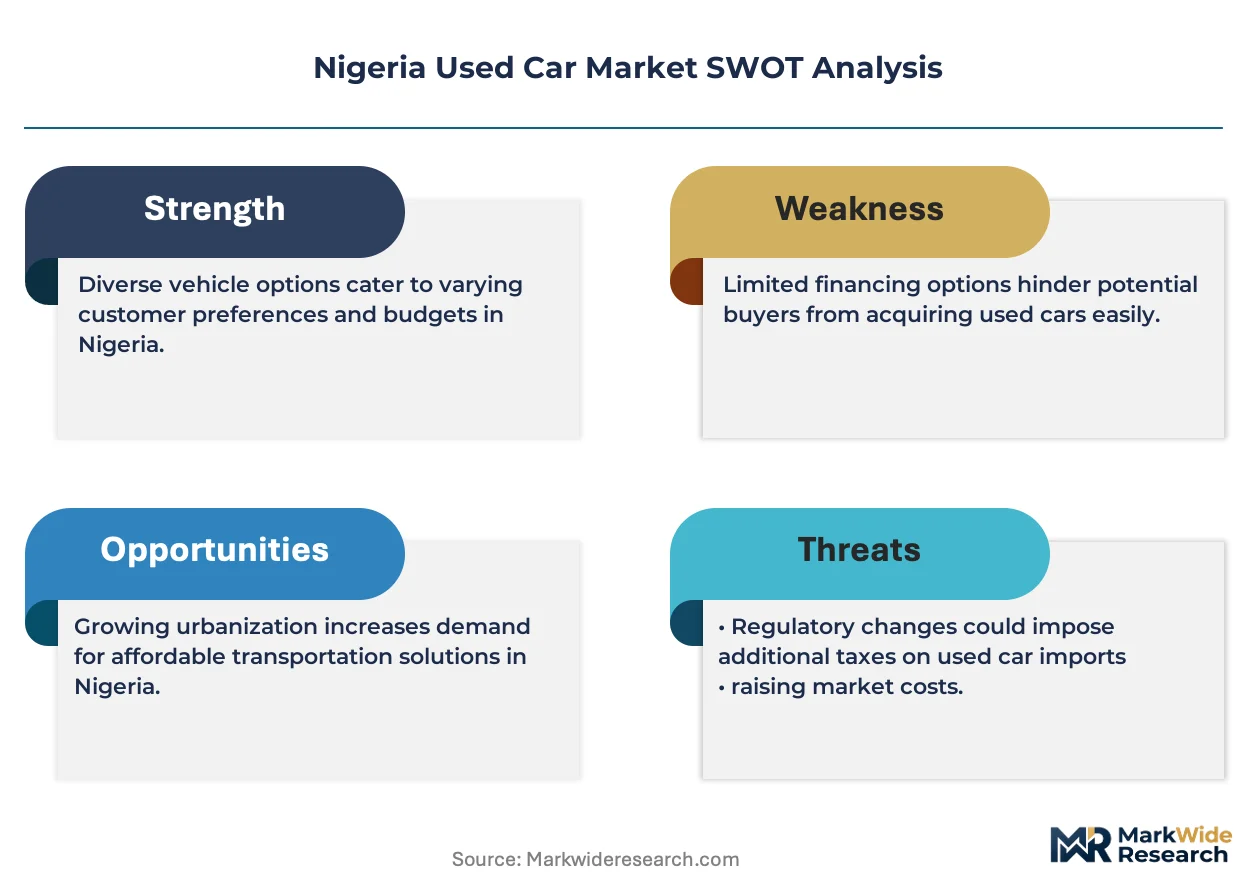
Nigeria's foreign exchange illiquidity is compressing new vehicle imports and redirecting household and fleet budgets toward pre-owned alternatives, while SON age-limit enforcement filters eligible inventory toward newer vintages.
Growth Catalysts
- Ride-hailing fleet expansion:Lagos and Abuja operators are scaling pre-owned vehicle procurement to manage operational cost pressures against currency-driven new-car price inflation.
- SON import age restrictions:The Standards Organisation of Nigeria's enforcement of vehicle age limits is redirecting buyer attention toward certified refurbishment channels with compliant inventory.
- Digital financing penetration:Embedded credit scoring platforms are unlocking transaction liquidity for buyers previously excluded from formal automotive lending.
Market Restraints
- Foreign exchange volatility:Central Bank of Nigeria dollar access constraints inflate landing costs for all imported units, compressing dealer margins and consumer affordability.
- Spare parts supply concentration:West African aftermarket distribution clusters in Lagos port corridors, creating inland logistics bottlenecks for northern and eastern states.
- Fuel subsidy removal:Federal government pricing reforms are elevating total cost of ownership for older, less efficient vehicle cohorts in the informal transport sector.
Strategic Opportunities
- Certified refurbishment networks:Structured inspection and warranty programs can capture margin pools currently lost to informal roadside transactions.
- North Nigerian geographic expansion:Kano and Kaduna urban corridors remain underserved by digital platforms and formal financing infrastructure.
- Autogas conversion services:Compressed natural gas retrofitting offers cost arbitrage against petrol price volatility for commercial fleet operators.
Industry Challenges
- Technical inspection standardization:Inconsistent odometer verification and structural assessment protocols across Lagos ports and inland markets erode buyer confidence.
- Documentation fraud:Title washing and falsified service histories complicate due diligence for distant buyers on digital platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nigeria Used Car Market |
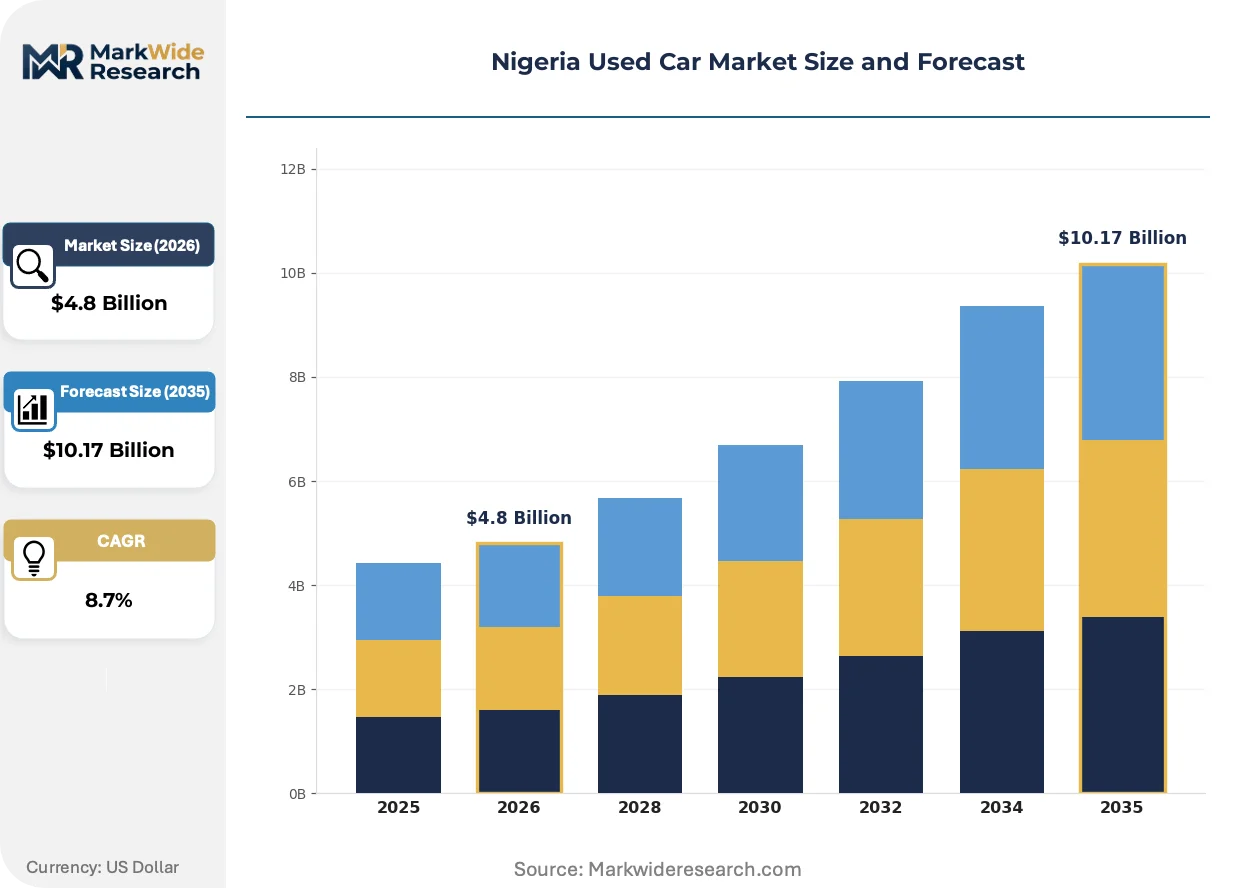
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Sedan, SUV, Hatchback, Truck Condition: Certified Pre-Owned, Non-Certified, Salvage, Refurbished Fuel Type: Petrol, Diesel, Electric, Hybrid Seller Type: Dealerships, Private Sellers, Auctions, Online Platforms |
| Companies Covered | Toyota, Honda, Lexus, Mercedes-Benz, BMW, Hyundai, Kia, Ford, Autochek, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nigeria Used Car Market Trends and Innovations
Digital infrastructure is rewiring how Nigerian buyers discover, inspect, and finance pre-owned vehicles, compressing information asymmetries that historically favored physical auction yards and roadside dealers.
Telematics-enabled vehicle monitoring is expanding into commercial fleet management as Lagos-based ride-hailing operators deploy GPS tracking and engine diagnostics to optimize utilization and residual value forecasting. Fleet managers are adopting these systems at accelerating rates to reduce maintenance surprises and support asset-backed financing structures. The technology is expanding into informal transport cooperatives, enabling micro-fleet owners to access credit previously reserved for formal corporate borrowers.
NADDC local content guidelines are interacting with SON import regulations to reshape eligible vehicle sourcing patterns, as assembly incentives nibble at import dependency without yet displacing it. The Standards Organisation of Nigeria's enforcement mechanisms are tightening documentation requirements at Lagos and Port Harcourt entry points. Commercial importers are responding by consolidating around newer model years that satisfy both age restrictions and emerging emissions benchmarks.
Aggregator platforms are unbundling the traditional dealership role by separating discovery, inspection, payment escrow, and financing into discrete digital services. Lagos State buyers are migrating from physical auction yards to mobile-first marketplaces that aggregate condition reports and enable remote transaction completion. Northern Nigerian demand corridors remain platform-underserved, preserving traditional broker networks in Kano and Kaduna trading clusters.
Nigeria Used Car Market Segmentation
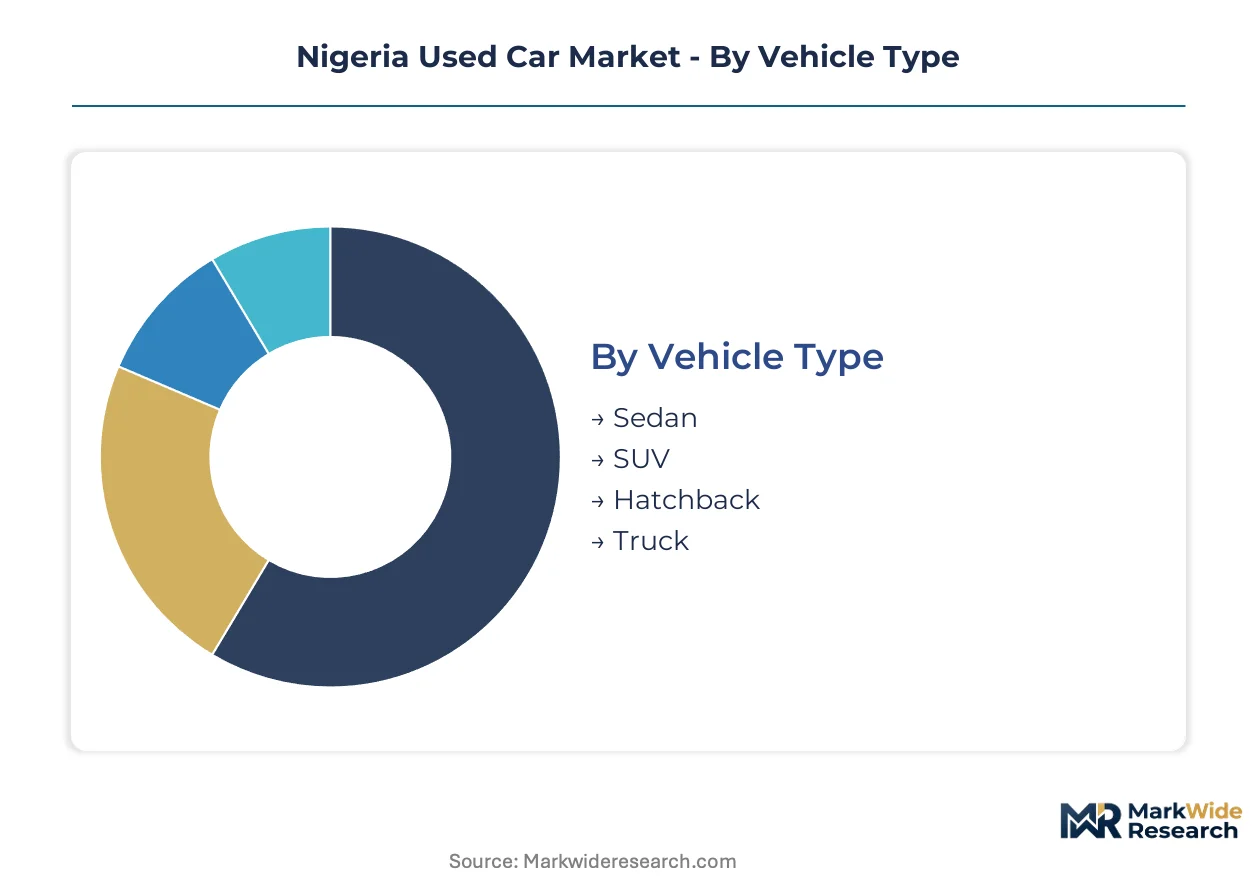
Nigeria's used car market fragments across vehicle specifications, transaction channels, and powertrain technologies. Each segmentation axis carries distinct margin structures, buyer risk profiles, and regulatory exposure that shape competitive positioning.
Vehicle Type:
Sedan and SUV architectures dominate Lagos port flows, with chassis specifications determining fleet utility and family transport suitability.
- Sedan:Three-box passenger configurations with enclosed cargo compartments attract family buyers prioritizing fuel economy for urban commuting. Lagos State households concentrate demand here, balancing purchase affordability against petrol price volatility following federal subsidy removal.
- SUV:Elevated ride height and expanded cabin volume command premium pricing for commercial fleet operators navigating degraded road infrastructure. Northern Nigerian transport cooperatives favor these platforms for passenger volume and durability on intercity routes.
- Hatchback:Compact two-box designs with integrated cargo access serve price-sensitive first-time buyers and urban delivery services.
- Truck:Light commercial chassis with open or enclosed beds support logistics and informal trade across Lagos-Abuja freight corridors.
SUV leads on scale; sedan leads on momentum.
Condition:
Certification status determines warranty backing, price tier, and buyer due diligence requirements across formal and informal transaction channels.
- Certified Pre-Owned:Dealer-backed inspection protocols with limited warranty coverage reduce information asymmetry for risk-averse buyers. SON age-limit enforcement is redirecting procurement toward these channels as compliant inventory concentrates in refurbishment networks.
- Non-Certified:Unwarranted transactions through roadside brokers and informal yards dominate volume but expose buyers to odometer fraud and hidden structural damage.
- Salvage:Insurance-totaled vehicles requiring substantial reconstruction circulate through specialized trading clusters with minimal documentation.
- Refurbished:Systematic mechanical and cosmetic restoration programs are capturing margin pools previously lost to informal resale.
Non-Certified leads on scale; Certified Pre-Owned leads on momentum.
Fuel Type:
Powertrain selection interacts with federal pricing policy, aftermarket infrastructure density, and total cost of ownership calculations for commercial operators.
- Petrol:Spark-ignition engines with established spare parts networks across West African distribution corridors sustain dominant market presence. Toyota's aftermarket density reinforces loyalty among second-hand petrol buyers in Lagos and Abuja.
- Diesel:Compression-ignition platforms with superior torque characteristics attract heavy-duty commercial users despite higher acquisition costs.
- Electric:Battery-electric drivetrains face charging infrastructure scarcity and grid reliability constraints that limit penetration.
- Hybrid:Dual-powertrain systems combining petrol engines with electric assist offer fuel economy advantages where Honda's efficiency reputation competes for informal transport sector share.
Petrol leads on scale; hybrid leads on momentum.
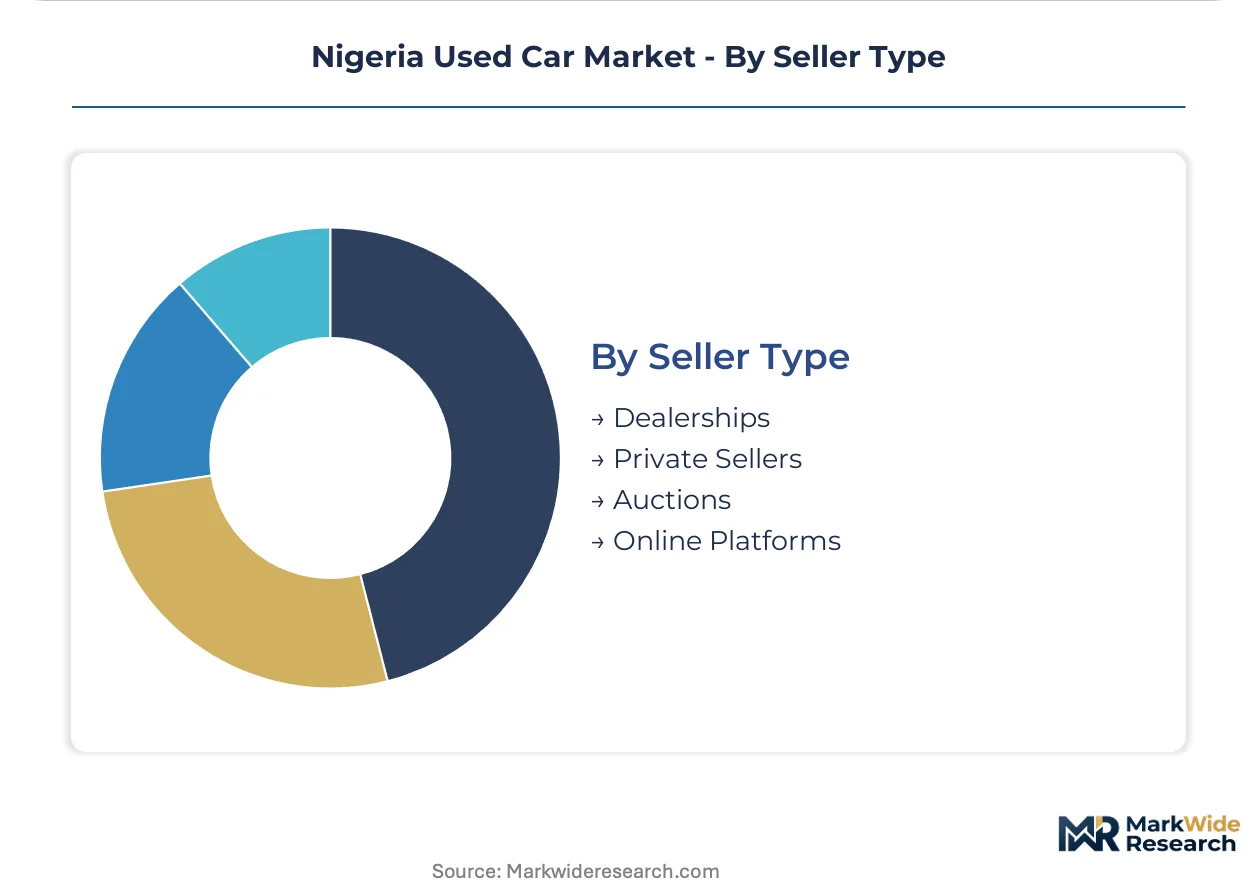
Seller Type:
Transaction channel selection shapes price transparency, financing access, and documentation reliability for buyers across Nigeria's geographic corridors.
- Dealerships:Brick-and-mortar operations with physical inventory and formal registration support concentrate in Lagos State port proximity. These channels embed Autochek financing partnerships to unlock credit for buyers excluded from traditional automotive lending.
- Private Sellers:Direct owner-to-buyer transfers through informal networks dominate northern and eastern states with limited platform penetration.
- Auctions:Physical bidding yards face displacement as digital infrastructure compresses information advantages previously held by onsite inspection.
- Online Platforms:Mobile-first marketplaces aggregating condition reports and payment escrow are capturing Lagos demand from traditional auction channels.
Private sellers lead on scale; online platforms lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Nigeria's used car trade originated in Lagos port corridors during the 1970s oil boom, when import liberalization established vehicle re-export networks across West Africa. Decades of exchange rate volatility and regulatory evolution have concentrated transaction infrastructure in southern coastal states while fragmenting northern supply chains.
Lagos State
Lagos anchors national transaction volume through Apapa and Tin Can Island port complexes, where SON inspection facilities filter compliant inventory. The state's cluster of digital financing platforms and refurbishment workshops draws procurement budgets from ride-hailing fleets and household buyers. Lagos State vehicle registration authorities process the majority of national title transfers.
Federal Capital Territory
Abuja's administrative class generates premium-tier demand for certified pre-owned SUVs and sedans serving diplomatic and government contractor mobility needs. NADDC policy coordination with federal transport regulators shapes fleet procurement standards that cascade to neighboring states. The territory's concentrated purchasing power supports dedicated dealership networks absent in comparable population centers.
Kano State
Kano's position as northern Nigeria's commercial hub sustains informal trading clusters for non-certified vehicles arriving via overland routes from neighboring countries. The state's transport cooperatives prioritize durable SUV platforms for intercity passenger services across degraded road infrastructure. Kano's spare parts markets function as redistribution nodes for Sahelian demand corridors.
Rivers State
Port Harcourt's oil sector employment base supports steady replacement demand for pickup trucks and light commercial vehicles serving energy logistics contractors. SON enforcement at Onne and Port Harcourt terminals redirects import flows toward newer vintages compliant with age restrictions. The state's vehicle financing penetration lags Lagos but exceeds northern averages.
Oyo State
Ibadan's manufacturing heritage and educational institutions create segmented demand spanning economy sedans for faculty transport and refurbished commercial vehicles for agricultural logistics. The state's position on the Lagos-Kano transit corridor positions it as a secondary redistribution point for inland markets. Oyo's independent refurbishment workshops compete with Lagos-based certified networks on price.
Nigeria Used Car Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification and financing integration dimensions, with warranty-backed inventory commanding substantial price premiums over informal roadside transactions. The market structure fragments across three tiers: multinational brand networks with official pre-owned programs, digital platforms embedding credit infrastructure, and decentralized broker-dealers reliant on cash transactions. Strategic archetypes include OEM-authorized refurbishment specialists, fintech-integrated aggregators, and regional parts-and-service bundlers. Dominant competitive moves center on backward integration into inspection standardization and geographic expansion into underserved northern corridors.
Among Japanese OEMs with established West African aftermarket density, Toyota and Honda exemplify divergent positioning archetypes—Toyota anchoring spare parts availability loyalty while Honda competes on fuel efficiency reputation within informal transport segments. Autochek occupies the fintech-integrated tier, representing how embedded credit scoring can unlock transaction liquidity previously excluded from formal automotive lending. These three entities illustrate how brand heritage, aftermarket infrastructure, and financing innovation respectively define competitive differentiation in a market where documentation reliability and total cost of ownership calculations dominate purchase decisions.
| Leading Market Players |
|---|
| Toyota |
| Honda |
| Lexus |
| Mercedes-Benz |
| BMW |
| Hyundai |
| Kia |
| Ford |
| Autochek |
| Others |
Pricing and Supply Chain Analysis
Brent crude benchmarks cascade through Nigerian used car pricing tiers via fuel cost-of-ownership calculations and landing cost inflation, compressing margins on older petrol-intensive cohorts while elevating certified hybrid premiums. Central Bank of Nigeria dollar illiquidity amplifies this commodity linkage by inflating naira-denominated acquisition costs for all imported inventory.
Pricing Analysis
Three-tier pricing structure across certified pre-owned, non-certified dealer, and informal roadside segments dominates transaction economics. Certification grade and spare parts availability density drive price differentiation, with Toyota platforms commanding premiums in Lagos due to aftermarket infrastructure concentration. Pricing pressure stems from foreign exchange volatility eroding dealer margins on dollar-denominated imports. Informal transport cooperatives exhibit highest price sensitivity; diplomatic fleet buyers in Abuja show lowest.
Supply Chain Analysis
Dual-sourcing requirements from ride-hailing fleet buyers mandate multi-port qualification across Lagos Apapa and Port Harcourt Onne terminals to mitigate single-point inspection bottlenecks. Supply draws from United States, United Arab Emirates, and European export markets for compliant vintage inventory. Component dependencies span engine assemblies, transmission systems, and telematics hardware. Tariff exposure at West African port corridors presents structural risk. Distribution runs through Lagos-based refurbishment networks with northern redistribution via Kano trading clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through certified refurbishment network buildout, capturing value pools currently lost to informal transactions while SON compliance requirements filter demand toward quality-tier inventory.
For Market Incumbents: Acquire inspection standardization capabilities to defend against documentation fraud erosion of buyer confidence. Consolidate around newer vintage procurement that satisfies both SON age restrictions and emerging emissions benchmarks. Backward integration into spare parts warehousing secures aftermarket loyalty against Honda fuel-efficiency competition. For New Entrants and Emerging Players: Launch via mobile-first marketplace models targeting Kano and Kaduna demand corridors underserved by digital financing infrastructure. Penetrate northern Nigerian geographic whitespace through embedded credit scoring partnerships with local transport cooperatives. Autogas conversion service bundling offers differentiated fleet value proposition against petrol price volatility. For Investors and Strategic Acquirers: Asymmetric upside sits with fintech-integrated platform archetypes combining condition aggregation with credit infrastructure. Long-term viability hinges on regulatory compliance automation as SON enforcement tightens. Watch telematics penetration rates in informal transport cooperatives as inflection indicator for asset-backed financing scalability.| Strategic Initiative | Industry Significance |
|---|---|
| Certified Refurbishment Network Expansion | Captures margin pools from SON age-limit compliance redirecting buyer flows. |
| Embedded Credit Scoring Integration | Unlocks transaction liquidity for buyers excluded from formal automotive lending. |
| Telematics Fleet Deployment | Enables asset-backed financing structures for informal transport cooperatives. |
| Autogas Conversion Service Launch | Offers cost arbitrage against federal petrol subsidy removal pricing pressure. |
| Northern Geographic Platform Expansion | Addresses Kano-Kaduna whitespace before traditional broker networks digitize. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with used car dealership operators, ride-hailing fleet procurement managers, refurbishment workshop owners, and SON compliance officers with secondary validation against customs import records, vehicle registration databases, and Central Bank of Nigeria foreign exchange policy filings. Bottom-up transaction volume estimates triangulated against top-down macroeconomic consumption models.
Segment-weighting approaches applied across vehicle type, condition tier, fuel architecture, and seller channel dimensions throughout the forecast period. CAGRs derived from historical trajectory analysis adjusted for regulatory inflection points and platform penetration curves. Model inputs incorporated port throughput data, naira exchange rate volatility bands, and telematics adoption rates in commercial fleet segments.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sustained foreign exchange illiquidity or accelerated SON enforcement escalation. Deviation in Central Bank dollar access policy would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Used Vehicles
South Korea Used Car Market
Used Vehicles
Brazil Used Car Market
Used Vehicles
New Zealand Used Car Market
Used Vehicles
United Arab Emirates Used Car Market
Used Vehicles
Poland Used Car Market
Used Vehicles
North America Used Truck Market
Used Vehicles
Myanmar Used Car Market
Used Vehicles
Netherlands Used Car Market
Used Vehicles
Vietnam Used Car Market
Used Vehicles
Germany Used Car Market
Used Vehicles
Ethiopia Used Car Market
Used Vehicles
Used Semi Truck Market
Used Vehicles
Switzerland Used Car Market
Used Vehicles
Norway Used Car Market
Used Vehicles
Australia Used Car Market
Used Vehicles
Used Cars in Russia Market