
 Embedded Multimedia Card Market | 2026-2036
Embedded Multimedia Card Market Size, Share, and Industry Trends Forecast 2026-2036
Embedded Multimedia Card Market Intelligence
Flash memory engineering talent scarcity is reorganizing competitive dynamics across the Embedded Multimedia Card landscape. Samsung Electronics leverages captive 3D NAND fabrication to anchor premium eMMC supply chains. SK Hynix sustains cost competitiveness through vertical integration into DRAM and NAND wafer production. Phison Electronics specializes in controller IC design, differentiating its offerings against integrated device manufacturers.
An embedded multimedia card combines NAND flash memory with a controller in a single ball grid array package, typically operating at interface speeds up to HS400 for eMMC 5.1 or UFS 3.1 specifications, and serves as non-volatile storage for systems with severe space, power, and reliability constraints. eMMC products dominate volume shipments in budget smartphones and industrial gateways where cost sensitivity outweighs performance requirements, while UFS interfaces capture expanding share in automotive infotainment modules demanding faster sequential read speeds. Consumer Electronics remains the largest end user category by unit volume, though Automotive applications generate superior margin pools due to extended qualification cycles and AEC-Q100 compliance overhead.
South Korea's Ministry of Trade, Industry and Energy coordinates national semiconductor investment incentives that directly expand local eMMC and UFS manufacturing capacity. China's MIIT enforces GB standard certification for storage components in critical infrastructure, shaping product design requirements for domestic and export-bound suppliers. The EU's RoHS and REACH frameworks restrict hazardous substances in electronic assemblies, compelling reformulation of solder ball compositions and encapsulant materials. Stakeholders must monitor evolving automotive functional safety standards and regional content requirements as determinants of manufacturing location decisions and qualification timelines.
Market Dynamics
Automotive OEMs are consolidating storage procurement around qualified eMMC and UFS suppliers capable of meeting AEC-Q100 reliability mandates and China's MIIT data-retention requirements simultaneously.
Growth Catalysts
- Automotive ADAS integration:Camera and radar modules require high-reliability flash storage for real-time data logging. OEMs specify eMMC 5.1 and UFS 3.1 for infotainment head units across production lines.
- China MIIT connected-vehicle mandates:Stricter GB standard certification for storage components in critical infrastructure expands addressable demand for domestic-qualified suppliers.
- South Korea Pyeongtaek cluster concentration:Government-backed semiconductor investment incentives under the Ministry of Trade, Industry and Energy expand captive 3D NAND fabrication capacity serving regional module assembly.
Market Restraints
- NAND flash wafer supply concentration:Three fabrication clusters control upstream die output, creating allocation risk during technology transition cycles.
- AEC-Q100 qualification overhead:Extended automotive certification timelines delay revenue recognition and freeze out suppliers lacking capital reserves.
- UFS interface substitution pressure:Higher-performance automotive modules are displacing eMMC sockets in premium vehicle segments.
Strategic Opportunities
- Industrial IoT gateway expansion:Edge computing nodes in manufacturing facilities require cost-optimized eMMC for firmware and configuration storage.
- India PLI scheme electronics manufacturing:Production-linked incentives for semiconductor assembly and testing attract module packaging investment.
- EU RoHS material reformulation:REACH-compliant encapsulant and solder ball compositions create first-mover advantage for qualified European suppliers.
Industry Challenges
- Flash memory controller engineering scarcity:Mixed-signal design expertise for high-speed interface PHY layers concentrates among experienced semiconductor firms.
- Dual automotive-functional-safety certification:ISO 26262 compliance alongside AEC-Q100 extends development cycles and requires dedicated quality systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Embedded Multimedia Card Market |
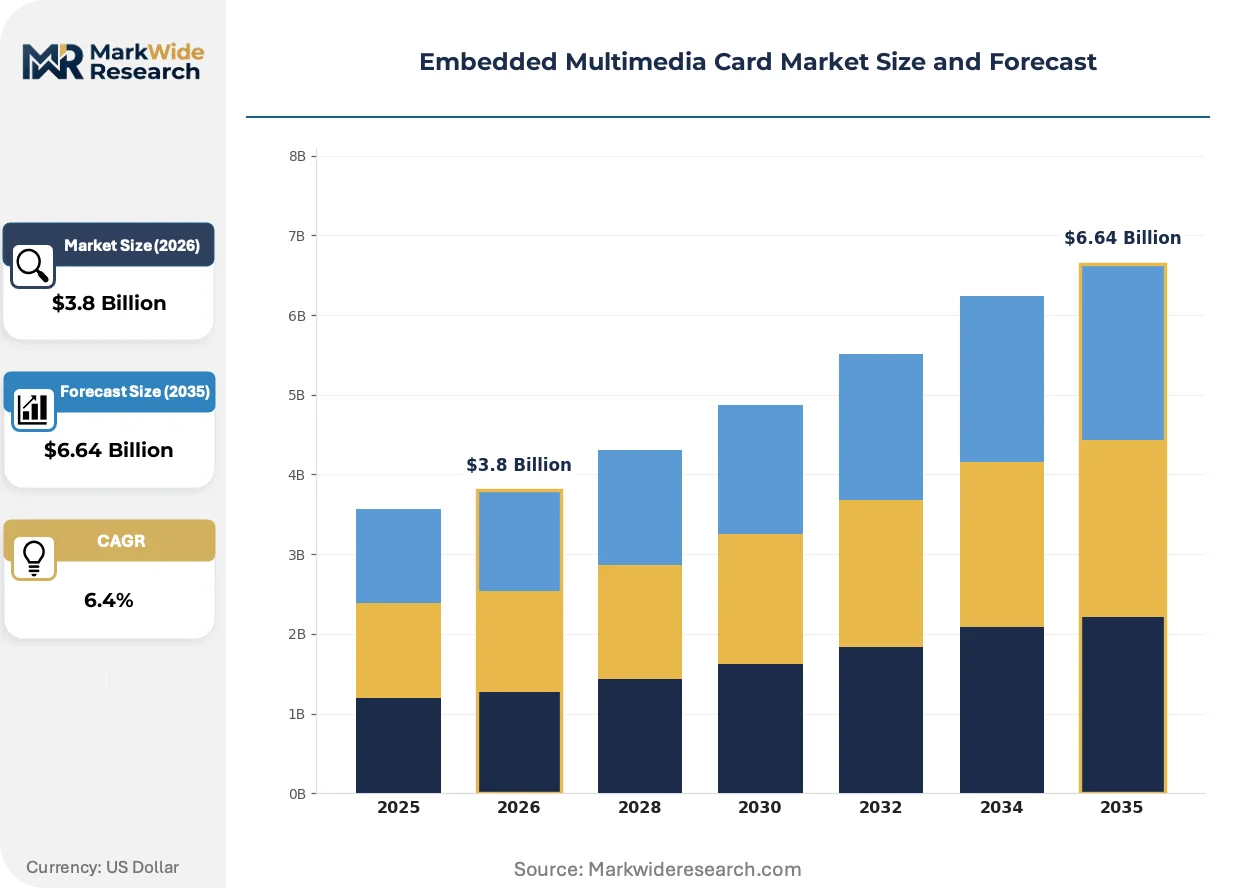
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: SD Memory Card, MicroSD Card, eMMC, UFS Technology: NAND Flash, DRAM, 3D NAND, SLC End User: Consumer Electronics, Automotive, Industrial, Healthcare Installation: Embedded, Removable, Integrated, Onboard |
| Companies Covered | SK Hynix, Kingston Technology, Samsung Electronics, Silicon Motion Technology, Phison Electronics, Micron Technology, Kioxia, Transcend Information, Western Digital, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Embedded Multimedia Card Market Strategic Shifts & Innovations
Controller architecture evolution and interface specification advancement are compressing form factors while expanding addressable temperature and vibration envelopes for embedded storage.
Multi-chip package stacking is miniaturizing eMMC footprints while maintaining HS400 interface speeds. Automotive tier-1 suppliers are adopting 11.5x13mm BGA packages for space-constrained camera modules. This miniaturization is enabling single-board computer designs in industrial drones and medical wearables.
China's MIIT enforcement of GB standard certification for storage components in connected vehicles is forcing design modifications. Domestic suppliers must implement enhanced error-correction and extended data-retention algorithms. Export-bound manufacturers serving Chinese OEMs are establishing parallel qualification tracks to maintain market access.
Long-term supply agreements are replacing spot-market NAND procurement for automotive-qualified eMMC. Tier-1 electronics manufacturing services firms are negotiating die-bank reservations directly with fabrication operators. This pattern is most pronounced in South Korea, where Hyundai Mobis and Samsung SDS coordinate captive supply arrangements.
Embedded Multimedia Card Market Segmentation
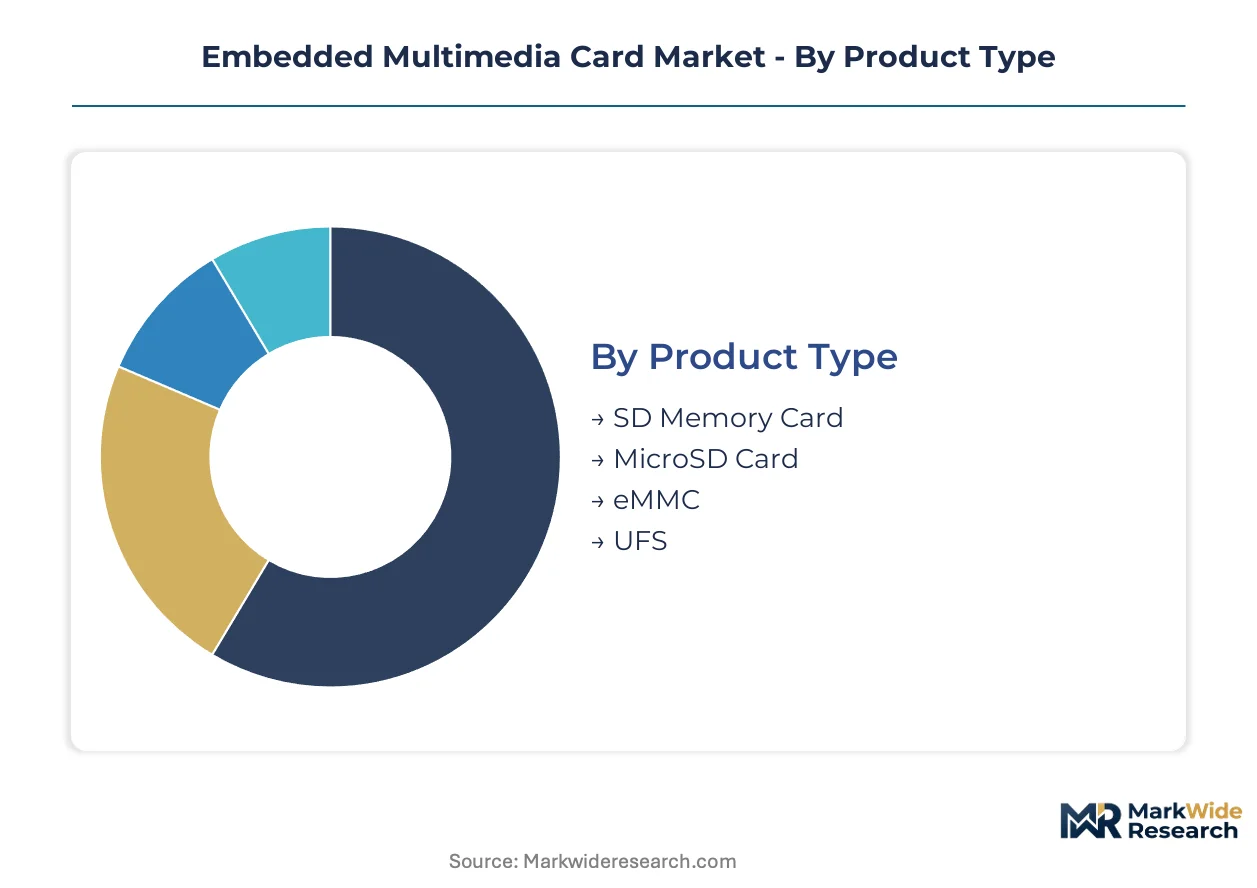
eMMC and UFS specifications diverge sharply across application environments, with interface speed requirements and qualification overhead determining supplier selection. NAND flash cell architecture and controller integration depth create tiered performance bands that map directly to end-use reliability mandates.
Product Type:
Margin pools concentrate in automotive-qualified UFS modules where AEC-Q100 certification creates supply scarcity.
- SD Memory Card:Removable flash format utilizing NAND flash with integrated controller, operating at UHS-I or UHS-II bus speeds. Demand concentrates in consumer imaging equipment and portable gaming consoles where swappable storage remains essential.
- MicroSD Card:Miniaturized removable format in 11x15mm footprint, prevalent in surveillance cameras and Raspberry Pi single-board computers where physical expansion slots persist. Automotive and industrial segments are phasing out MicroSD sockets in favor of soldered-down storage.
- eMMC:Ball grid array package combining NAND die with controller, supporting HS400 interface speeds. Dominates budget smartphone and industrial gateway applications where cost sensitivity outweighs sequential read performance requirements.
- UFS:High-performance embedded interface with full-duplex M-PHY signaling, displacing eMMC in premium automotive infotainment modules requiring faster boot times and 4K video streaming capability.
The dominant share belongs to eMMC, while UFS is closing the gap fastest in automotive-qualified sockets.
Technology:
Wafer fabrication node advancement determines cost per gigabit and endurance characteristics across technology tiers.
- NAND Flash:Planar floating-gate or charge-trap cell architecture, now largely superseded by 3D stacking in new designs. Legacy planar NAND persists in cost-optimized industrial modules where mature process yields drive lowest unit economics.
- DRAM:Volatile memory paired with flash in hybrid storage subsystems for write caching and metadata buffering. Concentrated in enterprise SSD controllers and high-reliability automotive modules where power-loss protection mandates DRAM-backed mapping tables.
- 3D NAND:Vertically stacked charge-trap cells in 128-layer and 176-layer configurations, enabling terabit-scale die densities. Samsung Electronics and SK Hynix fabrication clusters in South Korea anchor supply for premium eMMC and UFS products.
- SLC:Single-level cell architecture storing one bit per cell, delivering highest endurance and widest temperature operating ranges. SLC NAND commands premium pricing in military avionics and medical imaging equipment where write cycle limits determine field lifetime.
3D NAND captures the largest production volume, while SLC maintains the steepest expansion trajectory in safety-critical applications.
End User:
Qualification timeline length and compliance documentation burden separate margin profiles across end-use categories.
- Consumer Electronics:Smartphones, tablets, and wearable devices driving volume shipments with 2-3 year product lifecycles. Chinese OEMs dominate procurement, with MIIT GB standard certification increasingly required for domestic market access.
- Automotive:Infotainment head units, ADAS camera modules, and telematics control units requiring AEC-Q100 Grade 2 or Grade 3 temperature specifications. Extended qualification cycles and ISO 26262 functional safety compliance create supplier stickiness and superior margin pools.
- Industrial:Edge computing gateways, programmable logic controllers, and robotics controllers operating in extended temperature ranges. Demand concentrates in German manufacturing automation and Japanese factory equipment markets.
- Healthcare:Portable ultrasound machines, patient monitoring systems, and diagnostic imaging equipment requiring FDA or NMPA device-level clearance. Medical-grade eMMC demands enhanced data retention algorithms and extended supply guarantees.
Consumer Electronics holds the dominant share by unit volume, while Automotive is gaining share fastest on margin expansion.
Installation:
Physical attachment method determines field serviceability and vibration resistance in target applications.
- Embedded:Soldered ball grid array mounting with no user-removable interface, standard in smartphones and automotive modules where shock and vibration resistance is paramount.
- Removable:Socketed card formats enabling field replacement and capacity upgrades, persisting in professional imaging equipment and industrial data loggers where physical media exchange remains operational requirement.
- Integrated:Multi-chip package combining eMMC or UFS with application processor in single module, adopted by Qualcomm and MediaTek reference designs for space-constrained mobile devices.
- Onboard:Direct NAND die attach to system motherboard with discrete controller, deployed in ultra-cost-optimized consumer electronics where package-level integration cost is prohibitive.
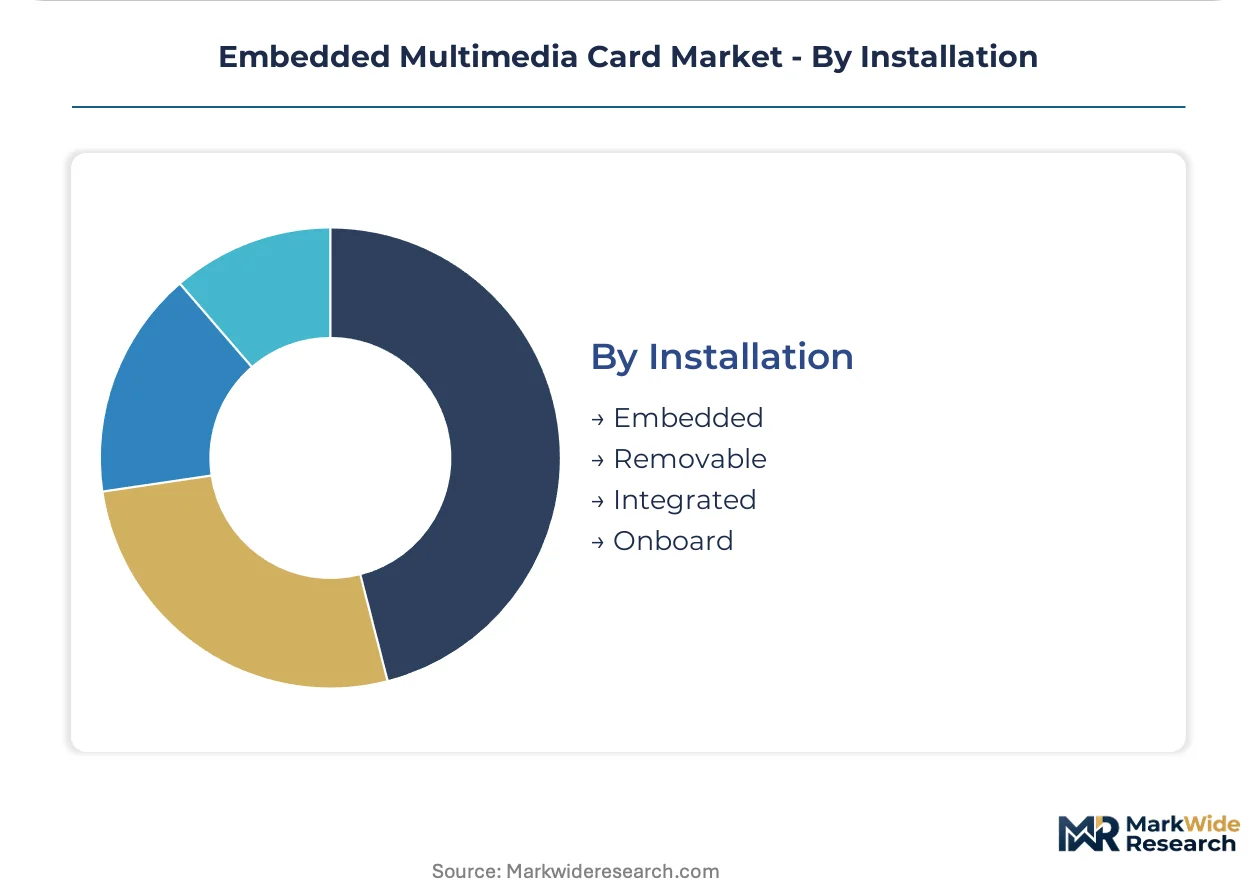
Embedded installation dominates shipment volumes, while Integrated formats are climbing fastest in mobile processor reference designs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korea's Ministry of Trade, Industry and Energy anchors the dominant semiconductor geography through Pyeongtaek and Hwaseong fabrication clusters. Government-backed investment incentives expand captive 3D NAND capacity serving regional module assembly. Chinese OEM procurement and automotive qualification requirements reshape manufacturing location decisions across Asia-Pacific.
China
Domestic OEMs drive eMMC and UFS procurement for budget smartphones and connected vehicle programs. MIIT enforces GB standard certification for storage components in critical infrastructure, compelling enhanced error-correction algorithms. Yangtze River Delta module assemblers establish parallel qualification tracks to maintain market access.
South Korea
Automotive infotainment and ADAS storage demand concentrates procurement around qualified suppliers. The Ministry of Trade, Industry and Energy coordinates national investment incentives expanding local manufacturing capacity. Pyeongtaek and Hwaseong fabrication clusters anchor supply for premium eMMC and UFS products.
United States
FDA-regulated medical imaging equipment and NHTSA-influenced automotive programs generate demand for high-reliability storage. Extended qualification cycles for AEC-Q100 compliance create supplier stickiness in Detroit and Austin automotive electronics corridors. Silicon Valley edge computing gateway deployments consume industrial-grade eMMC.
Germany
Industrial automation and automotive tier-1 suppliers specify extended-temperature eMMC for factory equipment. ECHA REACH frameworks restrict hazardous substances in electronic assemblies, compelling solder ball composition reformulation. Bavaria and Baden-Württemberg manufacturing clusters concentrate procurement for robotics controllers.
Japan
METI-supported semiconductor initiatives sustain domestic fabrication for automotive and industrial applications. Precision manufacturing equipment and medical devices demand SLC NAND with widest temperature operating ranges. Kyushu fabrication facilities supply die for safety-critical avionics and diagnostic imaging subsystems.
Embedded Multimedia Card Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier in the Embedded Multimedia Card landscape. Captive NAND fabrication and controller IC design capabilities separate strategic positions. Three archetypes predominate: integrated device manufacturers with wafer fabs, fabless controller specialists, and memory module integrators. Competitive moves center on long-term supply agreements with automotive tier-1s and die-bank reservations with fabrication operators.
Among Asia-Pacific-based fabricators, Samsung Electronics and SK Hynix exemplify the integrated device manufacturer archetype through captive 3D NAND production. Phison Electronics occupies a specialist position in controller IC design. These three anchors represent the vertical-tier structure: full integration versus focused component specialization.
| Leading Market Players |
|---|
| SK Hynix |
| Kingston Technology |
| Samsung Electronics |
| Silicon Motion Technology |
| Phison Electronics |
| Micron Technology |
| Kioxia |
| Transcend Information |
| Western Digital |
| Others |
Cost & Logistics Intelligence
Captive 3D NAND fabrication capacity in South Korea's Pyeongtaek cluster generates scale economies that compress cost-per-gigabit floors while concentrating pricing power among integrated device manufacturers. This upstream consolidation propagates through module assembly tiers, where automotive qualification requirements and China's MIIT certification mandates create tiered price bands that separate AEC-Q100-compliant suppliers from commodity eMMC integrators.
Pricing Analysis
Long-term die-bank reservation contracts dominate procurement for automotive-qualified eMMC and UFS, displacing spot-market NAND purchases as tier-1 suppliers seek allocation certainty through technology transition cycles. Price differentiation separates AEC-Q100 Grade 2 automotive modules from industrial-grade alternatives, with certification overhead and extended temperature specifications commanding substantial premiums. Cost compression in budget smartphone eMMC intensifies as Chinese OEMs consolidate procurement around domestic-qualified suppliers. Consumer electronics buyers exhibit highest price sensitivity, while automotive OEMs prioritize supply assurance over unit cost minimization.
Supply Chain Analysis
Inventory buffers at module assemblers have compressed to 4-6 weeks as just-in-time coordination with wafer fabrication operators replaces speculative die stocking. Supply concentrates in South Korea, China, and Taiwan, with 3D NAND wafer output feeding regional packaging and testing facilities. The supply chain rests on high-purity silicon wafers, specialty lead-free solder ball compositions, and REACH-compliant encapsulant materials. Single-source vulnerability around controller IC design expertise concentrates among experienced mixed-signal semiconductor firms. Distribution runs through tier-1 electronics manufacturing services firms and direct OEM procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Embedded Multimedia Card market is entering a cyclical recovery phase as automotive ADAS integration and industrial IoT gateway expansion absorb excess 3D NAND wafer capacity that accumulated during consumer electronics demand softness.
For Market Incumbents: Compound captive fabrication advantages by expanding AEC-Q100 qualification coverage into emerging automotive camera module sockets. Secure long-term die-bank reservations with fabrication operators before technology transition cycles constrain allocation. Defend against UFS interface substitution in premium vehicle segments by accelerating controller architecture roadmaps. For New Entrants and Emerging Players: AEC-Q100 fast-track certification programs offer entry pathways into automotive-qualified supply chains currently dominated by established integrators. White-space concentrates in India's PLI-supported semiconductor assembly and testing facilities, where production-linked incentives reduce capital intensity for module packaging operations. Target industrial IoT gateway applications in German manufacturing automation clusters, where extended-temperature specifications and smaller volume requirements reduce direct competition from scale-optimized incumbents. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among controller IC design specialists with automotive qualification track records and long-term supply agreements with tier-1 electronics manufacturing services firms. Over the projection horizon, acquisition value concentrates in fabless controller firms possessing mixed-signal PHY layer expertise and established MIIT GB standard certification for Chinese market access. Monitor NAND flash wafer pricing inflection as the signal for margin expansion timing in downstream module assembly operations.| Strategic Initiative | Industry Significance |
|---|---|
| Automotive Qualification Expansion | AEC-Q100 Grade 2 certification opens ADAS camera module procurement to qualified suppliers. |
| Long-term Die-Bank Reservation | Direct wafer allocation agreements with Samsung or SK Hynix fabrication clusters secure supply assurance. |
| Controller Architecture Advancement | HS400 and UFS 3.1 PHY layer development maintains interface speed competitiveness against emerging alternatives. |
| MIIT GB Standard Certification | Enhanced error-correction algorithms satisfy China's connected vehicle data-retention mandates for domestic market access. |
| India PLI Scheme Participation | Production-linked incentives for semiconductor assembly reduce capital intensity for regional module packaging operations. |
Research Approach
Findings reconcile primary fieldwork against secondary review of SEC 10-K filings, MIIT regulatory bulletins, and AEC-Q100 qualification databases. Semiconductor supply chain executives, automotive tier-1 procurement managers, and controller IC design engineers provided structured input. Bottom-up triangulation across module shipment data and top-down validation against wafer fabrication capacity announcements ensure analytical consistency.
Segmentation dimensions modeled include interface specification tier, NAND flash cell architecture, end-use qualification requirement, and geographic manufacturing cluster. CAGRs derive from trend extrapolation across technology transition cycles and demand elasticity estimates for automotive versus consumer applications. Forecast inputs incorporate MIIT enforcement timelines for GB standard certification and South Korean Ministry of Trade, Industry and Energy investment incentive disbursement schedules.
Decision-makers should treat outputs as directional under assumptions of continued automotive electrification and stable NAND flash wafer supply concentration; material deviation in consumer electronics demand or trade policy would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Global Zener Diode Market
Semiconductor Devices
Voltage Controlled Oscillators Market
Semiconductor Devices
Digital Tunable Capacitors Market
Semiconductor Devices
Ultra Low Power Microcontroller Market
Semiconductor Devices
Europe Silicon Carbide Wafers Market
Semiconductor Devices
Gallium Nitride (Gan) Semiconductor Devices Market
Semiconductor Devices
Data Processing Unit Market
Semiconductor Devices
Europe Semiconductor Device Market
Semiconductor Devices
COF (Chip-On-Film) Market
Semiconductor Devices
Gan Transistor Market
Semiconductor Devices
Global Bipolar Power Transistor Market
Semiconductor Devices
Global Trench Gate Power MOSFET Market
Semiconductor Devices
Asia-Pacific MLCC Market
Semiconductor Devices
Japan Semiconductor Device Market
Semiconductor Devices
Field Programmable Gate Array (FPGA) Market
Semiconductor Devices
China Semiconductor Device Market