
 Cloth Cutting Machines Market | 2026-2036
Cloth Cutting Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Cloth Cutting Machines Market Outlook
Buyer concentration among large-scale apparel manufacturers is pivoting toward mid-tier suppliers seeking automated cutting solutions. Lectra leverages vertical integration across software and hardware to sustain its position in pattern-to-cut workflows. Eastman Machine Company anchors its competitiveness through specialized blade systems for technical textiles. Zünd Systemtechnik differentiates via modular digital cutting platforms that serve both textile and composite applications.
Cloth cutting machines are industrial equipment designed to sever fabric layers with precision, operating through mechanical blades, rotary tools, or directed energy beams at feed rates up to 1.5 meters per second depending on material stack height. These systems serve apparel production, technical textile fabrication, and upholstered goods manufacturing by converting rolled goods into patterned plies ready for assembly. CNC systems occupy the fastest-expanding tier as programmable nesting algorithms reduce material waste below eight percent. Laser cutting technology leads in synthetic fabric applications where sealed edges prevent fraying. Die-cutting remains mature within footwear midsole and upper production where steel-rule tooling delivers repeatability at volume scale.
OSHA machine guarding standards and CE marking under the EU Machinery Directive shape equipment design mandates for operator safety and electromagnetic compatibility. EPA emissions thresholds for laser fume extraction systems influence capital specifications in United States manufacturing facilities. China's GB standards administered by SAMR define electrical safety and precision tolerances for domestic and export-bound equipment. Stakeholders must monitor how evolving dual carbon goals from China's MEE redirect investment toward energy-efficient servo-driven architectures over pneumatic legacy systems.
Market Dynamics
Apparel manufacturers are compressing pattern-to-garment cycles from weeks to days, forcing equipment buyers to prioritize servo-driven CNC architectures over pneumatic mechanical systems that cannot sustain 1.5 meter-per-second feed rates across multi-ply stacks.
Growth Catalysts
- Fast-fashion velocity mandates:Zara and Shein suppliers in Guangdong province are replacing legacy mechanical cutters with automated nesting systems to meet 48-hour sample turnaround requirements.
- REACH compliance in Europe:ECHA restrictions on solvent-based fabric treatments are redirecting synthetic textile production toward laser-sealed edges that eliminate chemical fray-prevention coatings.
- Technical textile expansion:Carbon fiber prepreg and aramid composite cutting for aerospace interiors and EV battery enclosures is absorbing high-precision digital cutting platforms previously confined to apparel.
Market Restraints
- Steel and servo motor cost volatility:Machine frames and precision drive systems face input price swings that compress OEM margins on mid-tier equipment.
- Blade supply concentration:Tungsten carbide cutting tool production clusters in China's Hunan province, creating single-source vulnerability for European and North American machine builders.
- Laser fume extraction mandates:EPA thresholds for volatile organic compound capture add fifteen to twenty percent to installed system costs in United States facilities.
Strategic Opportunities
- India apparel manufacturing corridors:Tamil Nadu and Gujarat textile clusters remain underpenetrated by automated cutting, with PLI scheme incentives accelerating capital expenditure timelines.
- Footwear midsole die-cutting automation:EVA and TPU foam cutting for athletic shoe production is migrating from manual steel-rule presses to programmable die systems serving Vietnam and Indonesia contract manufacturers.
- EU Green Deal carbon accounting:CSRD disclosure requirements are pressuring garment brands to document material waste reduction, creating specification pull for nesting software that demonstrates sub-eight-percent scrap rates.
Industry Challenges
- CNC nesting programmer scarcity:Apparel manufacturers lack operators trained in CAD-to-cut workflow optimization, extending commissioning timelines and forcing vendors to embed training into installation contracts.
- CE marking certification delays:EU Machinery Directive conformity assessment timelines for electromagnetic compatibility and functional safety have stretched to fourteen months, freezing export-bound inventory.
- Legacy pneumatic system integration:Mechanical cutter floors built in the 1990s require complete electrical infrastructure replacement to accommodate servo-driven CNC platforms, doubling effective project costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cloth Cutting Machines Market |
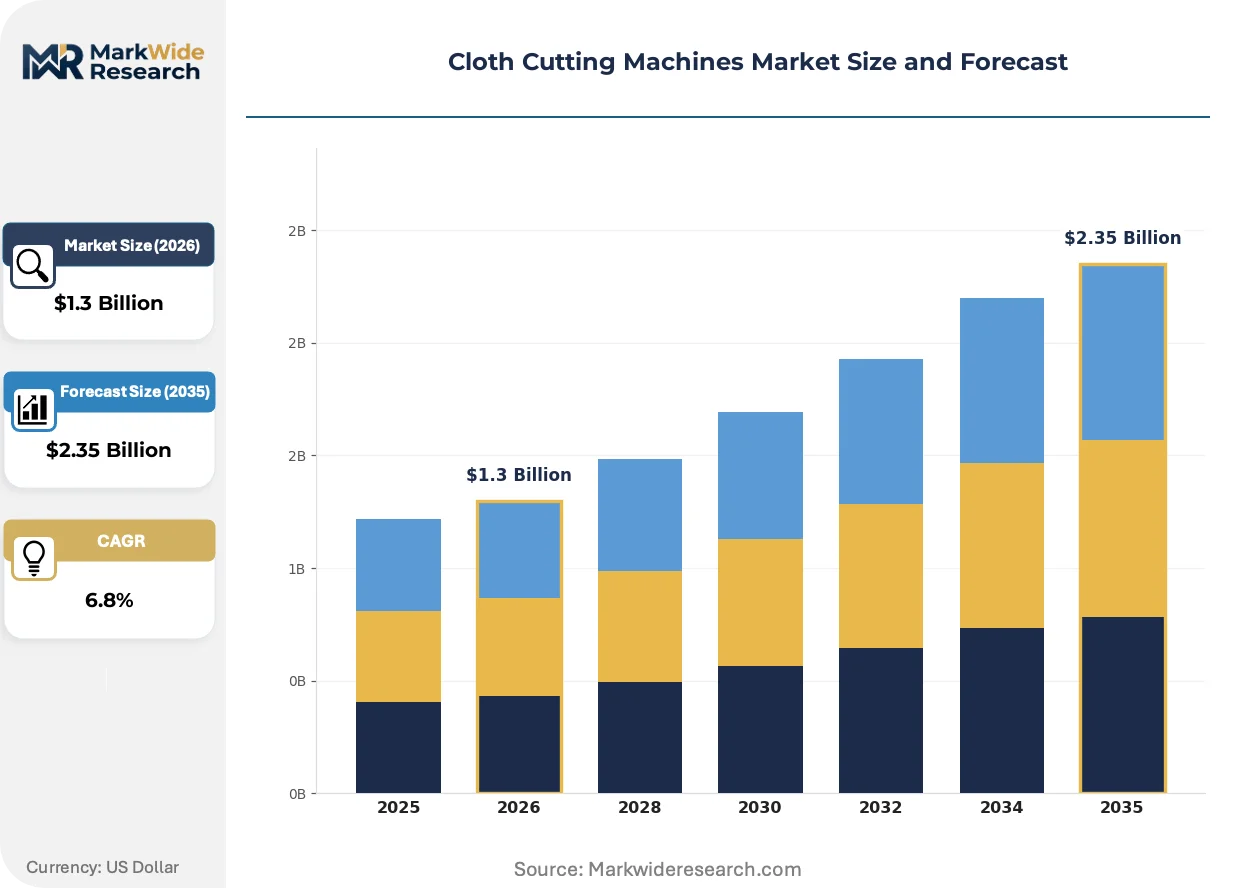
| Market Size in 2026 | $1.3 Billion |
| Market Size in 2035 | $2.35 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual, Electric, CNC, Laser Application: Textile, Apparel, Upholstery, Footwear End User: Manufacturers, Designers, Retailers, Tailors Technology: Die-Cutting, Water Jet, Plasma, Ultrasonic |
| Companies Covered | Eastman Machine Company, Gerber Technology, Lectra, REXEL, KURIS Spezialmaschinen, Bullmer, Zünd Systemtechnik, Calemard, Aeronaut Automation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cloth Cutting Machines Market Strategic Shifts
Cloud-connected nesting algorithms and edge-computing controllers are redistributing intelligence from centralized factory servers to individual cutting heads, compressing pattern update cycles and enabling real-time yield optimization without IT infrastructure overhaul.
Vision-guided cutting heads equipped with fabric distortion compensation are decentralizing quality control from post-cut inspection stations to the cutting bed itself. High-volume sportswear manufacturers in Vietnam and Bangladesh are adopting these systems to handle printed knit fabrics that shift during layup. The technology is compressing rework rates and eliminating separate scanning stations that previously bottlenecked floor layouts.
EPA industrial emissions guidelines for laser fume extraction are forcing United States facilities to specify activated carbon filtration systems with continuous monitoring. Garment contractors in Los Angeles and North Carolina are retrofitting existing CO2 laser cutters with closed-loop extraction to avoid production halts during compliance audits. Synthetic fabric specialists face the steepest capital burden, as polyester and nylon cutting generates higher particulate loads than natural fibers.
Mid-tier apparel suppliers are unbundling maintenance contracts from equipment purchases, treating cutting platforms as utility-like assets with uptime guarantees. Vietnamese and Turkish contract manufacturers now specify outcome-based service agreements where vendors absorb blade wear and calibration costs. This procurement shift is pressuring OEMs to build predictive maintenance capabilities into controller firmware rather than relying on scheduled technician visits.
Cloth Cutting Machines Market Segmentation
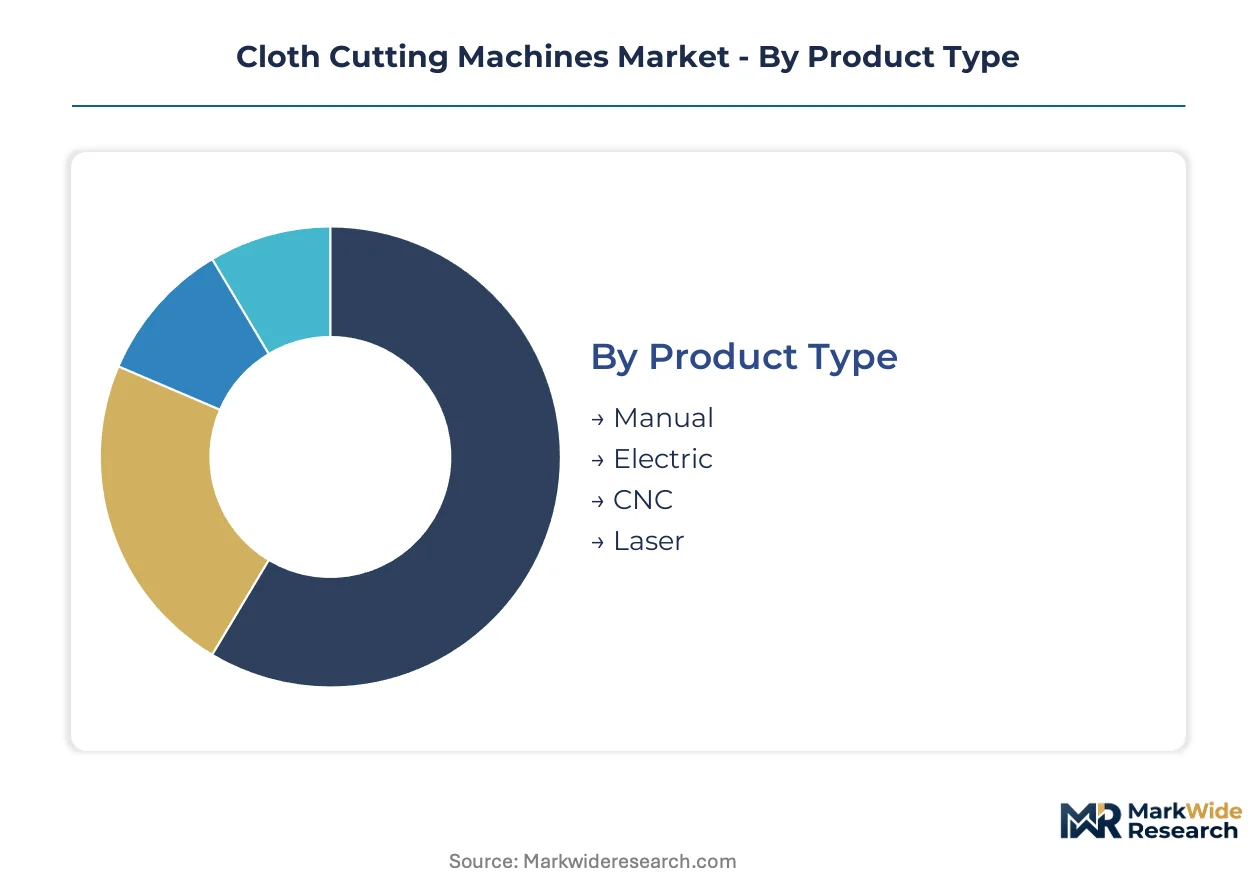
Cloth cutting machines serve divergent operational scales—from artisan tailors to automated factory floors—creating distinct equipment specifications across each segment. Capital deployment patterns vary sharply: servo-driven CNC platforms demand infrastructure investments that manual systems never require. Understanding these tiered requirements illuminates where OEMs can defend margin and where price competition dominates.
Product Type:
Capital intensity stratifies sharply across this dimension, with automated architectures requiring electrical infrastructure and precision motion systems that multiply upfront outlays.
- CNC:Programmable nesting algorithms coordinate multi-axis servo drives to execute complex pattern libraries with sub-millimeter repeatability. Guangdong apparel clusters absorb the bulk of new installations as suppliers to Zara and Shein compress sample turnaround windows. CE marking timelines stretching fourteen months constrain European OEM delivery schedules.
- Laser:Directed CO2 or fiber beams vaporize fabric edges to create sealed seams that prevent fraying in synthetic textiles. REACH compliance is redirecting European synthetic production toward laser-sealed edges that eliminate solvent-based fray-prevention coatings. EPA fume extraction mandates add fifteen to twenty percent to installed costs in United States facilities.
- Manual:Hand-operated shears and straight-knife cutters serve alteration shops and small-batch producers with minimal capital barriers. Entry cost rarely exceeds several hundred dollars.
- Electric:Motorized rotary and reciprocating blades accelerate cut speeds for mid-volume operations without programmable control systems. Popular among independent tailors in India's Tamil Nadu corridor.
CNC platforms absorb the bulk of installed capacity in automated factory environments; laser systems are expanding most quickly as synthetic fabric volumes climb and chemical coating regulations tighten.
Application:
Volume concentration and margin structure diverge across end-use categories, with technical textile fabrication commanding premium pricing over commoditized apparel production.
- Apparel:Multi-ply cutting of woven and knit fabrics for garment assembly dominates unit demand. Fast-fashion velocity mandates in Guangdong and Zhejiang provinces drive replacement of legacy mechanical systems.
- Footwear:EVA and TPU foam die-cutting for midsole production requires steel-rule tooling precision at volume scale. Vietnam and Indonesia contract manufacturers are migrating from manual presses to programmable die systems.
- Technical Textile:Carbon fiber prepreg and aramid composite cutting for aerospace interiors and EV battery enclosures absorbs high-precision digital platforms. This segment commands the steepest equipment premiums.
- Upholstery:Leather and synthetic hide cutting for furniture and automotive seating applications. Italian and Polish manufacturers concentrate demand for specialized hide nesting systems.
Apparel applications anchor total installed base; technical textile cutting is climbing the fastest as aerospace and electric vehicle supply chains expand.
End User:
Procurement sophistication and service contract expectations fragment across buyer types, with large manufacturers demanding outcome-based uptime guarantees that smaller operators rarely request.
- Manufacturers:Large-scale production facilities specifying automated cutting floors with predictive maintenance integration. Vietnamese and Turkish contract manufacturers now unbundle maintenance contracts to treat platforms as utility-like assets.
- Retailers:Vertical apparel brands operating captive cut-and-sew operations for private-label collections. Shein's Guangdong suppliers exemplify this model.
- Designers:Small-batch studios and sampling departments requiring rapid pattern iteration without volume scale. Cloud-connected nesting algorithms serve this tier through subscription software models.
- Tailors:Independent craftsmen and alteration shops with minimal automation requirements. Price sensitivity dominates procurement decisions.
Manufacturers represent the dominant revenue concentration; designers are gaining share fastest as sampling velocity becomes a competitive differentiator for emerging brands.
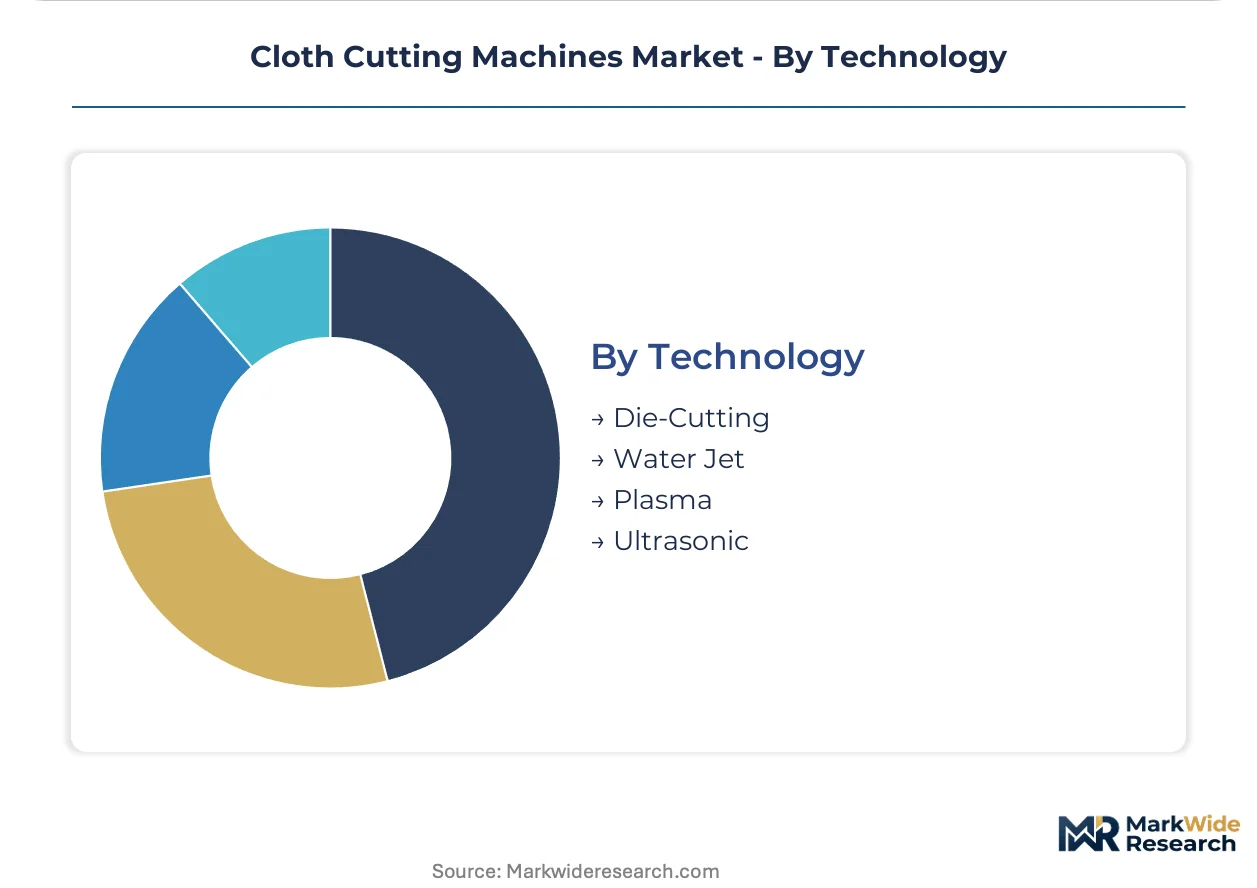
Technology:
Supply concentration for consumables and precision components creates divergent risk profiles across cutting methodologies.
- Die-Cutting:Steel-rule and rotary die systems deliver repeatability at volume for footwear and packaging applications. Tungsten carbide tool production concentration in China's Hunan province creates single-source vulnerability for European and North American machine builders.
- Ultrasonic:High-frequency mechanical vibration fuses synthetic fabric edges without thermal damage. Sealed-edge quality suits medical textile and filtration applications.
- Water Jet:High-pressure abrasive streams cut multi-layer stacks without heat-affected zones. Technical textile and composite applications favor this cold-cutting approach.
- Plasma:Ionized gas streams sever conductive materials at high velocity. Limited textile adoption due to thermal damage constraints on synthetic fibers.
Die-cutting retains the largest installed base; ultrasonic systems are expanding most quickly in medical and technical textile niches requiring sealed-edge precision.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Apparel manufacturing concentrates in coastal China, where Guangdong and Zhejiang textile clusters drive replacement demand for legacy mechanical cutters. Fast-fashion velocity mandates from Zara and Shein suppliers compress equipment procurement cycles across multiple geographies.
China
Guangdong province hosts the densest concentration of automated cutting floor investments, with Shein suppliers replacing pneumatic systems to meet 48-hour sample turnaround requirements. GB standards administered by SAMR define electrical safety and precision tolerances for export-bound equipment. Zhejiang textile clusters in Shaoxing and Keqiao are absorbing servo-driven CNC platforms as dual carbon goals from China's MEE redirect investment away from energy-intensive legacy architectures.
United States
Garment contractors in Los Angeles and North Carolina face EPA industrial emissions guidelines for laser fume extraction systems that add fifteen to twenty percent to installed capital costs. OSHA machine guarding standards shape equipment design mandates for operator safety across cutting floors. Technical textile fabrication for aerospace interiors in Washington and South Carolina absorbs high-precision digital platforms previously confined to apparel applications.
Germany
Automotive upholstery manufacturers in Baden-Württemberg specify specialized hide nesting systems for leather and synthetic cutting applications. CE marking under the EU Machinery Directive creates fourteen-month conformity assessment timelines that freeze export-bound inventory for domestic OEMs. Bavarian technical textile producers serving EV battery enclosure supply chains absorb premium digital cutting platforms at steeper equipment price points than commoditized apparel systems.
Vietnam
Contract manufacturers in Ho Chi Minh City and Binh Duong province are migrating footwear midsole production from manual steel-rule presses to programmable die systems. Mid-tier apparel suppliers unbundle maintenance contracts to treat cutting platforms as utility-like assets with uptime guarantees. PLI scheme incentives in competing jurisdictions accelerate capital expenditure timelines for automated nesting systems.
India
Tamil Nadu and Gujarat textile corridors remain underpenetrated by automated cutting solutions despite accelerating fast-fashion supplier migration. BIS standards shape equipment certification requirements for domestic and export-bound machinery. Tiruppur knitwear clusters are beginning to absorb cloud-connected nesting algorithms as sampling velocity becomes a competitive differentiator for emerging brands.
Cloth Cutting Machines Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue adjacent composite and technical textile applications beyond traditional apparel. The vendor base stratifies across three tiers: integrated software-hardware platforms, specialized blade system fabricators, and modular digital cutting specialists. Strategic archetypes include pattern-to-cut workflow integrators, technical textile precision specialists, and utility-like service contract providers. Competitive moves concentrate on predictive maintenance firmware integration and geographic expansion into underpenetrated South Asian manufacturing corridors.
Among European-headquartered platform providers, Lectra and Zünd Systemtechnik exemplify divergent specialization vectors—Lectra occupying the pattern-to-cut workflow integration archetype, Zünd Systemtechnik representing modular digital cutting platforms that serve textile and composite applications. Eastman Machine Company anchors the specialized blade systems tier for technical textile fabrication. These three entities collectively illustrate how competitive positioning fragments across software integration, hardware modularity, and consumable precision domains.
| Leading Market Players |
|---|
| Eastman Machine Company |
| Gerber Technology |
| Lectra |
| REXEL |
| KURIS Spezialmaschinen |
| Bullmer |
| Zünd Systemtechnik |
| Calemard |
| Aeronaut Automation |
| Others |
Value Chain & Pricing Dynamics
Steel price indices and rare-earth magnet benchmarks cascade through cloth cutting machine supply chains, compressing margins on servo-driven CNC platforms while amplifying pricing power for blade-system specialists with captive tungsten carbide sourcing. Equipment buyers face tiered cost exposure: pneumatic legacy architectures absorb commodity steel volatility directly, whereas automated nesting systems hinge on precision motor and controller costs that OEMs struggle to pass through.
Pricing Analysis
High-volume apparel manufacturers capture standard-tier equipment at compressed margins, while technical textile fabricators absorb premium pricing for aerospace-grade precision systems. Pricing stratifies across certification-grade CNC platforms, mid-tier electric cutters, and entry-level manual systems, with CE marking timelines and EPA fume extraction mandates widening the cost gap between export-bound and domestic-only configurations. Cost compression in mid-tier equipment is intensifying because steel and servo motor input volatility outpaces OEM pricing power. Independent tailors in India's Tamil Nadu corridor exhibit the steepest price sensitivity, whereas German automotive upholstery manufacturers show minimal elasticity for specialized hide nesting systems.
Supply Chain Analysis
Skilled CNC nesting programmer scarcity in Vietnam and Bangladesh extends commissioning timelines, forcing OEMs to embed training costs into delivered equipment pricing. Machine frame fabrication concentrates in China, precision servo motor production clusters in Japan and Germany, and tungsten carbide blade manufacturing dominates China's Hunan province. Supply chain risk centers on single-source vulnerability for cutting tool consumables, where Hunan-based carbide producers feed global machine builders with limited alternative sourcing. Distribution runs through direct OEM sales teams for large manufacturers and regional distributor networks serving mid-tier apparel suppliers and independent tailors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Servo-driven CNC architectures are systematically displacing pneumatic mechanical systems across automated cutting floors, compressing the window for legacy equipment suppliers to capture replacement revenue. This technology transition rewards vendors with integrated software-hardware platforms and punishes pure hardware fabricators lacking nesting algorithm capabilities.
For Market Incumbents: Cement pattern-to-cut workflow dominance by embedding predictive maintenance firmware that absorbs blade wear and calibration costs under outcome-based service contracts. Threats from modular digital cutting platforms serving adjacent composite applications demand defensive certification investment in CE marking and EPA emissions compliance to freeze export-bound inventory advantages. Capacity addition in Vietnam's Ho Chi Minh City corridor captures mid-tier apparel supplier migration before emerging entrants establish local service infrastructure.
For New Entrants and Emerging Players: Enter via India's Tamil Nadu and Gujarat textile corridors, where PLI scheme incentives accelerate capital expenditure timelines yet automated cutting penetration remains shallow compared to Guangdong benchmarks. The footwear midsole die-cutting segment in Vietnam and Indonesia presents the most penetrable white-space target, with EVA and TPU foam cutting migrating from manual steel-rule presses to programmable systems. A cloud-connected nesting algorithm subscription model serves designer studios and sampling departments without requiring heavy equipment manufacturing capabilities.
For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized blade system fabricators with captive tungsten carbide sourcing in China's Hunan province, where input cost volatility compresses pure-play equipment margins but rewards consumables-integrated business models. Long-term viability across the projection horizon rests on software-hardware integration depth rather than standalone hardware fabrication scale. The signal to watch is unbundling velocity of maintenance contracts from equipment purchases, where outcome-based service agreement penetration exceeding critical mass indicates utility-like asset treatment and recurring revenue stability.
| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Firmware Integration | Vietnamese contract manufacturers now specify uptime guarantees where vendors absorb blade wear costs. |
| CE Marking Certification Investment | Fourteen-month EU Machinery Directive timelines freeze export-bound inventory for prepared OEMs. |
| Cloud-Connected Nesting Algorithm Launch | Shein suppliers in Guangdong compress 48-hour sample turnaround via real-time pattern updates. |
| Backward Integration into Blade Systems | Hunan province tungsten carbide concentration creates single-source vulnerability for unintegrated machine builders. |
| Technical Textile Platform Expansion | Bavarian EV battery enclosure producers absorb premium digital cutting platforms at steeper price points. |
Study Parameters
Trade association filings, customs export records, and equipment registration databases formed the secondary backbone, cross-referenced against primary interviews with plant engineers at Guangdong apparel clusters, procurement leads at Vietnamese contract manufacturers, aftermarket service heads at European OEMs, and maintenance directors at North Carolina garment contractors. Bottom-up triangulation across installed base estimates and top-down validation against capital expenditure disclosures ensured convergence on segment-level demand figures.
Historical trendline analysis of replacement cycle timing and technology adoption curves anchored the projection framework across the analysis window. Segmentation dimensions modeled include product architecture tier, end-use application intensity, buyer procurement sophistication, and regional regulatory compliance cluster. CAGRs derived from slope-stability testing against input cost volatility and capacity expansion announcements. Industry-specific forecast inputs incorporated REACH compliance trajectory for laser-sealed edge demand and China's MEE dual carbon goals for servo-driven architecture penetration.
Revisions become necessary when steel and rare-earth magnet price volatility exceeds historical bands, when CE marking or EPA emissions guidelines shift compliance cost structures, or when fast-fashion velocity mandates accelerate replacement cycles beyond modeled parameters. Material deviation in these triggers warrants pause and re-evaluation of installed base and revenue assumptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Textile Machinery and Equipment
Europe Fabric Shavers Market
Textile Machinery and Equipment
Global Digital Textile Printing Machine Market
Textile Machinery and Equipment
Cloth Measuring Machine Market
Textile Machinery and Equipment
US Textile Processing Machinery Market
Textile Machinery and Equipment
Multifunctional Clothes Folding Machine Market
Textile Machinery and Equipment
Webbing Cutting Machine Market
Textile Machinery and Equipment
3D Knitting Machines Market
Textile Machinery and Equipment
Tarpaulin Market
Textile Machinery and Equipment
Textile Mill Electric Drives Market
Textile Machinery and Equipment
Braiding Machine Market
Textile Machinery and Equipment
Cotton Processing Equipment Market
Textile Machinery and Equipment
Industrial Sewing Machines Market
Textile Machinery and Equipment
Warping Machines Market
Textile Machinery and Equipment
Sewing Machine Market
Textile Machinery and Equipment
Stringing Machines Market
Textile Machinery and Equipment
Netted Fabrics Market