
 Industrial Laminating Machines Market | 2026-2036
Industrial Laminating Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Laminating Machines Market Intelligence
Market Context
The capital-intensity divergence between full-line system builders and niche module suppliers is bifurcating competitive dynamics across the industrial laminating machines landscape. BOBST Group SA leverages its integrated coating-to-finishing workflow to anchor premium positioning among packaging converters. Nordson Corporation competes through precision adhesive dispensing technology that sustains margin pools in electronics assembly applications. Faustel Inc. specializes in custom roll-to-roll configurations that occupy specialized territory within automotive component lamination.
Technical Definition and Segment Structure
Industrial laminating machines are capital equipment systems that bond multiple substrate layers through controlled application of heat, pressure, adhesive, or radiation energy, typically operating at web speeds from ten to five hundred meters per minute depending on material gauge and bond specification. These systems serve primary industrial purposes including protective barrier formation, structural reinforcement, surface decoration, and functional property enhancement across flexible packaging, printed materials, and engineered components. Roll laminators dominate volume deployment in high-throughput packaging lines where thermal and extrusion technologies anchor the installed base, while UV coating configurations represent the fastest-growing technology segment as converters pursue instant-cure throughput with reduced volatile organic compound exposure. Cold bonding equipment captures concentrated margin pools in temperature-sensitive electronics assembly applications where substrate warping risks exclude thermal methods.
Regulatory Framework and Outlook
The EU Green Deal and REACH chemical registration frameworks in Europe, alongside EPA air quality standards and OSHA workplace exposure limits in the United States, collectively shape equipment specifications by restricting solvent-based adhesive systems and mandating emission capture or alternative curing chemistries. China's MEE environmental compliance protocols and GB standards for industrial equipment safety add parallel compliance layers that influence machine design for Asia-Pacific deployment. Stakeholders must monitor evolving regulatory thresholds for per- and polyfluoroalkyl substance restrictions across multiple geographies, as these chemical controls will determine which lamination bonding technologies retain market access versus requiring fundamental process reinvestment.
Market Dynamics
Capital deployment in industrial laminating machines is bifurcating between high-volume packaging converters seeking solvent-free thermal systems and precision electronics manufacturers demanding cold-bonding configurations, with regulatory pressure from the EU Green Deal accelerating technology substitution timelines.
Growth Catalysts
- Solvent-free thermal lamination:Packaging converters in Germany and China are retrofitting lines to eliminate volatile organic compound emissions ahead of REACH enforcement deadlines.
- UV coating acceleration:Instant-cure chemistry reduces energy consumption and web handling complexity for flexible packaging producers serving food and beverage brands.
- Electronics assembly expansion:Cold bonding equipment demand concentrates in South Korea and Japan where temperature-sensitive substrate processing anchors display and semiconductor packaging investments.
Market Restraints
- Specialized steel roller supply:Precision-ground calendering rolls concentrate among German and Japanese specialty foundries, creating input bottlenecks for system builders.
- Fluoropolymer adhesive restrictions:Per- and polyfluoroalkyl substance controls under ECHA and EPA frameworks are eliminating bonding chemistries that anchored legacy barrier film production.
- Extrusion lamination energy intensity:Melt-bonding processes face margin compression from European carbon pricing and industrial electricity tariffs.
Strategic Opportunities
- India packaging infrastructure:Domestic flexible packaging capacity expansion under PLI scheme incentives creates demand for mid-speed thermal laminators with modular upgrade paths.
- Battery electrode lamination:Roll-to-roll bonding of solid-state electrolyte layers represents an emerging application where precision tension control commands premium positioning.
- Digital print finishing integration:Convergence of inkjet web printing and in-line coating is creating demand for compact laminating modules that eliminate secondary handling.
Industry Challenges
- Multi-physics simulation expertise:Web handling dynamics combining thermal, adhesive, and radiation bonding require scarce computational fluid dynamics and finite element analysis capabilities.
- Legacy control system integration:Retrofitting Industry 4.0 connectivity onto installed mechanical laminators demands specialized middleware development without disrupting continuous production.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Laminating Machines Market |
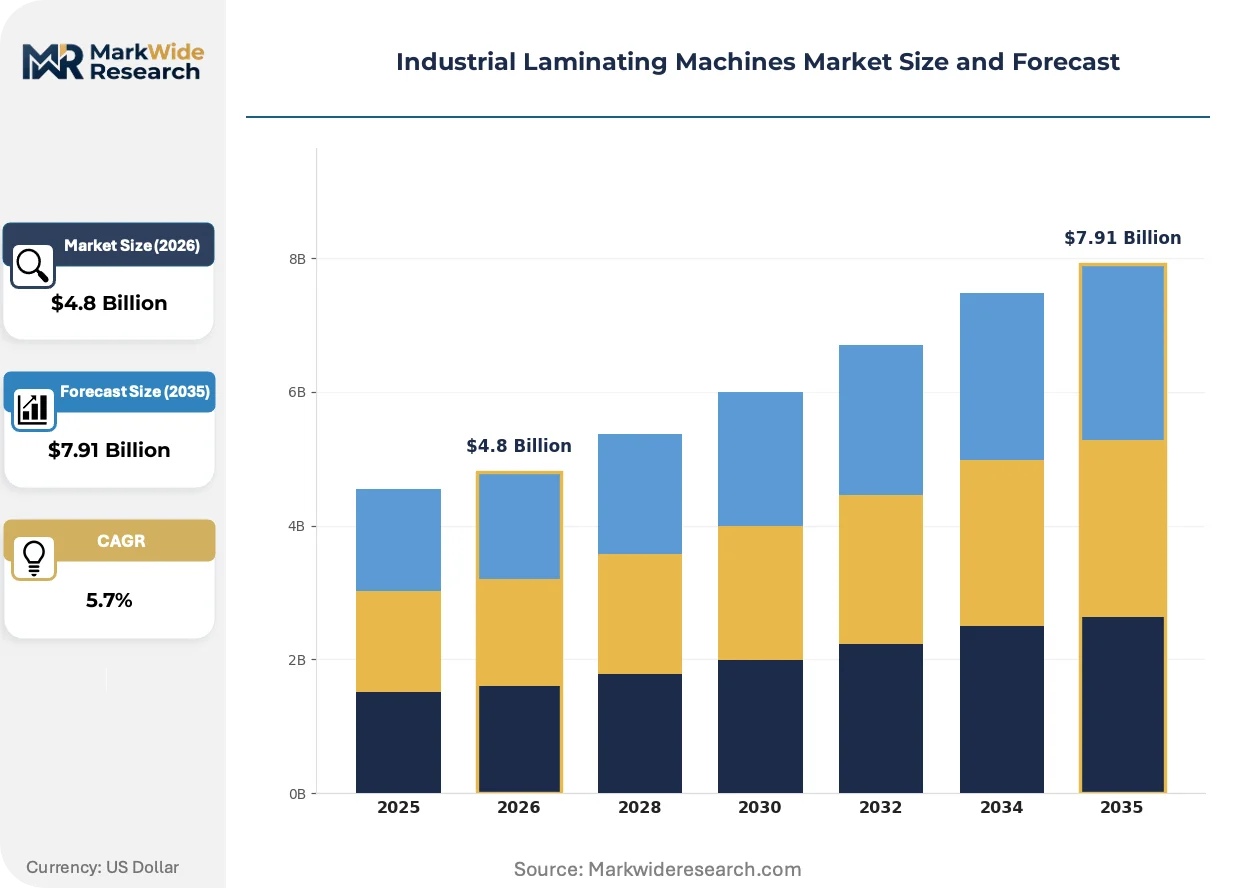
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Roll Laminators, Pouch Laminators, Heated Laminators, Cold Laminators, Pressure-Sensitive Laminators Technology: Thermal, UV Coating, Extrusion, Vacuum, Cold Bonding Application: Packaging, Printing, Automotive Components, Electronics Assembly, Signage Production End User Industry: Manufacturing Plants, Print Shops, Electronics Fabricators, Advertising Agencies, Assembly Facilities |
| Companies Covered | Black Bros. Co., Faustel Inc., Comexi Group Industries, FRIMO Group GmbH, BOBST Group SA, HMT Manufacturing Inc., Nordson Corporation, Menzel Maschinenbau, Monotech Systems Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Laminating Machines Market Strategic Shifts & Innovations
Equipment architecture is fragmenting between monolithic full-line systems and modular component platforms, with regulatory chemistry mandates and buyer consolidation rewriting specification priorities across converter tiers.
Electron beam curing technology is bifurcating the radiation energy segment by enabling instant polymerization without photoinitiator residues. High-barrier pharmaceutical packaging producers in Switzerland and Germany are piloting e-beam configurations at web speeds exceeding three hundred meters per minute. This capability is compressing the addressable market for conventional thermal drying tunnels while opening premium positioning for sterilization-grade lamination.
REACH authorization procedures for chromium trioxide in surface treatment are forcing lamination roller manufacturers toward ceramic and plasma-sprayed coating alternatives. The industrial consequence is extended qualification timelines for food-contact applications. Asian packaging converters serving EU export markets are accelerating supplier audits to secure compliant roller sources ahead of sunset date enforcement.
Converter procurement committees are consolidating capital equipment decisions at regional headquarters rather than plant-level engineering departments. This centralization is displacing distributed vendor relationships with framework agreements covering multi-site service and spare parts provisioning. The shift is most visible in North American flexible packaging where private equity-backed roll-ups are standardizing on single-source laminating platforms.
Industrial Laminating Machines Market Segmentation
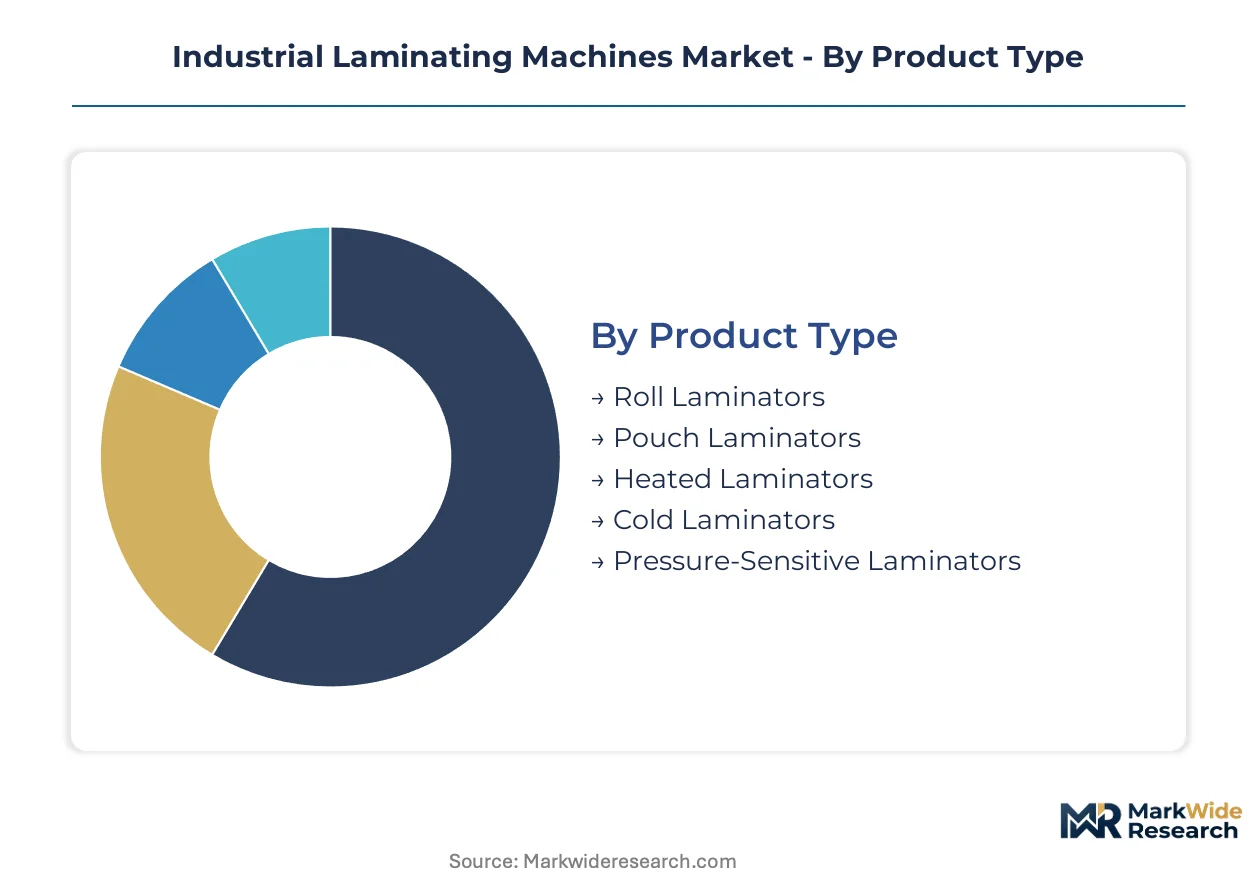
Industrial laminating machines serve divergent throughput requirements across flexible packaging converters and precision electronics fabricators, with equipment specifications varying dramatically by web speed, bond chemistry, and substrate temperature tolerance. Channel dynamics bifurcate between direct OEM relationships for full-line systems and specialized distributors for modular components.
Product Type:
Roll laminators and pouch laminators flow through distinct channel structures, with high-volume roll systems sold direct to packaging converters while compact pouch units distribute through office equipment dealers and print shop suppliers.
- Roll Laminators:Continuous web processing systems bond flexible substrates at speeds from fifty to five hundred meters per minute using thermal or extrusion methods. Demand concentrates in Germany and China where flexible packaging converters serving food and beverage brands retrofit solvent-free configurations ahead of REACH enforcement deadlines.
- Pouch Laminators:Batch-fed desktop and floor-standing units encase documents or small-format prints within pre-formed adhesive pouches. Print shops in the United States and Japan represent the core demand cluster, driven by short-run document finishing and educational materials protection.
- Heated Laminators:Thermal bonding equipment utilizes heated rollers or platens to activate adhesive layers between substrates.
- Cold Laminators:Pressure-activated adhesive systems operate without thermal input, preserving temperature-sensitive inks and films.
- Pressure-Sensitive Laminators:Equipment applies pre-coated adhesive films through controlled nip pressure without additional energy input.
Roll laminators dominate installed base. Pouch laminators is where expansion concentrates in small-format commercial print segments.
Technology:
Technology selection maps directly to application margin tiers, with UV coating and electron beam systems commanding premium positioning in pharmaceutical barrier packaging while thermal methods retain volume leadership in commodity flexible packaging.
- Thermal:Heat-activated adhesive bonding remains the workhorse technology for high-volume packaging lines, utilizing hot-melt or thermal-set chemistries. German and Chinese converters anchor demand as energy costs and carbon pricing pressure drive efficiency investments in Europe.
- UV Coating:Ultraviolet radiation instantly cures photoinitiator-based coatings without thermal drying tunnels, slashing energy consumption and floor space requirements. Swiss and German pharmaceutical packaging producers are expanding fastest here, drawn by sterilization-grade barrier capabilities.
- Extrusion:Molten polymer bonding creates structural laminates through direct extrusion onto substrates.
- Vacuum:Negative-pressure systems remove entrapped air during bonding for optical clarity applications.
- Cold Bonding:Ambient-temperature adhesive application preserves substrate integrity for temperature-sensitive electronics assembly in South Korea and Japan.
Thermal technology anchors volume deployment. UV coating commands the steepest expansion trajectory among radiation-curing alternatives.
Application:
Application segmentation reveals divergent equipment specifications, with packaging converters prioritizing web speed and electronics assemblers demanding micron-level tension control.
- Packaging:Flexible and rigid barrier formation for food, beverage, and pharmaceutical products constitutes the largest application segment. Asia-Pacific converters in China and India drive capital deployment under domestic capacity expansion programs and EU export compliance requirements.
- Electronics Assembly:Precision lamination of display films, battery electrodes, and semiconductor packaging demands cold bonding or vacuum configurations. South Korean and Japanese fabricators anchor this segment, with solid-state battery electrode bonding representing an emerging high-value niche.
- Printing:Surface protection and finishing for commercial and publication print.
- Automotive Components:Interior trim, insulation, and structural bonding applications.
- Signage Production:Large-format graphic protection and mounting for outdoor advertising.
Packaging dominates installed base. Electronics assembly is where expansion concentrates among precision equipment suppliers.
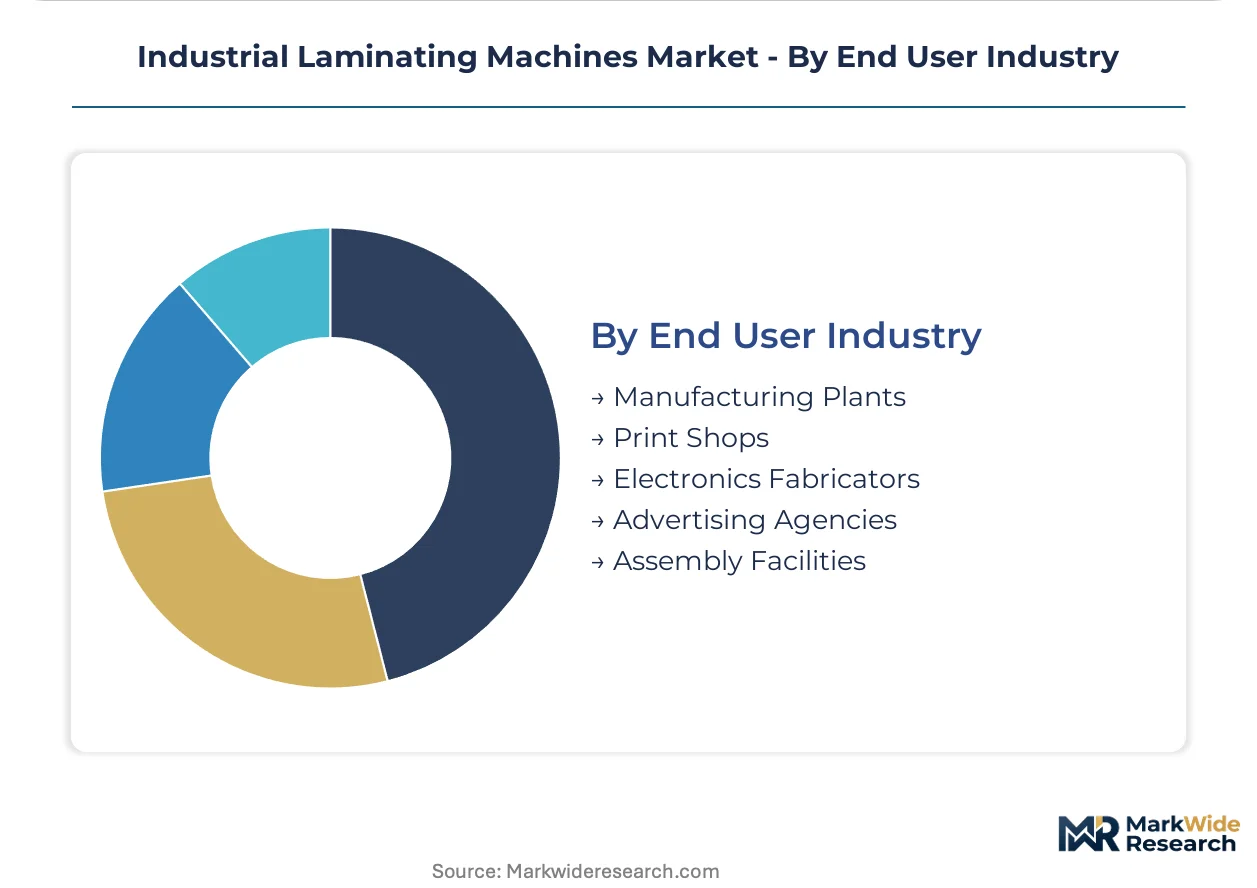
End User Industry:
End user procurement patterns split between centralized capital committees at manufacturing plants and distributed purchasing at print shops and advertising agencies.
- Manufacturing Plants:Integrated production facilities operate continuous laminating lines as upstream inputs to packaging or component assembly. German automotive suppliers and Chinese flexible packaging producers anchor demand, with procurement decisions increasingly centralized at regional headquarters.
- Electronics Fabricators:Display panel and semiconductor packaging facilities require cleanroom-compatible cold bonding systems. South Korean and Japanese producers concentrate here, with tension control precision determining supplier selection.
- Print Shops:Commercial and quick-print operations utilize compact thermal or pouch systems for document finishing.
- Advertising Agencies:Large-format graphic producers apply protective and mounting films to printed signage.
- Assembly Facilities:Contract manufacturers integrate lamination into multi-step component production workflows.
Manufacturing plants dominate installed base. Electronics fabricators is where expansion concentrates among precision equipment specialists.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and Switzerland exhibit the lowest price elasticity, prioritizing precision and regulatory compliance over capital cost, while Indian and Chinese converters remain highly sensitive to equipment pricing and financing terms.
Germany
Flexible packaging converters in Bavaria and Baden-Württemberg drive solvent-free thermal lamination retrofits ahead of REACH authorization deadlines. The EU Green Deal mandates emission reductions that accelerate capital replacement cycles. Industrial clusters around Stuttgart and Munich concentrate automotive component lamination investments.
China
Domestic flexible packaging capacity expansion in Jiangsu and Zhejiang provinces anchors roll laminator procurement. MEE environmental compliance protocols enforce stricter volatile organic compound controls on production lines. The Yangtze River Delta manufacturing corridor hosts the highest concentration of electronics assembly cold-bonding installations.
United States
EPA air quality standards and OSHA workplace exposure limits reshape equipment specifications for Midwestern packaging converters. Private equity-backed roll-ups in Wisconsin and Illinois centralize procurement decisions at regional headquarters. The Southeast automotive belt generates specialized demand for custom roll-to-roll configurations.
India
PLI scheme incentives for domestic flexible packaging capacity create demand for mid-speed thermal laminators with modular upgrade paths. Maharashtra and Gujarat-based converters prioritize equipment with financing flexibility and local service networks. The Delhi-NCR corridor emerges as a secondary demand node for pouch laminators serving commercial print.
South Korea
Electronics fabricators in Gyeonggi Province and the Seoul Capital Area command premium cold-bonding systems for display film lamination. MFDS pharmaceutical packaging regulations align equipment specifications with export market requirements. Busan-Ulsan industrial complexes anchor battery electrode lamination pilot programs.
Industrial Laminating Machines Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with full-line system builders commanding premium positioning through workflow integration while niche module suppliers capture margin pools in precision applications. The competitive terrain splits between scale-driven manufacturers pursuing multi-site framework agreements and technology-focused specialists defending positioning through proprietary bonding chemistries. Strategic archetypes include integrated coating-to-finishing providers, precision adhesive dispensing specialists, and custom roll-to-roll configuration engineers. Dominant competitive moves encompass regional service network expansion and portfolio diversification into adjacent curing technologies.
Among Swiss and German integrated providers, BOBST Group SA and FRIMO Group GmbH exemplify the premium-tier archetype through comprehensive workflow solutions. Nordson Corporation occupies a position within the precision technology specialist tier, representing North American expertise in controlled application systems. Faustel Inc. anchors the custom engineering segment, exemplifying mid-cap specialists that configure equipment for substrate-specific requirements.
| Leading Market Players |
|---|
| Black Bros. Co. |
| Faustel Inc. |
| Comexi Group Industries |
| FRIMO Group GmbH |
| BOBST Group SA |
| HMT Manufacturing Inc. |
| Nordson Corporation |
| Menzel Maschinenbau |
| Monotech Systems Ltd. |
| Others |
Cost & Logistics Intelligence
Eighteen-to-twenty-four-month qualification timelines for precision-ground calendering rolls concentrate pricing power among German and Japanese specialty foundries, while modular component platforms let niche suppliers capture margin pools that full-line builders cannot defend. Buyers face divergent cost structures: packaging converters absorb premium positioning for solvent-free thermal systems, while electronics fabricators prioritize precision over capital outlay.
Pricing Analysis
After-sales service contracts and spare parts provisioning drive lifetime value more than initial equipment sales for integrated system builders. Three-tier pricing structure across premium, standard, and economy levels separates BOBST Group SA's workflow-integrated configurations from mid-speed modular units and entry-level pouch systems. Cost compression in standard thermal laminators is intensifying because Chinese domestic manufacturers expand mid-speed capacity under PLI scheme incentives. Indian and Chinese converters exhibit highest price sensitivity, while Swiss and German pharmaceutical packaging producers prioritize regulatory compliance over capital cost.
Supply Chain Analysis
Strait of Malacca transit vulnerabilities and Red Sea disruptions expose just-in-time delivery models for precision-ground steel rollers sourced from German and Japanese foundries. Component manufacturing concentrates in Germany, China, and Japan, with specialized calendering rolls and ceramic coating equipment anchoring supply. Machine assembly draws from high-grade alloy steel, precision bearings, and radiation-curing lamp systems. Single-source vulnerability in chromium trioxide surface treatment alternatives under REACH authorization creates extended qualification bottlenecks. Distribution runs through direct OEM relationships for full-line systems and specialized distributors for modular components.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as private equity-backed packaging roll-ups in the United States and domestic capacity expansion programs in India centralize procurement decisions at regional headquarters, displacing plant-level vendor relationships.
For Market Incumbents: Compound defensive positioning through backward integration into precision roller manufacturing and captive coating chemistry development. Electron beam curing technology threatens thermal drying tunnel margins. Vertical integration into ceramic roller coating alternatives secures supply continuity ahead of REACH sunset dates. For New Entrants and Emerging Players: Anchor in India's mid-speed thermal laminator segment where PLI scheme incentives outpace established service networks. Battery electrode lamination for solid-state electrolyte bonding offers the most penetrable white-space target. Partner with domestic engineering integrators to bypass direct OEM channel barriers. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance-arbitrage play because EU Green Deal mandates and REACH chemical controls force recurring capital reinvestment cycles. Target custom roll-to-roll configuration specialists with proprietary tension control IP. Watch ECHA per- and polyfluoroalkyl substance restriction timelines as inflection indicator for bonding chemistry substitution demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Roller Manufacturing | Secures supply continuity as REACH authorization eliminates chromium trioxide surface treatment options. |
| Electron Beam Curing Technology Investment | Enables instant polymerization without photoinitiator residues for pharmaceutical barrier packaging. |
| Regional Service Network Expansion | Supports framework agreements with private equity-backed packaging roll-ups centralizing procurement. |
| Battery Electrode Lamination Module Development | Captures emerging demand for solid-state electrolyte bonding in South Korean and Japanese facilities. |
| Solvent-Free Thermal System Retrofit Programs | Aligns installed base with EU Green Deal emission mandates ahead of enforcement deadlines. |
Research Approach
Desk research of customs trade data, SEC filings from capital equipment manufacturers, and MEE environmental compliance protocols preceded structured interviews with plant engineers at flexible packaging converters, procurement leads at electronics fabricators, aftermarket service heads at OEMs, and technical directors at adhesive chemistry suppliers. Primary fieldwork combined with secondary validation from industry association reports and regulatory filing databases. Bottom-up unit economics triangulated against top-down market sizing.
Variance decomposition across technology segments, application verticals, and regional regulatory clusters shaped the analytical framework over the projection horizon. Modeled dimensions span bond chemistry type, web speed tier, substrate temperature tolerance, and end-use industry concentration. CAGRs derived from weighted average of historical replacement cycles and regulatory-driven acceleration scenarios. Forecast inputs incorporate REACH authorization timelines and PLI scheme incentive disbursement patterns.
Material uncertainties — tariff exposure on precision steel components, ECHA per- and polyfluoroalkyl substance restriction scope, and carbon pricing trajectory in Europe — sit outside the modeled envelope. Forecasts reflect documented assumptions about technology substitution elasticity and buyer consolidation pace. Practitioners should keep alternative scenarios live as EU Green Deal implementation intensity and Chinese MEE enforcement rigor evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Textile Machinery and Equipment
Textile Mill Electric Drives Market
Textile Machinery and Equipment
Electric Fabric Shaver Market
Textile Machinery and Equipment
Hoarding Tarpaulin Market
Textile Machinery and Equipment
Fiber Spinning Equipment Market
Textile Machinery and Equipment
Braiding Equipment Market
Textile Machinery and Equipment
Europe Fabric Shavers Market
Textile Machinery and Equipment
Industrial Laundry Market
Textile Machinery and Equipment
Dyeing Machine Market
Textile Machinery and Equipment
Yankee Dryer Market
Textile Machinery and Equipment
Cloth Measuring Machine Market
Textile Machinery and Equipment
Mesh Tarpaulin Sheets Market
Textile Machinery and Equipment
Tarpaulin Sheets Market
Textile Machinery and Equipment
Sewing Machine Component Market
Textile Machinery and Equipment
Stringing Machines Market
Textile Machinery and Equipment
Cotton Processing Equipment Market
Textile Machinery and Equipment
Plasma Surface Treatment Machine for Leather Market