
 Global Knitting Machinery Market | 2026-2036
Global Knitting Machinery Market Size, Share, and Industry Trends Forecast 2026-2036
Global Knitting Machinery Market Foresight
Fast-fashion garment producers is collapsing as technical fabric suppliers and sportswear brands expand capital expenditure on precision knitting systems. Shima Seiki leverages its dominance in computerized flatbed technology for whole-garment production. Mayer & CIE anchors European circular knitting engineering with sustained R&D investment in high-speed cylinder architectures. Santoni specializes in seamless circular machines for athletic apparel, competing on specialized electromechanical integration.
Knitting machinery encompasses electromechanically controlled systems that interloop yarns via needle beds to form structured fabrics, with modern units operating at speeds exceeding 3,000 courses per minute and integrating real-time tension monitoring for dimensional stability. These systems serve commercial textile production across apparel, industrial, and technical end-uses where fabric engineering precision determines performance. Flatbed machines lead in value terms due to whole-garment capability and reduced post-knitting labor, while circular machines dominate volume throughput for standardized sportswear fabric. Electronic control technology captures expanding margin pools as mechanical and pneumatic systems face replacement cycles driven by pattern complexity demands.
The EU Green Deal and REACH frameworks impose chemical and energy-efficiency standards on textile machinery sold across Europe, while China's MIIT enforces GB standards for domestic equipment efficiency and emissions. ISO 9001 and ISO 14001 certifications increasingly gate market access for machinery exporters into regulated procurement channels. Stakeholders must monitor how carbon-border adjustment mechanisms reshape machinery sourcing decisions between Asian manufacturing clusters and nearshore technical textile hubs.
Market Dynamics
Electronic control systems are displacing mechanical and pneumatic architectures across knitting machinery fleets, driven by EU Green Deal energy-efficiency mandates and sportswear brands' demand for pattern complexity that mechanical systems cannot deliver.
Growth Catalysts
- EU Green Deal textile sustainability requirements:Energy-efficiency mandates accelerate replacement cycles for legacy pneumatic systems across European textile manufacturing clusters.
- Technical textile output expansion:China's domestic technical fabric production supports localized machinery procurement, reducing import dependency for high-performance knitting systems.
- Seamless garment production:Sportswear brands expand machine fleets for whole-garment manufacturing, eliminating post-knitting labor and cutting floor space requirements.
Market Restraints
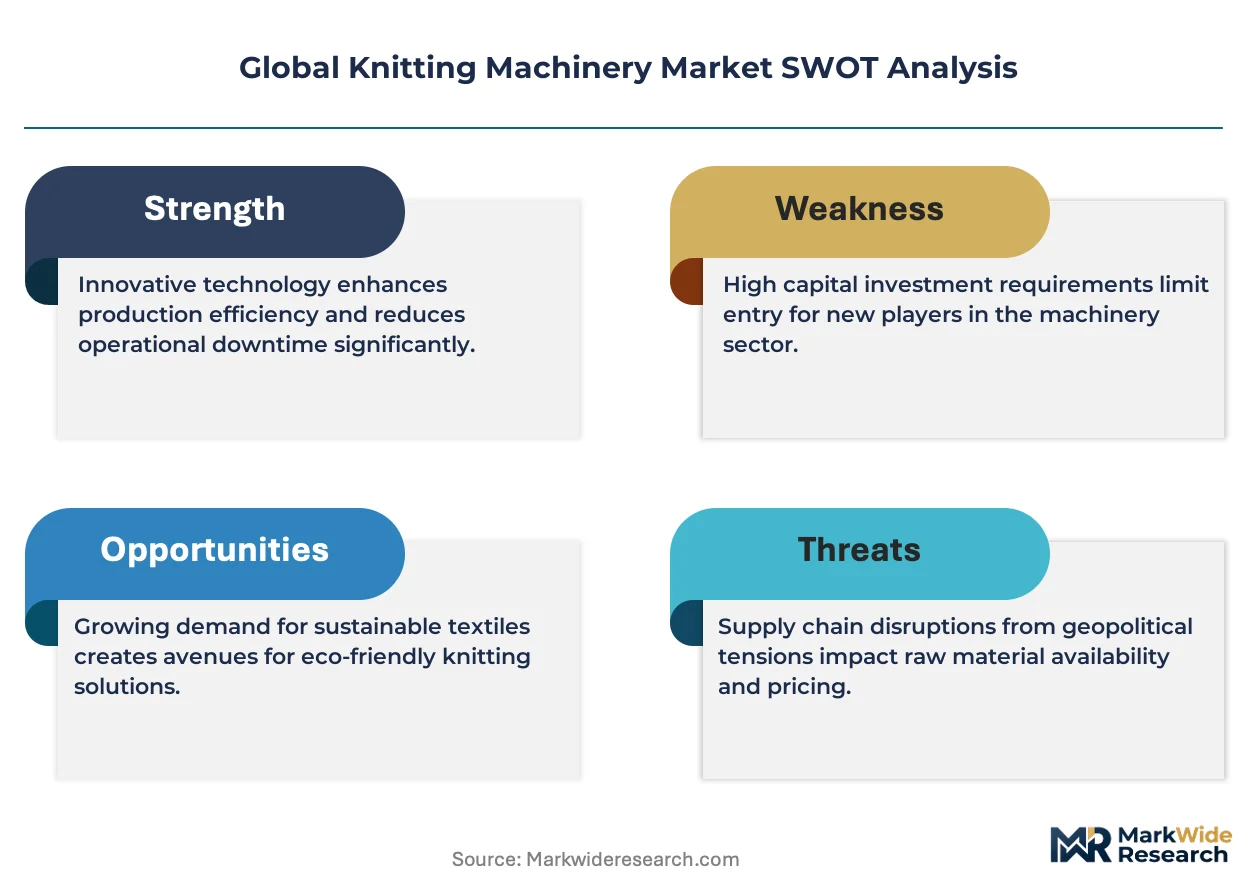
- High-grade steel and precision component costs:Volatility in specialty alloy pricing compresses margins for cylinder and needle bed manufacturers.
- Supply concentration in German and Japanese electromechanical component bases:Dependency on specialized servo motor and encoder suppliers creates vulnerability to regional disruptions.
- REACH chemical compliance for lubricants and coatings:Restricted substance lists force reformulation of machine maintenance consumables, extending certification timelines.
Strategic Opportunities
- India technical textile manufacturing corridors:PLI scheme incentives for technical fabric production create greenfield demand for precision knitting systems in Tamil Nadu and Gujarat.
- Digital twin integration with knitting controllers:Convergence of IoT sensors and predictive maintenance software enables outcome-based service contracts for fleet operators.
- Carbon border adjustment mechanism pre-positioning:Nearshore technical textile hubs in Portugal and Turkey attract machinery investment to circumvent EU carbon tariffs on imported fabrics.
Industry Challenges
- Electromechanical technician scarcity:Shortage of engineers trained in servo system calibration and real-time tension control limits field service capacity expansion.
- ISO 14001 certification complexity:Extended audit timelines for machinery exporters delay market access into regulated European procurement channels.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Knitting Machinery Market |
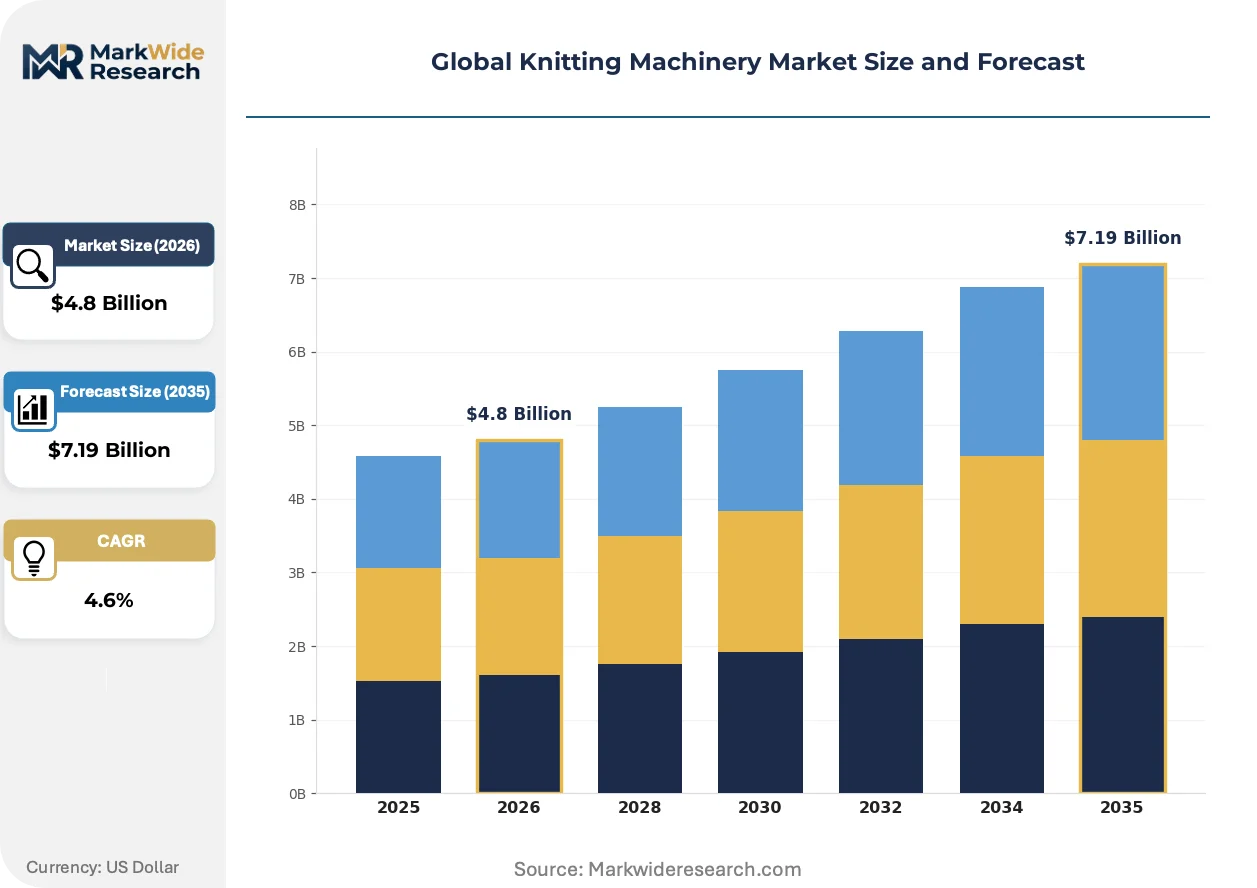
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flatbed Machines, Circular Machines, Warp Knitting Machines, Raschel Machines, Others Technology: Electronic Control, Mechanical, Pneumatic, Computerized, Manual Application: Sportswear Fabric, Technical Textiles, Fashion Apparel, Home Textiles, Industrial Textiles End User Industry: Textile Manufacturers, Garment Producers, Technical Fabric Suppliers, Sportswear Brands |
| Companies Covered | Stoll, Fukuhara, Santoni, Flying Tiger, Orizio, Shima Seiki, Pai Lung, Lamb, Mayer & CIE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Knitting Machinery Market Shifts & Advancements
Real-time tension monitoring and predictive maintenance algorithms are reshaping competitive positioning in knitting machinery, compressing the performance gap between premium electronic systems and mid-tier mechanical alternatives.
Direct-drive servo motors integrated into needle bed actuation are displacing belt-and-pulley mechanical transmission systems. Sportswear fabric producers in Vietnam and Bangladesh adopt these architectures to achieve sub-millimeter gauge consistency at speeds exceeding 3,000 courses per minute. The displacement of mechanical linkages eliminates backlash errors and reduces energy consumption by removing friction losses in power transmission.
China's MIIT GB standards for equipment efficiency and emissions are tightening domestic market entry requirements for imported machinery. Manufacturers must submit third-party testing documentation for energy consumption per kilogram of fabric output. European and Japanese exporters are responding by pre-certifying systems to dual GB-CE standards, extending product development cycles but securing access to the largest machinery procurement market.
After-sales service unbundling is fragmenting traditional machinery procurement relationships. Technical textile producers in Germany and South Korea now purchase base hardware through distributors while contracting directly with software vendors for pattern programming and remote diagnostics. This channel disintermediation compresses OEM service margins and shifts profit pools toward recurring software license revenue.
Global Knitting Machinery Market Segmentation
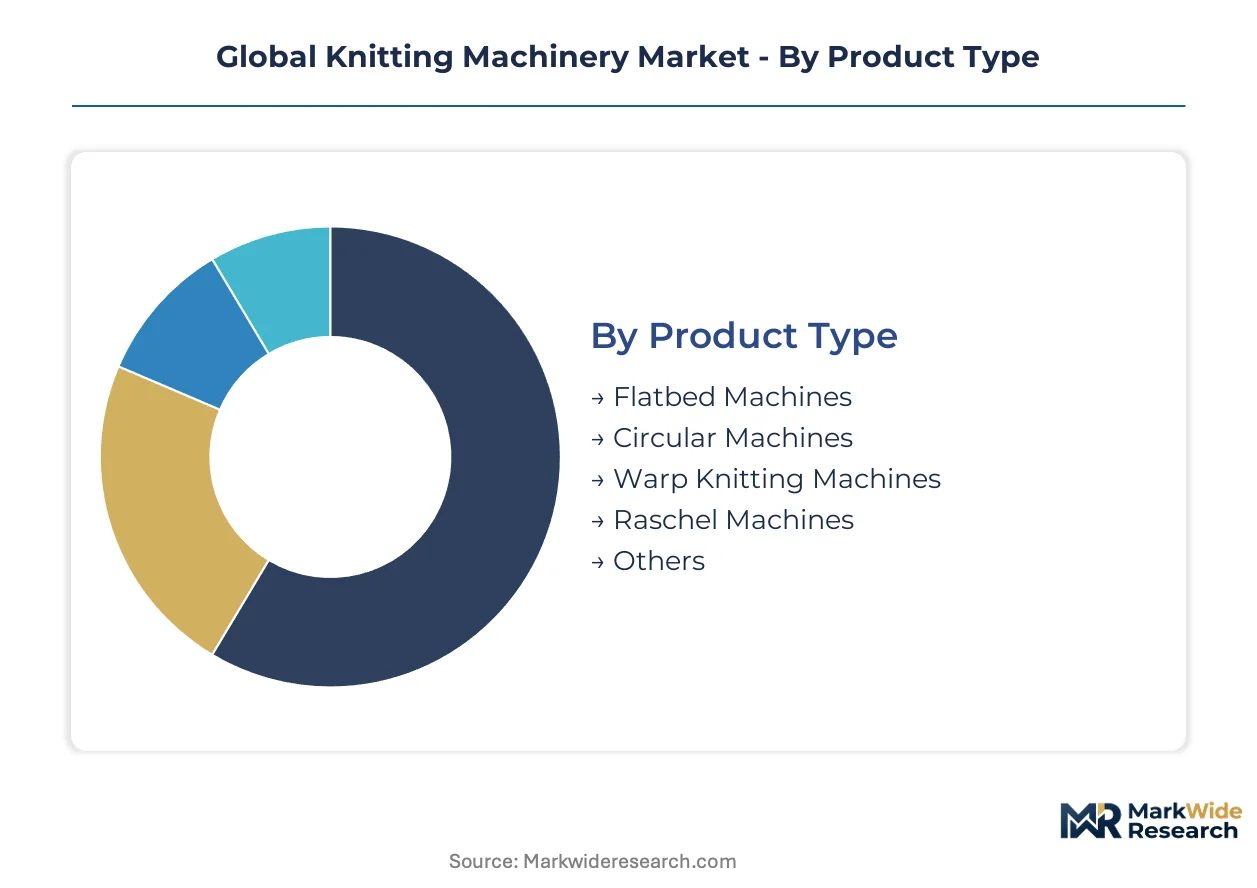
Segmentation in knitting machinery reveals how regulatory pressure, end-use precision requirements, and automation intensity fragment procurement patterns across textile manufacturing clusters. Understanding these divisions exposes where margin pools concentrate and which technology architectures face replacement urgency.
Product Type:
REACH chemical compliance and EU Green Deal energy standards create divergent certification burdens across machine architectures, favoring platforms with integrated electronic control systems over legacy mechanical alternatives.
- Flatbed Machines:Computerized needle bed systems enable whole-garment production without post-knitting assembly. Sportswear brands in Vietnam and Bangladesh expand fleets for seamless athletic apparel, driven by labor cost reduction and floor space optimization. These systems command premium positioning due to pattern complexity capabilities that circular architectures cannot replicate.
- Circular Machines:High-speed cylinder architectures dominate standardized fabric throughput for basic sportswear and technical textiles. German engineering clusters anchor precision component supply for these systems, though China's domestic manufacturers are capturing share in mid-speed segments through MIIT GB standard compliance.
- Warp Knitting Machines:Specialized for technical fabric structures requiring dimensional stability.
- Raschel Machines:Heavy-gauge systems for industrial mesh and netting applications.
- Others:Niche architectures including double-needle bar and specialized lace systems.
Circular machines handle the majority of throughput; flatbed systems are expanding most quickly on share as whole-garment adoption accelerates.
Technology:
Cost tier differentiation separates capital-intensive electronic platforms from maintenance-heavy mechanical fleets, with mid-tier pneumatic systems facing accelerated obsolescence.
- Electronic Control:Servo-driven needle actuation with real-time tension monitoring enables pattern complexity beyond mechanical limits. EU Green Deal mandates accelerate displacement of pneumatic systems across Portugal and Turkey manufacturing corridors, where energy efficiency determines procurement eligibility.
- Computerized:Software-integrated platforms with CAD pattern input and automated stitch correction. Technical fabric suppliers in South Korea adopt these systems for medical textile production requiring ISO 13485 traceability.
- Mechanical:Cam-driven architectures with limited pattern versatility.
- Pneumatic:Compressed air actuation systems facing regulatory phase-out.
- Manual:Artisan-scale production for luxury fashion sampling.
Electronic control systems capture the steepest expansion trajectory; mechanical installations are the fastest to lose share as replacement cycles compress.
Application:
Customer type concentration determines automation intensity, with branded sportswear producers demanding precision that commodity apparel manufacturers cannot justify.
- Technical Textiles:Engineered fabrics for medical, automotive, and filtration end-uses requiring certified dimensional stability. China's domestic output expansion supports localized machinery procurement under MIIT efficiency standards, reducing import dependency for high-performance systems.
- Sportswear Fabric:Moisture-wicking and compression knit structures for athletic apparel brands. Production clusters in Tamil Nadu and Gujarat drive demand following India's PLI scheme incentives for technical fabric manufacturing.
- Fashion Apparel:Seasonal variety production with shorter run lengths.
- Home Textiles:Bedding and upholstery fabrics with lower gauge precision requirements.
- Industrial Textiles:Geotextiles and reinforcement meshes for civil engineering.
Technical textiles absorb the highest equipment investment per meter of output; sportswear fabric applications are climbing fastest as brand sustainability requirements tighten.
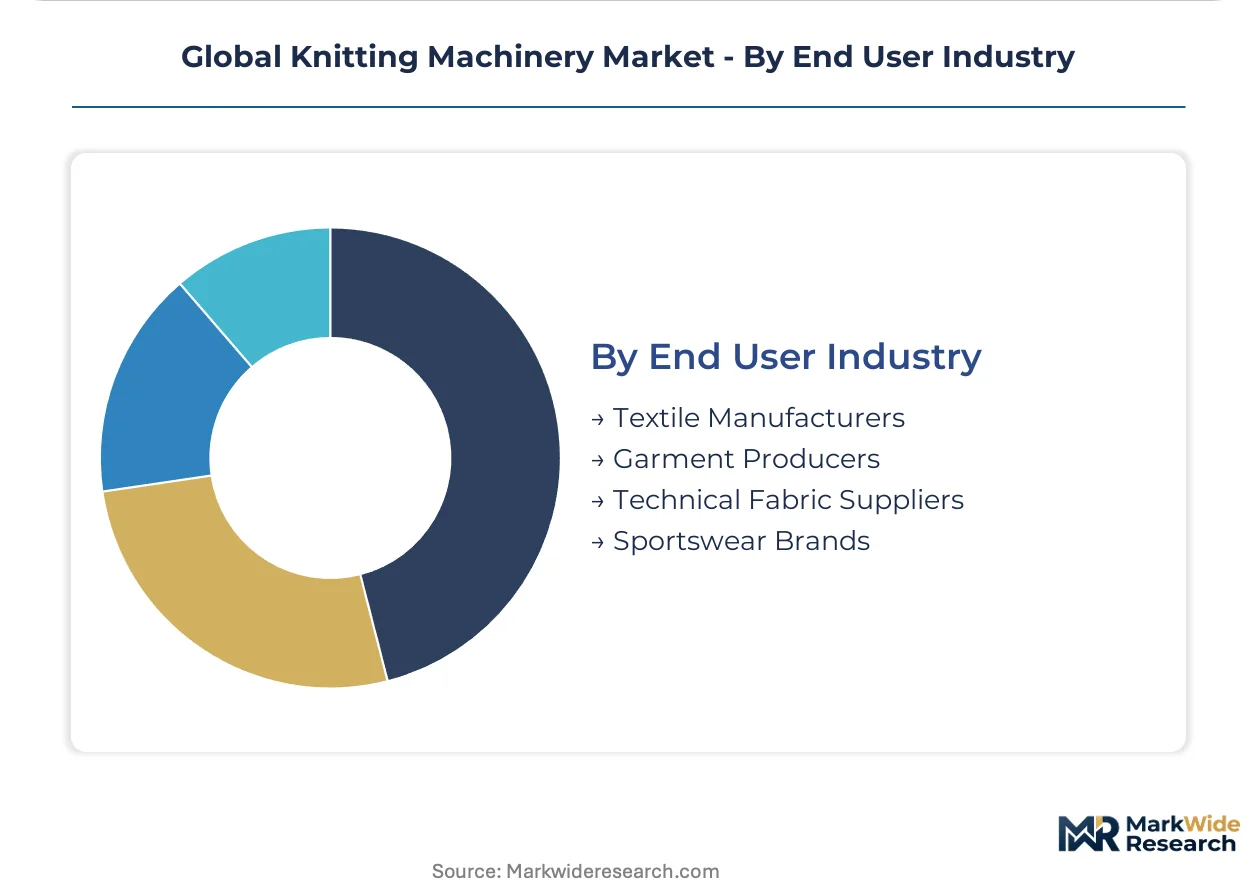
End User Industry:
Supply concentration in electromechanical component bases creates divergent procurement risk profiles across user categories with varying technical service capabilities.
- Sportswear Brands:Vertically integrated producers controlling design through manufacturing with dedicated machinery fleets. These operators prioritize seamless garment capability and energy efficiency credentials for EU market access, contracting directly for remote diagnostics and predictive maintenance software.
- Technical Fabric Suppliers:Specialized producers serving medical, automotive, and filtration OEMs with certified output. German and South Korean operators increasingly unbundle hardware procurement from software licensing, compressing OEM service margins.
- Textile Manufacturers:Commodity fabric producers with price-sensitive procurement.
- Garment Producers:Cut-make-trim operations with limited in-house knitting capacity.
Textile manufacturers represent the largest installed base; sportswear brands are gaining share fastest as vertical integration accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German engineering clusters export precision cylinder components to Portuguese and Turkish technical textile producers seeking EU Green Deal compliance. Chinese domestic manufacturers capture mid-speed circular machine share through MIIT GB standard certification, reducing import dependency for standardized sportswear fabric production.
China
Domestic technical textile output expansion drives localized machinery procurement under MIIT efficiency standards. The country's GB certification requirements for energy consumption per kilogram of fabric output force European and Japanese exporters into extended dual-standard pre-certification cycles. Manufacturing clusters in the Yangtze River Delta and Pearl River Delta absorb the highest concentration of flatbed and circular knitting system deployments.
Germany
Precision component engineering for high-speed cylinder architectures anchors European supply concentration. REACH chemical compliance and EU Green Deal energy-efficiency mandates accelerate pneumatic system replacement across domestic textile manufacturing. Engineering corridors in Baden-Württemberg and North Rhine-Westphalia concentrate servo motor and encoder supplier bases for electromechanical integration.
India
PLI scheme incentives for technical fabric production create greenfield demand corridors in Tamil Nadu and Gujarat. The country's Bureau of Indian Standards enforces equipment efficiency benchmarks that favor electronic control architectures over legacy mechanical alternatives. Sportswear fabric manufacturing clusters in Coimbatore and Surat expand precision knitting system fleets for moisture-wicking and compression knit structures.
Portugal
Nearshore positioning for EU carbon border adjustment mechanism avoidance attracts technical textile machinery investment from Asian fabric importers. The country's alignment with EU Green Deal textile sustainability requirements enables procurement eligibility for energy-efficient electronic systems. Porto and Lisbon metropolitan manufacturing zones concentrate seamless garment production capacity serving continental European sportswear brands.
Turkey
Technical textile hub development targets circumvention of EU carbon tariffs on imported fabrics from Asian supply sources. The country's customs union with the European Union ensures REACH chemical compliance alignment for machinery lubricants and coatings. Bursa and Istanbul industrial zones expand circular and flatbed machine fleets for standardized sportswear fabric serving German and French brand supply chains.
Global Knitting Machinery Market Competitive Landscape
Listed leaders compete with private specialists across electromechanical integration depth, creating a tiered structure where scale-driven fabricators face off against precision-focused niche operators. The vendor base separates into three strategic archetypes: Japanese and German precision engineering houses, Chinese cost-optimized domestic suppliers, and Italian seamless garment specialists. Dominant competitive moves include geographic expansion into India technical textile corridors and technology licensing partnerships for predictive maintenance software integration.
Within the precision engineering tier, Stoll and Shima Seiki occupy positions exemplifying computerized flatbed dominance for whole-garment production, while Mayer & CIE anchors European circular knitting engineering heritage. Santoni represents the seamless circular machine specialization vector competing on electromechanical integration for athletic apparel applications. These named entities serve as archetype anchors rather than exhaustive market coverage, with additional competitive density concentrated among Chinese domestic manufacturers capturing mid-tier share through MIIT GB standard compliance.
| Leading Market Players |
|---|
| Stoll |
| Fukuhara |
| Santoni |
| Flying Tiger |
| Orizio |
| Shima Seiki |
| Pai Lung |
| Lamb |
| Mayer & CIE |
| Others |
Supply & Pricing Matrix
Electronic control system displacement of mechanical and pneumatic architectures simultaneously redraws supply geography toward German and Japanese electromechanical component bases and compresses pricing economics for legacy equipment manufacturers facing accelerated replacement cycles.
Pricing Analysis
Current-generation electronic control systems, prior-generation mechanical architectures, and next-generation AI-integrated predictive maintenance platforms stratify across premium-mid-economy pricing tiers. Price differentiation hinges on ISO 14001 certification grade and after-sales service bundling, with unbundled software licensing emerging as a margin pool. Cost compression in mid-tier pneumatic systems is intensifying because EU Green Deal energy-efficiency mandates disqualify non-compliant equipment from procurement eligibility. Commodity apparel manufacturers exhibit highest price sensitivity, while vertically integrated sportswear brands prioritize energy credentials over unit cost.
Supply Chain Analysis
Germany and Japan anchor precision servo motor and encoder production for high-speed cylinder architectures, while China manufactures mid-speed circular machine frames under MIIT GB standard compliance. Specialty alloy supply for needle beds and cylinders draws from German and Japanese metallurgical suppliers, with high-grade steel pricing volatility creating margin pressure. Single-source vulnerability concentrates in precision electromechanical component supply, where regional disruptions in Baden-Württemberg engineering corridors would cascade through European textile manufacturing. Distribution runs through OEM-direct channels for large sportswear brands and regional distributor networks for mid-tier textile manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Replacement cycle acceleration driven by EU Green Deal energy-efficiency mandates positions the knitting machinery market for cyclical recovery, with regulatory compliance timelines creating predictable demand windows for electronic control system upgrades.
For Market Incumbents: Consolidate field service capacity around electromechanical technician training to address scarcity limiting expansion. Deepen backward integration into precision component supply through partnerships with German servo motor suppliers, mitigating single-source vulnerability. Prioritize dual GB-CE certification investment to secure access to China's domestic procurement market under tightening MIIT efficiency standards. For New Entrants and Emerging Players: Predictive maintenance software integration gaps in incumbent service portfolios create white-space opportunity for outcome-based contracting models. Target India's PLI scheme corridors in Tamil Nadu and Gujarat, where technical textile manufacturing expansion outpaces localized machinery supply. Pursue digital twin licensing partnerships with established hardware distributors to circumvent capital-intensive manufacturing entry barriers. For Investors and Strategic Acquirers: EU carbon border adjustment mechanism implementation reshapes the acquisition landscape toward nearshore technical textile hub exposure in Portugal and Turkey. Long-term viability favors precision engineering specialists with seamless garment capability and energy-efficient platform portfolios. Monitor carbon tariff enforcement intensity as the signal indicating accelerated nearshoring investment and associated machinery demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Dual GB-CE Certification Investment | Pre-certification to China's MIIT standards secures access to the largest machinery procurement market. |
| Predictive Maintenance Software Integration | IoT-enabled remote diagnostics shifts profit pools from hardware margins toward recurring license revenue. |
| Nearshore Manufacturing Footprint Expansion | Portuguese and Turkish production sites circumvent EU carbon tariffs on Asian-imported fabrics. |
| Electromechanical Technician Training Programs | Field service capacity expansion addresses scarcity limiting real-time tension control calibration support. |
| Backward Integration into Precision Components | Captive supply of servo motors and encoders mitigates dependency on German and Japanese supplier bases. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with knitting machinery OEM product managers, textile plant engineers, and aftermarket service directors; and secondary validation through customs trade data, MIIT GB standard documentation, and SEC filings from listed precision component suppliers. Bottom-up triangulation across machinery unit deployment estimates and top-down cross-check against textile manufacturing capacity expansion data ensured methodological consistency.
Across the projection horizon, the analytical framework modeled segmentation across product type, technology generation, end-use application, and regional regulatory cluster. CAGRs were derived from replacement cycle velocity analysis and greenfield capacity addition trajectories. Key inputs included EU Green Deal implementation timelines, India's PLI scheme disbursement schedules, and China's domestic technical textile output expansion rates.
Underlying assumptions cover sustained regulatory enforcement of energy-efficiency mandates and stable specialty alloy pricing, with deviation risk concentrated in carbon border adjustment mechanism implementation delays and electromechanical component supply disruptions. Recalibration cycles align with material shifts in EU textile sustainability regulation and MIIT standard revision announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Textile Machinery and Equipment
Braiding Equipment Market
Textile Machinery and Equipment
Cloth Measuring Machine Market
Textile Machinery and Equipment
Tarpaulin Sheets Market
Textile Machinery and Equipment
US Textile Processing Machinery Market
Textile Machinery and Equipment
Automatic Roll Filters Market
Textile Machinery and Equipment
Warping Machines Market
Textile Machinery and Equipment
Cloth Cutting Machines Market
Textile Machinery and Equipment
Global Rotary Clothes Dryer Market
Textile Machinery and Equipment
Stringing Machines Market
Textile Machinery and Equipment
Global Custom T-Shirt Printing Market
Textile Machinery and Equipment
3D Knitting Machines Market
Textile Machinery and Equipment
Fabric Reversing Machines Market
Textile Machinery and Equipment
Netted Fabrics Market
Textile Machinery and Equipment
Yankee Dryer Market
Textile Machinery and Equipment
Textile Tester Market
Textile Machinery and Equipment
Global Warp Knitting Machine Market