
 Disposable Garment Bags Market | 2026-2036
Disposable Garment Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Disposable Garment Bags Market Analytics
Market Overview
China is narrowing its cost advantage in blown polyethylene film production as Southeast Asian suppliers expand capacity. Novolex Holdings Inc leverages integrated resin-to-bag manufacturing across multiple North American plants. Mondi Group anchors European supply through kraft-paper hybrid lines that serve luxury retail channels. BioBag Americas specializes in compostable resin formulations that meet industrial degradation standards.
Product and Segment Analysis
Disposable garment bags are thin-film or non-woven enclosures, typically 0.5–2.0 mil in thickness, designed to shield apparel from dust, moisture, and handling damage during storage, transport, or post-cleaning delivery. Polyethylene bags dominate volume due to low resin costs and heat-seal compatibility with high-speed converting equipment. Non-woven bags carry premium positioning in hotel and bridal segments where breathability and reusability perceptions justify higher unit pricing. Biodegradable bags represent the fastest-expanding category, though margin pools remain concentrated in custom-thickness polyethylene contracts for national dry cleaner chains.
Regulatory Environment and Outlook
The EPA oversees resin production emissions under Clean Air Act permits, while state-level bag bans in California and New York directly constrain polyethylene demand. The EU REACH framework restricts phthalate plasticizers in garment bag films, pushing converters toward certified alternative chemistries. Stakeholders must monitor emerging extended producer responsibility schemes that could restructure who bears end-of-life collection costs.
Market Dynamics
The EU Single-Use Plastics Directive is compressing polyethylene demand while simultaneously opening margin pools for certified compostable alternatives, forcing converters to reconfigure resin sourcing and extrusion lines simultaneously.
Growth Catalysts
- Organized retail expansion in India:Branded apparel chains and hospitality groups are standardizing garment protection protocols, creating pull for custom-printed non-woven bags with logo integration.
- California's SB 54 extended producer responsibility law:Dry cleaning chains face mandated recycled content thresholds, accelerating contract shifts toward post-consumer resin suppliers.
- Bio-based resin formulation advances:Industrial compostable films meeting ASTM D6400 are achieving heat-seal speeds matching conventional polyethylene, removing throughput penalties.
Market Restraints
- Ethylene feedstock volatility:Gulf Coast petrochemical complexes face hurricane-season disruption risk, transmitting cost spikes to blown film converters within 60-day windows.
- Thailand-Vietnam supply concentration:Southeast Asian capacity additions cluster in two coastal provinces, creating vessel-port bottlenecks during peak export months.
- Biodegradation certification gaps:Home-compostable claims lack harmonized testing protocols, exposing brands to greenwashing liability under FTC Green Guides enforcement.
Strategic Opportunities
- Brazilian formalwear rental platforms:São Paulo and Rio de Janeiro subscription services are scaling reusable garment bag circulation models with deposit-return logistics.
- EU Green Deal public procurement mandates:Municipal laundry contracts now specify compostable packaging, creating anchor demand for certified suppliers.
- RFID-embedded inventory tracking:Convergence of thin-film antenna printing with garment bag extrusion is digitizing dry cleaner logistics without secondary labeling.
Industry Challenges
- Composting infrastructure misalignment:Industrial degradation requires municipal anaerobic digesters, yet facility density varies tenfold between German and Polish regions.
- Extruder retooling timelines:Shifting from polyethylene to PLA blends demands screw and die modifications averaging 14-week procurement cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Disposable Garment Bags Market |
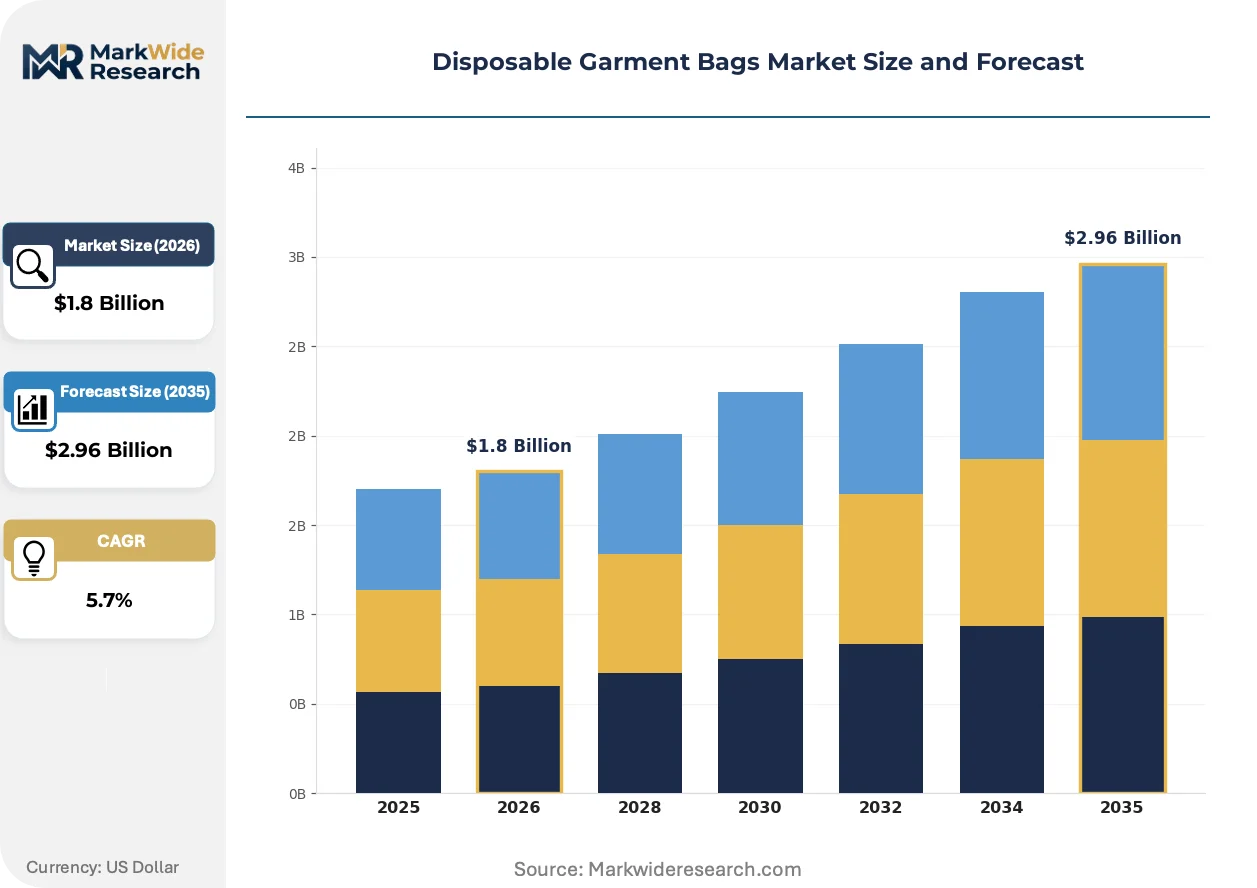
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic Bags, Non-Woven Bags, Polyethylene Bags, Biodegradable Bags End User: Retail Stores, Hotels, Dry Cleaners, E-commerce Thickness: Lightweight, Medium Weight, Heavyweight, Custom Thickness Size: Small, Medium, Large, Extra Large |
| Companies Covered | International Plastics Inc, Novolex Holdings Inc, Ampac Holdings, Mondi Group, Berry Global Group, Inteplast Group, ProAmpac, Advance Polybag, BioBag Americas, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Disposable Garment Bags Market Evolving Landscape
Converters are racing to embed traceability and circularity into film formulations before extended producer responsibility schemes harden compliance deadlines across major demand centers.
Thin-film RFID antenna integration is digitizing garment tracking through the dry cleaning supply chain. National chains in Germany and Japan are piloting bags with printed conductive traces that survive heat-sealing and solvent exposure. This convergence is digitizing inventory reconciliation, compressing loss rates and labor hours previously consumed by manual sorting.
REACH Annex XVII phthalate restrictions are forcing plasticizer substitutions in garment bag films. European converters are migrating to citrate-based alternatives certified under ECHA's substitution roadmap. Bridal and luxury retail segments face the tightest compliance windows, with Italian and French suppliers accelerating reformulation ahead of 2025 enforcement checkpoints.
Subscription-based protective packaging is displacing single-use bags in premium apparel e-commerce. Dutch and UK fashion rental platforms now circulate reusable non-woven enclosures with prepaid return logistics. This model concentrates most visibly in urban corridors with dense reverse-logistics networks, compressing per-garment packaging costs below disposable alternatives at scale thresholds above 10,000 monthly rotations.
Disposable Garment Bags Market Segmentation
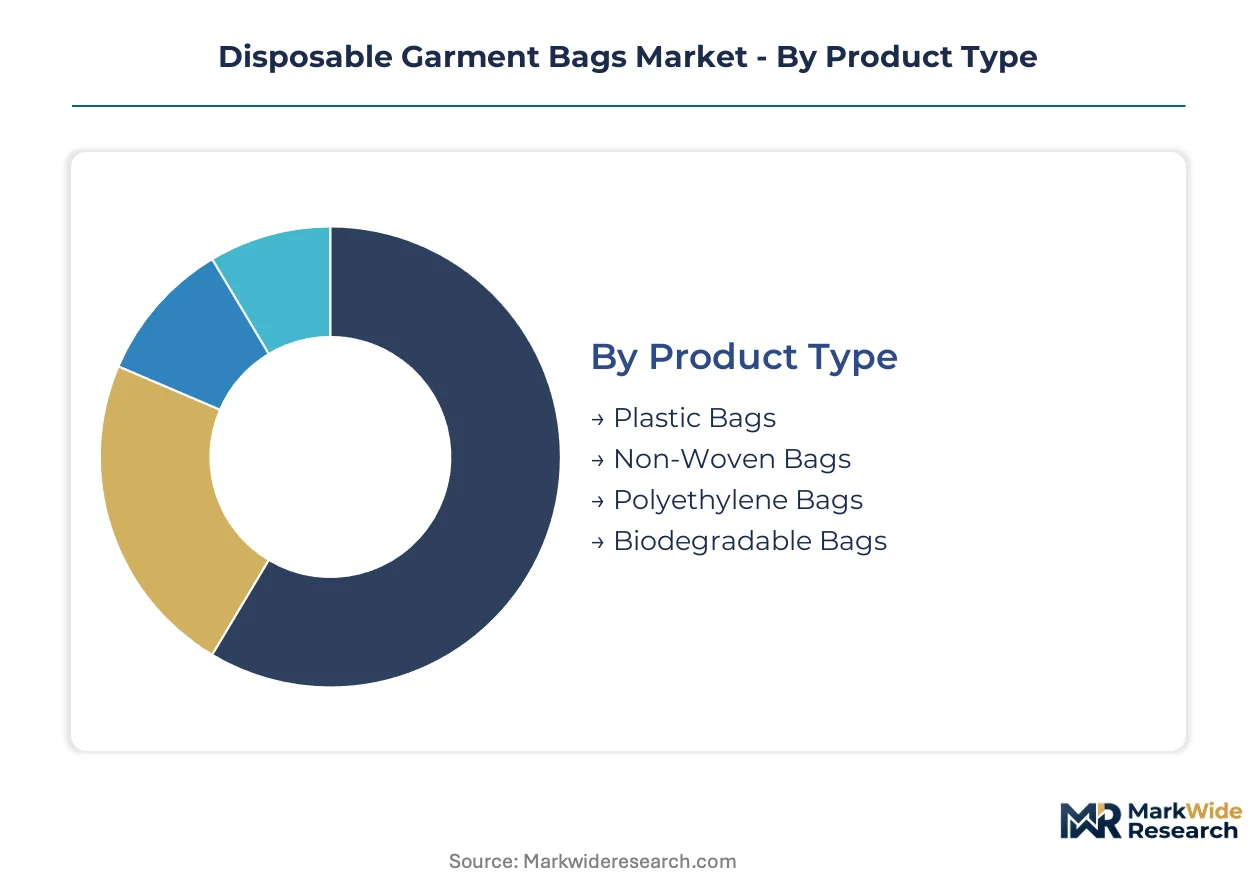
Disposable garment bags serve divergent functional requirements across dry cleaning logistics, retail presentation, and hospitality protocols. Segmentation reveals how material science, thickness engineering, and end-use specifications create distinct margin pools and sourcing strategies.
Product Type:
Material composition spans petroleum-derived films, synthetic non-wovens, and emerging bio-based alternatives with divergent degradation pathways and heat-seal compatibility.
- Polyethylene Bags:Blown low-density polyethylene films dominate volume due to resin cost efficiency and compatibility with high-speed converting equipment. Dry cleaning chains in the United States standardize these for post-cleaning delivery, though California's SB 54 recycled content mandates are forcing formulation shifts toward post-consumer resin.
- Biodegradable Bags:Industrial compostable films meeting ASTM D6400 standards are expanding fastest as EU Single-Use Plastics Directive compliance deadlines approach. Municipal laundry contracts in Germany now specify certified compostable packaging, creating anchor demand for suppliers with anaerobic digester partnerships.
- Plastic Bags:Conventional polypropylene and PVC formulations persist in budget dry cleaning segments where regulatory pressure remains lighter.
- Non-Woven Bags:Spunbond polypropylene structures serve hotel and bridal segments where breathability perceptions support premium positioning.
The dominant share belongs to polyethylene formulations, while biodegradable alternatives are closing the gap fastest.
End User:
Customer archetypes range from high-frequency institutional buyers to fragmented retail operators with divergent customization requirements and contract scale.
- Dry Cleaners:National chains negotiate custom-thickness polyethylene contracts with integrated converters, prioritizing heat-seal reliability and print registration for branding. California's extended producer responsibility law is accelerating shifts toward post-consumer resin suppliers.
- Hotels:Luxury hospitality groups in India standardize branded non-woven garment protection for guest laundry services, integrating logo printing into procurement specifications.
- Retail Stores:Apparel chains concentrate demand in custom-printed bags with size-specific dimensions for formalwear and outerwear categories.
- E-commerce:Fashion rental platforms in the Netherlands and United Kingdom pilot reusable non-woven circulation models with prepaid return logistics.
Dry cleaning networks command the largest contract volumes, though hospitality procurement is expanding most quickly.
Thickness:
Gauge selection balances puncture resistance against material cost and heat-seal energy requirements across handling intensity profiles.
- Custom Thickness:National dry cleaner chains specify precise mil ratings optimized for automated bagging equipment throughput and garment category protection levels.
- Medium Weight:1.0–1.5 mil films serve standard retail and hospitality applications where handling frequency demands moderate durability.
- Lightweight:Sub-0.8 mil formulations dominate high-volume disposable applications with minimal reuse cycles.
- Heavyweight:2.0+ mil structures protect formalwear and leather goods through extended storage and transport logistics.
Custom thickness specifications capture the premium contract tier, while medium weight films serve the broadest application base.
Size:
Dimension standardization follows apparel category norms with limited customization beyond logo integration.
- Large:Coat and gown dimensions dominate dry cleaning volume with established length and girth specifications.
- Medium:Standard shirt and blouse sizes serve the highest transaction frequency in retail and hospitality.
- Small:Accessory and children's apparel formats occupy niche procurement with limited contract scale.
- Extra Large:Bridal and formalwear dimensions command premium unit pricing with specialized handling requirements.
Large format bags anchor procurement volumes, while extra large segments generate the highest unit margins.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA regulations under the Clean Air Act govern resin production emissions across the United States, establishing the baseline environmental compliance framework that shapes operational standards for polyethylene film manufacturers serving dry cleaning and retail channels.
United States
Dry cleaning chains in California and New York face state-level bag bans and SB 54 extended producer responsibility mandates. The EPA oversees Clean Air Act permits for Gulf Coast petrochemical complexes supplying ethylene feedstock. Houston-area blown film converters supply national dry cleaner networks with custom-thickness polyethylene contracts.
Germany
Municipal laundry contracts now specify compostable packaging under EU Green Deal public procurement mandates. The ECHA REACH framework restricts phthalate plasticizers, pushing converters toward citrate-based alternatives. Industrial clusters in North Rhine-Westphalia anchor European supply for kraft-paper hybrid lines serving luxury retail.
China
Organized retail expansion drives demand for branded garment protection programs in tier-one cities. The MEE enforces dual carbon goals that tighten emissions standards for blown film production. Yangtze River Delta manufacturers are narrowing cost advantages as Southeast Asian suppliers expand capacity.
India
Branded apparel chains and hospitality groups in Maharashtra and Karnataka standardize logo-integrated non-woven bags for guest laundry services. BIS certification requirements shape procurement specifications for organized retail. Delhi-NCR dry cleaning networks are scaling polyethylene garment bag usage as operational standards tighten.
Brazil
Formalwear rental platforms in São Paulo and Rio de Janeiro pilot reusable garment bag circulation models with deposit-return logistics. ANVISA oversees packaging material safety standards for apparel protection products. Southeast industrial zones around São Paulo state concentrate converting capacity for South American distribution.
Disposable Garment Bags Market Competitive Landscape
Capability concentration sits with integrated resin-to-bag manufacturers; scale advantage sits with high-volume converters serving national dry cleaner chains. The market structures around three tiers: multinational packaging conglomerates with extrusion and converting assets, regional specialists in biodegradable formulations, and captive operations of major retail and hospitality groups. Dominant competitive moves include backward integration into resin compounding and strategic partnerships with municipal composting facilities to secure end-of-life certification pathways.
Among North American integrated manufacturers, Novolex Holdings Inc and Berry Global Group exemplify the scale-driven tier with multi-plant resin-to-bag manufacturing footprints. BioBag Americas occupies a position within the certified compostable specialist archetype, anchoring industrial biodegradable formulation capabilities that meet ASTM D6400 standards.
| Leading Market Players |
|---|
| International Plastics Inc |
| Novolex Holdings Inc |
| Ampac Holdings |
| Mondi Group |
| Berry Global Group |
| Inteplast Group |
| ProAmpac |
| Advance Polybag |
| BioBag Americas |
| Others |
Value Network & Pricing Analysis
Shanghai-to-Los Angeles container freight corridors transmit resin cost volatility directly to polyethylene garment bag converters, compressing margins for mid-tier suppliers while amplifying price differentiation between Gulf Coast-integrated manufacturers and Southeast Asian importers serving dry cleaning chains.
Pricing Analysis
Price spreads between North American and Southeast Asian supply widen during ethylene feedstock disruptions, with Gulf Coast petrochemical complexes commanding premium positioning. Pricing stratifies across certified compostable, post-consumer resin, and virgin polyethylene tiers based on regulatory compliance burden and heat-seal performance specifications. Cost compression in standard polyethylene runs through California's SB 54 recycled content mandates, which force formulation shifts without full cost pass-through. National dry cleaner chains exhibit lowest price sensitivity due to contract scale and equipment integration, while independent operators and budget hospitality segments face acute margin pressure.
Supply Chain Analysis
Contract manufacturing concentrates with Novolex Holdings Inc, Berry Global Group, and Mondi Group operating integrated resin-to-bag facilities across multiple coastal provinces. Raw material flows draw from Gulf Coast ethylene crackers, Yangtze River Delta blown film plants, and European kraft-paper hybrid lines serving luxury retail channels. Single-source vulnerability concentrates in Thailand-Vietnam coastal provinces where vessel-port bottlenecks spike during peak export windows. Distribution runs through national dry cleaner chain procurement offices, hospitality group central purchasing, and regional converting distributors serving fragmented retail operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Disposable garment bags are approaching a platform-economics inflection where RFID-embedded inventory tracking and subscription-based reusable models threaten single-use volume, requiring stakeholders to bet on interoperability with dry cleaner logistics software ecosystems.
For Market Incumbents: Harden defensible positions through backward integration into post-consumer resin compounding and captive anaerobic digester partnerships for compostable certification. California's extended producer responsibility mandates threaten virgin polyethylene contract volumes, making certified alternative chemistries the priority capability investment. National chain relationships provide channel control leverage against emerging reusable platform competitors.
For New Entrants and Emerging Players: Build out biodegradable formulation capabilities targeting municipal laundry contracts in Germany and EU Green Deal public procurement mandates. White-space concentrates in industrial compostable films with ASTM D6400 certification where incumbent retooling timelines create 14-week supply gaps. Go-to-market should anchor through anaerobic digester partnerships that secure end-of-life certification pathways ahead of compliance deadlines.
For Investors and Strategic Acquirers: Carve-out targets emerge from multinational packaging conglomerates seeking to divest non-core converting assets amid resin volatility. Long-term viability favors suppliers with dual polyethylene and bio-based production lines capable of serving both regulatory environments. Monitor EU Single-Use Plastics Directive enforcement checkpoints and California recycled content threshold escalations as demand inflection signals.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Gulf Coast petrochemical access insulates against ethylene feedstock volatility during hurricane season disruptions. |
| Anaerobic Digester Partnership Formation | German municipal laundry contracts now require certified compostable packaging with verified end-of-life pathways. |
| RFID-Embedded Film Development | Printed conductive traces surviving heat-sealing digitize dry cleaner inventory reconciliation without secondary labeling costs. |
| Post-Consumer Resin Capacity Expansion | California SB 54 mandates force national chains toward suppliers with verified recycled content supply chains. |
| Reusable Circulation Model Pilot | Dutch fashion rental platforms demonstrate deposit-return logistics compressing per-garment packaging costs below disposable alternatives. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with dry cleaner chain procurement directors, hospitality group supply chain managers, blown film converting plant engineers, and municipal laundry contract administrators. Secondary validation drew from EPA Clean Air Act permit filings, ECHA REACH substance restriction updates, EU Single-Use Plastics Directive implementation timelines, and customs trade data on polyethylene film imports. Bottom-up contract volume analysis triangulated against top-down resin consumption estimates to establish market sizing.
Calibration against historical price elasticities and regulatory compliance cost curves shaped the analytical framework across the analysis window. Segmentation dimensions modeled include material composition, end-user archetype, thickness specification, and regional regulatory cluster. CAGRs derived from weighted scenario analysis incorporating feedstock volatility, capacity expansion timelines, and substitution elasticity between polyethylene and biodegradable alternatives. Forecast inputs integrated ethylene cracker operating rates and municipal composting facility density differentials.
The forecast holds incumbent behavior within observed patterns; aggressive moves by bio-based resin specialists or reusable platform operators would shift outcomes beyond modeled ranges. Quarterly review of EU Green Deal procurement mandate adoption rates and California recycled content compliance thresholds is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Textile Machinery and Equipment
Braiding Equipment Market
Textile Machinery and Equipment
United States Fabric Shavers Market
Textile Machinery and Equipment
Mesh Tarpaulin Sheets Market
Textile Machinery and Equipment
Yankee Dryer Market
Textile Machinery and Equipment
Middle East and Africa Textile Films Market
Textile Machinery and Equipment
Mexico Screen Printing Mesh Market
Textile Machinery and Equipment
Industrial Laundry Market
Textile Machinery and Equipment
Textile Tester Market
Textile Machinery and Equipment
Plasma Surface Treatment Machine for Leather Market
Textile Machinery and Equipment
Webbing Cutting Machine Market
Textile Machinery and Equipment
Saddle Stitching Machine Market
Textile Machinery and Equipment
Braiding Machine Market
Textile Machinery and Equipment
Stringing Machines Market
Textile Machinery and Equipment
Global Spinning Machinery Market
Textile Machinery and Equipment
Sewing Machine Component Market
Textile Machinery and Equipment
Global Circular Knitting Machine Market