
 Drop Cloth Market | 2026-2036
Drop Cloth Market Size, Share, and Industry Trends Forecast 2026-2036
Drop Cloth Market Foresight
Market Context
China is tilting toward expanded woven polypropylene capacity to serve export-oriented drop cloth fabrication. Berry Plastics leverages its North American film extrusion footprint to supply contractor-grade plastic sheeting for containment applications. Milliken & Company anchors the premium canvas segment through specialized textile finishing that resists paint bleed-through and extends reuse cycles.
Technical Definition and Segment Structure
A drop cloth is a protective covering, typically fabricated from woven cotton canvas, spunbond polypropylene, or polyethylene film in weights ranging from 8 oz to 12 oz per square yard, designed to shield floors, furniture, and fixtures from paint splatter, dust, and debris during surface finishing operations. The material type dimension shows canvas sustaining its position in professional painter channels where breathability and slip resistance command price premiums, while polypropylene displaces lighter plastic films in commercial construction due to tear strength and foldability. Usage type splits reveal indoor residential applications as the mature volume base, with outdoor commercial usage representing the faster-growing margin pool where UV-stabilized and waterproof specifications apply.
Regulatory Environment and Outlook
The US EPA regulates volatile organic compound emissions from architectural coatings, indirectly shaping jobsite containment requirements that specify washable, reusable drop cloths over disposable alternatives. REACH compliance in Europe restricts certain phthalate plasticizers in PVC-based protective sheeting, redirecting formulation toward polyethylene and non-woven alternatives. Stakeholders must monitor evolving extended producer responsibility frameworks in multiple jurisdictions that could reclassify single-use protective textiles as regulated waste streams.
Market Dynamics
California's Title 24 building efficiency standards are compressing procurement timelines for reusable containment textiles, forcing contractors to abandon single-use plastic sheeting in favor of washable canvas and synthetic alternatives that satisfy material containment protocols.
Growth Catalysts
- Residential Renovation Surge:North American housing stock aging past 40 years is generating sustained repaint and refinishing volumes that elevate contractor-grade drop cloth consumption through professional painter networks.
- REACH Phthalate Restrictions:ECHA's evolving restrictions on plasticizers in PVC-based protective sheeting are redirecting European formulation toward polyethylene and non-woven polypropylene alternatives.
- Canvas Breathability Premium:Professional painting contractors specify woven cotton for its slip resistance and paint absorption properties, sustaining price premiums over synthetic substitutes in high-end residential channels.
Market Restraints
- Cotton Input Volatility:Weather-driven fluctuations in Texas and India cotton harvests create margin pressure for canvas fabricators dependent on ring-spun yarn supply.
- Chinese Woven Polypropylene Concentration:Export-oriented capacity expansion in Zhejiang and Jiangsu provinces concentrates upstream supply risk for North American and European drop cloth assemblers.
- Lightweight Film Substitution Ceiling:Ultra-thin polyethylene sheeting retains cost advantage in DIY and one-time residential applications, capping premium material penetration at the consumer tier.
Strategic Opportunities
- Extended Producer Responsibility Tailwinds:EU frameworks reclassifying single-use protective textiles as regulated waste streams create regulatory pull for durable, multi-cycle canvas and synthetic products.
- UV-Stabilized Outdoor Specification:Commercial construction and infrastructure maintenance sectors in Australia and the southern United States are formalizing waterproof, UV-resistant drop cloth standards for bridge and exterior building work.
- Direct Contractor E-Procurement:Specialized industrial supply platforms are disintermediating traditional distributor relationships, enabling manufacturers to capture margin through subscription replenishment models.
Industry Challenges
- Multi-Material Certification Complexity:Drop cloths combining cotton canvas with synthetic backing layers must satisfy conflicting textile safety standards across EPA, OSHA, and state-level environmental regulations.
- Reuse Cycle Verification:Commercial buyers increasingly demand documented wash-count durability data, forcing suppliers to invest in accelerated abrasion testing infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drop Cloth Market |
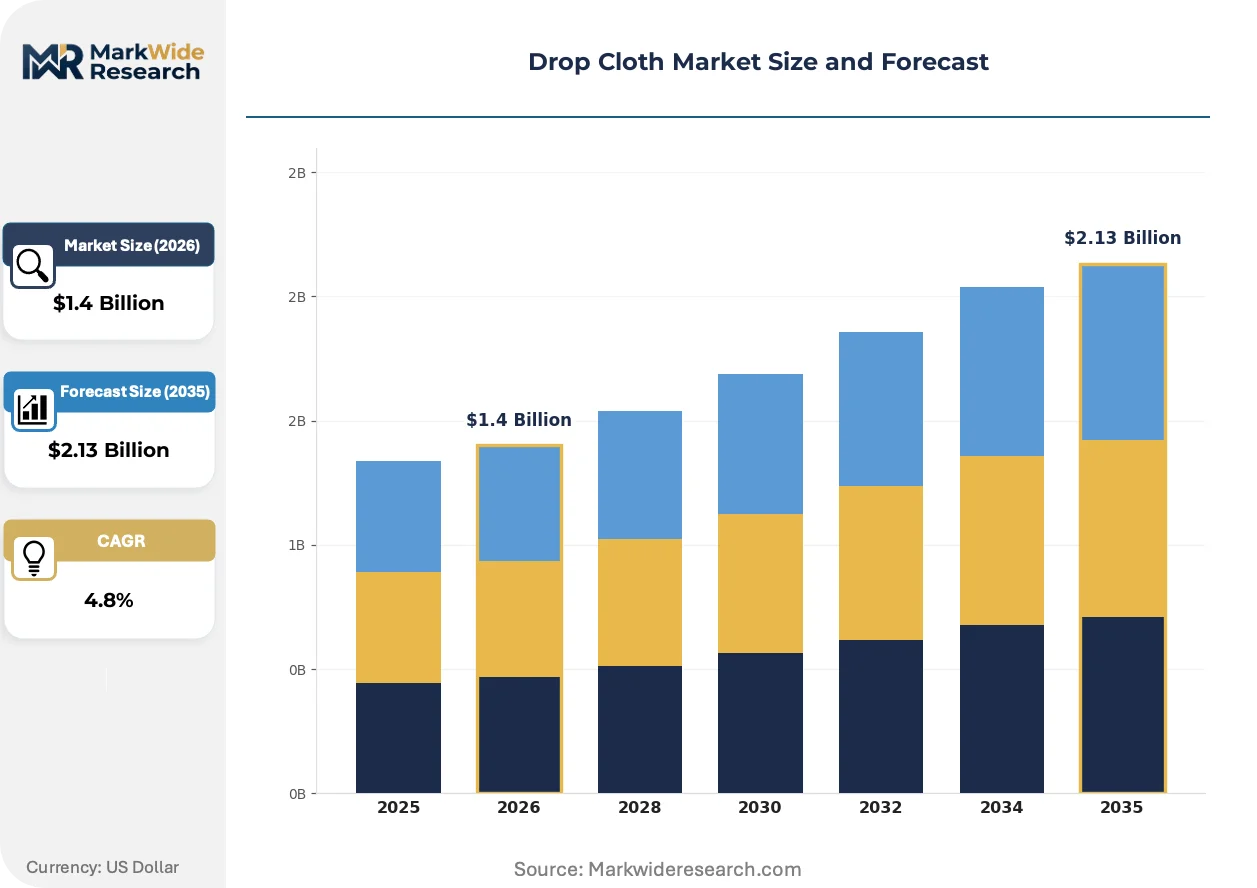
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.13 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Canvas, Plastic, Polypropylene, Cotton Usage Type: Indoor, Outdoor, Commercial, Residential Thickness: Lightweight, Medium, Heavyweight, Ultra-Heavyweight End User: Contractors, DIY Enthusiasts, Painters, Event Planners |
| Companies Covered | PSB Exports, Berry Plastics, KS International Inc., Chicago Canvas & Supply, Milliken & Company, Taihongdropcloth, 3M, Sigman Tarp, Homaster Co. Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drop Cloth Market Shifts & Advancements
Digital inventory management and predictive replenishment systems are rewiring how contractors specify and source protective textiles, compressing traditional seasonal buying patterns into continuous consumption models.
Spunbond-meltblown-spunbond (SMS) composite nonwovens are virtualizing the functional boundary between breathable canvas and impermeable plastic sheeting. Large-scale commercial painting contractors in the United States are specifying SMS for hospital and cleanroom environments where particulate containment and breathability must coexist. This material convergence is virtualizing the traditional segmentation between professional canvas and disposable film markets.
EPA volatile organic compound emission regulations for architectural coatings are tightening jobsite containment documentation requirements. Contractors in California, New York, and Massachusetts must now demonstrate washable, reusable protective material use to satisfy inspection protocols. The premium canvas segment is responding with specialized textile finishing that accelerates paint release during industrial laundering.
Professional painting crews are consolidating supplier relationships through integrated procurement platforms that bundle drop cloths with coatings, tape, and masking materials. This channel compression disadvantages standalone textile suppliers while rewarding manufacturers with full jobsite containment portfolios. The shift is most visible in metropolitan contractor markets where crew size and project velocity demand just-in-time material availability.
Drop Cloth Market Segmentation
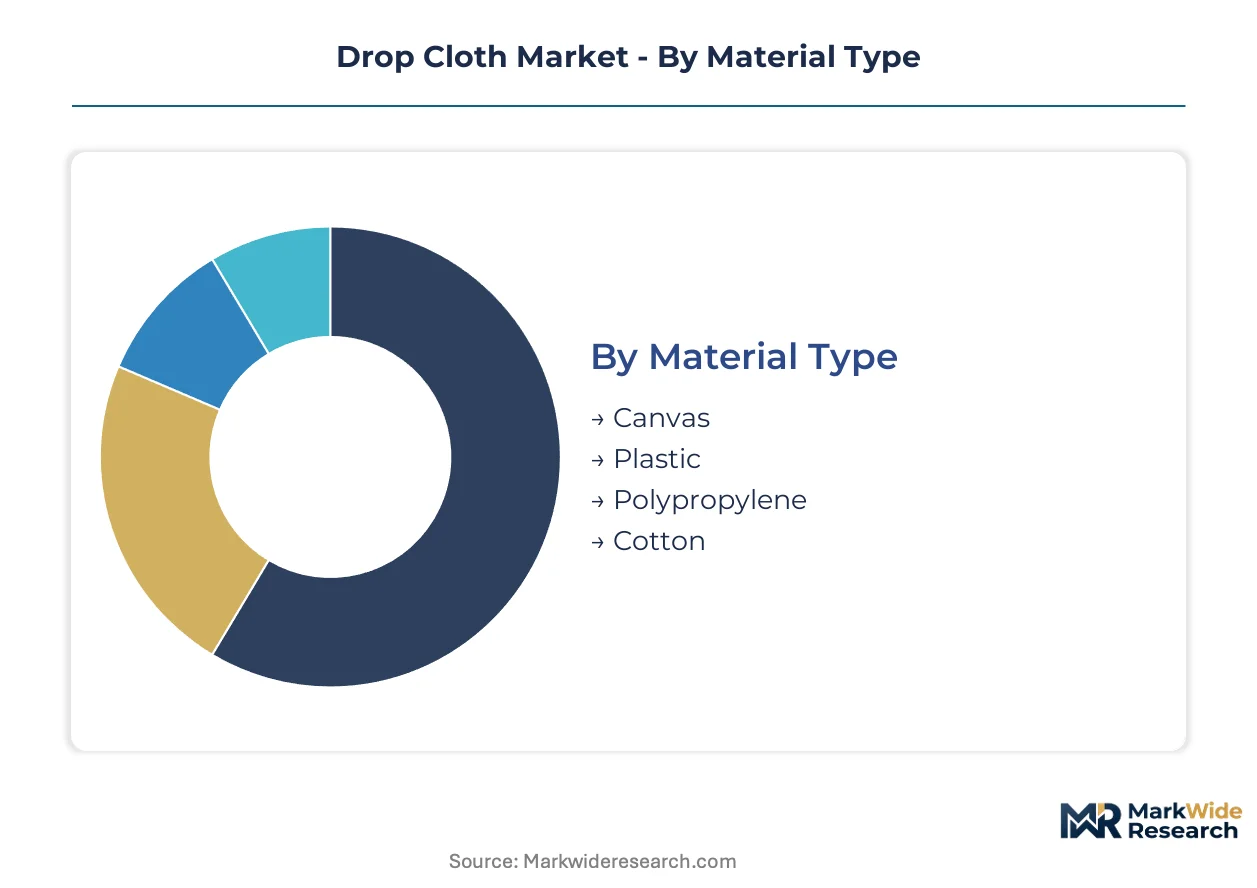
Drop cloth procurement patterns diverge sharply across material specifications and end-user workflows. Professional contractors prioritize wash-cycle durability and slip resistance, while residential consumers trade performance for unit cost in one-time applications.
Material Type:
The use-case spectrum spans breathable woven textiles for precision finishing to impermeable films for dust containment in demolition environments.
- Canvas:Woven cotton construction in 8-12 oz weights delivers paint absorption and floor grip that professional painters specify for high-end residential work. California contractors facing Title 24 containment mandates are upgrading to heavy-duty canvas that survives industrial laundering cycles.
- Polypropylene:Spunbond nonwoven fabrics combine tear resistance with foldability, displacing plastic films in commercial construction where crew mobility matters. REACH phthalate restrictions in Europe are accelerating formulation shifts toward this substrate.
- Plastic:Polyethylene sheeting retains dominance in DIY channels where single-use economics outweigh durability concerns.
- Cotton:Natural fiber variants serve specialty applications requiring breathability without synthetic additives, though harvest volatility constrains supply security.
The dominant share belongs to canvas, while polypropylene is closing the gap fastest.
Usage Type:
Cost tier stratification separates specification-grade containment from disposable protection, with commercial buyers absorbing premium pricing for documented compliance.
- Indoor:Residential repaint and refinishing generates baseline volume through painter networks and big-box retail, with breathability specifications preventing moisture trapping on hardwood surfaces.
- Commercial:Hospital, cleanroom, and institutional projects specify SMS composite nonwovens where particulate containment meets OSHA ventilation requirements. This segment commands 3-4x unit pricing over residential alternatives.
- Outdoor:UV-stabilized and waterproof specifications apply to bridge maintenance and infrastructure work in Australia and the southern United States.
- Residential:Homeowner-driven applications favor lightweight polyethylene for furniture protection during single-room projects.
Indoor residential work carries the volume base, with commercial applications expanding most quickly on regulatory tailwinds.
Thickness:
Customer type dictates mil-weight selection, with professional crews specifying calibrated durability against consumer preference for handling convenience.
- Heavyweight:10-12 oz canvas and 6-mil polyethylene serve commercial contractors requiring documented reuse cycles under EPA containment protocols.
- Medium:8 oz cotton and 4-mil synthetics balance durability with portability for renovation specialists serving mixed residential-commercial portfolios.
- Lightweight:Sub-2-mil films and 6 oz textiles target DIY consumers prioritizing low unit cost and compact storage.
- Ultra-Heavyweight:Reinforced laminates and 15 oz canvas protect against abrasive debris in industrial demolition and infrastructure maintenance.
Heavyweight specifications anchor professional procurement, though medium-weight alternatives are gaining share fastest among independent renovation contractors.
End User:
Volume concentration sits with repeat-purchase professional channels, while event and DIY segments exhibit sporadic demand spikes tied to seasonal patterns.
- Contractors:Integrated painting, flooring, and restoration crews consume drop cloths as line-item consumables, with e-procurement platforms compressing replenishment cycles into continuous subscription models.
- Painters:Specialized finishing contractors specify canvas breathability and textile finishing that accelerates paint release during industrial washing.
- DIY Enthusiasts:Home improvement retailers capture this segment through seasonal promotions bundling lightweight sheeting with masking materials.
- Event Planners:Temporary floor protection for exhibitions and hospitality installations drives demand for branded, color-matched synthetic alternatives with rapid deployment features.
Contractors hold the dominant procurement position, while event planners are expanding fastest as experiential marketing budgets recover.

Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Long Beach anchors trans-Pacific resin flows that supply North American polyethylene sheeting production, while Rotterdam's petrochemical corridor feeds European spunbond nonwoven capacity for contractor-grade containment textiles.
United States
Residential renovation volumes in Texas and Florida drive canvas consumption through professional painter networks. EPA volatile organic compound regulations for architectural coatings mandate washable, reusable containment materials in California, New York, and Massachusetts. The Los Angeles-Long Beach metro cluster concentrates textile finishing operations that serve West Coast contractor procurement.
Germany
Commercial construction recovery across Bavaria and North Rhine-Westphalia elevates demand for SMS composite nonwovens in hospital and cleanroom applications. ECHA REACH restrictions on phthalate plasticizers redirect PVC-based protective sheeting formulation toward polyethylene alternatives. The Stuttgart industrial corridor hosts specialized textile converters serving Central European renovation specialists.
China
Zhejiang and Jiangsu province capacity expansion in woven polypropylene targets export-oriented drop cloth fabrication for North American and European assemblers. The country's national environmental regulator enforces stricter industrial emissions standards that elevate production costs for smaller fabricators. The Yangtze River Delta cluster concentrates spunbond nonwoven capacity serving domestic commercial construction demand.
Australia
Infrastructure maintenance programs in Queensland and New South Wales formalize UV-stabilized, waterproof drop cloth specifications for bridge and exterior building work. The Therapeutic Goods Administration's overlapping jurisdiction with construction safety standards creates multi-agency compliance requirements for hospital-grade containment textiles. The Sydney- Melbourne corridor anchors distribution networks serving commercial painting contractors.
India
Maharashtra and Gujarat state construction growth generates baseline demand for medium-weight canvas and synthetic alternatives in mixed residential-commercial portfolios. The Bureau of Indian Standards textile safety protocols create certification barriers for imported protective materials. The Mumbai-Pune industrial belt concentrates cotton processing capacity that supplies domestic canvas fabricators.
Drop Cloth Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream. The vendor base organizes around three strategic archetypes: diversified materials conglomerates with film extrusion and textile finishing capabilities, regional canvas converters serving professional painter networks, and specialized nonwoven producers targeting commercial construction channels. Capacity expansion and portfolio diversification represent the dominant competitive moves, with players extending from core materials into integrated jobsite containment offerings.
Among North American fabricators, Berry Plastics and Milliken & Company exemplify the materials-to-systems expansion pattern, while Chicago Canvas & Supply occupies a position within the regional specialist tier serving contractor-grade procurement channels.
| Leading Market Players |
|---|
| PSB Exports |
| Berry Plastics |
| KS International Inc. |
| Chicago Canvas & Supply |
| Milliken & Company |
| Taihongdropcloth |
| 3M |
| Sigman Tarp |
| Homaster Co. Limited |
| Others |
Supply & Pricing Matrix
The Port of Long Beach freight corridor cost dynamics compress margin structures for North American assemblers drawing from concentrated Asian textile feedstock sources, while California Title 24 compliance mandates create price stratification between washable canvas and disposable film alternatives.
Pricing Analysis
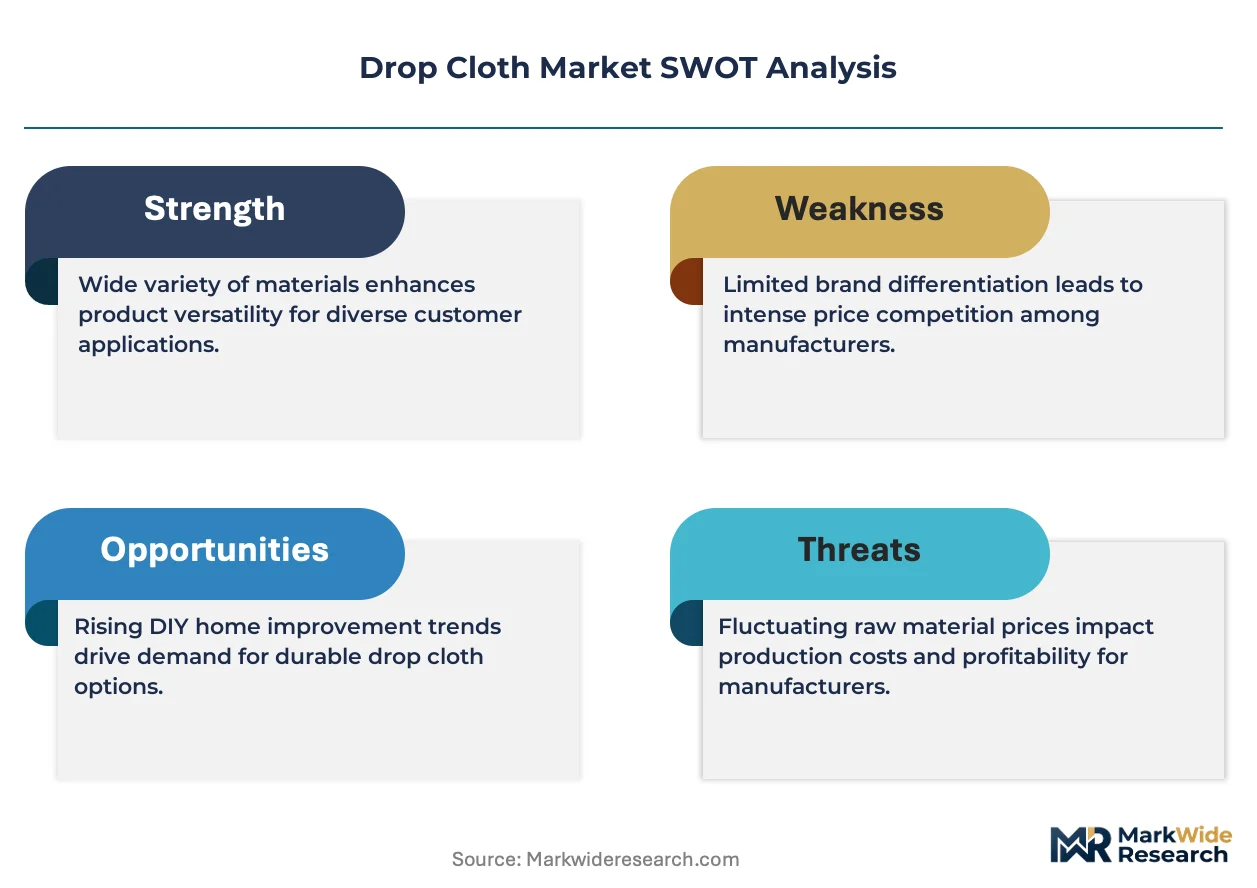
Volume-discount tiering separates contractor-grade procurement from retail channels. Three-tier pricing structure across premium canvas, standard polypropylene, and economy polyethylene levels reflects certification grade and wash-cycle documentation requirements. Cost compression in lightweight film tiers is intensifying because Chinese capacity expansion floods DIY segments. Home improvement retailers exhibit highest price sensitivity, while hospital and cleanroom contractors absorb premium positioning for SMS composite specifications.
Supply Chain Analysis
Export-control regimes on advanced nonwoven manufacturing equipment constrain European and North American producers seeking to replicate Chinese spunbond capacity. Raw material flows concentrate in China, India, and the United States for cotton, polypropylene resin, and polyethylene film respectively. Downstream assembly draws from Zhejiang province woven textile mills, Texas cotton gins, and Louisiana petrochemical corridors. Single-source vulnerability runs through Yangtze River Delta spunbond concentration. Distribution runs through industrial supply platforms disintermediating traditional distributor relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against ultra-thin polyethylene film commoditization threatening canvas and synthetic premium tiers.
For Market Incumbents: Pre-empt lightweight film encroachment by accelerating industrial laundering partnership networks that document wash-count durability for California EPA compliance. Anchor backward integration into Texas cotton processing to buffer harvest volatility. Capture channel control through subscription replenishment models that bundle containment textiles with coatings and masking materials. For New Entrants and Emerging Players: Establish a beachhead in UV-stabilized outdoor specifications for Australian and southern United States infrastructure maintenance. Target event planner segments with rapid-deployment branded synthetics as experiential marketing budgets recover. Pursue direct contractor e-procurement partnerships that bypass established distributor relationships. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors SMS composite nonwoven specialists bridging canvas breathability and plastic impermeability. Long-term viability hinges on regulatory tailwinds from extended producer responsibility frameworks reclassifying single-use textiles as regulated waste. Watch for inflection signals in industrial laundering infrastructure investment rates across California and New York metropolitan contractor markets.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cotton Processing | Texas gins and Indian ring-spinning operations buffer harvest volatility for canvas fabricators. |
| SMS Composite Capacity Expansion | Hospital and cleanroom specifications command 3-4x unit pricing over residential alternatives. |
| Industrial Laundering Partnership Networks | California EPA containment protocols require documented wash-cycle verification from contractors. |
| Direct Contractor E-Procurement Platform | Subscription replenishment models disintermediate traditional distributor margin capture. |
| UV-Stabilized Outdoor Specification Development | Australian bridge maintenance programs formalize waterproof containment textile standards. |
Research Methodology
Cross-validation between primary fieldwork with painting contractors and secondary customs trade data anchors the qualitative findings. Stakeholder interviews encompassed professional painting crew supervisors, industrial supply procurement officers, textile finishing plant managers, and hospital facilities compliance directors. Secondary sources included EPA architectural coatings enforcement records, ECHA REACH restriction updates, California Title 24 compliance documentation, and spunbond nonwoven capacity disclosures. Bottom-up contractor consumption estimates were triangulated against top-down resin flow analysis from Port of Long Beach import records.
Calibration against historical canvas and synthetic pricing volatility informed the projection framework. Segmentation dimensions encompassed material type, usage environment, thickness specification, and end-user procurement channel across the analysis window. CAGRs were derived from regression analysis of renovation activity indices, regulatory adoption curves, and substitution elasticity parameters. Industry-specific inputs included cotton harvest variance models and Chinese polypropylene capacity utilization rates.
Stress conditions across Texas-India cotton price spreads, Yangtze River Delta logistics disruptions, and EPA enforcement intensity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts assume sustained Title 24 compliance mandates and REACH phthalate restriction trajectories. Material shifts in extended producer responsibility reclassification timelines or spunbond equipment export licensing would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Textile Machinery and Equipment
Plasma Surface Treatment Machine for Leather Market
Textile Machinery and Equipment
Tarpaulin Sheets Market
Textile Machinery and Equipment
Mesh Tarpaulin Sheets Market
Textile Machinery and Equipment
Textile Mill Electric Drives Market
Textile Machinery and Equipment
Global Rotary Clothes Dryer Market
Textile Machinery and Equipment
Fabric Cutting Machines Market
Textile Machinery and Equipment
Hoarding Tarpaulin Market
Textile Machinery and Equipment
Global Digital Textile Printing Machine Market
Textile Machinery and Equipment
Global Custom T-Shirt Printing Market
Textile Machinery and Equipment
Global Circular Knitting Machine Market
Textile Machinery and Equipment
Global Digital Printing and Dyeing Machine Market
Textile Machinery and Equipment
Compact Spinning Machine Market
Textile Machinery and Equipment
Spools Market
Textile Machinery and Equipment
Saddle Stitching Machine Market
Textile Machinery and Equipment
Cloth Measuring Machine Market
Textile Machinery and Equipment
Netted Fabrics Market