
 Technical Textile Production Equipment Market | 2026-2036
Technical Textile Production Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Technical Textile Production Equipment Market Insights
Aftermarket service revenue is fragmenting across the technical textile production equipment landscape as original manufacturers and third-party service networks compete for maintenance contracts and spare parts fulfillment. Andritz leverages its broad process technology portfolio to capture recurring service streams across multiple textile platforms. BRÜCKNER anchors its position through deep specialization in finishing and coating equipment lines. KARL MAYER dominates warp knitting machine supply with extensive field engineering networks that sustain long-dated customer relationships.
Technical textile production equipment encompasses specialized machinery engineered to process high-performance fibers—aramid, carbon, glass, and ultra-high molecular weight polyethylene—into fabrics with defined tensile strength, thermal resistance, or chemical barrier properties exceeding conventional textiles, serving industries where material failure carries safety or regulatory consequences. Nonwoven machines utilizing spunbond and meltblown technologies lead capital deployment as filtration and medical applications expand capacity requirements. Weaving looms incorporating air-jet and water-jet systems represent mature, high-throughput segments where margin pools concentrate in aftermarket consumables and precision component replacement rather than new unit sales.
EU REACH and CE marking frameworks govern chemical handling and machinery safety certification for equipment deployed across European textile manufacturing zones, while China's GB standards and MIIT directives shape product specifications for machinery imported or locally assembled in Asian production hubs. FDA regulations in the United States impose stringent validation protocols on equipment producing medical textiles, creating compliance barriers that favor established suppliers with documented quality systems. Stakeholders must monitor evolving extended producer responsibility frameworks in the European Union and corresponding state-level mandates in California and New York that will redefine equipment design requirements for recyclable textile output.
Market Dynamics
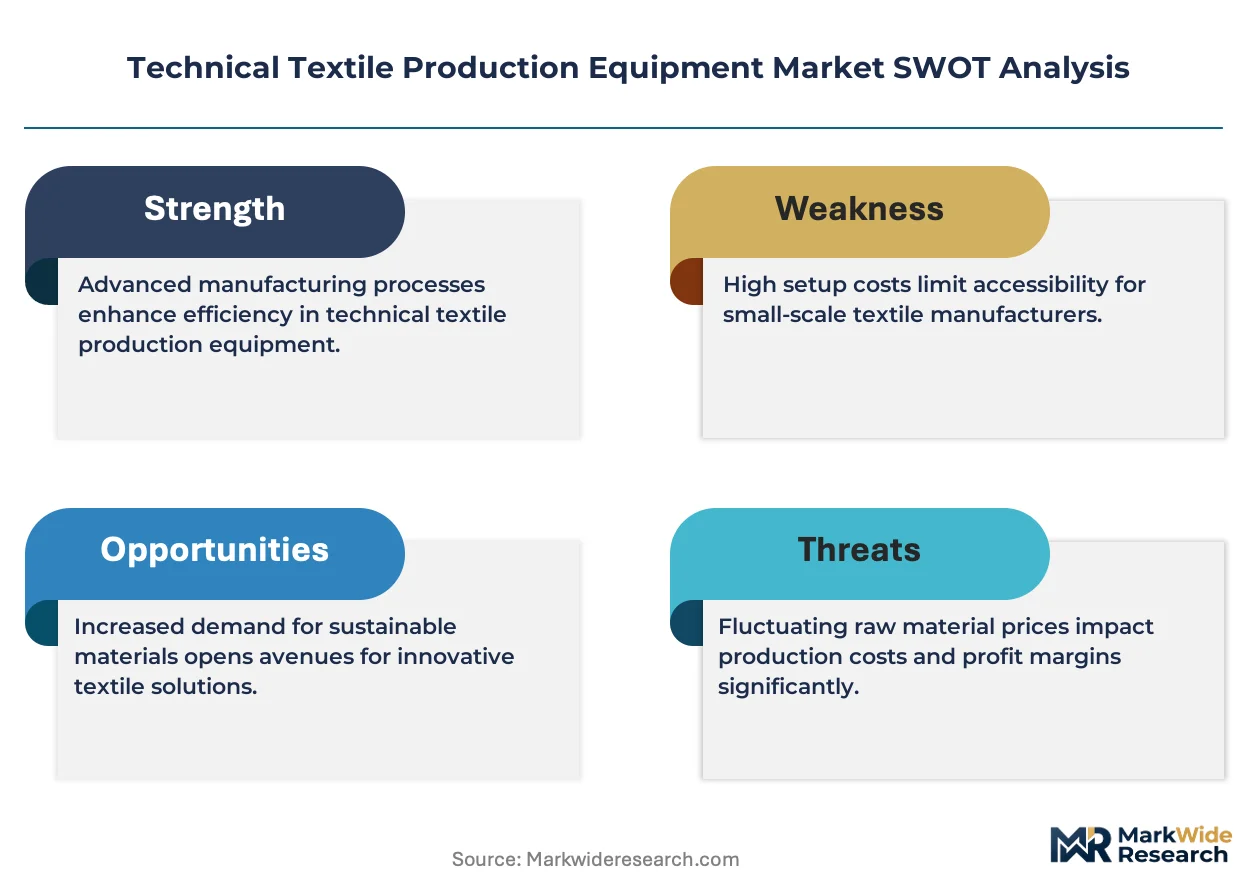
EU Green Deal textile sustainability mandates are compressing capital replacement cycles across European manufacturing bases, forcing equipment buyers to prioritize energy-efficient machinery and recyclable output compatibility over incremental upgrades.
Growth Catalysts
- Medical textile demand:Filtration and barrier fabric requirements in healthcare settings are expanding nonwoven machine procurement across developed manufacturing corridors.
- REACH chemical compliance:Stricter substance restrictions under EU REACH are accelerating replacement of legacy coating and finishing lines that cannot meet reduced emission thresholds.
- Carbon fiber processing:Aerospace and automotive lightweighting programs are driving warp knitting and weaving equipment orders for composite preform production.
Market Restraints
- High-performance fiber cost volatility:Aramid and ultra-high molecular weight polyethylene price swings compress margins for equipment buyers locked into long production contracts.
- Core component supply concentration:Precision servo drives and advanced control systems for multi-axial looms concentrate among German and Japanese suppliers, creating single-source vulnerabilities.
- Technical limitation in hybrid processing:Equipment capable of simultaneously handling thermoplastic and thermoset fiber matrices remains commercially immature, constraining multi-material output flexibility.
Strategic Opportunities
- India technical textile corridor:PLI scheme incentives for man-made fiber and technical textile production are opening greenfield equipment deployment opportunities in Surat and Tiruppur.
- Digital twin integration:Convergence of IoT sensors and predictive maintenance software is virtualizing equipment performance optimization before physical commissioning.
- Extended producer responsibility frameworks:EU mandates for textile recyclability are creating retrofit demand for separation-compatible finishing equipment and closed-loop processing modules.
Industry Challenges
- Multi-physics simulation expertise:Equipment design for high-speed carbon fiber handling requires rare combined knowledge of textile mechanics, thermal modeling, and control engineering that outpaces workforce development.
- FDA validation timelines:Medical textile equipment qualification protocols in the United States extend commercialization cycles by 18-24 months, straining R&D amortization schedules.
- Legacy system integration:Brownfield facilities in Germany's Chemnitz corridor face costly downtime when connecting modern air-jet looms to existing MES and quality tracking infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Technical Textile Production Equipment Market |
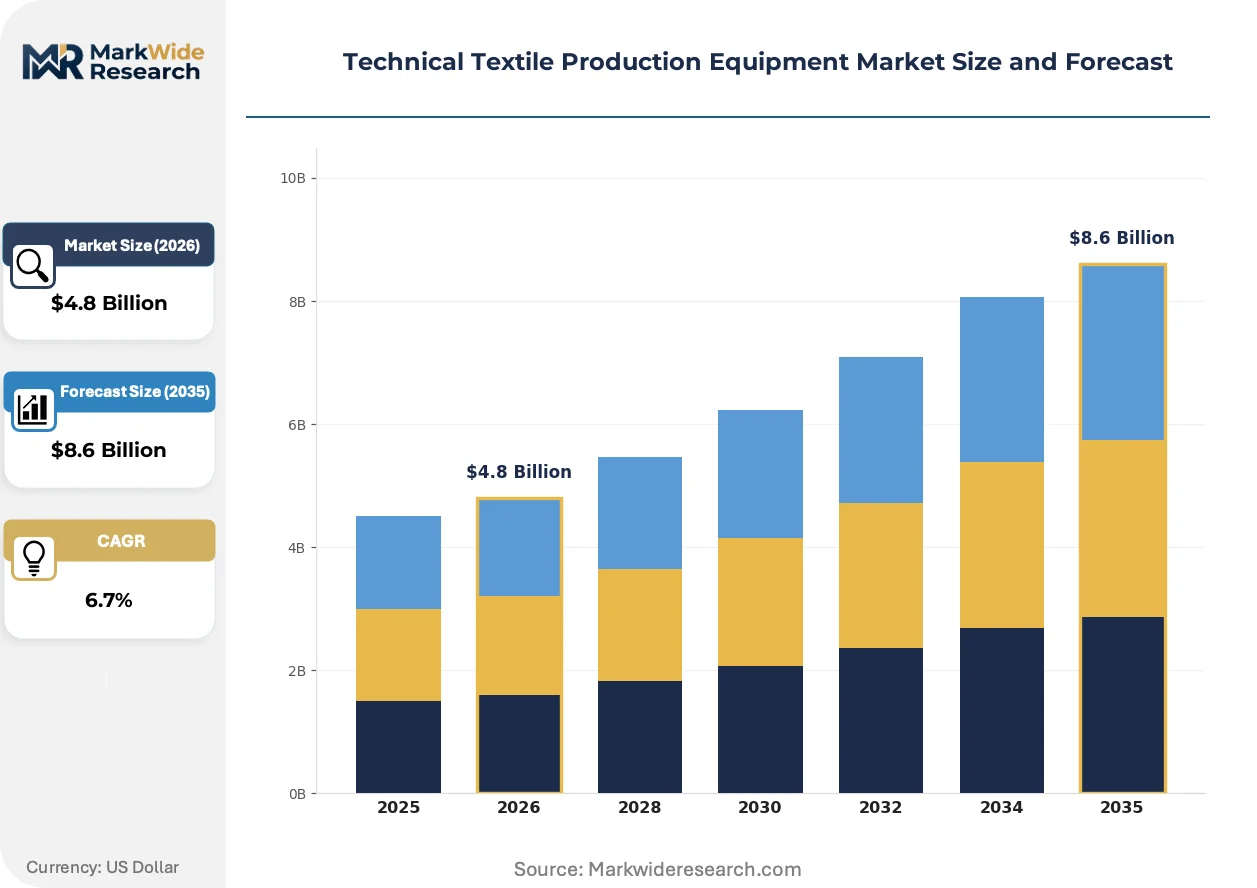
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Warp Knitting Machines, Circular Knitting Machines, Weaving Looms, Nonwoven Machines, Tufting Machines Technology: Air-Jet, Water-Jet, Needle Punching, Spunbond, Meltblown Application: Protective Apparel, Automotive Components, Industrial Filters, Geotextiles, Medical Textiles, Sports Gear End User Industry: Construction, Transportation Equipment, Personal Protective Equipment, Environmental Engineering |
| Companies Covered | Andritz, BRÜCKNER, Dilo Group, Itema, KARL MAYER, Kawanoe Zoki, Kusters Calico, Reifenhäuser Reicofil, Stäubli International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Technical Textile Production Equipment Market Trends and Innovations
Digital thread technologies are collapsing design-to-production lead times while regulatory pressure on embodied carbon redefines equipment specification priorities across buyer segments.
Artificial intelligence-driven process control is virtualizing quality assurance functions that previously required manual inspection stations and offline testing protocols. Automotive airbag and seatbelt manufacturers in Stuttgart's engineered textiles cluster are adopting these systems fastest, compressing defect detection response times from hours to milliseconds. The technology is virtualizing traditional finishing line configurations by enabling real-time tension and temperature adjustments without mechanical reconfiguration.
EU F-Gas Regulation phase-down schedules are forcing refrigerant-dependent thermal bonding equipment toward alternative heating technologies. Manufacturers serving European medical nonwoven markets must redesign drying and calendaring modules to eliminate hydrofluorocarbon reliance while maintaining throughput specifications. German equipment suppliers are responding with infrared and induction heating retrofits that align with CE marking requirements for reduced climate impact.
Equipment-as-a-service contracting is displacing outright purchase models among mid-cap technical textile producers seeking to preserve balance sheet flexibility. Tier-one automotive suppliers in the United States are driving this shift, preferring performance-guaranteed uptime arrangements over capital ownership of coating and laminating lines. This pattern concentrates most visibly in Michigan and South Carolina manufacturing zones where supplier qualification requirements favor vendors with embedded service networks.
Technical Textile Production Equipment Market Segmentation
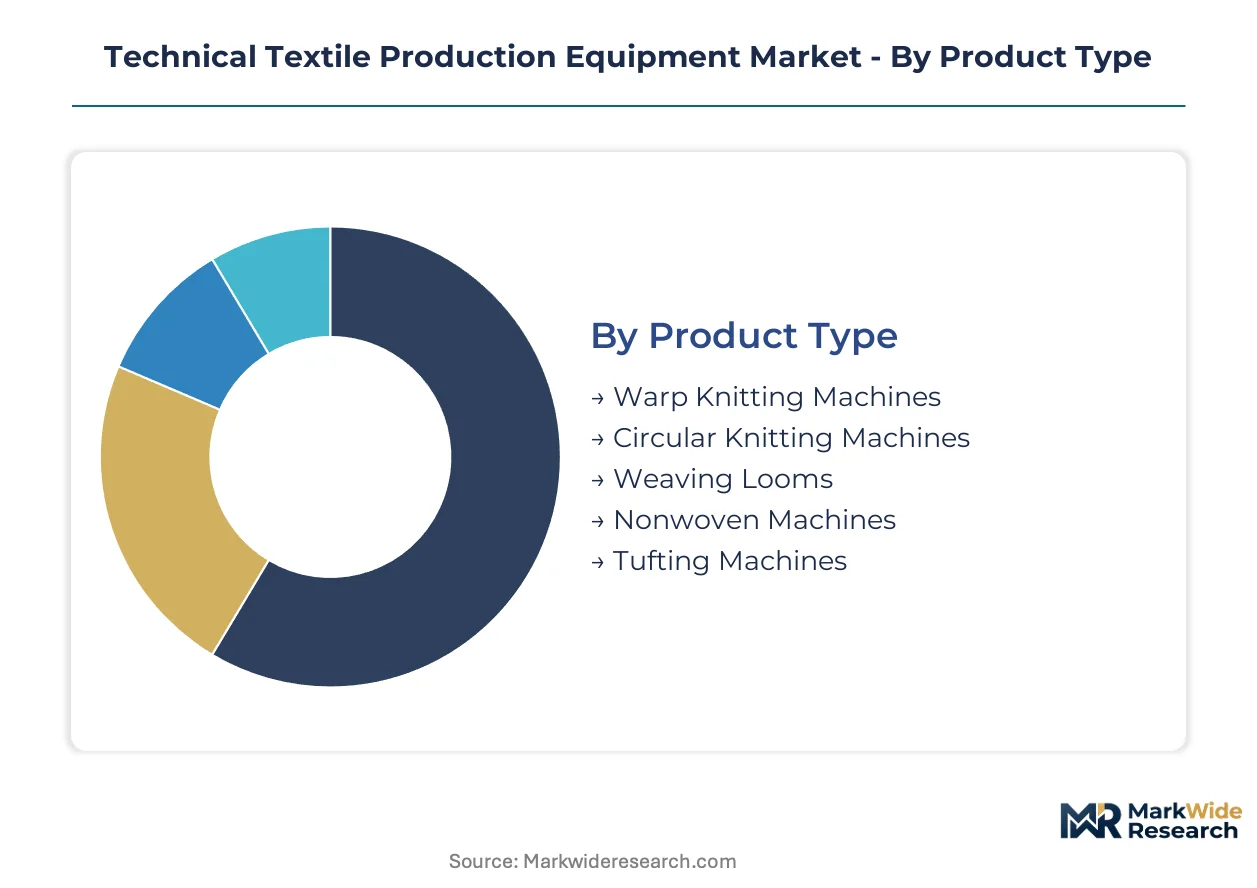
Equipment segmentation in technical textiles reveals how fiber processing requirements diverge across end-use performance thresholds. Buyers configure machinery portfolios around thermal resistance, tensile strength, and chemical barrier specifications that vary dramatically by application.
Product Type:
Equipment selection tracks the structural complexity of fabric architectures demanded by safety-critical applications.
- Nonwoven Machines:Spunbond and meltblown configurations process polypropylene and polyester into filtration media and medical barriers without yarn interlacing. Demand concentrates in Germany's medical textile corridor around Chemnitz, where EU Green Deal sustainability mandates accelerate replacement of solvent-dependent bonding equipment.
- Weaving Looms:Air-jet and water-jet systems interlace high-performance yarns into dimensionally stable fabrics for composite preforms and industrial belting. Stuttgart's automotive airbag suppliers drive procurement of multi-axial rapier looms capable of handling aramid and carbon fiber at high insertion rates.
- Warp Knitting Machines:Karl Mayer tricot and raschel configurations produce mesh and net structures for geotextile stabilization and athletic footwear uppers.
- Circular Knitting Machines:Double-needlebed systems create seamless tubular structures for compression garments and protective sleeve applications.
- Tufting Machines:Multi-needle gauge configurations anchor pile yarns into primary backings for artificial turf and automotive carpet systems.
The dominant share belongs to Nonwoven Machines, while Weaving Looms is closing the gap fastest on carbon fiber composite demand.
Technology:
Process selection determines energy intensity, fiber damage rates, and output surface characteristics for downstream bonding or coating operations.
- Spunbond:Continuous filament extrusion and attenuation through heated air streams produces uniform web structures for hygiene and filtration applications. German manufacturers in Saxony deploy these systems most intensively for EU medical nonwoven certification.
- Meltblown:High-velocity hot air attenuates molten polymer into microfiber webs with sub-micron filtration efficiency. FDA validation requirements for surgical mask media extend equipment qualification timelines in United States manufacturing zones.
- Air-Jet:Compressed air propels weft yarns across shed openings at speeds exceeding 2,000 meters per minute for high-volume technical fabric production.
- Water-Jet:High-pressure water streams insert weft without mechanical stress, preserving strength in glass and carbon fiber processing.
- Needle Punching:Barbed needles mechanically entangle fiber webs into felts for geotextile drainage and insulation applications.
Spunbond holds the installed base lead, though Meltblown is gaining share fastest on healthcare filtration requirements.
Application:
Performance specifications cascade from regulatory exposure—medical device standards, automotive crash testing, environmental containment protocols—into equipment capability requirements.
- Medical Textiles:Barrier fabrics, implantable meshes, and wound dressings demand biocompatible processing environments with validated sterilization compatibility. FDA 21 CFR Part 820 quality system requirements govern equipment qualification protocols in United States production facilities.
- Automotive Components:Airbag fabrics, seatbelt webbing, and tire cord require controlled tension processing to meet NHTSA crash performance standards. Stuttgart's engineered textiles cluster sources specialized warp knitting and weaving equipment with integrated quality tracking.
- Protective Apparel:Heat-resistant and chemical barrier garments utilize aramid and meta-aramid processing on modified spinning and weaving lines.
- Industrial Filters:Liquid and gas separation media employ precision needle punching and thermal bonding for defined pore size distribution.
- Geotextiles:Soil stabilization and drainage fabrics utilize high-tenacity polypropylene processing on wide-width looms and nonwoven lines.
- Sports Gear:Lightweight composite preforms and impact-absorbing pads integrate carbon fiber and UHMWPE on specialized knitting and braiding equipment.
Medical Textiles commands the premium equipment spend, while Automotive Components is expanding most quickly on electric vehicle lightweighting programs.
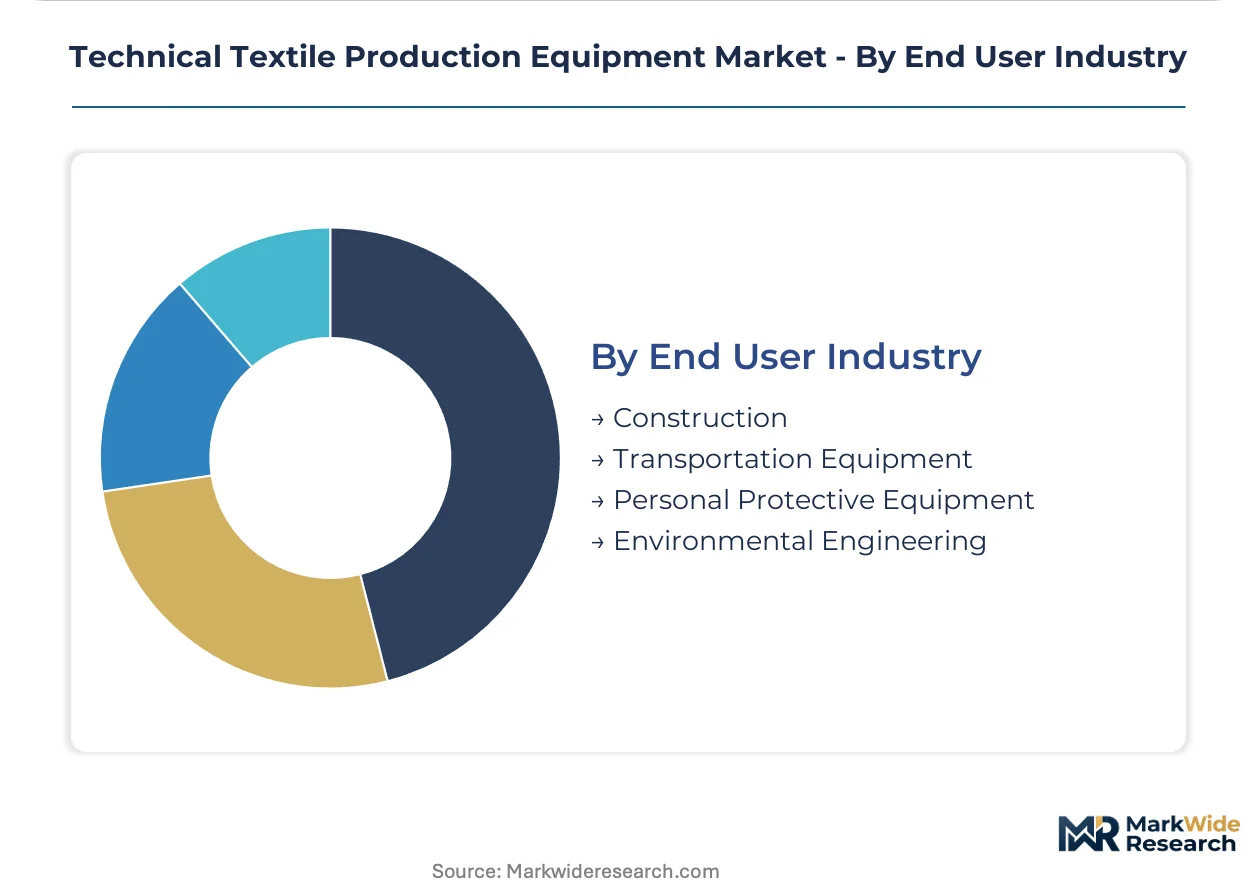
End User Industry:
Capital deployment patterns reflect infrastructure investment cycles and regulatory enforcement intensity across downstream sectors.
- Transportation Equipment:Aerospace and automotive manufacturers specify composite preform machinery for structural weight reduction. EU REACH substance restrictions on hexavalent chromium accelerate replacement of legacy coating lines in German supplier parks.
- Personal Protective Equipment:Industrial safety mandates drive procurement of cut-resistant and flame-retardant fabric processing equipment. OSHA enforcement priorities in United States manufacturing zones sustain demand for high-visibility and arc-flash protective textile machinery.
- Construction:Geotextile and geomembrane production scales with infrastructure stimulus allocation and environmental remediation project pipelines.
- Environmental Engineering:Filtration and containment applications for water treatment and pollution control deploy specialized nonwoven and membrane processing systems.
Transportation Equipment leads capital absorption, though Personal Protective Equipment is climbing fastest on regulatory mandate expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment procurement patterns diverge sharply across manufacturing corridors. German buyers prioritize REACH-compliant coating line replacements, while Indian producers respond to PLI scheme incentives with greenfield nonwoven investments. Chinese manufacturers emphasize GB standard alignment for domestic medical textile certification.
Germany
Medical nonwoven demand and automotive airbag fabric requirements dominate equipment orders. EU F-Gas Regulation phase-down schedules force thermal bonding equipment redesigns toward infrared heating alternatives. The Chemnitz-Stuttgart corridor concentrates warp knitting and weaving machine procurement for composite preform production.
United States
FDA validation protocols for medical textile equipment extend commercialization timelines for domestic and imported machinery. OSHA enforcement on personal protective equipment sustains demand for cut-resistant fabric processing lines. Michigan and South Carolina manufacturing zones favor equipment-as-a-service contracting over capital purchases.
China
MIIT directives on man-made fiber quality standards shape specifications for locally assembled and imported machinery. Domestic medical textile certification under GB standards drives meltblown and spunbond capacity expansion. Yangtze River Delta manufacturers concentrate filtration media equipment deployment.
India
PLI scheme incentives for technical textile production open greenfield equipment opportunities in Surat and Tiruppur. BIS certification requirements for medical nonwovens influence imported machinery specifications. Western and Southern states concentrate needle punching and thermal bonding line investments for geotextile applications.
Japan
PMDA quality system requirements for medical device textiles govern equipment qualification protocols. METI carbon neutrality roadmaps accelerate energy-efficient machinery replacement in Osaka-Nagoya manufacturing belts. Precision servo drive supply relationships with German and Japanese component makers create procurement dependencies.
Technical Textile Production Equipment Market Competitive Landscape
Capability concentration sits with specialized finishing and knitting equipment fabricators; scale advantage sits with diversified process technology conglomerates. The vendor structure organizes around three archetypes: broad-portfolio industrial groups capturing aftermarket service streams, deep-specialization equipment houses dominating single technology categories, and regional fabricators serving price-sensitive emerging markets. Competitive moves center on digital twin integration partnerships and extended producer responsibility retrofit service bundling.
Among European-based specialists, BRÜCKNER and KARL MAYER occupy positions exemplifying the deep-specialization archetype, while Andritz represents the diversified industrial group model with cross-platform service network leverage. These three entities anchor the competitive structure through distinct capability positioning rather than overlapping segment contestation.
| Leading Market Players |
|---|
| Andritz |
| BRÜCKNER |
| Dilo Group |
| Itema |
| KARL MAYER |
| Kawanoe Zoki |
| Kusters Calico |
| Reifenhäuser Reicofil |
| Stäubli International |
| Others |
Pricing and Supply Chain Analysis
Chemnitz-Stuttgart equipment corridors anchor European pricing power through concentrated finishing and knitting machine capacity, with OEMs commanding premium positioning on REACH-compliant configurations and extended producer responsibility retrofit bundling.
Pricing Analysis
Long-term offtake contracts dominate high-volume automotive and medical textile equipment procurement, insulating German suppliers from spot volatility while compressing margins on standardized nonwoven lines. Price differentiation hinges on FDA validation tier and CE marking complexity, with FDA-qualified machinery commanding substantial premiums over standard configurations. Cost compression in mid-tier spunbond equipment is intensifying as Chinese assemblers penetrate Southeast Asian markets. Tier-one automotive buyers in Stuttgart exhibit lowest price sensitivity due to supplier qualification lock-in, whereas Indian greenfield entrants in Surat prioritize capital efficiency above performance guarantees.
Supply Chain Analysis
High-performance fiber feedstock draws from German and Japanese precision servo drive suppliers, creating concentrated dependencies for multi-axial loom control systems. Aramid and carbon fiber raw material sourcing rests on Belgian and American chemical conglomerates, with ultra-high molecular weight polyethylene supply anchored in Dutch and Japanese polymer operations. Single-source vulnerability in advanced control electronics generates exposure to semiconductor allocation disruptions. Distribution runs through OEM-direct channels for large installations and specialized distributor networks for aftermarket components.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical textile production equipment sits in early-cycle expansion as EU Green Deal mandates force capital replacement waves across European installed bases, with medical textile certification requirements extending equipment commercialization timelines.
For Market Incumbents: Harden aftermarket service moats by embedding predictive maintenance software and capturing extended producer responsibility retrofit contracts before third-party networks consolidate. Deepen vertical integration into precision servo drive supply relationships to mitigate single-source vulnerability from Japanese component suppliers. Prioritize FDA validation documentation investments to extend qualification barriers against emerging competitors. For New Entrants and Emerging Players: Build out digital twin integration capabilities as a wedge into mid-cap technical textile producers seeking equipment-as-a-service alternatives to capital ownership. Target India's PLI scheme corridors in Surat and Tiruppur for greenfield nonwoven machine deployment where established European OEMs lack localized service density. Lead with performance-guaranteed uptime contracting to bypass upfront capital barriers. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because equipment qualification protocols under FDA and EU MDR create durable competitive moats that compound over extended replacement cycles. Acquisition candidates cluster around specialized finishing equipment houses with documented quality systems and embedded field engineering networks. Monitor FDA 510(k) submission volumes for medical textile machinery as an inflection indicator for capacity expansion timing.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Twin Integration Partnership | Virtual commissioning reduces physical prototyping costs for carbon fiber handling equipment. |
| Extended Producer Responsibility Retrofit Service | EU textile recyclability mandates create recurring revenue streams from separation-compatible module upgrades. |
| Backward Integration into Precision Servo Drives | In-house control system production mitigates German-Japanese supplier concentration risk. |
| Equipment-as-a-Service Platform Launch | Performance-guaranteed contracting captures mid-cap buyers seeking balance sheet flexibility. |
| FDA Validation Fast-Track Investment | Expedited 21 CFR Part 820 qualification protocols accelerate medical textile equipment commercialization. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs trade data, SEC machinery manufacturer filings, and EU ECHA substance restriction databases. Primary interviews engaged plant engineers at German automotive airbag suppliers, aftermarket service heads at warp knitting operations, and procurement leads at Indian technical textile greenfield projects. Secondary validation drew from MIIT equipment quality directives, FDA 510(k) device listings, and BIS certification records. Bottom-up equipment shipment tracking triangulates against top-down capital expenditure surveys across the analysis window.
Forecast inputs incorporate equipment type segmentation, technology generation cycles, and regional regulatory enforcement intensity across the projection horizon. Modeled dimensions span machine configuration, end-use application performance tier, and geographic certification cluster. CAGRs derive from installed base replacement velocity and greenfield capacity absorption rates. Carbon fiber composite demand curves and REACH substance restriction phase-in schedules inform trajectory assumptions.
Sensitivities concentrate around FDA validation timeline extensions, EU F-Gas Regulation enforcement acceleration, and high-performance fiber price volatility. Forecasts reflect documented assumptions on regulatory adherence and technology adoption curves. Cross-checking against MIIT domestic equipment production statistics and German mechanical engineering association order intake data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Textile Machinery and Equipment
T-Shirt Printing Machine Market
Textile Machinery and Equipment
Global Weaving Machinery Market
Textile Machinery and Equipment
Tarpaulin Sheets Market
Textile Machinery and Equipment
US Textile Processing Machinery Market
Textile Machinery and Equipment
Middle East and Africa Textile Films Market
Textile Machinery and Equipment
Embroidery Equipment Market
Textile Machinery and Equipment
Global Textile Machinery Market
Textile Machinery and Equipment
Sewing Machine Market
Textile Machinery and Equipment
Sewing Machine Component Market
Textile Machinery and Equipment
Industrial Sewing Machines Market
Textile Machinery and Equipment
Drop Cloth Market
Textile Machinery and Equipment
Global Knitting Machinery Market
Textile Machinery and Equipment
Global Rotary Clothes Dryer Market
Textile Machinery and Equipment
Global Digital Textile Printing Machine Market
Textile Machinery and Equipment
Cloth Cutting Machines Market
Textile Machinery and Equipment
Disposable Garment Bags Market