
 Middle East and Africa Stand-Up Paddleboard Market | 2026-2036
Middle East and Africa Stand-Up Paddleboard Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Stand-Up Paddleboard Market Foresight
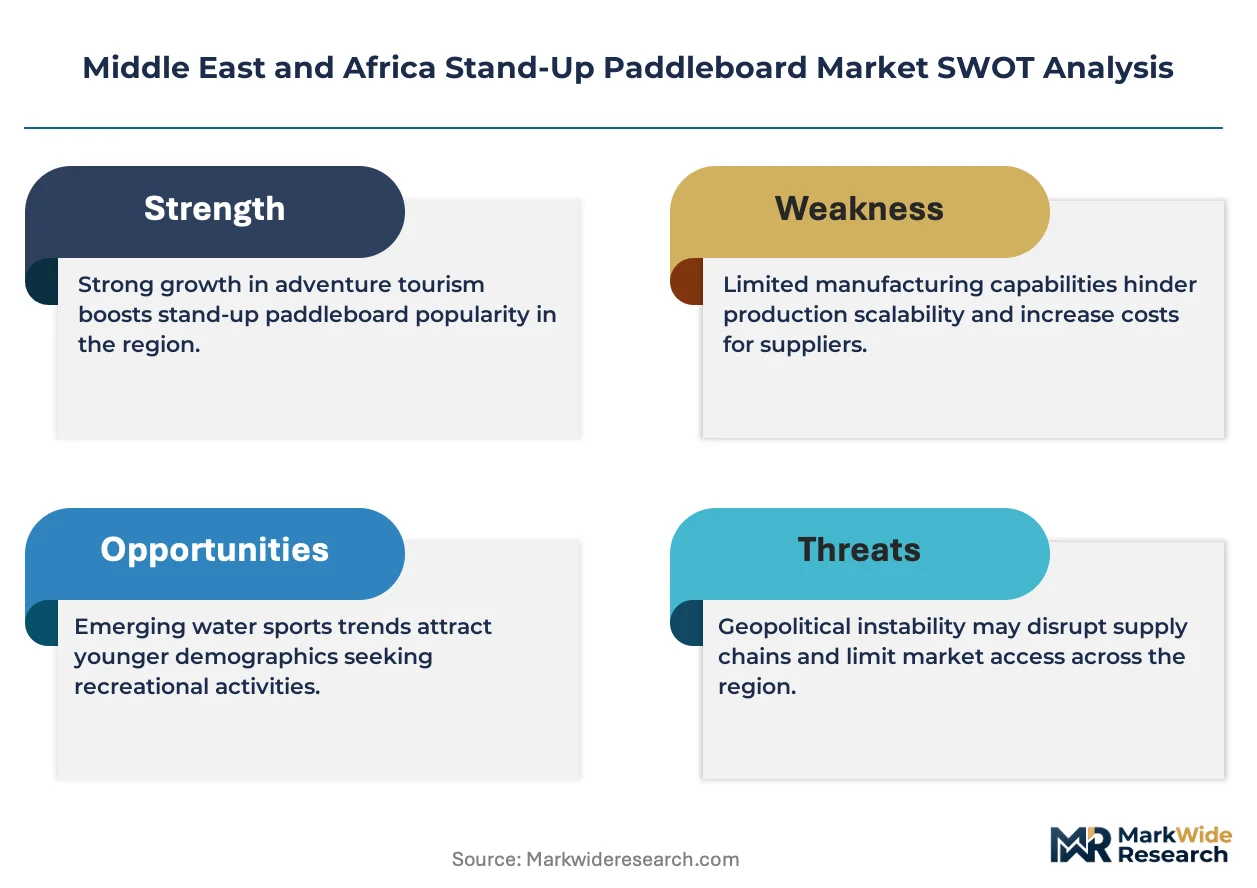
The capital-intensity divergence between epoxy-infused rigid board manufacturers and PVC inflatable assemblers is unwinding as automated drop-stitch machinery lowers entry barriers. Red Paddle Co leverages proprietary MSL fusion construction to sustain premium positioning across Middle Eastern resort channels. Starboard International anchors its regional presence through coastal distributor partnerships in Morocco and Kenya. Hobie Cat differentiates via fishing-specialized hull designs that occupy the angling niche in South African recreational harbors.
A stand-up paddleboard is a buoyant watercraft propelled by a standing rider using a single-bladed paddle, typically measuring 2.7 to 3.8 meters in length with a planing hull displacement between 150 and 300 liters. Fiberglass and carbon fiber composites dominate rigid board construction for performance applications, while PVC drop-stitch inflatable variants achieve 15-25 PSI internal pressure for rigidity comparable to hard boards at reduced transport weight. Inflatable boards lead volume through rental service procurement across Red Sea and Indian Ocean coastal operations. Recreational users represent the fastest-growing end-user category as fitness-oriented consumers in Gulf Cooperation Council states adopt paddleboarding for low-impact cardiovascular training. Carbon fiber segments command the strongest margin pools due to limited regional supply of aerospace-grade pre-preg material and specialized lamination labor.
South Africa's National Regulator for Compulsory Specifications mandates buoyancy and labeling standards for marine leisure craft, while the UAE's Emirates Authority for Standardization and Metrology enforces product conformity assessments for imported sporting equipment. The EU F-Gas Regulation indirectly shapes regional supply chains by restricting hydrofluorocarbon blowing agents used in PVC core production, compelling Middle Eastern distributors to source boards from compliant European manufacturers. Stakeholders must monitor evolving coastal access permits and marine protected area designations that could restrict launch points across East African and Arabian Peninsula shorelines.
Market Dynamics
Automated drop-stitch machinery is collapsing the capital barrier between rigid epoxy board manufacturing and PVC inflatable assembly, eroding the traditional margin premium held by composite specialists and redistributing competitive advantage toward scale-efficient assemblers.
Growth Catalysts
- Emirates Authority for Standardization and Metrology conformity assessments:Mandatory product certification for imported sporting equipment creates a quality floor that professionalizes distribution channels and accelerates replacement cycles among rental fleet operators.
- Fishing-specialized hull designs:Angling applications in South African recreational harbors expand addressable demand beyond core watersport enthusiasts into adjacent leisure verticals with higher equipment spend tolerance.
- Red Sea coastal tourism infrastructure:Waterfront development across Egyptian and Saudi Arabian resort corridors generates procurement pull from hospitality operators seeking experiential amenity differentiation.
Market Restraints
- Aerospace-grade pre-preg carbon fiber supply:Limited regional availability of specialized lamination material and skilled labor constrains high-margin composite segment expansion.
- EU F-Gas Regulation hydrofluorocarbon restrictions:Blowing agent constraints on PVC core production force Middle Eastern distributors toward compliant European sourcing, elongating lead times.
- Rigid inflatable boat substitution:Multi-passenger leisure craft compete for rental fleet capital allocation in coastal tourism operations prioritizing passenger throughput over individual experience.
Strategic Opportunities
- Kenyan and Tanzanian marine protected area adjacencies:Underdeveloped coastal tourism infrastructure along East African shorelines offers first-mover positioning for inflatable fleet operators before regulatory access restrictions crystallize.
- Fitness-oriented cardiovascular training adoption:Low-impact exercise positioning among Gulf Cooperation Council urban consumers expands recreational end-user base beyond traditional watersport demographics.
- MSL fusion construction technology:Proprietary heat-welded seam methods eliminate glue degradation failure modes, enabling premium warranty terms that differentiate resort channel offerings.
Industry Challenges
- Marine equipment safety certification timelines:South Africa's National Regulator for Compulsory Specifications buoyancy testing protocols create inventory holding costs for importers awaiting clearance.
- Coastal access permit fragmentation:Evolving municipal launch point regulations across Arabian Peninsula municipalities force operators to maintain redundant logistics networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Stand-Up Paddleboard Market |
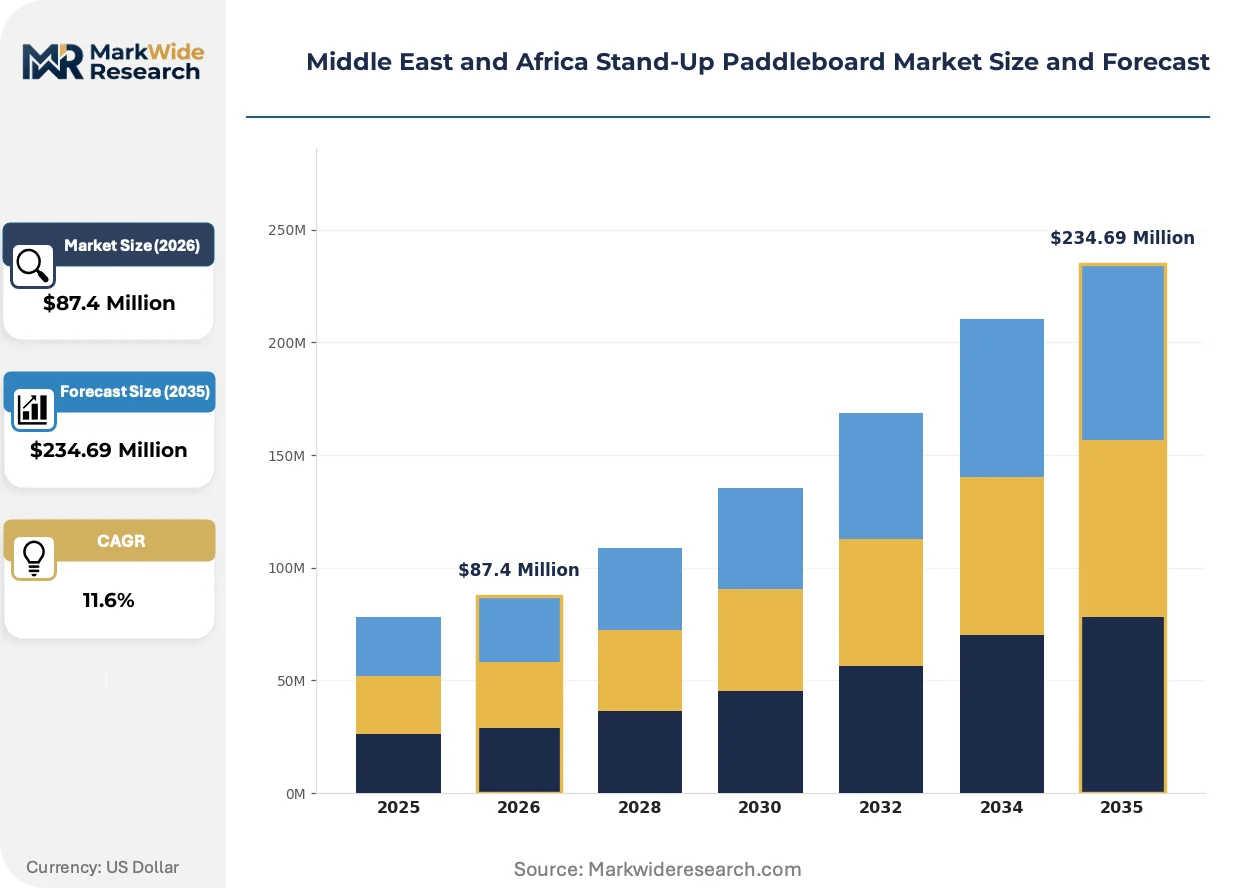
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $234.69 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inflatable, Rigid, Soft-Top, Fishing End User: Recreational Users, Fitness Enthusiasts, Rental Services, Professionals Material: Polyethylene, Fiberglass, PVC, Carbon Fiber Distribution Channel: Online Retail, Specialty Stores, Sports Outlets, Others |
| Companies Covered | Hobie Cat, Fanatic, Red Paddle Co, NSP Europe, JP Australia, Starboard International, Naish International, Tahe Outdoors, BOTE, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Stand-Up Paddleboard Market Shifts & Advancements
Material science advances and regulatory chemistry constraints are rewriting manufacturing economics while buyer behavior shifts toward experiential service models rather than equipment ownership.
Thermoplastic polyurethane rail reinforcements bonded to woven drop-stitch cores are bifurcating the inflatable segment into durability-tiered product lines. Red Sea resort operators now specify 15-25 PSI pressure-rated fleets for commercial use while recreational buyers accept lower-specification alternatives. This technical stratification is compressing mid-market positioning and forcing manufacturers to commit decisively to either commercial-grade or consumer-grade construction standards.
The EU F-Gas Regulation's hydrofluorocarbon blowing agent restrictions are reshaping regional supply chain geography. Middle Eastern distributors now face sourcing bifurcation between compliant European manufacturers and non-compliant Asian producers with divergent environmental credentials. Product categories serving institutional buyers with sustainability procurement mandates experience accelerated channel consolidation toward verified-compliant supply sources.
Fitness-oriented consumers in Gulf Cooperation Council states are displacing traditional ownership models with subscription-based rental access. Hotel and resort channels capture this behavioral pivot through integrated wellness programming that bundles paddleboard sessions with spa and dining packages. Dubai's waterfront hospitality cluster exhibits the most pronounced manifestation of this service-model transition, with equipment procurement increasingly centralized through hospitality group-level fleet contracts rather than individual property decisions.
Middle East and Africa Stand-Up Paddleboard Market Segmentation
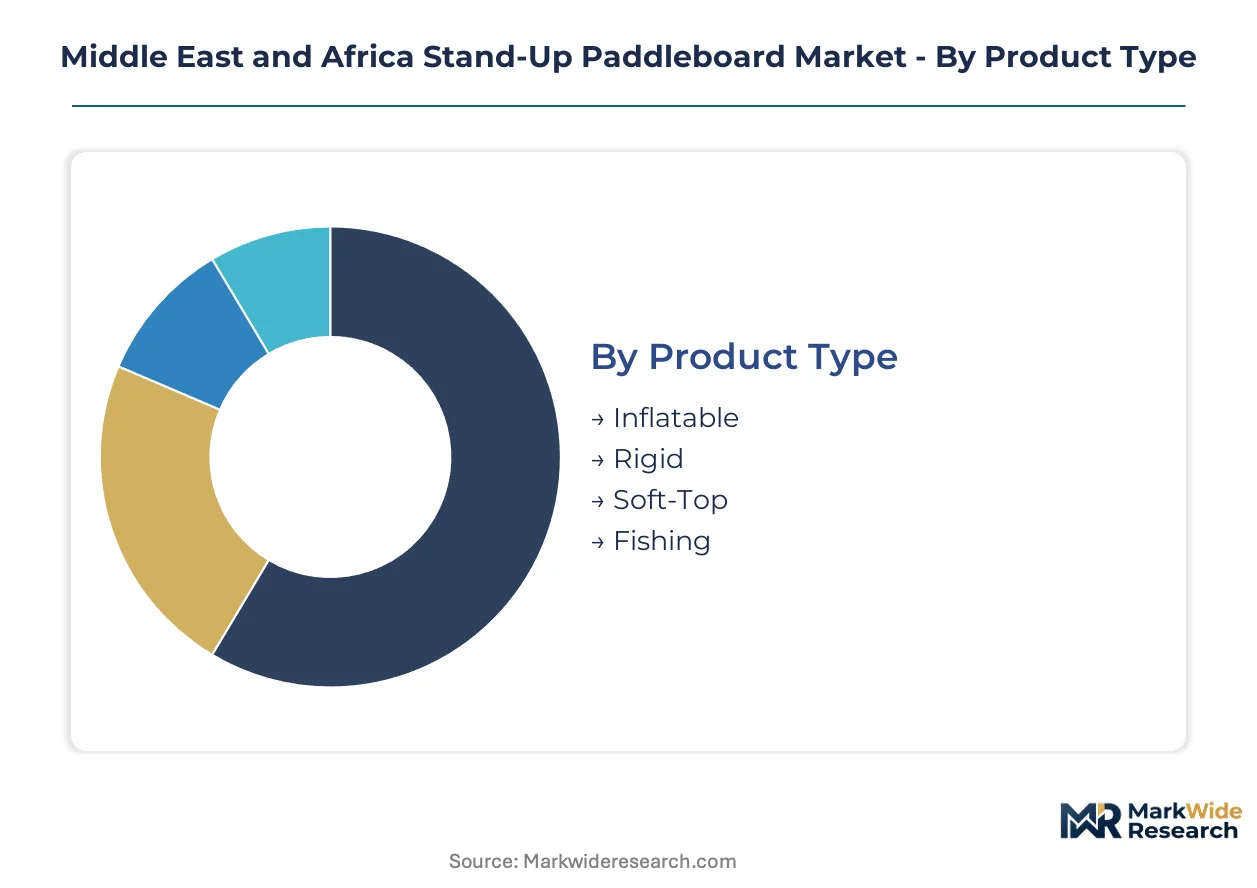
Product architecture and procurement patterns diverge sharply between resort fleet operators and individual buyers across Middle Eastern and African markets. Understanding where margin pools concentrate within each dimension enables targeted positioning against divergent certification requirements and durability specifications.
Product Type:
Margin pools concentrate in inflatable variants where automated drop-stitch machinery has collapsed capital barriers while preserving premium positioning through proprietary fusion construction.
- Inflatable:PVC drop-stitch cores achieve 15-25 PSI internal pressure for rigidity comparable to hard boards at reduced transport weight. Demand concentrates across Red Sea and Indian Ocean coastal rental operations where fleet portability and storage efficiency drive procurement decisions.
- Rigid:Epoxy-infused fiberglass and carbon fiber composites dominate performance applications requiring planing hull precision. Procurement concentrates in South African recreational harbors where fishing-specialized hull designs command equipment spend tolerance above standard recreational tiers.
- Soft-Top:Polyethylene foam-sandwich construction targets entry-level recreational users prioritizing impact durability over speed.
- Fishing:Angling-optimized hulls with rod holders and gear mounts occupy niche demand in South African and Namibian recreational harbors.
The dominant share belongs to Inflatable, while Fishing is closing the gap fastest through adjacent leisure vertical expansion.
End User:
Customer archetypes range from institutional fleet operators with centralized procurement authority to fragmented individual buyers with divergent price sensitivity and performance requirements.
- Recreational Users:Fitness-oriented consumers in Gulf Cooperation Council states adopt paddleboarding for low-impact cardiovascular training. Dubai's waterfront hospitality cluster exhibits pronounced service-model transition with subscription-based rental access displacing traditional ownership.
- Rental Services:Coastal tourism operators in Egyptian and Saudi Arabian resort corridors generate procurement pull through hospitality group-level fleet contracts rather than individual property decisions.
- Fitness Enthusiasts:Urban consumers seeking cross-training alternatives to gym-based exercise represent emerging demand concentrated in Abu Dhabi and Doha metropolitan zones.
- Professionals:Competitive athletes and instructors require carbon fiber performance boards with specialized lamination labor that constrains regional supply availability.
Rental Services command the dominant procurement volume, though Recreational Users are expanding most quickly through wellness programming integration.
Material:
Supply chain geography and regulatory chemistry constraints fragment sourcing strategies across durability tiers and certification requirements.
- Carbon Fiber:Aerospace-grade pre-preg material faces limited regional availability and specialized lamination labor constraints. Procurement concentrates among professional and high-performance recreational segments in South Africa where margin pools remain strongest despite supply bottlenecks.
- PVC:Drop-stitch inflatable construction dominates volume through rental fleet procurement. EU F-Gas Regulation hydrofluorocarbon blowing agent restrictions force Middle Eastern distributors toward compliant European sourcing with elongated lead times.
- Fiberglass:Epoxy-infused composite construction balances performance and cost for rigid board mid-market positioning.
- Polyethylene:Rotomolded soft-top construction serves entry-tier durability requirements with simplified manufacturing economics.
Carbon Fiber retains the strongest margin structure, while PVC is gaining share fastest through rental channel expansion.
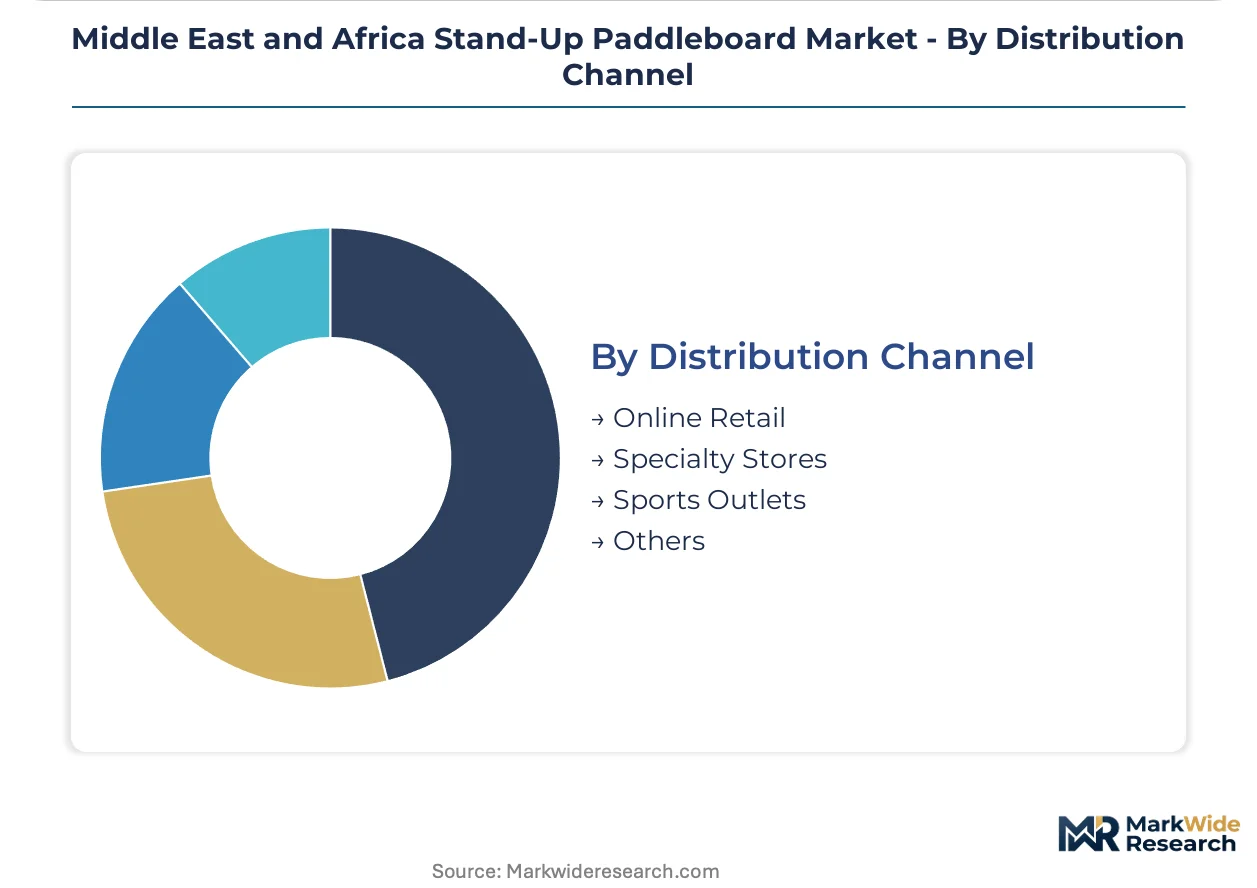
Distribution Channel:
Channel economics reflect divergent customer acquisition costs and post-sale service obligations across institutional and individual buyer segments.
- Specialty Stores:Watersport-focused retailers provide technical consultation and assembly services that support carbon fiber and high-performance rigid board sales. Concentration clusters in Cape Town and Durban where marine leisure culture sustains dedicated retail infrastructure.
- Online Retail:Direct-to-consumer platforms capture inflatable board demand from fitness-oriented buyers in Gulf Cooperation Council states. Emirates Authority for Standardization and Metrology conformity assessment requirements create quality floors that professionalize digital distribution channels.
- Sports Outlets:General sporting goods retailers serve recreational entry-tier demand with limited technical consultation.
- Others:Hospitality procurement desks and coastal tourism operators source through direct manufacturer relationships bypassing traditional retail markup.
Specialty Stores anchor premium positioning, while Online Retail is climbing the fastest through fitness demographic expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependency defines regional supply dynamics, with distributors sourcing inflatable boards from European and Asian manufacturers to serve coastal tourism clusters. Export activity remains minimal given limited domestic composite fabrication capacity.
United Arab Emirates
Dubai's waterfront hospitality sector drives fleet procurement through group-level centralized contracts. Emirates Authority for Standardization and Metrology enforces conformity assessments for imported sporting equipment. The Palm Jumeirah and Dubai Marina clusters anchor rental service density.
Saudi Arabia
Red Sea coastal tourism infrastructure generates procurement pull from resort developers seeking experiential differentiation. The Saudi Standards, Metrology and Quality Organization regulates product safety for marine leisure imports. NEOM and Amaala projects concentrate hospitality operator demand.
South Africa
Fishing-specialized hull designs expand addressable demand into angling verticals with elevated equipment tolerance. The National Regulator for Compulsory Specifications mandates buoyancy and labeling standards for marine leisure craft. Cape Town and Durban recreational harbors sustain dedicated watersport retail infrastructure.
Egypt
Red Sea resort corridors along Hurghada and Sharm el-Sheikh generate procurement from European tour operators. Egyptian Organization for Standardization and Quality regulates imported sporting goods conformity. Coastal tourism infrastructure expansion concentrates fleet demand.
Kenya
Underdeveloped coastal tourism infrastructure offers first-mover positioning before marine protected area access restrictions crystallize. Kenya Bureau of Standards enforces product safety for imported recreational equipment. Diani Beach and Watamu clusters exhibit emerging rental service formation.
Middle East and Africa Stand-Up Paddleboard Market Competitive Landscape
Concentration sits with specialized watersport fabricators holding proprietary construction methods and coastal distributor relationships. The vendor base spans British inflatable specialists, Hawaiian heritage brands, and European composite manufacturers. Two strategic archetypes dominate: fusion-construction innovators leveraging heat-welded seam technology, and fishing-specialized hull designers occupying adjacent leisure verticals. Competitive moves center on resort channel exclusivity agreements and MSL fusion construction licensing.
Within the premium inflatable tier, Red Paddle Co exemplifies proprietary technology anchoring through MSL fusion construction methods. Starboard International and Hobie Cat occupy differentiated positions, with the former representing coastal distributor partnership models across Morocco and Kenya, and the latter exemplifying angling-niche specialization in South African recreational harbors.
| Leading Market Players |
|---|
| Hobie Cat |
| Fanatic |
| Red Paddle Co |
| NSP Europe |
| JP Australia |
| Starboard International |
| Naish International |
| Tahe Outdoors |
| BOTE |
| Others |
Supply & Pricing Matrix
Long-term fleet procurement contracts between Red Sea resort operators and European manufacturers lock in volume commitments and price visibility across multi-season horizons, insulating hospitality buyers from spot-market volatility in PVC drop-stitch materials while compressing margins for distributors caught between fixed contract terms and fluctuating input costs.
Pricing Analysis
Rental service operators anchor three-tier pricing structure across premium, standard, and economy levels based on board durability certification and fleet replacement cycles. Price differentiation rests on MSL fusion construction warranties versus glued-seam alternatives, with Emirates Authority for Standardization and Metrology conformity tiers commanding 15-25% premiums. Cost compression in mid-market PVC inflatables is intensifying as automated machinery erodes labor-cost advantages. Individual recreational buyers in Gulf Cooperation Council states exhibit lowest price sensitivity due to wellness-bundled purchasing, while independent rental startups in East Africa face acute margin pressure.
Supply Chain Analysis
Strategic stockpile preferences dominate among Red Sea hospitality operators who pre-position seasonal fleet inventory ahead of certification clearance timelines. Manufacturing concentrates in China, Thailand, and Vietnam for PVC drop-stitch cores, with final assembly increasingly shifting to Romania and Poland to satisfy EU F-Gas Regulation compliance. Aerospace-grade pre-preg carbon fiber feeds from Japan and Germany, creating single-source vulnerability for South African performance board fabricators. Distribution runs through Dubai-based logistics hubs serving Arabian Peninsula coastal clusters, with direct manufacturer relationships bypassing traditional retail markup for institutional buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards defensive positioning through regulatory entrenchment, where Emirates Authority for Standardization and Metrology certification timelines create switching costs that lock rental operators into established supplier relationships.
For Market Incumbents: Compound channel control through exclusive resort partnerships along Saudi Arabia's NEOM and Amaala corridors before marine protected area access restrictions crystallize. Invest in backward integration into MSL fusion construction licensing to defend margin pools against automated assembly entrants. Prioritize certification buffer inventory to exploit South Africa's National Regulator for Compulsory Specifications clearance bottlenecks that strain competitor working capital. For New Entrants and Emerging Players: Emirates Authority for Standardization and Metrology fast-track certification for inflatable variants unlocks immediate access to Dubai's hospitality procurement desks. Target Kenyan and Tanzanian coastal clusters where underdeveloped rental infrastructure offers first-mover positioning before regulatory access restrictions emerge. Pursue fitness-center distribution partnerships in Abu Dhabi and Doha metropolitan zones as a go-to-market angle that bypasses saturated resort channels. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among hospitality group-level fleet contract holders with multi-season renewal visibility. Five-to-ten year viability favors manufacturers with proprietary heat-welded seam technology and established coastal distributor networks across Morocco and Kenya. Monitor marine protected area designation announcements as the critical inflection signal for East African supply-constraint timing.| Strategic Initiative | Industry Significance |
|---|---|
| MSL Fusion Construction Licensing | Proprietary heat-welded seam technology eliminates glue degradation failure modes in Red Sea resort fleets. |
| Coastal Distributor Partnership | Starboard International's Morocco and Kenya network exemplifies channel control against direct-import competition. |
| Fishing-Specialized Hull Development | Hobie Cat's angling-optimized designs capture elevated equipment spend in South African recreational harbors. |
| Emirates Authority Certification Fast-Track | Conformity assessment pre-clearance accelerates inventory velocity for Dubai hospitality procurement desks. |
| East African First-Mover Positioning | Kenyan and Tanzanian marine protected area adjacencies offer pre-restriction fleet deployment advantages. |
Research Methodology
Cross-validation between primary interviews with watersport equipment distributors and secondary customs data anchors the qualitative findings. Stakeholder engagement spanned resort procurement managers, coastal tourism operators, marine safety regulators, drop-stitch machinery suppliers, and fitness-center programming directors. Secondary sources included Emirates Authority for Standardization and Metrology conformity databases, South Africa's National Regulator for Compulsory Specifications buoyancy testing protocols, EU F-Gas Regulation compliance registries, and Red Sea hospitality development permits. Bottom-up fleet procurement surveys triangulate against top-down import volume analysis.
Sensitivity analysis across the modeling period tested demand elasticity for subscription-based rental access versus ownership models. Segmentation dimensions incorporated product architecture, end-user archetype, material certification tier, and distribution channel concentration. CAGRs derived from logistic diffusion curves fitted to hospitality infrastructure buildout timelines, with explicit modeling of PVC drop-stitch machinery automation rates and EU F-Gas Regulation supply chain reconfiguration lag effects.
Decision-makers should treat outputs as directional under stable coastal access permit regimes and sustained Red Sea tourism investment; material deviation in marine protected area enforcement intensity would warrant model refresh. Practitioners should keep alternative scenarios live as Saudi Arabia's NEOM and Amaala project completion schedules and Kenyan regulatory frameworks evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Global Rock Climbing Equipment Market
Sports Equipment
Kids Sports Equipment and Accessories Market
Sports Equipment
UK Horse Riding Equipment Market
Sports Equipment
US Fencing Market
Sports Equipment
Archery Equipment Market
Sports Equipment
Bicycle Helmet Market
Sports Equipment
Racket Sports Equipment Market
Sports Equipment
Golf Club Market
Sports Equipment
Shooting Ranges Market
Sports Equipment
Surfing Boards Market
Sports Equipment
Water Polo Suits Market
Sports Equipment
Parallel Bars Market
Sports Equipment
Playground Sets and Equipment Market
Sports Equipment
Fencing Equipment Market
Sports Equipment
Waist Support Belt Market
Sports Equipment
Trampoline Market