
 Surfing Boards Market | 2026-2036
Surfing Boards Market Size, Share, and Industry Trends Forecast 2026-2036
Surfing Boards Market Analytics
Australia is reconfiguring regional supply dynamics through expanded fiberglass and foam blank manufacturing along the Gold Coast. Firewire Surfboards leverages proprietary parabolic balsa rail construction to differentiate performance characteristics across its product lines. JS Industries anchors premium shortboard output through direct-to-consumer channels and team-rider validation programs. Channel Islands Surfboards sustains competitive positioning via custom shaping services and deep retail partnerships in California and Hawaii.
Surfing boards are hydrodynamic planing vessels typically measuring five to twelve feet in length, constructed from foam cores laminated with fiberglass and resin systems, designed to convert wave energy into controlled propulsion for riders. Shortboard and fish categories command the highest margin pools due to shorter replacement cycles and technology-intensive shaping requirements, while longboard demand remains structurally stable among beginner and touring segments. Epoxy construction is displacing traditional polyurethane across recreational and instructional usage tiers as durability expectations rise and environmental scrutiny intensifies.
The EPA governs volatile organic compound emissions from resin manufacturing facilities in the United States, while REACH regulates chemical inputs across European supply chains and California's Proposition 65 mandates disclosure requirements for fiberglass dust exposure. Australia's Competition and Consumer Commission monitors product safety standards for recreational watercraft, creating compliance layering that favors established manufacturers with dedicated quality infrastructure. Stakeholders must monitor evolving bio-resin certification protocols and regional carbon-accounting rules that will determine material eligibility for institutional procurement programs.
Market Dynamics
Epoxy construction is migrating from niche performance segments toward mass-market recreational tiers as durability expectations intensify and REACH chemical restrictions tighten polyurethane foam supply chains across European manufacturing bases.
Growth Catalysts
- REACH chemical restrictions:The EU's evolving framework on polyurethane foam formulations accelerates manufacturer investment in bio-based epoxy alternatives and parabolic balsa rail systems.
- Youth competitive programs:Collegiate and junior-level surfing circuits in Australia and the United States compress replacement cycles through institutional procurement of standardized equipment.
- Gold Coast manufacturing cluster:Expanded fiberglass and foam blank production along Australia's eastern seaboard shortens lead times for Asia-Pacific distribution networks.
Market Restraints
- Petrochemical input volatility:Resin and fiberglass pricing fluctuates with crude oil derivatives, compressing margin pools for mid-tier manufacturers lacking forward-contract coverage.
- Blank supplier concentration:Three specialized foam blank producers dominate North American supply, creating vulnerability to single-source disruptions.
- California Proposition 65 compliance:Fiberglass dust exposure disclosure mandates add litigation risk and insurance overhead for retail and rental operations.
Strategic Opportunities
- Bio-resin certification protocols:Early alignment with emerging carbon-accounting standards positions manufacturers for institutional procurement programs in European surf school networks.
- Direct-to-consumer channel expansion:Team-rider validation programs and custom shaping services bypass traditional retail markups while capturing premium price tiers.
- Longboard touring segment:Underpenetrated demand among aging recreational surfers in Portugal and Spain supports dedicated product line development.
Industry Challenges
- Master shaper talent scarcity:Hand-finishing expertise concentrates among aging practitioners in Hawaii and California, constraining custom output scalability.
- Capex intensity of epoxy conversion:Vacuum infusion and heated press equipment demands seven-figure facility upgrades for traditional polyurethane manufacturers.
- Multi-jurisdiction safety certification:Australia's Competition and Consumer Commission standards diverge from EPA volatile organic compound rules, fragmenting quality infrastructure requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Surfing Boards Market |
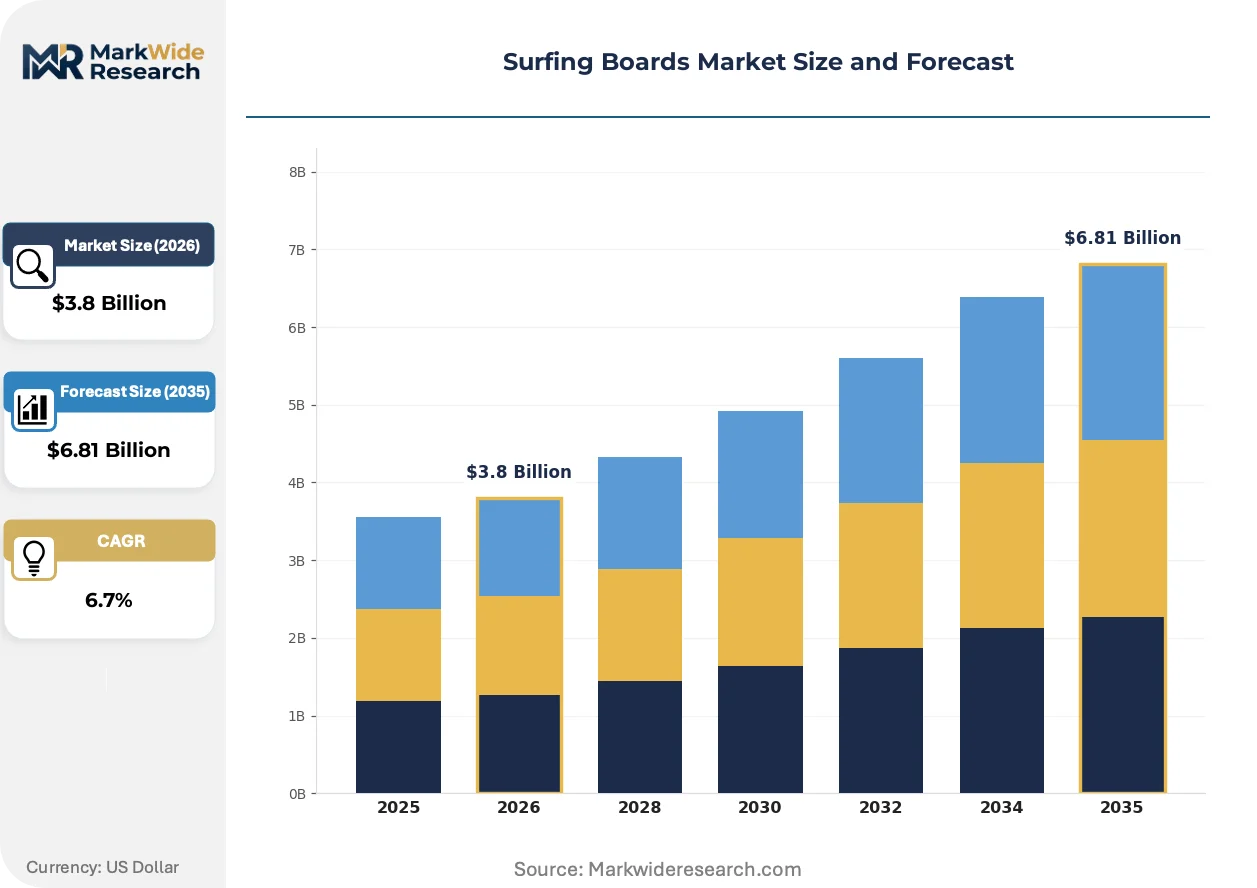
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Board Type: Shortboard, Longboard, Fish, Gun Material: Epoxy, Polyurethane, Bamboo, Carbon Fiber Skill Level: Beginner, Intermediate, Advanced, Professional Usage: Recreational, Competitive, Touring, Instructional |
| Companies Covered | Channel Islands Surfboards, Firewire Surfboards, JS Industries, Rip Curl Group Pty Ltd, Rusty Surfboards, Haydenshapes Surfboards, Boardriders, Billabong International Limited, Lost Enterprises, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Surfing Boards Market Evolving Landscape
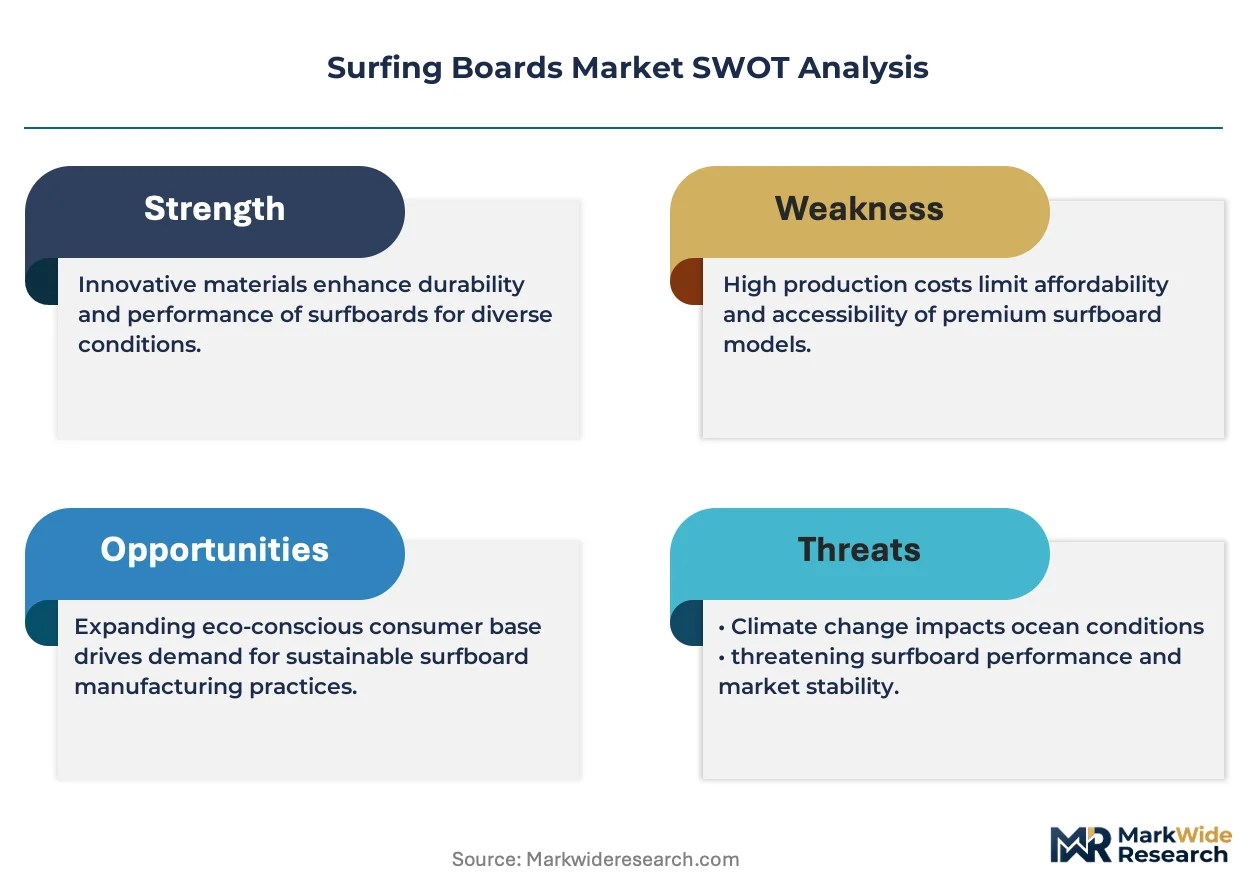
Material science advances and regulatory chemistry constraints are rewriting construction specifications across all price tiers. Distribution models are compressing as digital channels capture educated buyers. Sustainability credentials are becoming gatekeepers for institutional contracts.
Parabolic balsa rail construction is migrating from Firewire's proprietary systems toward licensed adoption by mid-tier Australian manufacturers seeking differentiation in shortboard performance categories. Recreational riders and surf schools now specify epoxy-balsa builds for durability despite twenty-percent price premiums over traditional polyurethane. This migration from niche to mainstream is compressing replacement cycle economics and reshaping warranty liability structures across the supply base.
The EPA's volatile organic compound emission standards for resin manufacturing facilities are forcing consolidation among small-batch fiberglass operations in California and Florida. Compliance retrofit costs exceed five hundred thousand dollars per facility, driving exit decisions among independent producers. Custom shaping houses are responding by outsourcing lamination to certified contract manufacturers or relocating finishing operations to Mexico.
Rental fleet operators and surf schools are unbundling equipment procurement from instruction packages, creating dedicated volume buyers with standardized specifications. This procurement model compression displaces individualized retail relationships in Australia, Portugal, and Indonesia. Institutional buyers now negotiate direct with manufacturers on three-year replacement cycles, bypassing traditional wholesale distribution entirely.
Surfing Boards Market Segmentation
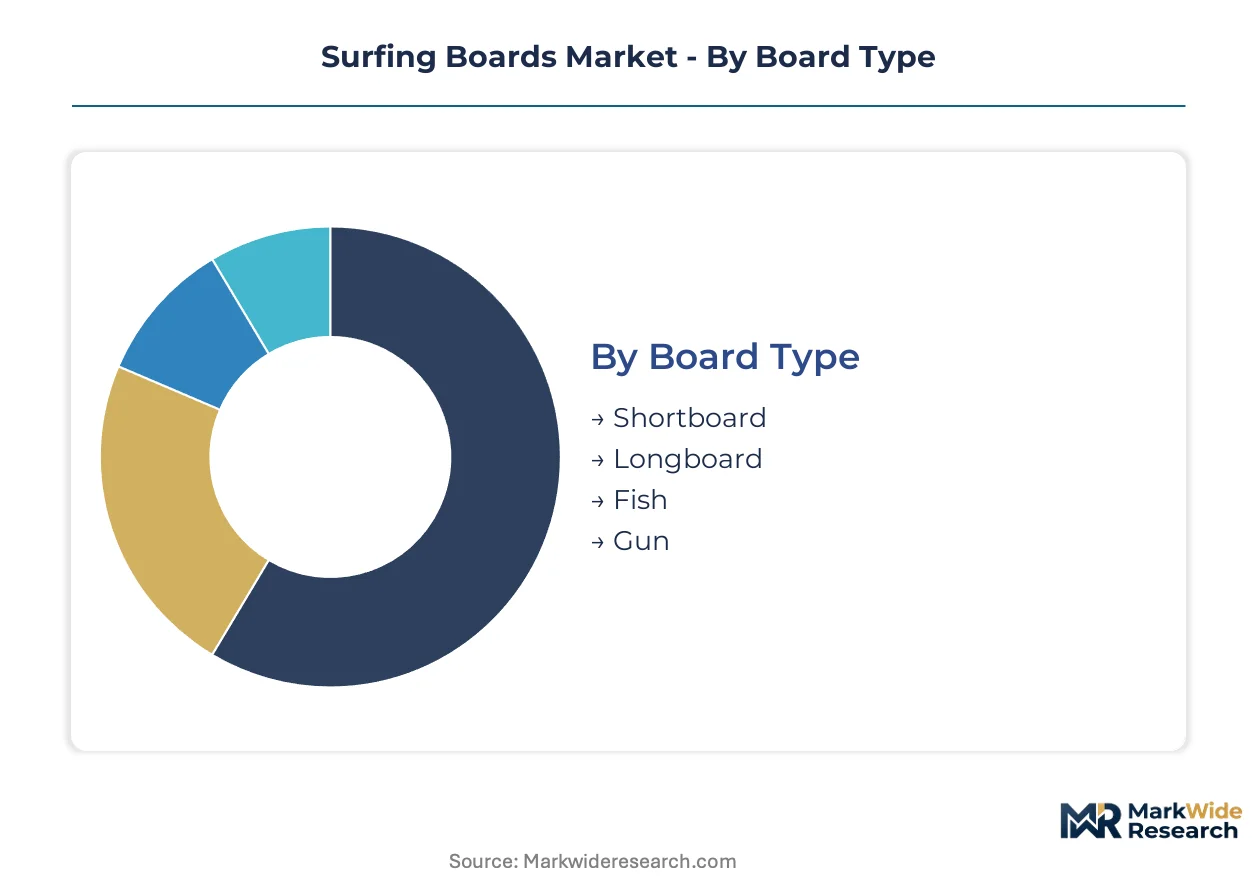
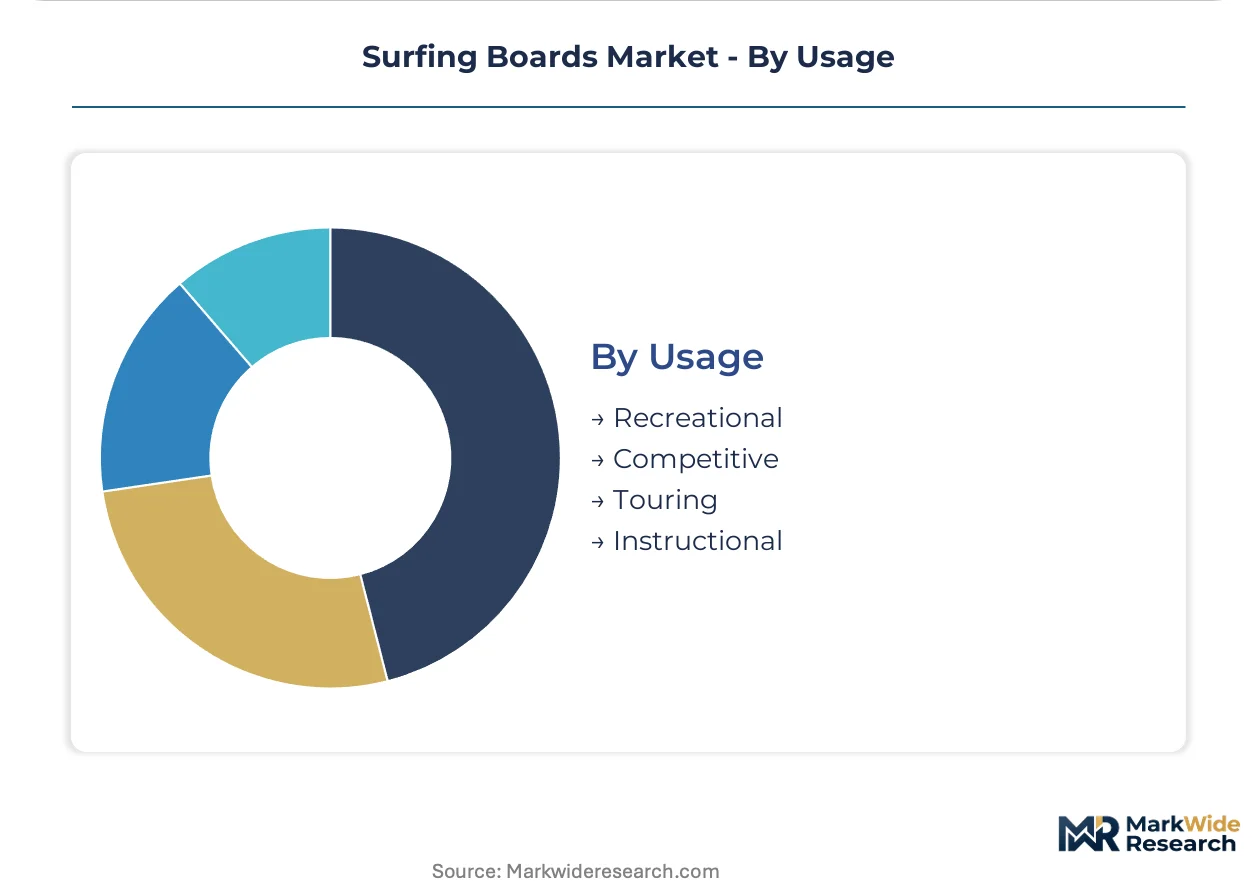
Segmentation in surfing boards reveals divergent margin structures and replacement economics across construction methods and rider profiles. Manufacturers calibrate warranty terms and service commitments differently for each tier, creating distinct after-sales revenue streams.
Board Type:
After-sales service intensity varies sharply by board type, with high-performance shortboards demanding frequent ding repair and fin system maintenance while longboards require minimal intervention over extended ownership periods.
- Shortboard:Compact planing hulls measuring five to seven feet prioritize maneuverability in steep wave faces. Australia's Gold Coast competitive circuits and California team-rider programs drive replacement every eighteen to twenty-four months. By volume, shortboard leads. By growth pace, fish is ahead.
- Longboard:Nine-to-twelve-foot displacement hulls optimize glide and stability for small-wave conditions. Portugal's aging recreational demographic and Spain's surf school networks sustain steady demand with five-to-seven-year replacement cycles.
- Fish:Wide-nose, swallow-tail designs bridge shortboard agility with longboard paddle power. Hybrid construction appeals to intermediate surfers seeking single-board versatility across variable conditions.
- Gun:Narrow, elongated shapes engineered for big-wave tow-in and paddle surfing. Specialized lamination requirements and custom rail profiles limit production to master shapers in Hawaii and Australia's eastern seaboard.
Margin concentration follows replacement frequency: shortboard and fish command premium pricing through compressed ownership cycles, while longboard and gun segments stabilize revenue through extended durability expectations.
Material:
Cost tier stratification separates premium epoxy-balsa builds from economy polyurethane constructions, with material choice directly determining warranty liability exposure and repair network density.
- Epoxy:Thermoset resin systems laminated over expanded polystyrene or balsa cores deliver superior impact resistance and reduced weight. REACH chemical restrictions in Europe and durability mandates from Australian surf schools accelerate displacement of traditional polyurethane. Epoxy holds the largest volume position. Carbon fiber is climbing the fastest.
- Polyurethane:Polyester resin over polyurethane foam blanks remains the historical standard for custom shaping houses. California's EPA volatile organic compound regulations and blank supplier concentration in North America constrain expansion.
- Bamboo:Veneer-sandwich construction substitutes renewable fiber for fiberglass in deck and bottom laminates. Bio-resin certification protocols in European institutional procurement favor bamboo-epoxy combinations for surf school fleets.
- Carbon Fiber:High-modulus fiber reinforcement concentrates in professional shortboards and big-wave guns where stiffness-to-weight ratios determine performance. Capex intensity limits adoption to premium tier manufacturers with vacuum infusion capability.
Supply concentration favors established epoxy producers with certified lamination facilities, while polyurethane dependence exposes mid-tier manufacturers to petrochemical input volatility.
Skill Level:
Customer type segmentation maps directly to distribution channel strategy, with beginners entering through rental-conversion programs and professionals negotiating direct manufacturer relationships.
- Beginner:Soft-top and epoxy constructions dominate entry-level procurement through surf school partnerships and resort rental fleets. Australia's coastal tourism infrastructure channels standardized specifications to volume manufacturers.
- Intermediate:Riders transitioning from rental equipment to first ownership drive fish and funboard demand. Custom shaping services capture this cohort through progressive rail and rocker adjustments.
- Advanced:Experienced surfers specify performance characteristics across multiple board types for condition-specific quiver building. Direct-to-consumer channels bypass retail markups for this educated buyer segment.
- Professional:Team-rider validation programs and contest circuit exposure requirements command dedicated production lines with rapid prototyping turnaround. Hawaii and Australia's Gold Coast concentrate elite talent and associated manufacturing relationships.
Revenue stability concentrates in beginner and intermediate tiers through institutional procurement, while professional segment volatility rewards manufacturers with flexible custom capacity.
Usage:
Application context determines construction durability specifications and replacement cycle economics, with competitive and instructional usage imposing the most rigorous performance standards.
- Recreational:Weekend and vacation surfers prioritize durability and transport convenience over marginal performance gains. Epoxy construction captures this segment through extended warranty terms and reduced repair frequency.
- Competitive:Junior, collegiate, and professional circuits demand standardized equipment for fairness and sponsor visibility. Australia's expanded competitive programming compresses replacement cycles across all skill tiers.
- Touring:Extended surf travel requires robust construction for airline handling and diverse wave conditions. Portugal and Spain's aging demographic supports dedicated product development for this underpenetrated segment.
- Instructional:Surf schools and rental operators unbundle equipment from lesson packages, creating volume buyers with three-year replacement mandates. Institutional procurement bypasses traditional wholesale distribution in Indonesia and Australia's eastern states.
Procurement centralization in instructional and competitive usage is reshaping manufacturer-customer relationships, while recreational and touring segments retain fragmented retail channel dependence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fiberglass and foam blank manufacturing clusters in Australia, California, and Portugal concentrate supply-side capacity, while REACH chemical restrictions and EPA emission standards fragment production compliance across jurisdictions.
United States
California's coastal competitive circuits and Hawaii's elite shaping houses drive demand for high-performance shortboards. EPA volatile organic compound regulations force lamination facility consolidation, pushing independent producers toward contract manufacturing or cross-border relocation. Los Angeles and Orange County retain custom shaping density despite compliance cost pressures.
Australia
Gold Coast manufacturing expansion shortens Asia-Pacific distribution lead times while Queensland and New South Wales surf school networks sustain institutional procurement volumes. The Competition and Consumer Commission enforces recreational watercraft safety standards that favor established quality infrastructure. Fiberglass and expanded polystyrene blank production concentrates along the eastern seaboard.
Portugal
Aging recreational demographics and surf tourism infrastructure in the Algarve and Lisbon coastal zones support longboard and touring segment demand. EU REACH chemical restrictions on polyurethane foam accelerate epoxy construction adoption among surf school fleets. Peniche and Ericeira host European competitive events that validate regional equipment specifications.
Indonesia
Bali and Lombok surf tourism drives rental fleet standardization and three-year replacement procurement cycles. Institutional buyers unbundle equipment from instruction packages, bypassing traditional wholesale channels. Local manufacturing remains limited; distribution depends on Australian and Chinese supply sources.
Spain
Basque Country and Galicia surf schools generate beginner and intermediate equipment demand through coastal tourism programs. National transposition of EU REACH framework restricts polyurethane foam formulations, favoring epoxy-balsa construction. Santander and San Sebastian anchor northern retail and rental network density.
Surfing Boards Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in blank supply and resin formulation. Market structure concentrates among established manufacturers with certified lamination facilities, while mid-tier players face exit pressures from compliance retrofit costs. Three archetypes dominate: vertically integrated premium builders, specialized custom shaping houses, and volume-oriented institutional suppliers. Competitive moves center on direct-to-consumer channel expansion and bio-resin certification alignment.
Within the premium construction tier, Firewire Surfboards and JS Industries exemplify technology-differentiated positioning, while Channel Islands Surfboards anchors the custom shaping archetype through retail partnership density. These three manufacturers represent distinct strategic paths: proprietary material systems, direct channel capture, and deep wholesale integration respectively.
| Leading Market Players |
|---|
| Channel Islands Surfboards |
| Firewire Surfboards |
| JS Industries |
| Rip Curl Group Pty Ltd |
| Rusty Surfboards |
| Haydenshapes Surfboards |
| Boardriders |
| Billabong International Limited |
| Lost Enterprises |
| Others |
Value Network & Pricing Analysis
The Brisbane-Sydney freight corridor carries foam blanks and resin systems from Gold Coast manufacturing clusters to Australian surf school networks and Asia-Pacific distribution nodes. Its container cost dynamics amplify pricing power for epoxy-balsa builders while compressing margins for polyurethane-dependent mid-tier manufacturers lacking forward-contract coverage on petrochemical inputs.
Pricing Analysis
REACH chemical restrictions dictate the pricing tier structure across European supply chains. Three-tier pricing structure across premium, standard, and economy levels separates certified bio-resin epoxy constructions from conventional polyurethane builds and entry-level soft-tops. Price differentiation hinges on lamination certification grade and volume scale in institutional procurement. Cost compression in standard-tier polyurethane runs through crude oil derivative volatility. Beginner segment buyers through surf school rental fleets exhibit highest price sensitivity; professional team-rider programs show lowest.
Supply Chain Analysis
Extended payment terms from Australian surf school networks and institutional procurement programs strain working capital for mid-tier manufacturers. Supply concentrates in Australia, the United States, and Portugal for fiberglass lamination and foam blank production. Raw material dependencies rest on petroleum-derived resins, balsa rail stock, and carbon fiber reinforcement. Single-source vulnerability permeates North American foam blank supply with three dominant producers. Distribution runs through direct-to-consumer channels for premium builders and wholesale networks for recreational tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Epoxy construction migration and REACH chemical restrictions constitute a regulatory-technology inflection reshaping material eligibility and procurement standards across institutional buyer networks.
For Market Incumbents: Pre-empt margin erosion from bio-resin certification mandates by accelerating in-house production of parabolic balsa rail systems and vacuum infusion capacity. Anchor quality infrastructure investments to Australia's Competition and Consumer Commission safety standards. Consolidate custom shaping relationships before master shaper talent scarcity constrains output scalability. For New Entrants and Emerging Players: Portugal's aging recreational demographic and underpenetrated longboard touring segment represent the most penetrable entry point for dedicated product line development. Australia's surf school procurement unbundling creates volume buyer access without traditional wholesale channel buildout. Pursue direct institutional contracting with three-year replacement cycle specifications. For Investors and Strategic Acquirers: Specialized epoxy lamination facilities with certified vacuum infusion capability offer the strongest acquisition target archetype for long-term viability across the analysis window. Monitor bio-resin certification protocol adoption rates in European surf school networks as the critical inflection indicator for material eligibility and pricing power shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Bio-Resin Certification Alignment | REACH-compliant epoxy formulations secure institutional procurement contracts in EU surf school networks. |
| Direct-to-Consumer Channel Expansion | Team-rider validation programs bypass retail markups and capture premium price tiers in Australia and California. |
| Backward Integration into Balsa Rail Supply | Proprietary parabolic rail construction differentiates shortboard performance and insulates from raw material volatility. |
| Custom Shaping Capacity Addition | Master shaper relationships in Hawaii and Queensland constrain scalable output for intermediate-to-advanced segments. |
| Institutional Procurement Partnership | Three-year replacement cycle contracts with Australian surf schools stabilize revenue and displace wholesale dependence. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with surf school procurement managers, custom shaping house owners, epoxy lamination facility engineers, and retail channel partners. Secondary validation drew from EPA emission filings, ECHA REACH substance registrations, Australian Competition and Consumer Commission safety standards, and customs trade data on fiberglass and resin imports. Bottom-up volume estimates from board-type and material segmentation triangulated against top-down market sizing from coastal tourism expenditure and competitive program enrollment data.
Calibration against historical replacement cycle compression and regulatory implementation timelines anchored growth trajectory assumptions across the projection horizon. Segmentation dimensions modeled include construction material, board type, skill tier, and usage context alongside regional regulatory cluster differentiation. CAGRs were derived from trend extrapolation of youth competitive program expansion and epoxy adoption curves. Forecast inputs incorporated petrochemical price volatility indices and bio-resin certification protocol development timelines.
Practitioners should monitor REACH chemical restriction enforcement intensity and EPA volatile organic compound compliance retrofit rates for early signals of supply-side consolidation acceleration. Forecasts reflect assumptions on institutional procurement unbundling velocity and master shaper talent pipeline constraints. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Kneeboard Market
Sports Equipment
Kick Scooter Tire Market
Sports Equipment
Shuffleboard Equipment Market
Sports Equipment
One-Piece Carbon Fiber Badminton Racket Market
Sports Equipment
Germany Horse Riding Equipment Market
Sports Equipment
Sports Mouthguard Market
Sports Equipment
Europe Archery Equipment Market
Sports Equipment
Global Golf Training Aids Market
Sports Equipment
Equestrian Equipment Market
Sports Equipment
Sports Equipment Market
Sports Equipment
Crampon Market
Sports Equipment
Global Rock Climbing Equipment Market
Sports Equipment
Mountain Bicycle Cassette Market
Sports Equipment
Smart Boxing Gear Market
Sports Equipment
Kids Sports Equipment and Accessories Market
Sports Equipment
Playground Sets and Equipment Market