
 Kids Sports Equipment and Accessories Market | 2026-2036
Kids Sports Equipment and Accessories Market Size, Share, and Industry Trends Forecast 2026-2036
Kids Sports Equipment and Accessories Market Foresight
Premium safety certification tiers is unwinding outdated commodity positioning across the kids sports equipment landscape. Nike Inc. leverages its R&D intensity to engineer youth-specific cushioning systems that exceed baseline protective standards. Adidas AG anchors European club partnerships to secure early-age brand loyalty through licensed mini-kits and training gear. Decathlon SA competes on manufacturing scale, vertically controlling design-to-retail cycles that compress price points for entry-level families.
Kids sports equipment and accessories encompasses purpose-built athletic goods engineered for developing bodies, typically incorporating scaled-down dimensions, reduced-weight composites such as aluminum alloys or carbon-fiber blends, and impact-absorbing polymers that meet juvenile biomechanical tolerances. These products serve organized youth athletics, recreational physical education, and developmental training programs where proper fit and injury prevention determine usability. Protective gear commands disproportionate margin pools as parental risk aversion intensifies spending on helmets, pads, and mouthguards. The pre-teens age bracket generates the steepest volume trajectory as school-sport mandates and club expansions converge at the nine-to-twelve demographic. Online retail is displacing traditional sporting goods stores for repeat purchases, though specialty shops retain dominance for first-fit categories requiring expert measurement.
ASTM International governs impact-resistance testing for youth helmets and facial protection, while the Consumer Product Safety Commission enforces recall protocols and lead-content bans that shape material sourcing decisions. State-level concussion protocols in California, Texas, and New York are mandating certified protective gear for public school athletics, tightening compliance thresholds for market access. Stakeholders must monitor how evolving biomechanical research on repetitive head impact reshapes product liability frameworks and insurance requirements for youth leagues and equipment vendors.
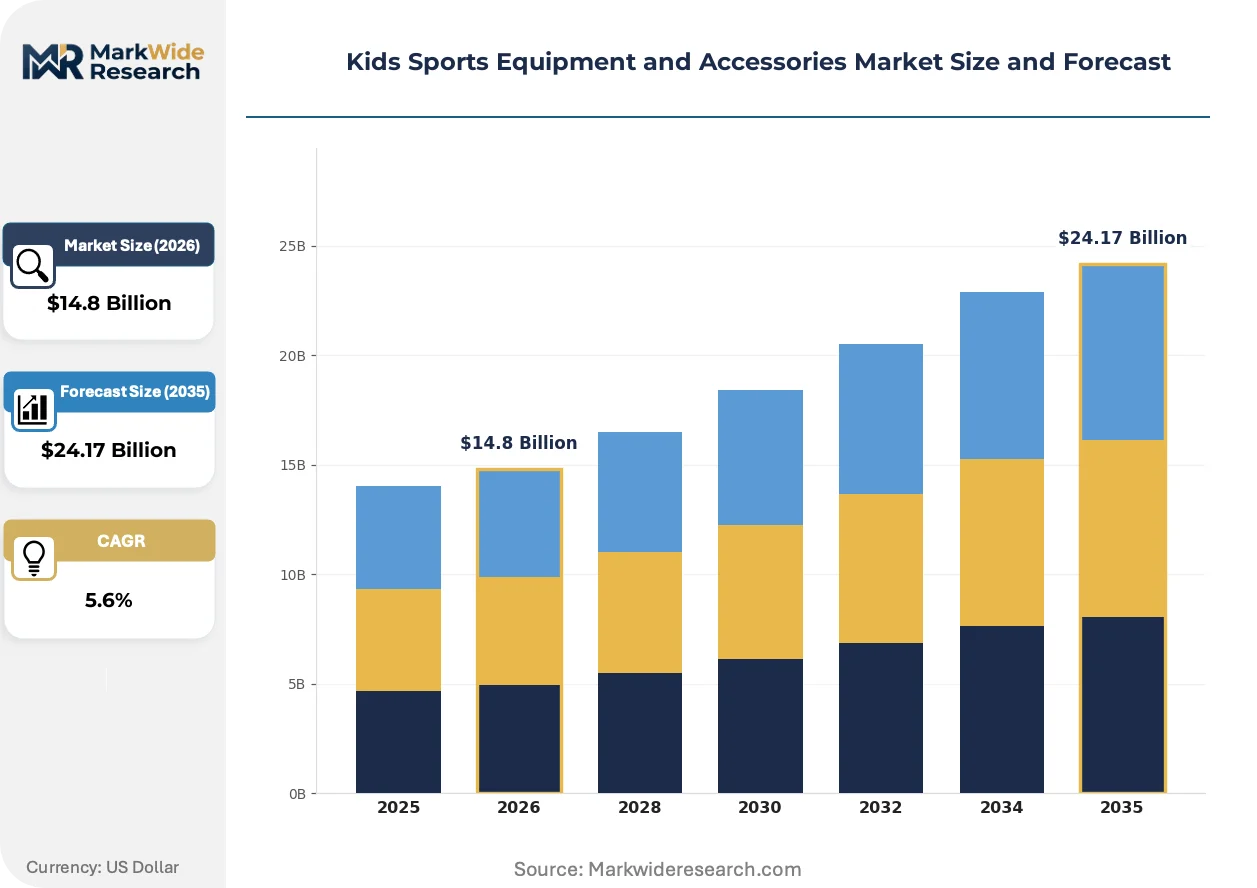
Market Dynamics
Parental risk aversion is compressing price elasticity for protective headgear while school concussion protocols mandate certified equipment, creating a bifurcation between compliance-grade and premium-safety tiers that reshapes vendor positioning.
Growth Catalysts
- State concussion mandates:California, Texas, and New York public school protocols require ASTM-certified protective gear for athletic participation, forcing inventory upgrades across district procurement cycles.
- Youth soccer expansion:North American league participation growth drives recurring demand for age-scaled balls, shin guards, and goalkeeper gloves sized for juvenile biomechanics.
- Carbon-fiber composites:Reduced-weight bat and racket materials enable earlier skill development while reducing repetitive strain injuries in pre-teen athletes.
Market Restraints
- Petrochemical input volatility:Impact-absorbing polymer prices fluctuate with crude oil derivatives, compressing margin stability for molded protective equipment manufacturers.
- Specialty retail concentration:First-fit categories requiring expert measurement depend on declining brick-and-mortar sporting goods chains, creating channel access risk for new entrants.
- Biomechanical testing gaps:Juvenile headform standards lag adult research, leaving liability exposure for helmet vendors as repetitive impact science evolves.
Strategic Opportunities
- Direct-to-parent subscription models:Size-exchange programs for growing children capture lifetime value through recurring replacement cycles bypassing seasonal retail.
- Smart mouthguard integration:Converging sensor technology with dental protection enables impact telemetry for youth leagues managing concussion protocols.
- Adaptive equipment for inclusive athletics:Wheelchair basketball and seated volleyball gear addresses underpenetrated parasports segments with specialized fitting requirements.
Industry Challenges
- Certification timeline compression:ASTM International's tightening test protocols require retooling cycles that outpace typical product development schedules.
- Pediatric anthropometric data scarcity:Sizing databases for diverse juvenile populations remain incomplete, forcing costly custom fitting for non-standard body types.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kids Sports Equipment and Accessories Market |
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $24.17 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Balls, Bats, Rackets, Protective Gear Age Group: Toddlers, Children, Pre-teens, Teens Activity Type: Soccer, Basketball, Gymnastics, Tennis Distribution Channel: Online Retail, Sporting Goods Stores, Department Stores, Specialty Shops |
| Companies Covered | Nike Inc., Adidas AG, PUMA SE, Under Armour Inc., Decathlon SA, Wilson Sporting Goods, Mizuno Corporation, Franklin Sports Inc., JD Sports Fashion plc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kids Sports Equipment and Accessories Market Shifts & Advancements
Material science breakthroughs and regulatory precision are converging to redefine safety-performance tradeoffs, while digital channels restructure how parents research and replace equipment across developmental growth spurts.
Additive manufacturing is fragmenting traditional mold-based production economics for custom-fitted mouthguards and protective pads. Club sports programs in competitive suburban districts are adopting scan-to-print workflows at accelerating rates. This technology is fragmenting volume concentration among mass-market suppliers while enabling regional dental labs and orthotics specialists to capture premium positioning.
ASTM International's revised youth helmet impact-resistance standards are mandating multi-directional testing protocols that obsolete single-axis certification. Manufacturers must redesign shell geometries and liner densities to meet rotational acceleration thresholds. The pre-teen football and ice hockey segments face the steepest compliance costs, with vendors absorbing retooling expenses to maintain school district eligibility.
Parents are consolidating purchase authority through league-sponsored bulk ordering platforms that aggregate sizing data and negotiate volume discounts. Traditional sporting goods retailers lose repeat purchase traffic as these digital cooperatives capture replacement cycles for outgrown gear. This behavioral shift concentrates most visibly in United States suburban districts with dense youth sports participation and active parent volunteer organizations.
Kids Sports Equipment and Accessories Market Segmentation
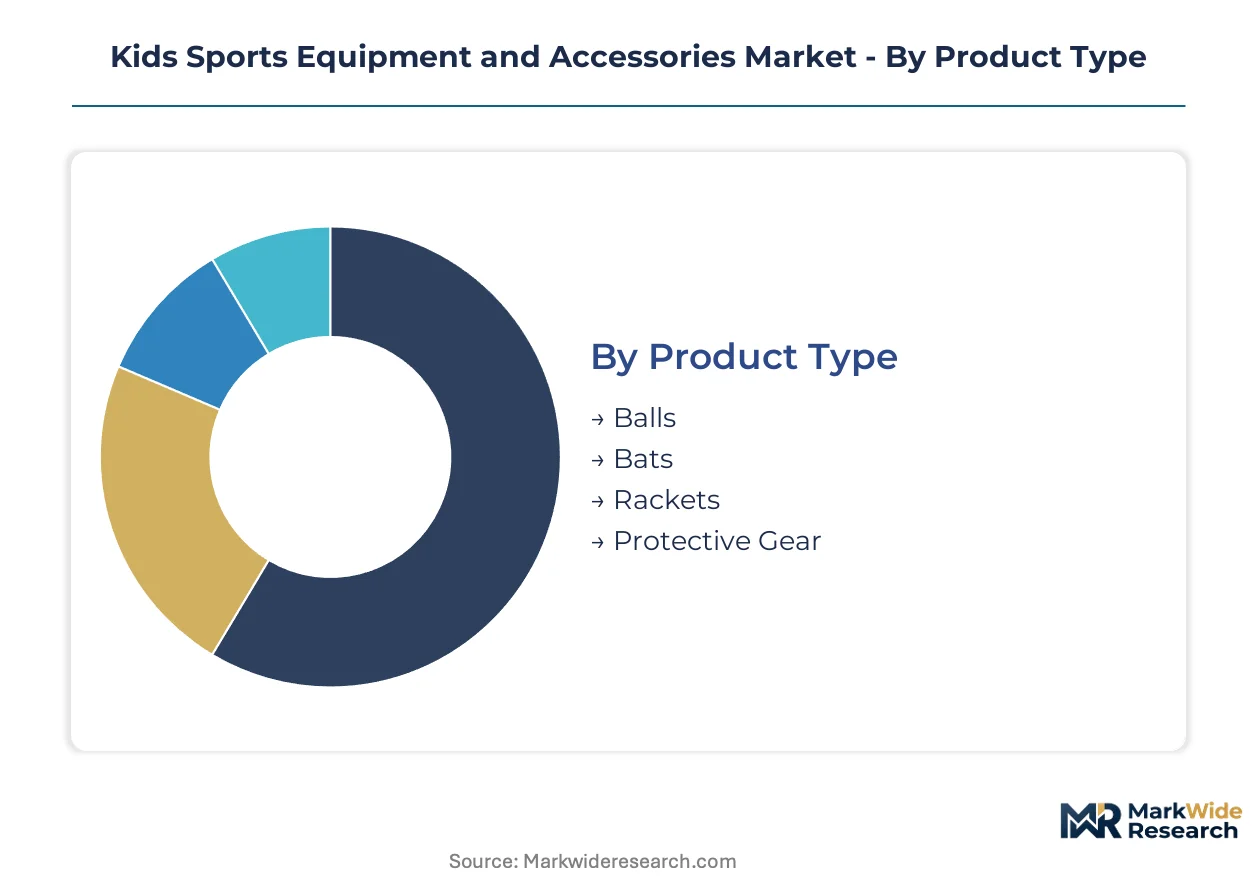
Kids sports equipment and accessories segment along developmental, functional, and commercial dimensions that shape manufacturing priorities and channel strategy. Understanding these splits reveals where safety certification investments concentrate and how growth trajectories diverge across age brackets and activity types.
Product Type:
Domestic production clusters around molded protective gear in the United States, while bat and racket assembly increasingly sources carbon-fiber composites from Asian suppliers. Balls remain the most geographically distributed manufacturing category.
- Protective Gear:Helmets, pads, and mouthguards incorporate multi-density foams and polycarbonate shells engineered for juvenile impact tolerances. California, Texas, and New York school districts mandate ASTM-certified gear, concentrating procurement upgrades in these states.
- Balls:Size-scaled constructions use synthetic leather and rubberized bladders calibrated for age-appropriate weight and rebound characteristics. Youth soccer league expansion across North America drives recurring replacement demand for size 3 and size 4 specifications.
- Bats:Aluminum alloys and carbon-fiber composites reduce swing weight for developing athletes. League regulations in competitive suburban districts constrain material specifications.
- Rackets:Graphite and carbon-fiber frames with junior grip circumferences enable earlier technical skill acquisition. Tennis academy pipelines in Florida and California anchor premium positioning.
Protective Gear commands the established base. The steepest expansion runs through Balls.
Age Group:
Cost tier segmentation separates entry-level toddler equipment from premium pre-teen gear where parental investment intensifies.
- Pre-teens:Nine-to-twelve demographic generates peak volume as school-sport mandates and club expansions converge. Equipment specifications bridge recreational and competitive tiers, requiring durability upgrades.
- Children:Five-to-eight segment depends on physical education procurement cycles and introductory league enrollment. Sizing standardization remains inconsistent across vendors.
- Toddlers:Foam-based introductory products prioritize safety over performance metrics. Preschool program adoption drives institutional purchasing.
- Teens:Thirteen-plus athletes transition toward adult-sizing thresholds, compressing category-specific demand. Retention challenges emerge as specialization narrows multi-sport participation.
Pre-teens anchor volume concentration. Toddlers exhibit the most rapid climb in per-capita spending.
Activity Type:
Application-based segmentation tracks how seasonal participation patterns and league infrastructure shape equipment replacement cycles.
- Soccer:Shin guards, goalkeeper gloves, and age-scaled balls dominate volume. North American league participation growth sustains recurring demand across all age brackets.
- Basketball:Indoor court specifications and rim height progressions drive size-graded ball and footwear requirements. School district procurement anchors institutional demand.
- Gymnastics:Mats, beams, and bars require specialized fitting for home and facility use. Club membership density in suburban districts determines regional concentration.
- Tennis:Racket sizing progression and court dimension scaling support developmental pipeline structures. Academy systems in warm-climate states sustain year-round demand.
Soccer captures the broadest participation base. Basketball demonstrates the strongest institutional procurement momentum.
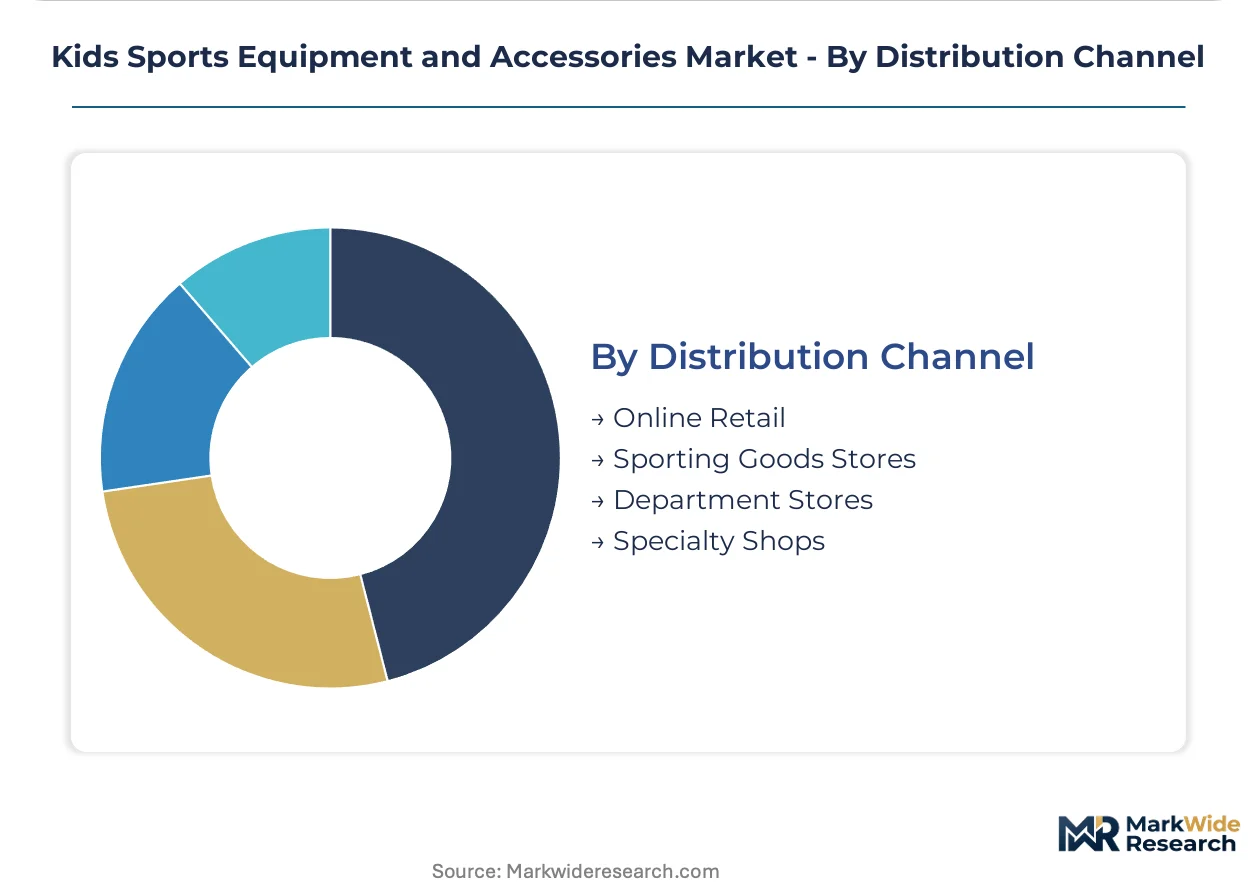
Distribution Channel:
Customer-type segmentation separates first-fit purchases requiring expert guidance from repeat replacements suited to transactional efficiency.
- Specialty Shops:Expert measurement services for helmets and protective gear retain dominance in safety-critical categories. Staff certification requirements create barrier to entry.
- Online Retail:Repeat purchases for outgrown gear consolidate through league-sponsored platforms and direct-to-parent subscriptions. Size-exchange programs capture lifetime value.
- Sporting Goods Stores:Multi-sport inventory breadth serves families with diversified athletic participation. Foot traffic compression challenges traditional chains.
- Department Stores:Entry-level positioning for recreational and seasonal equipment. Price compression limits margin recovery.
Specialty Shops defend the high-consideration segment. Online Retail gains share fastest in replacement cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Parents in suburban United States districts show the lowest price elasticity for ASTM-certified protective gear, while entry-level families in emerging markets prioritize cost compression over certification tiers, creating a demand-elasticity gradient that shapes regional vendor strategies.
United States
California, Texas, and New York public school concussion protocols mandate certified protective equipment, forcing district-level procurement upgrades every three to four years. The Consumer Product Safety Commission enforces lead-content bans and recall protocols that constrain material sourcing from Asian suppliers. Dallas-Fort Worth and Orange County anchor the densest youth sports club concentrations, where parent volunteer organizations drive league-sponsored bulk ordering platforms.
Germany
Club sports infrastructure and mandatory school athletics programs sustain steady equipment replacement cycles across the nine-to-twelve demographic. ECHA REACH regulations govern chemical content in impact-absorbing polymers and synthetic leather ball coverings. Bavaria's Munich-Stuttgart corridor hosts specialized retail chains that dominate first-fit protective gear measurements for competitive youth leagues.
China
Rising middle-class investment in developmental tennis and soccer academies expands demand for carbon-fiber rackets and age-scaled balls. SAMR enforces national standards for juvenile product safety that increasingly align with ASTM International test protocols. The Yangtze River Delta manufacturing cluster supplies molded protective equipment to both domestic distributors and export markets.
Brazil
Youth soccer league participation drives volume demand for size-graded balls and shin guards across municipal and private club systems. ANVISA regulates medical-grade mouthguard materials used in competitive athletics. São Paulo's industrial belt concentrates domestic assembly operations for entry-level equipment serving price-sensitive families in the five-to-eight segment.
United Kingdom
School sport mandates and county-level athletic programs anchor institutional procurement for protective gear and scaled-down rackets. Trading Standards enforces CE marking requirements for imported equipment. London's suburban districts and the Greater Manchester corridor exhibit the highest per-capita spending on premium safety-certified helmets and pads.
Kids Sports Equipment and Accessories Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with R&D-intensive specialists commanding premium positioning in protective gear while vertically integrated retailers compress price points for entry-level families. The market structure exhibits moderate consolidation among global athletic brands, with fragmentation persisting in regional specialty suppliers and custom-fitting services. Three archetypes dominate: multinational sportswear conglomerates with youth-specific R&D pipelines, mass-market retailers controlling design-to-retail cycles, and regional specialists offering measurement-dependent first-fit services. Competitive moves concentrate on direct-to-parent subscription models and smart equipment integration.
Among the multinational sportswear conglomerates, Nike Inc. and Adidas AG exemplify divergent geographic anchoring strategies, with the former emphasizing North American school-sport procurement relationships and the latter leveraging European club partnerships for early-age brand capture. PUMA SE occupies a position within the tier focused on lifestyle-athletic crossover positioning. Decathlon SA represents the vertically integrated mass-market archetype, compressing price points through captive manufacturing and direct retail control. Wilson Sporting Goods and Franklin Sports Inc. sit within the specialty equipment tier, serving measurement-critical categories where expert fitting retains channel importance.
| Leading Market Players |
|---|
| Nike Inc. |
| Adidas AG |
| PUMA SE |
| Under Armour Inc. |
| Decathlon SA |
| Wilson Sporting Goods |
| Mizuno Corporation |
| Franklin Sports Inc. |
| JD Sports Fashion plc. |
| Others |
Supply & Pricing Matrix
Long-term district procurement contracts with California, Texas, and New York public school systems lock in ASTM-certified protective gear supply while anchoring price visibility across multi-year replacement cycles. These agreements compress margin volatility for compliant vendors while forcing non-certified competitors toward spot-market pricing softness in the entry-level tier.
Pricing Analysis
ASTM International certification dictates the pricing tier structure across the kids sports equipment landscape, separating premium safety-grade helmets and pads from standard recreational offerings. Three-tier pricing structure across premium, standard, and economy levels stratifies by impact-resistance rating, with California school districts absorbing the steepest premiums for multi-directional testing compliance. Cost compression in the economy tier is intensifying because petrochemical input volatility squeezes molded protective equipment margins. Entry-level families in emerging markets exhibit the highest price sensitivity, while suburban United States parents show minimal elasticity for certified headgear.
Supply Chain Analysis
China and Vietnam anchor molded protective gear and synthetic leather ball production, while Taiwan and South Korea supply carbon-fiber composites for premium bats and rackets. The Yangtze River Delta manufacturing cluster draws from petroleum-derived polymers and aluminum alloy feedstocks, with downstream distribution running through league-sponsored bulk ordering platforms and direct-to-parent subscription channels. Single-source vulnerability concentrates in impact-absorbing polymer formulations where ASTM retooling requirements outpace alternative supplier qualification timelines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
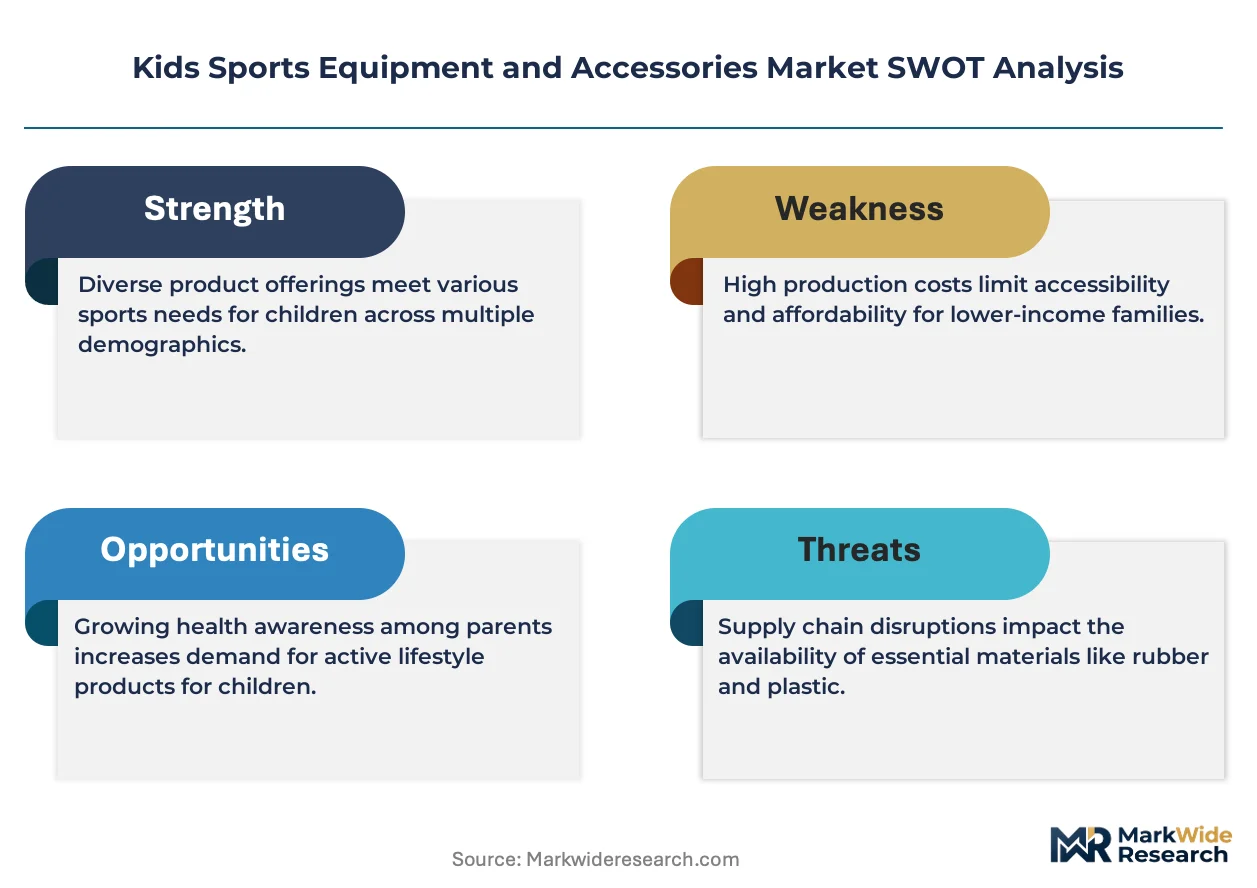
This market functions as a defensive-moat arena where regulatory entrenchment creates durable competitive positioning. State concussion mandates generate switching costs that cement incumbent relationships with district procurement officers.
For Market Incumbents: Consolidate ASTM certification leadership through accelerated retooling investments that outpace competitor compliance timelines, while capturing backward integration into impact-absorbing polymer formulation to offset petrochemical price volatility. Defensive positioning requires deepening district procurement relationships before rival vendors achieve multi-state certification coverage. For New Entrants and Emerging Players: Anchor in adaptive equipment for inclusive athletics, where wheelchair basketball and seated volleyball gear remains underpenetrated by mass-market suppliers. Parasports segments offer penetrable white space with specialized fitting requirements that reward regional measurement expertise over scale economies. Direct-to-parent subscription models with size-exchange programs provide the most viable go-to-market angle for bypassing entrenched retail channels. For Investors and Strategic Acquirers: Capital is best deployed toward regional specialty suppliers with captive measurement services and ASTM-certified product lines serving dense suburban districts. Long-term viability rests on regulatory compliance depth rather than brand recognition, with acquisition premiums justified by district contract renewal rates. The signal to watch is ASTM International protocol expansion into additional activity categories beyond football and ice hockey.| Strategic Initiative | Industry Significance |
|---|---|
| Smart Mouthguard Integration | Converging sensor telemetry with dental protection captures concussion protocol spending from youth leagues managing liability exposure. |
| Direct-to-Parent Subscription Launch | Size-exchange programs for growing children bypass seasonal retail compression while capturing lifetime replacement value. |
| Adaptive Equipment Portfolio Expansion | Wheelchair basketball and seated volleyball gear addresses parasports segments with specialized fitting requirements and limited competition. |
| ASTM Certification Acceleration | Multi-directional impact testing compliance maintains eligibility for California, Texas, and New York school district procurement cycles. |
| Backward Integration into Polymer Formulation | In-house production of impact-absorbing materials insulates margin stability from petrochemical price volatility. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across the primary research phase, encompassing youth league administrators, district procurement officers, protective gear product managers, specialty retail fitting specialists, and ASTM International testing laboratory directors. Secondary validation drew from Consumer Product Safety Commission recall databases, ASTM International standard revision records, state-level concussion protocol legislation, and customs trade data for carbon-fiber composite imports. Bottom-up equipment shipment analysis triangulated against top-down parental spending survey data.
Across the analysis window, the forecasting framework modeled volume and value trajectories through segmentation dimensions spanning age bracket, activity type, certification tier, and distribution channel. CAGRs were derived from regression analysis against youth sports participation rates, school district budget cycles, and replacement frequency patterns for outgrown gear. Industry-specific inputs included ASTM protocol adoption timelines and petrochemical price correlation coefficients for molded protective equipment.
Decision-makers should treat outputs as directional under assumptions of steady state concussion mandate enforcement and stable petrochemical input costs; material deviation in regulatory stringency or crude oil derivative pricing would warrant model refresh. Recalibration cycles align with material shifts in ASTM International testing protocols and state-level school sport safety legislation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Balance Bike Market
Sports Equipment
Ankle Roll Guard Market
Sports Equipment
Parallel Bars Market
Sports Equipment
Global Golf Accessories Market
Sports Equipment
Surfing Boards Market
Sports Equipment
Rally Sport Riding Gear Market
Sports Equipment
Golf Bags Market
Sports Equipment
Europe Running Gear Market
Sports Equipment
Carbon Fiber Badminton Racket Market
Sports Equipment
Europe Artificial Grass Market
Sports Equipment
Cricket Equipment Market
Sports Equipment
Pickleball Pitching Machine Market
Sports Equipment
Baseball Sliding Mitts Market
Sports Equipment
Sports Flooring Market
Sports Equipment
Baseball Equipment Market
Sports Equipment
Starting Blocks Market