
 UK Horse Riding Equipment Market | 2026-2036
UK Horse Riding Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
UK Horse Riding Equipment Market Insights
The UK's Animal Welfare (Sentience) Act is shifting how manufacturers source materials, pushing suppliers toward traceable leather and certified synthetic alternatives. Charles Owen leverages its British manufacturing heritage to sustain premium helmet production with domestic safety certification. Ariat International anchors its position through specialized riding boot lines engineered for competitive disciplines. Shires Equestrian competes across mid-market saddlery with broad distribution through UK tack shops and digital channels.
Horse riding equipment encompasses protective headgear, saddlery, footwear, and apparel designed to ASTM F1163 or PAS 015 safety standards, with leather and synthetic construction methods determining weight, breathability, and durability for rider protection and equine control. Helmets lead product category value due to mandatory replacement cycles and safety certification requirements, while synthetic material formulations represent the fastest-growing segment as riders seek weather-resistant, ethically sourced alternatives. Dressage applications command premium pricing through precision-engineered equipment specifications, whereas trail riding sustains volume demand among recreational participants across Britain's bridleway network.
The British Standards Institution governs PAS 015 helmet certification, while the Health and Safety Executive mandates workplace protective equipment standards for commercial riding establishments, and Trading Standards enforces consumer product safety regulations across retail channels. These frameworks elevate compliance costs for importers but simultaneously protect domestic manufacturers who already embed certification into production workflows. Stakeholders must monitor evolving sentience legislation and potential carbon border adjustments that could reshape material sourcing economics for leather-dependent product lines.
Market Dynamics
The UK's Animal Welfare (Sentience) Act is compressing material sourcing timelines for leather alternatives, forcing manufacturers to requalify supply chains while amateur riders at British Riding Schools accelerate protective headgear replacement cycles.
Growth Catalysts
- Sentience Act compliance:The Animal Welfare (Sentience) Act mandates traceable leather sourcing, pushing manufacturers toward certified synthetic alternatives that command premium positioning among ethically conscious riders.
- Amateur rider expansion:British Riding Schools report rising enrollment from recreational participants, expanding the addressable market for entry-level protective equipment and starter saddlery kits.
- PAS 015 certification:Mandatory helmet replacement cycles tied to British Standards Institution safety protocols ensure recurring revenue streams for certified headgear producers.
Market Restraints
- Leather price volatility:Input costs for full-grain hides fluctuate with livestock supply conditions, squeezing margin structures for traditional saddlery manufacturers dependent on premium leather construction.
- Import concentration:Synthetic textile feedstocks concentrate among Asian chemical producers, exposing UK equipment makers to shipping cost spikes and currency translation effects.
- Biodegradability trade-offs:Petroleum-derived synthetic alternatives face technical limitations in achieving comparable breathability and weight-to-strength ratios against natural leather.
Strategic Opportunities
- Scotland's equestrian corridor:Underpenetrated demand exists among Highland trail riding operators for weather-resistant synthetic tack designed for wet climate conditions.
- Carbon border readiness:Anticipated UK carbon border adjustments create first-mover advantage for domestic manufacturers with embedded low-carbon synthetic production workflows.
- Direct-to-consumer channels:Digital-native riders in England's Home Counties are bypassing traditional tack shops, opening margin expansion for brands investing in proprietary e-commerce infrastructure.
Industry Challenges
- PAS 015 retesting cycles:Certification renewal timelines compress product development schedules, requiring sustained R&D expenditure to maintain safety standard compliance.
- Synthetic material integration:Legacy stitching techniques require reconfiguration for bonded synthetic constructions, demanding capital retooling at domestic manufacturing facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Horse Riding Equipment Market |
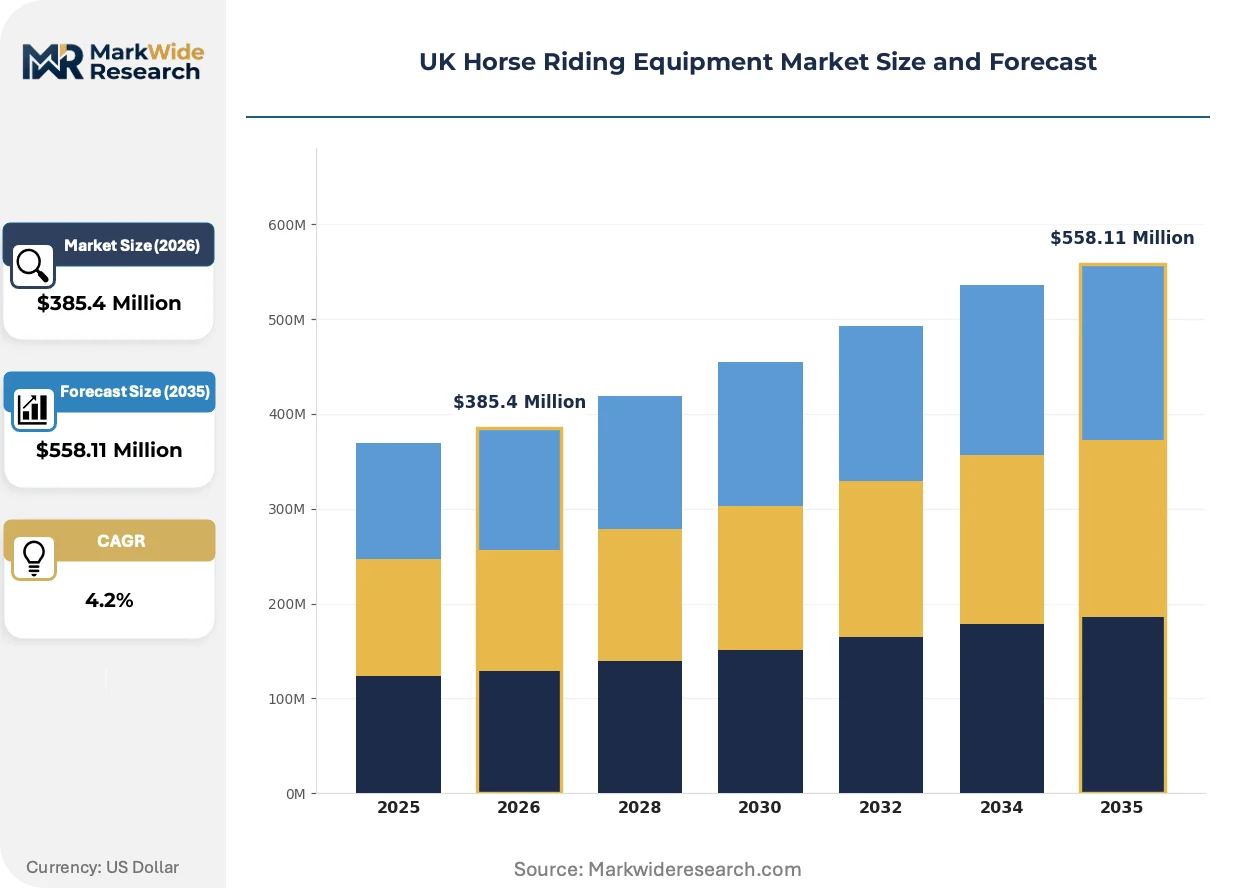
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $558.11 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Saddles, Bridles, Stirrups, Riding Boots, Helmets, Riding Gloves Material: Leather, Synthetic, Neoprene, Metal, Rubber, Fabric Application: Dressage, Show Jumping, Eventing, Trail Riding, Polo, Pony Riding End User: Equestrian Clubs, Riding Schools, Private Riders, Professional Jockeys, Trainers, Equipment Retailers |
| Companies Covered | Charles Owen, Ariat International, Harry Hall, Shires Equestrian, LeMieux, LuxeEquine, Dover Saddlery, Decathlon, Samshield, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Horse Riding Equipment Market Trends and Innovations
Material science advances and regulatory pressure are converging to reshape competitive positioning across protective equipment and saddlery categories, with sustainability credentials becoming a primary purchase filter.
MIPS (Multi-directional Impact Protection System) technology is consolidating into mid-tier helmet designs previously limited to premium competitive lines. Amateur riders at British Riding Schools are adopting MIPS-equipped headgear at accelerated rates following safety education campaigns. This diffusion pattern is consolidating market share among suppliers capable of integrating rotational impact protection without sacrificing aesthetic customization options.
The Animal Welfare (Sentience) Act is tightening material provenance requirements for leather alternatives used in saddle construction. Manufacturers must now document supply chain custody from raw material to finished product, elevating compliance costs for importers. Dressage equipment producers are responding fastest, reformulating synthetic flaps and seats to meet traceability standards while maintaining grip characteristics.
Recreational riders are fragmenting their purchase journeys across digital research and physical fitting experiences. Traditional tack shops in England's Home Counties are losing initial discovery to Instagram and TikTok content, then recovering transaction value through mandatory helmet fitting services. This hybrid pattern is most visible among parents purchasing first equipment for children enrolled at British Riding Schools.
UK Horse Riding Equipment Market Segmentation
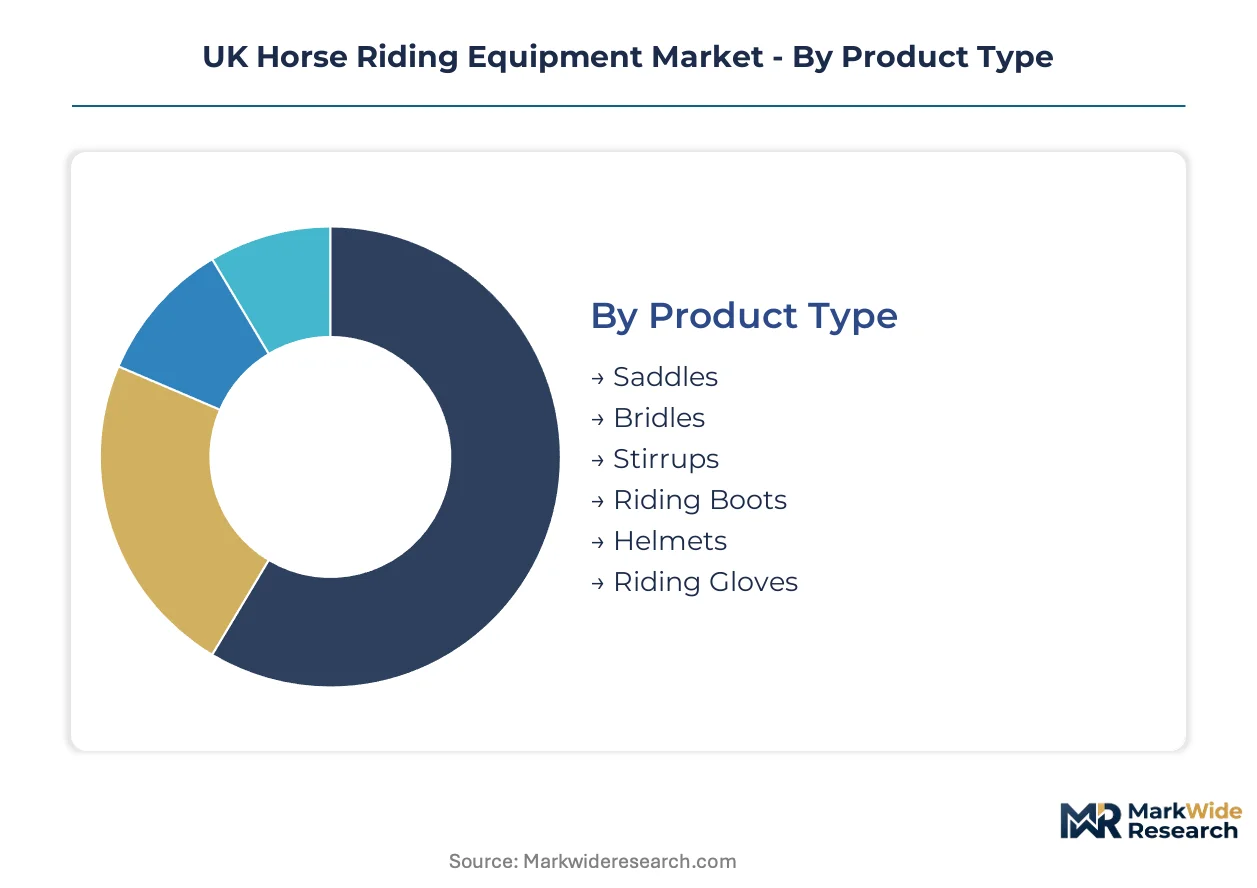
Segmentation in UK horse riding equipment reveals how safety mandates, material provenance rules, and discipline-specific performance requirements fragment purchasing authority across distinct buyer profiles. Manufacturers must calibrate certification depth, sourcing transparency, and price positioning differently for each slice.
Product Type:
Supply concentration clusters around protective headgear and precision saddlery, where British Standards Institution certification creates captive demand for domestic producers with embedded testing workflows.
- Helmets:PAS 015 certification mandates rotational impact protection and mandatory replacement cycles every 3-5 years. Demand concentrates among amateur riders at British Riding Schools in England's Home Counties, where safety education campaigns accelerate MIPS technology adoption.
- Saddles:Tree and panel construction requires leather or synthetic flaps meeting Animal Welfare (Sentience) Act traceability standards. Dressage practitioners in London's equestrian corridor drive premium positioning for custom-fitted English saddles with adjustable gullet systems.
- Bridles:Reins and headstall assemblies combining leather cheeks with synthetic grip materials.
- Stirrups:Safety release mechanisms and composite construction for weight reduction.
- Riding Boots:Tall leather or synthetic designs with reinforced toe caps for yard work and competition.
- Riding Gloves:Reinforced palm patches and breathable backs for rein control in variable weather.
Today's leader: Helmets. Tomorrow's challenger: Synthetic-material saddles.
Material:
Cost tier stratification separates heritage leather construction from petroleum-derived synthetics, with mid-market buyers arbitrating breathability against weather resistance and ethical sourcing credentials.
- Synthetic:Polyurethane and microfiber formulations achieving leather-like grip without livestock dependency. Highland trail riding operators in Scotland source weather-resistant synthetic tack for wet climate durability.
- Leather:Full-grain hides requiring documented supply chain custody under Animal Welfare (Sentience) Act rules. Competitive riders in England's Home Counties sustain demand for traditional bridle leather with hand-stitched finishing.
- Neoprene:Synthetic rubber padding for girth sleeves and bit guards.
- Metal:Stainless steel and aluminum alloys for stirrup irons and bit mouthpieces.
- Rubber:Molded compounds for grip surfaces and weatherproofing layers.
- Fabric:Technical textiles for apparel linings and lightweight equipment covers.
Synthetics are gaining share fastest among entry-level purchasers; leather retains pricing power with competitive disciplines.
Application:
Volume concentration sits with recreational participation, while margin concentration follows precision-engineered competitive equipment with discipline-specific certification requirements.
- Trail Riding:Recreational riders across Britain's bridleway network sustain volume demand for durable, low-maintenance equipment. Scottish Highland operators prioritize synthetic tack with corrosion-resistant hardware for exposed conditions.
- Dressage:Precision-engineered saddles and bridles with exacting flap positioning and ergonomic panel design. Riders in England's Home Counties command premium pricing for equipment meeting FEI technical specifications.
- Show Jumping:Lightweight close-contact saddles with forward-cut flaps.
- Eventing:Versatile equipment transitioning across dressage, cross-country, and show jumping phases.
- Polo:Reinforced knee rolls and shorter stirrup leathers for mallet swing clearance.
- Pony Riding:Scaled-down equipment for younger riders at British Riding Schools.
Trail riding dominates unit volume; dressage commands revenue per transaction.
End User:
Customer type determines procurement channel and compliance burden, with institutional buyers facing Health and Safety Executive mandates that individual private riders bypass.
- Riding Schools:Commercial establishments subject to Health and Safety Executive workplace protective equipment standards. British Riding Schools in England's Home Counties centralize helmet procurement through PAS 015 certified suppliers with bulk replacement programs.
- Private Riders:Individual enthusiasts fragmenting discovery across Instagram content and physical tack shop fitting services. Parents purchasing first equipment for children drive hybrid research-to-purchase journeys.
- Equestrian Clubs:Member-based organizations with group purchasing leverage.
- Professional Jockeys:Weight-restricted equipment with competition-specific modifications.
- Trainers:Instruction professionals advising client equipment selection.
- Equipment Retailers:Tack shops and digital channels holding inventory risk and fitting expertise.
Riding Schools anchor institutional demand; Private Riders are fragmenting fastest toward direct-to-consumer channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Professional riding instructors and yard managers cluster along England's Home Counties corridor, anchoring procurement demand for certified protective equipment and saddlery.
England's Home Counties
Amateur riders at British Riding Schools drive helmet replacement cycles and starter kit purchases. Trading Standards enforces consumer product safety regulations across retail channels, elevating compliance costs for imported goods. London's equestrian corridor concentrates premium dressage equipment demand among competitive riders seeking FEI-specification saddles.
Scotland
Highland trail riding operators generate underpenetrated demand for weather-resistant synthetic tack. The Health and Safety Executive mandates workplace protective equipment standards for commercial riding establishments, forcing procurement standardization. Edinburgh and Glasgow peripheries host emerging equestrian centers adopting corrosion-resistant hardware for wet climate durability.
Wales
Pony riding clubs and rural trekking businesses sustain volume demand for entry-level equipment. The Animal Welfare (Sentience) Act shapes material sourcing rules, pushing suppliers toward traceable leather alternatives. Brecon Beacons and Snowdonia regions concentrate recreational participation requiring low-maintenance synthetic construction.
Midlands
Manufacturing heritage supports domestic helmet production with embedded British Standards Institution certification workflows. PAS 015 helmet standards govern safety protocols, protecting domestic producers with established testing infrastructure. Warwickshire and Leicestershire host traditional saddlery workshops transitioning to bonded synthetic constructions.
UK Horse Riding Equipment Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across tiered positioning strata, with domestic certification workflows favoring vertically integrated British manufacturers over import-reliant distributors. The vendor base concentrates around heritage brands with embedded safety testing capabilities and digital-native entrants exploiting direct-to-consumer channel expansion. Two strategic archetypes dominate: PAS 015-certified domestic producers leveraging regulatory compliance as a barrier, and asset-light specialists outsourcing manufacturing while controlling brand and distribution. Competitive moves center on proprietary e-commerce infrastructure investment and synthetic material supply chain requalification under sentience legislation.
Within the heritage-certified tier, Charles Owen exemplifies domestic manufacturing anchoring through embedded British Standards Institution workflows, while Ariat International occupies a position as a transatlantic specialist in discipline-specific footwear. Shires Equestrian represents mid-market saddlery breadth across traditional tack shop and digital channels. These three players illustrate how certification depth, geographic origin, and channel strategy stratify competitive positioning.
| Leading Market Players |
|---|
| Charles Owen |
| Ariat International |
| Harry Hall |
| Shires Equestrian |
| LeMieux |
| LuxeEquine |
| Dover Saddlery |
| Decathlon |
| Samshield |
| Others |
Pricing and Supply Chain Analysis
Amateur riders at British Riding Schools demanding certified MIPS-equipped helmets are compressing procurement timelines for PAS 015-compliant suppliers, forcing manufacturers to absorb retesting costs or surrender margin to maintain shelf position against synthetic-alternative competitors.
Pricing Analysis
Bundled helmet-fitting services versus unbundled equipment-only transactions stratify pricing power across England's Home Counties. Three-tier pricing structure across premium, standard, and economy levels separates Charles Owen's domestic-certified lines from mid-market Shires Equestrian distribution and entry-level Decathlon imports. Price differentiation hinges on British Standards Institution certification depth and after-sales replacement programs. Pricing pressure stems from Asian synthetic feedstock cost volatility squeezing margin structures for petroleum-derived alternatives. Parents purchasing first equipment for children enrolled at British Riding Schools exhibit highest price sensitivity, while competitive dressage riders in London's equestrian corridor accept premium positioning for FEI-specification saddles.
Supply Chain Analysis
Certification gating through PAS 015 retesting cycles restricts viable supplier pools to domestic manufacturers with embedded British Standards Institution workflows and select Italian, German, and French heritage producers maintaining EU-equivalent safety protocols. Raw material dependencies center on full-grain hides from traceable UK and Irish livestock operations, petroleum-derived polyurethane formulations from Belgian and Dutch chemical producers, and stainless steel hardware from German metallurgical specialists. Single-source vulnerability concentrates in Asian synthetic textile feedstocks exposed to shipping cost spikes and currency translation effects. Distribution runs through traditional tack shops in England's Home Counties recovering transaction value through mandatory fitting services, supplemented by direct-to-consumer channels capturing digital-native rider discovery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
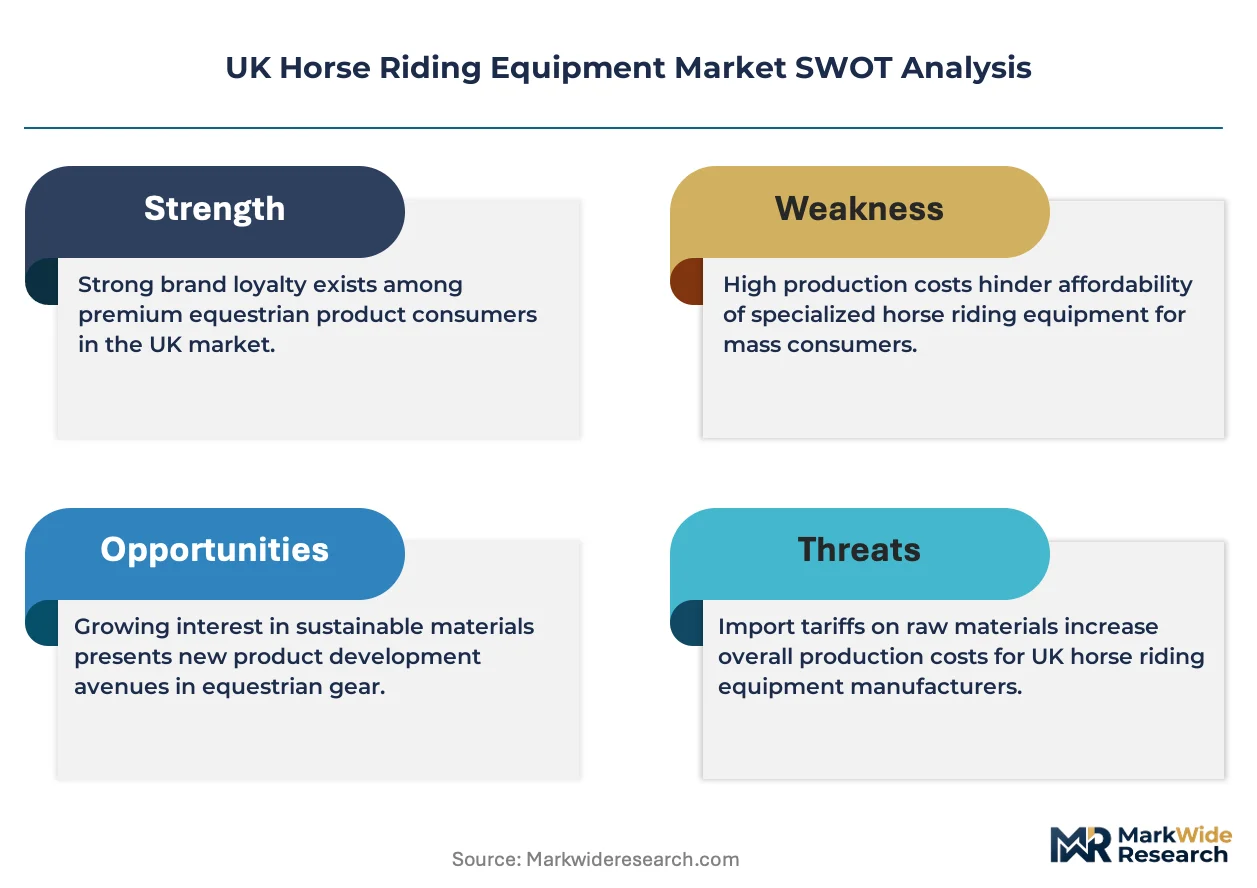
This market offers margin-expansion pathways through carbon border readiness and synthetic material supply chain requalification, as anticipated UK carbon border adjustments reward domestic manufacturers with embedded low-carbon production workflows.
For Market Incumbents: Anticipate retesting cycle compression by embedding PAS 015 certification workflows deeper into domestic manufacturing facilities, insulating against import compliance cost escalation. Prioritize backward integration into traceable leather sourcing networks and certified synthetic feedstock partnerships to defend margin position against sentience legislation compliance cost spikes. Channel control through proprietary e-commerce infrastructure captures digital-native riders fragmenting discovery away from traditional tack shops. For New Entrants and Emerging Players: Direct-to-consumer routes through Instagram and TikTok content discovery bypass established tack shop gatekeepers, opening white-space penetration among parents purchasing first equipment for children. Target Scotland's underpenetrated Highland trail riding operators with weather-resistant synthetic tack designed for wet climate durability, leveraging corrosion-resistant hardware specifications absent from incumbent catalog breadth. White-space capture in Wales pony trekking businesses offers volume scale through entry-level equipment kits. For Investors and Strategic Acquirers: Asymmetric upside sits with domestic manufacturers possessing embedded British Standards Institution certification infrastructure and synthetic material requalification capabilities under Animal Welfare (Sentience) Act timelines. Long-term viability favors vertically integrated producers with captive supply of traceable leather alternatives and low-carbon synthetic production workflows. Watch for carbon border adjustment implementation announcements as inflection indicator for domestic margin expansion versus import cost disadvantage.| Strategic Initiative | Industry Significance |
|---|---|
| Synthetic Material Supply Chain Requalification | Animal Welfare (Sentience) Act compliance creates captive demand for traceable leather alternatives. |
| Direct-to-Consumer Channel Buildout | Digital-native riders in England's Home Counties fragment discovery across Instagram and TikTok content. |
| PAS 015 Certification Infrastructure Investment | British Standards Institution testing workflows protect domestic producers against import compliance cost escalation. |
| Carbon Border Adjustment Readiness | Anticipated UK carbon border adjustments reward embedded low-carbon synthetic production workflows. |
| Highland Trail Riding Market Development | Scotland's underpenetrated operators generate demand for weather-resistant synthetic tack specifications. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary fieldwork with riding school procurement managers, domestic helmet manufacturers, tack shop operators, and British Riding School network administrators alongside secondary validation. Secondary sources encompassed British Standards Institution certification records, Health and Safety Executive workplace equipment enforcement data, Trading Standards consumer safety filings, and customs import records for synthetic textile feedstocks. Bottom-up equipment shipment tracking and top-down equestrian participation rate modeling were triangulated against PAS 015 replacement cycle estimates.
Comparable-period anchoring calibrated the projection horizon against historical helmet replacement cycle data and synthetic material adoption curves across preceding regulatory transitions. Segmentation dimensions modeled encompassed product type, material formulation, application discipline, and end-user procurement channel alongside geographic concentration across England's Home Counties, Scotland, Wales, and Midlands manufacturing clusters. CAGRs were derived from equipment unit velocity projections and average transaction value movements across certification tiers. Industry-specific forecast inputs incorporated Animal Welfare (Sentience) Act implementation timelines and anticipated carbon border adjustment mechanics.
Sentience legislation enforcement variance, carbon border adjustment timing, and synthetic material performance breakthroughs are the dominant revision risks to modeled outcomes. Forecasts reflect assumptions regarding PAS 015 certification continuity and amateur rider enrollment stability at British Riding Schools. A model refresh is warranted upon material change in carbon border adjustment implementation scope or synthetic material breathability parity achievements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Global Sporting Goods Market
Sports Equipment
Table Tennis Equipment Market
Sports Equipment
Bicycle Drivetrain Cassette Market
Sports Equipment
Parallel Bars Market
Sports Equipment
Winter Sporting Goods Market
Sports Equipment
Ergonomic Strap Systems Market
Sports Equipment
Sports Protection Equipment Market
Sports Equipment
Europe Running Gear Market
Sports Equipment
Boxing Gloves Market
Sports Equipment
Volleyball Shoes Market
Sports Equipment
Global Rock Climbing Equipment Market
Sports Equipment
Golf Bags Market
Sports Equipment
Slam Ball Market
Sports Equipment
Cleat Market
Sports Equipment
Running Gear Market
Sports Equipment
Asia-Pacific Bicycle Market