
 US Fencing Market | 2026-2036
US Fencing Market Size, Share, and Industry Trends Forecast 2026-2036
US Fencing Market Intelligence
Modular panel-and-post bundling is realigning residential buyer choice toward faster, specification-grade installations with fewer field decisions. Trex Company Inc. leverages composite chemistry expertise to anchor premium positioning in low-maintenance residential segments. CertainTeed Corporation sustains broad vinyl and aluminum portfolios across multiple distribution tiers. Ameristar Fence Products Incorporated specializes in ornamental steel systems for commercial and institutional perimeter security.
Fencing encompasses engineered barrier systems fabricated from wood, metal, vinyl, or composite materials, typically installed in modular sections spanning six to eight feet in height, designed to demarcate property boundaries, control access, or provide visual screening. Residential end users dominate volume consumption, though commercial and industrial segments concentrate margin pools in anti-climb and crash-rated specifications. Vinyl fences capture growing share in moisture-prone coastal counties, while chain link fences retain cost-driven agricultural and utility applications. DIY kits expand through home improvement stores, yet custom installations channel higher value through contractor networks.
ASTM International publishes structural performance standards for fence materials, while the International Code Council governs installation compliance through adopted building codes across US jurisdictions. The EPA regulates pressure-treating chemicals for wooden fence components, constraining traditional preservative formulations. Local zoning boards and homeowners associations increasingly mandate material and height restrictions, fragmenting product approval pathways. Stakeholders must monitor evolving state-level amendments to ICC codes and emerging municipal bans on specific chemistries or materials.
Market Dynamics
Modular panel-and-post bundling is compressing installation timelines and reducing field decision complexity for residential contractors across Texas, Florida, and California.
Growth Catalysts
- ICC Building Code Adoption:State-level amendments to International Code Council standards in hurricane zones are mandating higher wind-load ratings for perimeter systems, accelerating replacement cycles in coastal counties.
- Vinyl Chemistry Advances:Improved UV stabilizers and impact modifiers are extending product lifespans in moisture-prone regions, displacing traditional wood in subdivision developments.
- Retrofitting Concentration:Post-hurricane rebuilding in Florida and wildfire-hardening in California are converging to drive specification-grade fencing procurement through insurance-mandated upgrades.
Market Restraints
- PVC Resin Volatility:Feedstock cost fluctuations for vinyl fencing raw materials are compressing margins for extrusion-dependent manufacturers without backward integration into resin supply.
- Treated Wood Restrictions:EPA regulations on pressure-treating chemicals, particularly copper-based formulations, are constraining traditional preservative options and raising compliance costs for wooden fence producers.
- Steel Import Concentration:Ornamental metal fencing remains exposed to tariff-sensitive supply chains for galvanized steel tubing and aluminum extrusions.
Strategic Opportunities
- Smart Perimeter Integration:Convergence of composite fencing with embedded sensor conduits and low-voltage power routing is creating premium positioning for connected home security ecosystems.
- DIY Channel Expansion:Home improvement retailers are expanding modular kit assortments with pre-drilled posts and snap-together rails, capturing weekend-installer demand in suburban Texas markets.
- LEED-Compliant Materials:Green building certification preferences in California municipalities are creating specification advantages for recycled-content composite and FSC-certified wood alternatives.
Industry Challenges
- Installation Labor Scarcity:Skilled fence contractor capacity constraints in high-growth housing markets are extending project backlogs and forcing manufacturers to simplify field assembly requirements.
- Municipal Zoning Fragmentation:Homeowners association design guidelines and local height restrictions vary block-by-block in master-planned communities, complicating standardized product rollouts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Fencing Market |
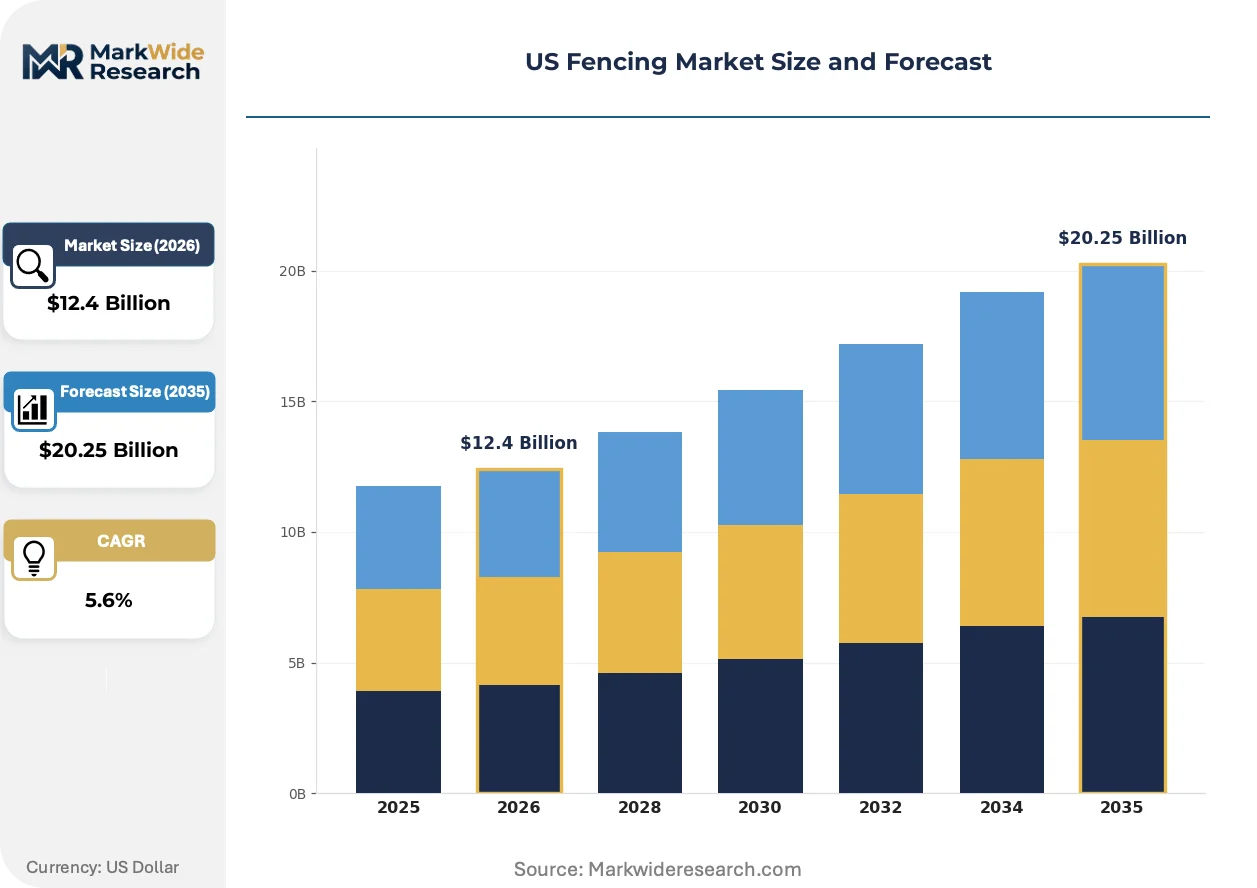
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $20.25 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wooden Fences, Vinyl Fences, Chain Link Fences, Aluminum Fences Installation Type: DIY Kits, Professional Installation, Instant Fencing Solutions, Custom Installations End User: Residential, Commercial, Industrial, Agricultural Distribution Channel: Online Retailers, Home Improvement Stores, Specialty Fencing Suppliers, Contractors |
| Companies Covered | CertainTeed Corporation, Gregory Industries, Allied Tube & Conduit, Ply Gem Holdings Inc., Long Fence Company Inc., Ameristar Fence Products Incorporated, Bekaert, Trex Company Inc., Associated Materials LLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Fencing Market Strategic Shifts & Innovations
Three forces are actively restructuring how fencing is specified, procured, and installed across residential and commercial segments.
Composite capping technology is modularizing residential fence manufacturing by enabling pre-finished, color-matched components that ship ready for assembly without on-site painting or staining. Subdivision developers in Florida and coastal California are specifying these systems to reduce punch-list items and warranty exposure. The shift is compressing value capture toward material suppliers with in-house compounding capabilities and away from local finishing contractors.
ASTM International wind-load testing protocols are tightening performance verification requirements for perimeter systems in designated storm corridors. Manufacturers must now submit full-scale structural testing data rather than engineering calculations alone to satisfy Florida Product Approval and Miami-Dade County protocols. The burden falls heaviest on ornamental steel and aluminum producers serving commercial security applications where failure carries liability exposure.
Buying patterns among residential developers are compressing supplier relationships toward turnkey specification-and-installation bundles. Single-source accountability is displacing traditional bid-package fragmentation where property owners separately sourced materials and labor. Texas master-planned communities are piloting this consolidated procurement model most aggressively, with national builders extending the approach to Florida and Arizona markets.
US Fencing Market Segmentation
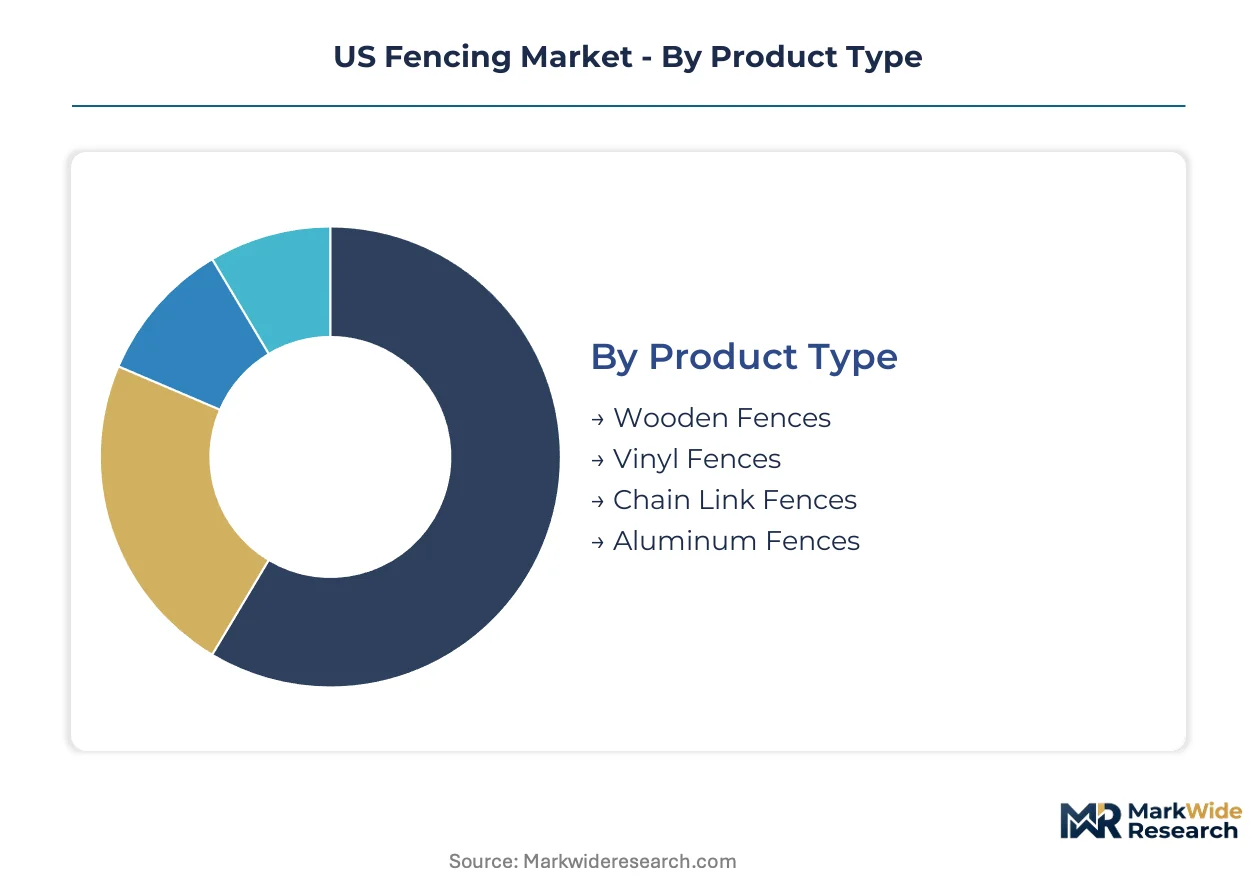
Segmentation in the US fencing market determines which ASTM and ICC certification pathways manufacturers must navigate. Product type dictates material-specific testing protocols, while installation and distribution choices shape compliance documentation requirements for wind-load and structural performance verification.
Product Type:
ASTM F964 governs vinyl extrusion performance, while ASTM F567 applies to chain link installation integrity. Miami-Dade County Product Approval and Florida Building Code compliance create tiered regulatory burdens across material categories.
- Vinyl Fences:Polyvinyl chloride extrusions with UV stabilizers and impact modifiers resist moisture degradation in coastal counties. Florida subdivision developers specify these systems for hurricane-zone retrofitting where ICC wind-load mandates apply. ASTM F964 certification requirements concentrate compliance investment among extrusion specialists with in-house compounding capabilities.
- Wooden Fences:Pressure-treated lumber and cedar pickets face EPA restrictions on copper-based preservatives. California wildfire-hardening codes and Texas residential construction volumes drive demand, though treated wood regulations raise compliance costs for traditional manufacturers.
- Chain Link Fences:Galvanized steel mesh systems retain cost positioning in agricultural and utility perimeter applications.
- Aluminum Fences:Powder-coated extrusions serve ornamental residential and commercial specifications with lower maintenance requirements than steel alternatives.
Vinyl sits at the top of the volume ranking, with aluminum climbing the fastest in commercial security specifications.
Installation Type:
Installation complexity determines contractor licensing requirements and permit pathways under local ICC code adoptions. DIY channels face fewer regulatory checkpoints than permanent foundation systems requiring engineering stamps.
- Professional Installation:Full-service contractors manage permit acquisition, post-hole excavation, and concrete footing compliance with local zoning height restrictions. Texas master-planned communities and Florida coastal counties concentrate demand where wind-load engineering documentation is mandatory.
- DIY Kits:Pre-drilled posts and snap-together rails reduce skill barriers for weekend installers. Home Depot and Lowe's distribution in suburban Texas markets expands access, though product liability exposure limits specification-grade component availability.
- Custom Installations:Site-fabricated systems accommodate irregular terrain and HOA design guidelines in fragmented municipal jurisdictions.
- Instant Fencing Solutions:Temporary panel systems serve construction sites and event perimeter needs without permanent foundation requirements.
Professional installation commands the highest revenue per project, with DIY kits expanding most quickly through retail channel penetration.
End User:
End-user category determines performance specification intensity and warranty exposure. Residential volume dominates unit consumption while commercial and industrial segments concentrate premium pricing for security-rated systems.
- Residential:Single-family subdivisions and homeowner association communities in Texas, Florida, and California drive material selection toward low-maintenance vinyl and composite systems. Insurance-mandated upgrades in hurricane and wildfire zones accelerate replacement cycles.
- Commercial:Office parks, retail centers, and institutional facilities require ornamental steel and aluminum with anti-climb specifications. ASTM wind-load testing and liability exposure favor established manufacturers with full-scale structural certification.
- Industrial:Manufacturing facilities and logistics yards prioritize chain link and welded wire for cost-effective perimeter security.
- Agricultural:Ranch and farm applications retain traditional wood post-and-rail and barbed wire systems for livestock containment.
Residential claims the largest unit volume, with commercial posting the steepest margin expansion trajectory.
Distribution Channel:
Channel structure determines specification influence and inventory carrying costs. Contractor-direct relationships capture turnkey project bundling while retail channels serve price-sensitive replacement demand.
- Contractors:Installation professionals source materials through wholesale distributors and direct manufacturer relationships. National builders in Texas consolidate procurement through single-source accountability models that compress bid-package fragmentation.
- Home Improvement Stores:Home Depot and Lowe's stock modular vinyl and wood fence panels for consumer self-installation. Suburban expansion in Sun Belt metros supports SKU proliferation in DIY-accessible configurations.
- Specialty Fencing Suppliers:Regional distributors serve commercial and industrial specification markets with engineering support and custom fabrication capabilities.
- Online Retailers:E-commerce platforms expand kit availability for remote markets, though freight costs and damage rates constrain bulky panel shipments.
Contractors maintain the highest value capture per transaction, with home improvement stores gaining share fastest in residential replacement demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fencing manufacturing in the United States traces its modern scale to post-war suburban expansion across the Sun Belt, where standardized vinyl extrusion and treated lumber preservation created regional supply bases serving rapid residential development.
Texas
Master-planned communities in Dallas-Fort Worth and Houston drive specification-grade vinyl and composite procurement through consolidated builder contracts. ICC wind-load amendments apply variably across coastal versus inland counties, creating tiered compliance requirements. The Permian Basin and South Texas ranchlands sustain demand for agricultural barbed wire and pipe fencing through oil-field service expansion.
Florida
Hurricane-zone retrofitting and post-storm rebuilding concentrate demand for Miami-Dade County Product Approved perimeter systems in Tampa, Orlando, and Southeast Florida corridors. Florida Building Code wind-load mandates exceed national ICC baselines, forcing manufacturers to submit full-scale ASTM structural testing data. Vinyl fencing captures subdivision share from pressure-treated wood in moisture-prone coastal counties.
California
Wildfire-hardening codes in Los Angeles, San Diego, and Bay Area counties drive insurance-mandated replacement cycles toward non-combustible materials. EPA restrictions on copper-based wood preservatives intersect with CAL FIRE defensible-space regulations to constrain traditional fencing options. LEED-compliant recycled-content composites gain specification preference in municipal procurement across Sacramento and Central Valley developments.
Arizona
Phoenix and Tucson metro expansion sustains demand for low-maintenance vinyl and ornamental aluminum in retirement community and second-home markets. Desert climate conditions accelerate UV degradation testing requirements beyond ASTM F964 baselines. Contractor-direct procurement models from Texas builders are extending into Scottsdale and Mesa master-planned developments.
Carolinas
Charlotte and Raleigh-Durham residential construction volumes rank among the fastest-growing East Coast markets for perimeter system installation. Hurricane exposure in coastal North Carolina triggers ICC code adoption patterns similar to Florida, though with less stringent Miami-Dade protocols. Regional distribution hubs in Greensboro and Greenville serve expanding contractor networks across the Piedmont corridor.
US Fencing Market Key Industry Players
Premium-margin players sit above commodity-margin players across material specialization and certification depth, with composite and ornamental steel specialists commanding pricing power over standardized vinyl extruders and chain-link fabricators. The vendor base clusters around three strategic archetypes: vertically integrated resin compounders capturing value through in-house formulation, regional installation contractors bundling specification and labor, and import-dependent metal specialists exposed to tariff volatility. Dominant competitive moves include backward integration into raw material supply and geographic expansion through distributor acquisition in high-growth Sun Belt metros.
Among composite chemistry specialists, Trex Company Inc. and CertainTeed Corporation occupy positions reflecting material science depth and broad distribution reach respectively. Ameristar Fence Products Incorporated anchors the ornamental steel tier serving commercial security specifications. These three entities exemplify how certification-intensive segments concentrate around players with captive testing capabilities and established Florida Product Approval portfolios.
| Leading Market Players |
|---|
| CertainTeed Corporation |
| Gregory Industries |
| Allied Tube & Conduit |
| Ply Gem Holdings Inc. |
| Long Fence Company Inc. |
| Ameristar Fence Products Incorporated |
| Bekaert |
| Trex Company Inc. |
| Associated Materials LLC |
| Others |
Cost & Logistics Intelligence
Certification-grade Miami-Dade wind-load approval separates premium perimeter systems from commodity alternatives, concentrating pricing power among extruders with captive testing facilities while compressing margins for import-dependent metal fabricators lacking Florida Product Approval portfolios. This bifurcation shapes supply chain configurations: specification-grade vinyl compounders source UV stabilizers from domestic resin producers to maintain batch consistency for ASTM F964 compliance, whereas ornamental steel specialists remain exposed to tariff-sensitive galvanized tubing from concentrated offshore mills.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs residential and commercial procurement, with Miami-Dade certification and ICC wind-load compliance commanding 15-25% premiums over baseline ASTM F964 products. Price differentiation rests on certification depth and regional delivery logistics, Texas master-planned community bundling softening contractor pricing through volume consolidation. Cost compression in economy vinyl extrusions intensifies because PVC resin feedstock volatility squeezes non-integrated manufacturers. Agricultural chain-link buyers exhibit highest price sensitivity; commercial security purchasers prioritize liability-rated structural documentation over unit cost.
Supply Chain Analysis
Domestic-content preferences in Florida and California municipal procurement are reshaping sourcing toward US-based resin compounding and aluminum extrusion facilities, displacing previous reliance on Asian PVC additive suppliers. Raw material dependencies center on Gulf Coast petrochemical corridors for vinyl chloride monomer, domestic steel mills for galvanized chain-link mesh, and specialized pigment houses for UV-stable colorants. Tariff exposure on ornamental steel tubing from Mexico and Canada constitutes the primary structural risk. Distribution runs through contractor-direct wholesale networks for specification-grade projects, with Home Depot and Lowe's capturing suburban DIY replacement demand through pre-bundled kit inventory.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US fencing market compounds steadily as hurricane-zone retrofitting and wildfire-hardening codes perpetuate replacement cycles regardless of housing starts volatility. Residential subdivision consolidation and commercial security specification intensity create durable margin pools for positioned players.
For Market Incumbents: Deepen captive resin compounding capabilities to insulate margin structures from PVC feedstock volatility while accelerating Florida Product Approval portfolio expansion ahead of ICC code amendments in emerging coastal counties. Reinforce contractor-direct relationships in Texas master-planned communities where national builders are consolidating procurement toward single-source accountability models. For New Entrants and Emerging Players: E-commerce-enabled DIY kit distribution offers the most penetrable entry vector, particularly in suburban Dallas-Fort Worth and Phoenix markets where weekend installer demand outpaces retail SKU availability. Target agricultural barbed wire and pipe fencing segments in Permian Basin oil-field service corridors, where specification intensity remains low and regional distributor relationships are undertapped. For Investors and Strategic Acquirers: Consolidation pressure builds where fragmented regional installers lack Miami-Dade certification capabilities required for Florida coastal commercial projects. Long-term viability favors vertically integrated compounders with in-house ASTM testing infrastructure over import-dependent ornamental metal fabricators. Monitor ICC state-level amendment calendars as inflection indicators for specification-grade demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captive UV stabilizer formulation secures ASTM F964 batch consistency for Florida coastal specifications. |
| Florida Product Approval Portfolio Expansion | Miami-Dae County certification unlocks premium pricing in hurricane-zone commercial security segments. |
| DIY Channel Kit Proliferation | Pre-drilled post configurations capture weekend installer demand through Home Depot and Lowe's expansion. |
| Smart Perimeter Sensor Integration | Embedded conduit routing aligns composite fencing with connected home security ecosystem procurement. |
| Regional Installer Acquisition | Consolidated specification-and-installation bundling displaces fragmented bid-package sourcing in Texas. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with vinyl extrusion plant managers, fencing contractor procurement leads, national builder specification directors, and municipal zoning officials with secondary validation against ASTM International standard publications, ICC building code amendment databases, EPA treated wood regulatory filings, and residential construction permit data from Texas, Florida, and California jurisdictions. Bottom-up project pipeline analysis and top-down material consumption estimates were triangulated to anchor volume assumptions.
Comparable-period anchoring tied projection assumptions to historical replacement cycle patterns observed across prior hurricane seasons and wildfire events, with segmentation modeling across material type, installation complexity, end-user category, and distribution channel. CAGRs were derived from installed base depreciation curves and new construction correlation analysis, incorporating PVC resin price elasticity coefficients and contractor labor availability indices as industry-specific forecast inputs.
The model assumes a particular technology adoption path for composite capping and smart perimeter integration; alternative pathways for embedded sensor standardization would alter the outlook. Forecasts reflect documented assumptions regarding ICC code amendment timing and housing start trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Ice Hockey Equipment Market
Sports Equipment
Archery Equipment Market
Sports Equipment
Triathlon Bikes Market
Sports Equipment
Hunting Equipment and Accessories Market
Sports Equipment
Figure Skating Equipment Market
Sports Equipment
Smart Swim Goggles Market
Sports Equipment
Cleat Market
Sports Equipment
Fishing Rods Market
Sports Equipment
Clay Pigeon Thrower Market
Sports Equipment
Backboard Market
Sports Equipment
Fresh Water Rowing Boats Market
Sports Equipment
Golf Ball Market
Sports Equipment
Sports Devices Market
Sports Equipment
Global Bicycle Market
Sports Equipment
Crampon Market
Sports Equipment
Soccer Gear Market