
 Fencing Equipment Market | 2026-2036
Fencing Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Fencing Equipment Market Intelligence
The push for sustainable building materials under frameworks like the EU's Corporate Sustainability Reporting Directive (CSRD) is consolidating demand toward recyclable options like steel and aluminum. This shift affects procurement strategies for large commercial and institutional projects. Within this context, Leon Paul focuses on specialized product lines for niche applications. Allstar sustains its position through brand recognition in established markets, while PBT Fencing competes on manufacturing scale for institutional buyers.
Fencing equipment encompasses manufactured barrier systems designed for perimeter security, privacy, and property demarcation. These systems are constructed from materials like chain link, vinyl, or wood and are engineered to meet specific wind load, impact resistance, and longevity standards. The residential application segment remains the largest by volume, though commercial projects often yield higher margins per installation. In terms of product type, vinyl and aluminum are gaining share from traditional wood due to lower long-term maintenance requirements.
Product quality and safety are governed by standards like ISO 9001 for manufacturing processes and local building codes in jurisdictions across the United States. In Europe, CE marking requirements dictate material safety and structural performance for products sold within the European Economic Area. Vendors must now decide whether to invest in smart-fencing capabilities, such as integrated sensors, or focus on material science innovations to maintain a competitive edge.
Market Dynamics
The fencing equipment market is defined by the convergence of material science advancements and digital technology integration. This dynamic is creating a division between low-cost, traditional barrier systems and high-value, intelligent perimeter solutions with integrated sensing and monitoring capabilities.
Growth Catalysts
- Agricultural Expansion:Large-scale livestock farming operations, particularly in agricultural economies like Brazil and Australia, require extensive and durable fencing systems for animal containment and pasture management, driving volume demand for steel and wire products.
- Sustainability Mandates:Regulatory frameworks like the EU's Corporate Sustainability Reporting Directive (CSRD) push commercial developers toward materials with documented lifecycle benefits, increasing specifications for recyclable aluminum and steel fencing over less sustainable alternatives.
- Security Modernization:The integration of sensor-based technologies into fencing systems for real-time perimeter breach detection is a significant growth driver for commercial, industrial, and critical infrastructure applications.
Market Restraints
- Input Cost Volatility:Fluctuations in the global prices of raw materials, especially steel and aluminum, create pricing instability and compress margins for manufacturers, making project bidding and long-term financial planning difficult.
- Substitution from Low-End Alternatives:In residential and light agricultural applications, the market faces competition from traditional, lower-cost materials like wood and basic wire, which can limit the penetration of higher-value vinyl or composite systems.
- Fragmented Building Codes:The lack of uniform building codes for wind load and safety standards across different municipalities, particularly in the United States, complicates product design and inventory management for national-scale suppliers.
Strategic Opportunities
- Smart Infrastructure Projects:The development of smart cities and the protection of critical infrastructure like data centers and energy grids create an opportunity for advanced fencing systems with integrated surveillance and access control.
- Aquaculture Containment:The expanding aquaculture industry requires specialized, corrosion-resistant fencing and netting systems for fish farming in both coastal and inland locations, representing a niche but high-value application.
- Technology Convergence with Drones:Combining automated drone patrols with sensor-equipped smart fences offers a new service model for high-security perimeter monitoring, moving beyond static hardware sales to recurring revenue contracts.
Industry Challenges
- Installation Skill Gap:The shift toward smart fencing systems with integrated electronics and software creates a shortage of installers with the necessary technical skills for proper setup, calibration, and maintenance.
- Data Protocol Standardization:A lack of industry-wide standards for sensor data formats and communication protocols hinders interoperability between fencing hardware and third-party security management platforms.
- Certification and Compliance Burden:Meeting diverse international and regional standards, such as CE marking in Europe and specific security ratings in North America, requires significant investment in testing and documentation, creating barriers for smaller vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fencing Equipment Market |
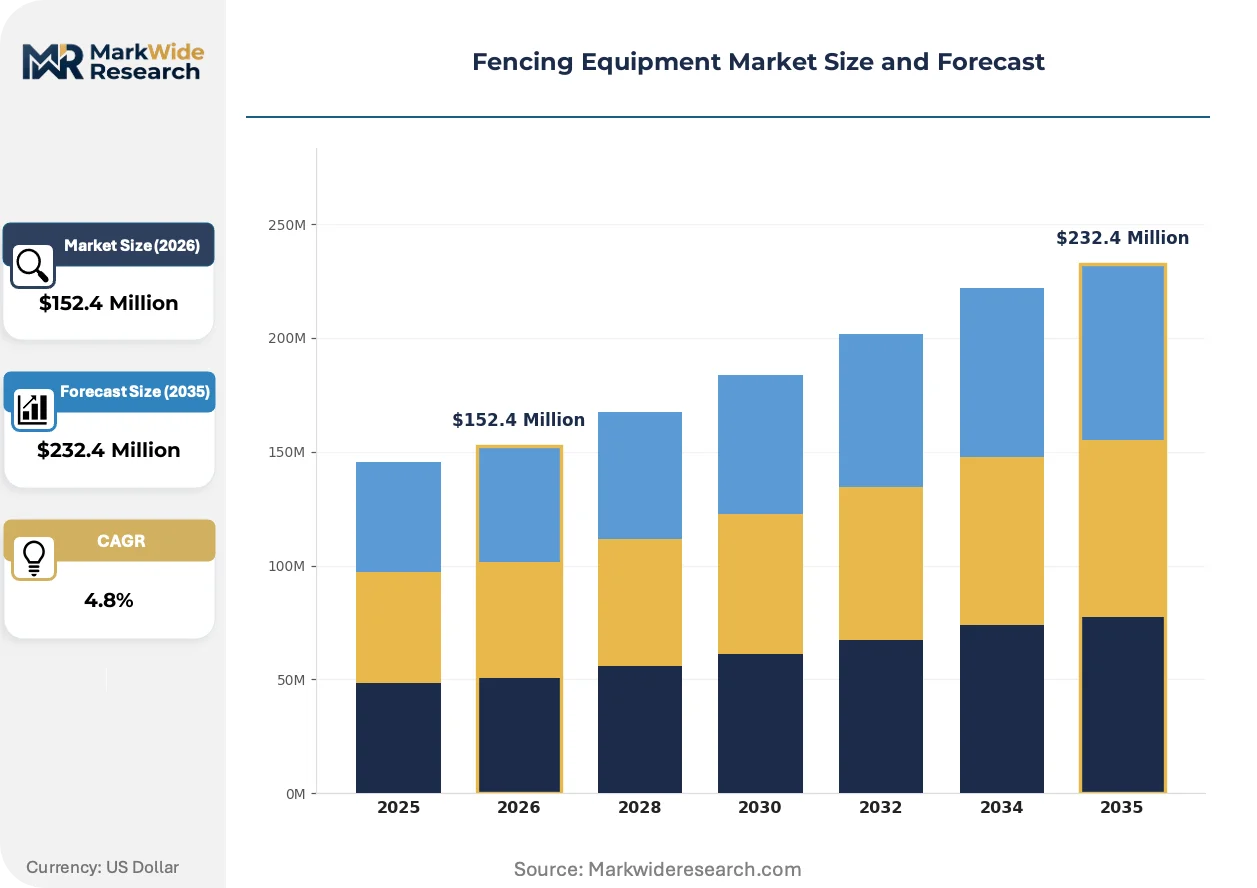
| Market Size in 2026 | $152.4 Million |
| Market Size in 2035 | $232.4 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chain Link, Vinyl, Wood, Steel, Aluminum, Bamboo Technology: Electric, Solar-Powered, Manual, Automated, Sensor-Based Application: Residential, Commercial, Agricultural, Recreational, Institutional End User: Property Owners, Facility Managers, Farmers, Sports Complexes, Schools |
| Companies Covered | Leon Paul, Allstar, PBT Fencing, Absolute Fencing Gear, American Fencers Supply Co., Blue Gauntlet, Alliance Fencing Equipment, Prieur Sports, Negrini, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fencing Equipment Market Strategic Shifts & Innovations
The market's evolution is centered on the transformation of fencing from a passive physical barrier into an active component of a site's security and operational infrastructure. This shift is driven by advancements in material composition, embedded electronics, and new manufacturing techniques.
Prefabricated, panelized fencing systems incorporate integrated conduits for wiring and sensor attachments. Commercial and large-scale institutional developers are adopting these systems to accelerate project timelines and reduce on-site labor dependencies. This approach is modularizing fence construction, simplifying the installation of security technologies like cameras and access controls while allowing for easier future upgrades.
New regulations in the United States focused on critical infrastructure protection are mandating higher performance standards for perimeter security. These directives compel operators of energy, transportation, and data infrastructure to invest in fencing that meets certified anti-climb, anti-cut, and impact-resistance criteria. The industrial and utility sectors are most affected, leading a wave of upgrades from standard chain-link to high-security engineered systems.
A notable behavioral change is the move away from specifying materials on initial price toward a total cost of ownership (TCO) analysis. This model challenges the position of traditional wood fencing by accounting for its long-term maintenance, repair, and replacement costs. The shift is most visible in the North American residential and municipal sectors, where buyers now favor lower-maintenance vinyl and aluminum products for their superior lifecycle value.
Fencing Equipment Market Segmentation
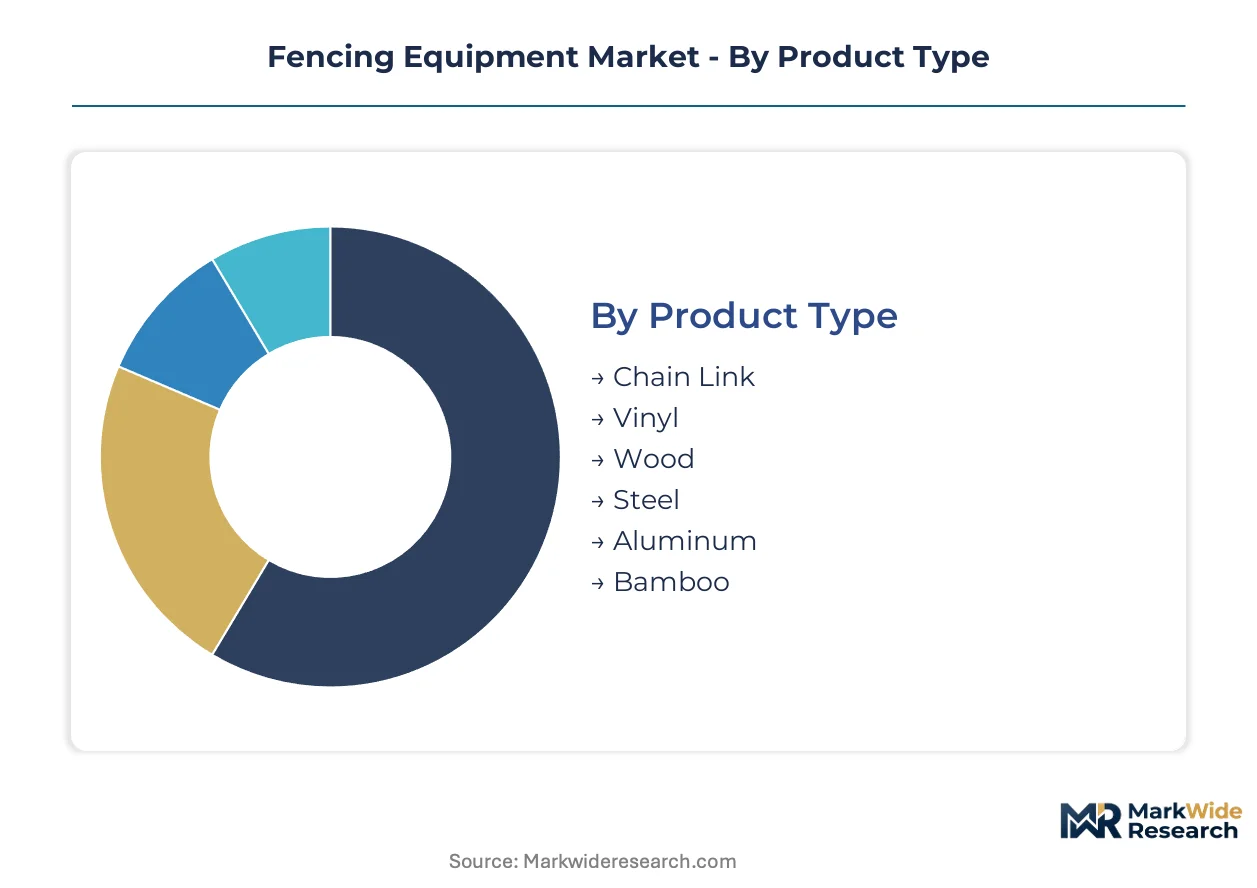
The fencing equipment market exhibits diverse requirements across various end-use sectors, necessitating a granular segmentation to understand specific demand patterns. This detailed breakdown helps manufacturers align product development with distinct application needs and procurement priorities. Analysis of these segments reveals the underlying drivers shaping product innovation and material preferences.
Product Type:
The product type category highlights the spectrum from highly standardized commodity barriers to specialized material solutions. Manufacturers balance material cost with performance specifications for diverse applications.
- Vinyl:These systems consist of PVC or composite formulations, offering superior weather resistance and minimal long-term maintenance. Demand for vinyl fencing concentrates in North American residential and municipal sectors due to its lifecycle value.
- Aluminum:Fabricated from lightweight, corrosion-resistant alloys, aluminum fencing is favored for its recyclability and low upkeep. Commercial and institutional projects increasingly specify aluminum to meet sustainability mandates like the EU's CSRD.
- Chain Link:Composed of woven steel wire, chain link provides a cost-effective and durable solution for basic perimeter security.
- Wood:Traditional wood fencing offers aesthetic appeal and a lower initial installation cost for residential and light agricultural uses.
- Steel:Robust and durable, steel fencing is critical for large-scale agricultural operations and industrial security applications.
- Bamboo:This natural, rapidly renewable material serves niche markets focused on sustainable aesthetics and privacy screening.
Most installed capacity flows through Wood. Expansion is steepest in Vinyl.
Technology:
Technology segmentation illustrates the cost-benefit analysis from basic physical barriers to advanced, integrated security systems. Investments in smart capabilities are reshaping market offerings.
- Sensor-Based:These systems integrate various sensors for real-time perimeter breach detection and monitoring, crucial for critical infrastructure protection. Commercial, industrial, and utility sectors are driving the adoption of sensor-based fencing for enhanced security.
- Automated:Automated fencing incorporates motorized gates and access control systems for controlled entry and exit points. Smart city initiatives and data center protection projects require robust automated solutions.
- Electric:Electric fencing provides an effective deterrent for animal containment and agricultural perimeter control.
- Solar-Powered:Utilizing photovoltaic panels, solar-powered fencing solutions are ideal for remote installations where grid power is unavailable.
- Manual:Manual fencing refers to basic, non-powered barrier systems primarily used for property demarcation and simple access control.
Adoption of Manual is widespread, while Sensor-Based presents new revenue models.
Application:
Application segments differentiate between high-volume, lower-margin installations and specialized projects yielding higher returns. Each segment has distinct material and technology preferences.
- Residential:This segment represents the largest volume, focusing on privacy, aesthetic appeal, and property demarcation for individual homes. Property owners increasingly choose lower-maintenance materials like vinyl and aluminum.
- Agricultural:Large-scale livestock farming and pasture management drive demand for durable and extensive fencing systems. Brazil and Australia represent key agricultural economies requiring robust solutions.
- Commercial:Commercial projects often yield higher margins per installation, emphasizing security, corporate image, and regulatory compliance.
- Institutional:Schools, government buildings, and healthcare facilities require fencing for safety, security, and controlled access.
- Recreational:Public parks, sports complexes, and recreational facilities utilize fencing for safety, crowd control, and boundary definition.
Residential accounts for the bulk of unit sales, with Commercial driving innovation in system design.
End User:
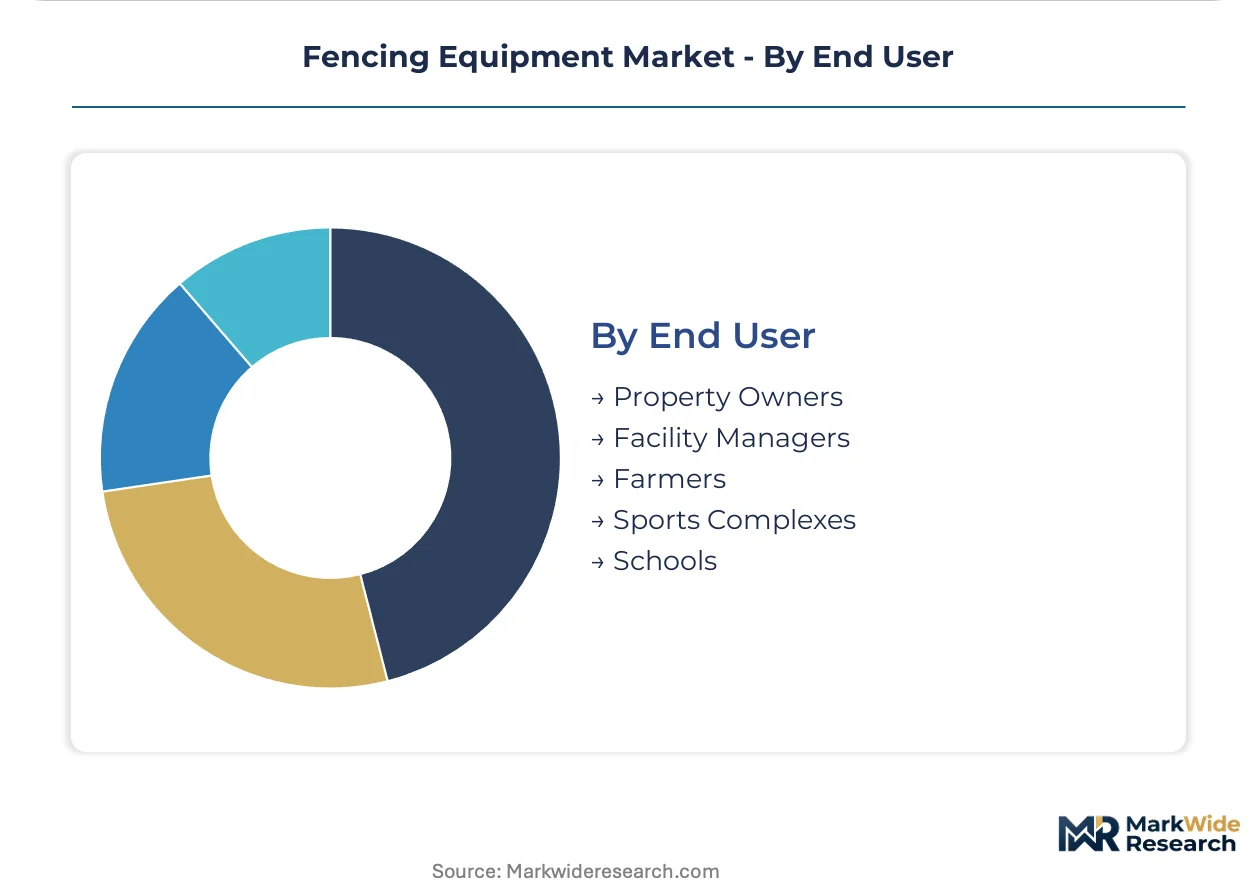
End user segmentation reflects diverse procurement drivers, from individual property enhancement to large-scale operational security. Each user type has specific performance and budget considerations.
- Property Owners:Individual homeowners and small business owners prioritize aesthetics, privacy, and long-term value for their properties. The shift to lower-maintenance materials is prominent among these buyers.
- Farmers:Agricultural producers require robust and extensive fencing for livestock containment, crop protection, and pasture management. Durability and cost-effectiveness are key purchasing criteria.
- Facility Managers:Managers of commercial, industrial, and critical infrastructure sites focus on security, operational efficiency, and compliance with high-performance standards.
- Sports Complexes:These entities require fencing for crowd control, spectator safety, and demarcation of playing areas.
- Schools:Educational institutions prioritize student safety, campus security, and adherence to local building codes.
Procurement by Farmers focuses on durability, while Facility Managers prioritizes integrated security solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled fabrication and installation workforces anchor demand in key regions for fencing equipment. This talent pool often concentrates in areas with established industrial bases and agricultural sectors. These concentrations drive both product innovation and specialized project execution for fencing solutions.
Brazil
Brazil's extensive agricultural sector drives significant demand for durable fencing systems, particularly for livestock management. The national agricultural regulator, ANVISA, sets standards for equipment used in farming operations. Key industrial clusters around São Paulo contribute to both manufacturing and distribution of these essential products.
Australia
Australian large-scale farming operations require robust fencing for animal containment and property demarcation. The Therapeutic Goods Administration (TGA) oversees some product safety aspects relevant to agricultural equipment. Agricultural hubs in Queensland and New South Wales represent significant demand centers for fencing solutions.
United States
The United States sees substantial demand from residential and critical infrastructure projects for various fencing types. Local building codes across different municipalities dictate specific wind load and safety standards. Major urban centers like Houston and Dallas drive commercial installations and specialized security fencing.
Germany
Germany's market for fencing equipment is influenced by sustainability mandates under the EU's Corporate Sustainability Reporting Directive (CSRD). CE marking requirements ensure material safety and structural performance for products sold within the European Economic Area. Manufacturing centers in Bavaria focus on innovative and compliant fencing solutions.
China
China's rapid infrastructure development and agricultural modernization fuel significant fencing demand across various sectors. GB standards, established by the Standardization Administration of China, ensure product quality and safety. Industrial zones in Guangdong Province lead in the production capacity for diverse fencing materials.
Fencing Equipment Market Key Industry Players
Capital-heavy producers compete with asset-light designers in the fencing equipment market. The industry exhibits a tiered structure, from large-scale material manufacturers to specialized component suppliers. Strategic archetypes include commodity volume players, niche solution providers, and technology integrators for smart systems. Companies often engage in geographic expansion and portfolio diversification, alongside strategic partnerships, to capture market share.
Within the context of specialized product lines, Leon Paul exemplifies a focus on niche applications, offering high-performance equipment for a discerning clientele. Allstar sustains its position through strong brand recognition in established markets, serving a broad customer base with its well-known and trusted products. PBT Fencing competes effectively on manufacturing scale, primarily targeting institutional buyers with its cost-effective and robust offerings for large commercial and public sector projects. These three companies collectively illustrate the varied approaches to market penetration and customer segmentation, from premium niche to volume-driven institutional solutions, within the fencing equipment sector.
| Leading Market Players |
|---|
| Leon Paul |
| Allstar |
| PBT Fencing |
| Absolute Fencing Gear |
| American Fencers Supply Co. |
| Blue Gauntlet |
| Alliance Fencing Equipment |
| Prieur Sports |
| Negrini |
| Others |
Cost & Logistics Intelligence
The **London Metal Exchange (LME) aluminum index** and steel futures prices heavily influence fencing equipment costs, cascading through the supply chain into distinct pricing tiers for end-users. This volatility creates procurement challenges for manufacturers and impacts project budgeting for large-scale installations.
Pricing Analysis
Bundled installation and maintenance services often command premium pricing in the fencing equipment market. Project-based contracts dominate commercial and institutional sales, while per-unit transactional models serve residential buyers. Price differentiation stems from material quality grades, specific certifications like CE marking, and the volume scale of the order. Pricing softness reflects input cost volatility for steel and aluminum, alongside substitution pressure from lower-cost wood options. Residential property owners exhibit the highest price sensitivity, whereas critical infrastructure operators prioritize performance over initial cost.
Supply Chain Analysis
Direct sales to large commercial clients and institutional buyers form a significant distribution model, complemented by specialized distributor networks for residential and light agricultural applications. China holds substantial production capacity for diverse fencing materials, while Germany specializes in innovative, compliant solutions. The supply chain for fencing equipment draws heavily from steel, aluminum, and PVC resin producers. Commodity price volatility for these raw materials presents a structural risk across the entire value chain.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The fencing equipment market presents a clear margin-expansion story, driven by the increasing demand for high-value smart systems and lower-maintenance material shifts.
For Market Incumbents:Extend product portfolios into advanced sensor-based fencing systems for critical infrastructure protection. Invest in specialized installation training programs to address the emerging skill gap for smart system deployment. This proactive approach mitigates the threat from technology-focused new entrants and reinforces market leadership through certified expertise. Focus R&D on material science innovations that reduce long-term maintenance requirements, securing market share against lower-cost alternatives.
For New Entrants and Emerging Players:Begin with niche applications requiring specialized solutions, such as aquaculture containment or remote solar-powered electric fences. Target regions with expanding agricultural sectors, like Brazil, where demand for durable and extensive systems is high. A go-to-market angle focusing on integrated design-build-maintain contracts for modular, prefabricated systems offers a differentiated value proposition, appealing to commercial developers seeking accelerated project timelines.
For Investors and Strategic Acquirers:Asymmetric upside sits with technology integrators specializing in perimeter security and data analytics for smart fencing solutions. The long-term viability of this market hinges on the ongoing modernization of infrastructure and increasing security mandates. Identify acquisition targets with strong intellectual property in sensor technology or established networks for complex system installations. A key signal to watch is the adoption rate of industry-wide data protocol standardization, which will unlock greater interoperability and market scale.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand smart fencing R&D | Drives innovation in perimeter security and creates new revenue streams for integrated systems. |
| Invest in installer training | Addresses the technical skill gap and ensures proper deployment of complex smart fencing solutions. |
| Develop modular panel systems | Accelerates project timelines and reduces on-site labor dependencies for commercial installations. |
| Secure long-term material contracts | Mitigates input cost volatility and stabilizes margins for high-volume manufacturers. |
| Target aquaculture containment | Opens a high-value niche application requiring specialized corrosion-resistant fencing solutions. |
Research Approach
Multiple input streams — primary interviews, secondary publications, and internal databases — were reconciled to construct a comprehensive market view. This involved engaging facility managers, agricultural producers, residential property developers, and material science engineers across key geographies. Secondary sources included local building codes, ISO 9001 documentation, CE marking requirements, and reports from agricultural regulators like ANVISA and TGA. A bottom-up approach was triangulated with top-down validation to ensure data accuracy.
The analytical framework cross-referenced historical market performance against expert panel input to project future trends across the analysis window. Segmentation dimensions modeled included product type, technology, application, end user, and material composition. Compound annual growth rates were derived from an assessment of demand elasticity and market penetration rates within these segments. Key forecast inputs included raw material price forecasts and infrastructure spending projections.
Several conditions sit outside the modeled scope, including unforeseen geopolitical instability affecting commodity prices or rapid shifts in regulatory mandates. These forecasts reflect a set of base assumptions regarding market dynamics and technological progression. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Figure Skating Equipment Market
Sports Equipment
Tennis Ball Machine Market
Sports Equipment
Curling Equipment Market
Sports Equipment
Windsurfing Equipment Market
Sports Equipment
Riding Gear Market
Sports Equipment
Synthetic Ice Skating Rink Market
Sports Equipment
Motocross Gears Market
Sports Equipment
Mountain Bicycle Cassette Market
Sports Equipment
Clay Pigeon Thrower Market
Sports Equipment
Global Weighted Hula Hoop Market
Sports Equipment
Winter Sports Equipment Market
Sports Equipment
Air Cushion Basketball Shoes Market
Sports Equipment
Surfing Equipment Market
Sports Equipment
Medicine Balls Market
Sports Equipment
Golf Gloves Market
Sports Equipment
Running Gear Market