
 Water Polo Suits Market | 2026-2036
Water Polo Suits Market Size, Share, and Industry Trends Forecast 2026-2036
Water Polo Suits Market Analytics
Aftermarket team customization and bulk club ordering is reconfiguring margin distribution away from individual retail sales toward institutional procurement channels. TYR leverages its established presence in collegiate aquatics to sustain recurring volume from university water polo programs. KAP7 International anchors its position through specialized water polo-specific design expertise that larger swim brands rarely match. Arena competes by extending its elite competitive swimwear reputation into water polo through athlete endorsement relationships.
Water polo suits are form-fitting competitive garments engineered from chlorine-resistant polyester-spandex blends with flatlock seam construction to withstand aggressive underwater grappling and repeated pool chemical exposure. These suits must maintain compression integrity and colorfastness through rigorous training cycles while meeting federation-mandated coverage requirements for gender-specific competition categories. Men's suits and women's suits represent the established volume base, while training suits capture expanding demand from club programs seeking durable practice alternatives to premium competition pieces. Polyester dominates material selection for its superior chlorine resistance, though spandex blends command attention where stretch recovery and body-hugging fit determine performance perception.
FINA, the international aquatics federation, governs suit approval standards that determine competitive eligibility and directly influence manufacturer R&D priorities and product certification investments. In the United States, NCAA equipment guidelines shape institutional purchasing criteria for collegiate programs, while state high school athletic associations in California and Texas enforce participation rules that cascade into seasonal replacement demand. Stakeholders must monitor federation textile specification revisions and regional procurement consolidation trends to anticipate where compliance costs and volume concentration will shift profit pools next.
Market Dynamics
Federation textile specification revisions are compressing manufacturer certification timelines while institutional procurement consolidation shifts volume concentration toward club and university channels.
Growth Catalysts
- FINA suit-approval protocols:Tightened textile specifications for competitive eligibility are forcing manufacturers to upgrade R&D capabilities, creating barrier-protected demand for certified suppliers.
- California and Texas youth programs:Expanding club-level equipment procurement budgets are generating recurring seasonal replacement volume from state high school athletic associations.
- Chlorine-resistant polyester-spandex blends:Material advances extending suit lifespan through aggressive underwater grappling cycles are reducing total cost of ownership for training programs.
Market Restraints
- Petrochemical input volatility:Polyester feedstock price swings compress margin predictability for manufacturers locked into annual institutional contract pricing.
- Specialized dye and finish supplier concentration:Colorfastness chemical providers cluster in limited geographies, exposing brands to supply interruption risk.
- FINA certification timeline rigidity:Fixed approval windows prevent rapid product iteration, freezing design cycles at 18-24 month intervals.
Strategic Opportunities
- Australia national federation subsidies:Federally funded athlete equipment cost reductions are accelerating adoption rates among price-sensitive competitive swimmers transitioning to water polo.
- Aftermarket team customization services:Bulk club ordering with integrated logo and color matching is capturing margin previously lost to third-party decorators.
- Training suit category expansion:Durable practice alternatives to premium competition pieces are opening volume segments in recreational and masters programs.
Industry Challenges
- Flatlock seam technician scarcity:Specialized construction skills for underwater grappling durability are concentrated among aging workforce pools in traditional manufacturing regions.
- Multi-federation compliance complexity:NCAA, FINA, and state high school athletic associations maintain divergent coverage requirements, fragmenting product SKUs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Water Polo Suits Market |
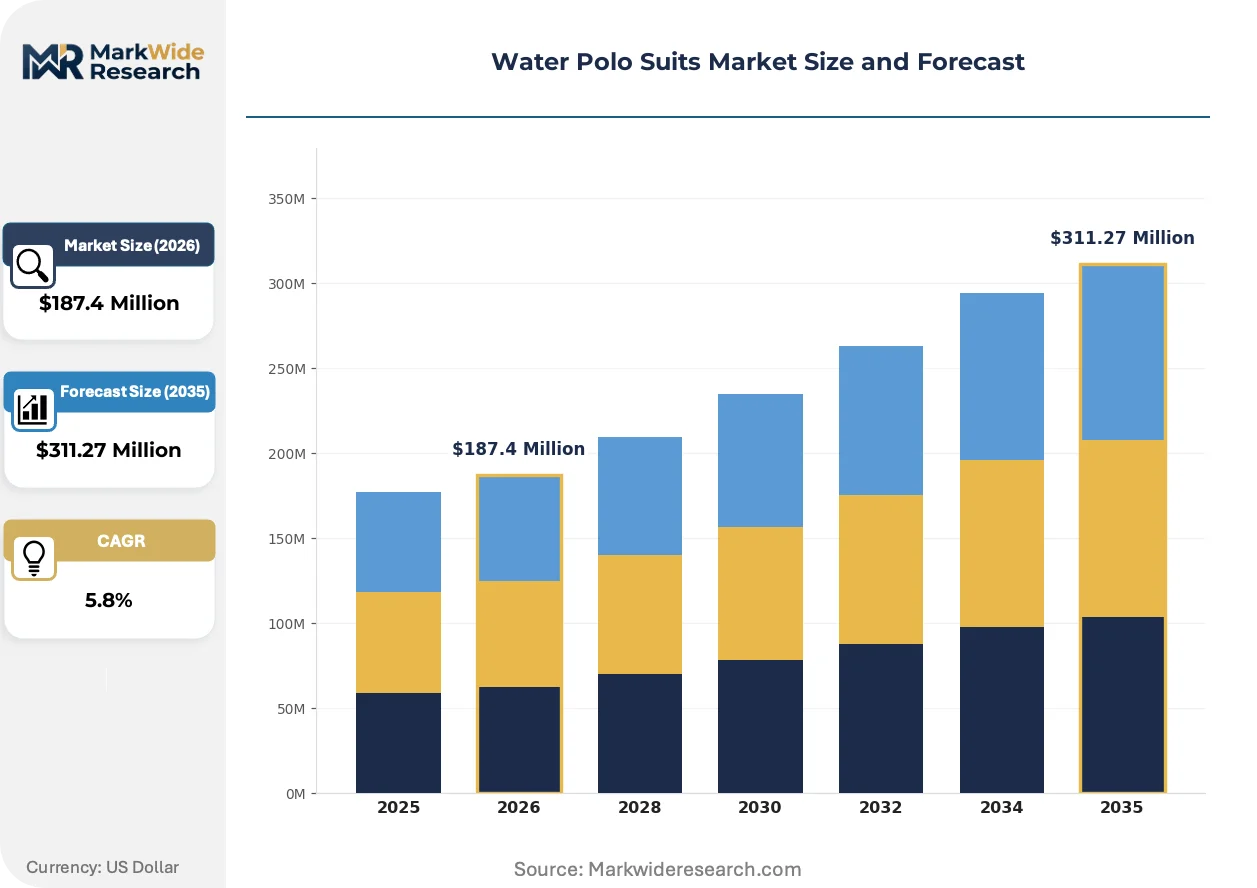
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Men's Suits, Women's Suits, Kids' Suits, Training Suits Material: Polyester, Nylon, Spandex, Neoprene Application: Professional Competition, Recreational Use, Training, Water Aerobics End User: Athletes, Coaches, Fitness Enthusiasts, Schools |
| Companies Covered | TYR, KAP7 International, Turbo, Jolyn, Dolfin, Arena, Nike, Total Waterpolo, Speedo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Water Polo Suits Market Evolving Landscape
Digital design workflows and federation-mandated specification transparency are compressing product development cycles while reshaping how manufacturers validate performance claims.
3D body scanning and pattern digitization is digitizing the fit customization process for institutional bulk orders. Collegiate aquatics programs in the United States are adopting these tools to reduce sizing errors in remote team orders. The technology is digitizing margin capture from alteration services and reducing return rates for direct-to-club shipments.
FINA's updated suit-approval protocols are mandating pre-competition textile testing documentation from certified laboratories. Manufacturers must now submit seam strength and chlorine degradation data before competitive eligibility designation. European competitive swimwear producers are responding by integrating in-house testing facilities to compress certification timelines.
Club procurement officers are consolidating seasonal purchases through dedicated team portals that bypass traditional retail intermediaries. Bulk ordering platforms with integrated customization tools are displacing individual athlete retail purchases in organized programs. This behavioral shift concentrates most visibly in California and Texas, where state high school athletic associations govern participation rules that cascade into coordinated equipment procurement.
Water Polo Suits Market Segmentation
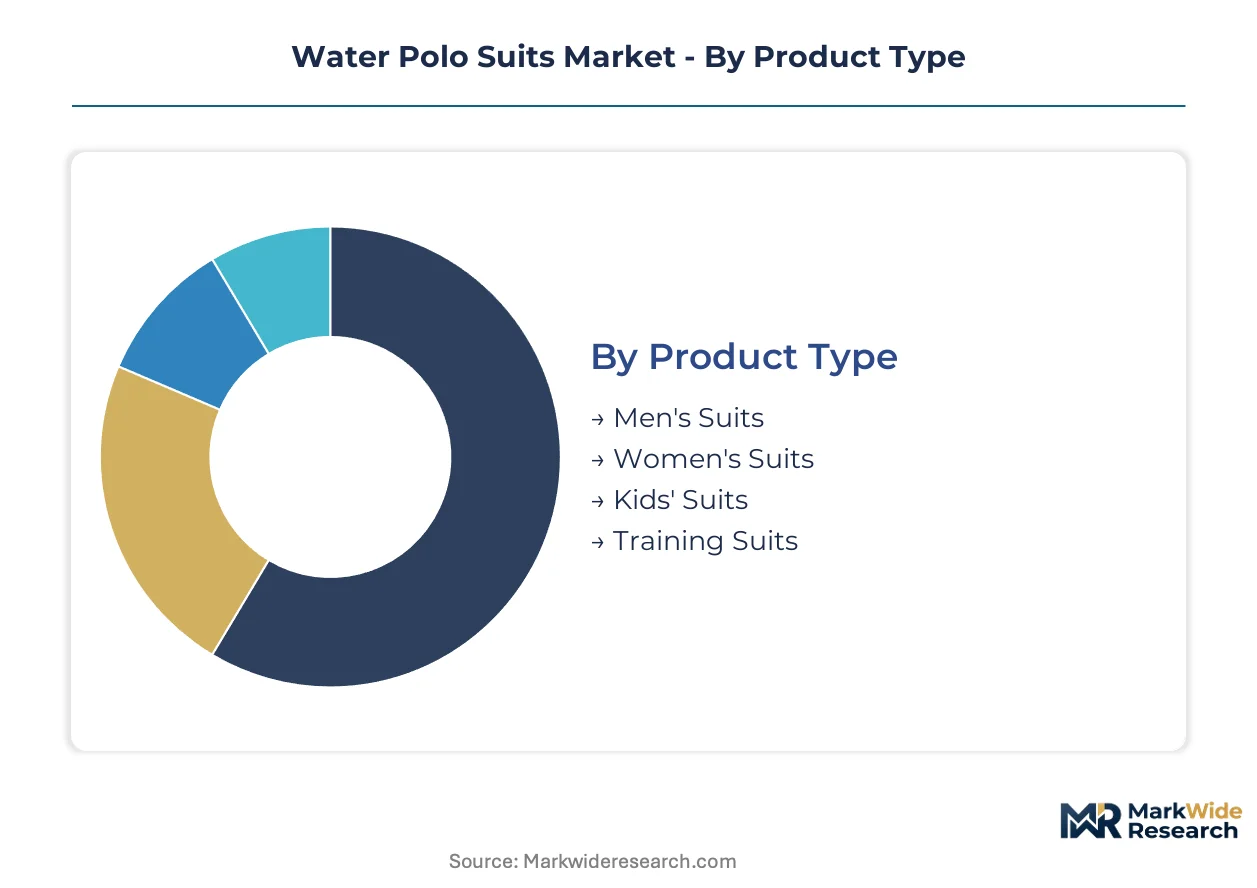
Segmentation in water polo suits reveals how federation compliance requirements, material durability demands, and procurement channel economics fragment addressable volume across distinct technical and commercial boundaries. Manufacturers must align product architecture with these intersecting dimensions to capture recurring institutional contracts.
Product Type:
Mature competition formats anchor established demand while emerging practice categories reshape volume distribution toward training-focused alternatives.
- Men's Suits:Compression-cut designs with reinforced flatlock seams withstand underwater grappling forces during aggressive defensive play. California and Texas high school athletic associations generate concentrated seasonal replacement orders through coordinated team procurement. Men's suits retain volume leadership; training suits hold the steepest expansion curve.
- Women's Suits:FINA-mandated coverage specifications dictate leg-line placement and torso compression zones for competitive eligibility. Australian national federation subsidies accelerate adoption among price-sensitive athletes transitioning from competitive swimming programs.
- Kids' Suits:Rapid size-turnover in youth club programs drives recurring replacement cycles, with durability prioritized over premium textile specifications.
- Training Suits:Chlorine-resistant polyester constructions extend functional lifespan through daily practice schedules, capturing margin from programs seeking cost-per-use efficiency.
Men's suits command the largest addressable base; training suits are climbing the fastest as club programs professionalize practice infrastructure.
Material:
Cost tier differentiation separates commodity feedstocks from performance-engineered blends with certification-backed durability claims.
- Polyester:Dominant selection for superior chlorine resistance and colorfastness through repeated pool chemical exposure. Institutional procurement officers in collegiate aquatics programs specify polyester blends for bulk seasonal orders to minimize total cost of ownership.
- Spandex:Critical stretch-recovery properties enable body-hugging fit that determines athlete performance perception in elite competition. Spandex blends gain priority where FINA textile specifications mandate compression integrity validation.
- Nylon:Alternative base fiber with softer hand feel, though inferior chlorine resistance limits deployment to recreational and entry-level segments.
- Neoprene:Thermal insulation properties serve niche cold-water training applications and masters program participants in temperate climates.
Polyester anchors procurement volume; spandex commands the highest per-unit margins through technical differentiation.
Application:
Customer type stratification separates federation-regulated competitive use from discretionary recreational participation with divergent price sensitivity profiles.
- Professional Competition:FINA-certified suits with laboratory-documented seam strength and chlorine degradation data. European manufacturers integrate in-house testing facilities to compress approval timelines for elite athlete endorsement relationships.
- Training:Durable practice alternatives displacing premium competition pieces in club program budgets, with bulk ordering platforms capturing margin from remote team shipments.
- Recreational Use:Casual participation in municipal pool programs and summer leagues with minimal federation compliance requirements.
- Water Aerobics:Cross-category demand from fitness programming with distinct coverage preferences and lower compression specifications.
Professional competition drives certification investment; training applications are gaining share fastest through procurement consolidation.
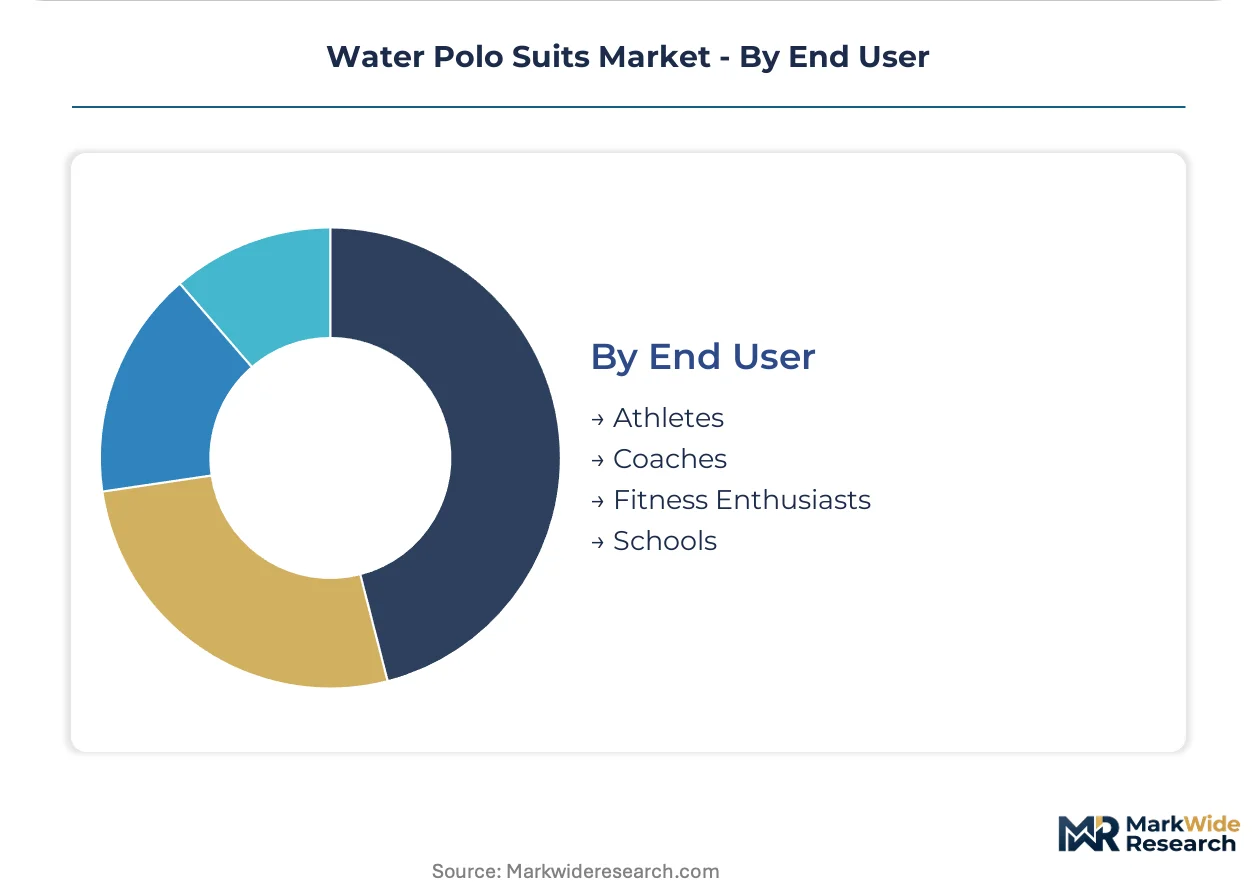
End User:
Procurement authority concentration determines whether purchasing flows through individual athlete retail or institutional volume contracts with integrated customization.
- Athletes:Individual competitors selecting suits based on federation eligibility lists and personal fit preferences, with digital sizing tools reducing return rates.
- Schools:State high school athletic associations in California and Texas enforce participation rules that cascade into coordinated seasonal replacement demand through dedicated team portals.
- Coaches:Program directors consolidating bulk orders with logo integration and color matching, displacing third-party decorators.
- Fitness Enthusiasts:Masters program participants and recreational swimmers with intermittent replacement cycles and price-sensitive selection criteria.
Schools concentrate procurement volume; coaches control the fastest-growing channel through team-level ordering authority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across geographies, with Australian federation subsidies compressing athlete equipment costs while California and Texas club programs absorb premium pricing for institutional bulk orders.
United States
California and Texas high school athletic associations generate concentrated seasonal replacement demand through coordinated team procurement portals. NCAA equipment guidelines shape institutional purchasing criteria for collegiate aquatics programs across the country. Los Angeles and Austin metropolitan areas anchor youth club program expansion with expanding equipment budgets.
Australia
National federation subsidies lower athlete equipment costs, accelerating adoption among price-sensitive competitive swimmers transitioning to water polo. TGA oversight ensures textile safety standards align with international federation requirements. Sydney and Melbourne metropolitan clusters concentrate elite training facilities with subsidized suit procurement programs.
Italy
European competitive swimwear producers integrate in-house testing facilities to compress FINA certification timelines for elite athlete relationships. CE marking requirements govern textile safety for regional distribution. Northern Italian manufacturing clusters around Milan and Bologna maintain specialized flatlock seam technician pools for premium suit construction.
Japan
METI industrial standards intersect with FINA protocols to create dual-layer compliance requirements for imported competitive garments. JIS standards for textile durability influence material selection for chlorine-resistant applications. Tokyo and Osaka metropolitan areas concentrate masters program participation with recurring replacement cycles.
Hungary
Strong water polo tradition sustains club-level equipment procurement through municipal sports funding mechanisms. EU REACH regulations govern dye and finish chemical compliance for regional manufacturers. Budapest anchors Central European distribution with specialized retail channels serving competitive athlete segments.
Water Polo Suits Market Competitive Landscape
Specialized water polo designers and diversified swimwear conglomerates split the market between federation-certified premium tiers and volume-accessible training categories. Consolidation pressure operates selectively, with institutional procurement consolidation favoring suppliers capable of integrated team customization at scale. Three archetypes dominate: legacy aquatics brands extending competitive swimwear reputations, water polo-native specialists with design-specific expertise, and athletic apparel conglomerates leveraging distribution infrastructure. Competitive moves center on backward integration into dye and finish chemical supply, plus captive certification testing capacity to compress approval timelines.
Within the specialist tier, KAP7 International exemplifies water polo-native design expertise that larger swim brands rarely replicate. TYR and Arena occupy positions bridging competitive swimming heritage into water polo-specific federation compliance, leveraging established athlete endorsement relationships and collegiate program contracts. These three anchors demonstrate how certification-backed durability claims and institutional channel access determine competitive position.
| Leading Market Players |
|---|
| TYR |
| KAP7 International |
| Turbo |
| Jolyn |
| Dolfin |
| Arena |
| Nike |
| Total Waterpolo |
| Speedo |
| Others |
Value Network & Pricing Analysis
Italian dye and finish chemical suppliers cluster around Milan and Bologna, concentrating margin capture upstream while federation certification costs anchor downstream pricing tiers for competitive eligibility.
Pricing Analysis
Aftermarket team customization services drive lifetime value through recurring seasonal orders with integrated logo and color matching. Three-tier pricing structure across premium competition, standard training, and economy entry levels separates FINA-certified suits from practice alternatives. Price differentiation rests on certification grade and volume scale, with institutional bulk orders capturing margin from individual retail. Pricing pressure stems from petrochemical input volatility compressing predictability for manufacturers locked into annual contract pricing. Club procurement officers in California and Texas demonstrate lowest price sensitivity due to subsidized equipment budgets, while Australian individual athletes exhibit highest sensitivity despite federation subsidies.
Supply Chain Analysis
Contract manufacturing capacity concentrates with specialized Italian swimwear producers and Vietnamese textile mills serving volume training segments. Geographic supply concentration centers on Italy for premium competition construction, Vietnam for polyester feedstock conversion, and China for chlorine-resistant chemical finishing. Raw material dependencies draw from petroleum-derived polyester chips, spandex fiber imports, and specialized colorfastness dyes. Single-source vulnerability in European dye chemical providers exposes brands to supply interruption risk. Distribution runs through institutional team portals displacing traditional retail intermediaries in organized programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
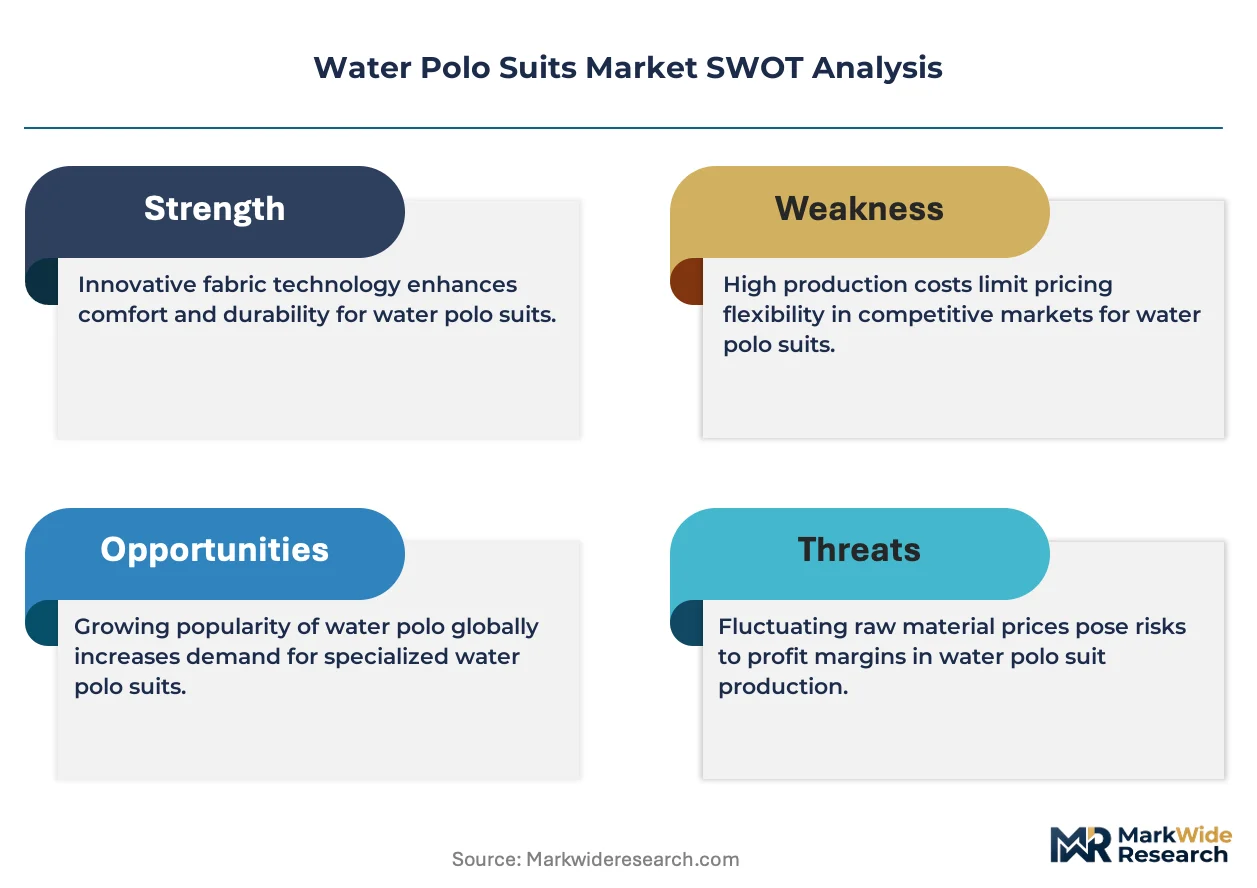
Water polo suits represent a fragmentation opportunity as procurement authority shifts from individual athletes to club and university channels, creating niche positions for specialists with federation certification capabilities.
For Market Incumbents: Pre-empt margin erosion from athletic apparel conglomerates by securing captive dye chemical supply through backward integration into Italian finishing operations. Expand in-house FINA testing facilities to compress certification timelines below 18-month windows, locking out competitors lacking laboratory documentation capabilities. For New Entrants and Emerging Players: Build out training suit specialization targeting masters programs and recreational leagues with minimal federation compliance requirements. Australia offers the most penetrable geography due to federation subsidies lowering adoption barriers. Deploy direct-to-club digital portals with 3D body scanning integration to bypass established retail relationships. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed European swimwear conglomerates seeking portfolio rationalization away from niche federation-regulated categories. Long-term viability favors specialists with certification-backed durability claims and institutional channel lock-in. Watch FINA textile specification revision timing as inflection indicator for R&D investment requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Dye Chemical Supply | Captive colorfastness finishing reduces exposure to Italian supplier concentration risk. |
| In-House FINA Certification Testing | Laboratory integration compresses approval timelines for competitive eligibility designation. |
| Team Portal Digital Platform Launch | Bulk ordering with 3D sizing displaces retail intermediaries in California and Texas clubs. |
| Training Suit Category Expansion | Durable practice alternatives capture margin from cost-conscious masters programs. |
| Australian Distribution Partnership | Federation subsidy alignment accelerates adoption among price-sensitive competitive swimmers. |
Research Methodology
Initial hypotheses were tested against primary input from federation compliance officers, collegiate aquatics program directors, club procurement managers, and specialized dye chemical suppliers and refined through secondary validation against FINA certification databases, NCAA equipment guidelines, customs trade records, and state high school athletic association procurement filings. Bottom-up demand modeling from institutional order flows was triangulated with top-down market sizing from polyester-spandex consumption data.
Demand-supply-balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, material grade tier, application category, and procurement channel authority. CAGRs were derived from institutional volume growth trajectories and replacement cycle compression. Industry-specific forecast inputs incorporated FINA protocol revision schedules and California-Texas high school athletic association budget appropriations.
The forecast holds incumbent behavior within observed patterns; aggressive moves by athletic apparel conglomerates into certification-backed competition tiers would shift outcomes. Quarterly review of federation textile specification proposals and institutional procurement portal adoption rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Carbon Fiber Badminton Racket Market
Sports Equipment
Global Darts Market
Sports Equipment
Cycling Sunglasses Market
Sports Equipment
United States Running Gear Market
Sports Equipment
Gym Shoes Market
Sports Equipment
Starting Blocks Market
Sports Equipment
Bicycle Tire Market
Sports Equipment
Air Cushion Basketball Shoes Market
Sports Equipment
Diving Board Market
Sports Equipment
Triathlon Bikes Market
Sports Equipment
Global Spikeball Equipment Market
Sports Equipment
Juggling Clubs Market
Sports Equipment
Dirt Bike Market
Sports Equipment
Global Cycling Power Meters Market
Sports Equipment
Slam Ball Market
Sports Equipment
Global Wakeboarding Equipment Market