
 Archery Equipment Market | 2026-2036
Archery Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Archery Equipment Market Intelligence
ASTM International standards for bow safety and arrow spine consistency is expanding the cost-of-entry calculus for new manufacturers. Mathews Archery leverages in-house machining to sustain premium positioning. Hoyt Archery anchors Olympic and competitive segments through technology leadership in carbon riser design. Bear Archery competes on heritage brand strength and accessible price points.
Archery equipment encompasses bows, arrows, and accessories engineered to precise draw weights, brace heights, and spine deflection ratings for target shooting, hunting, or competitive sport. Carbon fiber and aluminum alloy construction dominates high-performance segments, while laminated wood persists in traditional and entry-level lines. Bows command the largest revenue pool, though arrows generate recurring replacement demand. Military end users represent a concentrated but restricted growth channel. Distribution through online channels is accelerating as direct-to-consumer brands bypass traditional retail markups.
FAA regulations govern arrow transport in checked baggage, while state wildlife agencies mandate hunter education certification that includes equipment safety modules. ISO 9001 quality management and NFPA standards for recreational facility equipment further shape product liability exposure. Stakeholders must monitor evolving carbon fiber supply constraints and state-level hunting participation trends to calibrate inventory and regional marketing investment.
Market Dynamics
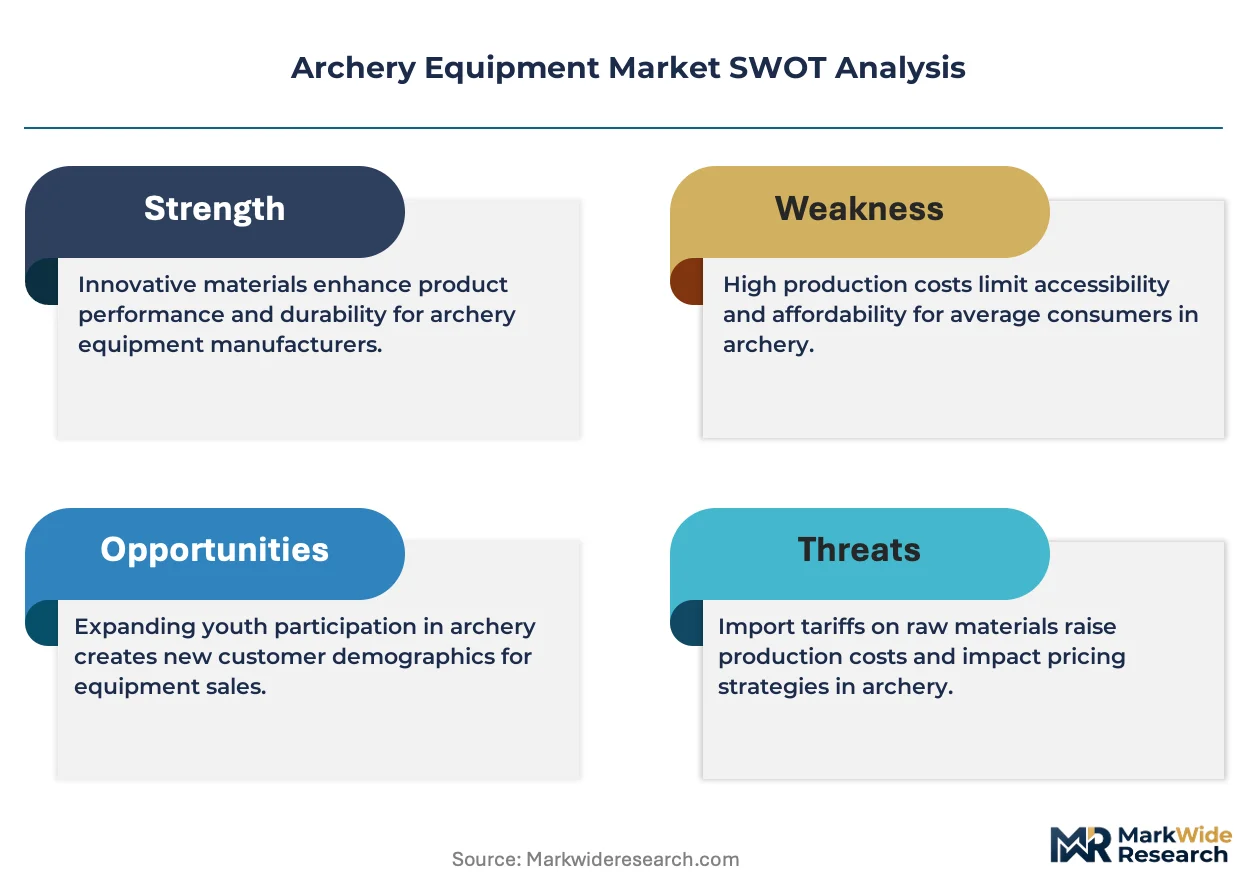
Carbon fiber supply constraints are compressing manufacturing margins while ASTM International's tightening bow safety and arrow spine standards force design retooling across the value chain.
Growth Catalysts
- Youth Archery Initiatives:School athletics departments and Olympic training programs in the United States are scaling equipment procurement, creating sustained institutional demand for certified competition-grade bows and arrows.
- Hunting License Expansion:State wildlife agencies are mandating hunter education certification that includes equipment safety modules, driving replacement cycles and upgrade purchases among licensed participants.
- Carbon Riser Technology:Advances in carbon fiber layup processes are enabling lighter, stiffer bow platforms that meet competitive performance thresholds without metal fatigue limitations.
Market Restraints
- Carbon Fiber Supply Concentration:Aerospace and automotive sectors dominate carbon fiber offtake, leaving archery manufacturers exposed to allocation rationing and price volatility for high-modulus precursors.
- ASTM Compliance Friction:Arrow spine consistency testing requirements and bow safety certification timelines extend product development cycles, delaying revenue recognition for new model introductions.
- Traditional Wood Substitution:Laminated wood bows retain price-sensitive entry-level segments, capping premium carbon platform penetration in recreational and beginner categories.
Strategic Opportunities
- Direct-to-Consumer Channels:Online distribution is accelerating as specialized archery brands bypass traditional retail markups, capturing margin and customer data simultaneously.
- Military End-Use Concentration:Specialized procurement programs for silent weapon training systems represent a restricted but high-value channel with long contract horizons and technical specification lock-in.
- NFPA Facility Standards:Recreational facility equipment mandates under National Fire Protection Association guidelines are driving replacement demand for range safety systems and target infrastructure.
Industry Challenges
- ISO 9001 Certification Burden:Quality management system audits and documentation requirements consume engineering resources at mid-tier manufacturers without dedicated compliance staff.
- FAA Arrow Transport Complexity:Checked baggage regulations governing projectile equipment create customer service friction and return logistics costs for direct-ship retailers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Archery Equipment Market |
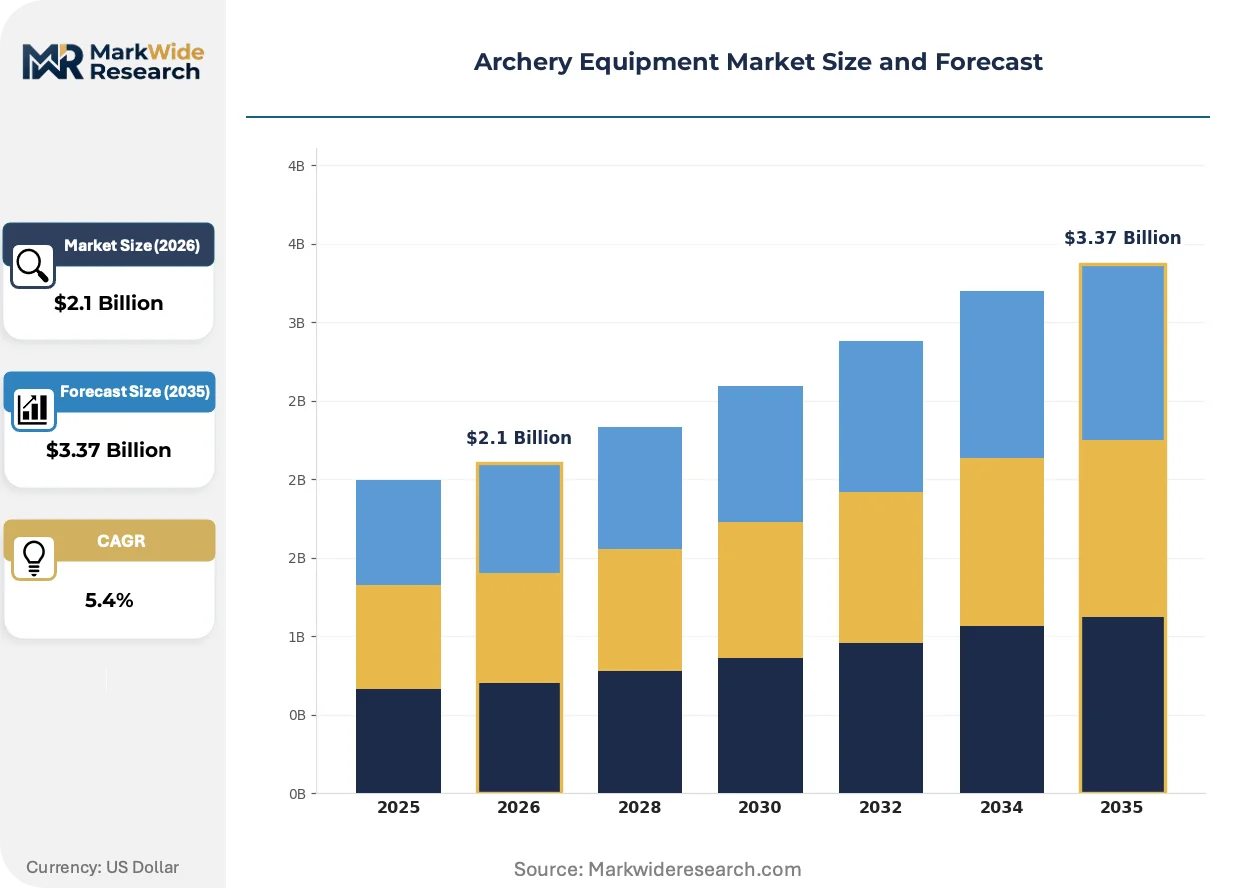
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.37 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bows, Arrows, Quivers, Targets End User: Individuals, Schools, Clubs, Military Distribution Channel: Online, Retail Stores, Events, Wholesale Price Tier: Budget, Mid-range, Premium, Luxury |
| Companies Covered | Mathews Archery, Hoyt Archery, Bear Archery, PSE Archery, Easton Archery, Bowtech Archery, Escalade, Inc., SAS (Southwest Archery), Samick Sports, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Archery Equipment Market Strategic Shifts & Innovations
Precision manufacturing and digital fitting technologies are compressing the gap between mass-produced and custom-tuned equipment, reshaping how archers select and upgrade their setups.
Carbon fiber riser construction is overtaking aluminum alloy as the dominant platform for competitive and hunting bows. Olympic programs and serious amateur competitors are adopting carbon platforms at accelerating rates. This shift is overtaking legacy machining-dependent supply chains and rewarding manufacturers with in-house composite fabrication capabilities.
ASTM International's revised bow safety standards are tightening compliance windows for new market entrants. Manufacturers must now submit to third-party spine consistency verification and dynamic load testing before commercial release. United States-based brands with established quality labs are responding fastest, while smaller importers face extended certification delays.
Digital bow tuning and mobile-enabled draw weight analysis are changing how archers evaluate equipment. Specialty retailers are deploying in-store sensor systems that replace subjective feel with measurable performance data. This pattern is most visible in United States metropolitan markets where technical buyers research extensively online before visiting physical showrooms.
Archery Equipment Market Segmentation
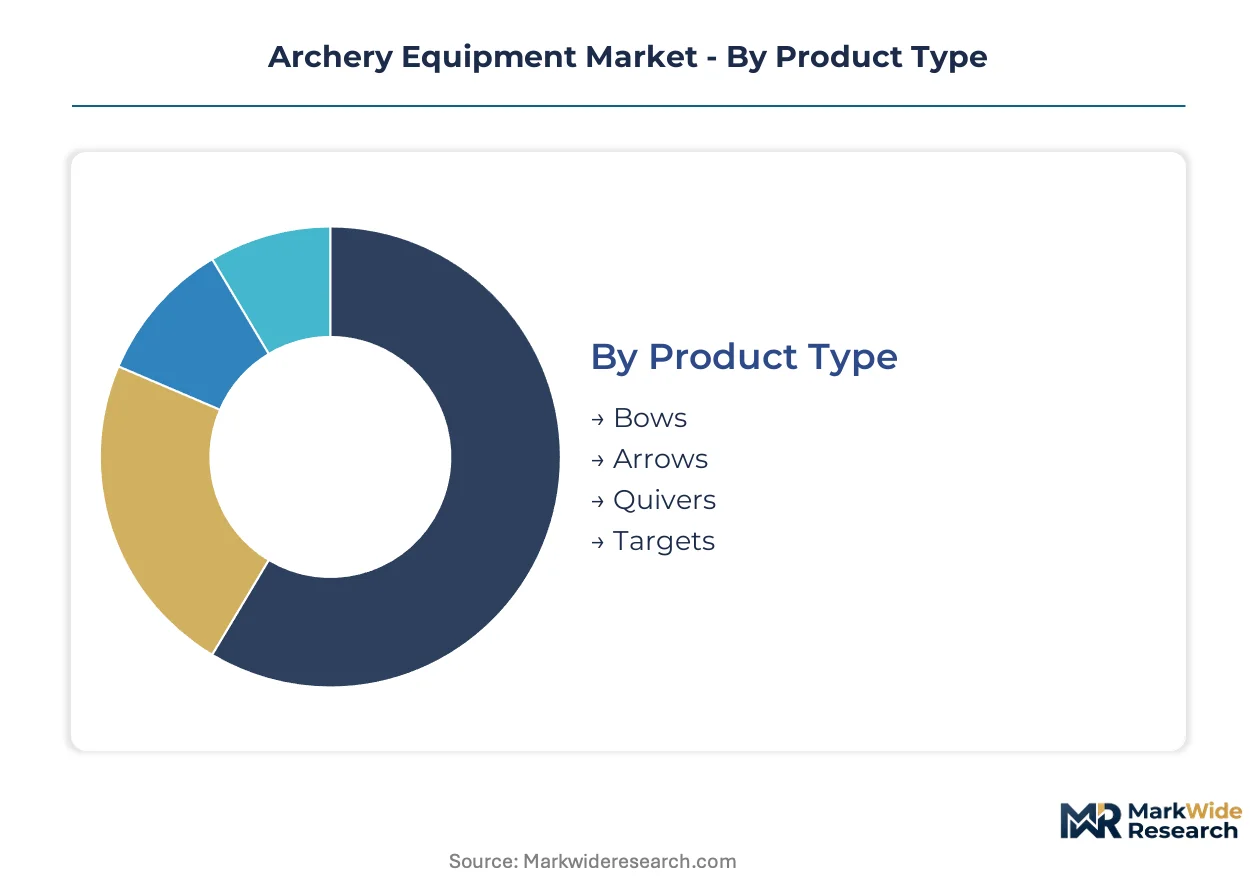
Archery equipment segments diverge sharply by technical specification, procurement authority, and price sensitivity. Carbon fiber tolerances, institutional certification requirements, and channel margin structures create distinct competitive arenas that reward specialized positioning.
Product Type:
Carbon fiber layup precision and spine deflection tolerances define performance differentiation across equipment categories.
- Bows:Recurve and compound platforms engineered to precise draw weights and brace heights dominate revenue concentration. Olympic training programs and competitive circuits in the United States specify carbon riser construction with machined aluminum limb pockets, locking in multi-year replacement cycles.
- Arrows:Carbon fiber shafts with spine consistency ratings between 300-1000 generate recurring replacement demand. ASTM International spine verification requirements and FAA transport regulations create compliance friction that favors established manufacturers with in-house testing labs.
- Quivers:Hip-mounted and bow-mounted designs with quick-detach mechanisms serve hunting and target disciplines. Quiver attachment standardization varies by bow manufacturer, creating ecosystem lock-in effects.
- Targets:Layered foam and bag-style constructions rated for specific arrow speeds and broadhead compatibility. NFPA facility standards and range safety mandates drive institutional replacement demand for certified target systems.
Bows lead on scale; arrows lead on momentum.
End User:
Procurement authority and volume concentration separate fragmented consumer demand from institutional purchasing power.
- Individuals:Hunters and recreational shooters purchasing through retail and direct channels. Hunter education certification requirements in multiple states create predictable equipment upgrade triggers tied to license renewal cycles.
- Schools:Athletics departments and physical education programs scaling equipment procurement. National Archery in the Schools Program (NASP) standardization drives volume demand for Genesis-style universal draw weight bows.
- Clubs:Competitive leagues and recreational associations with centralized equipment budgets. Club-level tournament participation concentrates demand for ILF (International Limb Fitting) standard recurve equipment.
- Military:Specialized silent weapon training programs with long contract horizons and technical specification lock-in. Military procurement represents restricted access but premium pricing for manufacturers meeting security clearance and performance thresholds.
Individuals lead on scale; schools lead on momentum.
Distribution Channel:
Margin capture and customer data access separate direct-to-consumer insurgents from legacy retail networks.
- Online:Direct-to-consumer brands bypassing traditional retail markups with digital fitting tools and subscription arrow replenishment. FAA checked baggage regulations for arrow transport create customer service complexity that rewards retailers with dedicated logistics expertise.
- Retail Stores:Specialty pro shops and big-box sporting goods with in-store tuning services and bow press capabilities. Retail concentration in the United States Midwest and Southeast correlates with hunting license density.
- Events:Tournament vending and trade show direct sales with immediate fitting and tuning services. Event channels capture impulse upgrades from competitive archers testing equipment under tournament conditions.
- Wholesale:Volume distribution to regional retailers and institutional buyers with consolidated procurement authority. Wholesale relationships require ISO 9001 certification and extended payment terms that strain working capital.
Retail stores lead on scale; online leads on momentum.
Price Tier:
Manufacturing cost structures and certification burden stratify competitive positioning across accessible and premium segments.
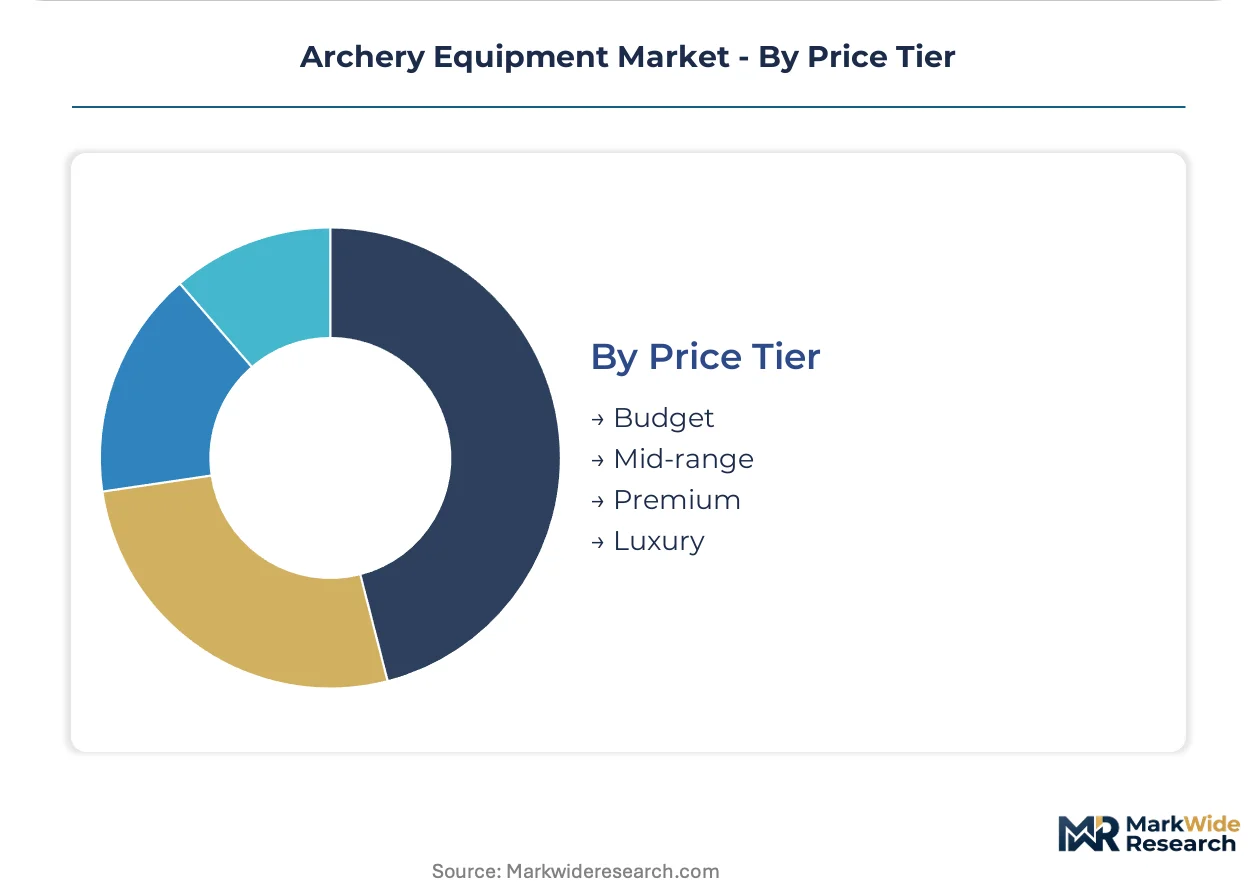
- Budget:Laminated wood and entry-level aluminum construction serving price-sensitive beginners and youth programs. Budget tier penetration faces pressure from ASTM compliance costs that compress margins at low price points.
- Mid-range:Machined aluminum risers with adjustable draw weight systems targeting recreational hunters and club competitors. Mid-range equipment balances performance thresholds with accessible price positioning for education-certified hunters.
- Premium:Carbon fiber riser platforms with custom grip options and precision limb alignment systems. Premium tier demand concentrates in competitive circuits and serious hunting enthusiasts seeking measurable accuracy gains.
- Luxury:Limited edition finishes, custom fabrication, and concierge fitting services for collectors and elite competitors. Luxury positioning requires in-house machining capabilities and extended delivery timelines that exclude mass manufacturers.
Mid-range leads on scale; premium leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized machining talent and composite fabrication expertise concentrate in industrial clusters across the United States, Germany, China, South Korea, and Australia, anchoring regional production capabilities and procurement patterns.
United States
Youth archery initiatives and Olympic training programs drive institutional equipment procurement through schools and athletics departments. FAA regulations govern arrow transport in checked baggage, creating compliance complexity for direct-to-consumer channels. Wisconsin and Utah host machining clusters where in-house carbon riser fabrication capabilities concentrate.
Germany
Competitive archery clubs and recreational associations sustain demand for ILF-standard recurve equipment with centralized procurement budgets. REACH chemical safety standards and CE marking requirements shape carbon fiber precursor import protocols. Bavaria and Baden-Württemberg anchor precision manufacturing clusters serving European tournament circuits.
China
Export-oriented fabrication capacity supplies entry-level and mid-range equipment to North American and European distributors. GB standards and MIIT industrial policy guidelines influence carbon fiber allocation across recreational and defense-adjacent production lines. Guangdong and Zhejiang provinces concentrate laminate bow and arrow shaft manufacturing for international brands.
South Korea
Olympic medal performance and national archery academy programs sustain premium equipment demand from institutional buyers. MFDS quality frameworks and KOC sports equipment procurement standards filter supplier qualification. Gyeonggi-do and Seoul Capital Area clusters specialize in carbon fiber limb and precision riser production for competitive export markets.
Australia
Hunting license growth and field archery club expansion drive replacement cycles among individual consumers. TGA equipment safety guidelines and state wildlife agency hunter education mandates shape retail compliance requirements. Queensland and New South Wales concentrate distribution infrastructure serving Pacific regional tournament circuits.
Archery Equipment Market Key Industry Players
The competitive structure tilts toward heritage-brand incumbents with machining depth and carbon composite integration. Three to five established manufacturers command premium positioning through Olympic certification and tournament sponsorship, while mid-tier fabricators compete on price-accessible aluminum platforms. Two strategic archetypes dominate: vertically integrated specialists with captive carbon fiber supply, and brand-licensing distributors outsourcing production to Asian contract manufacturers. Competitive moves concentrate on direct-to-consumer channel buildout and ASTM compliance certification acceleration.
Within the heritage-brand tier, Mathews Archery, Hoyt Archery, and Bear Archery exemplify divergent positioning strategies. Mathews Archery represents the vertically integrated machining specialist archetype with Wisconsin-based production control. Hoyt Archery occupies the Olympic-anchored technology leadership position through carbon riser design credentials. Bear Archery exemplifies accessible heritage positioning targeting education-certified hunters and youth program entry points. These three entities collectively illustrate how brand history, geographic concentration, and fabrication depth segment competitive terrain without requiring identical capability investments.
| Leading Market Players |
|---|
| Mathews Archery |
| Hoyt Archery |
| Bear Archery |
| PSE Archery |
| Easton Archery |
| Bowtech Archery |
| Escalade, Inc. |
| SAS (Southwest Archery) |
| Samick Sports |
| Others |
Cost & Logistics Intelligence
School athletics departments and Olympic training programs concentrate procurement authority in institutional buyers, locking in contract-based long-term offtake pricing that favors established manufacturers with ASTM certification and in-house carbon fiber fabrication capabilities.
Pricing Analysis
Bundled equipment-and-service packages dominate institutional procurement while unbundled component sales persist in direct-to-consumer channels. Three-tier pricing structure across premium carbon riser, standard aluminum, and economy laminated wood levels differentiates by certification grade and after-sales tuning support. Cost compression in mid-range aluminum tiers is intensifying because ASTM spine consistency testing extends development cycles without corresponding price recovery. Budget-tier buyers in youth programs exhibit highest price sensitivity; military and competitive Olympic segments demonstrate lowest sensitivity due to performance specification lock-in.
Supply Chain Analysis
Certification and qualification gating through ASTM International spine verification and ISO 9001 quality management audits restricts supplier entry, concentrating fabrication in the United States, China, and South Korea. Carbon fiber precursor supply draws from aerospace and automotive offtake pools, with high-modulus tow creating single-source vulnerability when allocation rationing occurs. Distribution runs through specialty retail pro shops with bow press capabilities and direct-to-consumer digital channels with dedicated logistics expertise for FAA-compliant arrow transport.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Carbon riser technology maturation and direct-to-consumer channel expansion create margin expansion headroom as premium-tier adoption displaces aluminum platforms among competitive and hunting segments.
For Market Incumbents: Lock in carbon fiber supply agreements with aerospace allocation pools to defend against precursor rationing. Accelerate ASTM certification timelines for new model introductions to outpace smaller importers facing extended third-party spine verification delays. Deepen in-house composite fabrication capabilities in Wisconsin and Utah machining clusters to maintain premium positioning against Asian contract manufacturers. For New Entrants and Emerging Players: Youth program coordinators in school athletics departments represent an underserved buyer archetype with standardized NASP equipment specifications and predictable replacement cycles. Digital-native hunters seeking subscription arrow replenishment present a penetrable direct-to-consumer segment bypassing traditional retail markups. Prioritize online distribution with dedicated FAA logistics expertise to reduce customer service friction in checked baggage arrow transport. For Investors and Strategic Acquirers: Outdoor recreation conglomerates with existing hunting and shooting sports portfolios are the most active acquirer in this space, seeking brand consolidation and channel integration opportunities. Five-to-ten year viability hinges on carbon fiber supply security and ASTM compliance infrastructure rather than pure manufacturing scale. Target acquisition archetype: mid-tier fabricators with ISO 9001 certification and established wholesale relationships but lacking direct-to-consumer capabilities. Monitor state wildlife agency hunter education mandate expansion as enrollment inflection signal for equipment upgrade demand.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Riser Platform Expansion | Captures Olympic and competitive segments migrating from aluminum fatigue-limited designs. |
| Direct-to-Consumer Channel Buildout | Bypasses retail markups while capturing customer data for subscription arrow replenishment. |
| ASTM Certification Acceleration | Compresses product development timelines to outpace smaller importers facing verification delays. |
| Carbon Fiber Supply Agreement | Secures high-modulus precursor allocation against aerospace and automotive offtake competition. |
| Digital Fitting Technology Deployment | Replaces subjective equipment evaluation with measurable performance data in metropolitan showrooms. |
Research Approach
Multiple input streams — primary interviews with bow manufacturers, specialty retail operators, and school athletics procurement officers; secondary validation through ASTM International certification databases, FAA regulatory filings, and state wildlife agency hunter education statistics; plus customs trade records for carbon fiber precursor imports — were reconciled through bottom-up and top-down triangulation to establish market sizing and growth trajectories.
Historical volume trends were cross-referenced against panel input from industry stakeholders to construct analytical frameworks across the projection horizon, modeling bow type, arrow specification tier, end-user procurement authority, distribution channel margin structure, and regional manufacturing cluster concentration. CAGRs were derived from segmented growth rate reconciliation with carbon fiber supply constraint scenarios and youth program enrollment trajectories as industry-specific forecast inputs.
Underlying measurement precision varies by segment; military and Olympic institutional procurement carries tighter precision than fragmented individual consumer demand. Forecasts reflect documented assumptions regarding carbon fiber allocation continuity and state-level hunter education mandate expansion. A model refresh is warranted upon material change in ASTM International spine consistency testing protocols or aerospace sector carbon fiber offtake patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Cycling Sunglasses Market
Sports Equipment
Smart Swim Goggles Market
Sports Equipment
Riding Gear Market
Sports Equipment
Tennis Pole Market
Sports Equipment
Motocross Gears Market
Sports Equipment
Golf Gloves Market
Sports Equipment
Water Polo Suits Market
Sports Equipment
Trail Shoes Market
Sports Equipment
Sponge Wrestling Mat Market
Sports Equipment
Pickleball Paddle Market
Sports Equipment
Boxing Equipment Market
Sports Equipment
Street Skateboards Accessories Market
Sports Equipment
Running Gear Market
Sports Equipment
Stadium Seating Market
Sports Equipment
Skating Shoes Market
Sports Equipment
Volleyball Shoes Market