
 Middle East and Africa Repair and Rehabilitation Market | 2026-2036
Middle East and Africa Repair and Rehabilitation Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Repair and Rehabilitation Market Foresight
Cementitious repair material production across the Middle East is hardening around a handful of large-scale suppliers with integrated raw material access. Sika AG leverages its regional manufacturing footprint in the UAE to supply epoxy and polyurethane injection systems for concrete crack repair across Gulf markets. MAPEI SpA anchors its position through specialized cementitious grouts formulated for high-temperature desert environments. Fosroc competes with advanced corrosion-inhibiting admixtures tailored to coastal infrastructure exposed to chloride attack.
Repair and rehabilitation encompasses the engineering assessment, material intervention, and structural strengthening of deteriorated concrete, masonry, and steel assets to restore load-bearing capacity and extend service life. Techniques include electrochemical chloride extraction, cathodic protection, and carbon-fiber reinforced polymer (CFRP) laminate bonding with tensile strengths exceeding 3,000 MPa. Structural Repairs command the deepest project value pools given the specialized engineering and high-performance material requirements of foundation and column retrofit work. Smart Repair Technologies represent the fastest-expanding technology category as embedded sensors and drone-based inspection protocols reduce lifecycle monitoring costs for facility managers. Residential Renovations remain a fragmented, price-sensitive segment where local contractors dominate bidding.
Saudi Arabia's Saudi Building Code and the UAE's Dubai Municipality regulations mandate periodic structural audits for buildings exceeding 30 years of age, directly expanding inspection and intervention demand. South Africa's National Regulator for Compulsory Specifications enforces SANS 2001 construction standards that specify repair material performance grades for public infrastructure tenders. Egypt's Housing and Building National Research Center develops localized repair protocols for structures damaged by rising groundwater tables in the Nile Delta. Stakeholders must monitor how evolving green building certifications and embodied carbon accounting reshape material selection criteria for rehabilitation projects.
Market Dynamics
Gulf government mandates for structural audits of aging infrastructure are compressing inspection cycles and forcing facility managers toward predictive maintenance platforms rather than reactive repair contracts.
Growth Catalysts
- Saudi Building Code mandates:Periodic structural audits for buildings exceeding 30 years expand inspection demand across Riyadh and Jeddah municipal portfolios.
- Fiber-reinforced polymer systems:These materials displace steel reinforcement in seismic retrofit programs across high-rise residential towers.
- Water treatment facilities:Aging desalination and distribution networks across the UAE require cathodic protection and chloride extraction interventions.
Market Restraints
- Epoxy resin supply concentration:Raw material sourcing depends on petrochemical feedstock suppliers concentrated in the Arabian Gulf, exposing contractors to price volatility.
- Skilled applicator scarcity:CFRP laminate bonding and electrochemical repair techniques require certified technicians that remain scarce outside Dubai and Cape Town.
- Cementitious grout import dependency:Specialized high-temperature formulations for desert environments often ship from European manufacturing bases, extending lead times.
Strategic Opportunities
- Egypt Nile Delta groundwater damage:Rising water tables create localized demand for waterproofing and foundation rehabilitation protocols developed by the Housing and Building National Research Center.
- Drone-based inspection convergence:Embedded sensor networks combined with aerial survey platforms reduce lifecycle monitoring costs for industrial facility managers.
- Green building certification tailwinds:Embodied carbon accounting in rehabilitation material selection opens preference shifts toward low-carbon cementitious alternatives.
Industry Challenges
- Certification timeline compression:SANS 2001 compliance for South African public infrastructure tenders demands extensive material testing that delays project mobilization.
- Multi-technology integration complexity:Projects combining cathodic protection, CFRP strengthening, and smart monitoring systems require coordination across specialized subcontractors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Repair and Rehabilitation Market |
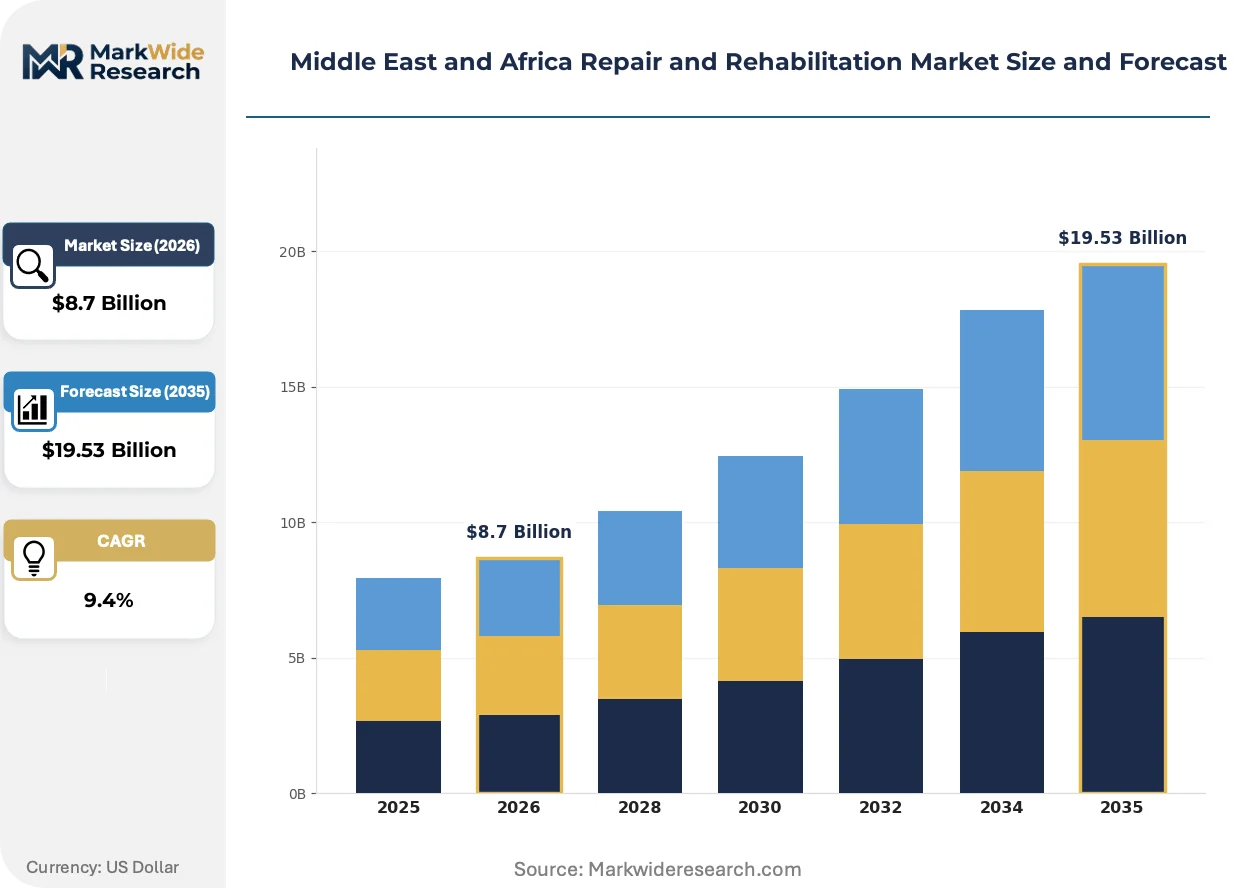
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Structural Repairs, Surface Treatments, Maintenance Services, Restoration Projects Project Type: Residential Renovations, Commercial Upgrades, Infrastructure Development, Historical Restorations Technology: Cementitious Solutions, Polymer Coatings, Fiber-Reinforced Materials, Smart Repair Technologies End User: Government Bodies, Private Developers, Construction Firms, Facility Managers |
| Companies Covered | Sika AG, MAPEI SpA, Fosroc, BASF SE, Saint Gobain, Al Geemi Contracting LLC, Freyssinet, Hilti Corporation, Kryton International Inc, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Repair and Rehabilitation Market Shifts & Advancements
Material science advances and digital inspection tools are collapsing the traditional separation between assessment and intervention phases in infrastructure rehabilitation workflows.
Self-healing concrete incorporating bacterial precipitators and microencapsulated healing agents is unifying the repair function into the material itself. Saudi Aramco and UAE municipal authorities are piloting these systems in coastal infrastructure exposed to chloride-induced corrosion. This convergence is unifying preventive and corrective maintenance budgets into single capital allocations.
Dubai Municipality regulations now mandate drone-assisted facade inspections for buildings exceeding 15 stories, accelerating adoption of photogrammetry and thermal imaging protocols. Engineering consultancies are restructuring field teams around data analysts rather than manual surveyors. High-rise commercial assets in Dubai Marina and Business Bay districts face the steepest compliance deadlines.
Facility managers in Saudi Vision 2030 megaprojects are consolidating repair procurement under 10-year performance-based contracts that bundle assessment, intervention, and monitoring. Traditional lump-sum civil contractors are losing share to integrated service providers. King Abdullah Financial District and NEOM developments anchor this contracting evolution.
Middle East and Africa Repair and Rehabilitation Market Segmentation
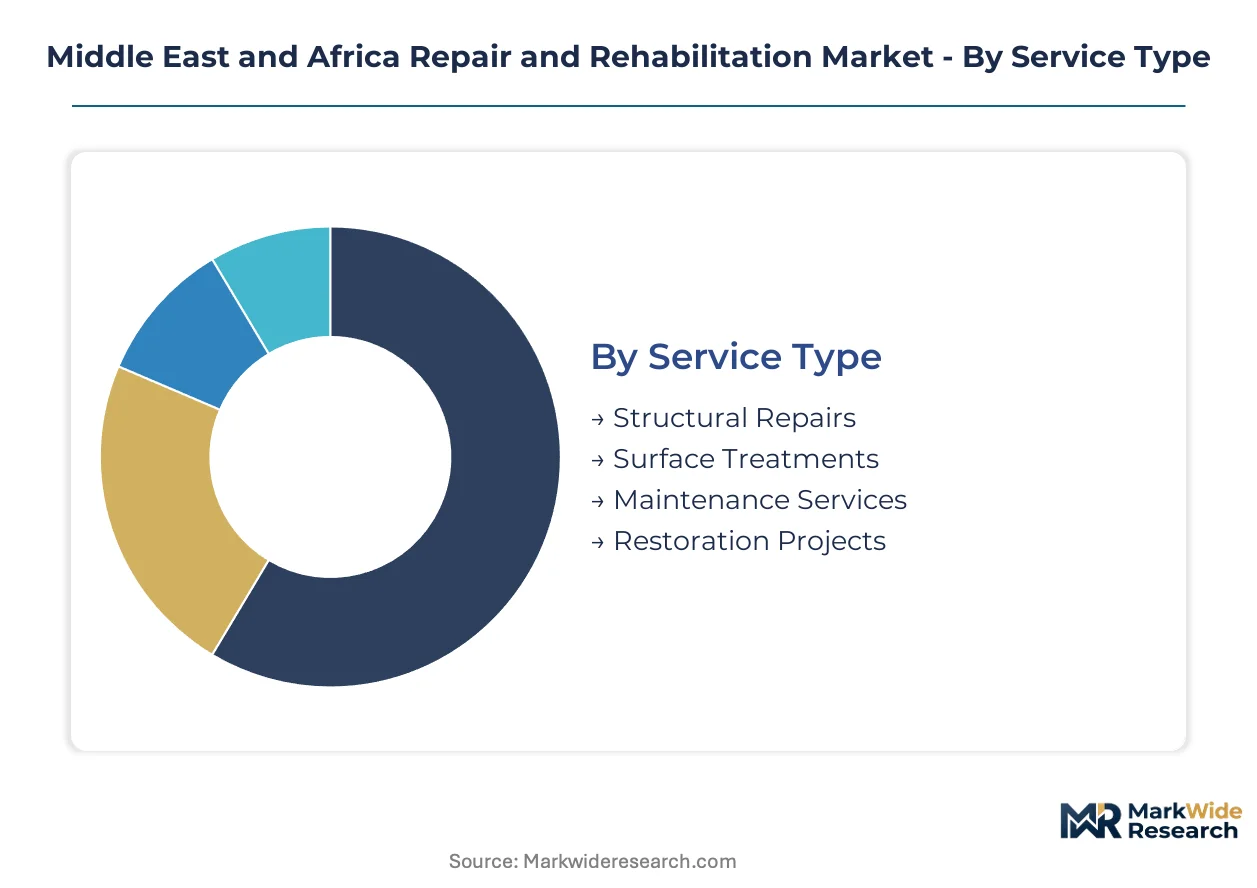
Segmentation in the Middle East and Africa Repair and Rehabilitation Market reveals how intervention complexity, asset ownership patterns, and material innovation create distinct procurement behaviors across project types. Understanding these divides allows suppliers to calibrate technical service depth against contract value thresholds.
Service Type:
Upgrade and replacement cycles vary dramatically by intervention depth, with structural interventions demanding multi-year engineering engagement while surface treatments compress to seasonal maintenance windows.
- Structural Repairs:Foundation retrofitting, column strengthening, and load-bearing wall rehabilitation using carbon-fiber reinforced polymer laminates and post-tensioning systems. Saudi Vision 2030 megaprojects in Riyadh and NEOM are concentrating demand for seismic upgrading of existing municipal assets alongside new construction.
- Surface Treatments:Protective coatings, crack injection, and aesthetic refinishing that restore appearance without altering structural performance. UAE coastal high-rises in Dubai Marina drive demand for chloride-resistant sealers as facade inspection mandates compress maintenance cycles.
- Maintenance Services:Scheduled inspection and preventive intervention programs.
- Restoration Projects:Heritage asset preservation combining modern materials with traditional construction techniques.
Structural Repairs sits at the top of the volume ranking, with Smart Repair Technologies climbing the fastest.
Project Type:
Cost tier differentiation separates high-complexity infrastructure mandates with decade-long performance guarantees from price-sensitive residential bidding where local contractors dominate.
- Infrastructure Development:Bridge retrofitting, water treatment facility rehabilitation, and transportation network strengthening. Egypt's Nile Delta desalination plants and Saudi highway interchanges require cathodic protection and electrochemical chloride extraction.
- Commercial Upgrades:High-rise facade rehabilitation, MEP system replacement, and tenant improvement structural modifications. Dubai Municipality's drone-assisted inspection mandates for buildings exceeding 15 stories accelerate procurement of integrated assessment-intervention contracts.
- Residential Renovations:Individual unit and small-scale building repairs.
- Historical Restorations:Heritage structure preservation with material authenticity requirements.
Infrastructure Development commands the deepest project values, though Commercial Upgrades are expanding most quickly as compliance deadlines tighten.
Technology:
Application environment dictates material selection, with desert thermal cycling and coastal chloride exposure pushing specification toward specialized formulations that standard products cannot satisfy.
- Fiber-Reinforced Materials:Carbon-fiber, glass-fiber, and aramid composites delivering tensile strengths exceeding 3,000 MPa for seismic retrofit and load enhancement. Saudi Aramco pilots self-healing concrete with bacterial precipitators in coastal infrastructure exposed to chloride-induced corrosion.
- Smart Repair Technologies:Embedded sensor networks, drone-based inspection platforms, and predictive analytics dashboards. Facility managers in King Abdullah Financial District consolidate procurement under 10-year performance-based contracts bundling assessment, intervention, and monitoring.
- Cementitious Solutions:Grouts, mortars, and shotcrete for concrete restoration.
- Polymer Coatings:Epoxy and polyurethane protective layers for chemical and abrasion resistance.
Fiber-Reinforced Materials anchor current procurement volumes, while Smart Repair Technologies show the steepest expansion trajectory as lifecycle cost accounting gains priority.
End User:
Customer type determines contracting structure, with government bodies mandating extended warranties and certified applicator qualifications that private developers often waive for speed.
- Government Bodies:Municipal authorities, ministry portfolios, and state-owned enterprises with public tender compliance requirements. South Africa's National Regulator for Compulsory Specifications enforces SANS 2001 construction standards specifying repair material performance grades.
- Facility Managers:Industrial plant operators, commercial property managers, and institutional maintenance directors consolidating repair procurement under integrated service agreements. UAE desalination network operators demand cathodic protection and chloride extraction interventions with embedded monitoring.
- Private Developers:Real estate investment and development companies.
- Construction Firms:General contractors and specialized trade subcontractors.
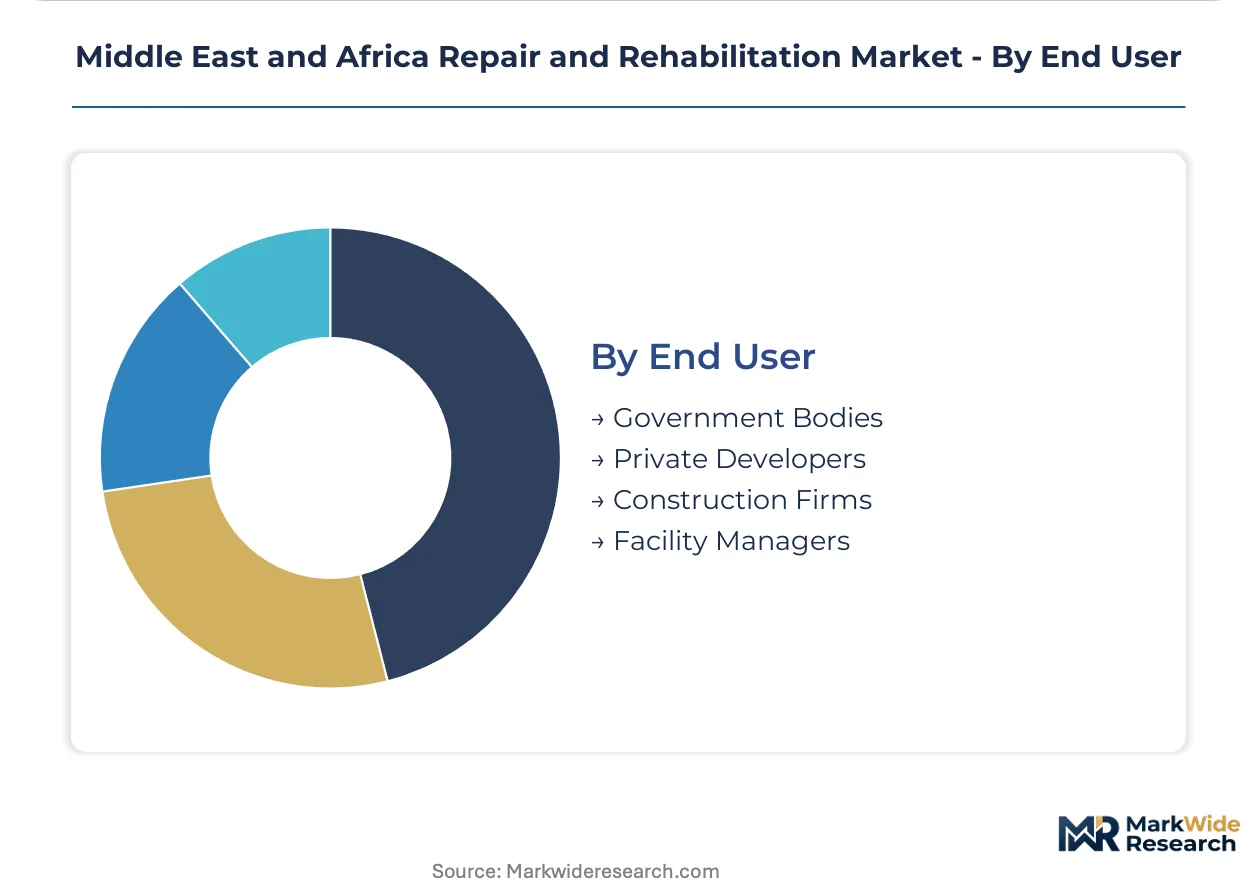
Government Bodies dominate absolute contract value, with Facility Managers gaining share fastest as performance-based contracting replaces traditional lump-sum arrangements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage in repair and rehabilitation procurement is shifting project awards toward jurisdictions with streamlined certification timelines. Contractors migrate toward Saudi Arabia and the UAE where building code mandates create predictable demand pipelines, while South Africa's extensive SANS 2001 testing requirements compress margins for smaller operators.
Saudi Arabia
Vision 2030 megaprojects in Riyadh and NEOM are driving seismic retrofit demand for aging municipal assets. The Saudi Building Code mandates periodic structural audits for buildings exceeding 30 years, forcing facility managers toward predictive maintenance platforms. King Abdullah Financial District anchors the shift toward 10-year performance-based repair contracts.
United Arab Emirates
Dubai Municipality regulations now mandate drone-assisted facade inspections for buildings exceeding 15 stories, collapsing traditional inspection cycles. MOHAP oversees healthcare infrastructure standards while desalination network operators demand cathodic protection with embedded monitoring. Dubai Marina and Business Bay districts face the steepest compliance deadlines for chloride-resistant sealer procurement.
South Africa
The National Regulator for Compulsory Specifications enforces SANS 2001 construction standards specifying repair material performance grades for public infrastructure tenders. Cape Town concentrates certified CFRP applicators capable of electrochemical repair techniques. Johannesburg and Durban industrial corridors drive demand for foundation rehabilitation in manufacturing facilities.
Egypt
Rising groundwater tables in the Nile Delta are creating localized demand for waterproofing protocols developed by the Housing and Building National Research Center. Cairo's aging concrete infrastructure requires extensive chloride extraction interventions. Alexandria coastal assets face accelerated corrosion cycles demanding specialized polymer coating formulations.
Israel
Seismic retrofit programs in Tel Aviv and Haifa are displacing conventional steel reinforcement with fiber-reinforced polymer systems. The country's national construction standards mandate structural assessments for pre-1990 buildings. High-rise residential towers in central districts anchor demand for carbon-fiber wrapping techniques.
Middle East and Africa Repair and Rehabilitation Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue smart monitoring integration and low-carbon material certification. The vendor base stratifies between integrated chemical conglomerates with regional manufacturing footprints and specialized applicator networks winning performance-based contracts. Three archetypes dominate: raw-material-integrated suppliers, certified installation specialists, and digital platform providers bundling assessment with intervention. Competitive moves concentrate on backward integration into petrochemical feedstocks and strategic partnerships with drone inspection service providers.
Among Swiss-based chemical specialists, Sika AG anchors the integrated supplier archetype through its UAE manufacturing footprint. MAPEI SpA represents Italian-formulated cementitious grout specialists targeting high-temperature desert environments. Fosroc occupies a position within the corrosion-inhibiting admixture segment for coastal infrastructure exposed to chloride attack.
| Leading Market Players |
|---|
| Sika AG |
| MAPEI SpA |
| Fosroc |
| BASF SE |
| Saint Gobain |
| Al Geemi Contracting LLC |
| Freyssinet |
| Hilti Corporation |
| Kryton International Inc |
| Others |
Supply & Pricing Matrix
Embodied carbon accounting in rehabilitation material selection gates qualified supply and premium-tier pricing access across Middle East and Africa procurement. Contractors sourcing low-carbon cementitious alternatives face extended certification timelines that compress margins for uncertified competitors while rewarding validated suppliers with performance-based contract premiums.
Pricing Analysis
Distributor margins on epoxy injection systems and CFRP laminates compress project-based pricing into three-tier structures across premium, standard, and economy certification levels. Price differentiation hinges on SANS 2001 compliance grade and applicator certification status, with South African public tenders demanding the highest-grade materials. Cost compression in standard-tier cementitious grouts is intensifying as European import dependency extends lead times. Residential renovation contractors in Egypt and Nigeria exhibit the sharpest price sensitivity, while Saudi Vision 2030 facility managers prioritize lifecycle cost over unit pricing.
Supply Chain Analysis
Regional distribution centers in the UAE and Saudi Arabia anchor hub-and-spoke patterns serving Gulf markets, with secondary nodes in Cape Town and Cairo covering African demand. Manufacturing concentrates in the UAE, Germany, and Italy for specialized formulations. Raw material sourcing draws from petrochemical feedstock suppliers in the Arabian Gulf, carbon fiber producers in Japan and the USA, and bacterial precipitator suppliers in Switzerland. Single-source vulnerability around epoxy resin feedstocks exposes contractors to volatility. Distribution runs through certified applicator networks rather than open merchant channels, with Sika AG and MAPEI SpA controlling direct-to-contractor relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through the shift toward 10-year performance-based contracts that bundle assessment, intervention, and monitoring into single capital allocations.
For Market Incumbents: To counter emerging digital platform providers bundling drone inspection with repair procurement, backward integration into petrochemical feedstocks secures cost position on epoxy and polyurethane systems. Incumbents should anchor certified applicator networks in Riyadh and Dubai to defend share against integrated service providers winning King Abdullah Financial District and NEOM mandates. For New Entrants and Emerging Players: Enter via Egypt's Nile Delta waterproofing segment, where rising groundwater tables outpace local protocol development and the Housing and Building National Research Center seeks implementation partners. Target heritage restoration projects in Cairo and Alexandria where material authenticity requirements limit price competition. Lead with drone-based inspection convergence as the go-to-market wedge. For Investors and Strategic Acquirers: Roll-up economics work for certified installation specialists because fragmented residential renovation markets across Nigeria, Kenya, and Morocco lack national-scale operators. Five-to-ten year viability hinges on consolidation of applicator networks ahead of green building certification mandates. Watch for Saudi Building Code expansion beyond the 30-year audit threshold as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Petrochemical Feedstocks | Sika AG's UAE manufacturing footprint secures captive epoxy supply against Arabian Gulf price volatility. |
| Certified Applicator Network Expansion | Freyssinet's Cape Town training hub addresses skilled technician scarcity for CFRP laminate bonding. |
| Drone Inspection Platform Partnership | Dubai Municipality's 15-story mandate accelerates photogrammetry adoption across Marina and Business Bay assets. |
| Low-Carbon Material Certification Investment | MAPEI SpA's desert-formulated grouts align with embodied carbon accounting reshaping Saudi tender criteria. |
| Performance-Based Contracting Capability | Integrated service providers displace lump-sum civil contractors in King Abdullah Financial District procurement. |
Research Methodology
Coverage spans Saudi Arabia, the UAE, South Africa, Egypt, and Israel, with primary inputs from each market. The study combines interviews with facility managers at Saudi Vision 2030 developments, procurement officers at UAE desalination network operators, certified CFRP applicators in Cape Town, and technical directors at Egypt's Housing and Building National Research Center. Secondary validation draws from Dubai Municipality building codes, SANS 2001 construction standards, Saudi Building Code amendments, and customs data on cementitious grout imports. Bottom-up project pipeline analysis triangulates against top-down infrastructure budget disclosures.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. The analytical framework models segmentation by service type (structural repairs, surface treatments, maintenance, restoration), project type (infrastructure, commercial, residential, heritage), technology (fiber-reinforced materials, smart repair technologies, cementitious solutions, polymer coatings), and end user (government bodies, facility managers, private developers, construction firms). CAGRs derive from regression against public infrastructure tender awards and Vision 2030 megaproject disclosures. Key inputs include cathodic protection deployment rates at UAE water treatment facilities and CFRP adoption curves in Israeli seismic retrofit programs.
The model holds under sustained government infrastructure budget expansion and stable petrochemical feedstock availability; deviation in epoxy resin supply disruption or Saudi fiscal consolidation would shift trajectory. Forecasts reflect documented assumptions on regulatory enforcement intensity and certification timeline compression. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction and Engineering
China Marble Market
Construction and Engineering
Japan HVAC Market
Construction and Engineering
Europe District Cooling Pipeline Network Market
Construction and Engineering
Industrial Chiller Market
Construction and Engineering
US Commercial Water Heater Market
Construction and Engineering
GRC Conduit Fittings Market
Construction and Engineering
USA and Canada Fence Screen Market
Construction and Engineering
Roofing Underlay Market
Construction and Engineering
Crushing Screening Equipment Market
Construction and Engineering
H Beam Market
Construction and Engineering
Automated Bending Machine Market
Construction and Engineering
North America Prefabricated Housing Market
Construction and Engineering
Crossover Ladder Market
Construction and Engineering
Outsourcing Civil Engineering Services Market
Construction and Engineering
Wet Scrubber Market
Construction and Engineering
Global IoT in Construction Market