
 Middle East and Africa Meal Replacement Products Market | 2026-2036
Middle East and Africa Meal Replacement Products Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Meal Replacement Products Market Foresight
Subscription-based replenishment services is repositioning how meal replacement products reach consumers across the Middle East and Africa. Nestlé SA leverages its extensive distribution infrastructure to sustain shelf presence in modern trade channels across the Gulf. Abbott Laboratories anchors its competitive stance through specialized clinical nutrition formulations targeting diabetic end users. Herbalife Nutrition differentiates via direct-selling networks that control last-mile engagement in South African townships and Nigerian cities.
Meal replacement products are formulated, shelf-stable food items designed to deliver complete macronutrient profiles—typically 15-30 grams of protein per serving—through controlled-calorie formats that substitute for conventional meals in structured dietary regimens. Ready-to-drink protein shakes lead volume consumption among busy professionals seeking portable nutrition solutions, while plant-based ingredient formulations represent the fastest-growing margin pool as Gulf consumers shift toward flexitarian dietary patterns. Powder formats retain mature, price-sensitive demand across North African markets where bulk purchasing remains culturally preferred.
Saudi Food and Drug Authority nutrition labeling mandates and South African National Health and Nutrition Examination standards govern permissible health claims and compositional thresholds across the region. These frameworks compel manufacturers to reformulate products with verified protein content disclosures and restricted sugar thresholds, elevating compliance costs for new entrants. Stakeholders must monitor evolving Gulf Cooperation Council harmonization talks on functional food classification to anticipate market access shifts.
Market Dynamics
Subscription-based replenishment services are concentrating purchasing power among digitally native consumers across Gulf urban centers, compressing traditional retail margins while elevating formulation transparency requirements under Saudi Food and Drug Authority mandates.
Growth Catalysts
- SFDA Labeling Mandates:Saudi Arabia's nutrition disclosure requirements for protein content and sugar thresholds are accelerating reformulation investments, advantaging manufacturers with existing analytical capabilities.
- Flexitarian Dietary Migration:Gulf consumer pivot toward plant-forward eating patterns is expanding addressable demand for pea and fava protein isolates in ready-to-drink formats.
- South Africa Fitness Concentration:Metropolitan gym culture in Johannesburg and Cape Town is anchoring per-capita consumption rates for controlled-calorie meal replacements among structured-diet adherents.
Market Restraints
- Whey Protein Import Dependency:Regional supply chains rely on concentrated European and North American dairy protein sources, exposing margins to currency volatility and shipping cost spikes.
- GCC Harmonization Friction:Divergent functional food classification standards across Gulf Cooperation Council member states fragment compliance pathways and delay multi-market launches.
- Traditional Meal Substitution:Cultural preference for freshly prepared communal dining in North African households limits routine adoption of shelf-stable alternatives.
Strategic Opportunities
- Nigerian Urban Expansion:Lagos and Abuja's emerging professional class remains underserved by specialized nutrition retail, creating first-mover potential for direct-to-consumer fulfillment infrastructure.
- Clinical Nutrition Crossover:Diabetic and metabolic syndrome patient populations across the Gulf present adjacent demand for medical-grade formulations with glycemic control positioning.
- MOHAP Digital Health Integration:UAE Ministry of Health and Prevention wellness initiative alignment offers regulatory tailwind for products substantiating weight management claims through verified clinical data.
Industry Challenges
- Halal Certification Complexity:Multi-jurisdictional religious compliance requirements for animal-derived proteins extend product development timelines and audit costs.
- Cold Chain Gaps:Temperature-controlled distribution infrastructure deficits in secondary Egyptian and Moroccan cities constrain ready-to-drink format penetration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Meal Replacement Products Market |
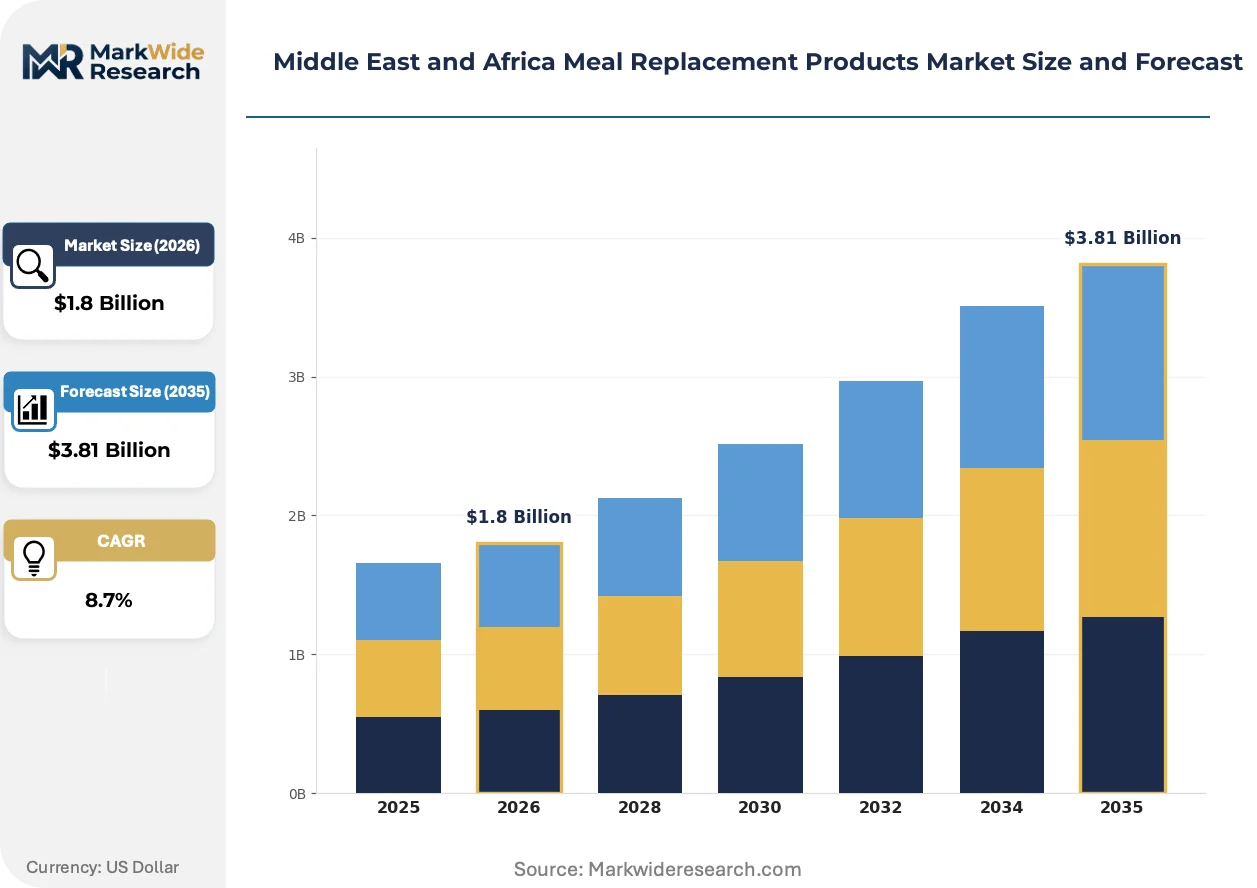
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Protein Shakes, Bars, Powder, Ready-to-Drink End User: Athletes, Weight Watchers, Busy Professionals, Diabetics Packaging Type: Box, Bottle, Sachet, Can Ingredient Type: Plant-based, Dairy, Nut-based, Others |
| Companies Covered | Nutritech, Mannatech, Incorporated, Nestlé SA, Abbott Laboratories, Herbalife Nutrition, Organo Gold Africa (Pty) Ltd., Futurelife, Glanbia Plc, Evolve Nutrition, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Meal Replacement Products Market Shifts & Advancements
Formulation science and distribution architecture are undergoing parallel transformation across Middle East and Africa markets, with protein sourcing, regulatory disclosure, and channel access each experiencing distinct pressure points.
Precision fermentation-derived dairy proteins are modularizing ingredient supply options for manufacturers seeking to decouple from conventional whey supply constraints. Regional formulators in UAE and Saudi Arabia are piloting these inputs for premium-positioned shakes. This technology is modularizing cost structures by enabling localized production of functional proteins without herd-dependent supply volatility.
South African National Health and Nutrition Examination standards are tightening permissible health claim language for weight management positioning. Manufacturers must now submit compositional verification to the national regulator before marketing products with satiety or metabolic benefit assertions. Powder-format producers serving price-sensitive North African markets face the steepest compliance cost absorption.
Direct-selling networks are displacing conventional retail as the primary customer acquisition channel in South African townships and Nigerian secondary cities. Independent distributors control last-mile engagement and credit extension, capturing consumer segments unreachable by modern trade. This channel rotation is most pronounced in peri-urban clusters where formal retail infrastructure remains underdeveloped.
Middle East and Africa Meal Replacement Products Market Segmentation
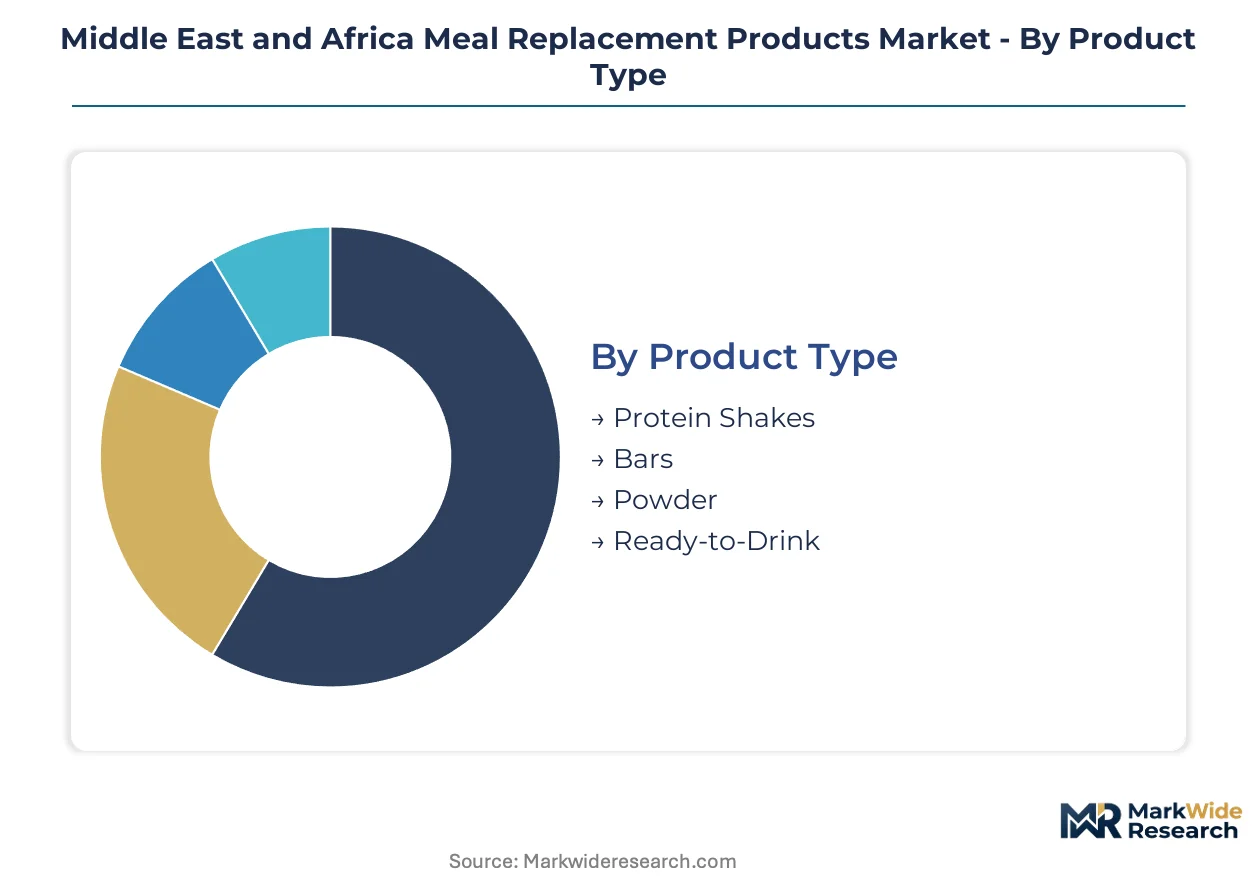
Segmentation in Middle East and Africa meal replacement markets exposes divergent capital requirements across formulation technologies and distribution architectures. Product format selection determines cold chain investment intensity, while ingredient sourcing strategies separate premium-positioned entrants from cost-optimized competitors.
Product Type:
Ready-to-drink formats demand the heaviest upfront capital deployment for aseptic filling lines and refrigerated logistics infrastructure across Gulf urban corridors.
- Ready-to-Drink:Shelf-stable liquid formulations in tetra-pak or bottle formats require high-speed aseptic processing equipment. Saudi Arabia's SFDA mandates precise protein disclosure thresholds that elevate analytical lab investments for entrants. Demand concentrates among Riyadh and Dubai office workers seeking commute-compatible nutrition solutions.
- Powder:Dry-blend formulations in bulk canisters or pouches minimize per-unit packaging costs and tolerate ambient distribution. South African metropolitan gym chains and Nigerian direct-selling networks anchor volume procurement for this format.
- Protein Shakes:Pre-mixed refrigerated products with limited shelf stability. Cold chain gaps in secondary Egyptian and Moroccan cities constrain penetration.
- Bars:Extruded and enrobed solid formats with intermediate capital requirements for coating and packaging lines. Convenience retail in Gulf modern trade channels drives placement.
Powder absorbs the bulk of installed capacity; ready-to-drink is expanding most quickly.
End User:
Customer-type segmentation reveals sharply divergent price elasticity and channel access patterns across the region's heterogeneous consumer base.
- Busy Professionals:Time-constrained white-collar workers in Gulf financial districts prioritize convenience and premium positioning. Johannesburg and Cape Town corporate campuses show parallel demand concentration.
- Diabetics:Clinically validated glycemic control formulations command premium pricing and require regulatory substantiation. UAE MOHAP digital health integration initiatives create favorable reimbursement pathways for compliant products.
- Athletes:Performance-oriented consumers in South African fitness culture drive high-protein format innovation. Metropolitan gym partnerships dominate acquisition channels.
- Weight Watchers:Calorie-controlled program adherents seeking structured meal substitution. Subscription replenishment services capture this segment in Gulf urban centers.
Busy professionals generate the highest per-capita revenue; diabetics are climbing the fastest as clinical nutrition boundaries blur.
Packaging Type:
Primary packaging selection governs shelf-life extension, portion control economics, and retail format compatibility across modern trade and informal channels.
- Bottle:PET or glass containers for ready-to-drink liquids with premium visual presence. Saudi and UAE supermarket chilled sections allocate disproportionate shelf space.
- Sachet:Single-serve flexible pouches enabling trial-sized distribution and price accessibility. Nigerian and South African township direct-selling networks favor this format for credit-extension viability.
- Box:Multi-serve cartons for powder formats supporting bulk purchasing preferences in North African households.
- Can:Metal containers for ambient-stable liquid products with extended shelf life. Limited regional adoption due to recycling infrastructure gaps.
Sachet formats dominate unit volume; bottle packaging commands the steepest value expansion trajectory.
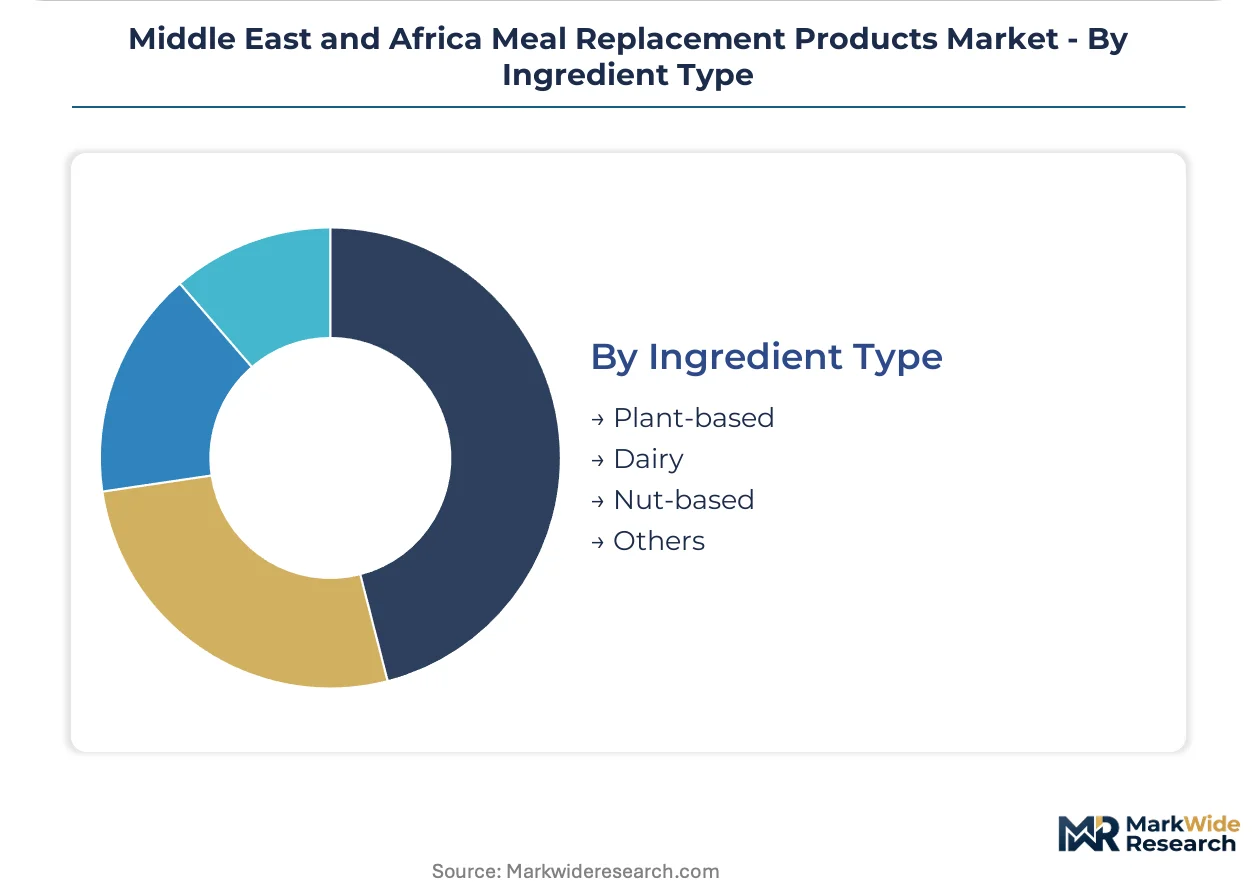
Ingredient Type:
Raw material sourcing strategies separate flexitarian-positioned premium offerings from conventional dairy-dependent supply chains.
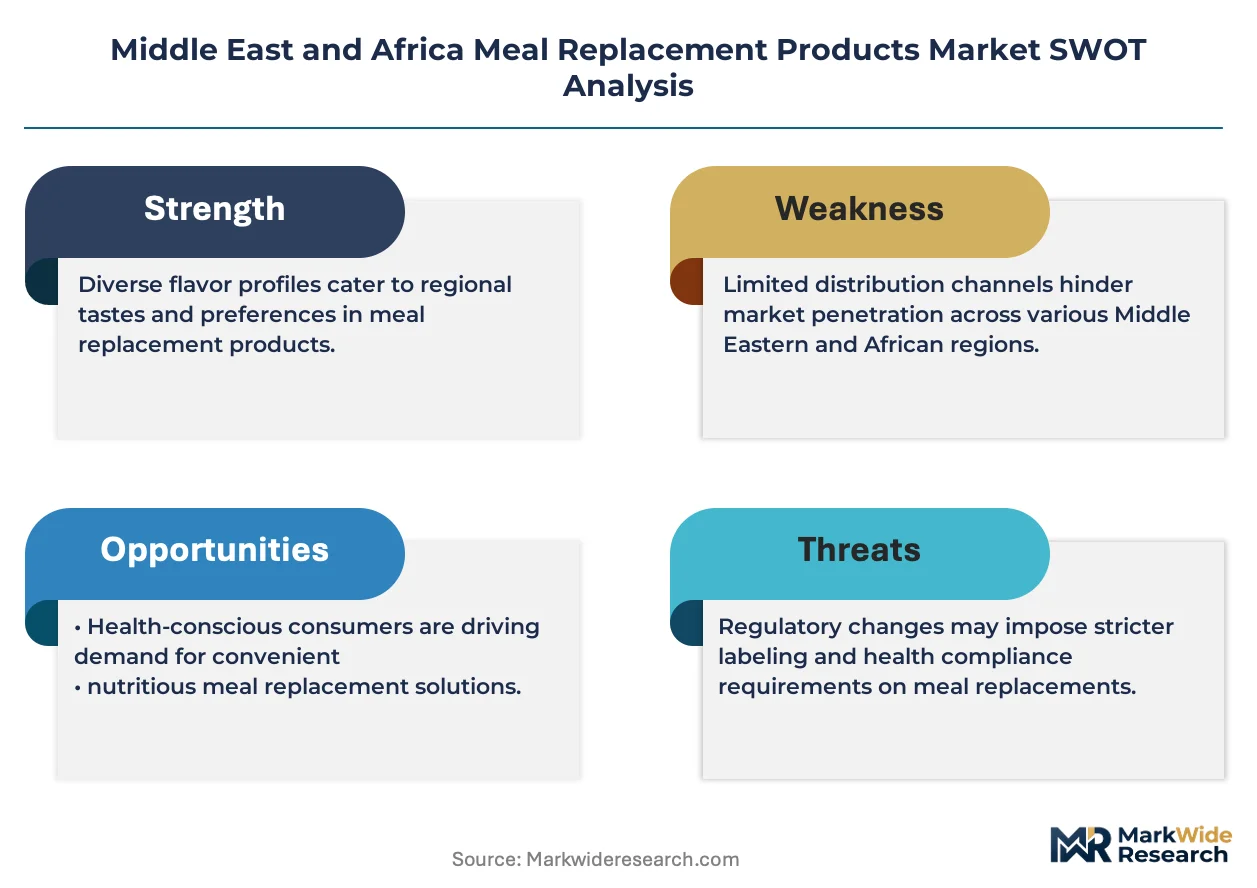
- Plant-based:Pea, fava, and rice protein isolates requiring specialized extraction and flavor-masking investments. Gulf consumer migration toward flexitarian patterns accelerates demand.
- Dairy:Whey and casein proteins from concentrated European and North American supply sources. Currency exposure and halal certification complexity elevate risk profiles.
- Nut-based:Almond and peanut protein formulations with allergen management requirements. Premium positioning in UAE and Saudi wellness retail.
- Others:Insect protein and precision fermentation alternatives in early pilot phases. UAE-based formulators test modular supply options.
Dairy retains volume leadership; plant-based is gaining share fastest across Gulf metropolitan markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity concentrates in South Africa and UAE manufacturing zones, while consumption clusters in Gulf urban centers and South African metropolitan areas. This geographic mismatch creates logistics-intensive supply patterns across the region.
Saudi Arabia
Riyadh and Jeddah office workers drive ready-to-drink format adoption for commute-compatible nutrition. SFDA labeling mandates for protein disclosure and sugar thresholds compel reformulation investments among market entrants. Eastern Province industrial zones host contract manufacturing facilities serving Gulf distribution networks.
United Arab Emirates
Dubai's professional workforce anchors premium positioning demand for plant-based and clinical nutrition formulations. MOHAP digital health integration initiatives create favorable pathways for products substantiating weight management claims. Abu Dhabi wellness retail clusters concentrate high-margin product placement in modern trade channels.
South Africa
Johannesburg and Cape Town gym cultures anchor per-capita consumption for high-protein controlled-calorie formats. National Health and Nutrition Examination standards tighten permissible health claim language for satiety positioning. Gauteng manufacturing facilities supply powder formats to Nigerian direct-selling networks.
Nigeria
Lagos and Abuja emerging professional classes remain underserved by specialized nutrition retail infrastructure. Central Bank of Nigeria foreign exchange policies expose imported whey protein formulations to currency volatility. Direct-selling networks in peri-urban Lagos clusters capture consumer segments unreachable by formal retail.
Egypt
Cairo metropolitan households maintain cultural preference for freshly prepared communal dining, limiting routine shelf-stable adoption. Cold chain infrastructure gaps in secondary Alexandria and Delta cities constrain ready-to-drink penetration. Local formulators target price-sensitive demand through bulk powder packaging for North African export.
Middle East and Africa Meal Replacement Products Market Competitive Landscape
Top-tier vendors anchor Gulf modern trade shelf presence, while direct-selling networks and regional specialists capture peri-urban and township segments. Market structure stratifies across three archetypes: multinational nutrition conglomerates with clinical formulation capabilities, direct-selling organizations controlling last-mile credit extension, and regional contract manufacturers serving private-label demand. Dominant competitive moves include portfolio diversification into plant-based ingredient platforms and geographic expansion through Nigerian urban fulfillment infrastructure.
Among the multinational nutrition conglomerates, Nestlé SA and Abbott Laboratories exemplify divergent strategic positioning within the premium tier. Nestlé leverages extensive Gulf distribution infrastructure for modern trade dominance, while Abbott anchors clinical nutrition credibility through diabetic-end-user specialization. Herbalife Nutrition occupies a distinct position within the direct-selling archetype, controlling township and secondary city engagement through independent distributor networks. Regional specialists including Futurelife and Nutritech represent South Africa-based formulators capturing price-sensitive metropolitan gym demand and North African bulk powder preferences.
| Leading Market Players |
|---|
| Nutritech |
| Mannatech, Incorporated |
| Nestlé SA |
| Abbott Laboratories |
| Herbalife Nutrition |
| Organo Gold Africa (Pty) Ltd. |
| Futurelife |
| Glanbia Plc |
| Evolve Nutrition |
| Others |
Supply & Pricing Matrix
Backward integration into regional whey processing and local plant-protein extraction anchors pricing power for manufacturers navigating SFDA compliance costs and import tariff exposure. This sourcing architecture simultaneously buffers margin compression from European dairy price volatility and enables premium positioning for Gulf flexitarian consumers.
Pricing Analysis
Margin tightening in powder formats reflects bulk purchasing preferences across North African households and Nigerian direct-selling networks. Three-tier pricing structure across premium ready-to-drink, standard powder, and economy sachet levels separates convenience-positioned Gulf professionals from price-sensitive township distributors. Pricing pressure stems from Central Bank of Nigeria foreign exchange policies exposing imported whey formulations to currency volatility. Direct-selling network participants in South African peri-urban clusters exhibit highest price sensitivity; UAE wellness retail consumers show lowest elasticity.
Supply Chain Analysis
Saudi domestic-content mandates for food manufacturing are reshaping sourcing patterns toward Eastern Province contract facilities and UAE-based precision fermentation pilots. Raw material dependencies center on European whey concentrates, North American casein isolates, and emerging pea protein supplies from regional agricultural projects. Supply chain risk concentrates in single-source vulnerability for halal-certified animal proteins requiring multi-jurisdictional religious audits. Distribution runs through modern trade channels in Gulf urban centers, direct-selling networks in Nigerian secondary cities, and gym partnerships in South African metropolitan areas.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around manufacturers with analytical capabilities for SFDA protein disclosure mandates and cold chain infrastructure for ready-to-drink formats, forcing out formulators lacking compliance scale.
For Market Incumbents: Anchor Gulf modern trade shelf presence through aseptic filling capacity expansion in Saudi Eastern Province zones. Defend against plant-based entrants by securing captive fava protein supplies from regional agricultural processors. Prioritize MOHAP digital health integration for diabetic formulation reimbursement pathways.
For New Entrants and Emerging Players: Enter via Nigerian urban fulfillment infrastructure targeting Lagos and Abuja professional classes underserved by specialized nutrition retail. Capture South African township demand through sachet-format credit-extension partnerships with independent distributors. Deploy direct-selling networks as primary customer acquisition channel.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by multinational nutrition conglomerates seeking clinical formulation capabilities and Gulf distribution infrastructure. Long-term viability favors manufacturers with vertical control over halal-certified protein sourcing and SFDA-compliant analytical labs. Watch GCC functional food harmonization talks as regulatory inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Plant-Based Formulation Expansion | Pea and fava protein platforms capture Gulf flexitarian migration away from dairy-dependent supply chains. |
| Direct-to-Consumer Fulfillment Buildout | Lagos and Abuja urban infrastructure targets emerging professional classes outside modern trade reach. |
| Clinical Nutrition Certification Investment | MOHAP and SFDA substantiation requirements open diabetic and metabolic syndrome adjacent demand. |
| Precision Fermentation Pilot Scaling | UAE-based modular protein production decouples margins from European whey import volatility. |
| Halal Certification Streamlining | Unified multi-jurisdictional religious compliance reduces audit timelines for animal-derived protein portfolios. |
Research Methodology
Document review covered SFDA regulatory filings, South African National Health and Nutrition Examination standards, and GCC trade data, complemented by interviews with brand managers at multinational nutrition conglomerates, category buyers at Gulf modern trade retailers, supply planners at regional contract manufacturers, and channel heads at direct-selling organizations. Secondary validation drew from customs records, Nielsen retail audit data, and hospital procurement databases. Bottom-up demand modeling triangulated against top-down macroeconomic indicators.
Historical consumption patterns cross-referenced against panel input from industry stakeholders shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product format, end user archetype, packaging type, ingredient sourcing strategy, and regional regulatory cluster. CAGRs derived from trend extrapolation adjusted for compliance cost absorption and channel migration patterns. Forecast inputs incorporated SFDA reformulation timelines and Nigerian foreign exchange volatility assumptions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under GCC harmonization delays or sustained currency depreciation in import-dependent markets. Projections reflect assumptions around cold chain infrastructure buildout and plant-protein supply scaling. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Food Sources
South American Algae Protein Market
Alternative Food Sources
Global Algae Protein Market
Alternative Food Sources
Sugar Alternative Market
Alternative Food Sources
Monoprotein Market
Alternative Food Sources
Mycoprotein Market
Alternative Food Sources
Mealworms Market
Alternative Food Sources
North America Precision Fermentation Market
Alternative Food Sources
Asia-Pacific Fat Replacers Market
Alternative Food Sources
Global Meal Replacement Shakes Market
Alternative Food Sources
Plant-Based Compound Feed Market
Alternative Food Sources
Fish Meal Alternative Market
Alternative Food Sources
Plant-Based Squalene Market
Alternative Food Sources
Egg Substitutes Market
Alternative Food Sources
Seitan Market
Alternative Food Sources
Africa Potato Protein Market
Alternative Food Sources
Meal Replacement Bars Market