
 Plant-Based Compound Feed Market | 2026-2036
Plant-Based Compound Feed Market Size, Share, and Industry Trends Forecast 2026-2036
Plant-Based Compound Feed Market Insights
Soymeal substitution with sunflower and rapeseed protein concentrates is broadening formulation flexibility for European and North American compounders. Cargill, Incorporated leverages its origination network across the Black Sea and Canadian prairies to secure non-GMO oilseed supplies. Archer Daniels Midland Company sustains crushing capacity advantages in Argentina and the US Midwest. Roquette Frères differentiates through pea protein isolate technology scaled to aquafeed specifications.
Plant-based compound feed denotes nutritionally complete rations formulated from processed legumes, cereal grains, oilseed meals, and agricultural by-products, typically standardized to 16-22% crude protein and 2,800-3,200 kcal/kg metabolizable energy for targeted livestock species. Manufacturers pellet or extrude blends to optimize digestibility and reduce feed conversion ratios in intensive operations. Poultry feed occupies the largest volume share given broiler sector consolidation, while aquafeed registers the fastest structural expansion as salmon and shrimp producers phase out marine-derived meals. Ingredient sourcing from legumes and oilseeds captures margin pools where crushers command forward-contract premiums on identity-preserved supply chains.
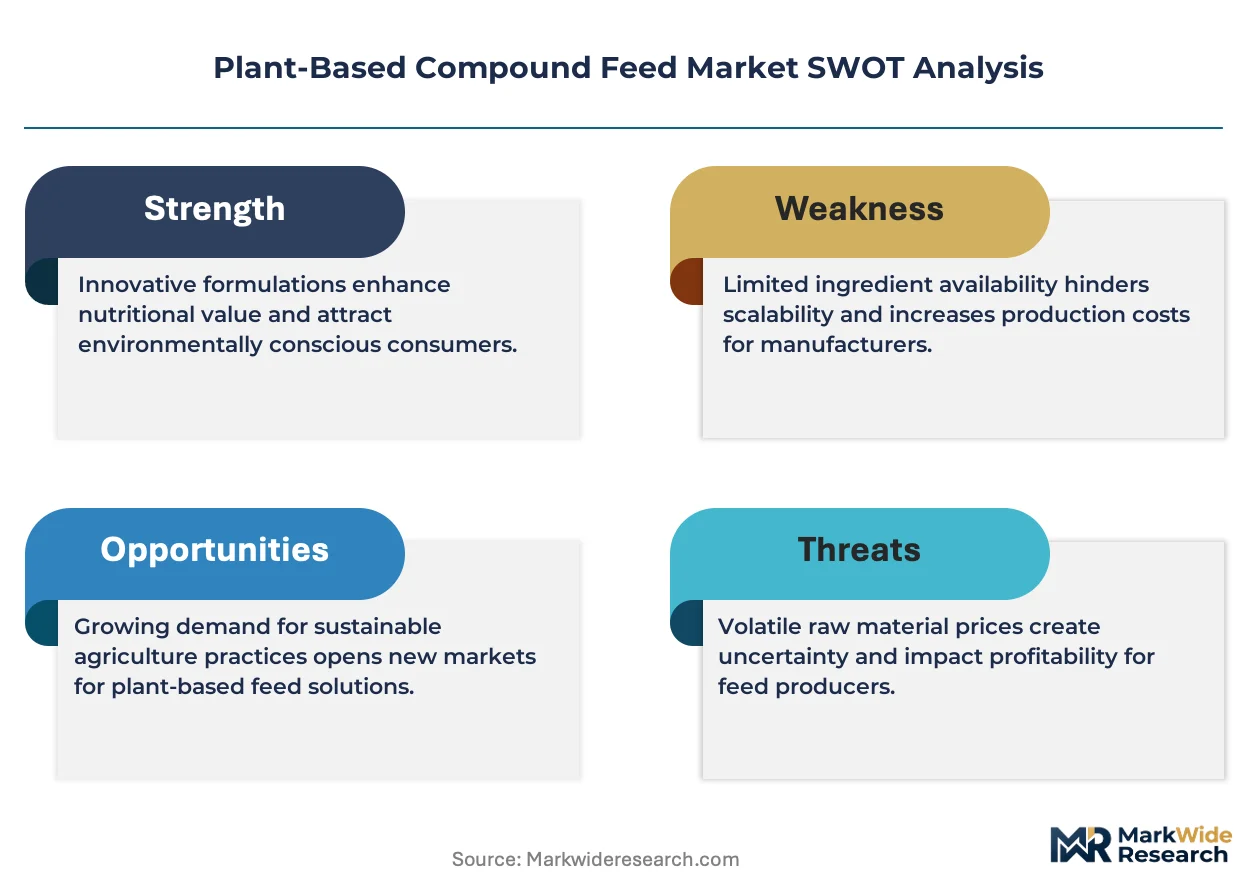
The EU Green Deal and REACH frameworks restrict deforestation-linked soy imports, compelling reformulation toward certified alternative proteins. The US EPA and FDA jointly oversee feed safety under the Food Safety Modernization Act, elevating traceability requirements for mycotoxin control and pathogen mitigation. Brazil's national agricultural regulator enforces sanitary standards on cross-border grain movements, shaping export-oriented feed mill compliance costs. Stakeholders must monitor evolving carbon-accounting methodologies for scope-three emissions tied to crop cultivation and land-use change.
Market Dynamics
The EU Green Deal's Farm to Fork strategy is compressing formulation timelines as compounders scramble to certify deforestation-free supply chains before import restrictions fully activate. This regulatory pressure is converging with integrator demand for price-stable alternatives to volatile soy markets, reshaping procurement architectures across intensive livestock operations.
Growth Catalysts
- EU Deforestation Regulation:Mandatory due diligence on forest-risk commodities is accelerating certified oilseed meal adoption, with compounders in Germany and the Netherlands reformulating rations to maintain market access.
- Aquafeed Protein Transition:Salmon and shrimp producers are phasing out fishmeal inclusion, creating pull-through demand for high-digestibility legume concentrates that match marine protein performance metrics.
- Brazilian Integrator Consolidation:JBS and BRF captive feed-mixing capacity expansion is standardizing plant-based ration specifications across export-grade beef and broiler operations.
Market Restraints
- Sunflower Meal Supply Concentration:Black Sea origination bottlenecks expose European compounders to weather-driven yield volatility and export corridor disruptions.
- Pea Protein Processing Cost:Wet-fractionation energy intensity and capital requirements limit margin expansion for mid-scale compounders without backward integration into crushing assets.
- Amino Acid Imbalance:Rapeseed and sunflower meals require synthetic lysine and methionine supplementation, eroding cost advantages against soymeal in least-cost formulation models.
Strategic Opportunities
- India Poultry Integration:Underpenetrated compound feed penetration in backyard-to-commercial transition zones offers volume expansion for standardized plant-based broiler rations.
- Precision Fermentation Convergence:Microbial protein production is converging with conventional oilseed processing, enabling novel ingredient streams that bypass agricultural land-use constraints entirely.
- Carbon Accounting Differentiation:EU CSRD scope-three disclosure requirements create premium positioning for compounders with verified low-cultivation-emission supply chains.
Industry Challenges
- Formulation Chemist Scarcity:Talent pipelines for amino acid optimization and anti-nutritional factor mitigation lag behind reformulation velocity demands.
- Identity-Preserved Segregation Costs:Non-GMO and organic certification require parallel handling infrastructure, compressing margins at toll-mixing facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plant-Based Compound Feed Market |
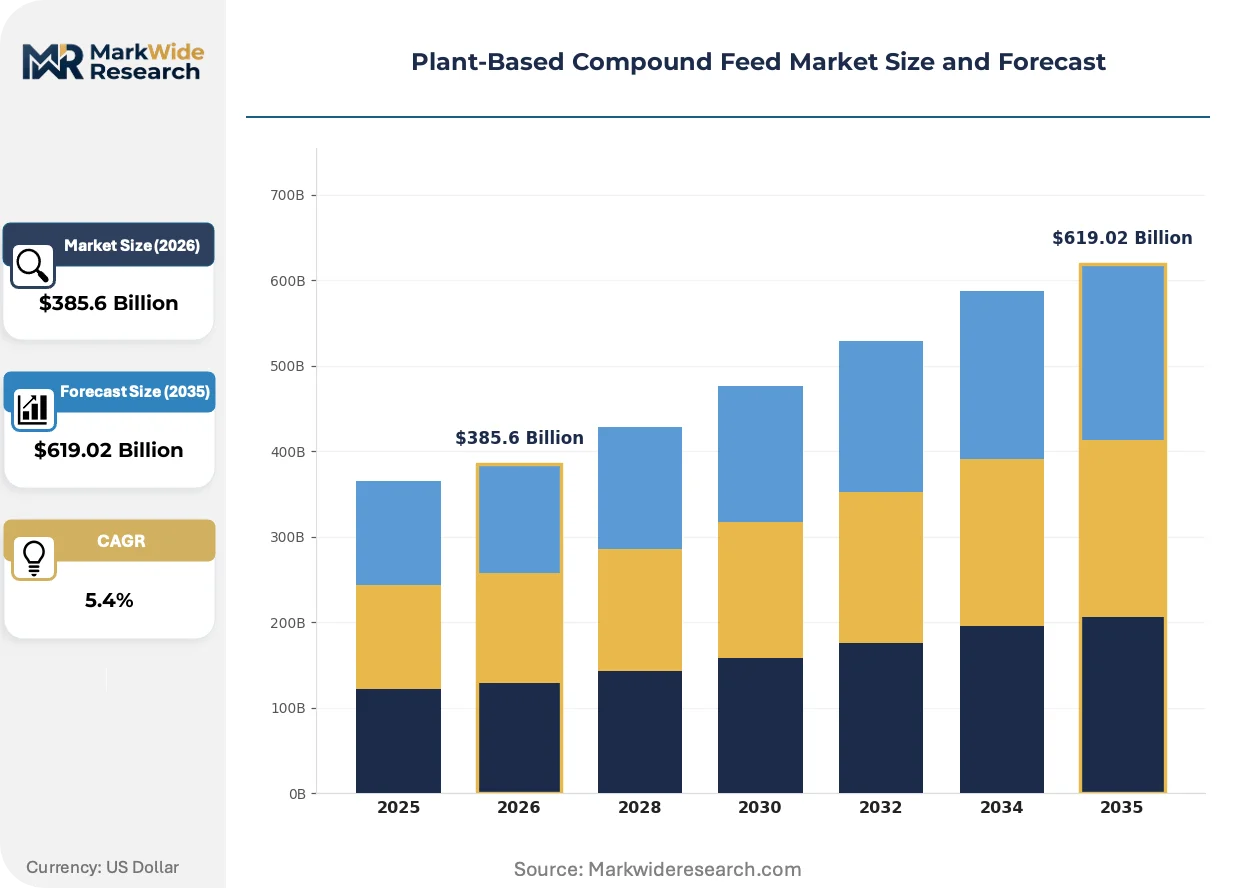
| Market Size in 2026 | $385.6 Billion |
| Market Size in 2035 | $619.02 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Poultry Feed, Aquafeed, Ruminant Feed, Swine Feed Ingredient Source: Legumes, Grains, Oilseeds, By-products End User: Farmers, Feed Manufacturers, Distributors, Livestock Owners Packaging Type: Bags, Bulk, Customized Containers, Totes |
| Companies Covered | Cargill, Incorporated, Archer Daniels Midland Company, Roquette Frères, Glanbia PLC, Ingredion Incorporated, Hamlet Protein, Emsland Group, A&B Ingredients Inc., HL Agro Products Pvt. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plant-Based Compound Feed Market Trends and Innovations
Ingredient processing technology and regulatory compliance architectures are diverging from commodity feed paradigms toward precision-formulation platforms. This shift is compressing traditional cost-plus pricing models while elevating technical service intensity.
Extruded pea protein concentrate is converging with aquafeed extrusion systems, enabling salmon producers in Norway to replace 30-40% of fishmeal without digestibility penalties. Marine Harvest and Lerøy are retrofitting feed mills to handle higher-inclusion legume matrices. This convergence is displacing traditional soy-fishmeal binary formulations in premium salmon segments.
REACH and EU Green Deal due diligence frameworks are mandating geolocation verification for oilseed imports, forcing compounders to deploy satellite-based traceability systems. German and Danish feed groups are pre-certifying Brazilian and Argentinian suppliers to avoid customs detention. Poultry integrators with export exposure to EU retail channels face the steepest compliance cost escalation.
Direct contracting between meatpackers and oilseed crushers is displacing spot-market procurement for protein meals. JBS and Marfrig are negotiating multi-year rapeseed and sunflower meal offtakes with Black Sea and Canadian originators. This pattern is most visible in Brazil, where vertical coordination locks in margin visibility for both crushing and feed-mixing operations.
Plant-Based Compound Feed Market Segmentation
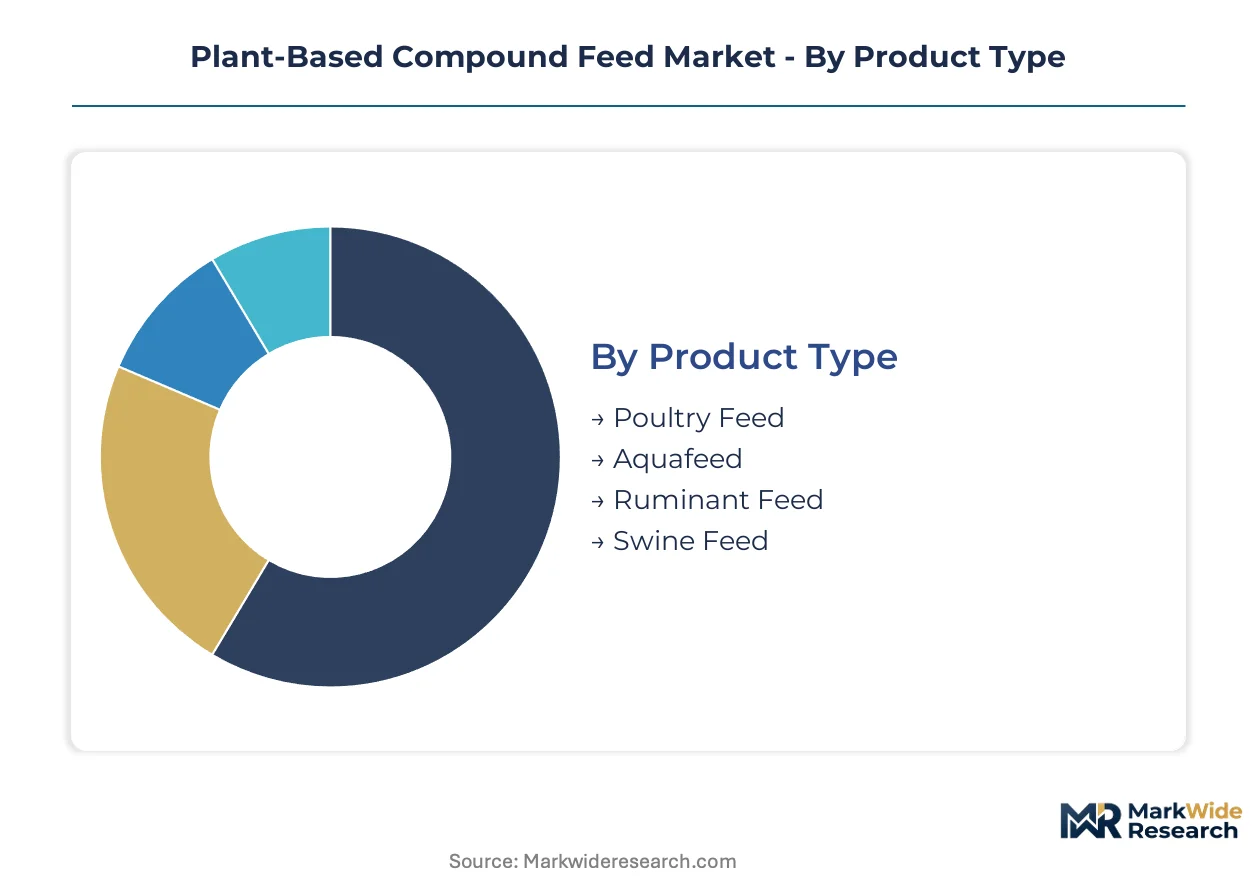
Feed buyers prioritize species-specific nutritional performance, ingredient traceability, and procurement flexibility when selecting plant-based compound feed. Segmentation reveals how formulation chemistry, supply chain architecture, and end-use intensity create distinct margin pools across the value chain.
Product Type:
Poultry integrators and aquaculture operators drive the steepest volume differentials based on feed conversion efficiency targets and export certification requirements.
- Poultry Feed:Standardized to 18-20% crude protein with lysine-methionine balancing for broiler operations. Brazilian integrators JBS and BRF specify deforestation-free soy alternatives to maintain EU retail channel access. This segment commands the largest volume share given broiler sector consolidation across Southeast Asia and Latin America.
- Aquafeed:High-digestibility extruded formulations replacing 30-40% of fishmeal in Norwegian salmon operations. Marine Harvest and Lerøy retrofit mills to handle pea protein concentrates that match marine protein performance metrics. This segment gains share fastest as marine-derived meal phase-out accelerates.
- Ruminant Feed:Fiber-optimized blends incorporating oilseed meals and agricultural by-products for dairy and beef finishing operations. EU Green Deal methane reduction targets pressure reformulation toward lower-fermentation feed matrices.
- Swine Feed:Energy-dense formulations with standardized amino acid profiles for intensive farrow-to-finish systems. Chinese and Vietnamese pork producers drive procurement of cost-stable legume alternatives to volatile soy markets.
Poultry Feed leads on scale; Aquafeed leads on momentum.
Ingredient Source:
Procurement teams weight cost stability, anti-nutritional factor profiles, and carbon accounting verifiability when selecting raw material categories.
- Legumes:Pea and faba bean protein concentrates processed through wet-fractionation for aquafeed and premium poultry specifications. Roquette Frères scales isolate technology to match salmon digestibility requirements. Black Sea and Canadian originators command forward-contract premiums on identity-preserved supply chains.
- Oilseeds:Rapeseed and sunflower meals displacing soymeal in EU compounders facing deforestation regulation deadlines. Cargill leverages origination networks across the Black Sea and Canadian prairies to secure non-GMO supplies. REACH and EU Green Deal due diligence frameworks mandate geolocation verification for import certification.
- Grains:Wheat and corn derivatives providing metabolizable energy density in least-cost formulation models. US Midwest and Argentine crushers sustain capacity advantages in starch-protein separation.
- By-products:Wheat middlings, rice bran, and distillers grains capturing margin pools in ruminant and swine rations. Brazilian meatpackers vertically integrate into agricultural residue processing to lock in feed-mixing cost visibility.
Oilseeds concentrate reformulation investment; Legumes capture the steepest expansion trajectory.
End User:
Technical service intensity and volume scale separate procurement behaviors across customer archetypes.
- Feed Manufacturers:Toll-mixing facilities requiring formulation flexibility and rapid certification turnaround for private-label integrator contracts. German and Dutch compounders deploy satellite-based traceability systems to pre-certify Brazilian and Argentinian suppliers.
- Farmers:Small-to-mid scale operations prioritizing price-stable procurement and local distributor relationships. India's backyard-to-commercial poultry transition zones offer volume expansion for standardized broiler rations.
- Livestock Owners:Intensive operations with captive feed-mixing capacity negotiating direct oilseed crusher contracts. JBS and Marfrig structure multi-year rapeseed and sunflower meal offtakes with Black Sea originators.
- Distributors:Regional logistics networks managing inventory risk across seasonal demand cycles. Identity-preserved segregation requirements compress margins at facilities without parallel handling infrastructure.
Feed Manufacturers concentrate technical investment; Livestock Owners drive direct procurement restructuring.
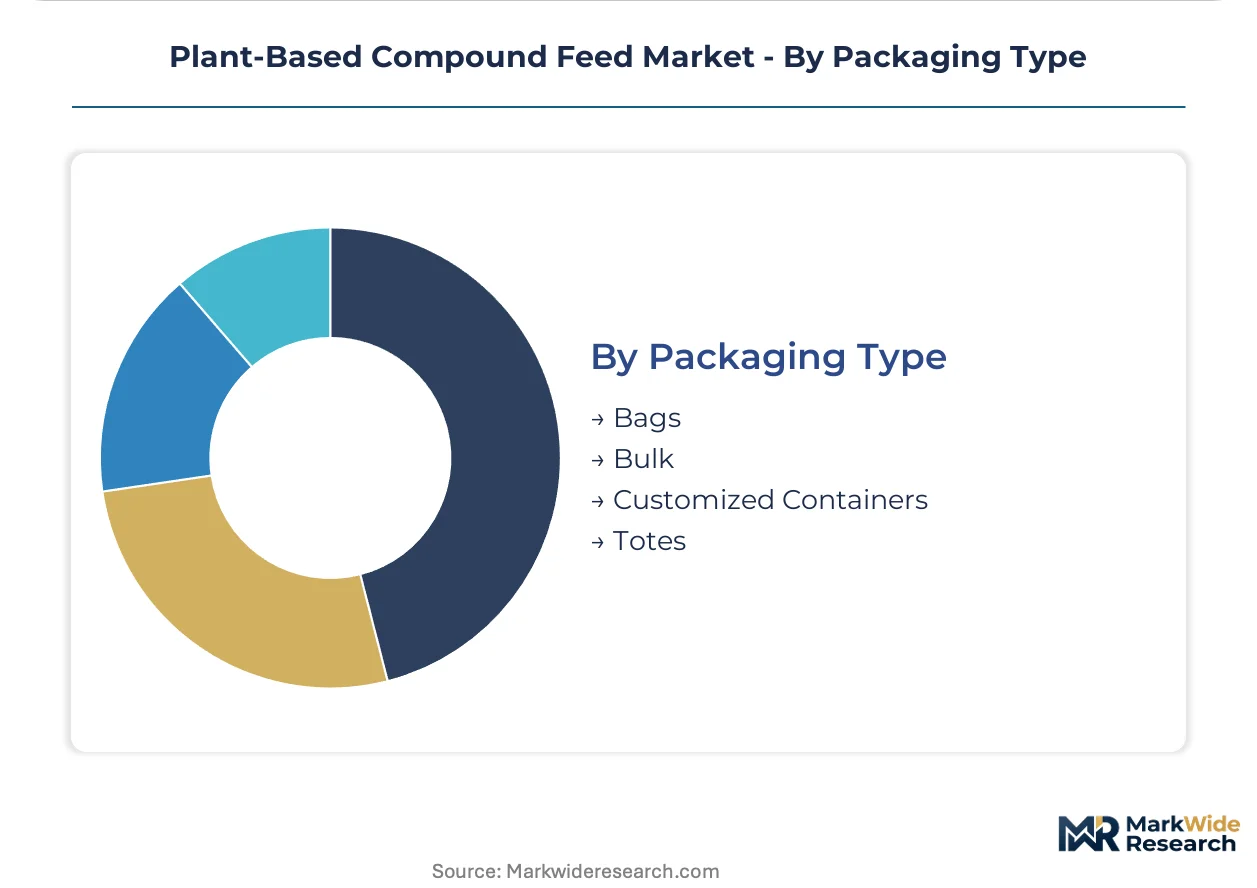
Packaging Type:
Logistics economics and contamination risk separate procurement preferences across handling formats.
- Bulk:Unpackaged delivery to captive feed mills and large-scale integrators minimizing per-unit handling costs. Brazilian integrated meatpackers standardize bulk reception for export-grade beef and broiler operations.
- Bags:25-50kg woven polypropylene for smallholder and mid-scale farm direct delivery. Non-GMO and organic certification requirements elevate packaging traceability specifications.
- Totes:Intermediate bulk containers for specialty aquafeed and precision-formulation rations requiring moisture control. Norwegian salmon producers specify tote delivery for high-value legume concentrate handling.
- Customized Containers:Client-specified formats for pharmaceutical-grade feed additives and probiotic-enhanced formulations. REACH frameworks elevate pathogen mitigation and mycotoxin control documentation.
Bulk dominates volume throughput; Customized Containers capture premium positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's integrated meatpackers anchor procurement restructuring as JBS and BRF expand captive feed-mixing capacity to supply export-grade beef and broiler operations. Demand concentrates across four additional national markets where regulatory pressure and integrator consolidation reshape formulation chemistry.
United States
Poultry integrators in the Southeast and Midwest drive soy-alternative procurement to reduce input cost volatility. The FDA and EPA jointly oversee feed safety under the Food Safety Modernization Act, elevating traceability requirements for mycotoxin control. Iowa and Arkansas host the densest concentration of toll-mixing facilities serving consolidated broiler operations.
Germany
Compounders scramble to certify deforestation-free supply chains before EU Green Deal import restrictions fully activate. REACH and ECHA frameworks mandate geolocation verification for oilseed imports, forcing satellite-based traceability system deployment. The Lower Saxony cluster hosts reformulation laboratories serving Dutch and Danish integrators.
India
Backyard-to-commercial poultry transition zones in Maharashtra and Telangana offer volume expansion for standardized plant-based broiler rations. FSSAI and BIS enforce sanitary standards on cross-border grain movements, shaping compliance costs for imported oilseed meals. Gujarat's crushing capacity expansion supports domestic protein concentrate supply.
Norway
Salmon producers Marine Harvest and Lerøy retrofit feed mills to handle pea protein concentrates replacing fishmeal. The Norwegian Food Safety Authority enforces strict residue monitoring on novel ingredient streams. Bergen and Trondheim anchor aquafeed technology clusters driving marine protein phase-out.
Argentina
Crushers sustain capacity advantages in soybean and sunflower processing for export-oriented protein meal supply. The national agricultural regulator enforces sanitary certification on cross-border grain movements. Rosario and Buenos Aires concentrate oilseed origination infrastructure serving Brazilian and European compounders.
Plant-Based Compound Feed Market Competitive Landscape
Global majors compete with regional champions across origination networks and formulation technology tiers. The vendor base separates into three strategic archetypes: integrated agribusiness traders commanding crushing assets, specialized protein processors scaling isolate technology, and toll-mixing facilities serving private-label integrator contracts. M&A activity concentrates on backward integration into oilseed crushing, while capacity expansion targets aquafeed-extrusion system retrofits.
Among North American agribusiness giants, Cargill, Incorporated and Archer Daniels Midland Company occupy positions anchored by origination networks across the Black Sea, Canadian prairies, and US Midwest. European specialists include Roquette Frères, a French processor exemplifying the pea protein isolate technology tier scaled to aquafeed specifications. These three companies represent the dominant competitive vectors: trader-crusher integration, regional origination dominance, and novel protein processing specialization.
| Leading Market Players |
|---|
| Cargill, Incorporated |
| Archer Daniels Midland Company |
| Roquette Frères |
| Glanbia PLC |
| Ingredion Incorporated |
| Hamlet Protein |
| Emsland Group |
| A&B Ingredients Inc. |
| HL Agro Products Pvt. Ltd. |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-cap compounders across Northern Europe anchor procurement discipline through multi-generational supplier relationships that buffer spot-market volatility while compressing margin pools for toll-mixing facilities without backward crushing assets. This ownership pattern concentrates pricing power among crushers with captive origination networks, forcing independent compounders into forward-contract premiums or reformulation toward lower-cost legume matrices.
Pricing Analysis
Input-cost pass-through from Black Sea sunflower and Canadian rapeseed origination governs compounder procurement economics, with crushers commanding forward-contract premiums on identity-preserved supply chains. Price differentiation stratifies across premium certified tiers (EU Green Deal-compliant), standard commercial grades, and economy spot-market lots. Pricing pressure intensifies as synthetic amino acid supplementation erodes cost advantages against soymeal in least-cost models. Smallholder distributors in India exhibit highest price sensitivity; Norwegian salmon integrators demonstrate lowest sensitivity given marine protein phase-out mandates.
Supply Chain Analysis
EU Green Deal domestic-content mandates and India's PLI scheme for oilseed processing are reshaping sourcing architectures toward regional crushing capacity expansion. Supply concentration centers on Brazil, Argentina, and the Black Sea basin for protein meal origination. Raw material dependencies rest on sunflower seeds, rapeseed, and pea protein concentrates. Single-source vulnerability runs through Black Sea export corridor disruptions. Distribution feeds from integrated meatpacker captive mills toward toll-mixing facilities and regional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EU Deforestation Regulation deadlines compress formulation timelines and elevate certified supply chain investment returns.
For Market Incumbents: Extend crushing capacity advantages through multi-year offtake structures with Black Sea and Canadian originators that lock in margin visibility against spot volatility. Deepen backward integration into pea protein isolate technology to defend positioning against precision fermentation substitutes. Prioritize satellite-based traceability system deployment to pre-certify suppliers before REACH enforcement intensifies.
For New Entrants and Emerging Players: Digital-channel direct contracting platforms offer low-friction entry into India's backyard-to-commercial poultry transition zones where standardized broiler rations face underpenetrated demand. Target Maharashtra and Telangana integrators with private-label formulation services. Pursue toll-mixing partnerships with German compounders seeking rapid certification turnaround.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale toll-mixing facilities without crushing assets, where margin compression from identity-preserved segregation costs creates distressed entry points. Long-term viability favors compounders with verified low-cultivation-emission supply chains aligned to EU CSRD scope-three disclosure requirements. Monitor precision fermentation scale-up announcements as inflection signal for conventional oilseed processing obsolescence risk.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Crushing Assets | JBS and Marfrig structures lock in rapeseed meal cost visibility across Brazilian feed-mixing operations. |
| Aquafeed Extrusion System Retrofit | Marine Harvest and Lerøy mill conversions enable 30-40% fishmeal replacement with pea protein concentrates. |
| Satellite-Based Traceability Deployment | German compounders pre-certify Brazilian suppliers to avoid EU Green Deal customs detention risks. |
| Multi-Year Oilseed Meal Offtake Negotiation | Black Sea originators secure forward-contract premiums on identity-preserved non-GMO supply chains. |
| Pea Protein Isolate Technology Scale-Up | Roquette Frères aquafeed specifications match salmon digestibility requirements displacing marine meals. |
Research Methodology
Direct dialogue with compounder procurement directors, oilseed crusher operations managers, aquafeed mill engineers, and EU regulatory affairs specialists grounded qualitative insights in operational reality. Secondary validation drew from EFSA feed safety assessments, EU Deforestation Regulation implementation guidance, Brazilian agricultural export certification databases, and Norwegian Food Safety Authority residue monitoring protocols. Bottom-up volume modeling across species-specific formulation tiers triangulated against top-down crushing capacity and trade flow analysis.
Segmentation outputs across poultry, aquafeed, ruminant, and swine species channels combined with ingredient-source splits by legumes, oilseeds, grains, and by-products generated granular demand projections across the analysis window. CAGRs derived from historical trade flow elasticity and regulatory compliance cost absorption rates. Key inputs included Black Sea sunflower yield variance, synthetic amino acid price indices, and salmon producer fishmeal substitution curves.
The model assumes a particular technology adoption path; alternative pathways for precision fermentation protein production would alter the outlook toward accelerated conventional oilseed processing displacement. Forecasts reflect assumptions around EU Green Deal enforcement timelines and Brazilian integrator captive capacity expansion. A small set of triggers—Black Sea export corridor stability, pea protein wet-fractionation energy cost trajectories, and EU CSRD audit standard finalization—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Food Sources
Precision Fermentation Market
Alternative Food Sources
South American Algae Protein Market
Alternative Food Sources
Flaxseed Based Egg Replacement Market
Alternative Food Sources
Vegan Ham Market
Alternative Food Sources
Seaweed Protein Market
Alternative Food Sources
Organic Gluten Substitutes Market
Alternative Food Sources
Carragean Alternatives Market
Alternative Food Sources
Meal Replacement Bars Market
Alternative Food Sources
Gluten Substitute Market
Alternative Food Sources
Vegetable Proteins Market
Alternative Food Sources
Hemp-Based Products Market
Alternative Food Sources
North America Meal Products Replacement Market
Alternative Food Sources
Global Meal Replacement Shakes Market
Alternative Food Sources
Monoprotein Market
Alternative Food Sources
Meat Alternative Market
Alternative Food Sources
Fat Substitutes Market