
 Global Predictive and Presymptomatic Testing Market | 2026-2036
Global Predictive and Presymptomatic Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Global Predictive and Presymptomatic Testing Market Intelligence
The European Union's Corporate Sustainability Reporting Directive (CSRD) is shifting healthcare provider focus toward preventative care models that reduce the long-term resource burden of treating chronic disease. Illumina dominates the technology-supply side with its foundational Next-Generation Sequencing platforms. Myriad Genetics specializes in hereditary cancer risk testing, while Quest Diagnostics leverages its extensive network of diagnostic laboratories for unmatched market access.
Predictive and presymptomatic testing analyzes genetic material or biomarkers to determine an individual's risk of developing a disease before symptoms appear. The process utilizes Next-Generation Sequencing to identify specific mutations, enabling proactive health management and clinical intervention. Cancer Susceptibility testing leads the application segments, while Neurological Risk Assessment for conditions like Alzheimer's is an area of rapid development. Diagnostic Labs and Specialized Medical Centers form the core end-user base, processing the majority of complex tests.
Regulatory oversight from bodies like the U.S. Food and Drug Administration (FDA) and the European Union under its Medical Device Regulation (MDR) governs test accuracy and clinical validation. Data privacy is a critical compliance layer, enforced by frameworks such as HIPAA in the United States and GDPR in Europe. Future success depends on navigating the complex ethical considerations and disparate reimbursement policies that differ significantly by country.
Market Dynamics
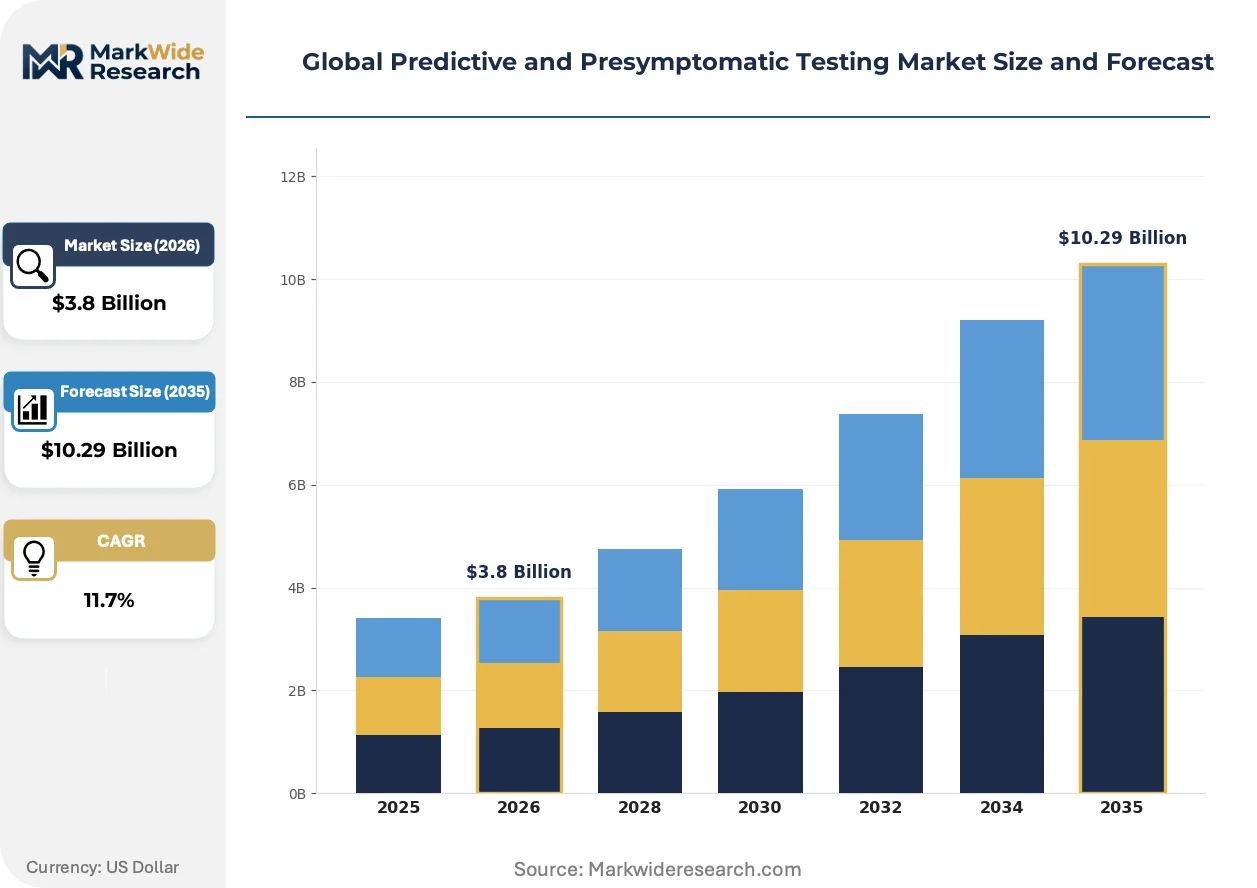
The central dynamic shaping the market is the convergence of rapidly falling Next-Generation Sequencing costs with the clinical imperative for earlier disease detection. This combination enables large-scale population screening programs, particularly for cancer susceptibility, shifting the focus from treatment to prevention.
Growth Catalysts
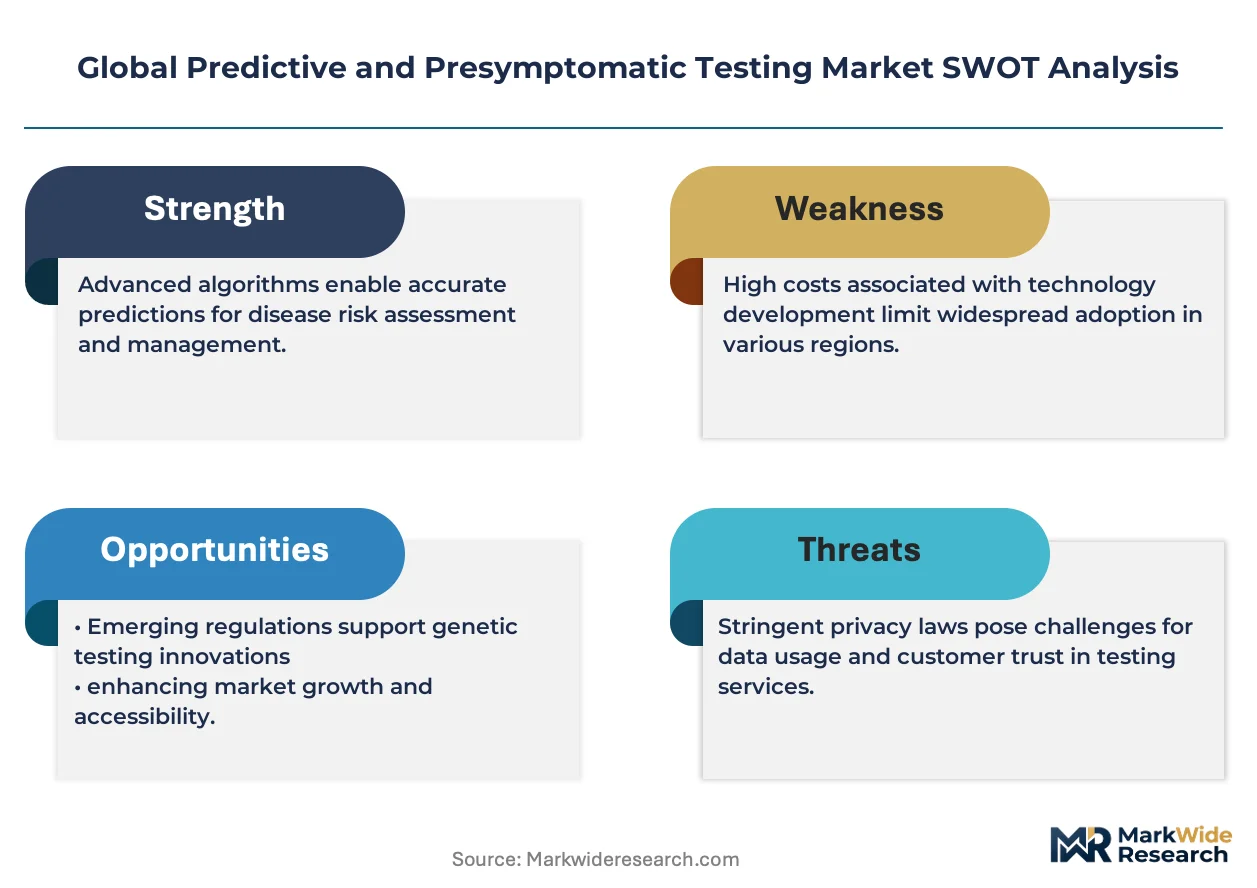
- Preventative Care Mandates:The European Union's Corporate Sustainability Reporting Directive (CSRD) incentivizes corporate wellness programs and preventative health, creating a pull for predictive testing services that can demonstrate long-term healthcare cost reduction.
- NGS Technology Accessibility:Continuous improvements in the speed and cost-efficiency of Next-Generation Sequencing platforms make genetic testing more affordable for both diagnostic labs and individual consumers, broadening market access beyond specialized research centers.
- Expanded Clinical Applications:The successful application of predictive testing in oncology is creating a model for expansion into other complex disease areas, with Neurological Risk Assessment for conditions like Alzheimer's representing the fastest-growing new segment.
Market Restraints
- Reimbursement Disparities:Inconsistent and fragmented reimbursement policies for presymptomatic testing across different countries and private insurers create significant financial uncertainty for labs and limit patient access, especially in markets without clear national guidelines.
- Data Privacy Compliance:The stringent requirements of regulations like HIPAA in the United States and GDPR in Europe impose significant compliance costs and complexities related to the storage, sharing, and security of sensitive patient genetic data.
- Clinical Validation Hurdles:Gaining regulatory approval from bodies like the FDA or achieving CE marking under the EU's MDR requires extensive and costly clinical validation studies to prove a test's analytical accuracy and clinical utility, slowing market entry for new diagnostics.
Strategic Opportunities
- Pharmacogenomic Integration:There is a significant opportunity to expand testing beyond disease risk into pharmacogenomics, which analyzes how an individual's genes affect their response to specific drugs, enabling personalized medicine and optimizing treatment efficacy.
- Emerging Market Penetration:Markets in parts of Asia-Pacific with rising healthcare expenditure and a growing middle class present untapped opportunities for providers of predictive testing services, particularly for hereditary cancers prevalent in those populations.
- AI-Powered Interpretation:Integrating artificial intelligence and machine learning algorithms with NGS data analysis can enhance the accuracy of risk prediction, identify novel biomarkers, and automate the interpretation of complex genetic variants, creating a significant competitive advantage.
Industry Challenges
- Specialized Talent Shortage:A critical bottleneck is the scarcity of qualified bioinformaticians and genetic counselors who are essential for accurately interpreting complex genomic data and communicating nuanced risk information to patients and physicians.
- Lack of Data Standardization:The absence of universally accepted standards for data formatting, analysis pipelines, and clinical reporting among different laboratories can lead to variability in test results and complicates data sharing for research purposes.
- EHR System Integration:A persistent operational challenge is the difficulty of integrating complex genomic data reports into the existing Electronic Health Record (EHR) systems used by hospitals, which hinders the seamless incorporation of genetic insights into routine clinical workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Predictive and Presymptomatic Testing Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.29 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Test Type: Genetic Screening, Biomarker Detection, Molecular Analysis, Blood Biometrics, Protein Profiling Application: Chronic Disorder Forecasting, Neurological Risk Assessment, Cancer Susceptibility, Cardiovascular Prediction, Metabolic Condition Evaluation End User: Diagnostic Labs, Research Institutes, Personal Health Clinics, Specialized Medical Centers, Counseling Services Technology: Next-Generation Sequencing, PCR Amplification, Microarray Technologies, Mass Spectrometry, CRISPR-based Methods |
| Companies Covered | 23andMe, Abbott Laboratories, Quest Diagnostics, Myriad Genetics, Veracyte, Illumina, Positive Bioscience, Color Genomics, Ambry Genetics Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Predictive and Presymptomatic Testing Market Strategic Shifts & Innovations
The market's evolution is defined by the transition from purely academic discovery to scalable, clinically integrated workflows. This shift is driven by software advancements that manage data complexity and by clearer regulatory pathways that provide a framework for commercialization.
AI-powered variant interpretation software is a critical technological development, designed to analyze the vast datasets produced by Next-Generation Sequencing. Diagnostic labs and specialized medical centers are rapidly adopting these platforms to manage increasing test volumes and reduce turnaround times. This software is automating the identification of pathogenic mutations, which was previously a manual and expertise-intensive task, thereby increasing laboratory throughput and consistency.
Regulatory frameworks are solidifying around genetic diagnostics, providing clearer commercialization pathways. The European Union's Medical Device Regulation (MDR) now classifies many predictive tests as in-vitro diagnostic devices, demanding rigorous proof of clinical validity and performance. Test developers targeting the EU are most affected, as they must now invest significantly in clinical trials to obtain and maintain the required CE marking for market access.
Consumer and clinician behavior is moving from single-gene analysis toward comprehensive panel testing as a first-line diagnostic approach. This pattern disrupts the traditional, sequential testing model that was often triggered by existing symptoms, with providers now ordering broad panels for cancer or neurological risk preemptively. This trend is most prominent in advanced healthcare systems like the United States, supported by evolving clinical guidelines and more favorable reimbursement structures for multi-gene panels.
Global Predictive and Presymptomatic Testing Market Segmentation
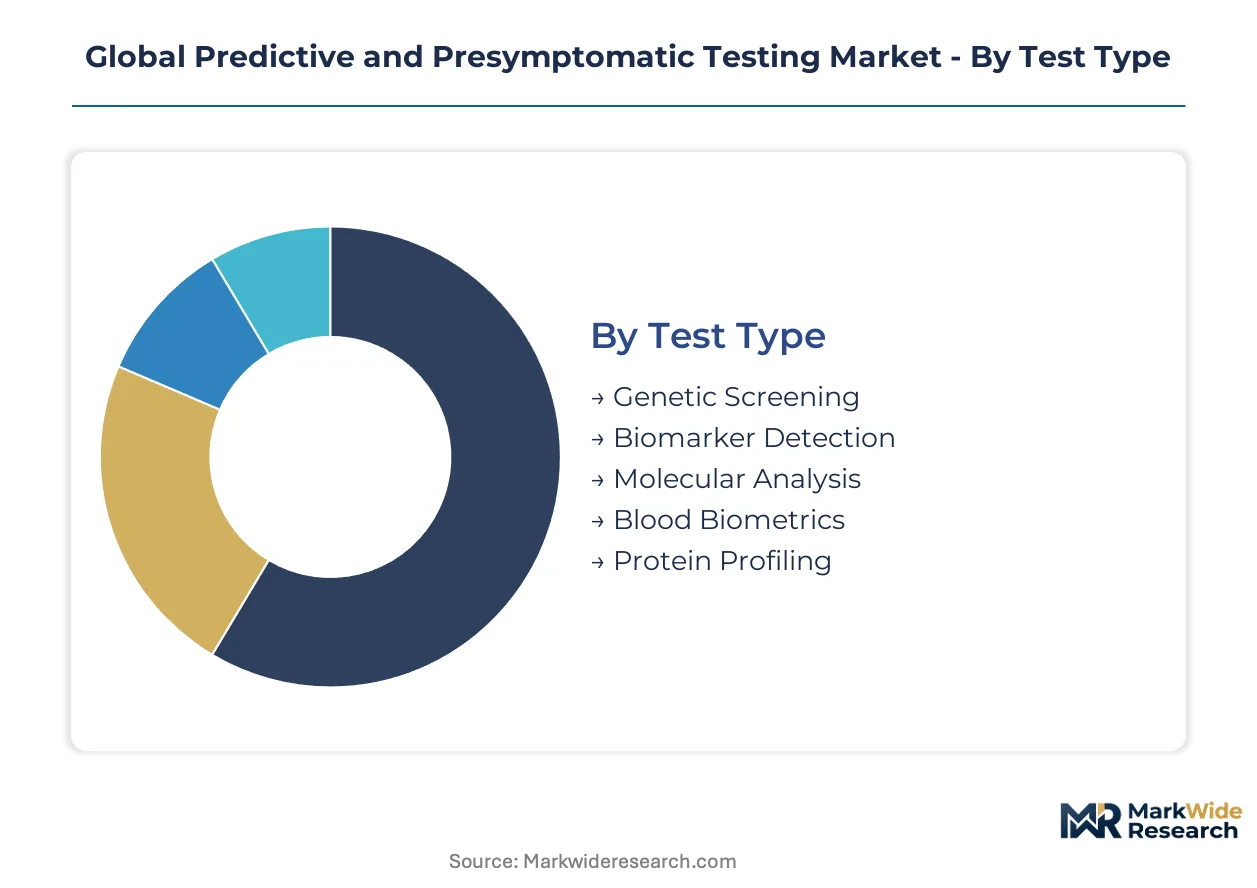
The predictive and presymptomatic testing market categorizes its diverse offerings to address specific clinical needs and technological capabilities. Understanding these segments clarifies the market's structure and highlights areas of concentrated demand and innovation across different user groups.
Test Type:
Predictive tests integrate into clinical workflows at varying depths, from standalone diagnostic panels to embedded components of comprehensive health management systems.
- Genetic Screening:This test type analyzes an individual's DNA to identify predispositions to genetic conditions or carrier status for inherited diseases. Demand concentrates in specialized medical centers, driven by increased awareness of hereditary cancer risks and proactive health management.
- Molecular Analysis:Molecular analysis examines biomolecules like DNA, RNA, and proteins to detect specific mutations, gene expressions, or pathogen presence. This method sees significant demand from diagnostic labs for complex disease identification and risk stratification in oncology.
- Biomarker Detection:This involves identifying specific biological indicators in blood or tissue that signal disease risk or progression.
- Blood Biometrics:Blood biometrics refers to measuring various components in blood samples to assess physiological health and disease predisposition.
- Protein Profiling:This technique analyzes the proteome to identify specific protein patterns associated with disease states or increased future risk.
Genetic Screening leads volumes today; Molecular Analysis is gaining share fastest.
Application:
Applications for predictive testing delineate distinct clinical areas, each addressing unique patient populations and disease burdens through targeted risk assessment.
- Cancer Susceptibility:This application identifies genetic mutations that increase an individual's risk of developing specific cancers, such as BRCA1/2 for breast and ovarian cancer. Demand for these tests is significant in the United States, supported by favorable reimbursement policies and growing clinician adoption.
- Neurological Risk Assessment:This segment evaluates genetic markers and biomarkers associated with neurological conditions like Alzheimer's disease or Parkinson's. Rapid development in this area is driven by an aging global population and the imperative for early intervention strategies.
- Chronic Disorder Forecasting:This involves predicting the likelihood of developing long-term conditions such as diabetes or autoimmune diseases based on genetic predispositions.
- Cardiovascular Prediction:Cardiovascular prediction uses genetic and biomarker data to assess an individual's risk for heart disease, stroke, or other circulatory conditions.
- Metabolic Condition Evaluation:This application focuses on identifying genetic factors influencing metabolic disorders, including obesity, type 2 diabetes, and lipid abnormalities.
Cancer Susceptibility represents the most established application; Neurological Risk Assessment exhibits the steepest expansion trajectory.
End User:
End users for predictive testing span a range of healthcare providers and research entities, each integrating these diagnostics into their unique operational models and patient care pathways.
- Diagnostic Labs:These facilities process the majority of complex predictive tests, leveraging high-throughput Next-Generation Sequencing platforms and advanced bioinformatics. Diagnostic labs in the United States benefit from robust infrastructure and high consumer health engagement, driving significant test volumes.
- Specialized Medical Centers:These centers integrate predictive testing into comprehensive patient care, particularly for oncology and rare disease management, offering genetic counseling and clinical intervention. European specialized centers are increasingly adopting these tests due to preventative care mandates from directives like CSRD.
- Research Institutes:Research institutes utilize predictive testing for cohort studies, biomarker discovery, and the development of novel diagnostic assays.
- Personal Health Clinics:These clinics offer direct-to-consumer or physician-ordered predictive tests for personalized wellness and early disease risk identification.
- Counseling Services:Genetic counseling services provide interpretation of complex genetic results and guide patients through implications for family planning and health management.
Diagnostic Labs and Specialized Medical Centers collectively form the foundational end-user base; Personal Health Clinics are driving increased patient accessibility.
Technology:
Technologies underpinning predictive testing vary significantly in their maturity, cost-efficiency, and analytical depth, influencing their widespread adoption and specific clinical utility.
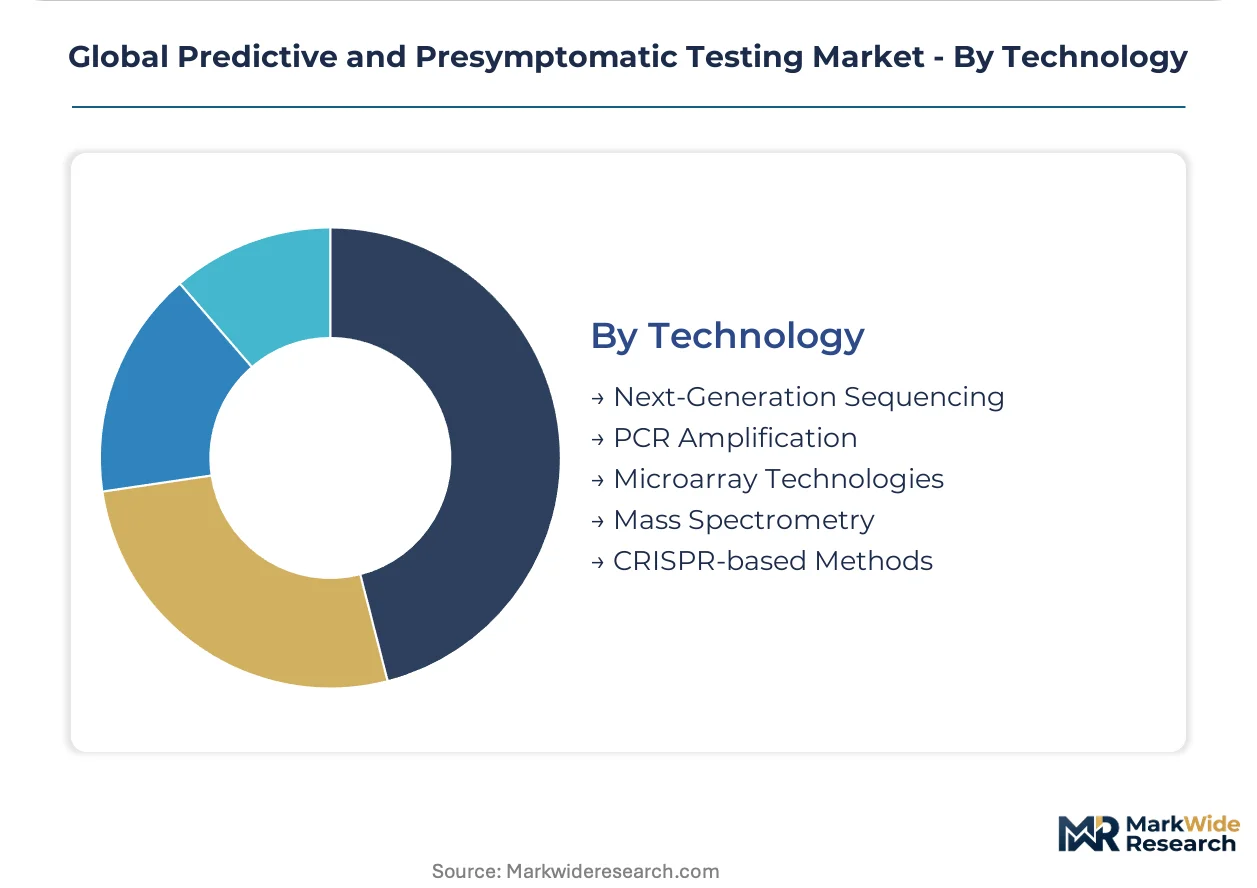
- Next-Generation Sequencing:NGS platforms enable rapid and cost-effective sequencing of entire genomes or targeted gene panels, identifying disease-associated mutations with high precision. Illumina dominates the supply side, facilitating broader population screening programs due to decreasing costs.
- CRISPR-based Methods:These advanced gene-editing technologies are being explored for highly precise and rapid detection of specific genetic variants, offering potential for point-of-care diagnostics. Research in the United States and Europe is rapidly advancing CRISPR's diagnostic capabilities for future clinical use.
- PCR Amplification:Polymerase Chain Reaction amplifies specific DNA sequences for detection, remaining a foundational technology for targeted genetic analysis.
- Microarray Technologies:Microarrays allow for simultaneous analysis of thousands of genetic variations, useful for gene expression profiling and copy number variation detection.
- Mass Spectrometry:Mass spectrometry identifies and quantifies biomolecules, playing a role in protein profiling and metabolite analysis for biomarker discovery.
Next-Generation Sequencing remains the core technological enabler; CRISPR-based Methods represent a significant innovation frontier.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global predictive and presymptomatic testing market gained foundational traction from breakthroughs in genomic sequencing technologies. The United States notably scaled the clinical application of these advancements, establishing early leadership in diagnostic infrastructure. This expansion continues to drive market evolution across diverse international healthcare systems.
United States
The United States market demonstrates robust demand for predictive testing, driven by advanced diagnostic lab infrastructure and high consumer health engagement. Favorable reimbursement policies from private insurers and government programs like Medicare support broader test utilization. Major biotech clusters in Boston and the San Francisco Bay Area actively develop and commercialize novel genetic assays.
Germany
Germany's healthcare system prioritizes preventative care, with demand for predictive testing influenced by directives like the EU's CSRD. Rigorous regulatory oversight under the EU's Medical Device Regulation (MDR) ensures high standards for test accuracy and clinical validity. Specialized medical centers in regions like Munich and Heidelberg integrate advanced genetic diagnostics into patient management.
Japan
Japan's aging population fuels demand for early disease detection, particularly for neurological conditions and chronic disorders. The Pharmaceuticals and Medical Devices Agency (PMDA) regulates genetic tests, ensuring their safety and efficacy within the national healthcare system. Major medical research institutions in Tokyo and Kyoto actively contribute to biomarker discovery and clinical application.
China
China presents a significant emerging market opportunity for predictive testing, characterized by rising healthcare expenditure and a growing middle class. The National Medical Products Administration (NMPA) oversees test approvals, aligning with national health initiatives to improve population health. Genomics companies and diagnostic service providers in Shanghai and Shenzhen are rapidly expanding their offerings.
Global Predictive and Presymptomatic Testing Market Key Industry Players
Capital-heavy producers like Illumina compete with asset-light diagnostic service providers in the predictive and presymptomatic testing market. This structure creates distinct archetypes: foundational technology innovators, specialized genetic testing laboratories, and broad diagnostic network operators. Companies pursue strategic partnerships, technology licensing, and geographic expansion to solidify their market positions. Portfolio diversification into new clinical applications also represents a key competitive move.
Specialized genetic testing laboratories, such as Myriad Genetics, exemplify companies focusing on niche areas like hereditary cancer risk assessment. These firms leverage deep clinical expertise and targeted assay development. Illumina represents the foundational technology provider, supplying Next-Generation Sequencing platforms essential for complex genetic analysis across the industry. Broad diagnostic network operators like Quest Diagnostics leverage extensive infrastructure to provide widespread market access for predictive tests, integrating them into routine clinical workflows. These diverse players collectively advance the market through distinct operational models.
| Leading Market Players |
|---|
| 23andMe |
| Abbott Laboratories |
| Quest Diagnostics |
| Myriad Genetics |
| Veracyte |
| Illumina |
| Positive Bioscience |
| Color Genomics |
| Ambry Genetics Corporation |
| Others |
Cost & Logistics Intelligence
The European Union's Corporate Sustainability Reporting Directive (CSRD) gates qualified supply and premium-tier pricing access for predictive testing services. This directive mandates preventative care models, influencing procurement and market entry for compliant providers.
Pricing Analysis
Per-test transactional pricing dominates the predictive testing market, often bundled into comprehensive multi-gene panels. Price differentiation stems from the breadth of genetic markers analyzed, the specific regulatory approvals (e.g., FDA or CE marking), and the level of post-test genetic counseling provided. Pricing pressure intensifies for basic screening panels due to increasing competition and continuous advancements in Next-Generation Sequencing technology. Individual consumers are generally most price-sensitive, while specialized medical centers and diagnostic labs prioritize clinical utility and turnaround time over marginal cost differences.
Supply Chain Analysis
Reverse logistics for predictive testing primarily involves the secure destruction or archival of biological samples and genetic data, rather than physical returns. Next-Generation Sequencing platform manufacturing concentrates in the United States and Singapore, while key reagents and enzymes source from Germany and China. Single-source vulnerability for proprietary sequencing chemistries presents a structural risk. Distribution runs through a hub-and-spoke model, leveraging diagnostic labs and specialized medical centers for patient access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The predictive testing market presents a clear margin-expansion story, driven by continuous cost reductions in Next-Generation Sequencing technologies. This technological efficiency allows providers to offer comprehensive panels at improved profitability.
For Market Incumbents: Lock in long-term contracts with major diagnostic labs and specialized medical centers to defend market share against emerging entrants. Invest heavily in AI-powered variant interpretation software to reduce turnaround times and maintain clinical leadership, mitigating the threat of commoditization. Deepen vertical integration into genetic counseling services to offer comprehensive patient support.
For New Entrants and Emerging Players: CRISPR-based diagnostic methods offer a technology-first wedge into niche applications requiring rapid, highly precise variant detection. Target underpenetrated markets in Asia-Pacific for hereditary cancer susceptibility testing, leveraging lower-cost NGS solutions. A direct-to-consumer model with clear clinical utility messaging can capture early adopters seeking personalized health insights.
For Investors and Strategic Acquirers: Roll-up economics work for diagnostic lab networks because of fragmented service providers and the need for scale to manage reimbursement complexities. Long-term viability over a 5-10 year window favors platforms integrating advanced bioinformatics with extensive clinical validation data. Target specialized genetic testing laboratories with strong intellectual property in neurological risk assessment. The signal to watch is expanding reimbursement coverage for multi-gene panels in new geographies.
| Strategic Initiative | Industry Significance |
|---|---|
| AI-Powered Variant Interpretation | Automates complex genomic data analysis, reducing turnaround times for diagnostic labs. |
| Expansion into Pharmacogenomics | Diversifies revenue streams by enabling personalized drug response predictions for clinicians. |
| Clinical Validation for EU MDR | Secures market access in Europe by meeting rigorous regulatory standards for in-vitro diagnostics. |
| Strategic Partnerships with EHR Providers | Integrates genomic data seamlessly into hospital systems, enhancing clinical workflow efficiency. |
| Investment in CRISPR-based Diagnostics | Positions firms at the forefront of highly precise, rapid genetic variant detection technologies. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary insights with secondary validation. Stakeholders included diagnostic lab directors, genetic counselors, regulatory affairs leads, and specialized medical center administrators. Secondary sources comprised FDA filings, EU MDR documentation, scientific publications, and SEC 10-K filings from key technology providers. This approach utilized both bottom-up market sizing and top-down validation to ensure data integrity.
Segment-level weighting informed the forecast framework, modeling market dynamics across the analysis window. Segmentation dimensions included test type, application, end-user, technology, and regional regulatory frameworks. Compound annual growth rates were derived from historical trends and projected technological adoption curves. Key forecast inputs included Next-Generation Sequencing cost reductions and evolving reimbursement policy changes.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to regulatory shifts and technological breakthroughs. Forecasts reflect documented assumptions regarding clinical validation pathways and data privacy enforcement. Practitioners should monitor new reimbursement approvals and significant AI integration for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Rapid Diagnostics Market
Diagnostics
BRIC in-Vitro Diagnostics (IVD) Market
Diagnostics
Global STD Diagnostics Market
Diagnostics
Global Comprehensive Metabolic Panel Market
Diagnostics
Global Companion Animal Diagnostics Market
Diagnostics
Infectious Disease in Vitro Diagnostics Market
Diagnostics
Global Creatinine Measurement Market
Diagnostics
Canada Latent Tuberculosis Infection Detection Market
Diagnostics
Global Coagulation Analyzers Market
Diagnostics
Alanine Aminotransferase Reagent Market
Diagnostics
Cognitive Diagnostics Market
Diagnostics
Pancreatic Cyst Diagnostics Market
Diagnostics
Italy in Vitro Diagnostics Market
Diagnostics
Europe Breast Cancer Screening Tests Market
Diagnostics
North America Point of Care Diagnostics Market
Diagnostics
In-Vitro Diagnostics (IVD) Packaging Market