
 Global Medical Adhesives Market | 2026-2036
Global Medical Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
Global Medical Adhesives Market Foresight
Buyer concentration in hospital procurement is rebalancing as large health systems consolidate purchasing power while ambulatory surgical centers fragment demand across smaller orders. Henkel AG & Co. KGaA leverages its European manufacturing footprint to serve centralized tenders. 3M sustains technology leadership in silicone-based platforms for critical care applications. Baxter International Inc. anchors its position through specialized adhesive formulations for surgical sealing.
Medical adhesives comprise synthetic or biologically derived compounds engineered to bond tissue, secure devices, or seal wounds without mechanical fasteners, typically achieving lap-shear strengths between 0.1 and 5.0 MPa depending on substrate and cure chemistry. Cyanoacrylate formulations dominate emergency wound closure due to rapid polymerization kinetics, though hydrogel adhesives command premium positioning in burn and dermatological care where moisture vapor transmission rates prove critical. UV cure technology leads device assembly lines for catheter and sensor bonding, while water-based systems gain share in disposable tape applications where volatile organic compound thresholds tighten.
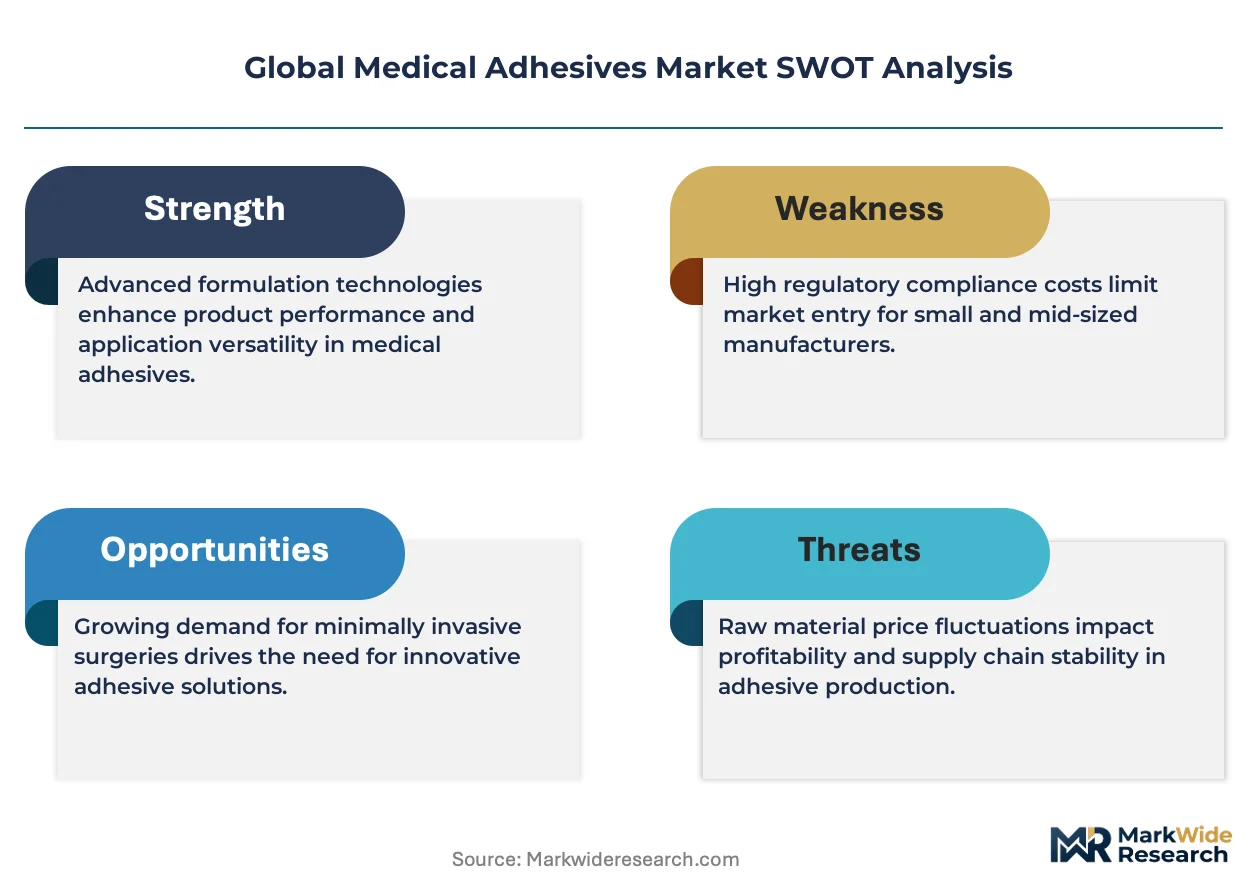
FDA 510(k) pathways and EU MDR conformity assessments shape product development timelines and clinical evidence requirements for adhesive manufacturers seeking commercial access. ISO 10993 biocompatibility testing standards govern cytotoxicity and sensitization profiles across all submission routes. REACH chemical registration obligations in Europe further constrain raw material sourcing flexibility. Stakeholders must monitor evolving notified body capacity constraints and polymer supply chain certification gaps to secure uninterrupted market participation.
Market Dynamics
EU MDR biocompatibility testing protocols are compressing product development timelines while Germany's Tuttlingen medical technology corridor concentrates specialized adhesive manufacturing capacity, creating a dual pressure on manufacturers to accelerate certification without sacrificing performance validation.
Growth Catalysts
- EU MDR Conformity Assessments:Tightened biocompatibility protocols under the Medical Device Regulation are filtering out marginal competitors and elevating demand for ISO 10993-certified formulations among European hospital procurement.
- Silicone-Based Platforms:Critical care applications in intensive care units and surgical theaters are standardizing on silicone adhesive chemistry for its moisture vapor transmission and gentle removal properties on fragile skin.
- Ambulatory Surgical Centers:Fragmentation of surgical volume into outpatient settings is generating steady demand for compact, single-use adhesive systems optimized for rapid turnover environments.
Market Restraints
- Raw Material Concentration:Cyanoacrylate monomer supply chains cluster in select Asian chemical manufacturing hubs, exposing formulators to freight cost volatility and customs processing delays.
- Biocompatibility Testing Burden:ISO 10993 cytotoxicity and sensitization studies require 18-24 month validation cycles, freezing smaller players out of premium surgical segments.
- Mechanical Fastener Substitution:Sutures and staples retain cost advantages in high-tension wound closures, limiting adhesive penetration in orthopedic and abdominal surgery applications.
Strategic Opportunities
- India's CDSCO Pathway:Streamlined medical device registration under India's Central Drugs Standard Control Organization is opening access to a hospital network expanding surgical capacity in tier-2 cities.
- UV Cure Device Assembly:Convergence of photochemistry with automated catheter and sensor production lines is creating demand for sub-second cure adhesives with validated bond strength consistency.
- Burn Care Hydrogels:Moisture vapor transmission rate optimization in hydrogel formulations addresses an underserved gap between emergency closure and long-term wound management in dermatological protocols.
Industry Challenges
- Polymer Chemist Scarcity:Formulation expertise combining biocompatibility knowledge with industrial scale-up experience concentrates in a handful of academic programs and incumbent firms.
- Notified Body Bottlenecks:EU MDR designation capacity constraints are extending conformity assessment queues, delaying revenue recognition for products awaiting CE marking.
- Legacy Tape Integration:Hospital supply chains maintain substantial inventory of conventional adhesive tapes, creating switching friction for advanced hydrogel and cyanoacrylate alternatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Medical Adhesives Market |
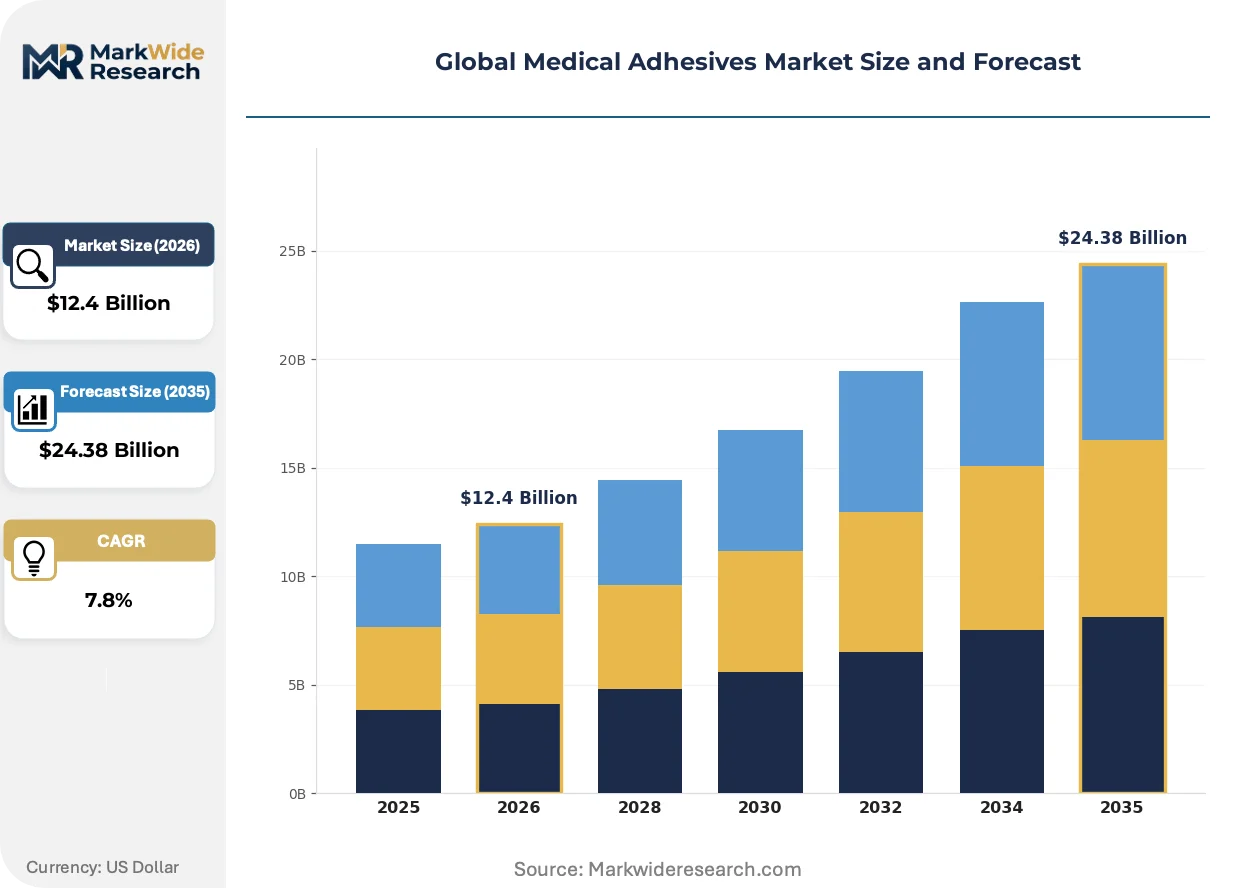
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $24.38 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acrylic, Silicone, Polyurethane, Cyanoacrylate, Hydrogel, Epoxy Application: Wound Care, Medical Device Assembly, Surgical Equipment, Orthopedics, Dental Procedures, Cardiovascular End User: Hospitals, Clinics, Diagnostic Laboratories, Ambulatory Surgical Centers, Research Institutes Technology: UV Cure, Hot Melt, Water-Based, Solvent-Based, Reactive, Anaerobic |
| Companies Covered | Solventum, Henkel AG & Co. KGaA, H.B. Fuller Company, 3M, Johnson & Johnson, Baxter International Inc., Bostik, Dymax, Permabond, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Medical Adhesives Market Shifts & Advancements
Photocurable adhesive systems are compressing manufacturing cycle times in medical device assembly while regulatory chemistry restrictions in Europe and raw material certification requirements are reshaping formulation priorities across the value chain.
Bioadhesive polymers derived from marine and plant sources are rewriting material selection criteria for implantable and long-wear applications. Cardiac monitoring patch manufacturers in Germany and the Netherlands are qualifying these formulations for 7-14 day wear durations. The shift is compressing reliance on petroleum-derived acrylates in segments where biodegradability and reduced inflammatory response command specification priority.
REACH chemical registration obligations are constraining raw material sourcing flexibility for European formulators. ECHA substance of very high concern listings are forcing reformulation of legacy pressure-sensitive adhesives used in disposable medical tapes. Manufacturers are responding by qualifying water-based acrylic systems that meet volatile organic compound thresholds without sacrificing peel adhesion performance on skin.
Centralized hospital procurement is fragmenting into tiered purchasing structures that separate strategic sourcing for advanced surgical sealants from operational buying of commodity wound closure tapes. Large German health systems like Charité and UK NHS trusts are consolidating high-value adhesive decisions at system level while delegating standard tape procurement to individual facility managers. This bifurcation is most visible in the Benelux region where hospital group purchasing organizations now maintain separate contract vehicles for cyanoacrylate surgical products versus hydrocolloid dressings.
Global Medical Adhesives Market Segmentation
Medical adhesives serve vastly different performance requirements across tissue bonding, device assembly, and long-wear applications. Segmentation reveals where formulation chemistry, cure mechanisms, and end-use specifications create distinct competitive arenas with diverging margin profiles and certification barriers.
Product Type:
Upgrade cycles vary dramatically by chemistry, with legacy acrylics facing displacement pressure from silicone and bioadhesive platforms in premium segments.
- Silicone:These elastomeric formulations achieve moisture vapor transmission rates critical for neonatal and geriatric skin applications. Demand concentrates in German and Dutch cardiac monitoring patch manufacturers where 7-14 day wear durations require gentle removal without epidermal stripping.
- Cyanoacrylate:Rapid polymerization kinetics deliver emergency wound closure in under 60 seconds, though monomer supply chains cluster in Asian chemical hubs exposing formulators to freight volatility. EU MDR biocompatibility testing now filters marginal competitors from premium surgical segments.
- Acrylic:Petroleum-derived pressure-sensitive adhesives dominate commodity medical tapes but face REACH-driven reformulation pressure across European disposable applications.
- Polyurethane:Tough, flexible films secure advanced wound dressings and catheter fixation where mechanical durability meets breathability requirements.
- Hydrogel:Water-swollen polymer networks optimize moisture balance in burn care and dermatological protocols, commanding specification priority where inflammatory response reduction matters.
- Epoxy:Rigid, high-strength bonds anchor permanent device assembly in imaging equipment and surgical instruments where thermal and chemical resistance prove essential.
Volume placements concentrate in Acrylic; the faster expansion belongs to Silicone.
Application:
Cost tier differentiation separates commodity wound closure from premium surgical sealants with 10-20x price multiples and diverging procurement channels.
- Medical Device Assembly:Automated catheter and sensor production lines demand sub-second cure adhesives with validated bond strength consistency. UV cure technology leads this segment where photochemistry convergence compresses manufacturing cycle times.
- Wound Care:Hydrogel and hydrocolloid formulations address moisture vapor transmission requirements across acute and chronic wound management, with hospital procurement bifurcating between system-level strategic sourcing and facility-level operational buying.
- Surgical Equipment:Specialized adhesive formulations for tissue sealing and hemostasis compete against mechanical fasteners in high-tension closure applications.
- Orthopedics:Load-bearing fixation applications retain suture and staple dominance due to tension requirements exceeding current adhesive lap-shear capabilities.
- Dental Procedures:Oral environment compatibility drives cyanoacrylate and resin-based selections for soft tissue management and provisional restoration.
- Cardiovascular:Implantable and external monitoring applications prioritize biocompatibility and long-wear adhesion on mobile skin surfaces.
Procurement value clusters in Medical Device Assembly; the steepest expansion trajectory appears in Wound Care.
End User:
Customer type determines order scale, certification requirements, and switching friction across centralized health systems versus fragmented outpatient settings.
- Hospitals:Large German health systems and UK NHS trusts consolidate high-value adhesive decisions at system level while delegating standard tape procurement to individual facility managers, creating tiered purchasing structures.
- Ambulatory Surgical Centers:Fragmentation of surgical volume into outpatient settings generates steady demand for compact, single-use adhesive systems optimized for rapid turnover environments.
- Clinics:Primary and specialty care settings drive recurring demand for wound closure and device fixation with lower per-order volumes but higher SKU diversity.
- Diagnostic Laboratories:Specimen collection and testing workflows utilize adhesive-based sample management and labeling systems with specific chemical resistance profiles.
- Research Institutes:Preclinical and clinical trial applications require custom formulations with extensive biocompatibility documentation and batch traceability.
Revenue concentration sits with Hospitals; Ambulatory Surgical Centers are climbing the fastest as surgical migration accelerates.
Technology:
Margin structure diverges sharply between energy-intensive cure systems and ambient-processing alternatives, with regulatory chemistry restrictions reshaping formulation priorities.
- UV Cure:Photoinitiator-activated polymerization delivers precise control over cure speed and bond line thickness in automated medical device assembly. German and Dutch manufacturers lead qualification of these systems for catheter and sensor bonding.
- Water-Based:Acrylic emulsions gain share in disposable tape applications where volatile organic compound thresholds tighten under REACH and EPA regulations, though peel adhesion performance on skin requires careful formulation balance.
- Hot Melt:Thermoplastic adhesives offer rapid processing without solvents in high-volume disposable applications where heat resistance requirements permit.
- Solvent-Based:Legacy systems face regulatory pressure from ECHA substance of very high concern listings and EPA air quality standards, forcing reformulation or phase-out.
- Reactive:Two-component systems deliver high-performance bonds in permanent device assembly where pot life and cure schedule flexibility matter.
- Anaerobic:Oxygen-inhibited cure chemistry secures metal-to-metal joints in surgical instruments and implantable devices where threadlocking and sealing converge.
Deployment scale favors Water-Based; the premium growth vector aligns with UV Cure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Asian chemical manufacturing hubs concentrate cyanoacrylate monomer supply chains, while European formulators navigate REACH registration obligations and FDA-regulated US markets anchor premium surgical sealant demand.
United States
FDA 510(k) pathways shape product development timelines for adhesive manufacturers seeking commercial access, with ISO 10993 biocompatibility testing standards governing cytotoxicity profiles. The agency's evolving review standards for tissue-bonding devices filter marginal competitors from premium segments. Boston's medical device corridor anchors specialized adhesive manufacturing capacity for cardiac monitoring and surgical applications.
Germany
The EU Medical Device Regulation tightens biocompatibility testing protocols, elevating demand for ISO 10993-certified formulations among European hospital procurement. ECHA substance of very high concern listings force reformulation of legacy pressure-sensitive adhesives used in disposable medical tapes. The Tuttlingen medical technology corridor concentrates specialized adhesive manufacturing capacity serving centralized tenders from large health systems.
China
NMPA medical device registration pathways are streamlining access for domestic and foreign adhesive manufacturers as hospital networks expand surgical capacity in tier-2 cities. The regulator's evolving standards for implantable device biocompatibility align gradually with ISO frameworks. Yangtze River Delta chemical manufacturing clusters anchor cyanoacrylate monomer production serving regional formulators.
India
CDSCO streamlined medical device registration is opening access to a hospital network expanding surgical capacity in tier-2 cities, generating demand for compact adhesive systems. The regulator's phased alignment with global biocompatibility standards compresses product development timelines for prepared entrants. Maharashtra's pharmaceutical and medical device manufacturing belt anchors formulation and packaging operations for domestic and export markets.
Japan
PMDA's stringent biocompatibility requirements for long-wear skin applications sustain premium positioning for silicone-based adhesive platforms in geriatric care. METI industrial policy supports domestic manufacturing of advanced medical materials amid supply chain recalibration. The Kansai region's chemical and materials science infrastructure anchors specialized adhesive research and pilot production facilities.
Global Medical Adhesives Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue bioadhesive and photocurable niches. The market structure reflects moderate consolidation among diversified chemical conglomerates alongside specialist formulators serving device manufacturers. Three archetypes dominate: diversified adhesives manufacturers with medical divisions, pure-play medical adhesive specialists, and medical device companies with captive adhesive operations. Competitive dynamics center on M&A activity absorbing niche technology platforms and capacity expansion in Asian manufacturing hubs to secure cyanoacrylate monomer supply.
Among diversified chemical conglomerates, Henkel AG & Co. KGaA and 3M occupy positions exemplifying scale-driven standard-tier supply to hospital procurement and device manufacturers. Baxter International Inc. represents the medical-device-captive archetype, anchoring specialized formulation capabilities within a broader healthcare portfolio. These three entities illustrate the competitive spectrum from commodity tape supply through premium surgical sealant development, with each archetype facing distinct margin pressures from regulatory compliance and raw material certification requirements.
| Leading Market Players |
|---|
| Solventum |
| Henkel AG & Co. KGaA |
| H.B. Fuller Company |
| 3M |
| Johnson & Johnson |
| Baxter International Inc. |
| Bostik |
| Dymax |
| Permabond |
| Others |
Supply & Pricing Matrix
REACH chemical registration obligations gate both qualified raw material supply and premium-tier pricing access for European formulators, compressing margins on legacy formulations while elevating certified alternatives. Hospital procurement committees now demand ISO 10993 documentation as a condition for premium-tier supplier qualification, effectively bifurcating the market between certified and non-certified supply tiers.
Pricing Analysis
Volume placements concentrate in acrylic commodity tapes while margin capture belongs to silicone and cyanoacrylate surgical platforms. Price differentiation separates ISO 10993-certified surgical sealants from standard wound closure tapes, with certification grade and volume scale as primary drivers. Pricing pressure stems from REACH-driven reformulation costs in European disposable applications. Ambulatory surgical centers exhibit highest price sensitivity due to fragmented order scales, while German hospital systems consolidating procurement at Charité-level demonstrate lowest sensitivity for premium surgical segments.
Supply Chain Analysis
Dual-sourcing requirements from large health systems and device manufacturers mandate multi-supplier qualification for cyanoacrylate monomers and silicone elastomers. Geographic supply concentration centers on China's Yangtze River Delta for monomer production, Germany's Tuttlingen corridor for specialized formulation, and India's Maharashtra belt for packaging operations. Raw material dependencies include petroleum-derived acrylates, bioadhesive marine polymers, and photoinitiator chemicals. Single-source vulnerability in Asian monomer supply creates exposure to freight volatility. Distribution runs through hospital group purchasing organizations in the Benelux region and specialized medical device distributors in North America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR conformity assessment bottlenecks are forcing weaker players without notified body relationships out of premium segments, consolidating viable supply around incumbents with established certification pathways.
For Market Incumbents: Anticipate margin compression in commodity tape segments as REACH reformulation costs accumulate, and respond by deepening captive supply of ISO 10993-certified raw materials. Secure dual notified body relationships to circumvent assessment queue delays that freeze revenue recognition. Prioritize R&D investment in UV cure platforms for device assembly applications where sub-second cure specifications command pricing power against Asian competitors. For New Entrants and Emerging Players: Photocurable adhesive systems with validated bond strength consistency offer the most penetrable wedge into automated catheter and sensor production lines serving German and Dutch manufacturers. Target India's CDSCO pathway for streamlined registration access to tier-2 city hospital networks expanding surgical capacity. Pursue white-space positioning in burn care hydrogels where moisture vapor transmission optimization remains underserved between emergency closure and long-term wound management protocols. For Investors and Strategic Acquirers: Notified body designation delays exceeding 18 months are the leading indicator that acquisition multiples for certified adhesive platforms will escalate as revenue recognition timelines stretch for unprepared competitors. Frame long-term viability around 5-10 year regulatory chemistry restrictions tightening across European and North American jurisdictions. Target acquisition profiles emphasizing polymer chemist talent density combined with existing ISO 10993 certification libraries rather than greenfield formulation capabilities.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR conformity assessment secures access to German hospital procurement consolidating at system level. |
| Backward Integration into Monomer Supply | Captive cyanoacrylate production mitigates Asian supply chain exposure for European formulators. |
| Hospital System Partnership | Direct relationships with Charité and NHS trusts bypass fragmented facility-level procurement friction. |
| Software Companion Development | Digital cure monitoring systems differentiate UV cure platforms in automated German device assembly. |
| Reimbursement Strategy | Coding alignment with surgical sealant procedures unlocks premium pricing in US hospital segments. |
Research Methodology
Document review covered FDA 510(k) filings, EU MDR technical documentation, and ISO 10993 biocompatibility test reports, complemented by interviews with hospital procurement managers, biomedical engineers at cardiac monitoring patch manufacturers, polymer chemists at specialized adhesive formulators, and GPO contracts managers at German health systems. Secondary validation drew from ECHA REACH substance registrations, customs trade data for cyanoacrylate monomer flows, and SEC filings from diversified chemical conglomerates with medical divisions. Bottom-up demand modeling from end-use application volumes was cross-referenced against top-down market sizing from raw material consumption patterns.
Historical volume trajectories were cross-referenced against expert panel input from adhesive formulators and device manufacturers to anchor growth assumptions across the analysis window. Segmentation modeling incorporated product chemistry, cure technology, application end-use, and geographic regulatory cluster dimensions. CAGRs were derived from slope analysis of normalized historical data adjusted for regulatory inflection points. Industry-specific forecast inputs included notified body capacity utilization rates and REACH substance of very high concern listing timelines.
Several conditions sit outside the modeled scope, including unforeseen polymer supply disruptions from geopolitical events, accelerated biodegradability mandates beyond current ECHA consultation timelines, and breakthrough mechanical fastening technologies displacing adhesive applications in orthopedic surgery. Forecasts reflect documented assumptions regarding regulatory chemistry restriction evolution and hospital procurement consolidation trajectories. Deviation in EU MDR notified body designation capacity or cyanoacrylate monomer supply chain configuration would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Adhesives and Sealants Distribution Market
Adhesives & Sealants
North America Construction Adhesives Market
Adhesives & Sealants
Adhesive Primer Market
Adhesives & Sealants
Southeast Asia Adhesives and Sealants Market
Adhesives & Sealants
Light Curing Adhesives Market
Adhesives & Sealants
Automotive Windshield Adhesives Market
Adhesives & Sealants
Asia-Pacific Reactive Adhesives Market
Adhesives & Sealants
Global Slack Wax Market
Adhesives & Sealants
India Tile Adhesive Market
Adhesives & Sealants
Capillary Underfill Material Market
Adhesives & Sealants
Acrylates Copolymer Market
Adhesives & Sealants
United States Construction Adhesives and Sealants Market
Adhesives & Sealants
Global Automotive Adhesive Market
Adhesives & Sealants
Plastic Adhesives Market
Adhesives & Sealants
Debonding-on-Demand Adhesive Tapes for Electronics Dismantling Market
Adhesives & Sealants
North America Pressure Sensitive Adhesives (PSA) Market