
 North America French Fries Market | 2026-2036
North America French Fries Market Size, Share, and Industry Trends Forecast 2026-2036
North America French Fries Market Insights
High-oleic sunflower oil is pivoting into mainstream fry production, displacing partially hydrogenated soybean blends across North American processing lines. Lamb Weston Holdings leverages its Idaho-based potato supply network to sustain cost advantages in frozen fry output. McCain Foods anchors its cross-border manufacturing footprint across Alberta and New Brunswick, while J.R. Simplot competes through differentiated specialty-cut portfolios targeting premium foodservice accounts.
North America French Fries comprise par-fried or blanched potato strips, typically cut to 9.5mm or 13mm widths, with moisture content reduced to 60-70% pre-freeze for optimal rethermalization. The product serves as a standardized, labor-saving carbohydrate component across commercial kitchens and retail freezers. Frozen product type dominates volume throughput due to extended shelf stability and fryer consistency, while air-fried preparation method captures the fastest-growing consumer segment as households replicate restaurant texture with reduced oil absorption. Bulk packaging type still occupies the largest margin pool, though snack pack formats are gaining traction in convenience retail channels.
The U.S. FDA enforces nutrition labeling standards that directly shape fry formulation decisions, while USDA grading protocols determine raw potato procurement specifications across the supply base. Health Canada's CFIA import requirements and the U.S. EPA's effluent guidelines for potato processing facilities add compliance layers that influence plant location and capital allocation. Stakeholders must monitor how state-level sodium warning mandates in California and New York propagate into national product specifications.
Market Dynamics
The North America French Fries Market is being fundamentally reshaped by the U.S. FDA's updated trans fat labeling requirements, which are forcing processors to abandon partially hydrogenated oils and reconfigure entire production lines around high-oleic alternatives.
Growth Catalysts
- Air-fryer appliance penetration:Household adoption of countertop air-frying equipment in the U.S. Southeast is creating pull for par-fried products with specific moisture profiles optimized for convection reheating.
- Health Canada's CFIA import harmonization:Streamlined cross-border frozen potato product standards between the U.S. and Canada are reducing customs friction and expanding distribution reach for integrated processors.
- Quick-service menu diversification:Major fast-food chains are expanding fry format variations, driving volume throughput for specialty-cut and seasoned product lines.
Market Restraints
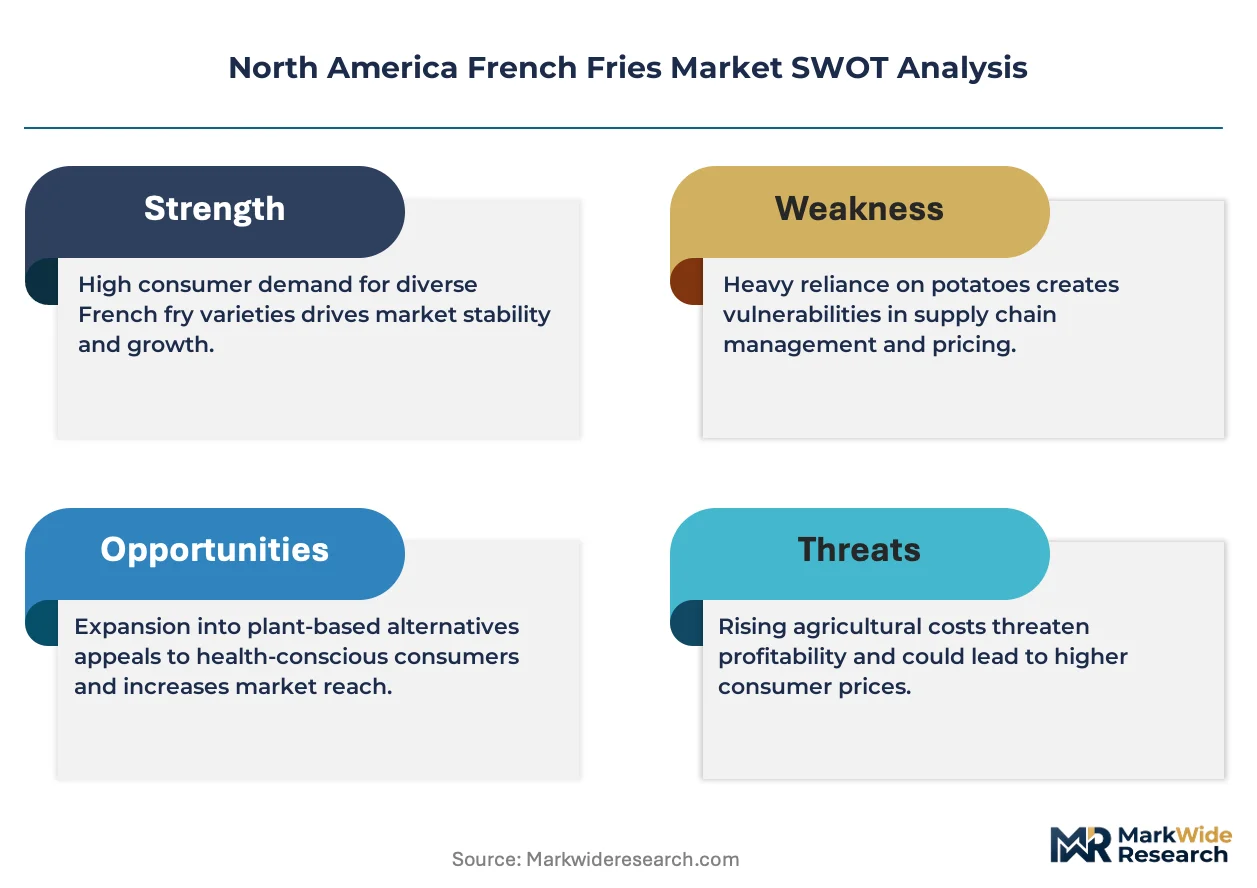
- Input cost volatility:Russet Burbank potato contract prices fluctuate with Idaho growing-season weather patterns, compressing margin predictability for processors locked into annual supply agreements.
- Supply concentration risk:Frozen fry production clusters heavily in the Pacific Northwest and Alberta, creating vulnerability to regional transportation disruptions or labor stoppages at key processing nodes.
- Regulatory friction:California and New York state-level sodium warning mandates are forcing national product reformulation decisions that increase R&D overhead without corresponding price recovery mechanisms.
Strategic Opportunities
- Underpenetrated Mexican foodservice:Quick-service and casual dining fry penetration in Mexican commercial kitchens remains below U.S. levels, offering volume expansion for processors with cross-border cold-chain capabilities.
- Regulatory tailwind:The U.S. EPA's effluent guideline updates for potato processing are accelerating capital investment in water-recovery systems, creating first-mover advantage for facilities achieving zero-liquid-discharge certification.
- Technology convergence:Computer vision sorting systems are converging with high-speed cutting lines, enabling real-time defect detection and yield optimization that was previously unattainable at commercial scale.
Industry Challenges
- Specialized maintenance technician scarcity:Automated fry lines require mechatronics expertise that outpaces vocational training output in rural processing communities.
- Capex intensity for oil-transition compliance:Converting existing fryer batteries to handle high-oleic sunflower oil requires complete heating system replacement and extended downtime.
- USDA grading protocol alignment:Harmonizing internal quality specifications with federal raw potato procurement standards creates procurement friction and rejected-lot exposure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America French Fries Market |
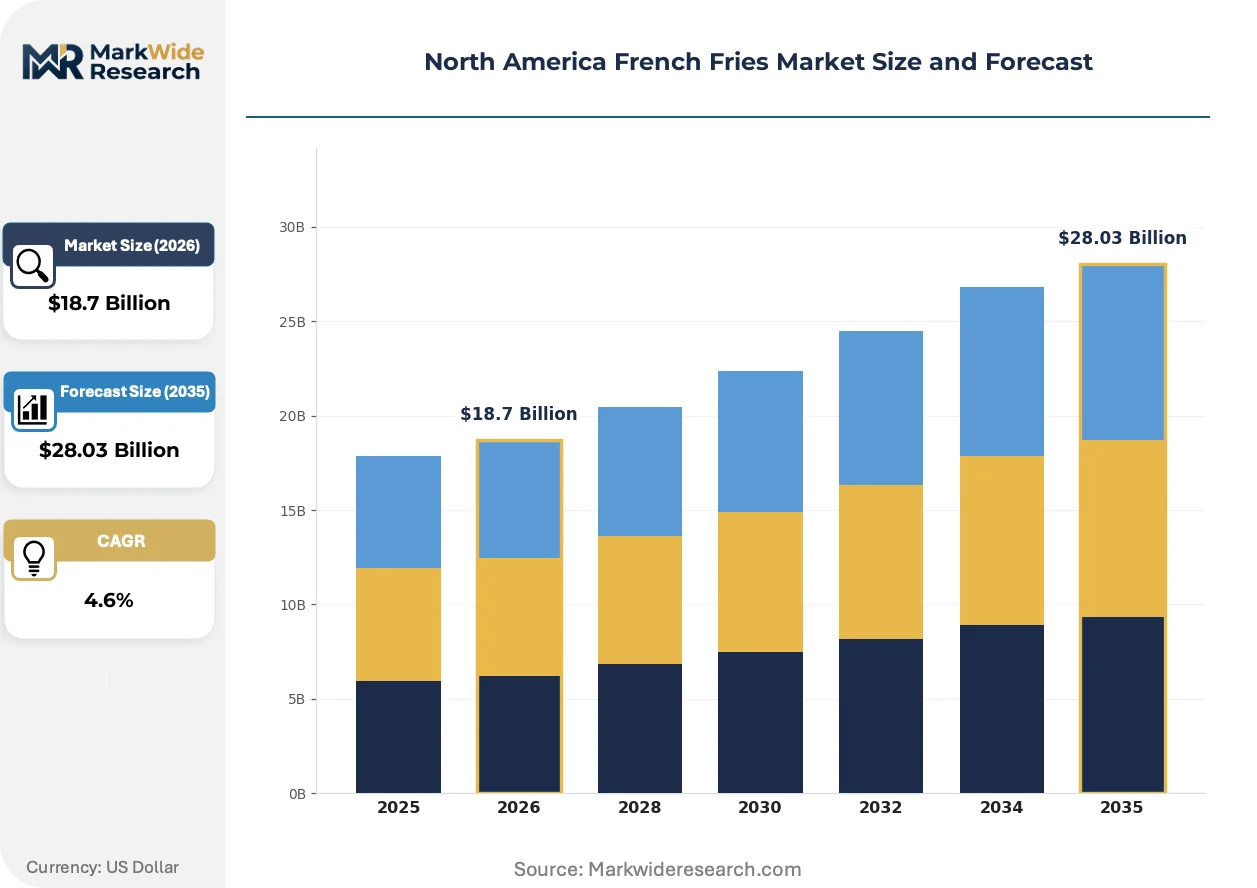
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.03 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Frozen, Fresh, Dehydrated, Specialty End User: Restaurants, Foodservice, Retail, Food Processing Preparation Method: Fried, Baked, Air-Fried, Microwave Packaging Type: Bulk, Retail Pack, Snack Pack, Others |
| Companies Covered | Lamb Weston Holdings Inc., McCain Foods Limited, J.R. Simplot Company, Ore-Ida, Cavendish Farms, Aviko (Royal Cosun), Alexia Foods, Agristo NV, Nathan’s Famous Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America French Fries Market Trends and Innovations
Processing technology and regulatory compliance are the twin engines of change in North American fry manufacturing, with oil chemistry reformulation and automation investments dominating capital allocation decisions across the value chain.
High-oleic sunflower oil is converging with existing fryer infrastructure through purpose-built heating and filtration retrofit packages. Mid-scale processors in the U.S. Midwest are adopting these systems fastest, driven by insurance liability concerns around trans fat litigation. This convergence is compressing the competitive window for laggard facilities still running legacy soybean blends, forcing accelerated depreciation schedules.
The U.S. FDA's updated Nutrition Facts label requirements for added sugars and revised serving sizes are reshaping portion-pack specifications across retail and foodservice channels. Processors must now maintain dual label inventories for products shipping before and after compliance deadlines. Frozen retail packs in the 16-32 ounce range face the most significant graphic redesign burden and associated packaging material waste.
Foodservice distributors are consolidating procurement around fewer, larger-volume suppliers capable of delivering multi-SKU fry portfolios with synchronized delivery windows. Independent operators and regional chains are losing negotiating leverage as broadline distributors prioritize national accounts with guaranteed volume commitments. This concentration is most visible in the U.S. Southeast, where Sysco and US Foods route density advantages have compressed regional processor margins.
North America French Fries Market Segmentation
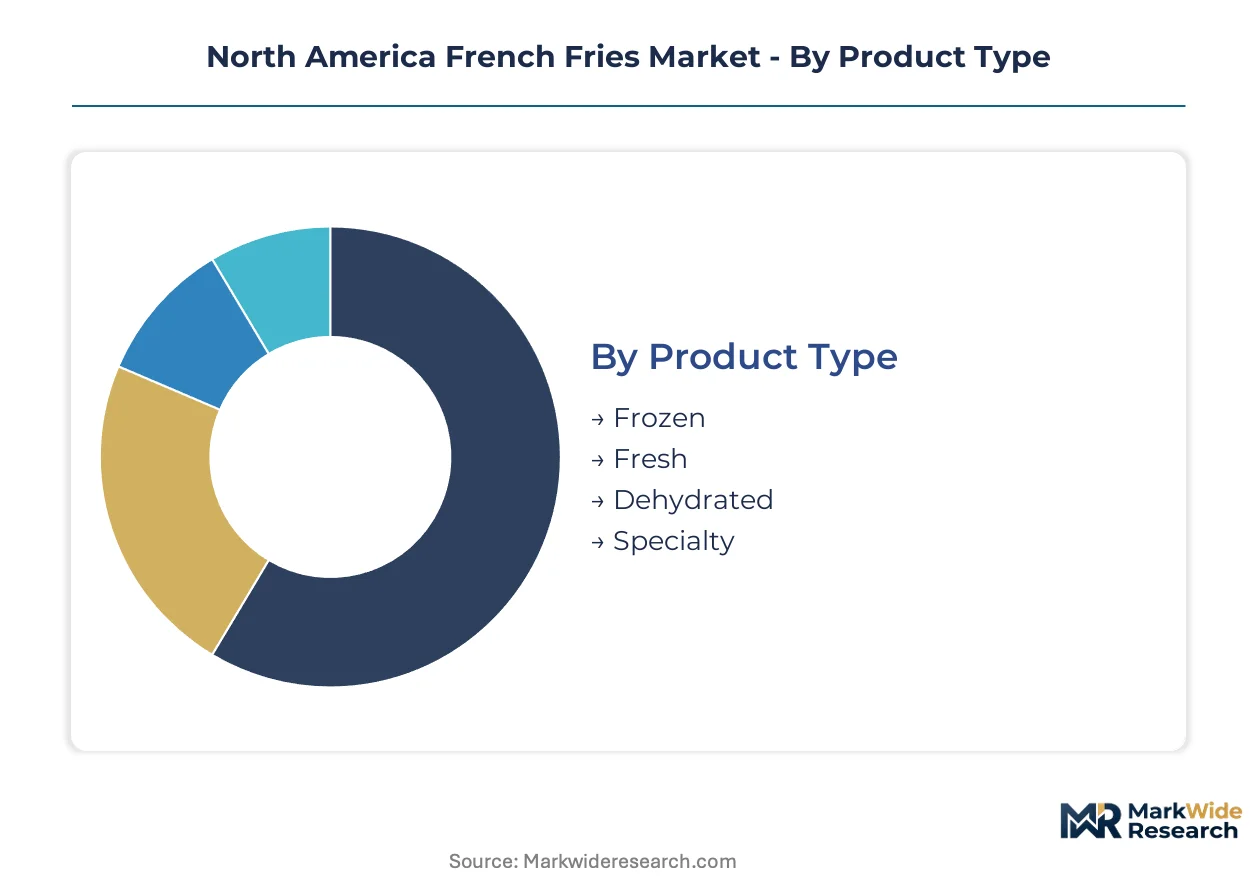
Segmentation in the North America French Fries Market reveals how processing infrastructure, distribution channels, and consumption occasions fragment demand across distinct technical and commercial profiles. Each dimension carries implications for capital allocation, margin structure, and regulatory exposure.
Product Type:
Supply concentration in Pacific Northwest and Alberta processing corridors shapes product-type availability across North American distribution networks.
- Frozen:Par-fried strips with 60-70% moisture content reduced pre-freeze for optimal rethermalization. Quick-service chains in the U.S. Southeast absorb the highest throughput volumes, driven by fryer consistency requirements and extended shelf stability for inventory management.
- Fresh:Unprocessed cut potatoes requiring same-day preparation, concentrated in high-turnover independent restaurants with dedicated prep labor. Labor cost inflation in California and New York is compressing addressable market for this format.
- Dehydrated:Low-moisture potato flakes and granules for industrial reconstitution applications.
- Specialty:Seasoned, battered, or alternative-cut formats targeting premium foodservice accounts.
Frozen absorbs the bulk of installed capacity; specialty is expanding most quickly.
End User:
Customer-type concentration determines pricing power and contract structure across the value chain.
- Restaurants:Full-service and casual dining operators specifying custom cut sizes and coating profiles. Chains in the U.S. Southeast negotiate multi-year supply agreements with volume guarantees, locking processors into fixed-price exposure during input cost spikes.
- Foodservice:Broadline distributors serving institutional and commercial accounts with standardized SKU portfolios. Sysco and US Foods route density advantages in the U.S. Southeast have compressed regional processor margins through consolidated procurement.
- Retail:Grocery and club channels moving frozen bags and private-label formats.
- Food Processing:Industrial buyers incorporating fries as ingredients in prepared meals and frozen entrees.
Foodservice commands the largest revenue pool; retail is climbing the fastest on air-fryer appliance penetration.
Preparation Method:
Equipment installed base in North American households and commercial kitchens dictates method-specific product formulation.
- Fried:Traditional deep-frying in oil baths, still dominant in commercial kitchen throughput. U.S. FDA trans fat labeling requirements are forcing oil chemistry reformulation across quick-service fryer batteries, with high-oleic sunflower oil displacing partially hydrogenated blends.
- Air-Fried:Convection-based reheating with minimal oil absorption, capturing steepest expansion trajectory in household consumption. Par-fried products with specific moisture profiles optimized for countertop convection equipment are gaining shelf space in U.S. Southeast retail channels.
- Baked:Oven preparation for health-positioned retail SKUs with reduced fat claims.
- Microwave:Rapid reheating formats for convenience-oriented snack occasions.
Fried retains dominant volume share; air-fried is gaining share fastest on consumer health positioning.
Packaging Type:
Margin structure and distribution economics vary sharply across format scale.
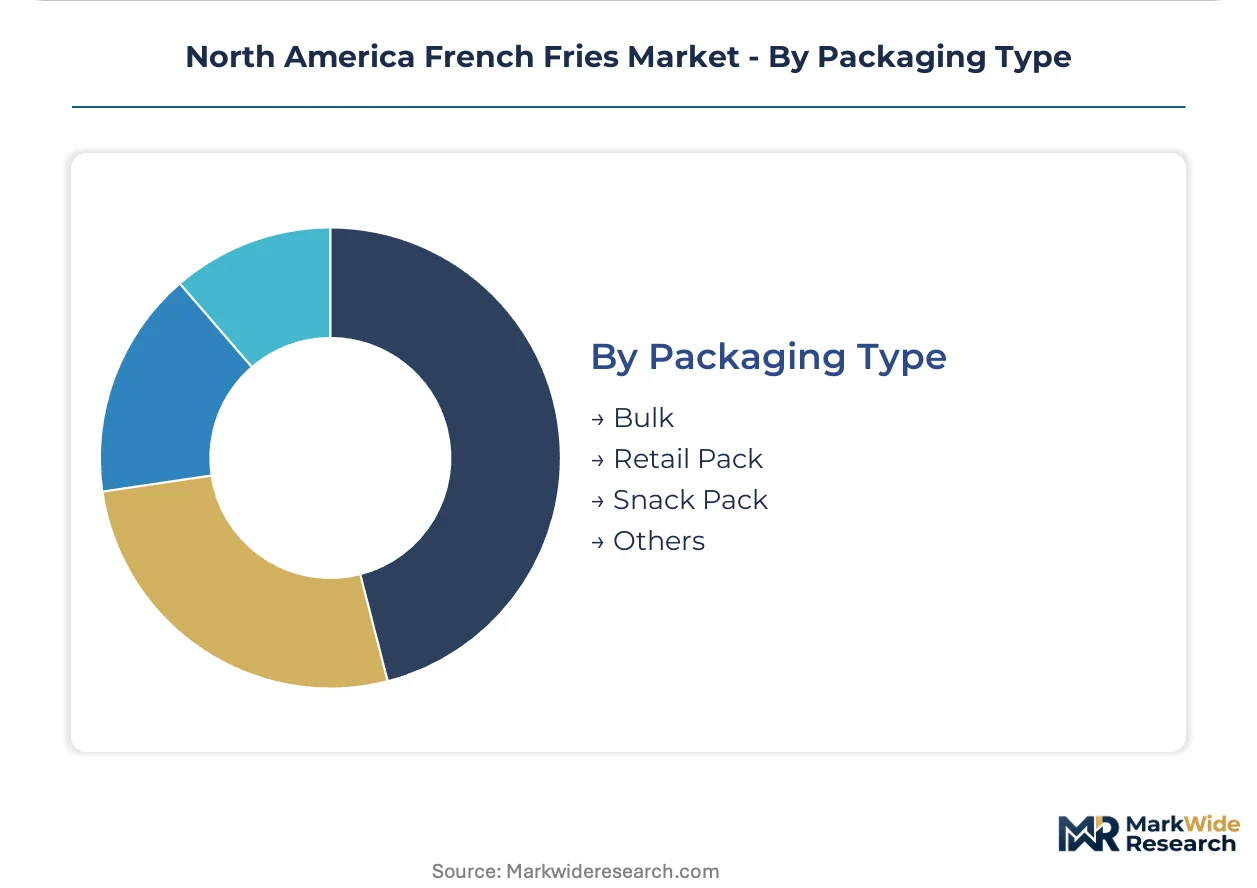
- Bulk:Large-format cases for high-volume foodservice accounts, occupying the largest margin pool. National quick-service chains specify 30-pound cases with synchronized delivery windows, requiring processors to maintain dedicated bulk line capacity.
- Retail Pack:16-32 ounce consumer bags facing U.S. FDA Nutrition Facts label redesign burden and associated packaging material waste from dual inventory maintenance.
- Snack Pack:Single-serve portions for convenience retail and vending channels.
- Others:Institutional formats and custom specifications for non-standard applications.
Bulk captures the bulk of processor margin contribution; snack pack is expanding most quickly in convenience retail channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in the U.S. Southeast, where quick-service chains and major processing facilities cluster near potato-growing regions. The analysis examines three countries where fry production, consumption, and regulatory frameworks shape regional dynamics.
United States
Quick-service restaurant chains in the Southeast absorb the highest frozen fry throughput volumes. The U.S. FDA enforces updated trans fat labeling requirements that force processors to abandon partially hydrogenated oils. Idaho-based processing corridors anchor production capacity, with Lamb Weston Holdings leveraging its potato supply network for cost advantages.
Canada
Cross-border manufacturing footprints serve integrated North American distribution networks. Health Canada's CFIA streamlines import harmonization for frozen potato products, reducing customs friction. Alberta and New Brunswick host major processing nodes that supply both domestic foodservice and U.S. export channels.
Mexico
Quick-service and casual dining fry penetration remains below U.S. levels, offering volume expansion potential. Processors with cross-border cold-chain capabilities target underpenetrated Mexican foodservice. Northern border states concentrate distribution infrastructure for U.S.-origin frozen products.
North America French Fries Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated processors commanding foodservice volumes and private-label specialists capturing retail growth. The structure tilts toward consolidation at the top, where three to four operators control bulk procurement relationships with national quick-service chains. Strategic archetypes include Idaho-based supply-network owners, cross-border manufacturing integrators, and differentiated specialty-cut portfolio builders. Dominant competitive moves center on oil-chemistry reformulation compliance and automated processing line upgrades.
Among Idaho-based supply-network owners, Lamb Weston Holdings exemplifies the archetype of captive potato sourcing tied to frozen output scale. McCain Foods Limited occupies a position as the cross-border manufacturing integrator with facilities spanning Alberta and New Brunswick. J.R. Simplot Company sits within the specialty-cut differentiation tier, targeting premium foodservice accounts with format variation.
| Leading Market Players |
|---|
| Lamb Weston Holdings Inc. |
| McCain Foods Limited |
| J.R. Simplot Company |
| Ore-Ida |
| Cavendish Farms |
| Aviko (Royal Cosun) |
| Alexia Foods |
| Agristo NV |
| Nathan's Famous Inc. |
| Others |
Pricing and Supply Chain Analysis
Captive potato sourcing through Idaho-based supply networks anchors both cost position and pricing power for integrated processors serving national quick-service chains. This backward integration into raw material procurement insulates margin structures from Russet Burbank contract volatility while locking in volume commitments that independent competitors cannot match.
Pricing Analysis
Bulk foodservice contracts capture volume share while retail specialty packs extract margin premiums. Three-tier pricing structure across premium battered formats, standard straight-cut lines, and economy private-label SKUs reflects oil-chemistry compliance costs and air-fryer optimization R&D. Pricing pressure stems from California and New York sodium warning mandates forcing national reformulation without price recovery mechanisms. National quick-service chains exhibit lowest price sensitivity due to menu price elasticity; independent regional operators face acute cost compression.
Supply Chain Analysis
The U.S. FDA's updated trans fat labeling requirements are reshaping sourcing patterns as processors abandon partially hydrogenated oil suppliers for high-oleic sunflower oil domestic producers. Frozen fry production draws from Idaho, Washington, and Alberta processing corridors with Russet Burbank potatoes, high-oleic oils, and specialized fryer filtration systems as critical inputs. Single-source vulnerability concentrates in Pacific Northwest transportation nodes where regional disruptions cascade across North American distribution. Distribution runs through Sysco and US Foods broadline networks with route density advantages in the U.S. Southeast.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play where U.S. FDA oil-chemistry mandates and automated line capex requirements are forcing sub-scale processors toward exit or acquisition.
For Market Incumbents: Extend high-oleic oil transition leadership by accelerating zero-liquid-discharge certification at Idaho facilities before EPA effluent guideline enforcement tightens. Lock in multi-year volume guarantees with Southeast quick-service chains to defend against McCain Foods' cross-border manufacturing expansion. Prioritize mechatronics technician apprenticeship programs to resolve automated line maintenance scarcity. For New Entrants and Emerging Players: Launch via direct-to-retail air-fryer optimized SKUs targeting the U.S. Southeast convenience channel where broadline distributor consolidation has left shelf space gaps. Mexican foodservice underpenetration offers white-space expansion for processors with cross-border cold-chain capabilities. Lead with par-fried moisture-profile differentiation rather than commodity straight-cut competition. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by integrated processors seeking Idaho supply-network control or automated line technology assets. Five-to-ten year viability favors facilities with EPA zero-liquid-discharge certification and locked high-oleic oil supply contracts. Watch for California sodium warning mandate propagation into federal standard as inflection signal for accelerated national reformulation capex needs.| Strategic Initiative | Industry Significance |
|---|---|
| High-Oleic Oil Transition | U.S. FDA trans fat compliance forces complete fryer battery replacement and supplier base restructuring. |
| Zero-Liquid-Discharge Certification | U.S. EPA effluent guideline updates create first-mover advantage for water-recovery system investment. |
| Air-Fryer Product Line Extension | Household convection appliance penetration in the U.S. Southeast pulls par-fried moisture-optimized formats. |
| Cross-Border Cold-Chain Expansion | Health Canada CFIA harmonization reduces customs friction for integrated Alberta-New Brunswick networks. |
| Computer Vision Sorting Integration | Real-time defect detection converges with high-speed cutting lines for yield optimization at commercial scale. |
Research Methodology
Independent corroboration across processor operations executives, quick-service chain procurement directors, and broadline distributor category managers underwrites the qualitative findings. Primary fieldwork with Idaho-based supply planners, Alberta plant engineers, and U.S. Southeast foodservice operators combined with secondary validation from USDA grading protocols, FDA labeling guidance documents, and EPA effluent guideline filings. Bottom-up installed capacity assessment triangulates against top-down quick-service chain volume commitments.
Rate-of-change decomposition across product type, preparation method, end-user channel, and packaging format dimensions structures the analytical framework. CAGRs derive from segment-level volume trajectories weighted by price realization trends across bulk foodservice, retail pack, and snack pack formats. Air-fryer appliance penetration curves and high-oleic oil transition timelines inform demand-side elasticity assumptions throughout the projection horizon.
Regulatory enforcement timing, input cost volatility in Russet Burbank contracts, and Mexican foodservice adoption velocity are the dominant revision risks. Forecasts reflect documented assumptions regarding FDA compliance deadlines and EPA implementation schedules. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed and Frozen Foods
Germany Frozen Snack Market
Processed and Frozen Foods
Popsicle and Ice Cream Bar Market
Processed and Frozen Foods
Europe Frozen Finger Chips Market
Processed and Frozen Foods
Asia-Pacific Frozen Food Market
Processed and Frozen Foods
Refrigerated Liquid Eggs Market
Processed and Frozen Foods
Dehydrated Potato Market
Processed and Frozen Foods
Frozen Pork Belly Market
Processed and Frozen Foods
Asia-Pacific Frozen Pizza Market
Processed and Frozen Foods
Frozen Noodles and Rice Products Market
Processed and Frozen Foods
Dumplings Market
Processed and Frozen Foods
Frozen Shrimp Market
Processed and Frozen Foods
North America Frozen Food Market
Processed and Frozen Foods
Freeze Dried Melt Market
Processed and Frozen Foods
Frozen Processed Food Market
Processed and Frozen Foods
Latin America Frozen Finger Chips Market
Processed and Frozen Foods
United States Frozen Yogurt Market