
 Europe Frozen Finger Chips Market | 2026-2036
Europe Frozen Finger Chips Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Frozen Finger Chips Market Intelligence
REACH is shifting the cost-of-entry calculus for frozen finger chip manufacturers operating across the European Economic Area. McCain Foods Limited leverages its vertically integrated potato supply chain to sustain cost discipline under tightening chemical compliance mandates. Aviko competes through specialized product lines targeting foodservice operators seeking consistent cut specifications and extended fry stability.
Frozen finger chips are par-fried potato strips, typically blanched at 85–95°C and flash-fried at 180–190°C before rapid freezing to −18°C, designed for finish-frying or baking without raw potato handling. French fries occupy the dominant volume position across European retail and foodservice channels, while potato wedges capture expanding placement in pub and casual-dining menus where texture differentiation commands price premiums. The food service distribution channel anchors margin pools through contract-based volume commitments, though online retail segments are gaining velocity as direct-to-restaurant platforms reduce intermediary layers.
EFSA acrylamide benchmarks, EU Green Deal sustainability disclosures, and national F-Gas regulations on refrigeration equipment collectively shape product formulation and capital expenditure timelines for processors. EMA food-contact material standards and CE marking requirements for processing machinery further constrain market access for non-compliant operators. Stakeholders must monitor evolving acrylamide threshold negotiations and cold-chain energy compliance costs as structural determinants of regional competitiveness.
Market Dynamics
Centralized kitchen models across Western European foodservice chains are displacing on-site potato preparation, locking in demand for par-fried frozen formats and reshaping processor capacity allocation toward contract manufacturing.
Growth Catalysts
- EU Green Deal Farm to Fork Strategy:Mandatory sustainability disclosures and lower-acrylamide production targets are accelerating capital flows into certified processing lines across Germany and France.
- Quick-service restaurant expansion:Labor cost inflation in the United Kingdom and Spain is forcing chains to outsource potato preparation to frozen suppliers with guaranteed cut consistency.
- Flash-freezing technology:Cryogenic freezing systems operating at −18°C preservation thresholds are extending fry stability windows and reducing cold-chain spoilage rates for long-haul distribution.
Market Restraints
- Input cost volatility:Natural gas price fluctuations directly compress margins for blanching and par-frying operations across Dutch and Belgian processing clusters.
- Supply concentration risk:Seed potato genetics and specialized fry-grade cultivars remain concentrated among limited breeders in the Netherlands and Germany.
- F-Gas regulatory friction:Phasedown mandates under EU refrigeration equipment rules are forcing premature cold-chain infrastructure replacement before standard depreciation cycles conclude.
Strategic Opportunities
- Underpenetrated Eastern European foodservice:Poland and Romania exhibit low frozen finger chip penetration in independent restaurants relative to Western European benchmarks.
- Direct-to-restaurant platforms:Digital procurement channels are disintermediating traditional broadline distributors in the United Kingdom and Nordic markets.
- Acrylamide threshold negotiations:Anticipated EFSA benchmark revisions create first-mover advantage for processors with validated low-temperature frying protocols.
Industry Challenges
- Process engineering talent scarcity:Deep expertise in par-frying parameter optimization and oil management systems remains concentrated among retiring specialists in Belgian processing hubs.
- REACH compliance timelines:Chemical safety dossier preparation for modified starch coatings and anti-foaming agents consumes 18-24 month certification windows.
- Cold-chain energy reconfiguration:F-Gas equipment phaseout demands simultaneous warehouse refrigeration overhaul and transport fleet retrofitting.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Frozen Finger Chips Market |
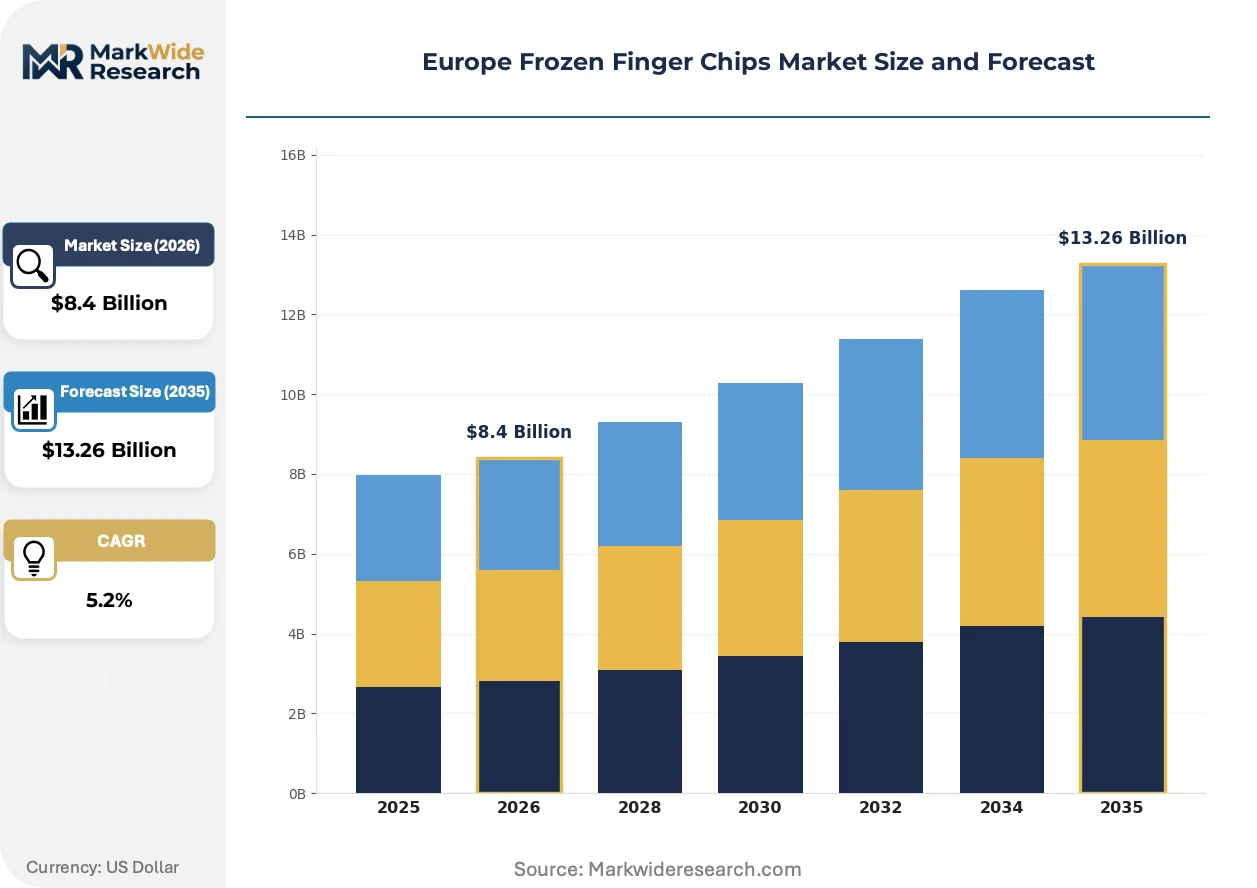
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $13.26 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: French Fries, Potato Wedges, Curly Fries, Mashed Potato Balls Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Food Service End Use: Household, Restaurants, Cafeterias, Food Trucks Packaging Type: Plastic Bags, Cardboard Boxes, Vacuum Packs, Bulk Packaging |
| Companies Covered | McCain Foods Limited, Nomad Foods Ltd, Aviko, Farm Frites, Agristo NV, Lutosa S.A., Clarebout Potatoes NV, Dr Oetker Group, Lamb Weston Holdings, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Frozen Finger Chips Market Strategic Shifts & Innovations
Processing technology and regulatory chemistry standards are converging to redefine product specifications and operational compliance thresholds across European frozen potato supply chains.
Air fryer-optimized coatings utilizing modified starch barriers and moisture-retention layers are rewriting finish-cooking performance expectations. Casual-dining chains in France and Germany are specifying these formulations in procurement contracts to ensure texture consistency across variable equipment types. The technology is compressing differentiation windows between premium and standard product tiers.
REACH authorization requirements for processing aids and food-contact substances are tightening substance eligibility lists. ECHA screening assessments are forcing reformulation of anti-foaming agents and blanching additives ahead of sunset date deadlines. Smaller processors in Southern Europe lacking dedicated regulatory affairs functions face accelerated market access barriers.
Consolidated buying cooperatives among mid-sized restaurant groups are displacing individual outlet purchasing decisions. These entities in the Netherlands and Belgium are negotiating volume-commitment contracts directly with processors, bypassing traditional foodservice distribution layers. The shift is most visible in pub and casual-dining channels where menu standardization permits centralized specification.
Europe Frozen Finger Chips Market Segmentation
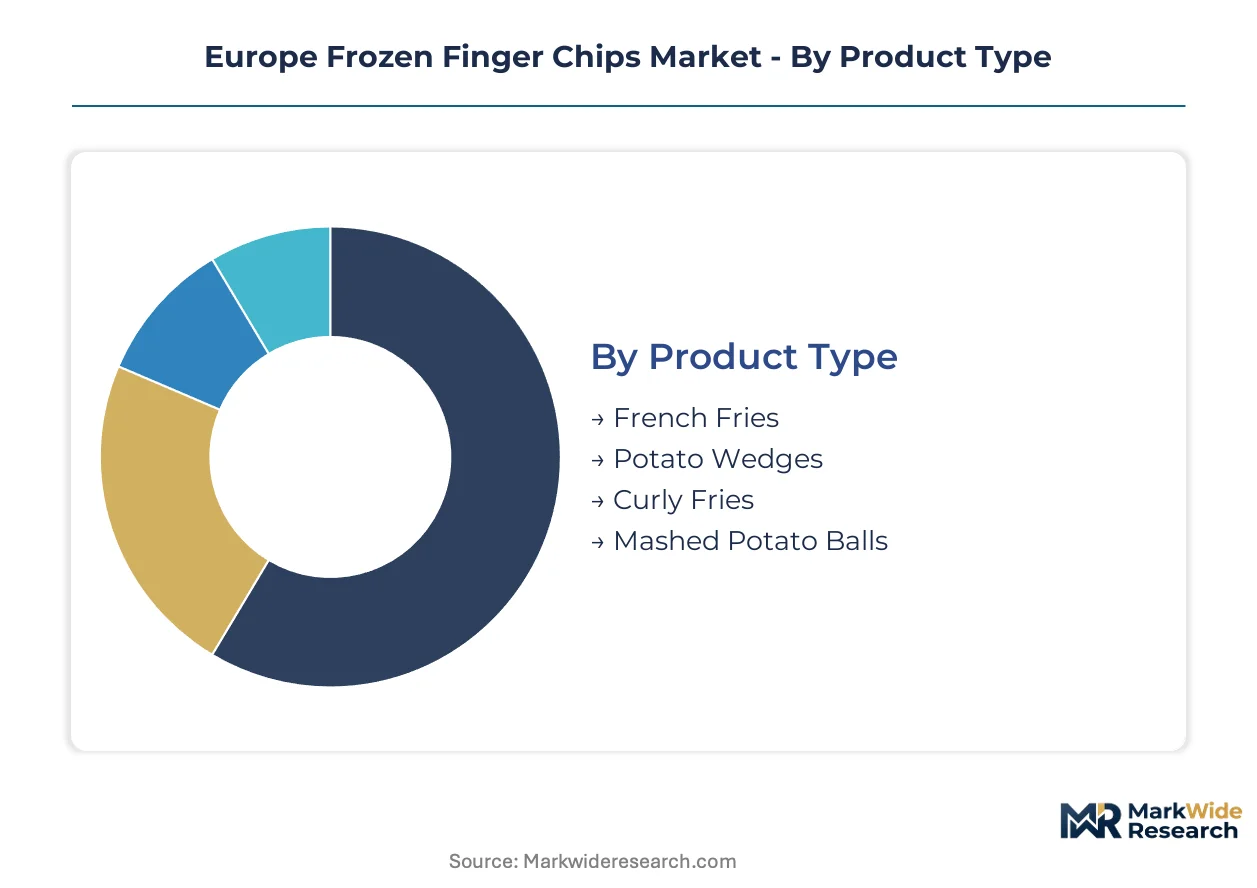
Product specifications and distribution economics create distinct margin profiles across frozen finger chip segments. Procurement patterns diverge sharply between centralized foodservice buyers and fragmented household purchasers, with packaging formats and channel access determining competitive positioning for processors.
Product Type:
Cut geometry and surface-area-to-volume ratios define frying performance and end-use suitability across processor portfolios.
- French Fries:Straight-cut strips with standardized 9-11mm thickness dominate par-fried production volumes across Belgian and Dutch processing clusters. Quick-service restaurants in Germany and the United Kingdom specify these formats for fryer basket compatibility and holding-time consistency.
- Potato Wedges:Skin-on wedge cuts with 60-80g portion weights command placement in British and Irish pub channels where texture differentiation supports menu pricing. EFSA acrylamide concerns favor thicker cuts with reduced surface browning.
- Curly Fries:Spiral-cut formats utilizing specialized rotary cutting heads occupy niche positions in cinema and stadium concessions across France and Spain.
- Mashed Potato Balls:Reconstituted potato spheres target Scandinavian cafeteria channels seeking portion-controlled carbohydrate sides.
Mature deployment sits with French Fries. Newer deployment is concentrated in Potato Wedges.
Distribution Channel:
Channel selection determines working capital intensity and price realization for frozen potato processors.
- Food Service:Contract-based volume commitments with broadline distributors anchor processor capacity planning across Western Europe. Centralized kitchen models in France and the Netherlands favor palletized bulk delivery with guaranteed cut specifications.
- Supermarkets:Private-label and branded bagged formats compete for freezer-section placement in German and British retail chains with air fryer cooking instructions now standard.
- Online Retail:Direct-to-consumer platforms are gaining velocity in Nordic markets where subscription-based frozen vegetable bundles include finger chip assortments.
- Convenience Stores:Impulse-sized formats target urban grab-and-go consumption in Italian and Spanish metropolitan areas with limited frozen capacity.
Food Service commands the steepest expansion trajectory in contract manufacturing. Supermarkets are seeing the slowest volume growth.
End Use:
Application context dictates oil type, finish-cooking method, and portion specification requirements.
- Restaurants:Full-service and casual-dining operators in Belgium and the Netherlands specify blanching parameters and fry stability windows in procurement tenders.
- Household:Home consumption across British and German markets favors resealable packaging with oven and air fryer preparation guidance.
- Cafeterias:Institutional feeding operations in France and Poland prioritize cost-per-portion metrics and extended holding performance.
- Food Trucks:Mobile foodservice in Spanish and Portuguese urban centers demands rapid finish-frying formats compatible with generator-powered equipment.
Restaurants absorb the highest-margin specialized formats. Cafeterias represent the most price-sensitive application segment.
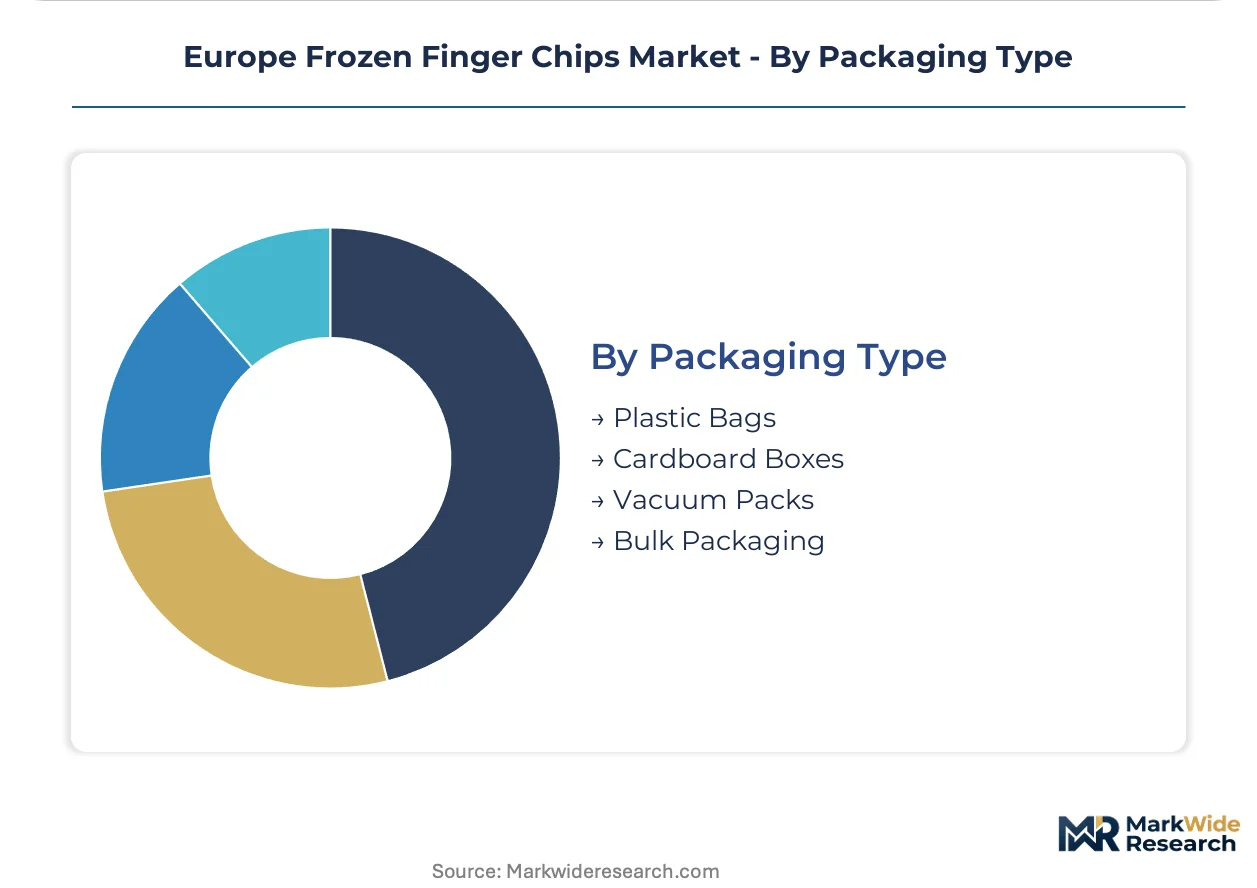
Packaging Type:
Material selection balances shelf-life extension, cold-chain durability, and EMA food-contact compliance costs.
- Plastic Bags:Multi-layer polyethylene structures with oxygen barrier properties dominate retail formats across German and Austrian supermarkets.
- Bulk Packaging:Foodservice-oriented poly-lined corrugated containers enable efficient palletization for Belgian and Dutch distribution centers serving chain restaurants.
- Vacuum Packs:Modified atmosphere packaging extends fry stability for premium-positioned products in French and Italian retail channels.
- Cardboard Boxes:Recyclable paper-based formats respond to EU Green Deal packaging waste directives in Scandinavian markets.
Plastic Bags retain volume leadership. Cardboard Boxes are climbing the fastest on sustainability mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Netherlands' Agriport A7 agro-logistics corridor concentrates frozen potato processing capacity within a 50-kilometer radius of Emmeloord and Dronten. This tax-advantaged zone hosts multiple par-frying facilities drawing from specialized seed potato breeding operations in Flevoland polders.
Germany
Quick-service restaurant chains headquartered in Munich and Berlin are expanding frozen finger chip procurement contracts to offset 12% year-over-year kitchen labor cost inflation. The Federal Office for Consumer Protection and Food Safety enforces strict acrylamide monitoring protocols under national implementation of EFSA benchmarks. Processing clusters in Lower Saxony and Mecklenburg-Western Pomerania are retrofitting blanching lines to meet these thresholds.
United Kingdom
Premium pub chains across Greater London and Manchester are specifying skin-on wedge formats in centralized procurement tenders. The Food Standards Agency coordinates with EFSA on evolving acrylamide baseline assessments. Cold storage facilities in the Midlands distribution corridor are replacing F-Gas refrigeration systems ahead of 2030 phaseout deadlines.
France
Casual-dining operators in Île-de-France and Auvergne-Rhône-Alpes are demanding air fryer-optimized coatings with modified starch barriers. The French Agency for Food, Environmental and Occupational Health Safety implements national controls aligned with EU Green Deal Farm to Fork sustainability disclosure requirements. Processing sites in Picardy are securing certified sustainable sourcing credentials for export contracts.
Belgium
Foodservice distributors serving Brussels and Antwerp are consolidating purchasing through cooperative buying groups. The Federal Agency for the Safety of the Food Chain enforces EMA food-contact material standards on packaging imports. Par-frying expertise clusters around Veurne and Poperinge, where oil management system optimization knowledge remains concentrated among veteran process engineers.
Poland
Independent restaurants in Warsaw and Krakow exhibit frozen finger chip penetration rates 40% below Western European benchmarks. The Chief Sanitary Inspectorate adapts EU regulatory frameworks to national enforcement protocols. Distribution infrastructure in Silesia and Greater Poland voivodeships is expanding cold-chain capacity to serve emerging foodservice demand.
Europe Frozen Finger Chips Market Key Industry Players
Benelux producers anchor the scale tier; Southern European specialists hold regional sourcing positions. The market structures around three to four dominant processors controlling majority par-frying capacity, with mid-tier operators competing on cut specification flexibility. Strategic archetypes include vertically integrated potato breeders, contract manufacturing specialists, and retail-private-label suppliers. Capacity expansion and backward integration into seed potato genetics represent the dominant competitive vectors.
Among Netherlands-based operators, McCain Foods Limited and Farm Frites occupy positions exemplifying scale-driven vertical integration, while Aviko represents the specialized foodservice contract manufacturing archetype. These entities anchor competitive dynamics through distinct supply chain configurations rather than direct product confrontation.
| Leading Market Players |
|---|
| McCain Foods Limited |
| Nomad Foods Ltd |
| Aviko |
| Farm Frites |
| Agristo NV |
| Lutosa S.A. |
| Clarebout Potatoes NV |
| Dr Oetker Group |
| Lamb Weston Holdings |
| Others |
Cost & Logistics Intelligence
Process engineering expertise concentrated in Belgian par-frying hubs drives labor-cost differentials that widen pricing-tier spreads between premium contract manufacturers and economy-oriented processors. REACH compliance timelines and F-Gas equipment retrofitting obligations further stratify cost structures across Dutch and German processing clusters.
Pricing Analysis
Lead-time-driven pricing angles dominate contract negotiations, with premium rates attaching to guaranteed short-lead fulfillment and spot inventory trading at discounts. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by certification grade and volume scale commitments. Price differentiation stems from EFSA acrylamide compliance validation and sustainable sourcing credentials. Cost compression in the economy tier is intensifying because of natural gas price volatility in blanching operations. Cafeteria operators exhibit the highest price sensitivity, while quick-service restaurant chains prioritize fry stability guarantees over unit cost.
Supply Chain Analysis
Workforce availability constraints in Belgian and Dutch manufacturing geographies limit expansion velocity for cryogenic freezing operations. Supply concentrates in the Netherlands, Belgium, and Germany, with seed potato genetics and specialized fry-grade cultivars drawing from concentrated breeding operations in Flevoland polders. Raw material dependencies center on natural gas for par-frying, modified starch coatings, and anti-foaming agents subject to REACH authorization. Single-source vulnerability in seed potato genetics represents the dominant structural risk. Distribution runs through broadline foodservice distributors with contract-based volume commitments anchoring downstream structure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where captive control over seed potato genetics and par-frying capacity determines margin capture. Players are pursuing backward integration into specialized fry-grade cultivar development as the decisive upstream lever.
For Market Incumbents: Hedge against margin compression by locking long-term supply agreements with Dutch seed potato breeders before genetics consolidation accelerates. Secure F-Gas-compliant cold-chain infrastructure ahead of depreciation cycle deadlines to avoid stranded asset risk. Reinforce foodservice contract stickiness through guaranteed cut specification protocols that raise switching costs for quick-service restaurant chains. For New Entrants and Emerging Players: Launch via direct-to-restaurant digital platforms in Poland and Romania where frozen finger chip penetration lags Western European benchmarks by substantial margins. Target independent restaurants in Warsaw and Krakow with flexible minimum order quantities and localized cut specifications. Exploit regulatory compliance gaps among smaller Southern European processors lacking dedicated ECHA affairs functions. For Investors and Strategic Acquirers: Re-rating potential sits with mid-scale contract manufacturers possessing validated low-temperature frying protocols given anticipated EFSA acrylamide benchmark revisions. Long-term viability across the projection horizon favors processors with integrated seed potato supply and certified sustainable sourcing credentials. Watch EFSA threshold negotiation timelines as the critical inflection signal for first-mover valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Seed Potato Genetics | Captive supply of fry-grade cultivars from Flevoland breeding operations insulates against input cost volatility. |
| Low-Acrylamide Production Line Certification | EFSA-compliant blanching protocols in German and French facilities secure premium contract positioning. |
| F-Gas-Compliant Cold-Chain Retrofit | Refrigeration equipment overhaul in Dutch and Belgian distribution centers ensures regulatory continuity. |
| Direct-to-Restaurant Platform Launch | Digital procurement channels in Nordic and British markets disintermediate traditional broadline distributors. |
| Eastern European Distribution Expansion | Cold-chain capacity buildout in Silesia and Greater Poland voivodeships captures underpenetrated foodservice demand. |
Research Approach
EU trade statistics, EFSA technical reports, and national food safety agency filings formed the secondary backbone of data collection. Primary interviews with par-frying plant managers, quick-service restaurant procurement directors, foodservice distribution channel partners, and regulatory affairs specialists at processing facilities validated demand-side assumptions. Bottom-up and top-down triangulation cross-checked volume estimates against capacity utilization rates across Dutch and Belgian processing clusters.
Bottom-up modeling anchored volume projections to individual facility throughput and contract manufacturing commitments, while top-down analysis tested aggregate figures against EU frozen potato trade flows. Segmentation dimensions included product cut geometry, distribution channel structure, end-use application context, and packaging format compliance with EMA food-contact standards. CAGRs were derived from trend extrapolation of foodservice procurement patterns and retail channel velocity. Industry-specific forecast inputs incorporated natural gas price assumptions for blanching operations and F-Gas equipment replacement cycles.
Regulatory timeline delays, seed potato harvest variability, and quick-service restaurant expansion pace are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions regarding EFSA benchmark implementation schedules and EU Green Deal disclosure phase-ins. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed and Frozen Foods
Frozen Basil Leaves Market
Processed and Frozen Foods
Middle East and Africa Freeze-Dried Product Market
Processed and Frozen Foods
Ice Cream and Frozen Dessert Market
Processed and Frozen Foods
Low-Fat Cool Whip Market
Processed and Frozen Foods
Europe Frozen Desserts Market
Processed and Frozen Foods
Frozen Fruit Bars Market
Processed and Frozen Foods
Frozen Shrimp Market
Processed and Frozen Foods
Frozen Meat Grinder Market
Processed and Frozen Foods
Ice Structuring Protein Market
Processed and Frozen Foods
Global Chilled and Deli Foods Market
Processed and Frozen Foods
Taiyaki Ice Cream Market
Processed and Frozen Foods
Processed and Frozen Vegetables Market
Processed and Frozen Foods
Frozen Dough Market
Processed and Frozen Foods
Frozen Meat Market
Processed and Frozen Foods
Frozen Ready Meals Market
Processed and Frozen Foods
Frozen Dumplings Market