
 Uniform Market | 2026-2036
Uniform Market Size, Share, and Industry Trends Forecast 2026-2036
Uniform Market Analysis
Modular uniform bundling is consolidating buyer choice across corporate and industrial procurement channels. Cintas Corporation leverages its rental-services infrastructure to anchor recurring revenue streams in North American facilities management. Dickies competes through workwear specialization that extends its brand into technical trades and outdoor segments. Fristads Kansas Group dominates European industrial uniform supply with flame-resistant fabric expertise that positions it ahead of tightening safety mandates.
Uniforms are standardized garments engineered to specified fabric weights, colorfastness ratings, and dimensional stability for organizational identification and worker protection. Military uniforms incorporate ripstop weaves and NIR-signature management in nylon-cotton blends, while healthcare scrubs prioritize antimicrobial polyester-cotton blends with fluid-barrier performance. Industrial applications lead volume demand through durable cotton and polyester-cotton blends that balance breathability with abrasion resistance. The material segment shows fastest structural expansion in technical wool blends and high-performance synthetic fibers serving extreme-climate and flame-threat environments.
OSHA, NFPA, and ISO 13688 standards govern protective uniform performance, with OSHA's general industry regulations mandating hazard-appropriate apparel and NFPA 2112 specifying flash-fire resistance for oil and gas workers. The EU's REACH chemicals framework and PPE Regulation constrain material inputs and market access for non-compliant suppliers. Stakeholders must monitor evolving PFAS restrictions and biocide regulations that are forcing reformulation of water-repellent and antimicrobial fabric treatments.
Market Dynamics
Modular bundling and rental-service models are compressing traditional uniform procurement cycles, while tightening OSHA and NFPA standards force fabric reformulation across industrial and healthcare segments.
Growth Catalysts
- OSHA workplace safety mandates:Expanding hazard-appropriate apparel requirements in oil and gas operations drive demand for flame-resistant garments certified to NFPA 2112 standards.
- Antimicrobial polyester-cotton blends:Healthcare systems adopting standardized staff apparel programs prioritize fluid-barrier performance and pathogen resistance in clinical environments.
- Vietnam and Bangladesh production clusters:Export-oriented manufacturing hubs scaling technical weaving capacity for ripstop and high-performance synthetic fiber output.
Market Restraints
- Cotton price volatility:Raw fiber cost swings compress margins for durable cotton and polyester-cotton blend producers serving volume industrial applications.
- PFAS regulatory friction:EU REACH restrictions and emerging EPA limits on per- and polyfluoroalkyl substances force reformulation of water-repellent fabric treatments mid-cycle.
- Technical wool supply concentration:Extreme-climate and flame-threat garment manufacturers face limited qualified spinning capacity for high-performance natural fiber blends.
Strategic Opportunities
- NIR-signature management technology:Military uniform specifications incorporating near-infrared reflectance control open adjacent demand from tactical law enforcement and private security sectors.
- Rental-service channel expansion:Facilities management buyers consolidating vendor relationships through subscription-based apparel programs reduce upfront capital requirements and inventory risk.
- Biocide regulation tailwinds:Tightening antimicrobial treatment standards favor suppliers with pre-certified compliant chemistries and documented environmental safety profiles.
Industry Challenges
- ISO 13688 certification timelines:Protective uniform testing protocols for dimensional stability and colorfastness ratings extend product development cycles by 4-6 months.
- Legacy sizing standard fragmentation:Inconsistent measurement systems across North American, European, and Asian markets complicate global SKU rationalization and inventory planning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Uniform Market |
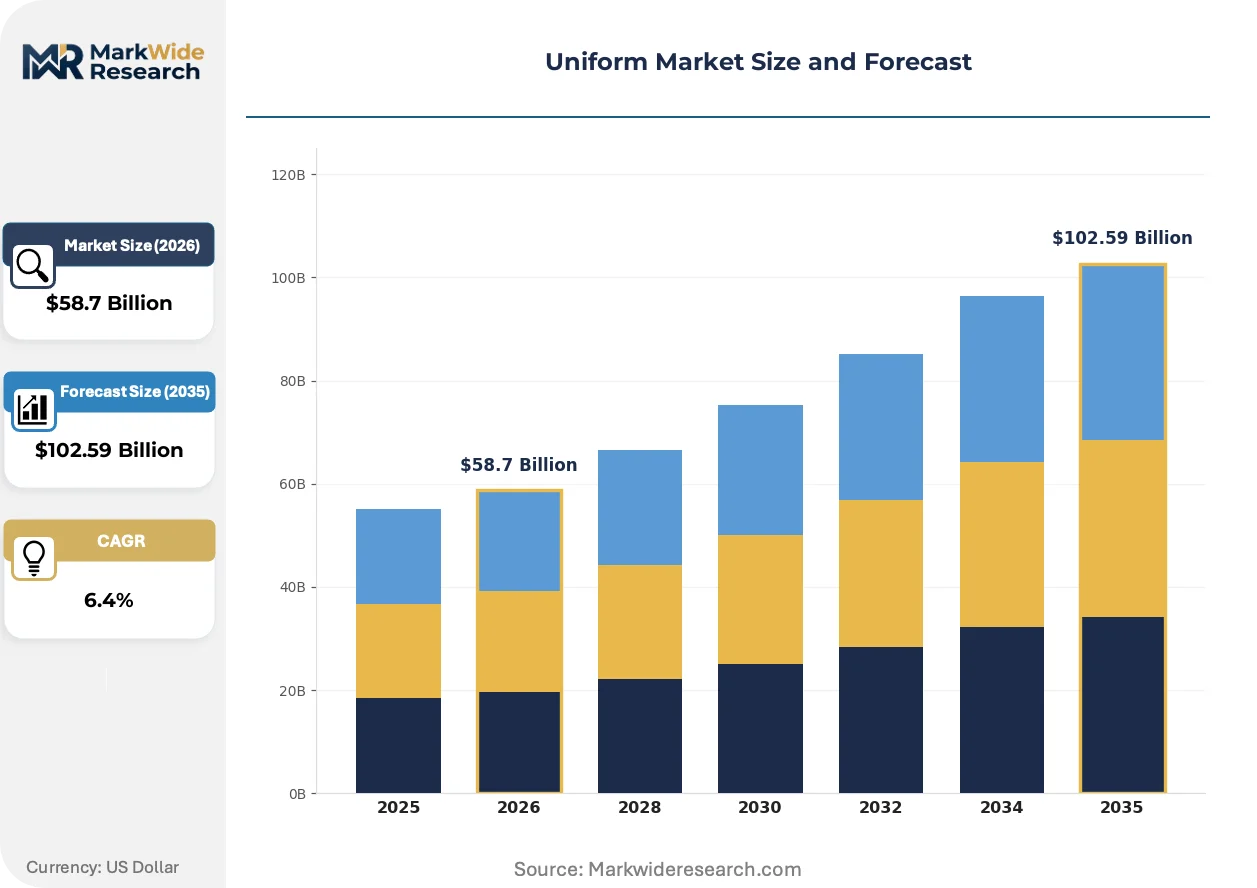
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $102.59 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Military, Healthcare, Industrial, School Material: Cotton, Polyester, Wool, Blends Size: Small, Medium, Large, XL End User: Corporations, Educational Institutions, Government Agencies, NGOs |
| Companies Covered | Carhartt, Dickies, Cintas Corporation, Fristads Kansas Group, Portwest, UniFirst Corporation, Red Kap, Simon Jersey, Vestis Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Uniform Market Emerging Trajectories
Digital textile printing and on-demand manufacturing are collapsing minimum order quantities, while smart fabric integration and circular material recovery reshape value capture across the uniform value chain.
Phase-change material (PCM) microencapsulation is rewriting thermal regulation performance in extreme-climate workwear. Mining, construction, and cold-storage logistics operators in Canada and Scandinavia are specifying PCM-lined garments for shift-long temperature stability. This technology is rewriting procurement specifications by embedding performance guarantees directly into fabric substrate contracts rather than finished garment warranties.
EU REACH chemicals framework amendments targeting PFAS and restricted substance lists are accelerating substitution of fluorinated water-repellent treatments with bio-based alternatives. Industrial laundries serving rental uniform programs face reformulation costs and re-certification delays. European oil and gas sector buyers are pre-qualifying suppliers with demonstrated PFAS-free chemistries to avoid supply disruption.
Corporate sustainability mandates are compressing uniform replacement cycles and redirecting spend toward take-back and fiber-recovery programs. Fortune 500 facilities managers in the United States are unbundling disposal services from procurement contracts and selecting vendors with verified mechanical recycling partnerships. This shift is most visible in technology and financial services sectors where employee apparel volumes intersect with public ESG disclosure requirements.
Uniform Market Segmentation
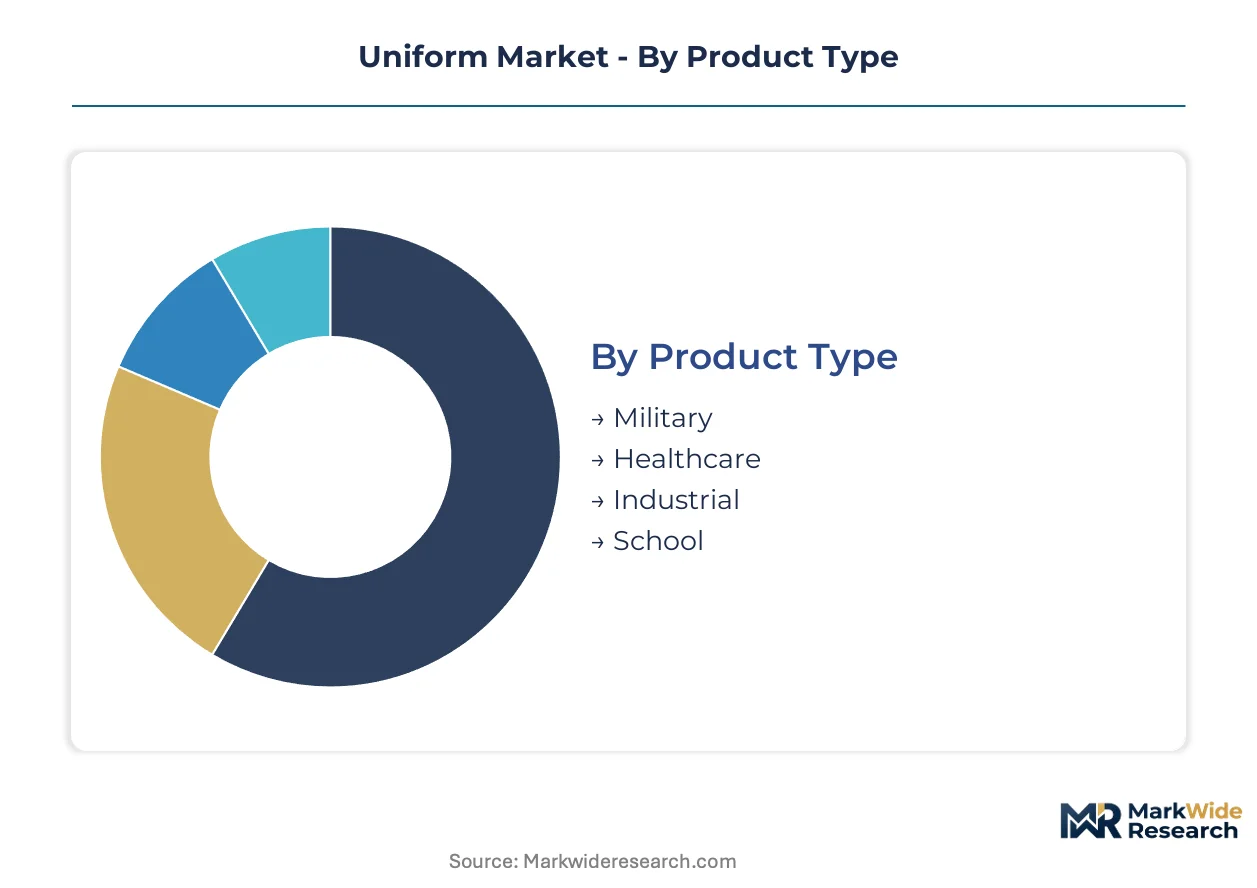
Uniform procurement decisions hinge on balancing protection level, replacement frequency, and regulatory compliance across divergent end-use environments. Segmentation reveals how fabric specification and sizing standardization create distinct margin profiles and supply chain requirements for manufacturers.
Product Type:
Buyer selection prioritizes hazard-appropriate performance certification and replacement cycle predictability.
- Military:Ripstop nylon-cotton blends with NIR-signature management dominate procurement specifications. Defense ministries in the United States and United Kingdom are consolidating multi-year uniform contracts with embedded technical upgrade clauses.
- Industrial:Durable cotton and polyester-cotton blends balance breathability with abrasion resistance for oil and gas, construction, and manufacturing floors. OSHA hazard-appropriate apparel mandates are compressing procurement cycles for flame-resistant variants certified to NFPA 2112.
- Healthcare:Antimicrobial polyester-cotton blends with fluid-barrier performance address pathogen exposure protocols.
- School:Cost-optimized cotton and polyester blends emphasize colorfastness durability through repeated commercial laundering.
Industrial leads on scale; military leads on momentum.
Material:
Raw fiber selection determines thermal regulation, flame resistance, and laundering durability across climate and hazard exposures.
- Blends:Polyester-cotton and technical synthetic-natural combinations optimize cost-performance ratios for high-frequency replacement programs. Healthcare systems in Germany and Japan are standardizing on antimicrobial-treated blends with documented environmental safety profiles.
- Cotton:Natural fiber base for breathability and skin tolerance in extended-wear environments. Price volatility in global cotton futures compresses margin predictability for volume industrial suppliers.
- Polyester:Synthetic durability and colorfastness for high-visibility and high-laundering applications.
- Wool:Technical wool blends serve extreme-climate and flame-threat environments with limited qualified spinning capacity.
Blends dominate volume throughput; wool commands premium positioning.
Size:
Fit standardization complexity escalates with geographic distribution breadth and workforce demographic diversity.
- Medium:Core volume SKU anchoring inventory planning and production scheduling for corporate and institutional programs. North American and European procurement patterns concentrate demand in this tier.
- Large:Secondary volume concentration serving industrial and military segments with broader physique distributions.
- Small:Healthcare and educational institution requirements with gender-diverse workforce proportions.
- XL:Specialized industrial and protective gear accommodating layering systems and body armor integration.
Medium anchors production economics; XL carries highest per-unit specification variance.
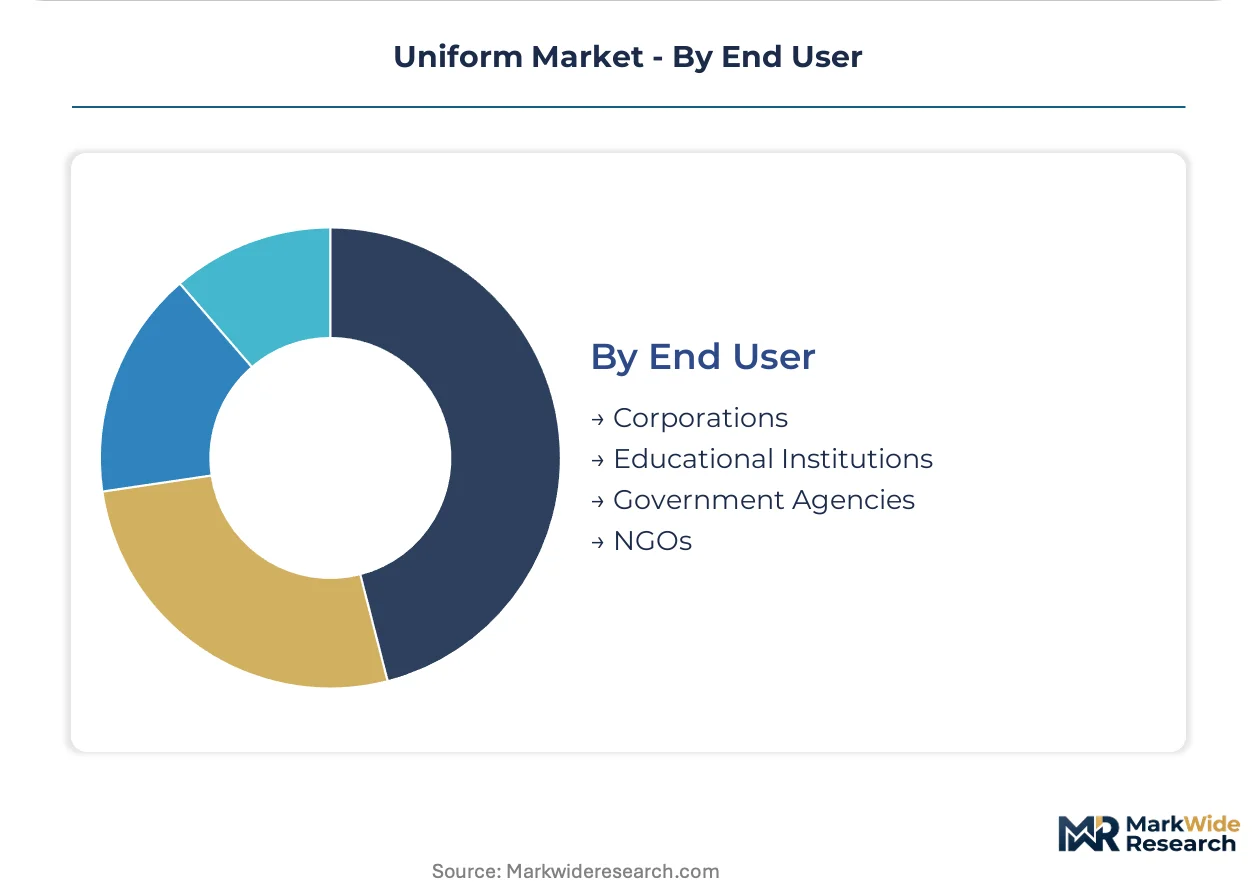
End User:
Contract structure and vendor consolidation appetite vary sharply across public procurement rigor and ESG disclosure obligations.
- Government Agencies:Defense, law enforcement, and public safety departments mandate certified performance with multi-year contract stability. United States federal procurement and United Kingdom Ministry of Defence frameworks emphasize domestic content requirements.
- Corporations:Fortune 500 facilities managers are unbundling disposal services and selecting vendors with verified mechanical recycling partnerships to meet ESG disclosure requirements.
- Educational Institutions:Cost-sensitive bulk procurement with extended replacement cycles and commercial laundering durability specifications.
- NGOs:Fragmented demand with mission-driven supplier selection criteria and field-deployment logistics complexity.
Government Agencies provide contract duration; Corporations drive sustainability specification evolution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial uniform production originated in the textile mills of 19th-century England and New England, spreading through military procurement networks to establish today's geographically distributed supply base spanning technical weaving clusters and rental-service infrastructure across multiple continents.
United States
Healthcare systems in Texas and California are expanding standardized staff apparel programs with antimicrobial specifications. OSHA workplace safety regulations mandate hazard-appropriate apparel for oil and gas operations concentrated in the Permian Basin and Gulf Coast. Cintas Corporation anchors rental-service infrastructure across North American facilities management channels.
Germany
Industrial laundries serving rental uniform programs face reformulation costs under EU REACH chemicals framework amendments. The country's technical textile sector specializes in flame-resistant fabric expertise ahead of tightening safety mandates. Manufacturing clusters in North Rhine-Westphalia scale capacity for high-performance synthetic fiber output.
Vietnam
Export-oriented uniform production clusters are scaling technical weaving capacity for ripstop and synthetic blends serving military procurement contracts. The country's central bank monitors currency stability for dollar-denominated export contracts. Ho Chi Minh City and Hanoi anchor garment manufacturing zones with qualified spinning capacity expansion.
Bangladesh
Volume industrial applications drive demand for durable cotton and polyester-cotton blends from the country's export processing zones. The central bank regulates working capital for spinning mills facing raw fiber cost volatility. Dhaka and Chittagong concentrate garment assembly operations with backward integration into fabric finishing.
United Kingdom
The Ministry of Defence consolidates multi-year uniform contracts with embedded technical upgrade clauses for NIR-signature management specifications. Simon Jersey occupies position within educational institution procurement channels. Manchester and Birmingham retain historical textile expertise converted to technical workwear production.
Uniform Market Vendor Landscape
The competitive structure tilts toward rental-service operators with recurring revenue infrastructure. Market concentration splits between integrated rental providers and specialized workwear manufacturers. Three archetypes dominate: subscription-based facilities managers, technical fabric specialists, and volume garment assemblers. Consolidation proceeds through multi-year contract anchoring and geographic expansion into adjacent service territories.
Within the rental-service tier, Cintas Corporation and UniFirst Corporation exemplify the subscription-based facilities management model. Dickies and Carhartt occupy positions as workwear specialists extending brand recognition into technical trades. Fristads Kansas Group anchors European industrial supply with flame-resistant fabric positioning. Portwest and Red Kap sit within the volume-accessible segment serving cost-optimized procurement channels.
| Leading Market Players |
|---|
| Carhartt |
| Dickies |
| Cintas Corporation |
| Fristads Kansas Group |
| Portwest |
| UniFirst Corporation |
| Red Kap |
| Simon Jersey |
| Vestis Corp. |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap textile specialists in Vietnam and Bangladesh anchor volume production, compressing margins for price-takers while private-equity-rolled-up rental-service operators in North America extract premium pricing through subscription lock-in. This ownership fragmentation creates divergent pricing discipline across procurement channels.
Pricing Analysis
Subscription-based rental pricing dominates corporate and industrial channels, separating certified flame-resistant tiers from standard workwear from economy-grade cotton basics. Price differentiation rests on NFPA 2112 certification status and embedded service bundling. Cost compression in economy cotton tiers is intensifying because of raw fiber volatility. Educational institutions exhibit highest price sensitivity; defense ministries show lowest.
Supply Chain Analysis
Single-source vulnerability sits with Bangladeshi spinning capacity for durable cotton and Vietnamese technical weaving for ripstop synthetics. Raw material dependencies draw from global cotton futures, polyester chip feedstocks, and specialized wool scouring. Tariff exposure runs through US-China trade friction affecting synthetic fiber inputs. Distribution runs through industrial laundry networks and direct-to-facility rental contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in uniform supply hinges on PFAS-free chemistry substitution creating premium-tier pricing power and rental-service consolidation capturing recurring revenue stability.
For Market Incumbents: Hedge cotton cost exposure through backward integration into Vietnamese spinning capacity. Defend rental-service margins by accelerating PFAS-free certification ahead of EPA limits. Lock in multi-year healthcare system contracts before antimicrobial biocide standards tighten further. For New Entrants and Emerging Players: Mid-sized European industrial laundries facing REACH reformulation costs represent an underserved buyer archetype for compliant chemistry partnerships. Private security firms seeking NIR-signature management specifications offer adjacent demand with lower certification barriers. Lead with technical fabric co-development rather than price undercutting. For Investors and Strategic Acquirers: Valuations sit cheapest among family-owned Bangladeshi garment assemblers lacking brand equity and direct buyer relationships. Long-term viability favors subscription-based facilities managers with embedded customer switching costs. Watch for PFAS regulatory enforcement acceleration as inflection signal for compliant-chemistry supplier premiums.| Strategic Initiative | Industry Significance |
|---|---|
| PFAS-Free Chemistry Certification | REACH and EPA restrictions favor suppliers with pre-qualified compliant treatments ahead of enforcement. |
| Rental-Service Channel Expansion | Cintas and UniFirst demonstrate subscription models reduce buyer capital requirements and inventory risk. |
| Technical Weaving Capacity Addition | Vietnamese clusters scaling ripstop output capture defense procurement contracts from legacy US suppliers. |
| Antimicrobial Blend Reformulation | German and Japanese healthcare systems prioritize documented environmental safety profiles in supplier selection. |
| Mechanical Recycling Partnership | Fortune 500 facilities managers unbundle disposal services to meet ESG disclosure requirements. |
Methodological Framework
Direct dialogue with procurement managers at industrial laundries, textile plant engineers in Vietnam and Bangladesh, and regulatory affairs leads at European chemical suppliers grounded qualitative findings. Secondary validation drew from OSHA enforcement databases, EU REACH substance restriction updates, US customs import records, and SEC filings from listed rental-service operators. Bottom-up demand modeling and top-down supply capacity estimates were triangulated to anchor projections.
Segment-level value outputs across the projection horizon reflect discrete modeling of military, industrial, healthcare, and school end-use demand. Material-grade stratification, regional regulatory clusters, and procurement channel structure shaped the analytical framework. CAGRs were derived from weighted average growth across these dimensions, with specific inputs including cotton futures volatility indices and defense ministry contract award timelines.
Underlying measurement precision varies by segment; military and healthcare procurement carry tighter precision than fragmented NGO demand. Forecasts reflect documented assumptions about regulatory enforcement timing and raw material cost trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel Textiles
Down Jacket Market
Apparel Textiles
Maternity Wear Market
Apparel Textiles
Japan Denim Jeans Market
Apparel Textiles
Global Western Wear Market
Apparel Textiles
Flame Retardant Apparel Market
Apparel Textiles
Thailand Garment Industry Market
Apparel Textiles
Rolle Market
Apparel Textiles
Cooling Apparel Market
Apparel Textiles
Women's Cheongsam Market
Apparel Textiles
Welding Apparels Market
Apparel Textiles
Knitwear Market
Apparel Textiles
Clothing Manufacturing Service Market
Apparel Textiles
Blank Apparel Market
Apparel Textiles
North America Textile Garment Market
Apparel Textiles
Zipper Market
Apparel Textiles
Women's Jerseys, Sweatshirts and Pullovers Market