
 Thailand Garment Industry Market | 2026-2036
Thailand Garment Industry Market Size, Share, and Industry Trends Forecast 2026-2036
Thailand Garment Industry Market Insights
Cut-and-sew outsourcing revenue is reconfiguring margin distribution between full-package production and basic assembly services in Thailand. Thai Wacoal PCL leverages its intimate apparel specialization to command premium pricing from Japanese department store buyers. Jong Stit anchors large-volume denim and casualwear contracts for European fast-fashion retailers through vertically integrated fabric-to-garment capacity. VT Garment differentiates via technical outerwear and performance sportswear manufacturing certified for US and EU import standards.
The Thailand Garment Industry encompasses the design, cutting, sewing, finishing, and packaging of woven and knitted apparel using fiber contents ranging from 100% cotton single jersey to 92/8 polyester-spandex blends, with stitch densities typically specified at 12-14 SPI for woven seams and 10-12 SPI for knit constructions, serving branded retailers, private-label distributors, and direct-to-consumer channels that require compliance with destination-market chemical and labeling regulations. T-Shirts and Pants categories dominate volume throughput due to standardized sizing and minimal fit complexity that accelerates line balancing. Cotton-based garment production retains structural importance for skin-contact applications despite rising raw-material price volatility. The E-commerce distribution channel is expanding fastest as Thai manufacturers build direct-ship capabilities bypassing traditional importer intermediaries.
Thailand's Ministry of Industry enforces Factory Act standards governing working hours and machinery safety in textile plants, while the Department of Foreign Trade administers rules of origin documentation essential for ASEAN trade-bloc tariff preferences and EU GSP beneficiary status. The Thailand Textile Institute promotes OEKO-TEX and GOTS certification adoption to maintain export eligibility amid tightening EU Green Deal due diligence requirements. Stakeholders must monitor how EU deforestation-free supply-chain regulations and emerging US customs enforcement on forced-labor presumptions reshape sourcing qualification criteria and factory audit intensity.
Market Dynamics
The Thailand garment sector is reconfiguring around automated cut-and-sew infrastructure as the Board of Investment redirects capital toward textile zones in the Eastern Economic Corridor, compressing lead times for sportswear procurement from international athletic brands.
Growth Catalysts
- Board of Investment Tax Incentives:Restructured benefits for textile zone investments are pulling capital toward Chonburi and Rayong industrial estates, accelerating automated facility deployment.
- EU GSP Beneficiary Status:Preferential tariff treatment under EU Generalized Scheme of Preferences maintains Thailand's cost competitiveness for denim and casualwear exports to European fast-fashion retailers.
- Sportswear Procurement Expansion:International athletic brands are expanding production commitments to Thai contract manufacturers, concentrating demand in technical outerwear and performance apparel segments.
Market Restraints
- Cotton Price Volatility:Raw-material cost swings for cotton-based single jersey fabrics are squeezing margin predictability for skin-contact garment producers.
- EU Deforestation-Free Supply-Chain Regulations:Due diligence requirements for forest-risk commodities are extending compliance burdens to cotton and man-made fiber sourcing, raising audit intensity for EU-bound exports.
- Labor Pool Constraints:Factory Act working-hour standards and machinery safety enforcement are tightening workforce availability in densely populated production zones.
Strategic Opportunities
- E-Commerce Direct-Ship Capabilities:Thai manufacturers are building bypass infrastructure around traditional importer intermediaries, capturing margin from direct-to-consumer channels.
- Technical Outerwear Certification:OEKO-TEX and GOTS adoption promoted by the Thailand Textile Institute opens eligibility for premium positioning in EU and US markets with tightening chemical compliance.
- Polyester-Spandex Blend Expansion:92/8 technical knit constructions are displacing pure cotton in performance applications, enabling higher-value product mix rotation.
Industry Challenges
- Forced-Labor Audit Intensity:Emerging US customs enforcement on forced-labor presumptions is requiring documentation system overhauls for factory qualification maintenance.
- Stitch Density Specification Complexity:Divergent SPI standards between woven seams at 12-14 SPI and knit constructions at 10-12 SPI are fragmenting line-balancing optimization across mixed-product facilities.
- Legacy System Integration:Automated cut-and-sew equipment deployment faces friction from existing ERP and production planning infrastructure in established Thai plants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thailand Garment Industry Market |
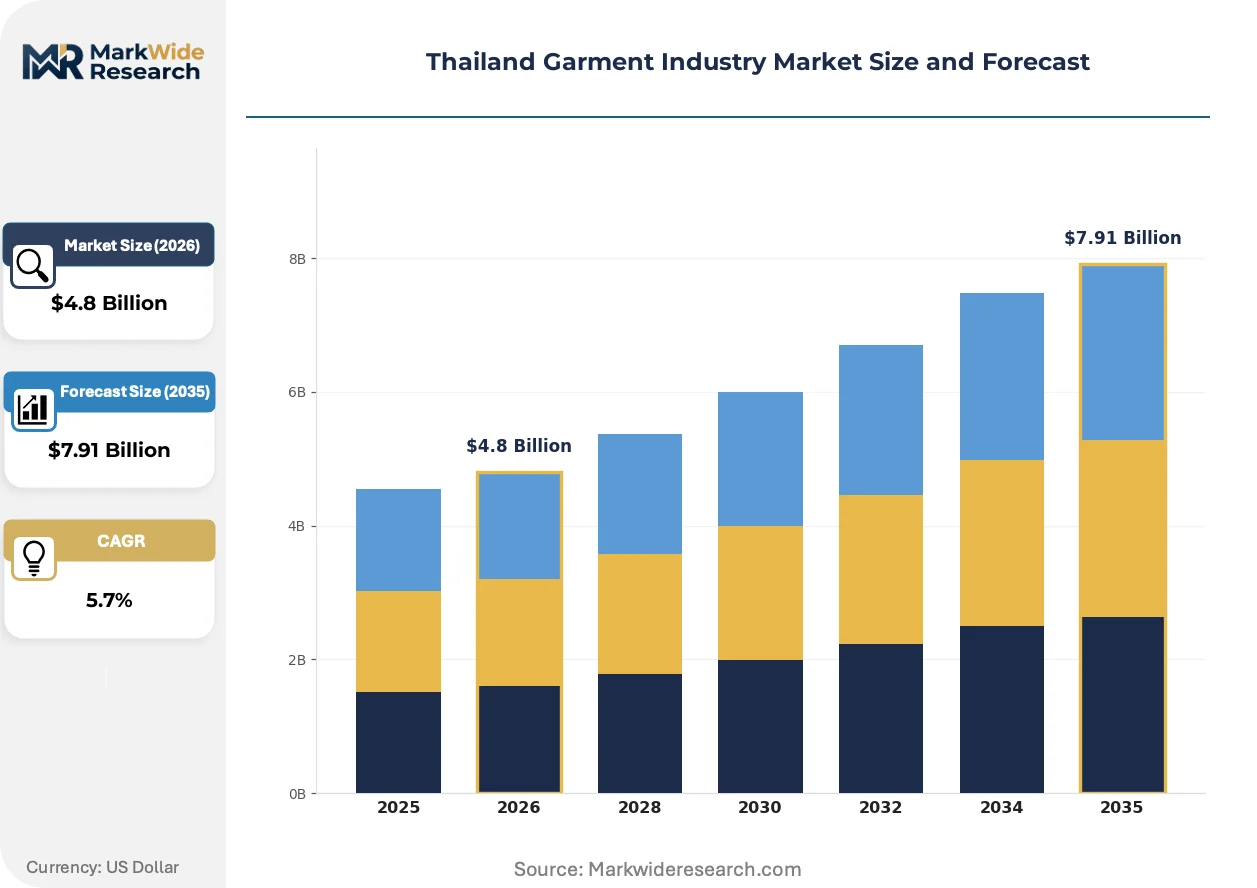
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: T-Shirts, Dresses, Jackets, Pants Material: Cotton, Polyester, Nylon, Wool End User: Retail, Wholesale, E-commerce, Exporters Distribution Channel: Online, Offline, Direct Sales, Partnerships |
| Companies Covered | High-Tech Apparel Co Ltd, Jong Stit, Thai Wacoal PCL, VT Garment, Nanyang Garment Co Ltd, Thai Garment Export Co Ltd, HBI Manufacturing (Thailand) Ltd, Wacoal (Thailand) PCL, ICC Co Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thailand Garment Industry Market Trends and Innovations
Digital manufacturing systems and compliance automation are compressing the gap between Thai production capacity and destination-market regulatory requirements, reshaping how manufacturers qualify for branded retailer contracts.
Automated pattern-making and cutting systems are digitizing the transition from marker-making to fabric lay-up, reducing material waste percentages in high-volume denim and casualwear operations. European fast-fashion retailers are mandating these systems as baseline qualifications for new contract awards. The technology is digitizing margin recovery in basic assembly services that previously offered limited pricing leverage.
EU Green Deal due diligence requirements are extending chemical management obligations upstream to fiber suppliers and dye houses serving Thai garment exporters. The Thailand Textile Institute is coordinating OEKO-TEX certification adoption to maintain EU market eligibility. Technical outerwear manufacturers with existing US and EU import standard compliance are adapting fastest to expanded documentation demands.
Direct-to-consumer channel development is fragmenting traditional importer-distributor relationships as Thai manufacturers invest in pick-pack-ship infrastructure for e-commerce fulfillment. Sportswear and intimate apparel segments are leading this channel pivot due to standardized sizing and lower return rates. The Eastern Economic Corridor industrial estates near Laem Chabang port are becoming the geographic focal point for these direct-ship capabilities.
Thailand Garment Industry Market Segmentation
Thai garment manufacturers configure production lines, inventory buffers, and quality protocols differently across product categories, fiber inputs, and customer channels. Understanding these segment boundaries clarifies where automation investments and compliance certifications deliver the strongest returns.
Product Type:
After-sales service intensity varies sharply across garment categories, with technical outerwear requiring repair networks and fit-adjustment support while basic knitwear demands minimal post-purchase engagement.
- T-Shirts:Single jersey and interlock constructions in 100% cotton or cotton-poly blends dominate volume throughput. Chonburi industrial estates concentrate production for fast-fashion retailers demanding rapid replenishment cycles with minimal fit complexity.
- Pants:Woven denim and twill constructions require precise pattern grading and wash-finishing capabilities. Rayong-based manufacturers anchor large-volume contracts for European buyers, though cotton price volatility squeezes margin predictability on basic five-pocket styles.
- Dresses:Mixed woven and knit assemblies with varied silhouettes fragment line-balancing efficiency. Thai producers serve regional Southeast Asian markets and domestic department stores with mid-tier positioning.
- Jackets:Technical outerwear with seam-sealing, insulation, and multi-layer construction commands premium pricing. VT Garment and similar specialists target US and EU import standards with OEKO-TEX certified facilities.
T-Shirts holds the largest share; momentum sits with Jackets as technical performance specifications displace commodity assembly.
Material:
Cost tier stratification separates commodity natural fibers from engineered synthetics, with pricing power concentrating in technical blend formulations that command specification premiums.
- Cotton:Skin-contact applications retain structural importance despite raw-material price swings. Thai Wacoal PCL and intimate apparel specialists source long-staple varieties for Japanese department store buyers requiring soft hand-feel and dye consistency.
- Polyester:92/8 polyester-spandex technical knits are displacing pure cotton in sportswear applications. The Thailand Textile Institute promotes certification adoption to maintain EU market eligibility for these higher-value constructions.
- Nylon:Lightweight durability drives demand in outerwear linings and activewear shells. Board of Investment tax incentives accelerate automated cutting investment for these precision-dependent fabrics.
- Wool:Limited domestic spinning capacity restricts volume, with most wool-blend garments serving premium positioning for cold-weather export markets.
Cotton retains volume leadership; polyester-spandex blends are climbing the fastest as athletic brands expand Thai production commitments.
End User:
Customer type determines order-size economics, with exporters and e-commerce channels fragmenting traditional wholesale consolidation.
- Retail:Branded store networks and domestic department stores demand consistent replenishment with standardized sizing. Thai manufacturers maintain buffer inventory for these predictable, high-frequency orders.
- Wholesale:Private-label distributors aggregate volume across multiple retail banners, concentrating purchasing power in the hands of large European and North American intermediaries.
- E-commerce:Direct-to-consumer channels are expanding fastest as Thai manufacturers build pick-pack-ship capabilities bypassing traditional importer intermediaries. Eastern Economic Corridor estates near Laem Chabang port anchor these direct-ship investments.
- Exporters:Contract manufacturing for international athletic brands concentrates in technical outerwear and performance apparel segments requiring US and EU compliance documentation.
Retail holds the largest share; e-commerce is gaining share fastest as manufacturers capture margin from disintermediation.
Distribution Channel:
Geographic concentration of logistics infrastructure shapes channel viability, with Eastern Economic Corridor industrial estates becoming the focal point for hybrid online-offline fulfillment.
- Online:Brand-owned websites and marketplace platforms require real-time inventory visibility and flexible minimum order quantities. Thai manufacturers invest in ERP integration to serve these fragmented demand signals.
- Offline:Traditional brick-and-mortar retail and wholesale showrooms remain significant for fit-dependent categories where physical inspection reduces return rates.
- Direct Sales:Manufacturer-owned retail and pop-up channels capture full margin but require working capital for inventory carrying costs and store operations.
- Partnerships:Strategic alliances with logistics providers and technology platforms enable smaller manufacturers to access export markets without dedicated infrastructure investment.
Offline holds the largest share; online is expanding most quickly as digital infrastructure compresses lead times for international buyers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European fast-fashion retailers exhibit the lowest demand elasticity, absorbing premium pricing for certified technical outerwear, while Southeast Asian domestic markets remain highly price-sensitive on basic cotton knits.
Chonburi Province
Sportswear procurement from international athletic brands drives capacity expansion in the Eastern Economic Corridor. The Board of Investment restructured tax incentives for textile zone investments in 2023. Automated cut-and-sew facilities near Laem Chabang port compress lead times for US and EU-bound exports.
Rayong Province
Denim and casualwear contracts from European fast-fashion retailers anchor large-volume production. Factory Act standards enforced by the Ministry of Industry govern working hours and machinery safety. Vertically integrated fabric-to-garment clusters concentrate near Map Ta Phut industrial estates.
Bangkok Metropolitan Region
Intimate apparel specialization serves Japanese department store buyers requiring soft hand-feel consistency. The Thailand Textile Institute promotes OEKO-TEX certification adoption to maintain EU market eligibility. Design and sample development studios cluster in Pathum Thani and Nonthaburi districts.
Samut Prakan Province
E-commerce direct-ship capabilities bypass traditional importer intermediaries for fastest channel expansion. The Department of Foreign Trade administers rules of origin documentation for ASEAN trade-bloc tariff preferences. Pick-pack-ship infrastructure investments concentrate near Suvarnabhumi Airport logistics corridors.
Chiang Mai Province
Smaller-batch production serves regional Southeast Asian markets with mid-tier positioning. Labor Pool Constraints from Factory Act enforcement tighten workforce availability less severely than in eastern industrial zones. Craft-oriented garment workshops maintain niche positioning for domestic heritage brands.
Thailand Garment Industry Market Competitive Landscape
Intimate apparel specialists and technical outerwear fabricators split the market into premium-margin and scale-driven segments. Thai manufacturers configure around three strategic archetypes: vertically integrated denim operators, certified performance apparel specialists, and regional fast-fashion suppliers. Consolidation pressure concentrates among mid-tier basic assembly services as automated equipment raises minimum efficient scale. Capacity expansion and certification upgrading represent the dominant competitive moves.
Within the premium-tier vector, Thai Wacoal PCL exemplifies intimate apparel specialization commanding pricing power from Japanese department store buyers. VT Garment occupies a position among technical outerwear manufacturers certified for US and EU import standards. Jong Stit anchors the scale-driven segment through large-volume denim and casualwear capacity. These three represent distinct archetypes rather than direct competitors, each serving non-overlapping buyer segments with differentiated compliance and production capabilities.
| Leading Market Players |
|---|
| High-Tech Apparel Co Ltd |
| Jong Stit |
| Thai Wacoal PCL |
| VT Garment |
| Nanyang Garment Co Ltd |
| Thai Garment Export Co Ltd |
| HBI Manufacturing (Thailand) Ltd |
| Wacoal (Thailand) PCL |
| ICC Co Ltd |
| Others |
Pricing and Supply Chain Analysis
EU deforestation-free supply-chain regulations function as a regulatory chokepoint that widens pricing tier spreads between certified and uncertified Thai garment exporters while forcing supply chain restructuring toward traceable fiber sourcing. Cotton price volatility simultaneously compresses margin predictability across basic assembly tiers and accelerates polyester-spandex blend adoption as manufacturers seek cost stability.
Pricing Analysis
After-sales service revenue from repair networks and fit-adjustment support drives lifetime value concentration in technical outerwear, while basic knitwear depends on transactional per-unit pricing with minimal post-purchase engagement. Three-tier pricing structure across premium OEKO-TEX certified, standard compliant, and economy non-certified levels separates Thai Wacoal PCL's intimate apparel positioning from commodity assembly. Cost compression in cotton-based single jersey production is intensifying because of raw-material price swings, squeezing margin predictability for skin-contact garment producers. European fast-fashion retailers exhibit the lowest price sensitivity, absorbing premium pricing for certified technical outerwear, while Southeast Asian domestic markets remain highly price-sensitive on basic cotton knits.
Supply Chain Analysis
Supplier-financing through extended payment terms from fiber traders and supply-chain finance facilities from Thai commercial banks sustains working capital for automated equipment deployment in Eastern Economic Corridor industrial estates. Geographic supply concentration draws from China for polyester-spandex technical knits, India for long-staple cotton varieties, and Vietnam for competing cut-and-sew capacity. Raw material dependencies rest on cotton futures markets, petroleum-derived synthetic fiber feedstocks, and imported dye chemicals from Chinese specialty chemical producers. Single-source vulnerability in EU-bound export certification creates exposure as OEKO-TEX and GOTS audit intensity escalates. Distribution runs through Laem Chabang port for ocean freight consolidation and Suvarnabhumi Airport corridors for e-commerce direct-ship fulfillment.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among international athletic brands and European fast-fashion retailers as procurement consolidation reduces the number of qualified Thai contract manufacturers, fragmenting margin distribution toward certified specialists.
For Market Incumbents: Entrench certification advantages by accelerating OEKO-TEX and GOTS adoption ahead of EU Green Deal due diligence expansion, and deepen backward integration into fabric finishing to capture margin from dye-house intermediaries. Automated cut-and-sew equipment deployment in Rayong and Chonburi industrial estates defends scale positions against Vietnamese cost competition. For New Entrants and Emerging Players: Establish a beachhead in e-commerce direct-ship capabilities for sportswear and intimate apparel segments where standardized sizing reduces return-rate risk. Technical outerwear certification gaps among mid-tier Bangkok Metropolitan Region producers represent the most penetrable white-space, with go-to-market leverage through pick-pack-ship infrastructure partnerships near Suvarnabhumi Airport logistics corridors. For Investors and Strategic Acquirers: Certified performance-apparel specialists with existing US and EU import standard compliance present acquisition targets with defensible positioning against regulatory tightening. Long-term viability across the analysis window hinges on automation scale and certification depth rather than labor-cost arbitrage. Watch for forced-labor audit intensity escalation as an inflection indicator that would accelerate consolidation among documentation-deficient producers.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Cut-and-Sew Deployment | Board of Investment tax incentives accelerate facility investment in Eastern Economic Corridor industrial estates. |
| Certification Upgrading Program | Thailand Textile Institute coordination maintains EU GSP beneficiary status amid Green Deal due diligence expansion. |
| Direct-Ship Infrastructure Buildout | Laem Chabang port proximity enables bypass of traditional importer intermediaries for e-commerce channels. |
| Backward Integration into Fabric Finishing | Vertically integrated fabric-to-garment capacity captures margin from Jong Stit's denim and casualwear model. |
| Technical Blend Formulation Expansion | 92/8 polyester-spandex displacement of pure cotton responds to athletic brand procurement expansion. |
Research Methodology
Desk research of customs trade records, Thailand Textile Institute certification databases, and Board of Investment incentive disclosure filings preceded structured interviews with garment factory operations directors, European fast-fashion retailer procurement leads, Japanese department store buyer representatives, and logistics corridor development officers. Primary fieldwork combined with secondary validation against Factory Act enforcement records and Department of Foreign Trade rules of origin documentation. Bottom-up capacity assessment across Chonburi, Rayong, and Bangkok Metropolitan Region industrial estates triangulated with top-down export value aggregation.
Assumptions held fixed include continuation of EU GSP beneficiary status, sustained Board of Investment tax incentive structures, and stable ASEAN trade-bloc tariff preference frameworks, while cotton price volatility trajectories and forced-labor enforcement intensity were varied across sensitivity scenarios. Segmentation dimensions modeled encompass product type, fiber material composition, end-user channel, and geographic production cluster. CAGRs were derived from installed capacity expansion schedules mapped against buyer procurement commitment timelines. Polyester-spandex blend adoption curves and automated equipment deployment rates served as industry-specific forecast inputs.
Sensitivities concentrate around EU deforestation-free regulation implementation timing, US customs forced-labor presumption enforcement escalation, and cotton futures market disruption. Forecasts reflect documented assumptions without guarantee of realization. Macroeconomic deviation, regulatory acceleration, or technological substitution in synthetic fiber production would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel Textiles
Automotive Textiles Market
Apparel Textiles
Clothing Manufacturing Service Market
Apparel Textiles
North America Garment Steamers Market
Apparel Textiles
Cooling Apparel Market
Apparel Textiles
Smart Apparel Market
Apparel Textiles
Stockings Market
Apparel Textiles
Global Western Wear Market
Apparel Textiles
Uniform Market
Apparel Textiles
Asia-Pacific Textile Garment Market
Apparel Textiles
China Denim Jeans Market
Apparel Textiles
Denim Market
Apparel Textiles
Smart Clothing Market
Apparel Textiles
South America Lingerie Market
Apparel Textiles
Dye Sublimated Apparel Market
Apparel Textiles
Asia-Pacific Footwear Sole Material Market
Apparel Textiles
Waterproof Fabrics for Sports Apparel Market