
 Organic Baby Clothes Market | 2026-2036
Organic Baby Clothes Market Size, Share, and Industry Trends Forecast 2026-2036
Organic Baby Clothes Market Outlook
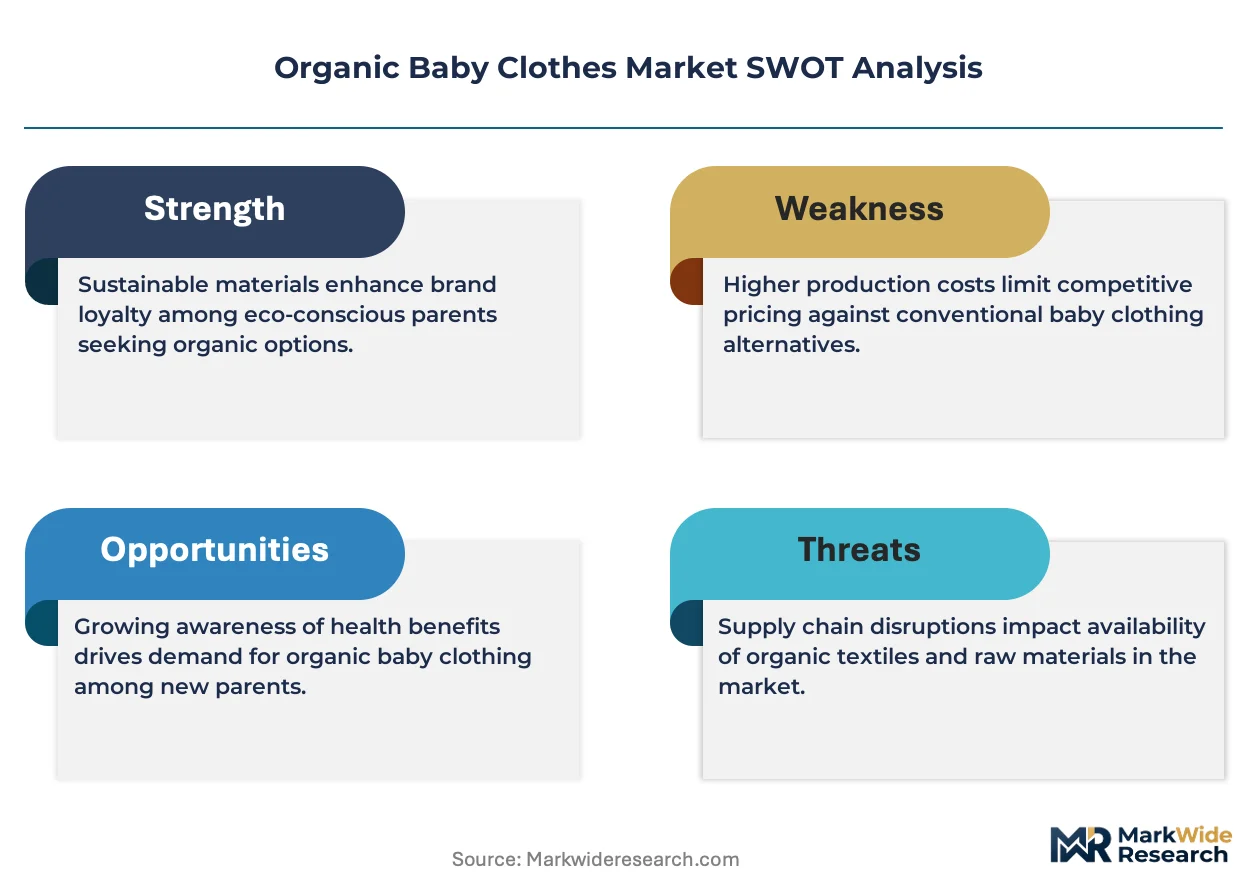
GOTS certification is collapsing the competitive field by filtering out suppliers unable to meet its organic fiber and social compliance thresholds. Hanna Andersson leverages its Pacific Northwest manufacturing base to sustain premium positioning. Monica + Andy anchors its model on direct-to-consumer transparency and limited-batch releases. Burt's Bees Baby competes through mass-retail distribution scale and accessible price points.
Organic baby clothes comprise garments manufactured from fibers grown without synthetic pesticides, GMOs, or petroleum-based fertilizers, typically requiring GOTS or OEKO-TEX Standard 100 verification and minimum organic content thresholds. Their primary purpose centers on reducing infant dermal exposure to residual agricultural chemicals and formaldehyde-based finishes common in conventional textile processing. Cotton dominates material volume due to established supply chains and consumer familiarity, while bamboo claims the fastest expansion trajectory driven by softness marketing and perceived antimicrobial properties. Online stores capture margin-rich direct sales, though boutique channels retain outsized influence on brand discovery and premium pricing power.
REACH in Europe, the USDA National Organic Program in the United States, and GOTS global standards collectively define permissible inputs, labeling claims, and market access prerequisites across major consumption zones. These frameworks elevate compliance costs for new entrants while rewarding incumbent certifiers with defensible positioning. Stakeholders must monitor evolving chemical restriction lists and traceability mandates to anticipate which fiber categories and sales channels face the next compliance bottlenecks.
Market Dynamics
GOTS certification requirements are compressing the supplier base by filtering out manufacturers unable to meet organic fiber and social compliance thresholds simultaneously. This structural force is redrawing competitive boundaries around certification access rather than production scale alone.
Growth Catalysts
- EU Green Deal textile sustainability mandates:Binding circularity requirements and extended producer responsibility frameworks are accelerating retailer demand for certified organic inventory across Germany, France, and the United Kingdom.
- Millennial and Gen Z parental cohorts:These consumer segments prioritize dermal safety and chemical transparency, driving direct-to-channel adoption and premium willingness-to-pay for verified organic garments.
- Bamboo fiber processing advances:Improved mechanical rather than chemical extraction methods are expanding supply availability while preserving the softness and antimicrobial marketing claims that differentiate this fastest-expanding material category.
Market Restraints
- Organic cotton input cost volatility:Weather-dependent yields and competing food-crop land use in India and Turkey create price instability that compresses margin structures for finished garment producers.
- GOTS certification timeline friction:The eighteen-to-twenty-four-month full certification cycle for new manufacturing facilities creates supply bottlenecks that limit rapid capacity scaling in response to demand surges.
- Conventional cotton price arbitrage:Persistently lower prices for non-organic alternatives in mass retail channels constrain price elasticity and volume expansion for certified organic positioning.
Strategic Opportunities
- Subscription-based replenishment models:Direct-to-consumer platforms are capturing recurring revenue through size-progression programs that align with infant growth cycles and reduce customer acquisition costs.
- Blockchain-enabled fiber traceability:Integration of distributed ledger verification with GOTS documentation is creating differentiation for brands targeting transparency-motivated purchasers in premium channels.
- Secondhand and resale platform expansion:Dedicated organic baby clothing resale marketplaces are extending garment utility cycles and capturing value from durability positioning that conventional fast fashion cannot replicate.
Industry Challenges
- Certification audit capacity constraints:Accredited GOTS inspector scarcity is extending lead times for facility approval and creating compliance backlogs for suppliers in high-growth manufacturing zones.
- Dye and finish chemical reformulation:Eliminating heavy metal and formaldehyde-based inputs while maintaining colorfastness and hand-feel standards requires sustained R&D investment that smaller suppliers cannot absorb.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organic Baby Clothes Market |
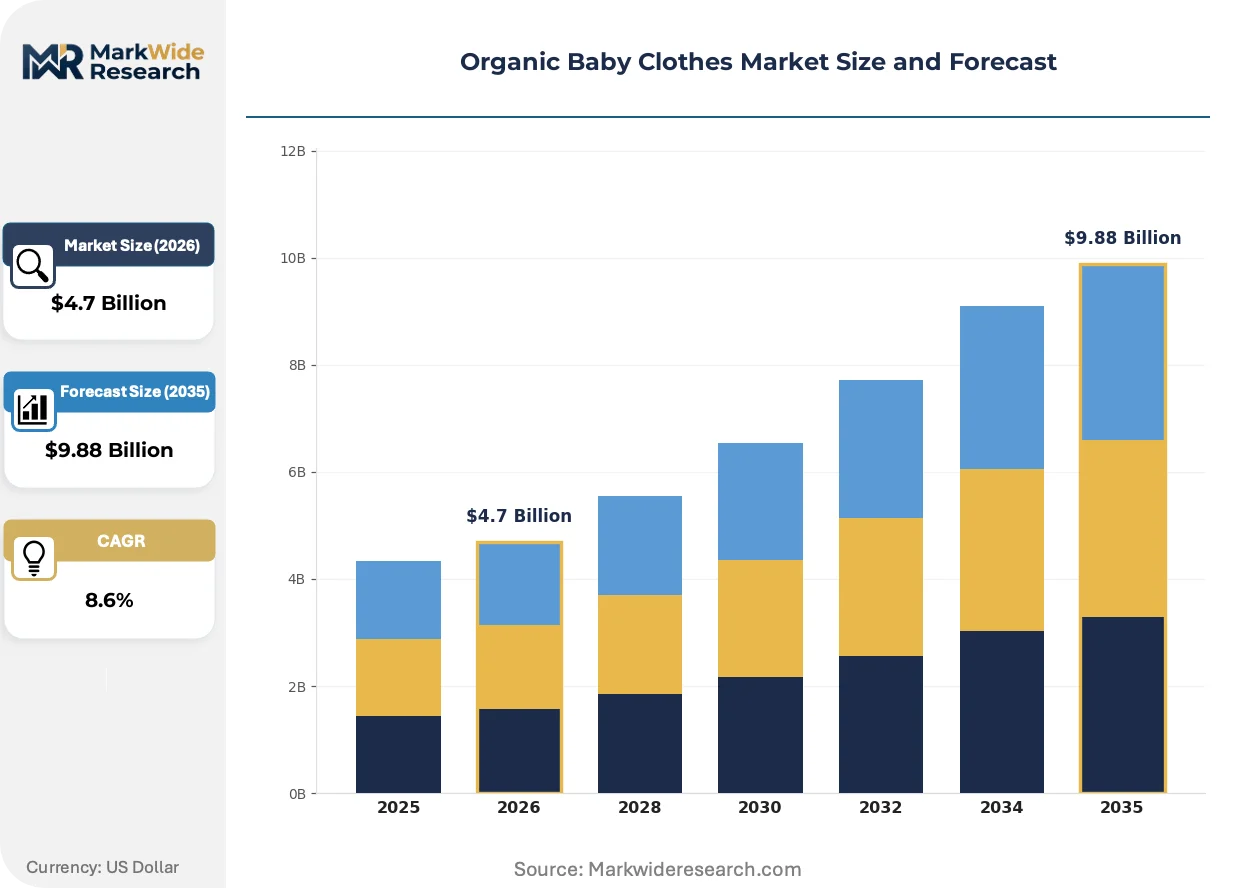
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $9.88 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Onesies, T-Shirts, Dresses, Sleepwear Material: Cotton, Bamboo, Hemp, Linen Age Group: Newborn, Infant, Toddler, Pre-School Sales Channel: Online Store, Retail, Wholesale, Boutique |
| Companies Covered | Quince, Monica + Andy, Hanna Andersson, Royal Apparel, Colored Organics, Burt’s Bees Baby, Organic Zoo, Alanic Global, Pehr, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organic Baby Clothes Market Strategic Shifts
Digital traceability infrastructure and fiber technology advances are reshaping how organic claims are verified and communicated. These developments are compressing information asymmetries between producers and purchasers while creating new competitive dimensions beyond certification possession alone.
Mechanical bamboo fiber extraction is bifurcating the material supply base by separating processors with closed-loop chemical recovery systems from those dependent on conventional viscose methods. Premium-positioned brands in German and French markets are sourcing exclusively from mechanical processors, while mass-channel suppliers face margin pressure from environmental compliance costs. This technology is compressing the addressable supplier pool for cost-competitive organic positioning.
REACH chemical restriction expansions are tightening permissible substance thresholds for textile finishes and dyes sold within European Union member states. The European Chemicals Agency's updated candidate list is forcing reformulation of softeners and flame retardants previously standard in infant garment production. Suppliers serving the EU Green Deal corridor are accelerating partnerships with dyehouses holding OEKO-TEX Standard 100 and GOTS dual certification.
Direct-to-consumer transparency platforms are displacing traditional boutique discovery channels as the primary brand entry point for first-time organic purchasers. Millennial parents in the United Kingdom and United States are researching fiber provenance through mobile-optimized supply chain visualizations before physical touchpoint engagement. This behavioral shift is concentrating marketing investment toward content production and influencer verification rather than wholesale relationship maintenance.
Organic Baby Clothes Market Segmentation
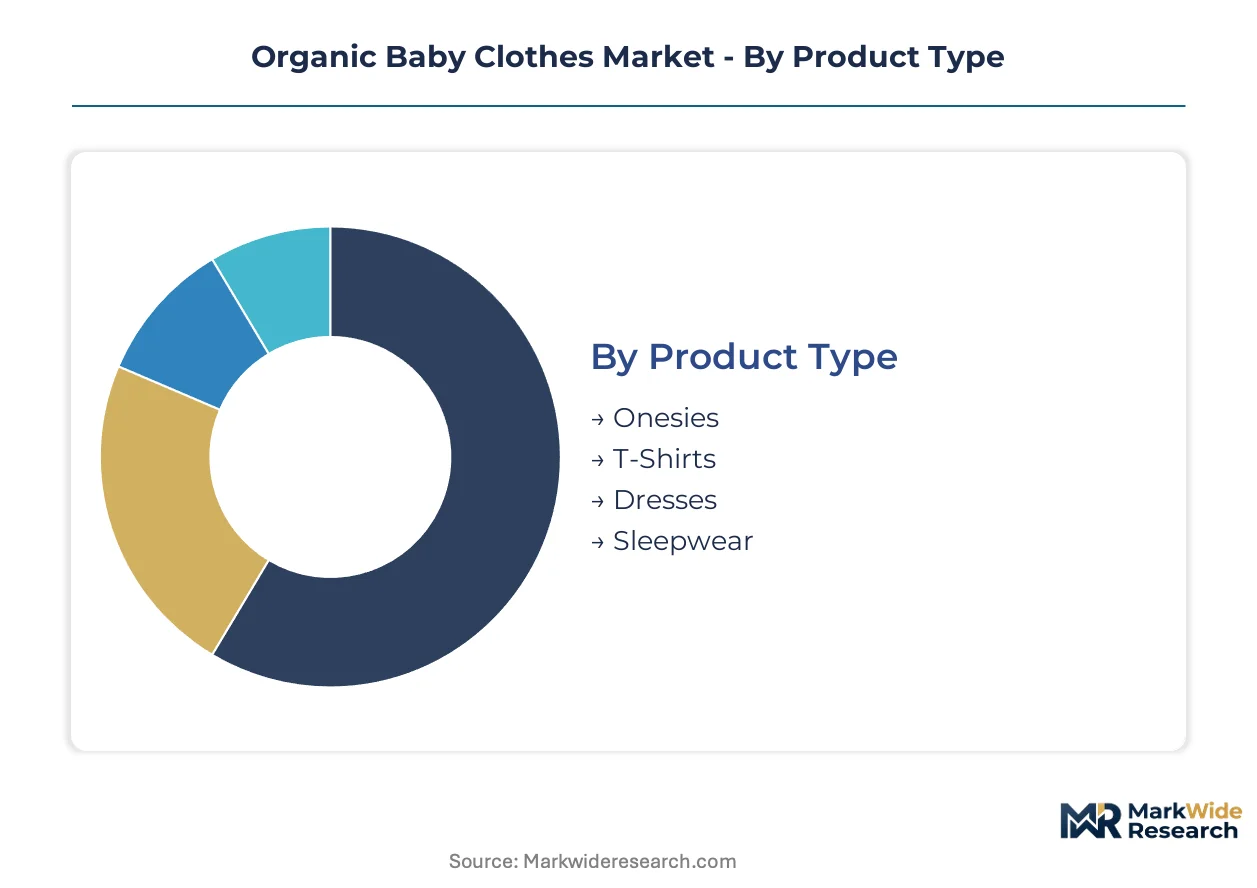
Organic baby clothes segmentation reveals how certification requirements, material provenance, and channel economics fragment purchasing behavior across parental cohorts. Each dimension carries distinct margin structures and compliance burdens that reshape supplier priorities.
Product Type:
Onesies and sleepwear dominate domestic manufacturing footprints in Turkey and Portugal, while dresses and T-shirts flow through export-led supply chains from India and China.
- Onesies:These envelope-neck bodysuits require GOTS-certified snaps and dye processes that meet REACH chemical thresholds. Demand concentrates in German and French direct-to-consumer channels where millennial parents prioritize dermal safety for base-layer garments worn against newborn skin.
- Sleepwear:Flame-retardant-free construction using organic wool or cotton interlock meets stricter EU safety standards than US CPSC requirements. UK boutiques and Scandinavian retailers drive premium positioning for GOTS-verified nightwear with temperature-regulating properties.
- T-Shirts:Short-sleeve tops represent volume-driven basics with lower certification premiums.
- Dresses:Higher-margin occasion wear with decorative stitching and natural dyes commands boutique placement.
Onesies hold the largest share; momentum sits with sleepwear as EU chemical restrictions tighten.
Material:
Cost tiers separate commodity organic cotton from premium-positioned bamboo and hemp fibers with specialized processing requirements.
- Cotton:GOTS-certified upland and pima varieties constitute the volume foundation, with established supply chains through India, Turkey, and the United States. Price volatility in agricultural inputs compresses margins for finished garment producers serving mass retail channels.
- Bamboo:Mechanical extraction methods in closed-loop systems differentiate premium European supply from conventional viscose processors. French and German brands source exclusively from certified mechanical processors, creating supply scarcity that supports price premiums.
- Hemp:Lower water requirements and natural pest resistance appeal to sustainability-positioned brands in UK and Netherlands markets.
- Linen:Breathable summer-weight garments target Mediterranean climate zones with limited seasonal demand windows.
Cotton commands volume leadership; bamboo gains share fastest through softness marketing and antimicrobial claims.
Age Group:
Customer lifetime value patterns concentrate investment in newborn and infant segments where first-brand attachment drives repeat purchasing.
- Newborn:Size 0-3 month garments require the strictest chemical residue thresholds given immature skin barrier function. US and UK hospitals distribute organic layette sets as premium gifts, creating brand entry points before independent purchasing begins.
- Infant:Three-to-twelve month sizing experiences the highest velocity of outgrowth, supporting subscription-based replenishment models in direct-to-consumer channels.
- Toddler:Active-wear durability requirements shift material blends toward hemp-cotton combinations.
- Pre-School:Larger sizing reduces per-unit premium tolerance as children approach conventional clothing transition.
Newborn captures margin concentration; infant segments show steepest expansion trajectory through size-progression subscriptions.
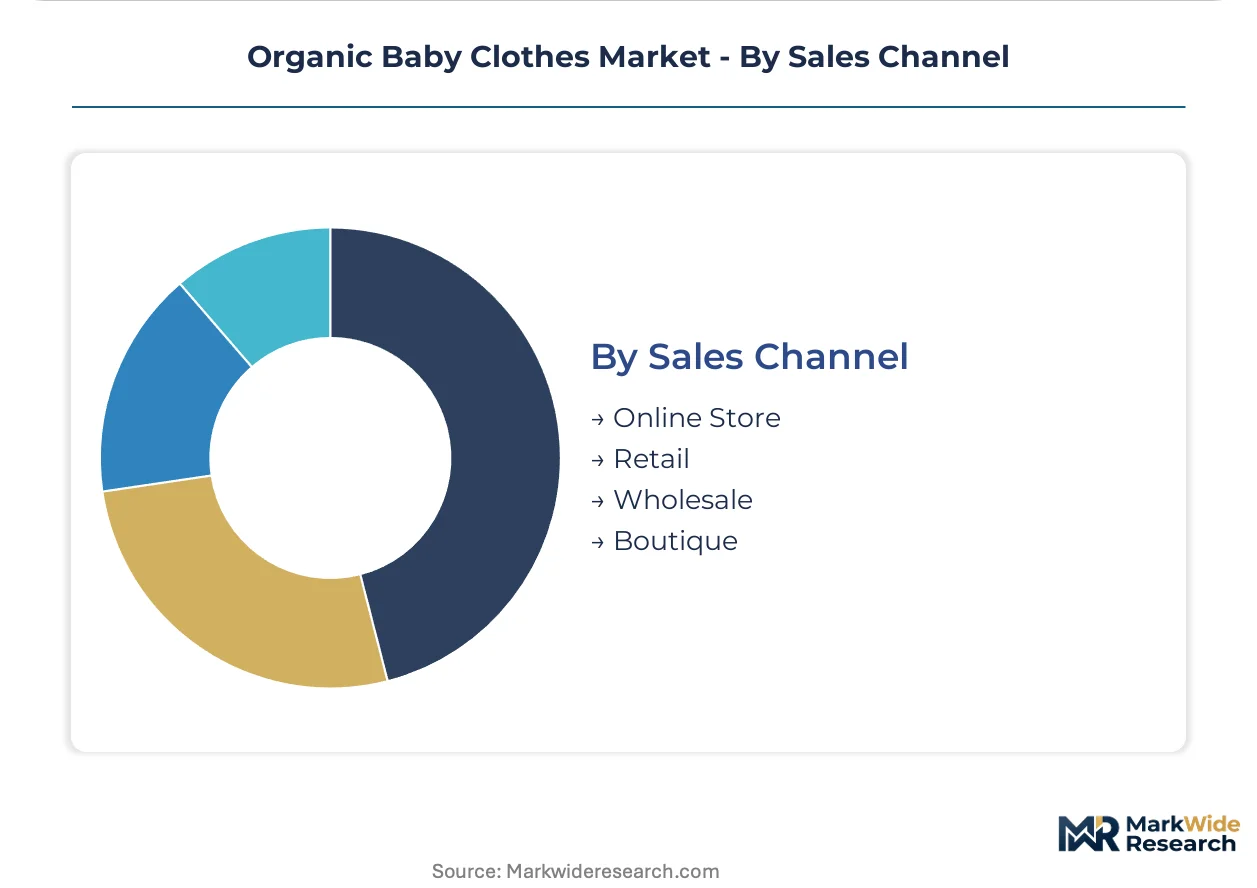
Sales Channel:
Margin structures bifurcate between high-touch boutique discovery and scalable online direct sales with divergent customer acquisition economics.
- Online Store:Brand-owned platforms capture full retail margin while enabling supply chain transparency content that converts millennial and Gen Z researchers. Mobile-optimized fiber provenance visualizations now precede physical touchpoint engagement for UK and US first-time purchasers.
- Boutique:Curated brick-and-mortar placement in Germany, France, and UK urban centers sustains premium pricing power through tactile quality verification and staff certification expertise.
- Retail:Mass-market shelf placement requires price compression that challenges organic certification cost absorption.
- Wholesale:B2B volume relationships with department stores and multi-brand retailers demand extended payment terms.
Online stores lead volume growth; boutiques defend margin premiums through discovery-phase influence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal textile sustainability mandates and REACH chemical restrictions are redrawing procurement geography across major consumption zones. National regulations now determine market access more than production cost alone.
Germany
Millennial parents in Berlin and Munich drive premium demand for GOTS-certified newborn garments. The country's Federal Institute for Risk Assessment enforces strict chemical residue thresholds under REACH implementation. Bavaria's textile clusters around Augsburg host specialized dyehouses holding dual OEKO-TEX and GOTS certification.
France
Parisian boutiques anchor brand discovery for first-time organic purchasers seeking transparency. ANSM and DGCCRF coordinate enforcement of textile labeling laws that exceed baseline EU requirements. The Lyon metropolitan area concentrates mechanical bamboo fiber processing facilities serving premium European brands.
United Kingdom
Subscription-based replenishment models capture recurring revenue from London and Southeast England parents. The UK's Office for Product Safety and Standards oversees post-Brexit chemical restriction alignment with REACH. Manchester's historic textile district now hosts GOTS-certified garment finishing operations.
United States
Direct-to-consumer platforms convert Pacific Northwest and Northeast parents through mobile supply chain visualizations. The USDA National Organic Program governs fiber origin claims while state-level California Proposition 65 drives additional chemical disclosure. Portland's manufacturing base sustains regional premium positioning through proximity sourcing.
India
Organic cotton cultivation in Gujarat and Maharashtra supplies fiber to export-oriented garment producers. The country's Textile Ministry operates certification facilitation schemes under its National Technical Textiles Mission. Tiruppur's knitwear cluster hosts GOTS-accredited facilities serving European and North American brand contracts.
Organic Baby Clothes Market Competitive Environment
Player mix skews toward direct-to-consumer specialists and heritage-certified manufacturers with regional manufacturing footprints. Market structure concentrates around certification possession rather than scale alone. Two strategic archetypes dominate: Pacific Northwest-based vertically integrated producers and digitally native subscription platforms. Competitive moves center on GOTS certification timeline acceleration and mechanical bamboo fiber supply locking.
Among heritage-certified manufacturers, Hanna Andersson anchors the Pacific Northwest production archetype through its Oregon-based manufacturing presence. Monica + Andy occupies the direct-to-consumer transparency tier with its Chicago-originated digital platform. Burt's Bees Baby represents mass-retail distribution scale through its accessible price-point positioning. These three exemplify how certification access, channel strategy, and geographic manufacturing concentration separate viable competitors from filtered-out suppliers.
| Leading Market Players |
|---|
| Quince |
| Monica + Andy |
| Hanna Andersson |
| Royal Apparel |
| Colored Organics |
| Burt's Bees Baby |
| Organic Zoo |
| Alanic Global |
| Pehr |
| Others |
Value Chain & Pricing Dynamics
Mechanical bamboo fiber extraction replacing conventional viscose methods redraws procurement geography toward Lyon-area processors while compressing price premiums for brands unable to secure closed-loop supply. This substitution dynamic simultaneously elevates GOTS-certified mechanical output pricing and depresses margin structures for mass-channel competitors locked into chemical-intensive alternatives.
Pricing Analysis
Certification level creates the primary spread between premium GOTS-verified garments and uncertified organic-labeled alternatives. Pricing stratifies across premium boutique tiers, standard direct-to-consumer levels, and economy mass-retail positioning. Cost compression in the economy tier intensifies because conventional cotton price arbitrage constrains certified organic price elasticity. Mass-retail parents exhibit highest price sensitivity while boutique-discovering millennial purchasers in Germany and France demonstrate lowest.
Supply Chain Analysis
Eighteen-to-twenty-four-month GOTS certification timelines strain inventory planning for brands scaling capacity. Raw cotton supply concentrates in India, Turkey, and the United States with mechanical bamboo processing clustering in France and Portugal. The supply chain draws from organic fiber cultivation and draws from specialized dyehouses holding dual OEKO-TEX and GOTS accreditation. Single-source vulnerability sits with accredited inspector scarcity extending facility approval backlogs. Distribution runs through direct-to-consumer platforms and boutique channels with divergent margin capture.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from digitally native subscription platforms capturing recurring revenue through size-progression models that conventional wholesale-dependent brands cannot replicate.
For Market Incumbents: Shield market position by accelerating mechanical bamboo fiber supply locking before Lyon-area processor capacity saturates. Deepen backward integration into GOTS-certified finishing operations in Portugal and Turkey to compress certification timeline friction. Certification investment represents the priority defensive lever against digitally native entrants.
For New Entrants and Emerging Players: Anchor in subscription-based replenishment models targeting UK and US infant segments where size-progression velocity supports recurring revenue capture. The most penetrable white space sits with blockchain-enabled fiber traceability platforms serving transparency-motivated millennial parents. A direct-to-consumer launch with mobile-optimized supply chain visualization converts researchers before physical touchpoint engagement.
For Investors and Strategic Acquirers: The market sits at a certification-filtering phase that favors vertically integrated manufacturers with captive GOTS-accredited facilities. Long-term viability over the coming decade hinges on regulatory alignment with EU Green Deal textile mandates and REACH chemical restriction expansions. Acquisition targets should demonstrate dual OEKO-TEX and GOTS certification with established European boutique relationships. The signal to monitor is ECHA candidate list updates forcing dye and finish reformulation that smaller suppliers cannot absorb.
| Strategic Initiative | Industry Significance |
|---|---|
| GOTS Certification Acceleration | Dual OEKO-TEX and GOTS accreditation secures EU Green Deal corridor access before competitor facility approval. |
| Mechanical Bamboo Supply Locking | Exclusive partnerships with Lyon-area closed-loop processors defend premium positioning against viscose-dependent rivals. |
| Subscription Platform Launch | Size-progression replenishment models align with infant outgrowth cycles and reduce customer acquisition costs. |
| Blockchain Traceability Integration | Distributed ledger verification with GOTS documentation targets transparency-motivated millennial and Gen Z parents. |
| Resale Marketplace Partnership | Secondhand platform expansion extends garment utility cycles and captures value from durability positioning. |
Study Parameters
Desk research of customs trade records, GOTS certification registries, and EU regulatory filings preceded structured interviews with brand supply chain directors, boutique category buyers, GOTS-accredited facility managers, and dyehouse technical directors. Primary fieldwork with subscription platform operators and resale marketplace founders combined with secondary validation against REACH restriction updates and USDA National Organic Program documentation. Bottom-up segment sizing triangulated against top-down market value reconstruction.
Variance decomposition across product type, material provenance, age group, and sales channel dimensions shaped analytical framework construction across the projection horizon. CAGRs derived from segment-level growth rate aggregation with organic cotton input cost volatility and GOTS certification timeline friction as industry-specific forecast inputs. Modeled outputs reflect demand elasticity assumptions for millennial parental cohorts and EU regulatory enforcement intensity.
Decision-makers should treat outputs as directional under sustained EU Green Deal implementation and stable organic cotton yield assumptions; material deviation in REACH chemical restriction timelines or inspector accreditation capacity would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel Textiles
Women's Jerseys, Sweatshirts and Pullovers Market
Apparel Textiles
Asia-Pacific Textile Garment Market
Apparel Textiles
Embroidery Market
Apparel Textiles
Hunting Apparel Market
Apparel Textiles
Asia-Pacific Footwear Sole Material Market
Apparel Textiles
Global Western Wear Market
Apparel Textiles
Europe Textile Garment Market
Apparel Textiles
North America Insect Repellent Apparel Market
Apparel Textiles
Apparel Supply Chain Market
Apparel Textiles
Clothing Manufacturing Service Market
Apparel Textiles
Flame Retardant Apparel Market
Apparel Textiles
Denim Market
Apparel Textiles
Global Socks Market
Apparel Textiles
Maternity Leggings Market
Apparel Textiles
Stockings Market
Apparel Textiles
Sweat Resistant Apparel Market