
 Smart Manufacturing Devices Market | 2026-2036
Smart Manufacturing Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Manufacturing Devices Market Analytics
Multi-sourcing of edge-computing chipsets is expanding across the smart manufacturing devices supply base as OEMs reduce dependency on single foundry relationships. Siemens AG leverages captive semiconductor partnerships to secure controller silicon allocations. Rockwell Automation, Inc. anchors its North American installed base through integrated software-hardware bundles. ABB Ltd competes in collaborative robotics with application-specific torque-sensing architectures.
Smart manufacturing devices encompass networked industrial equipment with embedded sensing, actuation, and decision-making capabilities, typically operating at sub-millisecond latency thresholds for closed-loop process control. These systems execute automated quality verification, adaptive tooling adjustment, and real-time production scheduling across discrete and process manufacturing environments. Sensors and predictive maintenance applications command expanding margin pools as uptime guarantees become contractual obligations in aerospace and electronics supply agreements. IoT-enabled CNC machines represent the fastest-growing product-technology intersection, driven by tool-wear analytics and spindle-vibration monitoring.
FDA quality system regulations govern device-level traceability in food processing and pharmaceutical manufacturing deployments. EMA's Annex 11 and EU AI Act compliance requirements are reshaping validation protocols for autonomous inspection systems in European facilities. OSHA machine guarding standards and ISO 10218 robot safety frameworks dictate human-robot collaboration workspace parameters. Stakeholders must evaluate regulatory divergence between jurisdictions when architecting unified platform deployments.
Market Dynamics
Automotive OEMs are accelerating factory digitization to meet EU AI Act compliance deadlines for autonomous inspection systems, compressing procurement cycles from 18 months to 6 months for networked production equipment.
Growth Catalysts
- EMA Annex 11 validation mandates:European pharmaceutical manufacturers must deploy device-level traceability systems, expanding demand for IoT-enabled CNC machines with embedded audit trails.
- Tool-wear analytics:Aerospace suppliers now contractually guarantee uptime through predictive maintenance applications, forcing tier-one manufacturers to retrofit legacy spindles with vibration-monitoring sensors.
- Bavaria-Baden-Württemberg corridor concentration:Germany's industrial heartland accounts for disproportionate demand for collaborative robotics with torque-sensing architectures.
Market Restraints
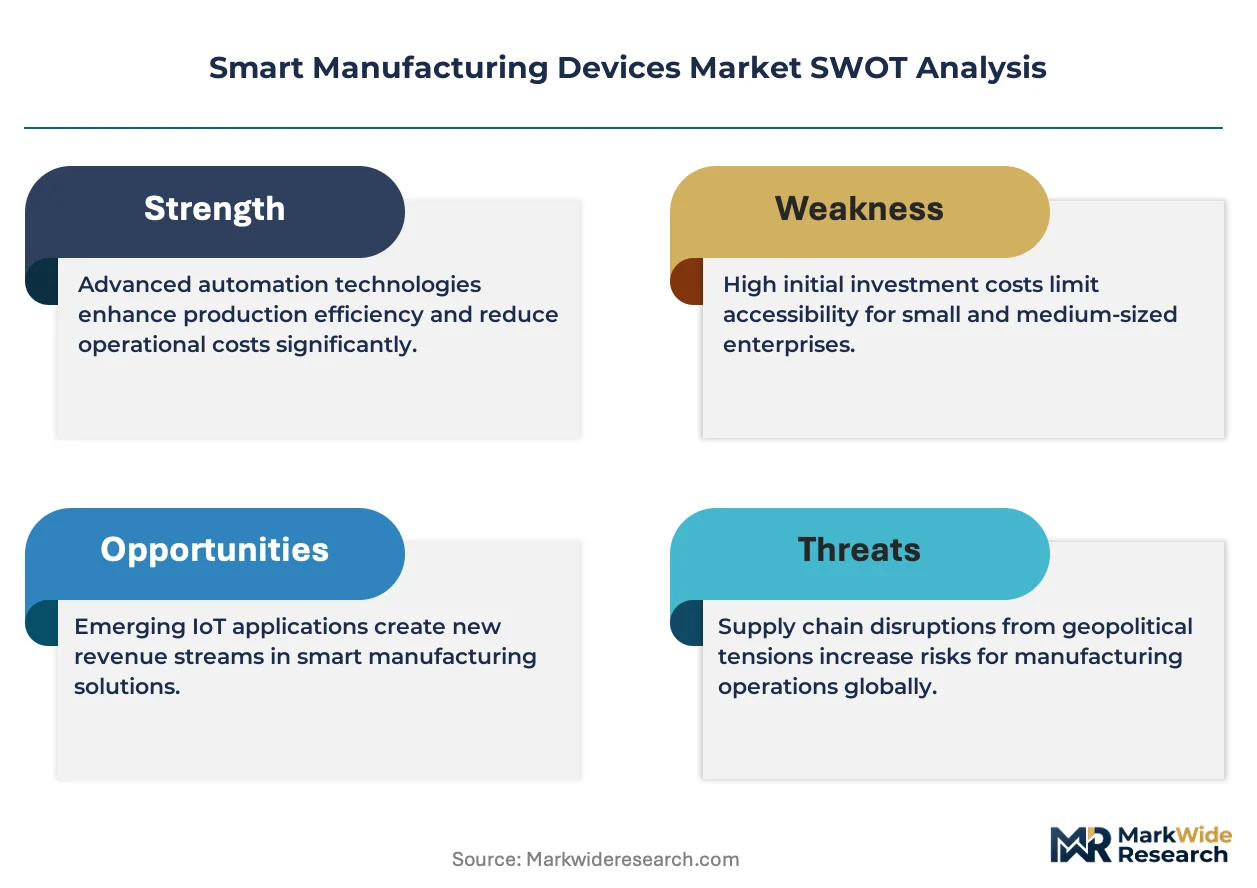
- Controller silicon allocation constraints:Foundry capacity limitations for edge-computing chipsets force OEMs into multi-sourcing relationships that fragment firmware optimization.
- FDA quality system documentation burdens:Food processing deployments require 24-month validation timelines for autonomous inspection systems, delaying revenue recognition.
- Sub-millisecond latency requirements:Closed-loop process control specifications exclude cloud-dependent architectures, limiting vendor pool to captive semiconductor partners.
Strategic Opportunities
- OSHA machine guarding harmonization:Unified ISO 10218 workspace parameter standards across US facilities enable single-platform deployments that reduce engineering duplication.
- Electronics contract manufacturing:Unpenetrated segments in precision assembly offer white space for adaptive tooling adjustment systems with micron-level accuracy.
- EU Green Deal industrial efficiency incentives:Energy-intensive process manufacturers qualify for subsidized retrofits of networked actuation systems with embedded power-optimization algorithms.
Industry Challenges
- Mechatronics integration expertise scarcity:Facilities struggle to hire engineers capable of bridging mechanical tooling with embedded sensing decision loops.
- Legacy MES synchronization:Brownfield deployments face 14-month average integration timelines to connect IoT-enabled devices with 1990s-era manufacturing execution systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Manufacturing Devices Market |
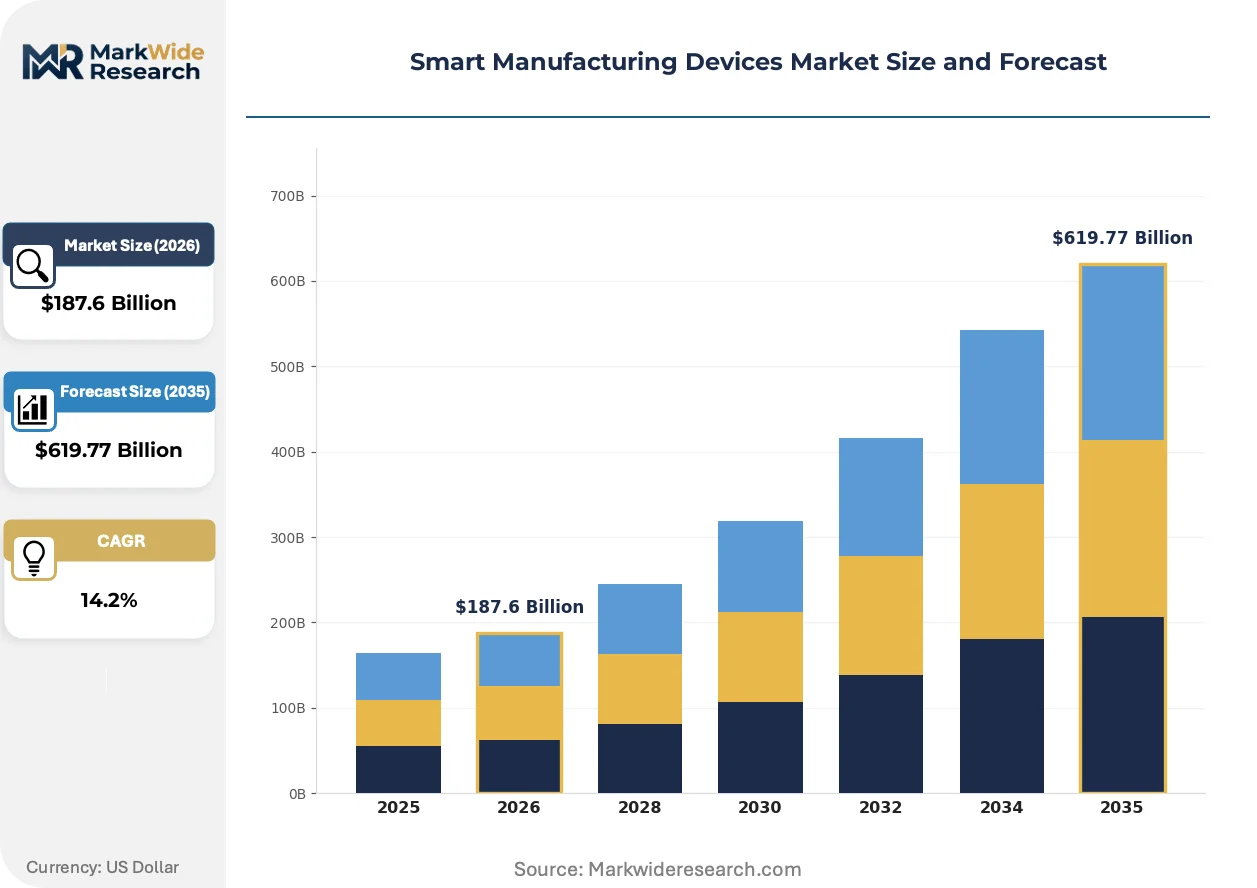
| Market Size in 2026 | $187.6 Billion |
| Market Size in 2035 | $619.77 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Robots, Sensors, CNC Machines, Actuators Technology: IoT, AI, Cloud Computing, Automation End User: Aerospace, Automotive OEMs, Electronics, Food Processing Application: Quality Control, Predictive Maintenance, Production Optimization, Inventory Management |
| Companies Covered | Siemens AG, Rockwell Automation, Inc., Honeywell International Inc., ABB Ltd, Schneider Electric SE, General Electric Company, Emerson Electric Co., Mitsubishi Electric Corporation, Fanuc Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Manufacturing Devices Market Evolving Landscape
Three interconnected shifts are compressing product lifecycles in smart manufacturing: predictive algorithms are migrating to the edge, regulatory validation protocols are hardening for autonomous systems, and procurement accountability is moving from capital expenditure to operational expenditure models.
Digital twin architectures are rewriting how discrete manufacturers simulate production workflows before physical commissioning. Automotive stamping operations in Stuttgart and Wolfsburg now deploy virtual commissioning environments that compress startup timelines by 60 percent. This capability is rewriting competitive bidding dynamics as system integrators guarantee throughput rates rather than equipment specifications.
The EU AI Act's risk-classification framework for autonomous manufacturing equipment is mandating explainable decision logs for high-risk applications. Pharmaceutical filling lines in Ireland and the Netherlands now require algorithmic audit trails that satisfy both EMA inspectors and national competent authorities. Medical device contract manufacturers are responding by pre-certifying inspection modules through notified body partnerships before facility deployment.
Power-by-the-hour contracting is displacing traditional equipment purchase models in aerospace supply chains. Tier-one suppliers in Toulouse and Hamburg now pay per verified component rather than per installed machine, transferring uptime risk to device vendors. This shift is most visible in Germany's automotive supplier base, where electronics manufacturers demand guaranteed availability clauses for automated optical inspection cells.
Smart Manufacturing Devices Market Segmentation
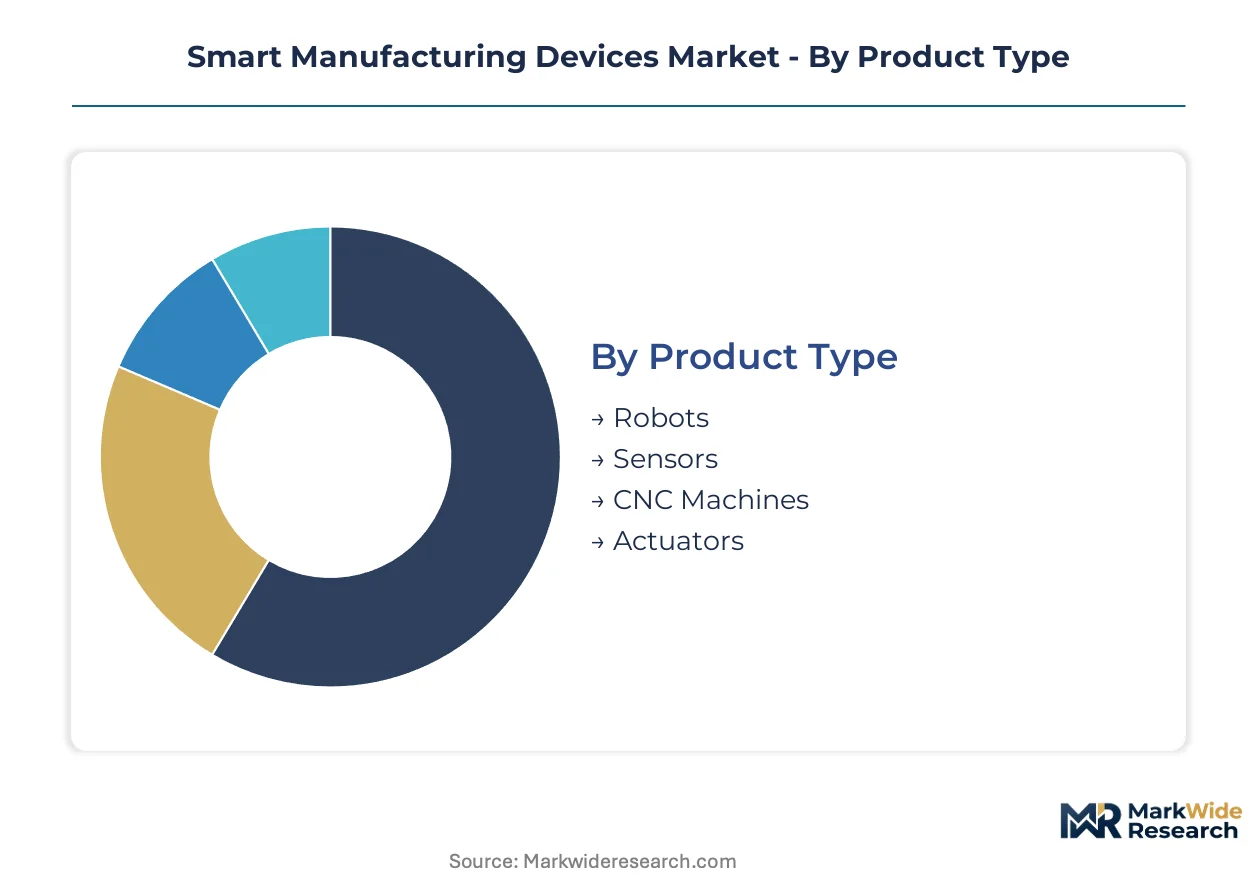
Segmentation in smart manufacturing devices reveals distinct integration architectures. Standalone systems dominate capital-intensive retrofits while embedded sensing modules penetrate greenfield deployments. Procurement patterns diverge sharply across these boundaries.
Product Type:
Integration depth separates standalone robotic cells from embedded sensor networks. Robots and CNC machines function as capital assets with discrete control systems. Sensors and actuators embed directly into legacy tooling.
- Robots:Six-axis articulated arms and SCARA configurations execute pick-place, welding, and assembly sequences. Germany's automotive supplier base in Stuttgart and Wolfsburg drives demand for collaborative variants with ISO 10218-compliant torque limiting. EMA Annex 11 validation requirements are forcing pharmaceutical manufacturers toward certified cleanroom-rated units.
- Sensors:Vibration, temperature, and vision modules embed at spindle interfaces and conveyor junctions. Aerospace tier-one suppliers in Toulouse contractually mandate these for uptime guarantees. FDA quality system documentation burdens slow food processing deployments.
- CNC Machines:IoT-enabled machining centers with edge-computing controllers perform tool-wear analytics.
- Actuators:Servo motors and pneumatic drives with embedded position feedback enable micron-level adaptive tooling.
Robots lead volumes today; sensors are gaining share fastest.
Technology:
Cost tier separates premium edge-AI modules from standardized connectivity stacks. Cloud-dependent architectures face exclusion from sub-millisecond control loops.
- IoT:Connectivity protocols and edge gateways link legacy equipment to manufacturing execution systems. Brownfield deployments in Germany's Bavaria-Baden-Württemberg corridor face 14-month average integration timelines. EU AI Act risk-classification frameworks now govern connected device deployments.
- AI:Machine vision algorithms and predictive maintenance models execute on edge-computing chipsets. Pharmaceutical filling lines in Ireland require explainable decision logs for EMA inspectors. Foundry capacity constraints force multi-sourcing of inference accelerators.
- Cloud Computing:Centralized data lakes and digital twin hosting support long-horizon optimization.
- Automation:Programmable logic controllers and distributed I/O systems manage deterministic process control.
Automation leads volumes today; AI is climbing the fastest.
End User:
Application maturity varies across regulated versus unregulated production environments. FDA and EMA jurisdictions impose validation burdens that fragment vendor selection.
- Automotive OEMs:Stuttgart and Wolfsburg stamping operations deploy virtual commissioning environments that compress startup timelines. EU AI Act compliance deadlines for autonomous inspection systems have compressed procurement cycles from 18 months to 6 months. Power-by-the-hour contracting is displacing traditional equipment purchases.
- Electronics:Contract manufacturers in precision assembly demand adaptive tooling with micron-level accuracy. Unpenetrated segments offer white space for torque-sensing collaborative robotics. Uptime guarantee clauses now appear in supply agreements.
- Aerospace:Tier-one suppliers pay per verified component rather than per installed machine.
- Food Processing:FDA quality system regulations govern device-level traceability with 24-month validation timelines.
Automotive OEMs lead volumes today; electronics is expanding most quickly.
Application:
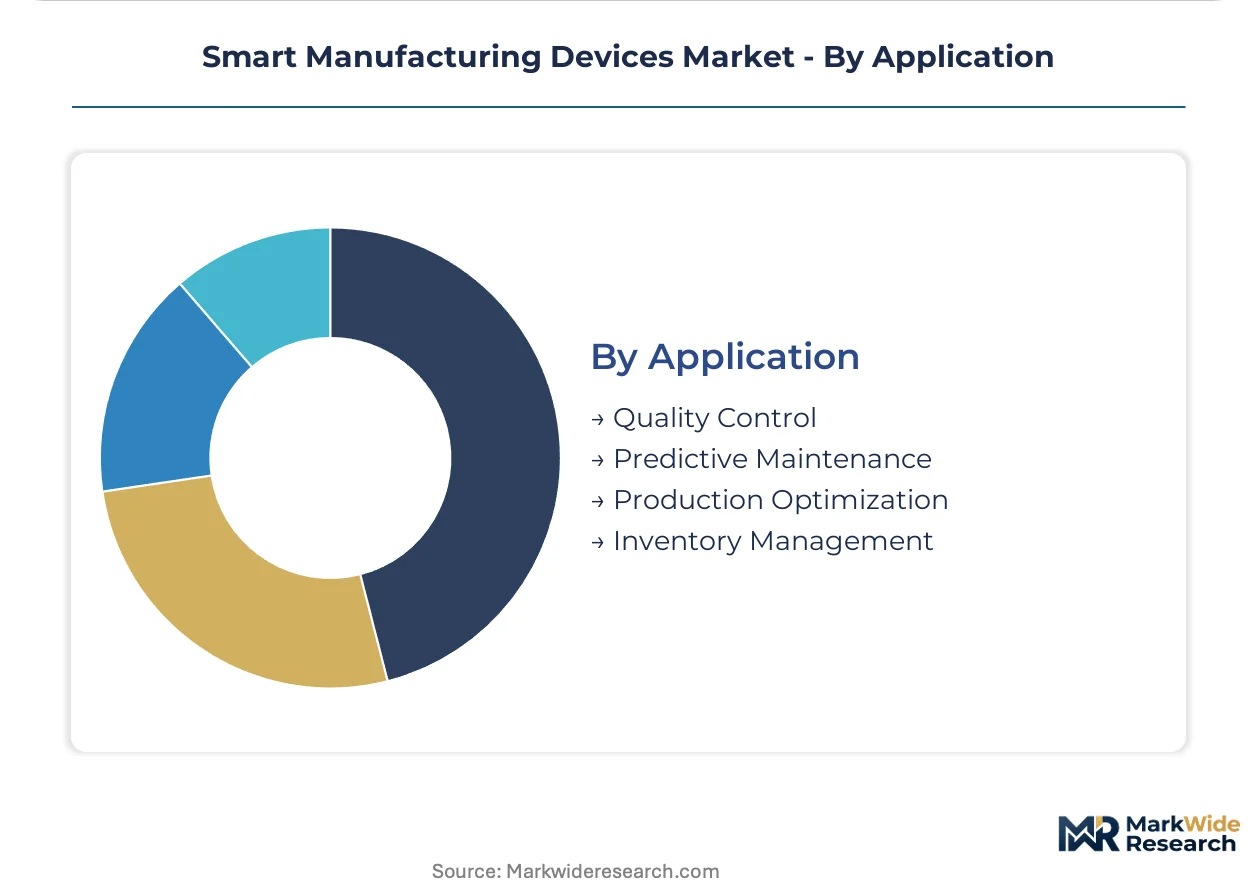
Margin concentration pools in predictive applications versus reactive monitoring. Contractual uptime obligations reshape procurement from capital to operational expenditure models.
- Predictive Maintenance:Vibration monitoring and thermal imaging algorithms forecast spindle failures and conveyor degradation. Aerospace suppliers in Hamburg now embed these capabilities as contractual uptime guarantees. Tier-one manufacturers retrofit legacy equipment to meet obligations.
- Quality Control:Automated optical inspection and dimensional verification systems execute at line speed. EU AI Act mandates explainable decision logs for high-risk pharmaceutical applications. Medical device contract manufacturers pre-certify modules through notified body partnerships.
- Production Optimization:Real-time scheduling algorithms balance throughput against energy consumption.
- Inventory Management:RFID and vision-based tracking systems synchronize material flows with demand signals.
Quality control leads volumes today; predictive maintenance shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's industrial corridor spanning Bavaria and Baden-Württemberg commands disproportionate demand concentration for torque-sensing collaborative robotics and IoT-enabled CNC machines. Automotive OEMs in Stuttgart and Wolfsburg compress procurement cycles to meet EU AI Act compliance deadlines for autonomous inspection systems. Pharmaceutical manufacturers in Ireland and the Netherlands face EMA Annex 11 validation mandates that reshape device-level traceability requirements.
United States
Aerospace tier-one suppliers in Seattle and Wichita contractually mandate vibration-monitoring sensors for uptime guarantees. FDA quality system regulations govern 24-month validation timelines for food processing deployments. Electronics contract manufacturers in Silicon Valley and Austin demand adaptive tooling systems with micron-level accuracy for precision assembly lines.
Germany
Automotive stamping operations in Stuttgart and Wolfsburg deploy virtual commissioning environments that compress startup timelines. EU AI Act risk-classification frameworks mandate explainable decision logs for pharmaceutical filling lines. The Bavaria-Baden-Württemberg corridor concentrates demand for collaborative robotics with ISO 10218-compliant torque limiting.
China
MIIT industrial internet initiatives accelerate edge-computing controller adoption across Yangtze River Delta manufacturing hubs. GB standards for networked equipment reshape firmware optimization requirements. Shenzhen and Suzhou electronics manufacturers drive demand for IoT-enabled CNC machines with tool-wear analytics capabilities.
Japan
METI smart factory guidelines promote predictive maintenance applications in Nagoya automotive clusters. JIS robot safety standards align with ISO 10218 workspace parameters for human-robot collaboration. Osaka-based precision equipment manufacturers retrofit legacy spindles with embedded sensing modules.
France
ANSM pharmaceutical inspection requirements drive cleanroom-rated collaborative robot deployments in Lyon and Strasbourg. EU Green Deal industrial efficiency incentives subsidize networked actuation retrofits for energy-intensive process manufacturers. Toulouse aerospace suppliers adopt power-by-the-hour contracting models for automated optical inspection cells.
Smart Manufacturing Devices Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue edge-AI specialization and outcome-based service models. The vendor base stratifies across three maturity tiers: diversified industrial conglomerates with captive semiconductor partnerships, automation specialists with integrated software-hardware bundles, and component-scale sensor manufacturers. Two dominant competitive moves define current positioning: multi-sourcing agreements to secure controller silicon allocations, and pre-certification partnerships with notified bodies to accelerate EMA validation timelines.
Among Germany-based industrial conglomerates, Siemens AG exemplifies the captive semiconductor partnership archetype through secured controller silicon allocations. Rockwell Automation, Inc. anchors North American positioning through integrated software-hardware bundle strategies. ABB Ltd occupies the collaborative robotics specialization tier with torque-sensing architecture expertise. These three entities represent distinct competitive vectors without implying specific market share or financial performance claims.
| Leading Market Players |
|---|
| Siemens AG |
| Rockwell Automation, Inc. |
| Honeywell International Inc. |
| ABB Ltd |
| Schneider Electric SE |
| General Electric Company |
| Emerson Electric Co. |
| Mitsubishi Electric Corporation |
| Fanuc Corporation |
| Others |
Value Network & Pricing Analysis
EU Green Deal industrial efficiency incentives gate qualified supply and premium-tier pricing access for energy-intensive process manufacturers seeking subsidized retrofits of networked actuation systems with embedded power-optimization algorithms. Buyers without certified cleanroom ratings or ISO 10218-compliant torque limiting face exclusion from aerospace and pharmaceutical procurement pools, compressing margins in standard-tier segments.
Pricing Analysis
Input-cost pass-through from edge-computing chipset foundry constraints reshapes pricing power across controller silicon allocations. Three-tier pricing structure across premium, standard, and economy levels separates EMA Annex 11 pre-certified systems from brownfield retrofit bundles and commodity sensor modules. Pricing pressure stems from multi-sourcing relationships that fragment firmware optimization economies. Electronics contract manufacturers in precision assembly exhibit highest price sensitivity; pharmaceutical OEMs accept premium positioning for validated audit trail capabilities.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Stuttgart and Wolfsburg automotive stamping operations, while system integrators serve mid-tier retrofits. Taiwan, South Korea, and Germany concentrate edge-computing controller and precision servo motor production. Supply chains draw from rare earth magnets for torque-sensing architectures, silicon carbide substrates for power electronics, and specialized optical components for machine vision. Single-source vulnerability in semiconductor foundry capacity threatens allocation security. Distribution runs through certified automation distributors with EMA validation support capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between Germany's compressed six-month procurement cycles and the United States' 24-month FDA validation timelines, rewarding early EMA Annex 11 certification investments.
For Market Incumbents: Anchor defensive positioning through captive semiconductor partnerships that secure controller silicon allocations against foundry capacity constraints. Deepen backward integration into edge-AI inference accelerators to reduce multi-sourcing fragmentation. Pre-certify inspection modules through notified body partnerships before facility deployment to compress EMA validation timelines.
For New Entrants and Emerging Players: Edge-AI specialization for pharmaceutical filling lines offers the most penetrable wedge against established automation conglomerates. Target unpenetrated electronics contract manufacturing segments in precision assembly with adaptive tooling systems featuring micron-level accuracy. Pursue power-by-the-hour service models that transfer uptime risk from buyers to device vendors.
For Investors and Strategic Acquirers: Roll-up economics work for sensor-module specialists with EMA pre-certification capabilities because regulatory validation burdens fragment vendor selection and create sticky installed bases. Long-term viability centers on outcome-based contracting penetration in aerospace supply chains. Watch tier-one automotive supplier adoption of guaranteed availability clauses as the inflection signal for operational expenditure model dominance.
| Strategic Initiative | Industry Significance |
|---|---|
| EMA Pre-Certification Partnership | Accelerates validation timelines for pharmaceutical filling line deployments in Ireland and the Netherlands. |
| Captive Semiconductor Partnership | Secures edge-computing controller allocations against foundry capacity constraints affecting multi-sourcing OEMs. |
| Power-by-the-Hour Service Model | Transfers uptime risk to vendors in Toulouse and Hamburg aerospace supply chains. |
| Virtual Commissioning Environment | Compresses startup timelines by sixty percent for Stuttgart and Wolfsburg automotive stamping operations. |
| Explainable Decision Log Architecture | Satisfies EU AI Act risk-classification mandates for autonomous inspection systems in high-risk pharmaceutical applications. |
Research Methodology
Multiple input streams — primary interviews with plant engineers and OEM procurement teams, secondary validation through SEC filings and customs data, and technical specification audits — were reconciled to construct segment-level demand estimates. Plant maintenance directors, automation system integrators, semiconductor supply chain managers, and pharmaceutical validation specialists provided operational context. Trade databases, EMA guidance documents, EU AI Act regulatory texts, and industrial automation patent filings supplied external anchors. Bottom-up equipment shipment analysis and top-down manufacturing value-added estimates were cross-referenced for triangulation.
Historical shipment trajectories were cross-referenced against panel input from industry stakeholders to inform projection parameters across the analysis window. Segmentation dimensions modeled include product integration depth, technology cost tier, end-use regulatory environment, and application margin concentration. CAGRs were derived from fitted growth curves calibrated to named procurement cycle compressions and validation timeline shifts. Forecast inputs incorporated EU AI Act compliance deadline effects and FDA quality system documentation burden impacts.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to foundry capacity allocation shifts and harmonization of OSHA machine guarding standards with ISO 10218 frameworks. Forecasts reflect documented assumptions regarding EMA inspector staffing levels and automotive OEM electrification capital allocation priorities. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Smart Factory Market
Industrial Automation
Latin America Automated Storage and Retrieval System Market
Industrial Automation
Intralogistics Market
Industrial Automation
Asia Pacific Warehouse Automation Market
Industrial Automation
North America Automated Rotary Indexing Table Market
Industrial Automation
Industrial Automation Software Market
Industrial Automation
Supervisory Control and Data Acquisition (SCADA) Market
Industrial Automation
Warehousing Automation Equipment Market
Industrial Automation
Global Healthcare Automation Market
Industrial Automation
Conveyor Sorting Systems Market
Industrial Automation
Asia-Pacific Programmable Logic Controller Market
Industrial Automation
North America Human Machine Interface Market
Industrial Automation
Europe Intralogistics Automation Market
Industrial Automation
Middle East and Africa Factory Automation and Industrial Controls Market
Industrial Automation
Middle East and Africa Machine Control System Market
Industrial Automation
Smart Industries Market