
 Plywood Market | 2026-2036
Plywood Market Size, Share, and Industry Trends Forecast 2026-2036
Plywood Market Intelligence
The EU Timber Regulation is decoupling European plywood procurement from unverified tropical sources, forcing importers to document legal harvest chains. West Fraser leverages its vertically integrated fiber supply across British Columbia and the US South to sustain certified product flows. Georgia-Pacific anchors North American structural panel capacity with scale advantages in softwood veneer production. Metsä Wood differentiates through engineered plywood systems tailored to modular construction specifications.
Plywood consists of thin wood veneers bonded with adhesives under heat and pressure, typically arranged with adjacent grain directions perpendicular to each other to achieve dimensional stability and strength-to-weight ratios exceeding solid lumber. Its primary purpose spans structural sheathing, concrete formwork, furniture substrates, and marine applications where moisture resistance matters. Softwood plywood dominates construction-grade volume due to cost efficiency in sheathing and subflooring, while marine plywood commands premium positioning in boatbuilding and coastal infrastructure. Cross-laminated technology is gaining share in multi-story timber frames as architects specify taller wood buildings. Engineered wood processes are reshaping margin pools by converting lower-grade fiber into performance-graded panels.
EPA formaldehyde emission standards in the United States, the EU Timber Regulation, and Japan's JIS standards collectively govern product access and material sourcing across major demand centers. These frameworks elevate compliance costs for adhesive formulations and chain-of-custody documentation, filtering smaller traders from premium segments. Stakeholders must monitor evolving carbon accounting rules for biogenic materials as embodied carbon metrics reshape procurement criteria in public infrastructure tenders.
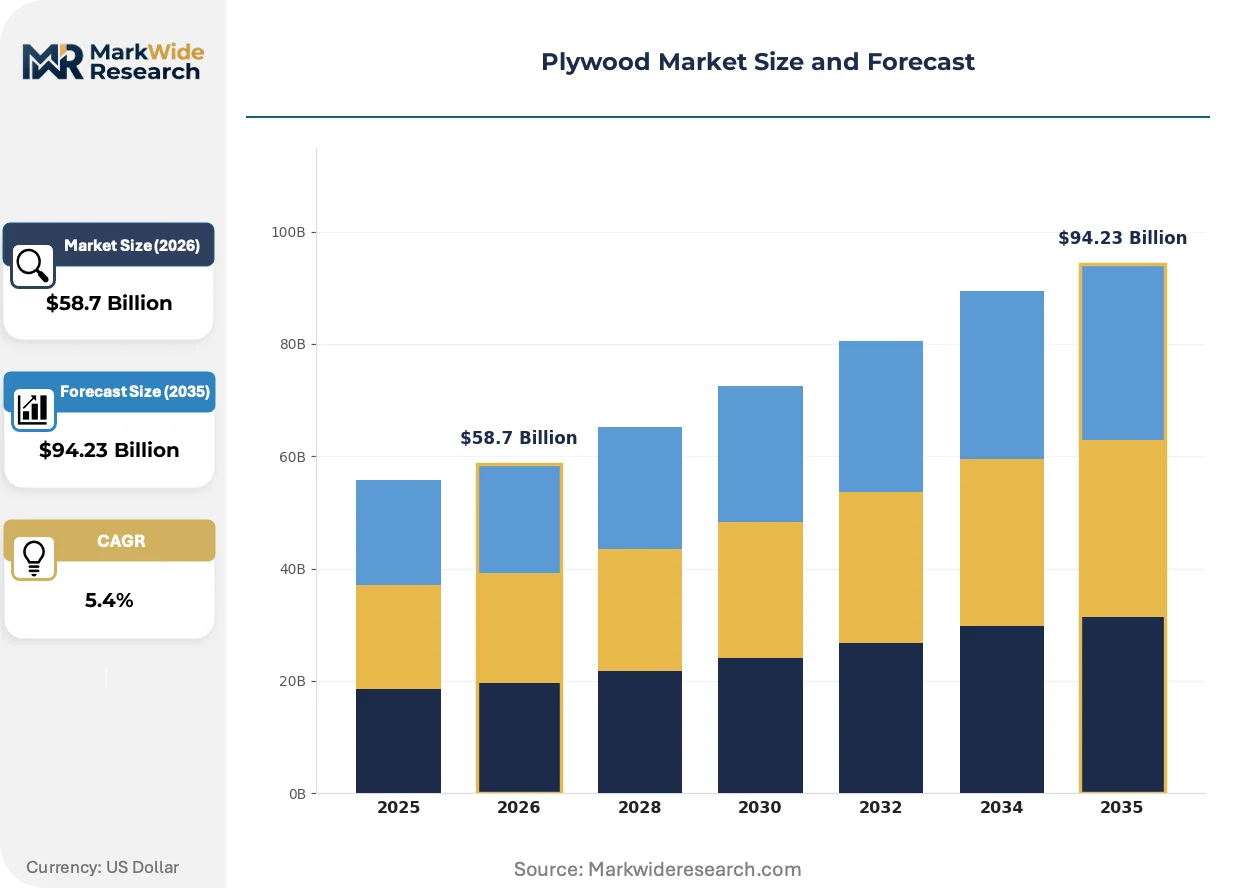
Market Dynamics
The EU Timber Regulation is forcing importers to abandon unverified tropical supply chains and rebuild procurement around documented legal harvest documentation, certified fiber flows, and third-party chain-of-custody verification systems.
Growth Catalysts
- Urbanization in Southeast Asia:Residential construction in Indonesia and Vietnam is absorbing greater engineered wood panel volumes as city populations expand and mid-rise timber frames displace concrete block construction.
- Cross-laminated timber technology:Architects in Germany, Austria, and Canada are specifying taller wood buildings, pulling structural plywood into multi-story frames previously reserved for steel and concrete.
- EPA formaldehyde emission standards:Stricter adhesive formulation rules in the United States are filtering uncertified imports and rewarding domestic producers with compliant resin systems and testing infrastructure.
Market Restraints
- Tropical hardwood fiber scarcity:Legal harvest documentation requirements under the EU Timber Regulation have shrunk available supply from unverified Southeast Asian and African sources, compressing merchantable veneer logs.
- Structural substitution by OSB:Oriented strand board continues displacing softwood plywood in North American sheathing applications where code acceptance and cost efficiency favor engineered strand panels.
- Adhesive cost volatility:Phenol-formaldehyde and melamine-urea resin prices fluctuate with petrochemical feedstock markets, squeezing margins on moisture-resistant and marine-grade product lines.
Strategic Opportunities
- Modular construction specifications:Prefabricated building systems in Sweden, Finland, and the United Kingdom are creating demand for precision-cut, performance-graded engineered plywood panels with documented structural ratings.
- Biogenic carbon accounting:Public infrastructure tenders in France, the Netherlands, and California are beginning to credit embodied carbon metrics for certified wood products, favoring documented low-carbon supply chains.
- Marine and coastal infrastructure:Boatbuilding yards in Florida, Queensland, and the Mediterranean are specifying premium moisture-resistant grades for pier decking, seawalls, and vessel hulls as coastal construction accelerates.
Industry Challenges
- Chain-of-custody certification timelines:FSC and PEFC documentation requirements demand 12-18 month audit cycles that delay market access for new tropical suppliers and strain working capital.
- Veneer drying and pressing equipment capex:Continuous press technology and energy-efficient kiln systems require capital deployment that mid-scale mills struggle to finance against volatile log costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plywood Market |
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $94.23 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Softwood Plywood, Hardwood Plywood, Marine Plywood, Structural Plywood End Use: Furniture, Construction, Packaging, Interior Design Thickness: Below 5 mm, 5 mm to 15 mm, 15 mm to 25 mm, Above 25 mm Technology: Veneer Lamination, Cross-Laminated, Glued Laminated, Engineered Wood |
| Companies Covered | West Fraser, Metsä Wood, Georgia-Pacific, Kronospan, Sveza, Weyerhaeuser Company, Columbia Forest Products, Eksons Corporation, Arauco, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plywood Market Strategic Shifts & Innovations
Digital traceability platforms, low-emission adhesive chemistry, and prefabrication-ready panel formats are compressing traditional supply chains and redefining how structural wood products reach construction sites.
Cross-laminated timber technology is converging with robotic fabrication systems to enable precision-cut, project-specific panel kits that ship directly to job sites. Timber frame contractors in Austria, Germany, and British Columbia are adopting these integrated design-to-fabrication workflows. The technology is converging with building information modeling to compress on-site labor hours and reduce material waste ratios.
REACH chemical restrictions and the EU Green Deal's embodied carbon mandates are tightening adhesive formulation requirements and elevating documentation burdens for imported panels. Manufacturers serving European markets must now submit extended safety data sheets and lifecycle assessments alongside physical product. Marine-grade and exterior-rated plywood face the steepest compliance ramps as phenol-formaldehyde alternatives undergo accelerated testing.
Direct mill-to-contractor procurement platforms are bypassing traditional distributor networks for large-scale commercial and multifamily projects. Volume buyers in Texas, Florida, and Ontario are negotiating frame-package contracts that specify certified fiber, cut-to-size dimensions, and sequenced delivery schedules. This channel compression is most visible in North American markets where national builders consolidate purchasing across regional divisions.
Plywood Market Segmentation
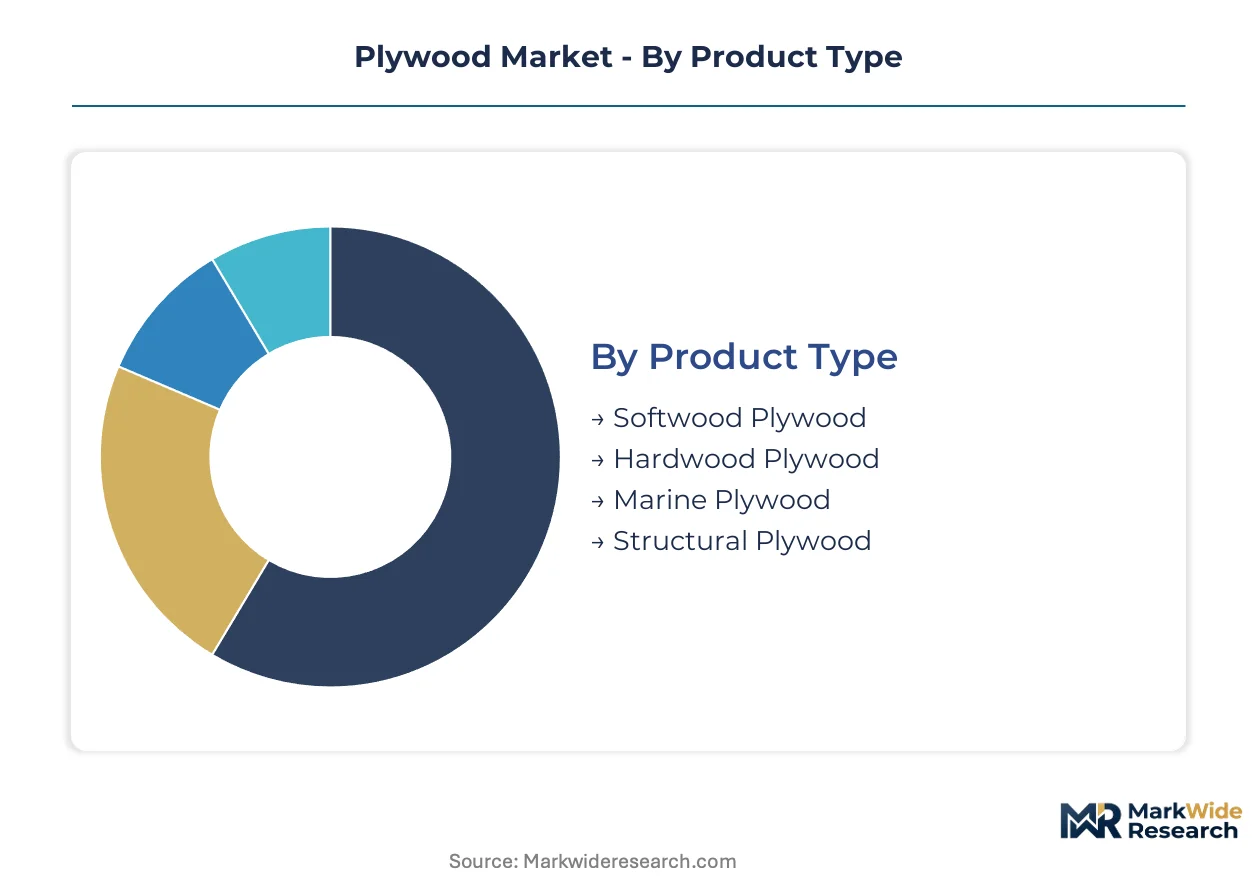
Plywood segmentation maps directly to performance specifications and regulatory compliance tiers. Specification choices determine adhesive chemistry, certification requirements, and end-market access across construction, furniture, and marine applications.
Product Type:
Structural performance and moisture resistance define the technology axis, with softwood and marine grades occupying opposite ends of the durability spectrum.
- Softwood Plywood:Composed of softwood veneers bonded with phenol-formaldehyde or urea-formaldehyde resins, this grade dominates structural sheathing and subflooring. Demand concentrates in US residential construction where code-compliant sheathing volumes sustain high-throughput mills across the US South and Pacific Northwest. EPA formaldehyde emission standards filter non-compliant imports and reward domestic producers with certified resin systems.
- Marine Plywood:Manufactured with waterproof phenolic adhesives and high-grade Douglas fir or tropical hardwood veneers, this specification resists delamination in prolonged wet exposure. Boatbuilding yards in Florida and Queensland specify these panels for hull construction and pier decking as coastal infrastructure investment accelerates. Premium positioning reflects stringent BS 1088 or AS/NZS 2272 certification requirements.
- Hardwood Plywood:Decorative face veneers over poplar or eucalyptus cores serve furniture substrates and interior millwork where aesthetic grade matters.
- Structural Plywood:Stress-graded panels with documented mechanical properties anchor concrete formwork and engineered timber connections in multi-story construction.
Mature deployment sits with softwood plywood in commodity construction applications. Newer deployment is concentrated in marine grades as coastal climate adaptation drives infrastructure specification upgrades.
End Use:
Application economics separate high-volume commodity flows from precision-specified project deliveries.
- Construction:Structural sheathing, concrete formwork, and permanent wood foundations absorb the majority of softwood and structural plywood volumes. Urbanization in Indonesia and Vietnam is pulling engineered panel demand as mid-rise timber frames displace concrete block construction. Cross-laminated timber technology is expanding addressable floor area for wood-based systems.
- Furniture:Hardwood-faced panels serve cabinetry, casegoods, and architectural millwork where surface quality and machinability command specification. EU Timber Regulation chain-of-custody requirements filter uncertified tropical hardwood supplies, compressing available veneer log flows and elevating documented legal harvest premiums.
- Interior Design:Decorative veneers and specialty finishes support commercial fit-out and residential renovation.
- Packaging:Economy-grade softwood panels protect heavy machinery and export goods where one-way durability suffices.
Volume leadership belongs to construction. Value capture is climbing fastest in interior design as architects specify certified, low-embodied-carbon panels for visible applications.
Thickness:
Panel thickness correlates with load-bearing capacity and spans structural versus non-structural application boundaries.
- 5 mm to 15 mm:This mid-range band dominates furniture substrates, interior wall paneling, and non-structural architectural applications. Precision sanding and uniform thickness tolerance enable CNC machining for modular cabinet systems. Swedish and Finnish prefabricated building manufacturers specify this range for interior componentry.
- 15 mm to 25 mm:Structural sheathing, subflooring, and roofing applications require this thickness band for code-compliant span ratings. North American production concentrates on 15/32-inch and 23/32-inch equivalents to match dimensional lumber framing modules.
- Below 5 mm:Ultra-thin bending plywood serves curved furniture forms and decorative overlays.
- Above 25 mm:Heavy-duty concrete formwork and industrial flooring demand maximum stiffness and fastener holding power.
Production scale centers on the 15-25 mm band. Specification innovation is advancing most quickly in below-5 mm grades as furniture designers pursue compound curves and reduced material intensity.
Technology:
Manufacturing process selection determines fiber efficiency, dimensional stability, and architectural scale potential.
- Cross-Laminated:Orthogonal layering of solid-sawn or veneer lumber creates massive panels with two-way structural action. German and Austrian architects specify CLT for multi-story residential and commercial buildings up to twelve stories, pulling plywood-compatible specification standards into tall wood construction. Robotic fabrication systems enable precision-cut, project-specific panel kits.
- Veneer Lamination:Traditional rotary-peeled veneer construction maintains cost leadership in commodity sheathing and furniture substrates. Continuous press technology and energy-efficient kiln systems differentiate capital-intensive producers.
- Glued Laminated:Edge-glued lumber laminations produce beams and columns rather than panels, occupying adjacent structural wood product categories.
- Engineered Wood:Composite processes converting lower-grade fiber into performance-graded panels reshape margin pools by expanding raw material flexibility.
Established capacity sits with veneer lamination. Steepest expansion trajectory belongs to cross-laminated technology as building codes evolve to permit taller timber structures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vancouver anchors North American plywood manufacturing through its integrated coastal mill network serving Pacific Rim export corridors and domestic construction supply chains.
United States
Residential construction across Texas and Florida absorbs structural sheathing volumes as housing starts recover in Sun Belt metros. EPA formaldehyde emission standards filter non-compliant imports and reward domestic producers with certified resin systems. Pacific Northwest veneer mills in Oregon and Washington sustain softwood plywood capacity for West Coast distribution.
Canada
Cross-laminated timber projects in British Columbia pull structural panel demand as Vancouver architects specify taller wood buildings up to twelve stories. Canadian Wood Council building code advocacy accelerates mid-rise timber frame acceptance. Interior British Columbia sawmills concentrate rotary-peeled veneer production for Asian export markets.
Germany
Modular construction specifications in Stuttgart and Munich create demand for precision-cut engineered plywood panels with documented structural ratings. EU Green Deal embodied carbon mandates elevate documentation burdens for imported panels. Bavarian prefabricated building manufacturers specify certified fiber for public infrastructure tenders.
Indonesia
Urbanization in Jakarta and Surabaya absorbs greater engineered wood panel volumes as mid-rise timber frames displace concrete block construction. EU Timber Regulation chain-of-custody requirements compress available veneer log flows from unverified sources. Kalimantan manufacturing hubs expand capacity for export-grade panels with FSC certification.
Vietnam
Furniture manufacturing clusters in Binh Duong and Dong Nai province drive hardwood plywood consumption for cabinetry and casegoods exports. Japan's JIS standards govern product access for premium panel segments. Ho Chi Minh City port infrastructure supports direct mill-to-contractor procurement platforms bypassing traditional distributor networks.
Plywood Market Key Industry Players
The competitive structure tilts toward vertically integrated fiber suppliers with captive timberland and certified chain-of-custody systems. North American producers concentrate around scale-driven softwood sheathing capacity, while European specialists occupy modular construction and engineered systems niches. Three archetypes dominate: timberland-integrated majors, regional veneer specialists, and prefabrication-focused engineered wood fabricators. Capacity expansion and certification-driven procurement partnerships represent the dominant competitive moves as regulatory barriers filter uncertified traders.
Among North American timberland-integrated producers, West Fraser and Georgia-Pacific exemplify scale-driven structural panel capacity with softwood veneer production advantages. Metsä Wood occupies a position within the European engineered systems tier, representing modular construction specialization. These three anchors illustrate how fiber control, certification infrastructure, and end-market specification relationships determine competitive positioning across distinct geographic demand centers.
| Leading Market Players |
|---|
| West Fraser |
| Metsä Wood |
| Georgia-Pacific |
| Kronospan |
| Sveza |
| Weyerhaeuser Company |
| Columbia Forest Products |
| Eksons Corporation |
| Arauco |
| Others |
Cost & Logistics Intelligence
Phenol-formaldehyde resin costs cascade from petrochemical feedstock volatility through marine-grade pricing tiers, compressing margins on moisture-resistant panels while certified fiber premiums widen spreads between documented legal harvest and uncertified tropical supply. Buyers in European furniture manufacturing and North American coastal construction absorb these input cost shifts through contract structures that index adhesive expenses separately from veneer log values.
Pricing Analysis
Certified chain-of-custody documentation anchors value-based pricing for FSC and PEFC-labeled panels serving EU public infrastructure tenders and California embodied carbon procurement rules. Price differentiation separates premium marine grades with BS 1088 certification from commodity softwood sheathing, with brand premiums attaching to West Fraser and Georgia-Pacific structural ratings. Cost compression in standard-grade sheathing intensifies as OSB substitution erodes plywood share in North American residential construction. Volume buyers at national builders exhibit highest price sensitivity, while boatyards in Florida and Queensland demonstrate lowest sensitivity for certified moisture-resistant specifications.
Supply Chain Analysis
Skilled veneer grading technicians and kiln operators concentrate in British Columbia, Oregon, and Washington state sawmill clusters, constraining capacity expansion timelines for rotary-peeled softwood production. Raw material flows draw from coastal Douglas fir and Southern yellow pine timberland, with phenolic adhesive chemistry resting on benzene and methanol feedstock markets. Single-source vulnerability concentrates in Indonesian and Vietnamese hardwood veneer supplies subject to EU Timber Regulation documentation delays. Distribution runs through direct mill-to-contractor procurement platforms bypassing traditional distributor networks for large-scale commercial and multifamily frame-package contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified fiber scarcity props pricing power across marine and structural grades, with FSC and PEFC audit timelines creating 12-18 month bottlenecks that filter uncertified competitors from premium segments.
For Market Incumbents: To counter OSB displacement in North American sheathing applications, anchor capacity utilization through backward integration into coastal Douglas fir timberland in British Columbia and Pacific Northwest regions. Prioritize continuous press technology upgrades and energy-efficient kiln systems to sustain cost leadership against mid-scale mills facing working capital constraints against volatile log costs. For New Entrants and Emerging Players: Begin with precision-cut engineered plywood panels for Swedish, Finnish, and United Kingdom modular construction specifications, where documented structural ratings and robotic fabrication compatibility create specification stickiness. Target biogenic carbon accounting credits in French and Dutch public infrastructure tenders as the most penetrable procurement channel, leveraging digital traceability platforms to compress traditional supply chain intermediation. For Investors and Strategic Acquirers: Accelerating EU Green Deal embodied carbon mandate enforcement is the leading indicator that certified low-carbon supply chains will command sustained valuation premiums over the coming decade. Acquisition focus should center on mid-scale mills with existing FSC certification infrastructure and captive veneer drying capacity in Southeast Asian manufacturing hubs. Monitor Kalimantan and Ho Chi Minh City port infrastructure investments as signals of export-grade panel capacity expansion timing.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Infrastructure Investment | FSC and PEFC chain-of-custody systems unlock EU Timber Regulation-compliant market access for tropical hardwood suppliers. |
| Continuous Press Technology Deployment | Energy-efficient veneer drying and pressing equipment differentiates capital-intensive producers against mid-scale competitors. |
| Direct Mill-to-Contractor Procurement Platforms | Bypassing distributor networks captures margin from national builders consolidating frame-package purchasing across regional divisions. |
| Cross-Laminated Timber Specification Development | Robotic fabrication integration with building information modeling compresses on-site labor hours for Austrian and German timber contractors. |
| Low-Emission Adhesive Chemistry R&D | REACH-compliant phenol-formaldehyde alternatives enable continued access to European marine-grade and exterior-rated panel segments. |
Research Approach
Document review covered trade customs data, SEC 10-K filings from North American timberland-integrated producers, EU Timber Regulation enforcement reports, and FSC certification registry databases, complemented by interviews with plant managers at Pacific Northwest veneer mills, procurement leads at Texas and Florida residential construction firms, and technical R&D directors at adhesive formulation suppliers. Primary fieldwork with distribution channel partners in Ho Chi Minh City and Jakarta validated secondary estimates of Southeast Asian manufacturing capacity expansion. Bottom-up production volume tallies triangulated against top-down consumption estimates from national construction starts and furniture export data.
Segment-level volume and value trajectories emerged from modeling across product type, end-use application, panel thickness, and manufacturing technology dimensions throughout the projection horizon. CAGRs were synthesized from log supply growth curves, urbanization-driven construction demand elasticities in Indonesia and Vietnam, and substitution dynamics between plywood and oriented strand board in North American sheathing markets. Forecast inputs incorporated EPA formaldehyde emission standard compliance timelines, EU Green Deal embodied carbon mandate implementation pacing, and cross-laminated timber building code evolution in Germany, Austria, and British Columbia.
Underlying measurement precision varies by segment; softwood plywood construction volumes carry tighter precision than marine-grade specialty applications given standardized building code specifications and established trade flow reporting. Forecasts reflect assumptions regarding sustained urbanization rates in Southeast Asia, continued OSB substitution pressure in North American residential construction, and stable EU Timber Regulation enforcement intensity. Material deviation in Indonesian or Vietnamese certification audit timelines, phenol-formaldehyde feedstock cost spikes, or accelerated cross-laminated timber code adoption warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper Products
Global Kraft Paper Market
Paper Products
Solid Bleached Sulfate (SBS) Board Market
Paper Products
Household Paper Market
Paper Products
Paper Pigment Market
Paper Products
Europe Paper Market
Paper Products
Liquid Paperboard Market
Paper Products
Specialty Paper Market
Paper Products
Inlay Paper Market
Paper Products
Glassine Paper Market
Paper Products
Chemical Pulp Market
Paper Products
Paper Products Market
Paper Products
Europe Tissue and Hygiene Paper Market
Paper Products
Global Thin Papers Market
Paper Products
Recovered Paper Market
Paper Products
Clay Coated Paper Market
Paper Products
Ceramic Paper Market