
 Natural Gas Storage Technologies Market | 2026-2036
Natural Gas Storage Technologies Market Size, Share, and Industry Trends Forecast 2026-2036
Natural Gas Storage Technologies Market Foresight
Aftermarket service revenue for cavern integrity monitoring is fragmenting across specialized contractors and integrated operators. Exxon Mobil Corporation leverages its depleted reservoir portfolio across the US Gulf Coast to capture long-duration storage contracts. Equinor ASA anchors North Sea offshore storage development with subsurface engineering capabilities. Uniper SE dominates European salt cavern operations through its Central German gas hub infrastructure.
Natural gas storage technologies encompass engineered systems for retaining methane in underground geologic formations, above-ground cryogenic vessels, or pressurized containers, typically operating at pressures ranging from 1,000 to 4,000 psi for compressed storage and minus 162 degrees Celsius for liquefied natural gas. These systems balance supply-demand mismatches across hours, seasons, and emergency disruptions. Depleted reservoirs and salt caverns command the largest share of working gas capacity due to established geology and lower unit development costs. LNG storage terminals represent the fastest-expanding segment as coastal import facilities multiply. Monitoring systems and injection technology concentrate margin pools where real-time pressure management and leak detection reduce regulatory liability.
The US EPA enforces methane emission thresholds under the Clean Air Act that compel operators to deploy advanced leak detection at storage facilities. The EU F-Gas Regulation and REACH framework restrict sealant and coating chemistries used in above-ground LNG containment. China's MEE imposes emission intensity benchmarks on provincial gas grid operators that drive investment in tighter cavern wellbore construction. Stakeholders must weigh geologic storage against liquefaction infrastructure as renewable penetration reshapes seasonal demand curves.
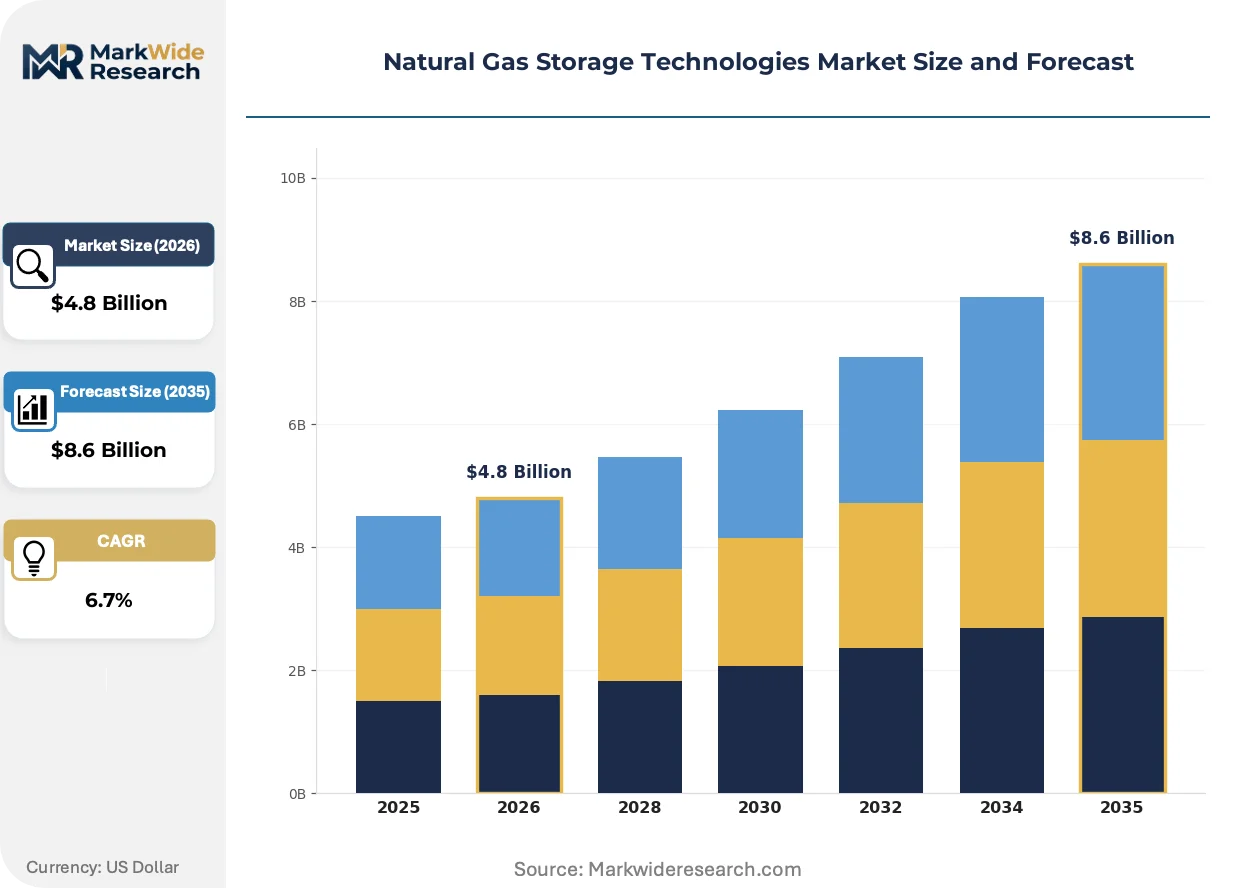
Market Dynamics
Renewable intermittency is forcing utilities to expand salt cavern and depleted reservoir capacity for multi-day grid balancing, tightening the link between storage geology and power system reliability.
Growth Catalysts
- EU F-Gas Regulation:Methane containment mandates are accelerating wellhead seal upgrades and automated leak detection deployment across underground facilities.
- Power sector decarbonization:Wind and solar volatility is extending injection-withdrawal cycles beyond traditional seasonal patterns, expanding working gas capacity requirements.
- Salt dome geology:The US Gulf Coast corridor anchors incremental cavern development due to favorable depth, thickness, and solution-mining economics.
Market Restraints
- Steel alloy volatility:Nickel and chromium price swings compress margins on high-pressure wellhead equipment and cavern tubing strings.
- Permitting timelines:EPA methane monitoring requirements and state environmental reviews extend salt cavern commissioning by three to five years.
- Battery storage substitution:Lithium-ion systems below four-hour duration are capturing peaking capacity contracts previously served by rapid-cycle gas storage.
Strategic Opportunities
- Hydrogen blending infrastructure:Salt caverns with upgraded wellbore metallurgy can store hydrogen-natural gas mixtures, opening adjacent chemical and steel sector demand.
- India's city gas distribution:The Petroleum and Natural Gas Regulatory Board mandates are building LNG import terminal and satellite storage networks in Gujarat and Maharashtra.
- Real-time fiber optic sensing:Distributed temperature and acoustic monitoring is digitizing cavern integrity assessment, reducing manual inspection frequency.
Industry Challenges
- Geomechanical modeling expertise:Finite-element analysis of salt creep and cavern convergence requires specialized subsurface engineers in short supply.
- Legacy SCADA integration:Older depleted reservoir facilities operate on proprietary control systems that resist API-standard data exchange with modern grid operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Natural Gas Storage Technologies Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Storage Type: Depleted Reservoirs, Aquifer Storage, Salt Caverns, LNG Storage Application: Peak Shaving, Base Load Supply, Seasonal Storage, Backup Supply Technology: Compressed Natural Gas, Liquefaction, Injection Technology, Monitoring Systems End User: Utilities, Industrial Users, Commercial Users, Residential Consumers |
| Companies Covered | Exxon Mobil Corporation, Equinor ASA, Uniper SE, Gazprom PJSC, Enbridge Inc., TC Energy Corporation, The Williams Companies, Inc., China National Petroleum Corporation, Kinder Morgan, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Natural Gas Storage Technologies Market Shifts & Advancements
Digital subsurface characterization and automated pressure management are compressing operational risk profiles while regulatory chemistry restrictions reshape above-ground containment materials.
Advanced distributed fiber optic sensing is digitizing cavern wall monitoring by converting temperature and strain data into real-time geometric deformation maps. Salt dome operators in Texas and Louisiana are deploying these systems to replace quarterly sonar surveys with continuous surveillance. The technology is digitizing integrity assurance workflows and reducing insurance premiums for long-duration storage contracts.
REACH framework restrictions on fluorinated sealants are forcing LNG terminal operators to reformulate above-ground tank gaskets and membrane materials. ECHA substance evaluation has delisted several legacy elastomers used in cryogenic containment, triggering a two-year qualification cycle for replacement chemistries. European import facilities are responding by accelerating in-house materials testing and dual-sourcing strategies.
Aftermarket service unbundling is fragmenting the traditional integrated operator model across North American salt caverns. Specialized contractors now bid separately for cavern leaching, wellhead maintenance, and integrity verification, compressing contract values for bundled service providers. This pattern is most visible in the US Gulf Coast, where independent engineering firms have captured monitoring scope from major storage operators.
Natural Gas Storage Technologies Market Segmentation
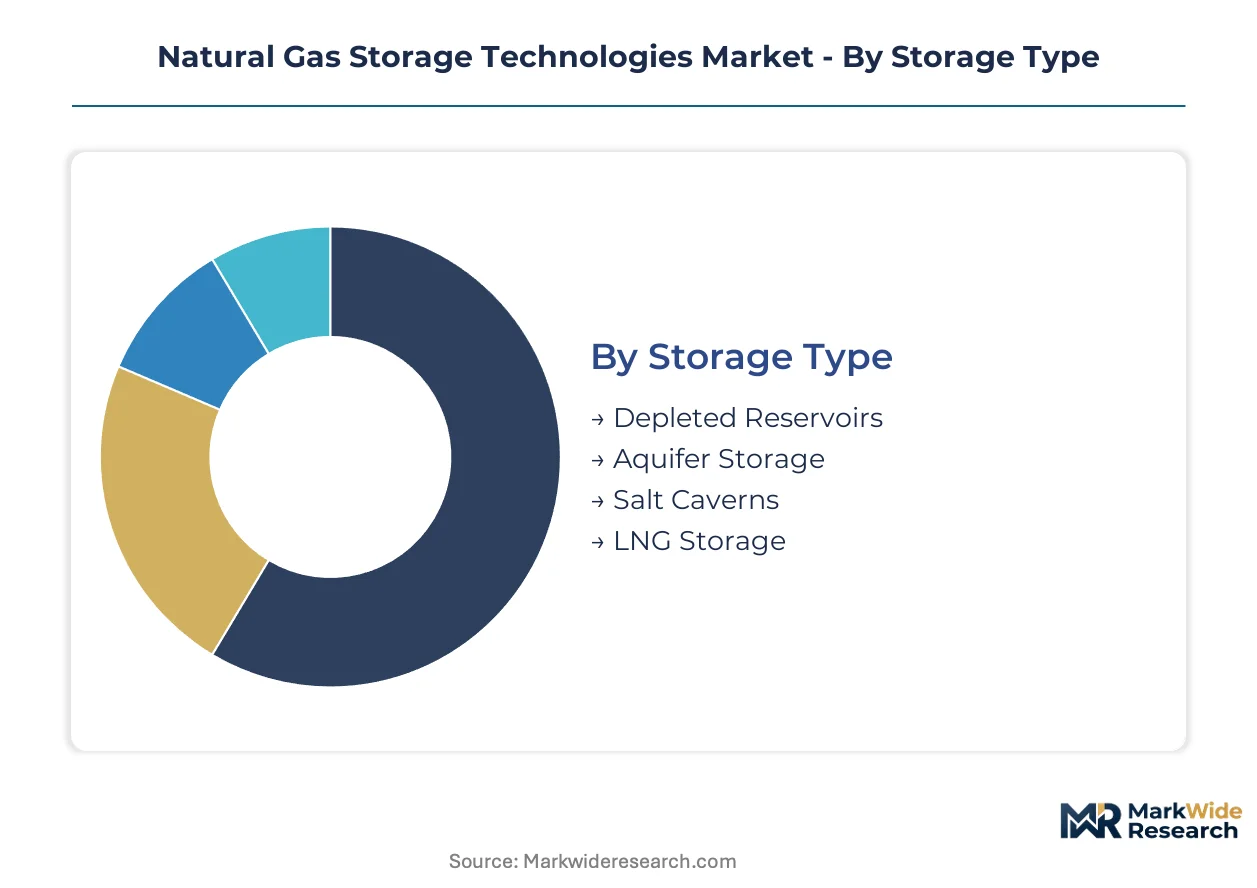
Storage technology selection dictates capital intensity, permitting timelines, and operational flexibility across the natural gas value chain. Segment boundaries blur as salt cavern operators adopt LNG-style monitoring systems and depleted reservoir sites integrate rapid-cycle compression equipment.
Storage Type:
Cycle frequency separates these segments—some turn inventory weekly while others hold gas across heating seasons.
- Depleted Reservoirs:Porous rock formations previously tapped for oil or gas production now store methane at pressures below original reservoir levels. Demand clusters in the US Gulf Coast where Exxon Mobil leverages legacy field infrastructure for long-duration contracts.
- Salt Caverns:Solution-mined voids in underground salt domes offer the fastest injection-withdrawal cycling due to impermeable walls and high deliverability rates. The US Gulf Coast corridor anchors incremental development as utilities balance renewable intermittency.
- Aquifer Storage:Water-bearing rock formations receive gas displacing native brine through dedicated wells. Operators in Germany and France utilize this technology where salt domes are absent.
- LNG Storage:Above-ground cryogenic tanks and insulated containment systems hold methane at minus 162 degrees Celsius. Coastal import terminals in India and China drive capacity expansion.
Depleted reservoirs dominate installed base. LNG storage is where expansion concentrates.
Application:
Revenue stability varies—some applications generate predictable seasonal cash flows while others capture volatile spot market premiums.
- Peak Shaving:Rapid withdrawal capacity meets demand spikes during cold snaps or supply interruptions. US utilities deploy salt caverns for this function as battery storage captures shorter-duration peaks.
- Seasonal Storage:Injection during summer months balances winter heating demand across months-long cycles. European operators under EU F-Gas Regulation constraints prioritize this application for grid stability.
- Base Load Supply:Continuous withdrawal supports industrial customers requiring uninterrupted methane delivery. Chemical plants and steel mills anchor demand.
- Backup Supply:Emergency reserves activate during pipeline ruptures or geopolitical supply disruptions. Strategic petroleum reserve models influence national gas security planning.
Seasonal storage commands the largest working gas volumes. Peak shaving is expanding most quickly as renewable penetration steepens intraday price volatility.
Technology:
Capital deployment intensity separates these categories—some require billion-dollar liquefaction trains while others deploy modular compression skids.
- Liquefaction:Cryogenic cooling systems convert pipeline gas to liquid for density-efficient transport and storage. Import terminal developers in India and China concentrate procurement.
- Injection Technology:High-pressure compressors and wellhead equipment move gas into underground formations. Salt cavern leaching operations in Texas and Louisiana drive specialized contractor demand.
- Compressed Natural Gas:Pressure vessels store methane at 3,000 psi for vehicle fueling and distributed generation. City gas distribution networks in Gujarat and Maharashtra adopt this for last-mile delivery.
- Monitoring Systems:Distributed fiber optic sensing and automated pressure management reduce regulatory liability. Real-time cavern integrity verification commands premium pricing.
Injection technology dominates capital expenditure. Monitoring systems show the steepest expansion trajectory as EPA methane rules tighten.
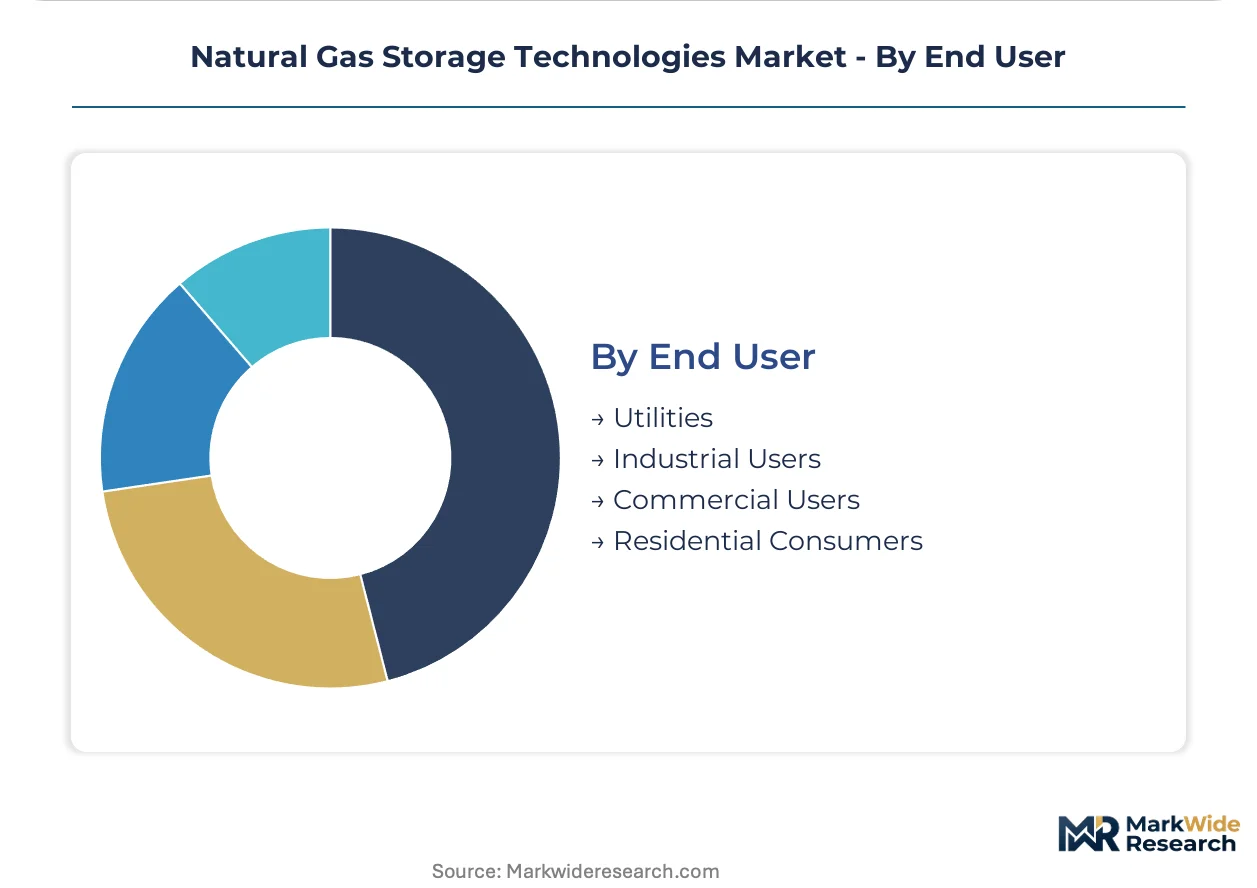
End User:
Contract duration and credit quality differentiate these customer segments—some sign decade-long storage agreements while others purchase interruptible services.
- Utilities:Gas distribution companies and power generators secure firm storage capacity for supply security obligations. US municipal utilities and European unbundled network operators anchor demand.
- Industrial Users:Petrochemical plants, fertilizer manufacturers, and steel mills require uninterrupted methane feedstock. German chemical clusters and US Gulf Coast refineries concentrate procurement.
- Commercial Users:Hospitals, universities, and large building complexes purchase backup supply services. Interruptible contracts predominate.
- Residential Consumers:Individual households access storage indirectly through utility procurement. Direct participation remains negligible outside liquefied petroleum gas markets.
Utilities dominate contracted capacity. Industrial users are where price premiums concentrate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and the Netherlands exhibit the lowest price elasticity, absorbing premium storage tariffs for seasonal security, while Indian and Chinese utilities remain highly price-sensitive, prioritizing lowest-cost depleted reservoir options over salt cavern premiums.
United States
Gulf Coast utilities and power generators drive demand for rapid-cycle salt cavern capacity to balance wind and solar intermittency. The EPA enforces methane emission thresholds under the Clean Air Act that compel advanced leak detection deployment. The Texas-Louisiana salt dome corridor anchors incremental cavern development through favorable geology and established solution-mining infrastructure.
Germany
Industrial chemical clusters and unbundled network operators require uninterrupted seasonal storage for supply security obligations. The EU F-Gas Regulation and national implementation frameworks restrict sealant chemistries and mandate automated containment monitoring. The Central German gas hub around Bad Lauchstädt concentrates salt cavern operations where Uniper SE maintains integrated infrastructure.
China
Provincial gas grid operators under emission intensity benchmarks from the MEE invest in tighter wellbore construction and real-time monitoring systems. National dual carbon goals accelerate LNG import terminal expansion along coastal provinces. The Yangtze River Delta and Pearl River Delta regions concentrate new above-ground cryogenic storage capacity to serve city gas distribution networks.
India
Petroleum and Natural Gas Regulatory Board mandates for city gas distribution build LNG import terminal and satellite storage networks. National infrastructure programs prioritize lowest-cost storage options for price-sensitive residential and commercial conversion targets. Gujarat and Maharashtra anchor procurement concentration, with Hazira and Dahej terminals driving monitoring system and containment equipment demand.
Netherlands
Integrated energy companies and trading houses utilize seasonal storage for arbitrage and grid balancing within the North West European market. REACH framework restrictions on fluorinated sealants force reformulation of tank gasket and membrane materials at Rotterdam-area import facilities. The Groningen depleted gas field transition and Zuidwending salt cavern complex illustrate the shift from production to dedicated storage geology.
Natural Gas Storage Technologies Market Competitive Landscape
Capability concentration sits with subsurface engineering specialists who command premium pricing for geomechanical modeling and cavern integrity verification; scale advantage sits with integrated energy majors who leverage legacy field portfolios for long-duration contract capture. The vendor base separates into three tiers: multinational operators with depleted reservoir footprints, European utilities with salt cavern hub control, and specialized contractors unbundling leaching and monitoring services. Dominant competitive moves include strategic partnerships for hydrogen blending infrastructure and selective capacity expansion in Gulf Coast salt domes.
Within the integrated operator tier, Exxon Mobil Corporation exemplifies the depleted reservoir archetype through its Gulf Coast legacy field positioning, while Equinor ASA represents North Sea offshore storage development anchored in subsurface engineering capabilities. Uniper SE occupies a distinct position within European salt cavern operations. These three entities illustrate how geographic endowment and infrastructure control determine competitive positioning without requiring equivalent technical specialization.
| Leading Market Players |
|---|
| Exxon Mobil Corporation |
| Equinor ASA |
| Uniper SE |
| Gazprom PJSC |
| Enbridge Inc. |
| TC Energy Corporation |
| The Williams Companies, Inc. |
| China National Petroleum Corporation |
| Kinder Morgan, Inc. |
| Others |
Supply & Pricing Matrix
Underutilized salt cavern capacity across the Texas-Louisiana corridor compresses spot pricing for rapid-cycle storage while tightening margins on bundled service contracts. This utilization imbalance forces integrated operators to unbundle leaching and monitoring scopes, fragmenting revenue pools across specialized contractors who compete on equipment uptime rather than geologic endowment.
Pricing Analysis
Aftermarket service revenue for cavern integrity monitoring and wellhead maintenance drives lifetime contract value beyond initial leaching capex. Three-tier pricing structure across premium, standard, and economy levels segments buyers by automation intensity and real-time data requirements. Cost compression in standard-tier monitoring bundles intensifies as fiber optic sensing commoditizes, while premium tiers commanding predictive analytics subscriptions face limited price elasticity. Utilities with renewable balancing obligations exhibit the lowest price sensitivity, absorbing tariffs for guaranteed deliverability, whereas merchant storage traders in the Gulf Coast spot market drive aggressive rate negotiations.
Supply Chain Analysis
Upstream metallurgy for high-pressure wellhead equipment draws from specialized steel alloy foundries concentrated in Germany, Japan, and South Korea. Nickel and chromium feedstocks for corrosion-resistant tubing strings rest on mining operations in Indonesia and the Philippines, with processing capacity anchored in Chinese stainless steel mills. Single-source vulnerability in solution-mining brine disposal logistics threatens commissioning timelines for new cavern developments. Distribution runs through integrated energy majors with captive field service divisions, though independent engineering firms are capturing monitoring and integrity verification scopes through competitive tendering.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized subsurface engineering capabilities for geomechanical modeling and salt creep analysis remain scarce relative to project pipelines, creating durable rent extraction for qualified contractors and forcing buyers into long lead times for critical expertise.
For Market Incumbents: Build regulatory compliance moats by pre-certifying cavern integrity systems under evolving EPA methane monitoring thresholds and EU F-Gas containment mandates. Lock in salt dome acreage through preemptive leasing in the Gulf Coast corridor before independent developers consolidate fragmented mineral rights. Battery storage substitution for sub-four-hour peaking contracts threatens rapid-cycle gas storage margins; respond by anchoring long-duration seasonal contracts with utilities facing renewable intermittency obligations. For New Entrants and Emerging Players: Build out hydrogen blending infrastructure capabilities as steel mills and chemical plants pilot methane-hydrogen mixture storage in repurposed salt caverns. India's city gas distribution buildout in Gujarat and Maharashtra presents the most penetrable geography, with Petroleum and Natural Gas Regulatory Board mandates creating guaranteed offtake for LNG terminal satellite storage. Target aftermarket monitoring services rather than integrated cavern development, as unbundling trends fragment incumbent bundled offerings and open procurement channels for specialized fiber optic sensing contractors. For Investors and Strategic Acquirers: Long-term, this sits as a grid-stability infrastructure play because renewable penetration steepens seasonal demand curves and extends injection-withdrawal cycles beyond traditional patterns. Acquisition targets should center on subsurface engineering specialists with finite-element modeling capabilities and established regulatory relationships, rather than commodity storage capacity owners. The signal to watch is FERC and EPA rulemaking velocity on methane detection automation, which would accelerate replacement demand for legacy SCADA systems and expand the addressable market for digital monitoring providers.| Strategic Initiative | Industry Significance |
|---|---|
| Hydrogen Blending Infrastructure | Opens adjacent demand from steel and chemical sectors piloting methane-hydrogen mixtures. |
| Real-Time Fiber Optic Sensing Deployment | Reduces manual inspection frequency and insurance premiums for long-duration storage contracts. |
| Salt Dome Acreage Pre-Leasing | Secures favorable geology in the Gulf Coast corridor before mineral rights consolidate. |
| Regulatory Pre-Certification | Accelerates commissioning timelines under tightening EPA methane monitoring requirements. |
| Aftermarket Service Unbundling | Captures monitoring scope from integrated operators through competitive specialized contracting. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with utility planning officers, salt cavern operators, EPC contractors, and subsurface engineering specialists; and secondary validation through EIA storage capacity reports, FERC facility filings, IEA natural gas market analyses, and EU regulatory implementation documents. Bottom-up triangulation against operator-disclosed working gas volumes and top-down reconciliation with national inventory surveys ensured segmentation integrity across storage type and application dimensions.
Forecast inputs incorporated project development pipelines, permitting velocity by regulatory jurisdiction, and steel alloy price trajectories affecting wellhead equipment procurement. Modeled dimensions spanned storage type, application cycle frequency, technology capital intensity, and end-user contract duration across the projection horizon. CAGRs derived from segment-level capacity addition schedules and unit economics for solution-mining operations, with cross-checking against historical injection-withdrawal velocity trends and renewable penetration curves by regional power market.
The forecast holds incumbent behavior within observed patterns; aggressive moves by battery storage developers or hydrogen infrastructure investors would shift outcomes beyond modeled ranges. Cross-checking against IEA World Energy Outlook storage capacity benchmarks and EIA working gas inventory volatility indices is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transmission and Distribution
United Kingdom High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
LNG Infrastructure Market
Transmission and Distribution
Pipeline Services Market
Transmission and Distribution
Middle-East and Africa DC Distribution Networks Market
Transmission and Distribution
Oil Pipeline Infrastructure Market
Transmission and Distribution
Underground Cabling EPC Market
Transmission and Distribution
South-East Asia DC Distribution Network Market
Transmission and Distribution
Transmission and Distribution Fault Detection Market
Transmission and Distribution
Global Industrial Distribution Market
Transmission and Distribution
Transmission Housing Demand Market
Transmission and Distribution
Africa High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Virtual Pipeline Market
Transmission and Distribution
Transmission Line Market
Transmission and Distribution
Smart Fault Detection System for Power Transmission Market
Transmission and Distribution
Japan High Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Pantograph Disconnector Market