
 South Africa Data Center Physical Security Market | 2026-2036
South Africa Data Center Physical Security Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Data Center Physical Security Market Insights
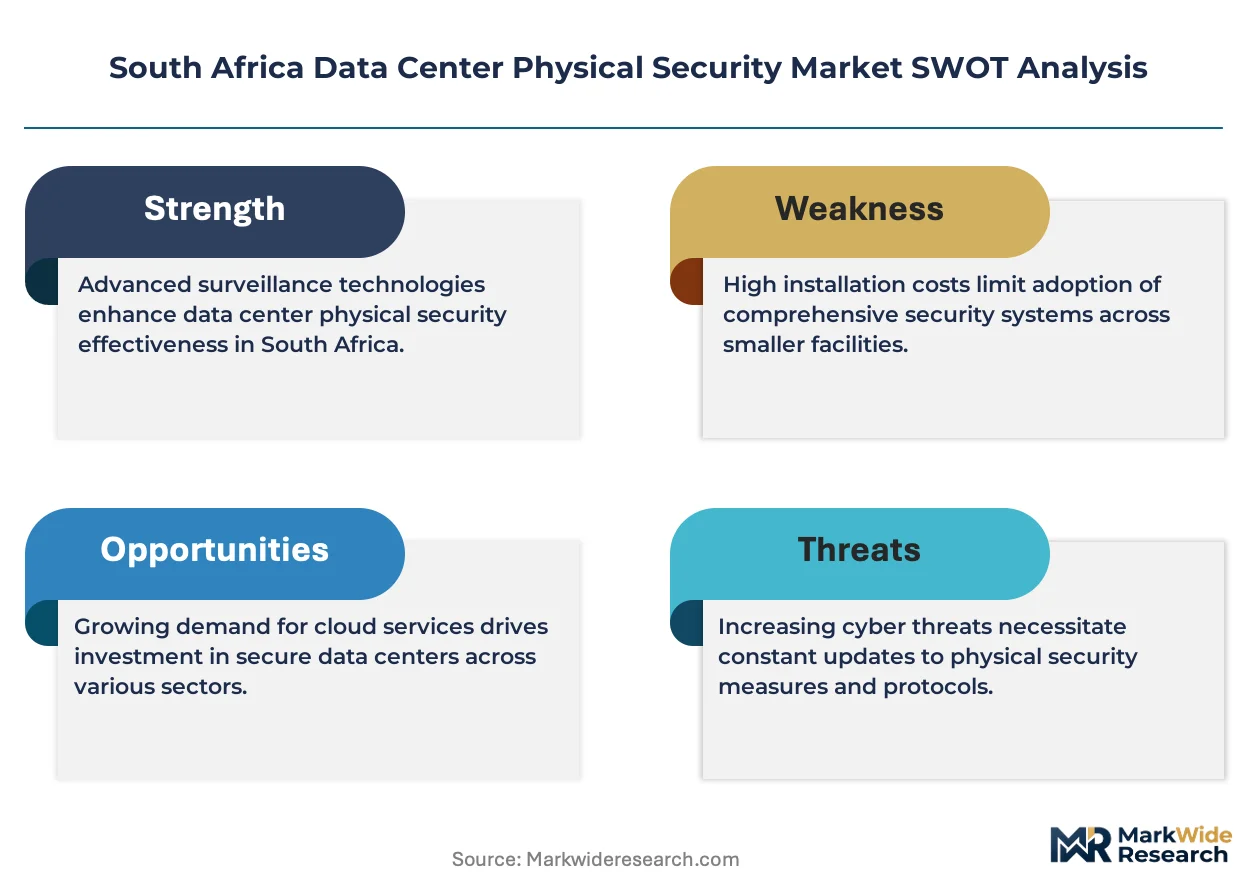
Edge computing architecture is rewriting physical security deployment patterns across South African data centers, pushing intelligence from central nodes to perimeter layers. Axis Communications AB leverages its video analytics portfolio to capture opportunities in this distributed model. Bosch Sicherheitssysteme GmbH anchors its position through deep integration of intrusion detection with building management systems. Siemens AG competes on the strength of its fire safety and access control convergence platforms.
South Africa data center physical security encompasses layered protection systems combining biometric authentication, video surveillance, intrusion detection, and environmental monitoring to safeguard critical infrastructure against unauthorized access, theft, and operational disruption. These systems typically operate across perimeter, building, and rack-level zones with response times measured in milliseconds for high-availability facilities. Surveillance systems dominate current expenditure as operators retrofit analog infrastructure with IP-based video analytics capable of behavioral recognition. Access control represents the fastest-expanding segment, driven by financial institutions mandating multi-factor biometric authentication for colocation facilities. Cloud providers concentrate procurement in hybrid installation models that blend onsite hardware with remote monitoring centers.
South Africa's national regulator for information protection enforces strict data handling protocols for surveillance footage, compelling vendors to certify local data residency capabilities. The country's central electrical authority mandates redundant power backup standards that directly shape environmental monitoring and fire suppression system specifications. Stakeholders must evaluate how evolving cybersecurity-physical security convergence standards will reshape certification requirements and procurement criteria for integrated platform vendors.
Market Dynamics
Edge computing architecture is compressing physical security deployment timelines across South African data centers, forcing intelligence distribution from central nodes to perimeter layers and reshaping vendor procurement specifications.
Growth Catalysts
- Protection of Personal Information Act:South Africa's data protection framework mandates strict surveillance data residency protocols, compelling facility operators to upgrade to compliant biometric and video analytics platforms.
- Cloud provider facility expansion:Hyperscale operators are scaling Cape Town and Johannesburg campuses, generating concentrated demand for integrated physical security infrastructure.
- Financial institution colocation mandates:Banks and insurers operating in Gauteng province require multi-factor biometric authentication for critical infrastructure access, accelerating access control procurement cycles.
Market Restraints
- Import dependency for specialized components:Biometric sensors and advanced video analytics hardware rely heavily on foreign supply chains, exposing operators to currency volatility and extended lead times.
- Technical limitation in legacy analog retrofitting:Existing coaxial infrastructure in older Johannesburg facilities constrains seamless IP-based video analytics deployment without comprehensive cable replacement.
- Regulatory friction from overlapping compliance:South Africa's central electrical authority redundancy mandates for power backup systems create specification conflicts with fire suppression and environmental monitoring integration requirements.
Strategic Opportunities
- Underpenetrated Western Cape edge nodes:Secondary data center development in Cape Town's peripheral zones lacks mature physical security vendor presence, creating first-mover advantages for integrated platform providers.
- Cybersecurity-physical security convergence:Unified threat management platforms that correlate network intrusion alerts with physical access anomalies address unmet demand from financial services operators.
- Remote monitoring center partnerships:Hybrid installation models blending onsite hardware with centralized surveillance operations reduce capital barriers for mid-tier colocation providers in Durban and Port Elizabeth.
Industry Challenges
- Certified systems integration talent scarcity:Shortage of technicians qualified in both IP networking and physical access control installation compresses deployment timelines for multi-zone security rollouts.
- Legacy building management system incompatibility:Integration complexity with existing Siemens, Honeywell, or Johnson Controls HVAC and fire safety infrastructure extends commissioning periods and inflates project costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Data Center Physical Security Market |
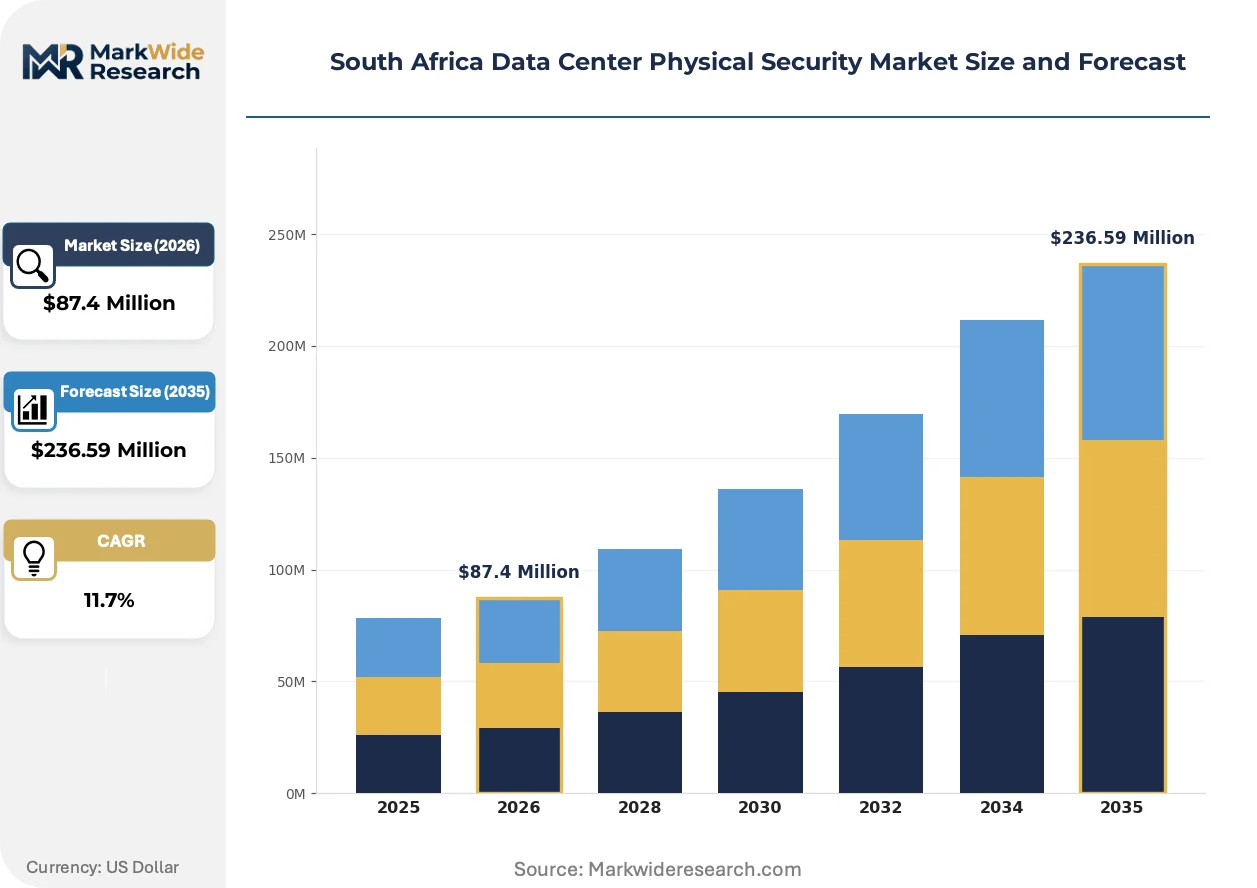
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $236.59 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution: Access Control, Surveillance Systems, Intrusion Detection, Fire Safety End User: Telecommunications, Financial Institutions, Cloud Providers, Healthcare Organizations Technology: Biometric Scanners, RFID, Video Analytics, Smart Locks Installation: Onsite, Offsite, Hybrid, Remote Monitoring |
| Companies Covered | Axis Communications AB, Bosch Sicherheitssysteme GmbH, Siemens AG, Assa Abloy AB, Johnson Controls International, Honeywell International, Cisco Systems, Schneider Electric SE, ABB Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Data Center Physical Security Market Trends and Innovations
Video analytics platforms are migrating processing workloads toward edge devices, compressing response latency and reducing backbone bandwidth requirements for real-time threat detection.
Software-defined perimeter controls are virtualizing access management functions that previously required dedicated hardware appliances. Financial institutions in Johannesburg are piloting these platforms for rack-level authentication, collapsing deployment costs while enabling granular audit trails. This architecture is virtualizing the traditional three-tier security hierarchy into distributed policy enforcement points.
South Africa's Protection of Personal Information Act enforcement is tightening consent and retention requirements for biometric data collection. The regulation compels vendors to architect local data residency capabilities and implement automated deletion workflows. Cloud providers operating Cape Town facilities are accelerating compliance certification timelines to maintain procurement eligibility.
Facility operators are unbundling after-sales service contracts from initial hardware procurement, favoring multi-vendor maintenance agreements with defined response time guarantees. Mid-tier colocation providers in Gauteng province are driving this shift, replacing single-source service dependencies with competitive third-party technical support arrangements. This purchasing pattern is most pronounced among telecom operators consolidating distributed infrastructure portfolios.
South Africa Data Center Physical Security Market Segmentation
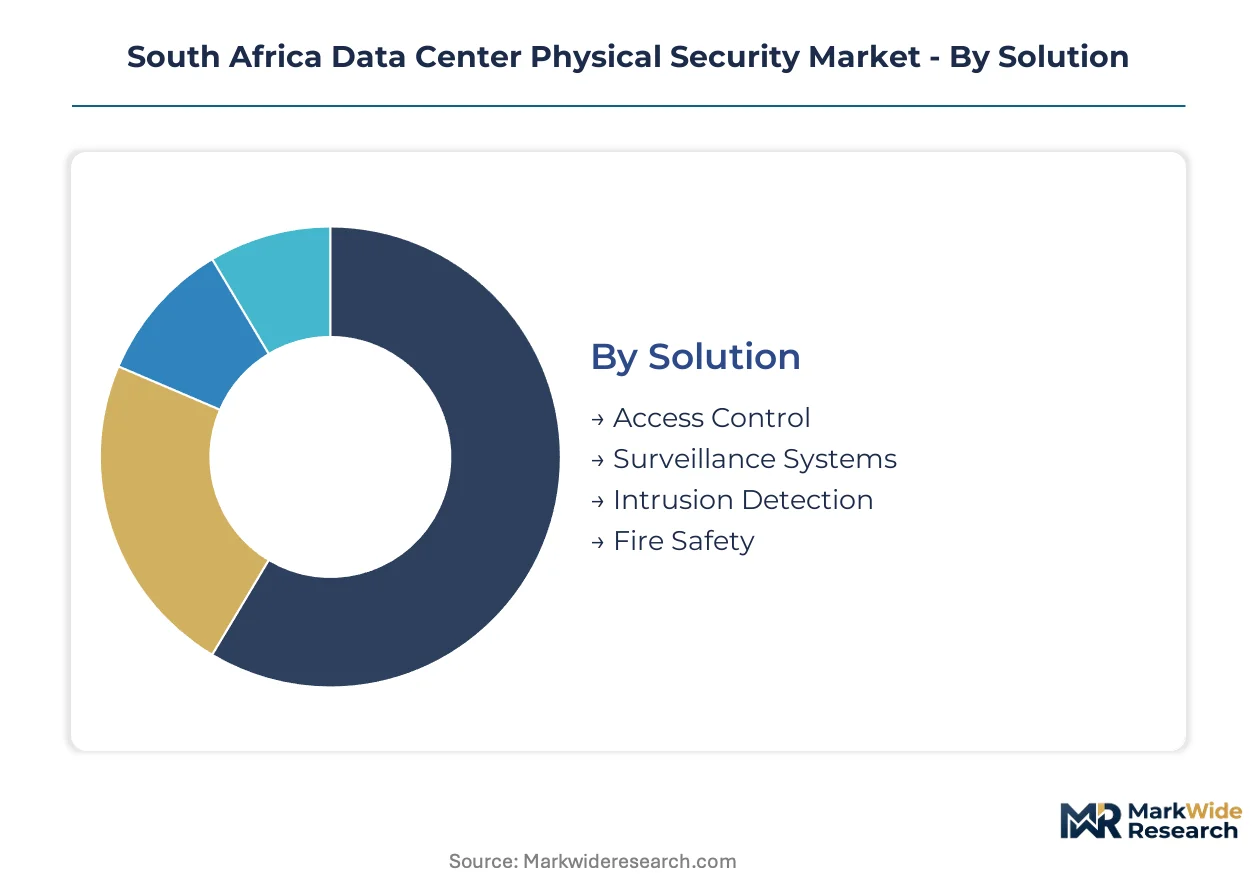
Segmentation reveals how procurement priorities diverge across South African data center operators. Facility scale, regulatory exposure, and integration complexity drive distinct vendor selection patterns.
Solution:
After-sales service intensity varies sharply across solution categories, with surveillance systems demanding continuous calibration while fire safety requires mandatory inspection protocols.
- Access Control:Multi-factor biometric authentication systems govern entry across perimeter, building, and rack-level zones. Financial institutions in Gauteng province mandate these systems for colocation facilities, compressing procurement cycles as banks consolidate infrastructure portfolios.
- Surveillance Systems:IP-based video analytics platforms with behavioral recognition capabilities replace legacy analog infrastructure. Cloud providers scaling Cape Town and Johannesburg campuses drive retrofit demand, though coaxial cable replacement in older facilities extends deployment timelines.
- Intrusion Detection:Perimeter sensors and motion detection arrays integrate with building management systems for unified threat response.
- Fire Safety:Suppression systems must satisfy central electrical authority redundancy mandates alongside environmental monitoring specifications.
Surveillance Systems holds the largest share; momentum sits with Access Control.
End User:
Cost tier stratification separates hyperscale cloud deployments from mid-tier colocation operators, with financial institutions occupying the premium integration segment.
- Telecommunications:Operators consolidating distributed infrastructure across Gauteng, Durban, and Port Elizabeth favor multi-vendor maintenance agreements over single-source service dependencies. Unbundled after-sales contracts reduce capital barriers for facility upgrades.
- Financial Institutions:Banks and insurers require multi-factor biometric authentication with granular audit trails for regulatory compliance. Johannesburg operators pilot software-defined perimeter controls for rack-level authentication, collapsing deployment costs while tightening security governance.
- Cloud Providers:Hyperscale operators concentrate procurement in hybrid installation models blending onsite hardware with remote monitoring centers.
- Healthcare Organizations:Rising demand for compliant patient data protection drives physical security investment in medical data centers.
Telecommunications holds the largest share; Healthcare Organizations are expanding most quickly.
Technology:
Application maturity separates biometric scanners and video analytics, which command premium pricing, from RFID and smart locks in commoditized deployment tiers.
- Biometric Scanners:Fingerprint, iris, and facial recognition systems process authentication at edge devices to compress response latency. Protection of Personal Information Act enforcement compels vendors to architect local data residency capabilities and automated deletion workflows.
- Video Analytics:Edge-deployed processing reduces backbone bandwidth requirements for real-time threat detection. Behavioral recognition algorithms migrate workloads from central servers to perimeter layers, aligning with distributed security architecture trends.
- RFID:Contactless credential systems support high-throughput access in large-scale facilities.
- Smart Locks:Network-connected locking mechanisms enable remote credential management and audit logging.
Video Analytics holds the largest share; Biometric Scanners are climbing the fastest.
Installation:
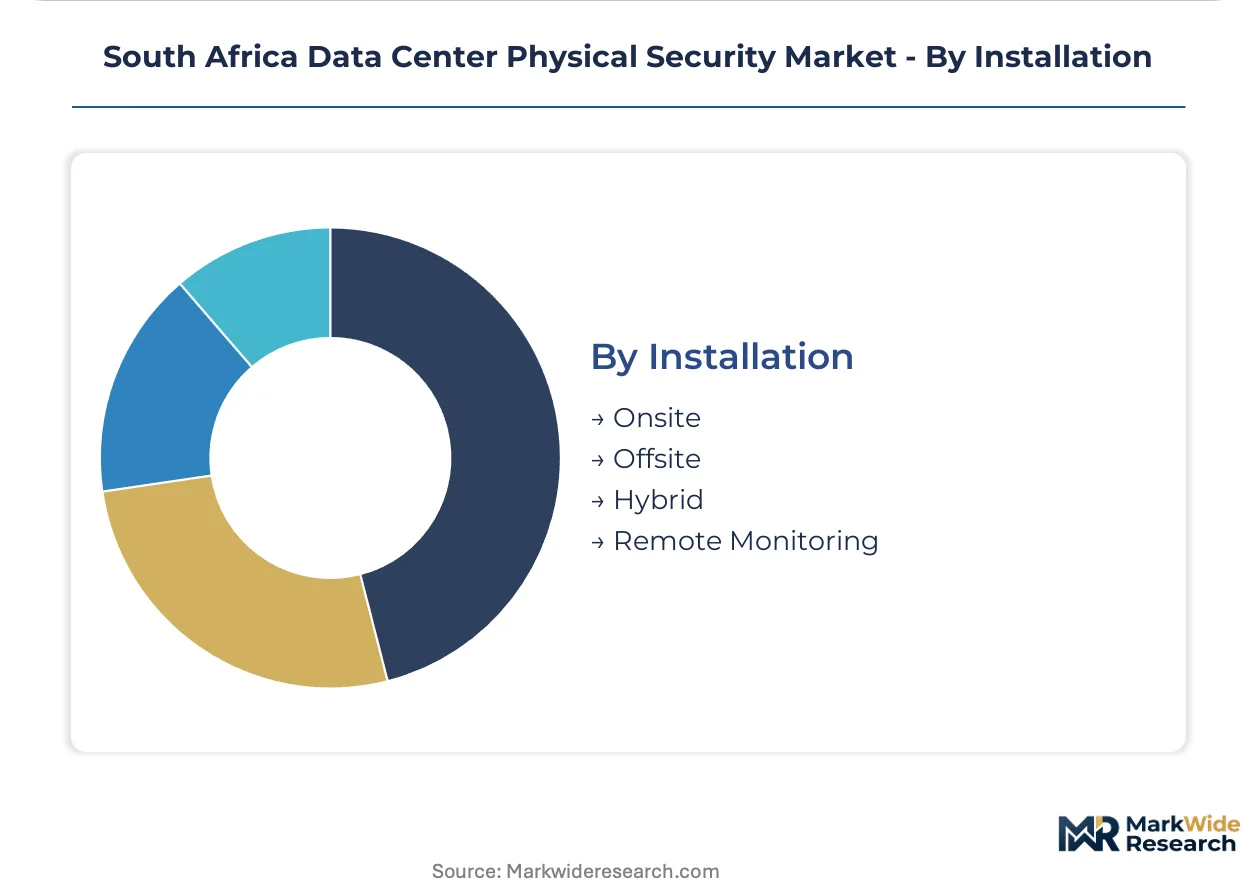
Volume concentration favors hybrid models, while pure offsite and remote monitoring configurations serve cost-constrained operators in secondary markets.
- Onsite:Dedicated hardware appliances deployed within facility premises deliver lowest-latency threat response for high-availability operations.
- Offsite:Centralized processing infrastructure reduces capital expenditure but introduces dependency on telecommunications backbone reliability.
- Hybrid:Blended architectures combine local edge processing with remote monitoring center oversight. Cloud providers and financial institutions prefer this model for operational resilience.
- Remote Monitoring:Third-party surveillance operations enable mid-tier colocation providers in Durban and Port Elizabeth to access enterprise-grade security capabilities without captive technical staffing.
Hybrid holds the largest share; Remote Monitoring is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Financial institutions and cloud hyperscalers dominate procurement across South Africa's data center corridors, concentrating demand in Gauteng province and Western Cape edge zones where regulatory compliance and latency requirements intersect.
Gauteng Province
Johannesburg and Pretoria host the densest concentration of financial services data centers, driving multi-factor biometric authentication mandates. The Protection of Personal Information Act enforces strict surveillance data residency protocols for facilities processing banking transactions. The Midrand corridor sees accelerated colocation buildouts as telecom operators consolidate distributed infrastructure portfolios.
Western Cape
Cape Town's emerging edge nodes attract cloud provider facility expansion with underpenetrated physical security vendor presence. The national regulator for information protection requires automated deletion workflows for biometric data collected at these secondary sites. Stellenbosch and Paarl peripheral zones present first-mover opportunities for integrated platform providers establishing local technical support.
KwaZulu-Natal
Durban's port-adjacent data centers serve maritime logistics and regional banking back-office operations with hybrid installation preferences. The central electrical authority mandates redundant power backup standards that shape environmental monitoring and fire suppression specifications. Umhlanga's emerging tech cluster favors remote monitoring center partnerships to reduce capital barriers.
Eastern Cape
Port Elizabeth's mid-tier colocation providers unbundle after-sales service contracts from initial hardware procurement. The country's data protection framework compels vendors to certify local data residency capabilities for surveillance footage handling. The Gqeberha industrial zone experiences procurement compression as operators retrofit legacy analog infrastructure with IP-based video analytics.
South Africa Data Center Physical Security Market Competitive Landscape
Channel-controlling players compete with product-specialist players across South Africa's data center physical security market, creating a tiered structure where integrated platform vendors capture premium contracts while component specialists serve retrofit segments. The vendor landscape separates into three strategic archetypes: Nordic-origin video analytics specialists, German-engineered building systems integrators, and diversified industrial conglomerates with fire safety convergence platforms. Competitive moves concentrate on cybersecurity-physical security convergence partnerships and certified systems integration talent acquisition.
Among Nordic-origin video analytics specialists, Axis Communications AB and Assa Abloy AB exemplify the edge-computing deployment model compressing intelligence toward perimeter layers. Bosch Sicherheitssysteme GmbH anchors the German-engineered tier through deep building management system integration. These three occupy positions where regulatory compliance capabilities and local data residency architecture determine procurement eligibility for financial institution and cloud provider contracts.
| Leading Market Players |
|---|
| Axis Communications AB |
| Bosch Sicherheitssysteme GmbH |
| Siemens AG |
| Assa Abloy AB |
| Johnson Controls International |
| Honeywell International |
| Cisco Systems |
| Schneider Electric SE |
| ABB Ltd |
| Others |
Pricing and Supply Chain Analysis
Chinese-manufactured biometric sensors and video analytics chipsets concentrate upstream supply, anchoring margin pools in certified systems integration and local data residency architecture rather than hardware procurement. This concentration forces South African facility operators to absorb currency volatility while competing on compliance certification and response-time guarantees.
Pricing Analysis
Cost-plus contracts with rand-dollar indexation dominate procurement for biometric hardware and advanced video analytics platforms. Three-tier pricing structure across premium, standard, and economy levels separates financial institution mandates from mid-tier colocation budgets, with certification grade and after-sales service bundling as primary differentiation drivers. Pricing pressure stems from unbundled maintenance agreements as telecom operators consolidate infrastructure portfolios. Mid-tier colocation providers in Durban and Port Elizabeth exhibit highest price sensitivity; cloud hyperscalers in Gauteng province demonstrate lowest sensitivity due to compliance-driven procurement mandates.
Supply Chain Analysis
Export-control regimes restricting advanced video analytics processors and biometric algorithm IP limit flows from the United States, China, and Germany into South African assembly channels. Component dependencies center on CMOS image sensors, edge-computing processors, and multi-factor authentication modules. Single-source vulnerability concentrates in specialized facial recognition chipsets subject to foreign technology licensing restrictions. Distribution runs through Johannesburg-based systems integrators with certified installation capabilities, extending to Cape Town and Durban through regional technical partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as edge computing architecture displaces centralized security models, creating niches for perimeter-focused specialists and cybersecurity-physical security convergence platforms.
For Market Incumbents: Pre-empt margin erosion from unbundled service contracts by deepening captive maintenance capabilities in Gauteng province. Acquire certified systems integration talent pools to compress deployment timelines threatened by IP networking and physical access control skill scarcity. Anchor position through vertical integration into remote monitoring center operations serving mid-tier colocation providers. For New Entrants and Emerging Players: Establish a beachhead in Western Cape edge nodes where cloud provider facility expansion outpaces mature vendor presence. Target Stellenbosch and Paarl peripheral zones with hybrid installation models blending local edge processing with centralized oversight. Lead with cybersecurity-physical security convergence platforms addressing unmet financial services demand for unified threat management. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed building systems integrators holding Siemens, Honeywell, and Johnson Controls certification relationships. Long-term viability hinges on regulatory compliance capabilities and local data residency architecture rather than hardware market share. Watch Protection of Personal Information Act enforcement timelines as inflection indicator for platform consolidation urgency.| Strategic Initiative | Industry Significance |
|---|---|
| Local Data Residency Certification | Protection of Personal Information Act mandates compel vendors to architect compliant biometric data handling capabilities. |
| Remote Monitoring Center Partnership | Hybrid installation models reduce capital barriers for mid-tier colocation providers in Durban and Port Elizabeth. |
| Edge Analytics Platform Launch | Video analytics workloads migrating to perimeter layers compress response latency for Cape Town cloud facilities. |
| Cybersecurity-Physical Security Integration | Unified threat management platforms correlate network intrusion alerts with physical access anomalies for Johannesburg banks. |
| Certified Systems Integration Acquisition | Technician scarcity in IP networking and physical access control compresses deployment timelines for multi-zone rollouts. |
Research Methodology
Desk research of trade customs records, central electrical authority filings, and data protection regulatory guidance preceded structured interviews with data center operations directors, physical security procurement managers, systems integration firm executives, and cloud provider facility planners. Primary fieldwork captured deployment timelines, compliance certification requirements, and vendor selection criteria across Gauteng, Western Cape, KwaZulu-Natal, and Eastern Cape provinces. Secondary validation drew from Protection of Personal Information Act enforcement notices, hyperscaler capex disclosures, and building management system integration case studies. Bottom-up facility-level capacity estimates triangulated against top-down solution category expenditure projections.
Assumptions held fixed include Protection of Personal Information Act enforcement intensity, central electrical authority redundancy mandates, and cloud provider Cape Town-Johannesburg expansion commitments; variables stress-tested include currency volatility, import tariff regimes, and legacy analog retrofitting penetration rates. Segmentation modeling spanned solution type, end-user industry, technology tier, and installation architecture across the projection horizon. CAGRs derived from facility buildout pipelines, procurement cycle compression patterns, and regulatory compliance investment trajectories. Edge computing adoption curves and biometric authentication mandate expansion served as primary forecast inputs.
Stress conditions across rand-dollar exchange rate bands, import lead time scenarios, and certified technician availability were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory enforcement timelines and hyperscaler facility commissioning schedules. Material shifts in Protection of Personal Information Act deletion workflow requirements or central electrical authority fire suppression integration specifications would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Singapore Data Center Server Market
Data Center Infrastructure
Data Center Support Infrastructure Market
Data Center Infrastructure
Canada Data Center Server Market
Data Center Infrastructure
Data Center Solutions Market
Data Center Infrastructure
South America Data Center Server Market
Data Center Infrastructure
Data Center Rack Solutions Market
Data Center Infrastructure
Norway Data Center Networking Market
Data Center Infrastructure
UK Data Center Rack Market
Data Center Infrastructure
Vietnam Data Center Power Market
Data Center Infrastructure
US Data Center Construction Market
Data Center Infrastructure
Internet Data Center Market
Data Center Infrastructure
Asia-Pacific Data Center Market
Data Center Infrastructure
Hyper-Converged Systems Market
Data Center Infrastructure
Chile Data Center Rack Market
Data Center Infrastructure
Chicago Data Center Market
Data Center Infrastructure
North America Data Center Construction Market