
 New Zealand Data Center Market | 2026-2036
New Zealand Data Center Market Size, Share, and Industry Trends Forecast 2026-2036
New Zealand Data Center Market Insights
Multi-source infrastructure procurement is restructuring how New Zealand enterprises provision compute capacity. NEXTDC anchors the domestic colocation landscape with facilities across Auckland and Wellington. Amazon Web Services competes through its local AWS Region launched in 2024. Microsoft Corporation extends its footprint via Azure availability zones, targeting hybrid cloud workloads from government and financial clients.
A data center is a dedicated facility housing servers, storage systems, networking equipment, and power infrastructure, typically maintaining temperatures between 18°C and 27°C through precision cooling architectures, designed to deliver continuous compute, storage, and connectivity services to enterprise and consumer applications. Colocation and cloud services command the dominant revenue pools as enterprises shift capital expenditure to operational models. Disaster recovery services are gaining traction among BFSI end users responding to operational resilience mandates. Cooling systems represent a critical technology battleground given New Zealand's temperate climate advantages for free-air cooling deployment.
New Zealand's Commerce Commission oversees telecommunications infrastructure competition, while the National Environmental Standards for Telecommunication Facilities govern facility siting and emissions. The Privacy Act 2020 and proposed digital economy frameworks are shaping data sovereignty requirements that localize storage demand. Stakeholders must monitor regulatory evolution around carbon reporting obligations and renewable energy certification standards that will determine facility compliance costs and customer procurement criteria.
Market Dynamics
Multi-tenant colocation demand is fragmenting across Auckland and Wellington corridors as enterprises disaggregate primary compute from disaster recovery workloads, forcing facility operators to architect for latency-sensitive edge proximity rather than consolidated campus scale.
Growth Catalysts
- Privacy Act 2020 data sovereignty mandates:Localized storage requirements compel multinational SaaS providers to establish New Zealand-based infrastructure, generating captive demand for domestic colocation capacity.
- Financial services operational resilience frameworks:BFSI end users face mandatory disaster recovery testing intervals, driving secondary site procurement across geographically separated facilities.
- Free-air cooling deployment:Temperate maritime climates enable economizer-dominant cooling architectures that compress operational expenditure versus mechanical refrigeration-dependent markets.
Market Restraints
- Transmission grid interconnection queues:Transpower New Zealand's connection approval timelines extend facility energization schedules, constraining supply response velocity to demand signals.
- Specialized electrical contractor scarcity:Medium-voltage switchgear commissioning expertise concentrates among Auckland-based trades, limiting simultaneous project execution capacity.
- Land use zoning friction:District plan amendments under the Resource Management Act create siting uncertainty for hyperscale campus developments outside established industrial precincts.
Strategic Opportunities
- Christchurch corridor underpenetration:South Island commercial density lacks proportional data center supply, creating first-mover positioning for seismic-resilient facility investment.
- Liquid cooling convergence with high-density AI training:Direct-to-chip thermal management integration enables GPU cluster hosting that air-cooled legacy facilities cannot accommodate.
- Renewable energy certification differentiation:Certified renewable power purchasing agreements command procurement preference from sustainability-mandated enterprise buyers.
Industry Challenges
- Critical facilities engineering talent pipeline:Datacenter-specific mechanical and electrical design expertise requires decade-long cultivation, constraining owner-operator expansion velocity.
- Legacy enterprise workload migration complexity:Mainframe-dependent government agencies face multi-year refactoring timelines that delay cloud-adjacent colocation adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | New Zealand Data Center Market |
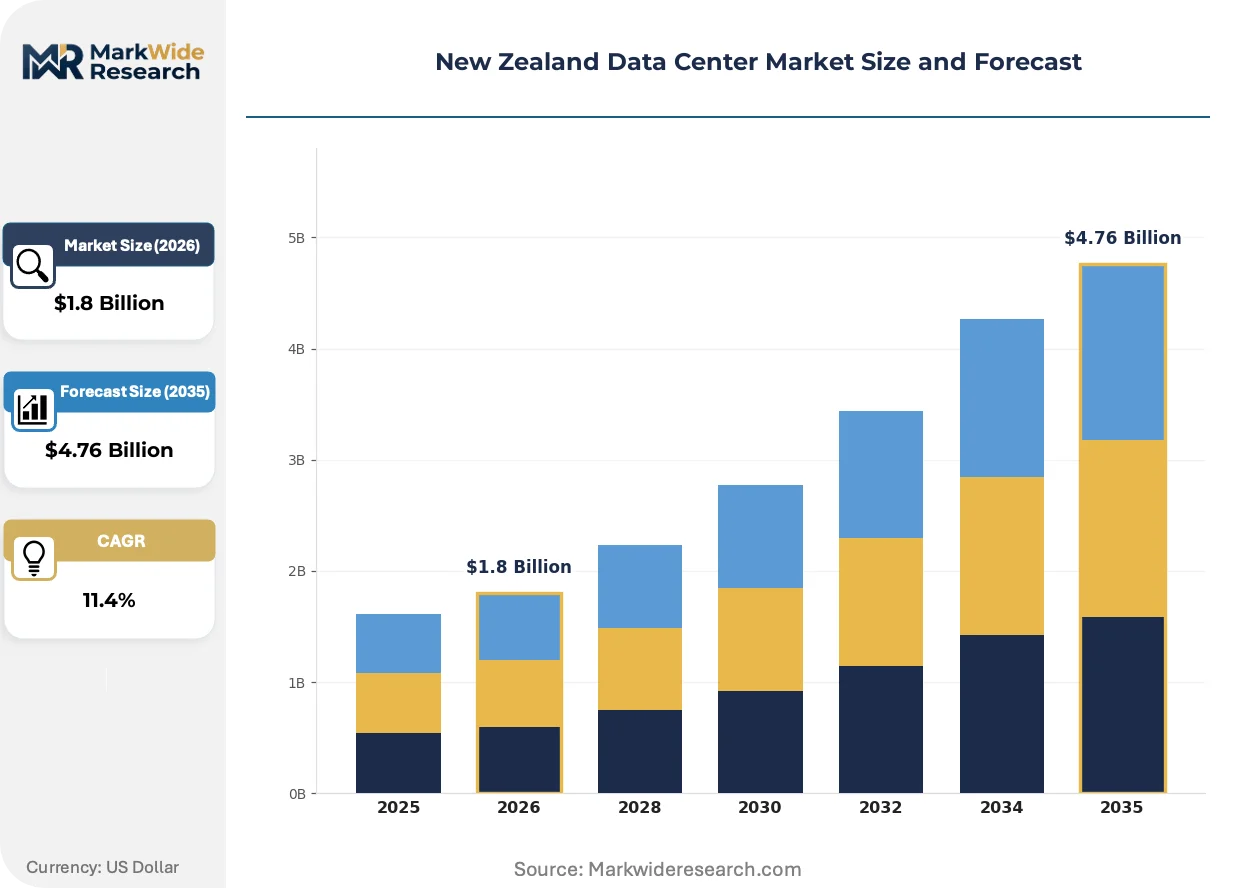
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
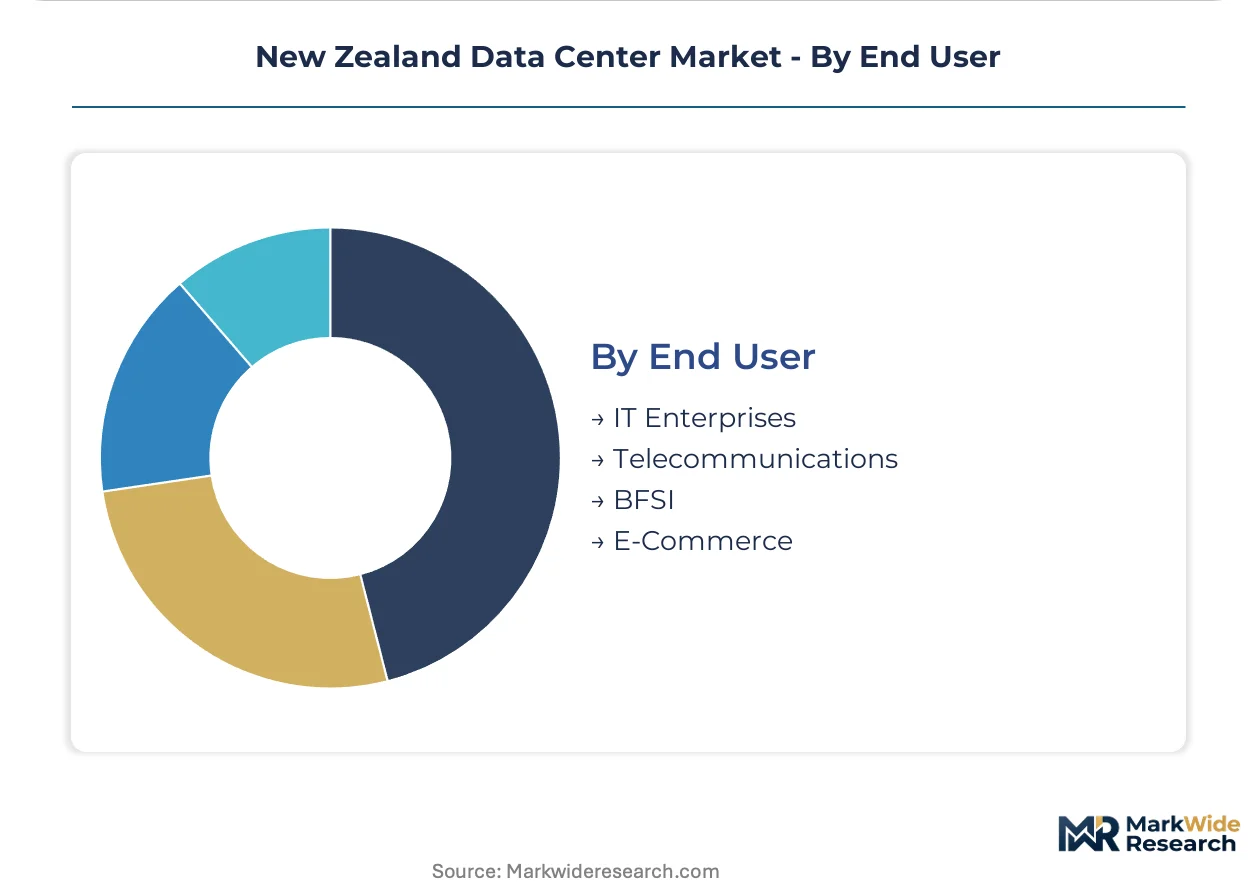
| Segmentation | Product Type: Colocation, Managed Hosting, Cloud Services, Hybrid Solutions Service Type: Infrastructure as a Service, Platform as a Service, Software as a Service, Disaster Recovery Technology: Virtualization, Cooling Systems, Networking Solutions, Security Tools End User: IT Enterprises, Telecommunications, BFSI, E-Commerce |
| Companies Covered | NEXTDC, CDC Data Centres, Amazon Web Services, Spark, DCI Data Centers, Microsoft Corporation, Datacom, DataVault, Google LLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
New Zealand Data Center Market Trends and Innovations
Prefabricated infrastructure delivery is compressing facility deployment timelines from traditional stick-built construction, while regulatory pressure on embodied carbon intensifies material selection scrutiny across the supply chain.
Containerized and skid-mounted power and cooling modules are modularizing data center infrastructure deployment. Hyperscale cloud operators and wholesale colocation providers specify factory-integrated electrical and mechanical packages that compress on-site construction duration. This industrialized approach is modularizing competitive positioning around speed-to-market rather than engineering customization.
New Zealand's updated National Environmental Standards for Telecommunication Facilities streamline consent pathways for low-impact facilities while tightening emissions disclosure for large-scale deployments. The Commerce Commission's infrastructure competition oversight now extends to data center interconnection pricing transparency. Facility operators are responding by pre-certifying campus expansions under permitted activity rules to accelerate subsequent capacity additions.
Enterprise buyers are consolidating vendor relationships around integrated colocation-network-security bundles that disaggregate traditional telecommunications procurement. Financial services and government agencies now specify cross-connected dual-facility architectures as standard requirements. This specification compression is most visible in Wellington, where proximity to parliamentary and regulatory institutions concentrates procurement decision-making authority.
New Zealand Data Center Market Segmentation
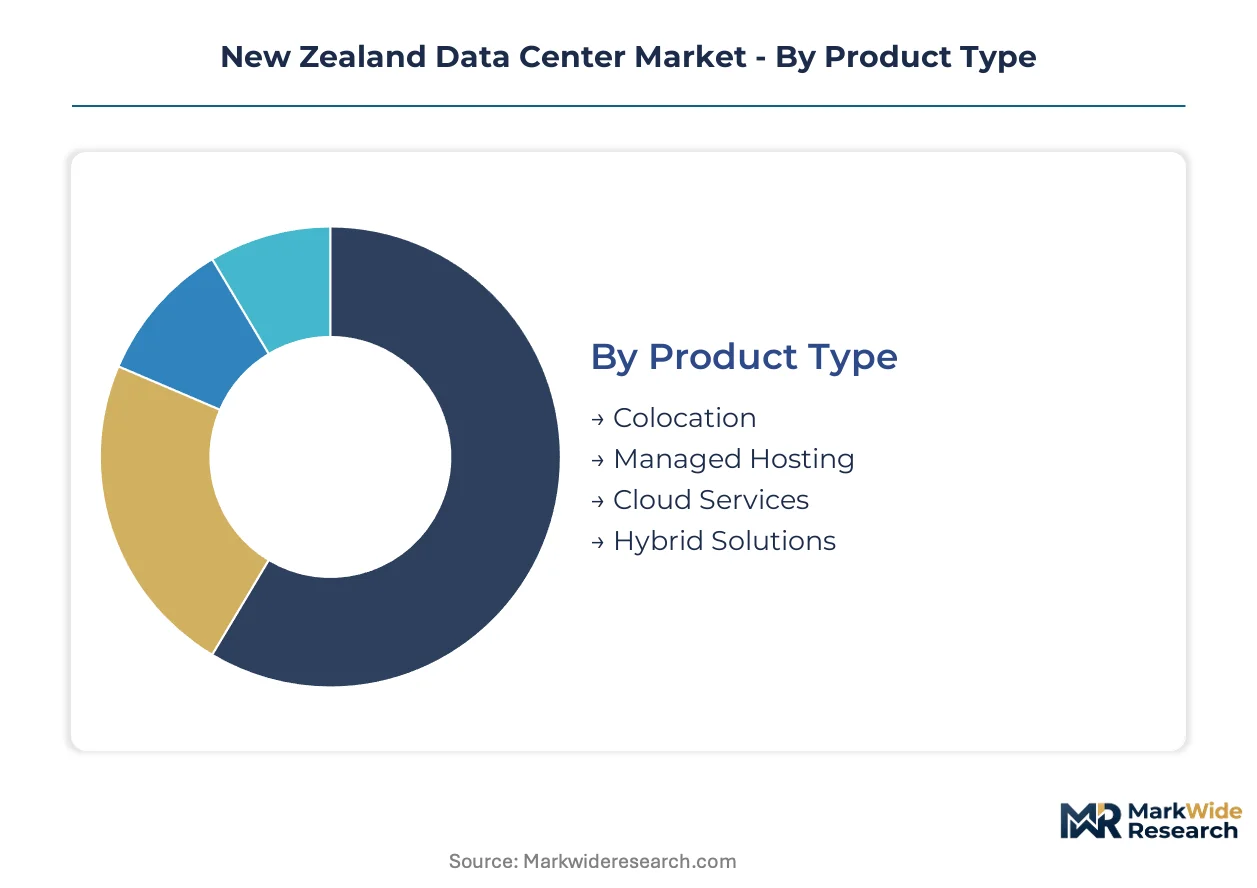
Segmentation in the New Zealand data center market reveals how procurement patterns diverge across operational models, technology stacks, and compliance requirements. Understanding these divides clarifies where facility operators must architect specialized capabilities versus standardized commodity offerings.
Product Type:
Standardized rack-density contracts dominate at the commodity end, while fully customized cage deployments anchor the premium tier with tailored power densities and cross-connect architectures.
- Colocation:Physical rack, cage, and suite leasing arrangements where enterprises retain hardware ownership while outsourcing facility infrastructure. Demand concentrates among Auckland-based financial services firms seeking proximity to NZX clearing infrastructure and latency-sensitive trading connectivity.
- Managed Hosting:Operator-owned server deployment with full hardware lifecycle management included in recurring fees. Wellington government agencies favor this model to satisfy Public Service Commission security accreditation requirements without capital procurement cycles.
- Cloud Services:On-demand compute and storage provisioning through hyperscale platforms with consumption-based billing.
- Hybrid Solutions:Integrated colocation-cloud orchestration enabling workload portability between on-premises and public cloud environments.
Most installed capacity flows through Colocation. Expansion is steepest in Hybrid Solutions.
Service Type:
Recurring revenue stability increases as services climb the stack from raw infrastructure toward application-layer subscriptions, with disaster recovery commanding premium pricing for guaranteed recovery time objectives.
- Infrastructure as a Service:Fundamental compute, storage, and networking resources delivered as metered utilities. Canterbury-based agricultural technology startups leverage IaaS for seasonal processing bursts without year-round hardware commitments.
- Platform as a Service:Application development and deployment environments abstracting underlying infrastructure management. Auckland software vendors targeting Australian expansion use PaaS to maintain development velocity without dual-territory facility investment.
- Software as a Service:End-user application delivery through browser-based interfaces with zero local infrastructure requirements.
- Disaster Recovery:Replicated infrastructure and automated failover orchestration ensuring business continuity during primary site outages.
Revenue concentration sits with Infrastructure as a Service. Disaster Recovery is climbing the fastest as BFSI operational resilience mandates tighten.
Technology:
Capital intensity peaks at the mechanical layer where cooling innovation determines facility competitiveness, while software-defined layers enable faster refresh cycles and vendor substitution.
- Virtualization:Hypervisor-based server abstraction maximizing hardware utilization through multi-tenant workload consolidation. Hamilton manufacturing enterprises deploy virtualization to consolidate legacy plant-floor systems onto modern infrastructure without application rewrites.
- Cooling Systems:Precision air handling, liquid cooling, and free-air economizer architectures maintaining thermal envelopes for high-density compute. Tauranga facilities exploit coastal maritime climate conditions to minimize mechanical refrigeration dependency and compress operational expenditure.
- Networking Solutions:Software-defined networking, spine-leaf architectures, and cross-facility interconnect fabrics.
- Security Tools:Physical access control, network segmentation, encryption key management, and threat detection platforms.
Deployment volume concentrates in Virtualization. Cooling Systems are gaining share fastest as GPU cluster densities exceed air-cooled thresholds.
End User:
Procurement sophistication varies sharply across verticals, with regulated industries demanding contractual audit rights and sovereign data guarantees that consumer-facing sectors rarely specify.
- IT Enterprises:Technology companies and software vendors requiring scalable compute for product development and customer-facing service delivery. Christchurch SaaS providers prioritize seismic-resilient secondary sites to maintain service continuity through South Island fault line risks.
- Telecommunications:Mobile network operators and fixed-line carriers hosting subscriber data, billing systems, and network function virtualization infrastructure.
- BFSI:Banks, insurers, and payment processors governed by Reserve Bank of New Zealand operational resilience standards and APRA cross-border recognition frameworks.
- E-Commerce:Online retailers and marketplace platforms with spiky traffic patterns around seasonal consumption events.
Contract value concentrates with BFSI. E-Commerce is expanding most quickly as direct-to-consumer digital channels displace traditional retail distribution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Auckland's metropolitan corridor concentrates New Zealand data center demand through proximity to financial exchanges, submarine cable landing stations, and enterprise headquarters clusters.
Auckland Metropolitan Area
Financial services firms and telecommunications carriers anchor colocation demand in Auckland's central business district and industrial periphery. The National Environmental Standards for Telecommunication Facilities streamline consent processes for low-impact facilities under permitted activity rules. Albany and Mount Wellington industrial precincts host the majority of operational hyperscale and enterprise-grade facilities.
Wellington Corridor
Government agencies and regulatory institutions drive managed hosting procurement with stringent security accreditation requirements. The Public Service Commission mandates specific infrastructure standards for crown entity data handling. Thorndon and Kaiwharawhara zones concentrate decision-making authority and dual-facility disaster recovery architectures.
Canterbury Region
Agricultural technology startups and SaaS providers seek seismic-resilient secondary sites for business continuity planning. The Christchurch City Council district plan amendments under the Resource Management Act create siting pathways for edge deployments. Rolleston and Christchurch Airport precincts emerge as preferred locations for disaster recovery workload placement.
Waikato Bay of Plenty
Manufacturing enterprises and logistics operators deploy virtualization infrastructure for plant-floor system consolidation. Regional council planning frameworks accommodate industrial data center zoning with reduced consent complexity. Tauranga's coastal maritime climate enables free-air cooling architectures that compress operational expenditure for high-density compute.
New Zealand Data Center Market Competitive Landscape
Global majors compete with regional champions across cloud platform availability, colocation footprint density, and sovereign data compliance capabilities. The New Zealand market exhibits tiered concentration with hyperscale cloud operators, domestic colocation specialists, and telecommunications-integrated providers occupying distinct competitive layers. Strategic archetypes include facility-first operators emphasizing physical infrastructure scale, platform-first competitors leveraging global cloud ecosystems, and network-anchored players bundling connectivity with compute. Capacity expansion and renewable energy certification differentiation represent the dominant competitive moves as sustainability mandates tighten procurement criteria.
Among Australia-anchored facility operators, NEXTDC and CDC Data Centres exemplify the regional champion archetype with trans-Tasman expansion strategies. Amazon Web Services occupies a position representing hyperscale cloud platform competition through its 2024 Auckland region launch. Microsoft Corporation sits within the enterprise hybrid cloud tier targeting government and financial services verticals.
| Leading Market Players |
|---|
| NEXTDC |
| CDC Data Centres |
| Amazon Web Services |
| Spark |
| DCI Data Centers |
| Microsoft Corporation |
| Datacom |
| DataVault |
| Google LLC |
| Others |
Pricing and Supply Chain Analysis
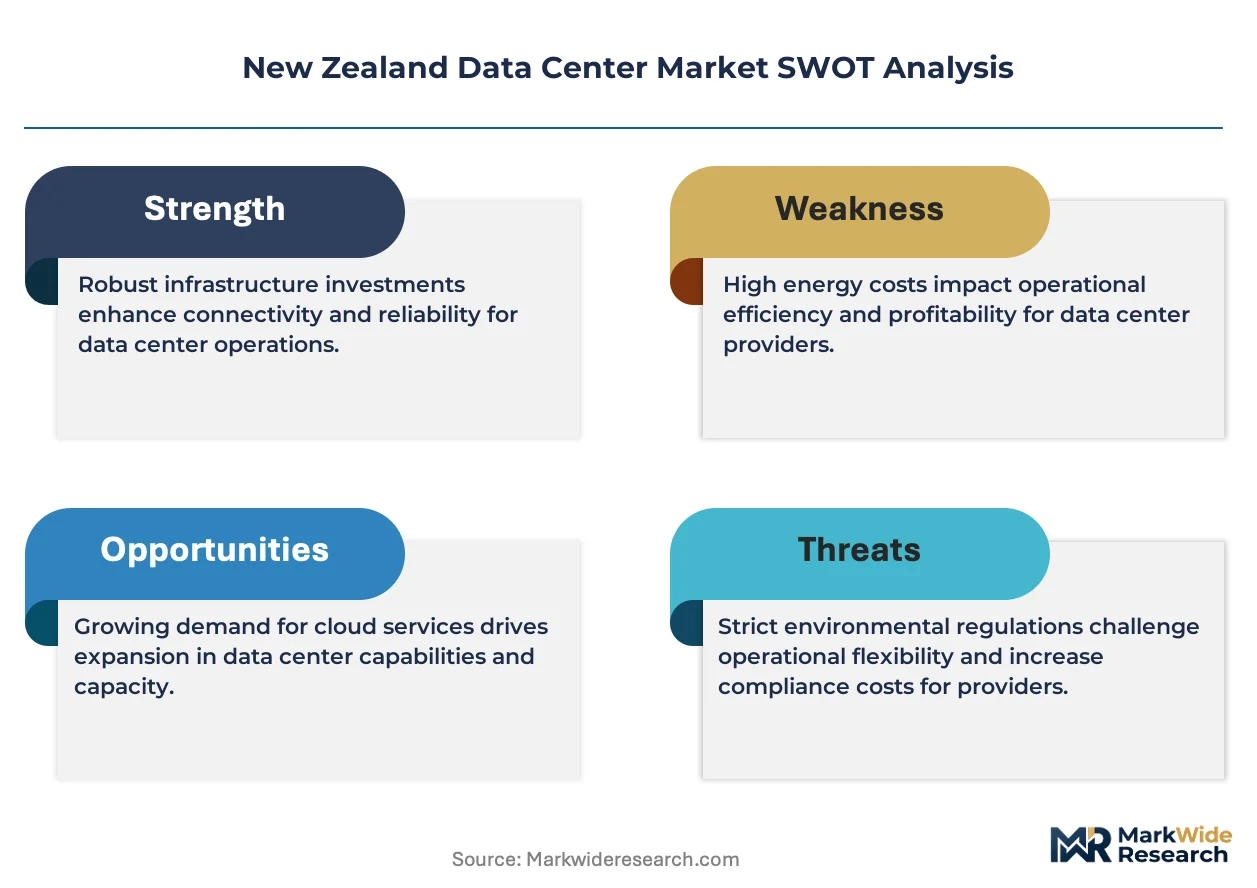
Backward integration into renewable energy generation anchors competitive positioning for New Zealand facility operators seeking to compress long-term operational expenditure while securing procurement preference from sustainability-mandated enterprise buyers. This vertical control over power sourcing simultaneously insulates against Transpower New Zealand grid interconnection queues and creates pricing leverage through certified renewable power purchasing agreement premiums.
Pricing Analysis
Input-cost pass-through from electricity spot markets and specialized electrical contractor scarcity shapes contract structures across the New Zealand data center landscape. Pricing stratifies across premium certified-renewable tiers, standard grid-connected baselines, and economy remote-facility options differentiated by latency performance and resilience certification. Cost compression in the economy tier is intensifying because hyperscale cloud operators are driving volume consolidation. Government agencies exhibit the lowest price sensitivity due to Public Service Commission security accreditation requirements, while agricultural technology startups demonstrate highest elasticity.
Supply Chain Analysis
Dual-sourcing requirements for medium-voltage switchgear and precision cooling modules are mandating multi-supplier qualification across New Zealand facility developments. Equipment sourcing draws from China for electrical infrastructure, Australia for mechanical systems, and the United States for networking hardware. Raw material dependencies span copper for busbar fabrication, aluminum for heat exchangers, and rare earth elements for uninterruptible power supply systems. Single-source vulnerability concentrates in Auckland-based specialized electrical contractor expertise. Distribution runs through direct manufacturer relationships for hyperscale deployments and distributor channels for mid-market colocation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
New Zealand data center demand functions as a regulatory compounder where Privacy Act 2020 data sovereignty mandates and Reserve Bank of New Zealand operational resilience standards generate structural procurement requirements that transcend cyclical IT spending patterns.
For Market Incumbents: Lock in long-term renewable energy certification differentiation through pre-emptive power purchasing agreements with Meridian Energy or Contact Energy to defend margin position against incoming hyperscale cloud price competition. Secure critical facilities engineering talent through apprenticeship pipelines with Auckland University of Technology to constrain competitor expansion velocity. For New Entrants and Emerging Players: Regional telecommunications carriers represent the most accessible channel partnership pathway for penetrating the Wellington government managed hosting segment where incumbent capacity constraints create white-space opportunity. Target Christchurch corridor underpenetration for seismic-resilient disaster recovery positioning, leveraging Rolleston industrial zoning pathways under amended district plans. For Investors and Strategic Acquirers: Roll-up economics work for Australia-anchored facility operators with trans-Tasman expansion capabilities because New Zealand's fragmented domestic colocation landscape lacks scale-efficient second-tier competitors. Monitor Transpower New Zealand grid interconnection queue clearance rates as the inflection signal for supply response velocity and competitive intensity.| Strategic Initiative | Industry Significance |
|---|---|
| Renewable Energy Certification Program | Certified power purchasing agreements from Meridian Energy satisfy Public Service Commission sustainability procurement criteria for crown entities. |
| Liquid Cooling Infrastructure Deployment | Direct-to-chip thermal management enables GPU cluster hosting that air-cooled legacy Auckland facilities cannot accommodate. |
| Christchurch Corridor Expansion | Seismic-resilient Rolleston facilities capture South Island disaster recovery demand from SaaS providers fault-line risk planning. |
| Prefabricated Modular Construction | Factory-integrated electrical and mechanical packages compress on-site construction duration against Transpower interconnection queue delays. |
| Dual-Facility Cross-Connection Architecture | Cross-connected Wellington-Thorndon and Kaiwharawhara sites satisfy BFSI mandatory disaster recovery testing interval requirements. |
Research Methodology
Multiple input streams — facility operator capacity disclosures, enterprise procurement manager interviews, and regulatory filing analysis — were reconciled through bottom-up and top-down triangulation. Primary discussions with data center engineering directors, cloud platform account executives, government ICT procurement officers, and financial services infrastructure leads were validated against secondary sources including Transpower New Zealand connection application records, Commerce Commission infrastructure competition filings, district plan amendment notices under the Resource Management Act, and hyperscaler capital expenditure disclosures.
Data-stream reconciliation anchored the analytical framework across the projection horizon, modeling demand segmentation by operational model, service tier, cooling technology, and end-user vertical. CAGRs were derived from facility pipeline tracking and enterprise workload migration velocity assessment. Industry-specific forecast inputs incorporated Privacy Act 2020 compliance timeline acceleration and Reserve Bank of New Zealand operational resilience framework implementation pacing.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Transpower grid interconnection approval timelines, specialized electrical contractor availability, and National Environmental Standards for Telecommunication Facilities evolution. Deviation in renewable energy certification standard adoption would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Data Center Containment Solution Market
Data Center Infrastructure
Japan Data Center Rack Market
Data Center Infrastructure
Sweden Data Center Power Market
Data Center Infrastructure
France Data Center Rack Market
Data Center Infrastructure
Multi-Tenant Data Center Market
Data Center Infrastructure
China Data Center Storage Market
Data Center Infrastructure
Australia Data Center Physical Security Market
Data Center Infrastructure
Data Center Colocation Market
Data Center Infrastructure
China Data Center Power Market
Data Center Infrastructure
Data Center Outsourcing and Infrastructure Utility Services Market
Data Center Infrastructure
Middle East Data Center Power Market
Data Center Infrastructure
Thailand Data Center Market
Data Center Infrastructure
Shanghai Data Center Market
Data Center Infrastructure
Hyperscale Data Center Market
Data Center Infrastructure
Converged Infrastructure Market
Data Center Infrastructure
Global Mega Data Center Market