
 London Data Center Market | 2026-2036
London Data Center Market Size, Share, and Industry Trends Forecast 2026-2036
London Data Center Market Insights
Hyperscale cloud buyers is bifurcating demand away from traditional enterprise tenants across Greater London. Equinix leverages its LD8-LD10 campus cluster to sustain interconnection density in the Docklands corridor. Digital Realty anchors wholesale capacity through its Powergate facility, while VIRTUS Data Centres competes on sovereign-cloud certification for UK public-sector workloads.
A data center constitutes a purpose-built facility housing compute, storage, and networking infrastructure with controlled temperature, humidity, and power redundancy measured in tiered uptime classifications; these installations enable continuous digital service delivery for enterprises and cloud providers. Colocation remains the dominant revenue architecture as enterprises shed owned assets, while edge deployments within micro data centers represent the fastest-expanding deployment category for latency-sensitive applications. Financial services end users command premium pricing for proximity hosting, whereas hybrid solutions capture margin pools from regulated clients requiring workload segregation.
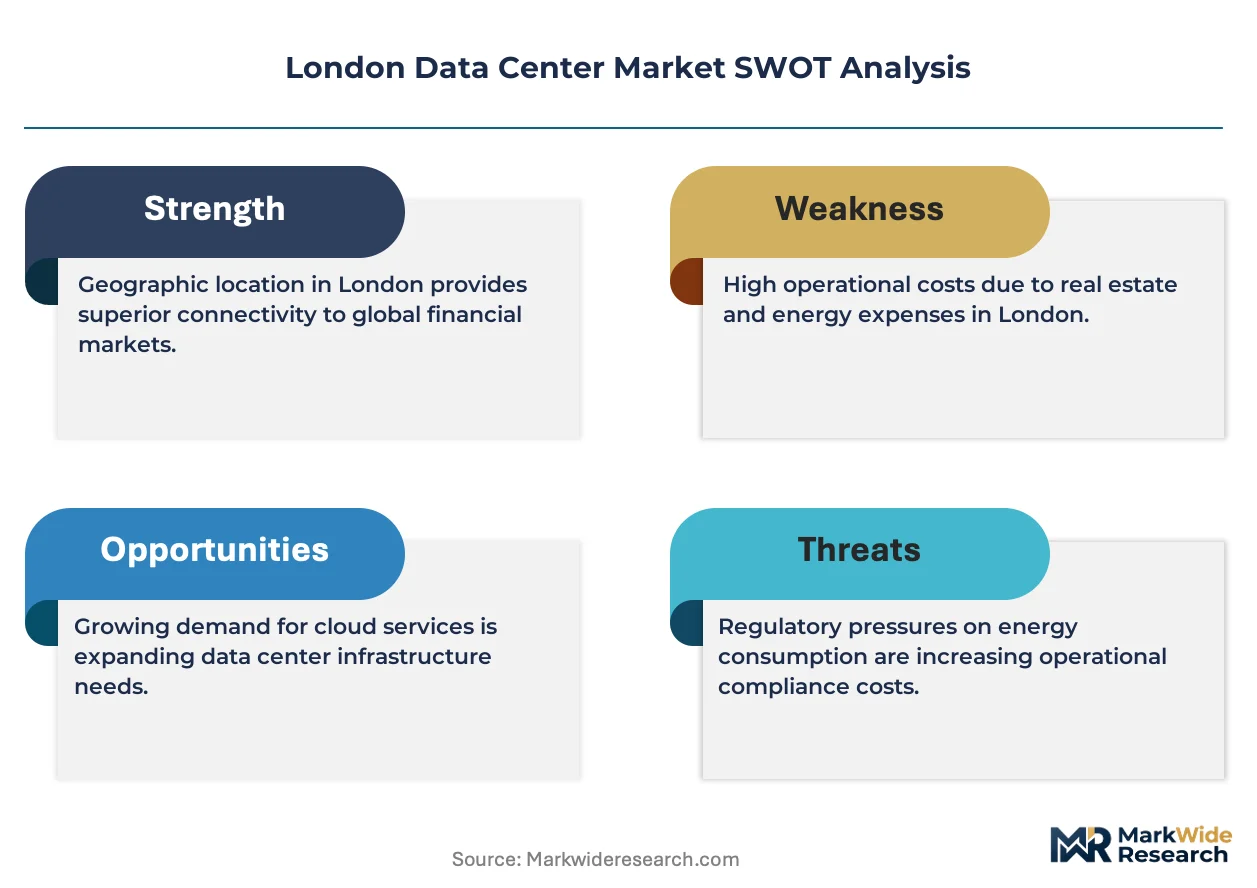
Ofcom governs telecommunications infrastructure access, Ofgem regulates power supply arrangements, and the UK Building Regulations impose Part L efficiency standards on new facility construction. These frameworks elevate compliance costs for operators while restricting greenfield development in power-constrained London boroughs. Stakeholders must weigh brownfield retrofit economics against peripheral greenfield sites as grid capacity and permitting timelines tighten across the capital.
Market Dynamics
Power density requirements from AI training clusters are compressing rack deployment timelines across Greater London, forcing operators to choose between liquid cooling retrofits and greenfield construction in peripheral zones.
Growth Catalysts
- Part L Building Regulations:The UK's net-zero efficiency standards are accelerating mechanical and engineering upgrades across legacy facilities, converting compliance pressure into modernization budgets.
- Latency arbitrage in financial services:High-frequency trading infrastructure demands sub-millisecond proximity to London's fiber exchanges, sustaining premium colocation pricing in Docklands and Slough.
- Liquid cooling:Direct-to-chip thermal management is enabling 50kW-plus rack densities that air-cooled legacy halls cannot support.
Market Restraints
- Grid capacity saturation:Central London boroughs face distribution network constraints that block new substation connections for 18-24 month lead times.
- Copper and electrical steel volatility:Transformer and busbar input costs swing with commodity markets, squeezing margin on fixed-price construction contracts.
- Permitting fragmentation:Ofcom infrastructure access rulings and local authority planning committees operate on misaligned timelines, extending approval cycles.
Strategic Opportunities
- Sovereign cloud certification:UK public-sector security clearances create a defensible niche for domestic operators against hyperscale incumbents.
- Edge micro data centers:5G network densification is pulling compute into Greater London's outer boroughs and Thames Valley corridor.
- Brownfield power reuse:Decommissioned industrial sites in Barking and Dagenham offer stranded grid capacity with faster energization than greenfield alternatives.
Industry Challenges
- Specialized mechanical contracting:Precision cooling and high-voltage electrical skills are concentrated among a small pool of certified technicians, inflating labor rates and project risk.
- Tier certification timelines:Uptime Institute audits for Tier III and IV classifications add 6-9 months to commissioning schedules, delaying revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | London Data Center Market |
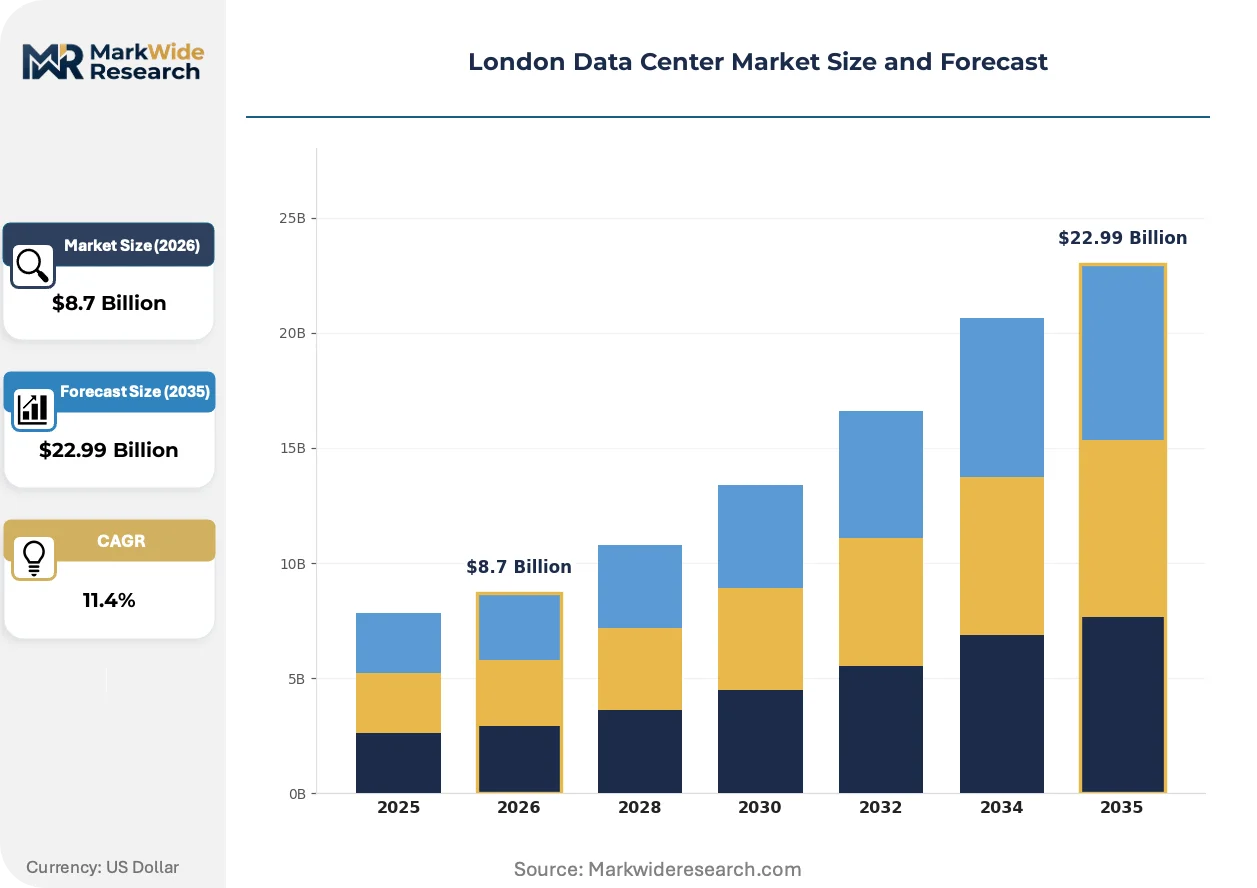
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Colocation, Managed Hosting, Cloud Services, Hybrid Solutions End User: Financial Services, Retail, Healthcare, Media & Entertainment Deployment: On-premises, Off-premises, Edge, Micro Data Centers Service Type: Infrastructure as a Service, Software as a Service, Disaster Recovery, Network Services |
| Companies Covered | Equinix, Digital Realty, VIRTUS Data Centres, Telehouse (KDDI), Ark Data Centres, Global Switch, CyrusOne, Kao Data, NTT Global Data Centers, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
London Data Center Market Trends and Innovations
Cooling architecture choices are splitting the London operator base into two camps with incompatible capital strategies and customer profiles.
Direct liquid cooling is bifurcating deployment economics across the capital's data center stock. The technology circulates dielectric fluid through cold plates mounted directly to processors, extracting heat more efficiently than raised-floor air systems. Hyperscale AI labs and quantitative trading firms are specifying liquid-cooled halls for new contracts, while enterprise colocation tenants remain anchored to conventional air-cooled infrastructure. This technical divergence is compressing residual values in legacy facilities that cannot accommodate retrofit piping and is forcing operators to segment their portfolios by thermal architecture rather than location alone.
Ofcom's wholesale fixed telecoms market review is reshaping interconnection economics in the Docklands corridor. The regulator's pricing controls on Openreach fiber access are lowering cross-connect costs for multi-tenant facilities. Wholesale data center operators serving financial services clients are expanding meet-me-room capacity to capture traffic aggregation benefits. Slough-based campuses with diverse fiber entry points are responding fastest, while single-carrier buildings face tenant churn toward better-connected alternatives.
Enterprise buyers are unbundling managed services from colocation contracts across Greater London. Legal and insurance sector tenants are separating infrastructure hosting from remote hands and smart-hands support, sourcing technical labor through specialized third-party engineering firms. This disintermediation compresses operator service margins while expanding addressable market for independent facilities management providers. The shift is most visible among mid-cap financial services firms in the City and Canary Wharf who previously accepted bundled premium pricing.
London Data Center Market Segmentation
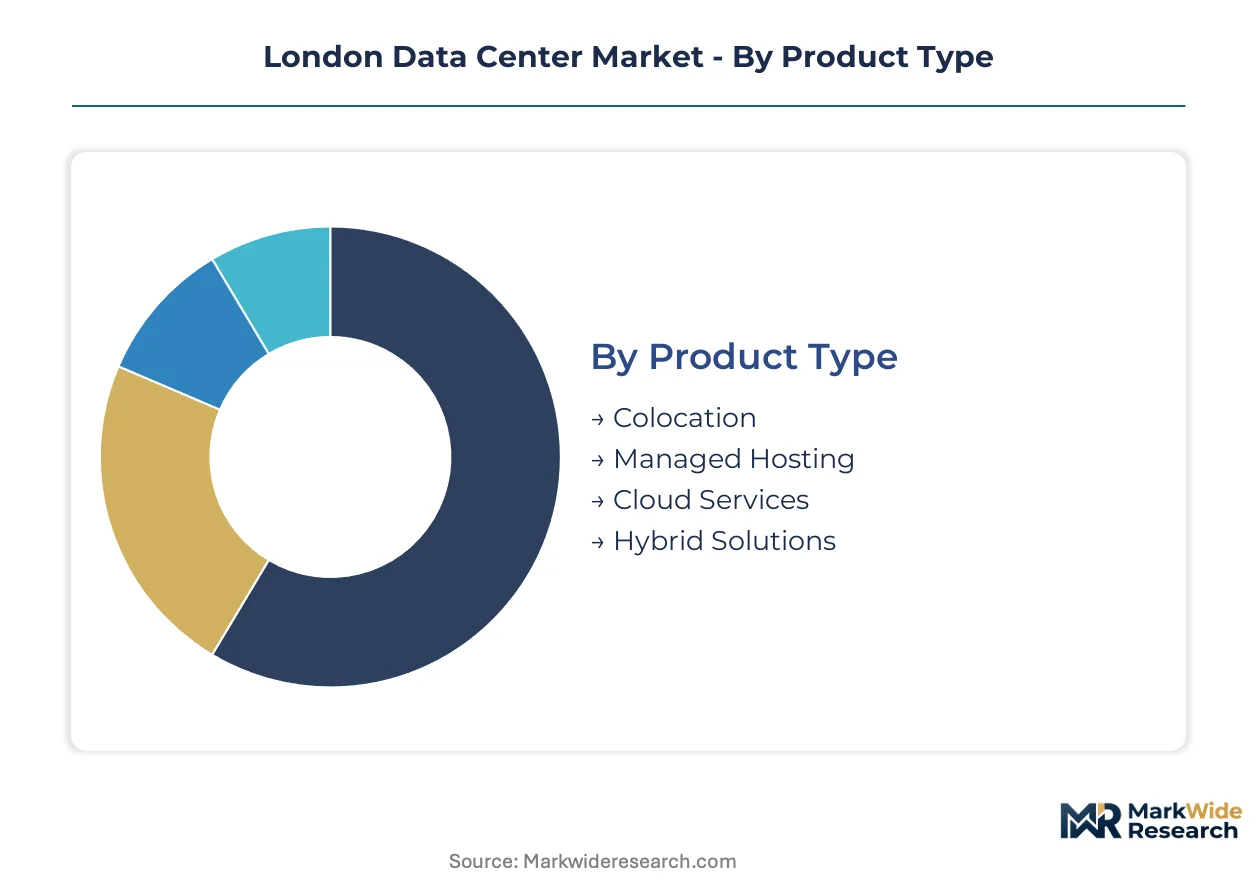
London's data center market segments along four axes that determine pricing power, contract duration, and facility engineering requirements. Each category channels demand through distinct procurement pathways and shapes operator capital allocation decisions.
Product Type:
Colocation flows through wholesale brokers and direct enterprise sales, while cloud services route through hyperscale aggregators and managed hosting travels via systems integrators.
- Colocation:Wholesale space and power leasing in multi-tenant facilities with cross-connect access to carrier hotels. Financial services firms in Docklands and Slough concentrate demand here, driven by latency arbitrage requirements for proximity to London's fiber exchanges.
- Managed Hosting:Operator-owned hardware with bundled remote hands and smart-hands support. Enterprise tenants in the City and Canary Wharf are unbundling these services, compressing margins while expanding addressable market for independent facilities management providers.
- Cloud Services:Hyperscale public cloud capacity delivered through London availability zones. Sovereign cloud certification creates defensible positioning for domestic operators against hyperscale incumbents in UK public-sector procurement.
- Hybrid Solutions:Workload segregation across on-premises, colocation, and public cloud environments. Regulated clients requiring data residency and audit trails drive premium pricing for architecture consulting and orchestration tooling.
Colocation dominates installed base. Hybrid solutions are where expansion concentrates.
End User:
Cost tier stratification separates premium proximity hosting from standard remote deployments across Greater London.
- Financial Services:High-frequency trading infrastructure, risk analytics clusters, and regulatory compliance archives. Sub-millisecond latency requirements to London Stock Exchange and LCH clearing systems command 40-60% pricing premiums in Docklands and Slough.
- Healthcare:Electronic health records, medical imaging archives, and clinical trial data management. NHS Digital compliance frameworks and patient data residency rules favor UK-sovereign certified facilities in peripheral zones with lower power costs.
- Retail:E-commerce transaction processing, inventory management systems, and customer analytics platforms. Seasonal demand spikes drive preference for burstable cloud contracts over fixed colocation commitments.
- Media & Entertainment:Content delivery networks, streaming transcoding farms, and post-production render clusters. 5G network densification is pulling compute into Greater London's outer boroughs and Thames Valley corridor.
Financial services anchors revenue per square meter. Healthcare is climbing the fastest as NHS migration accelerates.
Deployment:
Volume concentration splits between hyperscale campuses and distributed edge nodes based on latency tolerance and data gravity.
- On-premises:Enterprise-owned facilities within corporate real estate. Legacy banking headquarters in the Square Mile maintain captive data halls for core banking systems despite shedding peripheral workloads to colocation.
- Off-premises:Third-party data center capacity in Greater London and Thames Valley. Power density requirements from AI training clusters are compressing rack deployment timelines, forcing operators toward liquid cooling retrofits or peripheral greenfield construction.
- Edge:Distributed compute nodes within 10 milliseconds of end users. Mobile network operators are deploying edge infrastructure for autonomous vehicle telemetry and industrial IoT in Barking and Dagenham brownfield sites.
- Micro Data Centers:Containerized or modular facilities below 500kW capacity. Retail branch transformation and smart city sensor networks drive fastest expansion in outer London boroughs with constrained grid capacity.
Off-premises dominates installed base. Micro data centers are gaining share fastest as 5G densification accelerates.
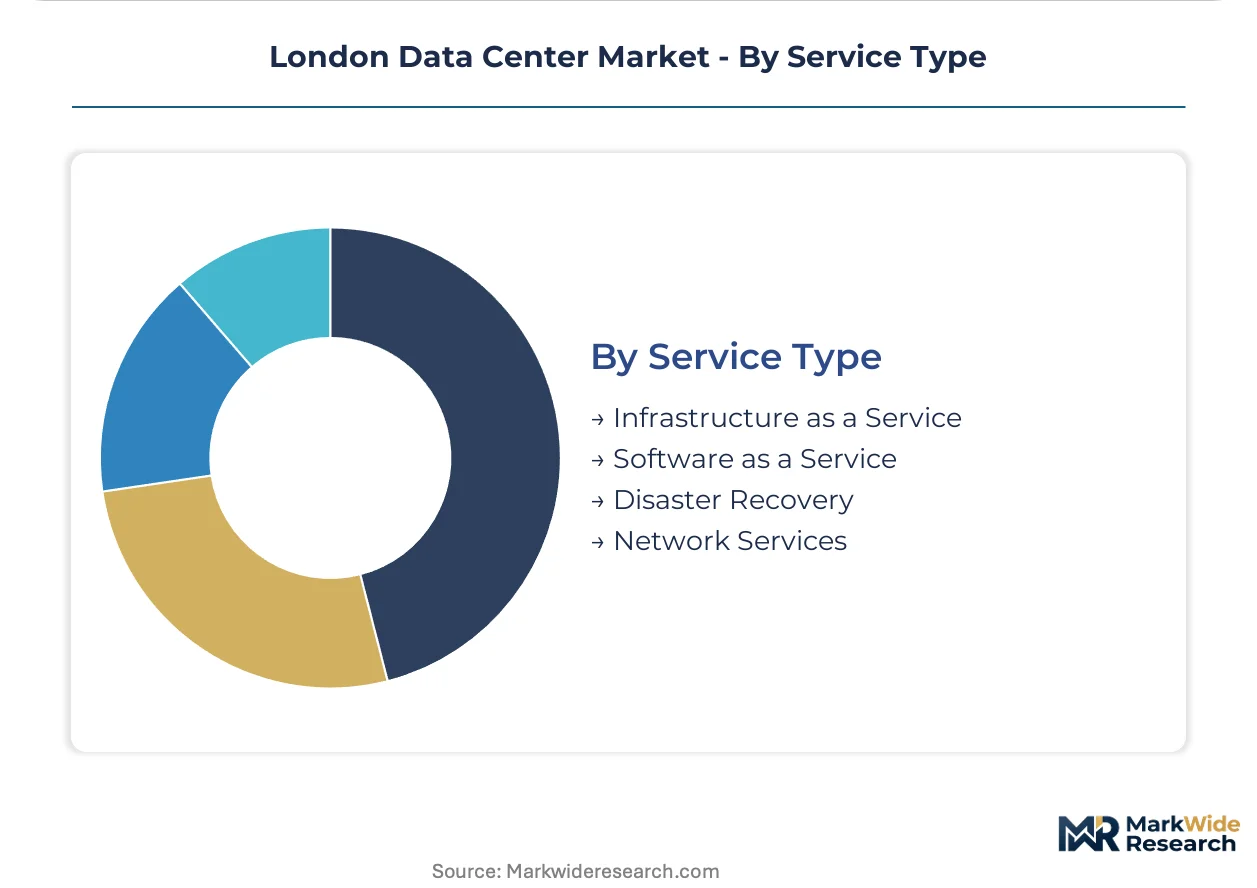
Service Type:
Customer type segmentation separates infrastructure buyers from application-layer procurement across regulated and unregulated verticals.
- Infrastructure as a Service:Raw compute, storage, and networking resources delivered via API or portal. Quantitative trading firms and AI labs specify liquid-cooled bare metal for GPU clusters, bifurcating deployment economics from air-cooled enterprise colocation.
- Software as a Service:Application hosting with bundled middleware and database management. Legal and insurance sector tenants are separating SaaS procurement from underlying infrastructure decisions, expanding addressable market for specialized managed service providers.
- Disaster Recovery:Secondary site replication, backup orchestration, and business continuity testing. Regulatory mandates from the Prudential Regulation Authority and Financial Conduct Authority sustain 15-20% of London data center capacity for DR standby.
- Network Services:Cross-connects, IP transit, and SD-WAN orchestration. Ofcom's wholesale fixed telecoms market review is lowering fiber access costs, reshaping interconnection economics in multi-tenant Docklands facilities.
Infrastructure as a Service dominates installed base. Network Services are where expansion concentrates as fiber liberalization proceeds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The London Internet Exchange anchors the United Kingdom's digital infrastructure, processing over 800 Gbps of peak traffic and underwriting the capital's dominance in European data center capacity.
Docklands
Latency-sensitive financial services firms concentrate demand for proximity hosting within 500 meters of fiber exchanges. Ofgem's grid connection queue reforms are compressing energization timelines for new substations. The LD8-LD10 campus cluster sustains interconnection density through meet-me-room expansions serving high-frequency trading infrastructure.
Slough
Hyperscale cloud buyers are absorbing wholesale space and power at densities exceeding 30 kW per rack. Part L Building Regulations mandate net-zero efficiency standards on all new facility construction. Powergate and adjacent campuses leverage diverse fiber entry points to capture traffic aggregation benefits from financial services clients.
Docklands Corridor
AI training clusters are forcing rack deployment timelines downward as liquid cooling retrofits compete with greenfield alternatives. Ofcom's wholesale fixed telecoms market review lowers cross-connect costs through Openreach pricing controls. Multi-tenant facilities are expanding carrier-neutral capacity to defend against single-carrier building churn.
Thames Valley
Edge micro data center deployments are accelerating along 5G network densification corridors. The UK's net-zero building standards accelerate mechanical and engineering upgrades across legacy brownfield sites. Peripheral zones offer stranded grid capacity with faster energization than constrained central London boroughs.
London Data Center Market Competitive Landscape
Listed leaders compete with private specialists across capital structure and risk tolerance, creating a tiered competitive field where scale advantages clash with operational flexibility. The market structure concentrates around three archetypes: global platform operators with interconnection density, wholesale capacity providers with power estate scale, and sovereign-certified specialists targeting regulated workloads. Dominant competitive moves include brownfield retrofit acceleration to capture stranded grid capacity and liquid cooling portfolio segmentation to serve bifurcated thermal demand from AI labs versus enterprise tenants.
Within the platform operator tier, Equinix anchors interconnection-centric positioning through its LD8-LD10 campus cluster, while Digital Realty exemplifies wholesale scale deployment via its Powergate facility. VIRTUS Data Centres occupies a position as the sovereign-certified specialist competing for UK public-sector security clearances. These three archetypes represent the competitive vectors shaping capital allocation across Greater London's constrained power environment.
| Leading Market Players |
|---|
| Equinix |
| Digital Realty |
| VIRTUS Data Centres |
| Telehouse (KDDI) |
| Ark Data Centres |
| Global Switch |
| CyrusOne |
| Kao Data |
| NTT Global Data Centers |
| Others |
Pricing and Supply Chain Analysis
Capacity reservation contracts with 10-15 year terms lock hyperscale cloud buyers into fixed power pricing while securing substation queue priority across Greater London's constrained grid. These arrangements bind operators to named energization timelines and shield tenants from Ofgem's distribution network volatility.
Pricing Analysis
Volume-discount tiering structures separate wholesale hyperscale commitments from retail colocation rack leases across Docklands and Slough. Pricing stratifies across premium proximity tiers for financial services latency arbitrage, standard air-cooled enterprise halls, and economy peripheral zones with longer fiber runs. Cost compression in standard enterprise tiers is intensifying because liquid cooling retrofits absorb capital that previously funded competitive lease rates. Healthcare and public-sector buyers exhibit highest price sensitivity due to fixed NHS Digital budgets, while quantitative trading firms show lowest sensitivity given sub-millisecond latency premiums.
Supply Chain Analysis
Specialized mechanical contracting chokepoints in the Thames Valley corridor constrain liquid cooling deployment velocity across Greater London. Equipment sourcing draws from Germany for precision cooling systems, China for electrical steel and copper busbars, and the USA for high-voltage switchgear. Single-source vulnerability concentrates in certified technician pools for direct-to-chip thermal management, inflating labor rates and project risk. Distribution runs through tier-one mechanical contractors with Uptime Institute credentials, who gate access to Tier III and IV commissioning schedules.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as AI training clusters bifurcate thermal demand away from legacy air-cooled enterprise tenants, creating parallel procurement pathways for liquid-cooled and conventional infrastructure.
For Market Incumbents: Compound interconnection density advantages through meet-me-room expansions in Docklands corridor facilities to defend against hyperscale cloud buyers' direct fiber builds. Accelerate brownfield power reuse in Barking and Dagenham to capture stranded grid capacity before peripheral greenfield sites achieve energization. Sovereign cloud certification investments anchor public-sector retention against domestic specialist challengers. For New Entrants and Emerging Players: Differentiate on liquid-cooled bare metal specialization for quantitative trading firms and AI labs seeking 50kW-plus rack densities unavailable in legacy halls. Target edge micro data center deployments in outer London boroughs where 5G densification outpaces incumbent platform operator response. Pursue sovereign-cloud certification as primary go-to-market angle for NHS Digital and central government workload capture. For Investors and Strategic Acquirers: Capital is best deployed toward brownfield retrofit specialists with secured substation connections and stranded industrial site leases across Greater London's peripheral zones. Long-term viability hinges on grid access entitlements rather than location premiums as central London capacity saturates. Watch Ofgem's distribution network queue reform implementation as inflection indicator for energization timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| Liquid Cooling Retrofit Acceleration | Enables 50kW-plus rack densities for AI training clusters in legacy Docklands halls. |
| Sovereign Cloud Certification Investment | Creates defensible positioning for UK public-sector security clearance requirements. |
| Brownfield Power Reuse Development | Captures stranded grid capacity in Barking and Dagenham with faster energization timelines. |
| Meet-Me-Room Capacity Expansion | Defends interconnection density against hyperscale direct fiber builds in Slough campuses. |
| Edge Micro Data Center Deployment | Addresses 5G network densification demand across outer London boroughs and Thames Valley. |
Research Methodology
A standing panel of data center operators, hyperscale cloud procurement officers, mechanical contractors with Uptime Institute credentials, and Ofgem grid connection specialists provided ongoing calibration across primary interview cycles. Secondary validation drew from UK Building Regulations Part L filings, Ofcom wholesale fixed telecoms market review documentation, Ofgem distribution network constraint maps, and operator capex disclosures. Bottom-up facility-level capacity modeling triangulated against top-down Greater London power demand projections.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation across product type, end user vertical, deployment architecture, and service tier. CAGRs were derived from facility commissioning timelines, power density evolution curves, and tenant mix shifts between hyperscale and enterprise colocation. Industry-specific inputs included liquid cooling penetration rates and sovereign cloud certification achievement timelines.
The analysis sits within stated boundaries; outcomes outside sustained AI training cluster demand or accelerated Part L compliance enforcement would require recalibration. Forecasts reflect assumptions regarding grid connection queue reform implementation and fiber liberalization pace. Practitioners should keep alternative scenarios live as Ofgem infrastructure access rulings and local authority planning committee alignment evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
South Africa Data Center Construction Market
Data Center Infrastructure
Canada Data Center Server Market
Data Center Infrastructure
North America Data Center Power Market
Data Center Infrastructure
Fault Tolerant Servers Market
Data Center Infrastructure
Middle East Data Center Physical Security Market
Data Center Infrastructure
Sweden Data Center Power Market
Data Center Infrastructure
Nigeria Data Center Physical Security Market
Data Center Infrastructure
Mexico Data Center Physical Security Market
Data Center Infrastructure
Data Center Colocation Market
Data Center Infrastructure
Italy Data Center Market
Data Center Infrastructure
Converged Infrastructure Management Market
Data Center Infrastructure
Switzerland Data Center Power Market
Data Center Infrastructure
Germany Data Center Construction Market
Data Center Infrastructure
China Internet Data Center Market
Data Center Infrastructure
Taiwan Data Center Market
Data Center Infrastructure
South America Data Center Power Market