
 Latin America Pharmaceutical Blister Packaging Market | 2026-2036
Latin America Pharmaceutical Blister Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Pharmaceutical Blister Packaging Market Insights
Pharmaceutical distribution through hospital and clinic procurement consortia is rewriting supply chain economics across Latin America. Amcor Limited leverages its regional converting footprint to sustain cost-competitive supply to Brazilian generics producers. Constantia Flexibles anchors high-barrier foil capacity in Mexico, while WestRock Company competes through integrated paperboard-backed blister card solutions for retail pharmacy channels.
Pharmaceutical blister packaging in Latin America comprises thermoformed or cold-formed cavity configurations sealed with lidding foil, engineered to provide moisture, oxygen, and light protection for solid oral dose forms. Cold form aluminum structures dominate where tropical humidity demands near-zero water vapor transmission rates, while PVC and PVDC thermoform variants serve cost-sensitive chronic medication programs. Blister packs capture the largest volume share across pharmacy and hospital end users, with child-resistant packaging representing the fastest-growing packaging type as ANVISA and national health ministries tighten pediatric safety mandates. Material selection increasingly stratifies between commodity plastic-foil composites for generics and premium multi-layer barrier laminates for biologics and stability-critical formulations.
ANVISA in Brazil, COFEPRIS in Mexico, and INVIMA in Colombia enforce GMP-aligned packaging standards that directly determine market access for both domestic and imported blister formats. The EU-MDR ripple effect through Latin American regulatory harmonization initiatives is elevating traceability and serialization requirements for export-oriented packaging operations. Stakeholders must monitor how rapidly evolving national pharmacopeia revisions and emerging sustainability mandates for pharmaceutical packaging waste will reshape material qualification timelines and capital deployment priorities.
Market Dynamics
ANVISA's alignment with ICH Q1A stability guidelines is redirecting material specifications across Brazil's pharmaceutical corridor, forcing converters to qualify high-performance foil laminates for tropical-climate barrier demands.
Growth Catalysts
- Regulatory harmonization:ANVISA's adoption of ICH Q1A guidelines accelerates cold-form blister qualification for moisture-sensitive generics.
- Hospital procurement consortia:Consolidated purchasing across São Paulo and Mexico City corridors concentrates volume demand and rewards scale-capable suppliers.
- Pediatric safety mandates:Child-resistant packaging requirements from Brazil's national health ministry expand addressable market for specialized lidding structures.
Market Restraints
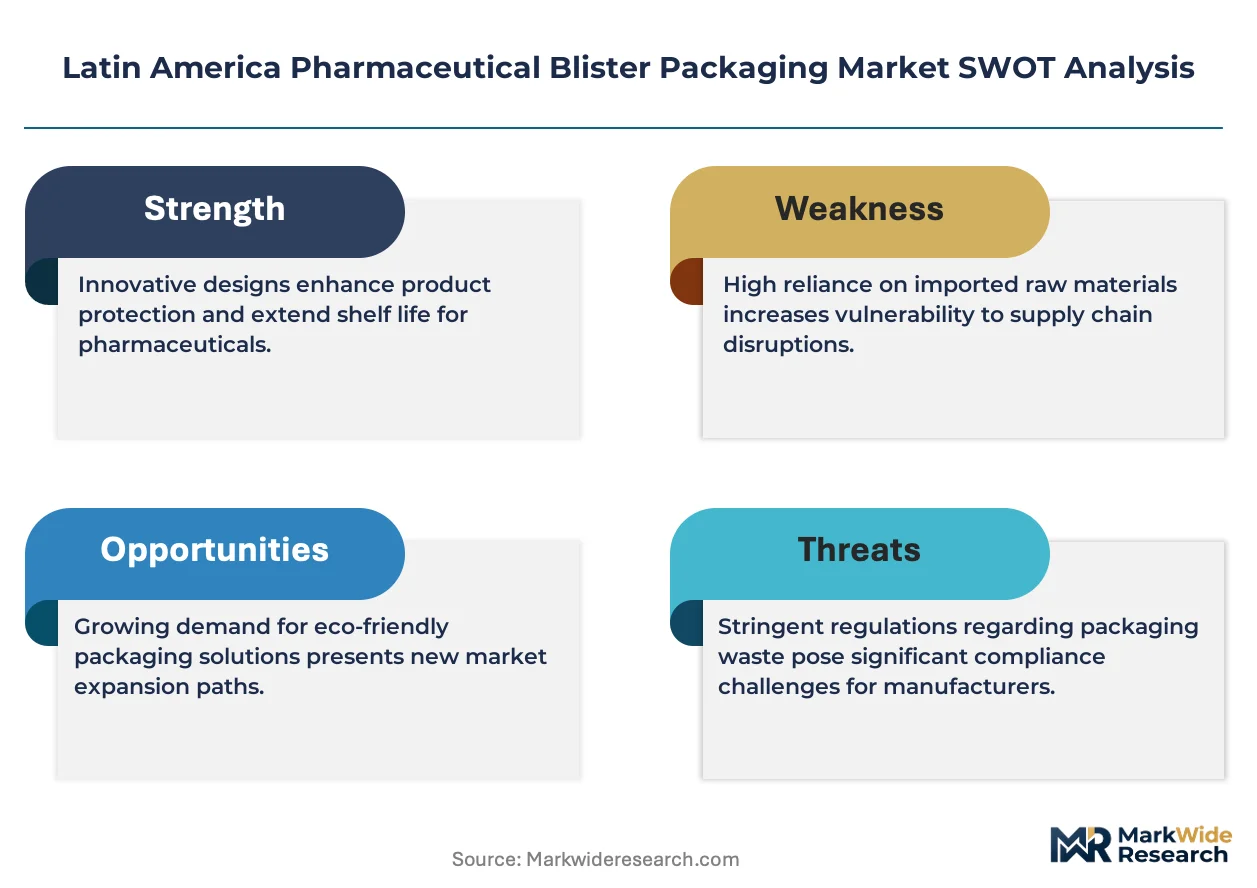
- Aluminum foil price volatility:Raw material input swings compress margin predictability for multi-layer laminate producers serving generics manufacturers.
- Import dependency for barrier films:Limited domestic production of PVDC and Aclar laminates concentrates supply risk with Asian resin suppliers.
- Cold-form equipment capex intensity:High-barrier aluminum cavity production requires specialized press investments that exclude smaller regional converters.
Strategic Opportunities
- Colombia's underpenetrated generics sector:INVIMA's streamlined GMP certification pathway invites blister packaging investment for emerging domestic manufacturers.
- Biologics stability packaging:Multi-layer high-barrier laminates address unmet needs for temperature-sensitive monoclonal antibody oral formulations entering regional trials.
- Retail pharmacy channel expansion:Direct-to-pharmacy distribution models in Mexico bypass traditional wholesaler markups and capture packaging specification influence.
Industry Challenges
- Serialization integration complexity:EU-MDR traceability requirements demand line-level IT upgrades that strain mid-cap converter operational bandwidth.
- Multi-layer laminate certification timelines:ANVISA material qualification protocols extend new product introduction cycles beyond generics manufacturers' launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Pharmaceutical Blister Packaging Market |
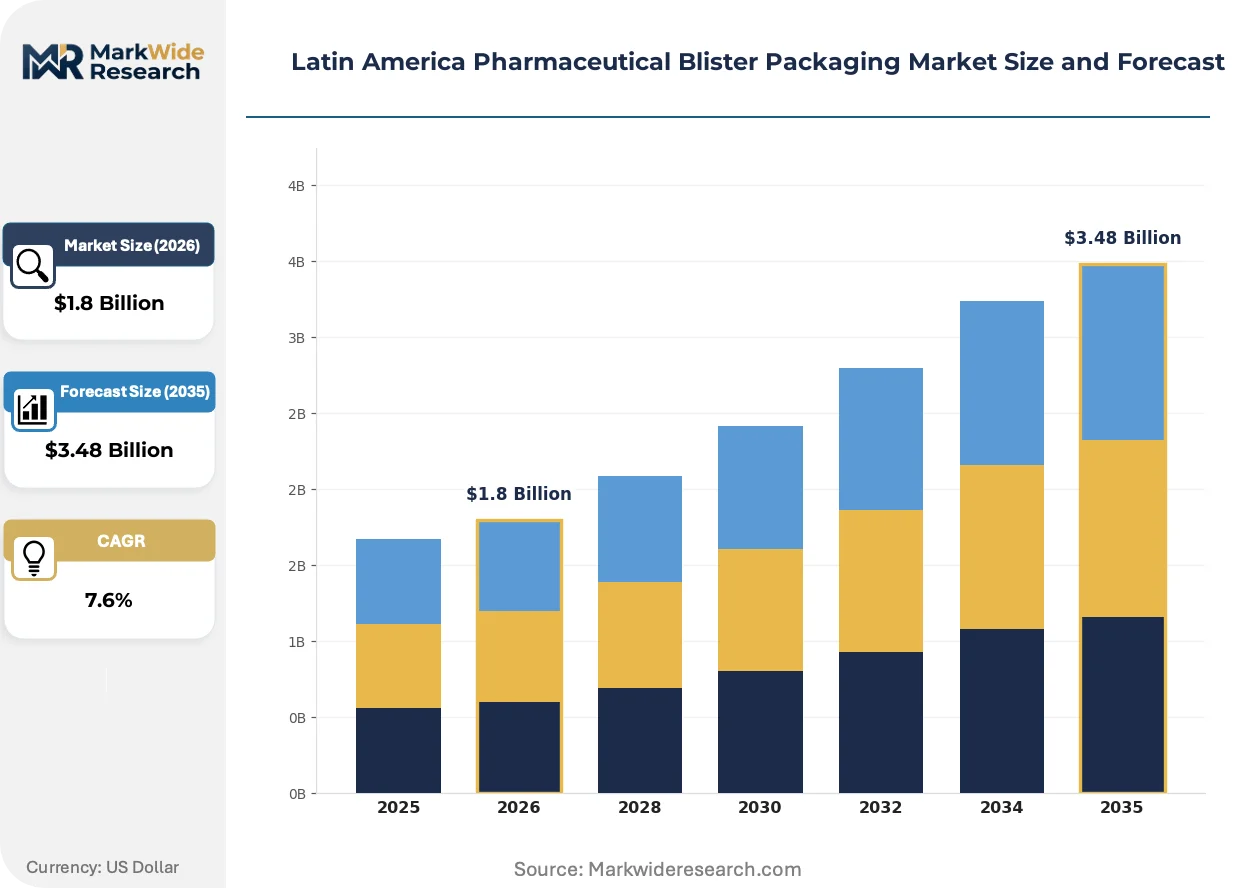
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.48 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cold Form, PVC, PVDC, Aluminum End User: Pharmacies, Hospitals, Clinics, Research Laboratories Packaging Type: Blister Packs, Clamshells, Rigid Trays, Child-Resistant Packaging Material: Plastic, Foil, Paper, Composites |
| Companies Covered | Amcor Limited, Constantia Flexibles, WestRock Company, Klockner Pentaplast Group, Sonoco Products Company, Tekni-Plex Inc, Uflex Limited, CCL Industries Inc, ACG Pharmapack Pvt. Ltd., Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Pharmaceutical Blister Packaging Market Trends and Innovations
Material science advances and regulatory traceability mandates are compressing traditional packaging specifications while opening premium segments for specialized barrier solutions across Latin American pharmaceutical supply chains.
Form-fill-seal automation with integrated vision inspection is rendering obsolete manual blister card assembly in São Paulo corridor generics facilities. Brazilian contract manufacturers deploying these systems achieve lot-level traceability compliance without secondary serialization stations. The capital efficiency of combined forming-sealing-inspection is compressing equipment payback periods and excluding semi-automatic operators from hospital consortia supplier lists.
ANVISA's pending adoption of EU-MDR-aligned Unique Device Identification rules will mandate machine-readable codes on individual blister units. Packaging converters must revalidate lidding foil printing specifications and thermal transfer ribbon compatibility. Export-oriented Brazilian generics manufacturers are pre-qualifying dual-compliant formats to avoid separate production runs for domestic and European markets.
Direct sourcing of finished blister packs by hospital procurement consortia is displacing traditional distributor-controlled specification channels. São Paulo's public health purchasing pools now require converter-direct relationships with documented GMP certification. Mexican social security institute tenders increasingly specify barrier performance metrics rather than material descriptions, shifting technical negotiation power toward engineering-capable suppliers.
Latin America Pharmaceutical Blister Packaging Market Segmentation
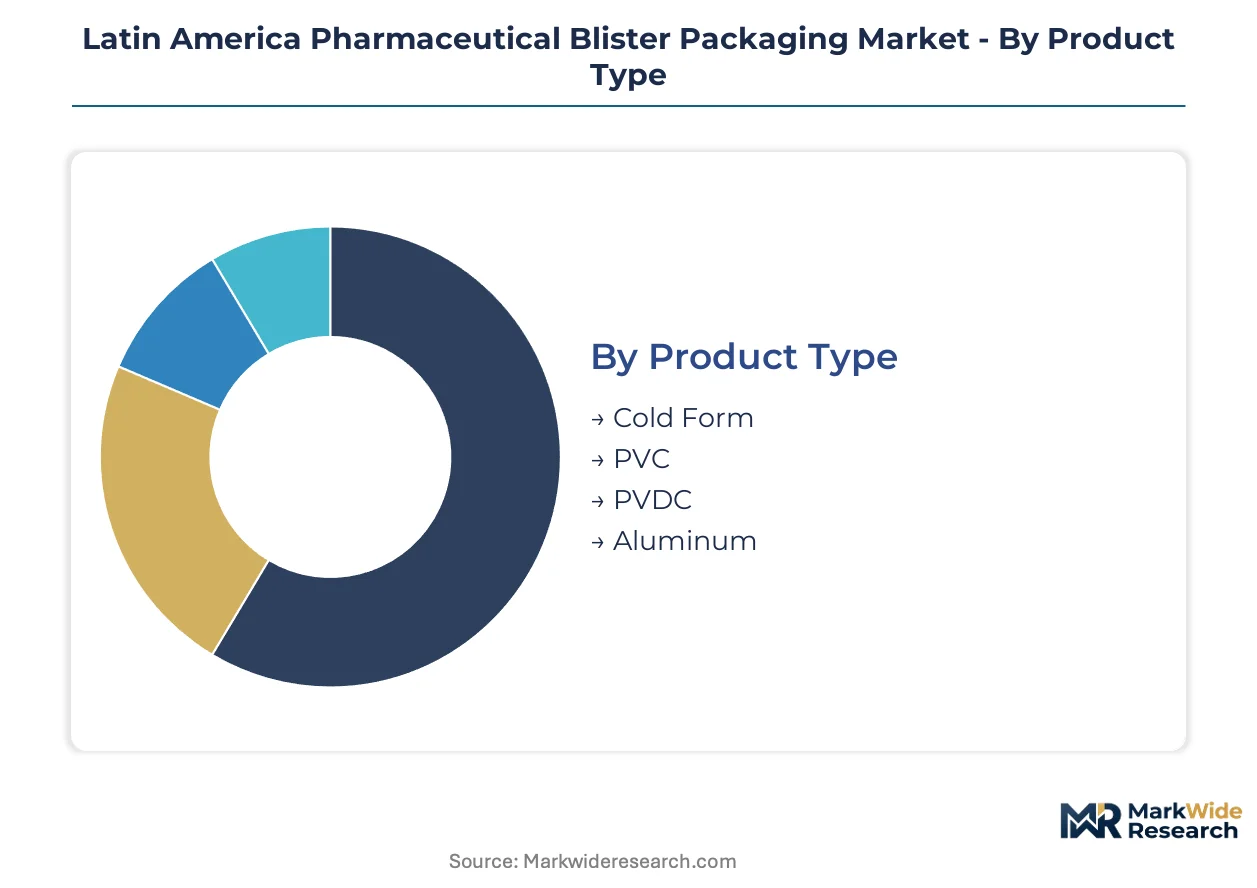
Pharmaceutical blister packaging specifications in Latin America diverge sharply across therapeutic stability requirements, distribution channel protocols, and pediatric safety mandates. Material and format selection directly determines regulatory clearance velocity under ANVISA, COFEPRIS, and INVIMA jurisdiction.
Product Type:
Cold-form aluminum structures command premium positioning where tropical humidity demands near-zero moisture transmission, while thermoform variants serve cost-engineered chronic medication programs.
- Cold Form:Multi-layer aluminum laminates achieve water vapor transmission rates below 0.01 g/m²/day. São Paulo generics manufacturers deploy these for hygroscopic statins and antihypertensives under ANVISA ICH Q1A alignment.
- PVDC:Polyvinylidene chloride coatings on PVC substrates deliver intermediate barrier performance at 40-60% cost reduction versus cold-form. Mexican social security tenders specify PVDC for diabetes and cardiovascular maintenance therapies.
- PVC:Unmodified polyvinyl chloride thermoforms serve lowest-cost antibiotic and analgesic programs where shelf-life requirements permit moderate moisture ingress.
- Aluminum:Pure foil lidding and strip pack formats dominate single-dose unit-dose hospital dispensing systems across Brazilian public health networks.
The dominant share belongs to PVC and PVDC thermoform combinations, while cold-form aluminum is closing the gap fastest on regulatory-driven stability upgrades.
End User:
Procurement consolidation across Latin American health systems is concentrating volume with scale-capable converters who can navigate direct-contracting requirements.
- Pharmacies:Retail chains in Mexico City and São Paulo specify child-resistant lidding and integrated paperboard backing for over-the-counter visibility. Direct-to-pharmacy distribution models bypass traditional wholesaler markups.
- Hospitals:São Paulo procurement consortia and Mexican IMSS tenders demand unit-dose compliance packaging with machine-readable traceability codes. Form-fill-seal automation with vision inspection is becoming mandatory for supplier qualification.
- Clinics:Outpatient facilities in Colombia's emerging generics corridor favor mid-barrier PVC-PVDC hybrids for specialty chronic care programs.
- Research Laboratories:Clinical trial material packaging requires temperature-indicating labels and stability-monitoring inserts for biologics entering regional Phase II and III studies.
Hospital procurement consortia command the largest volume concentration, though pharmacy direct-sourcing is expanding specification influence most rapidly.
Packaging Type:
Safety engineering and regulatory traceability are bifurcating formats between commodity pharmacy dispensing and specialized pediatric protection.
- Child-Resistant Packaging:Push-through and peel-push lidding structures with senior-friendly compliance features address Brazil's national health ministry mandates. These formats carry 25-40% premium over standard blisters.
- Blister Packs:Conventional cavity-and-lidding configurations remain the volume default across generic solid oral dose manufacturing in Brazil and Mexico.
- Clamshells:Thermoformed hinged containers serve medical device and diagnostic co-packaging applications with pharmaceutical kits.
- Rigid Trays:Thermoformed platforms with snap-fit closure provide surgical kit organization and sterile field compatibility in hospital central supply.
Standard blister packs retain the installed base majority, while child-resistant formats are gaining share fastest on pediatric safety mandate expansion.
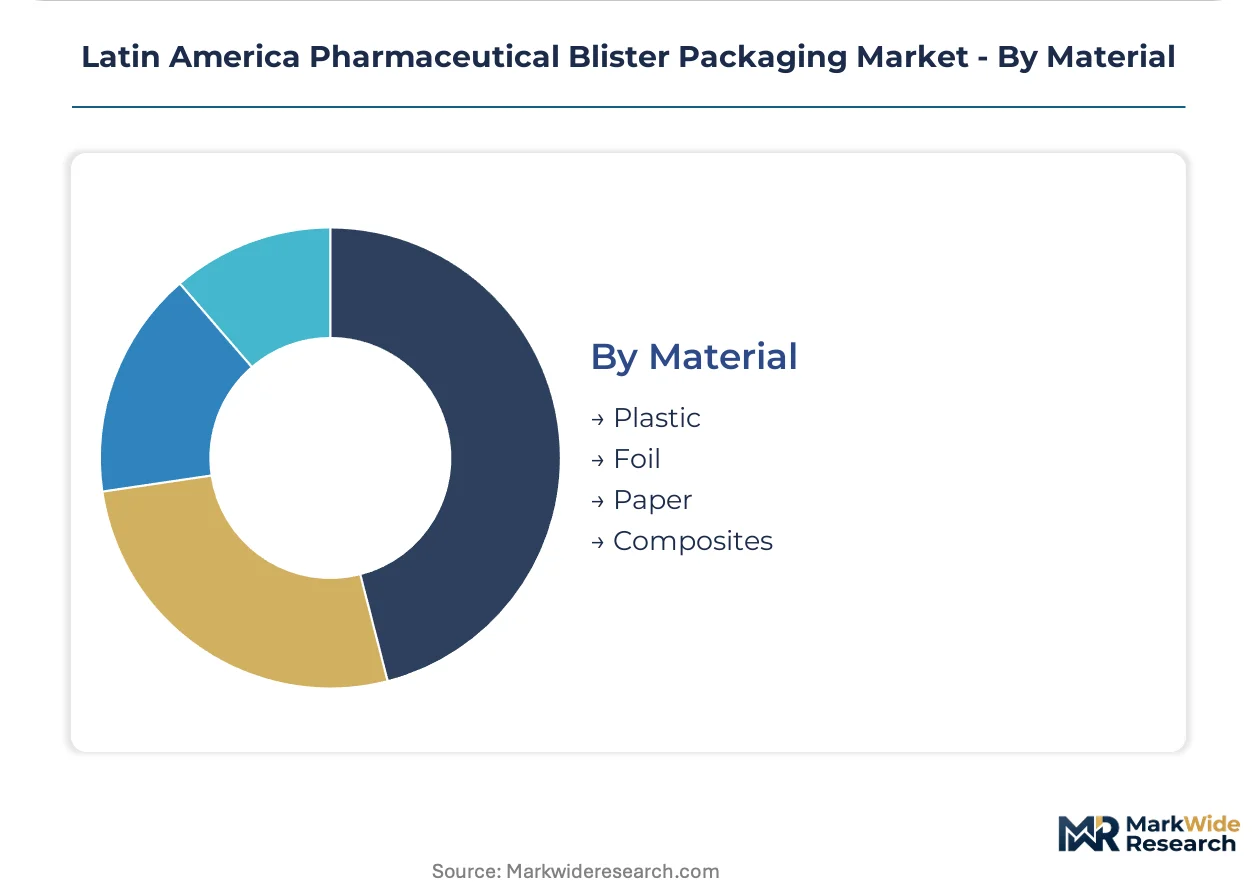
Material:
Raw material sourcing strategies are splitting between captive aluminum rolling capacity and import-dependent specialty films.
- Foil:Aluminum dominates high-barrier applications through Amcor and Constantia regional converting footprints. Price volatility in London Metal Exchange contracts compresses margin predictability for laminate producers.
- Plastic:PVC and PVDC resin dependence on Asian suppliers concentrates supply risk for Brazilian and Mexican converters.
- Composites:Multi-layer paperboard-foil-plastic laminates enable integrated blister card solutions for retail pharmacy shelf differentiation.
- Paper:Uncoated and coated paperboard substrates serve secondary packaging and patient information leaflet integration with sustainability positioning.
Foil laminates anchor the value concentration, though composite structures are climbing fastest on retail channel premium positioning requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Santos anchors Brazil's pharmaceutical logistics infrastructure, handling specialized containerized shipments of temperature-sensitive active pharmaceutical ingredients that feed São Paulo's blister converting corridor.
Brazil
ANVISA's ICH Q1A alignment drives cold-form blister qualification for moisture-sensitive generics. São Paulo's pharmaceutical corridor concentrates domestic packaging investment that displaces imported finished blisters. Hospital procurement consortia in the city now mandate direct converter relationships with documented GMP certification.
Mexico
COFEPRIS enforces GMP-aligned packaging standards that determine market access for imported blister formats. Mexico City procurement consortia and IMSS tenders increasingly specify barrier performance metrics rather than material descriptions. The Bajío Region's expanding generics manufacturing base attracts foil laminate converting capacity from multinational suppliers.
Colombia
INVIMA's streamlined GMP certification pathway invites blister packaging investment for emerging domestic manufacturers. Bogotá's pharmaceutical cluster favors mid-barrier PVC-PVDC hybrids for specialty chronic care programs. The country's underpenetrated generics sector represents untapped addressable volume for scale-capable converters.
Argentina
ANMAT maintains stability testing requirements that favor high-barrier laminates for humidity-sensitive formulations. Buenos Aires pharmaceutical manufacturers source cold-form structures through regional distributors given limited domestic converting capacity. Import dependency for barrier films concentrates supply risk with Brazilian and Mexican suppliers.
Chile
ISP enforces pharmacopeia-aligned packaging standards for imported and domestic pharmaceutical products. Santiago's hospital procurement networks specify unit-dose compliance packaging with traceability codes. The country's clinical trial activity generates demand for temperature-indicating blister configurations for biologics entering regional Phase II studies.
Latin America Pharmaceutical Blister Packaging Market Competitive Landscape
On the supply side, the industry is structured around three strategic archetypes: multinational converters with regional converting footprints, specialized high-barrier foil producers with tropical-climate expertise, and integrated paperboard-backed solution providers for retail pharmacy channels. Competitive positioning hinges on ANVISA qualification timelines, hospital consortia direct-contracting relationships, and cold-form equipment scale. M&A activity targets mid-cap converters with established GMP certifications, while capacity expansion concentrates in São Paulo and Mexico City corridors to capture procurement consortium volume.
Among multinational packaging specialists, Amcor Limited, Constantia Flexibles, and WestRock Company occupy distinct positioning vectors. Amcor leverages its regional converting footprint to sustain cost-competitive supply to Brazilian generics producers. Constantia anchors high-barrier foil capacity in Mexico for tropical-climate barrier demands. WestRock competes through integrated paperboard-backed blister card solutions designed for retail pharmacy channel visibility requirements.
| Leading Market Players |
|---|
| Amcor Limited |
| Constantia Flexibles |
| WestRock Company |
| Klockner Pentaplast Group |
| Sonoco Products Company |
| Tekni-Plex Inc |
| Uflex Limited |
| CCL Industries Inc |
| ACG Pharmapack Pvt. Ltd. |
| Others |
Pricing and Supply Chain Analysis
Asian resin suppliers for PVDC and Aclar barrier films concentrate upstream margin capture, forcing Latin American converters to absorb volatility while hospital procurement consortia squeeze downstream pricing power through consolidated volume tenders.
Pricing Analysis
Three-tier pricing structure across premium cold-form laminates, standard PVDC hybrids, and economy PVC thermoforms governs contract negotiations. Price differentiation rests on ANVISA qualification status and cold-form equipment scale, with certified high-barrier converters commanding 25-40% premiums over commodity suppliers. Cost compression in the PVC tier is intensifying because Brazilian generics manufacturers are consolidating supplier panels. Hospital procurement consortia exhibit the highest price sensitivity, while biologics developers show relative inelasticity for stability-critical barrier performance.
Supply Chain Analysis
Export-control scrutiny on advanced barrier film manufacturing equipment limits domestic capacity expansion in Brazil and Mexico, perpetuating import dependence for multi-layer laminate production. Raw material sourcing draws from Chinese PVDC resin suppliers, German aluminum rolling mills, and Japanese Aclar film producers. Single-source vulnerability concentrates around Asian specialty polymer supply, with Brazilian converters maintaining 90-120 day safety stocks. Distribution runs through converter-direct relationships with São Paulo and Mexico City hospital procurement consortia, displacing traditional pharmaceutical distributor intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-moat arena where ANVISA qualification timelines create switching costs that entrench incumbent converters with validated cold-form capacity.
For Market Incumbents: Pre-empt margin erosion in the PVC commodity tier by securing backward integration into aluminum foil rolling capacity. Anchor high-barrier foil production in São Paulo corridor to capture hospital consortia volume before Mexican Bajío Region generics manufacturing scales. Certification investment in EU-MDR dual-compliant formats defends against emerging Colombian converters with streamlined INVIMA pathways.
For New Entrants and Emerging Players: Build out mid-barrier PVC-PVDC hybrid capacity targeting Colombia's underpenetrated generics sector where INVIMA's accelerated GMP certification reduces qualification timelines. Bogotá's emerging pharmaceutical cluster offers the most penetrable geography given limited domestic converting infrastructure. Direct-to-pharmacy distribution partnerships in Mexico bypass entrenched hospital consortia supplier lists.
For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap converters with established ANVISA certifications and underutilized cold-form press capacity. Long-term viability hinges on regulatory entrenchment rather than commodity scale, with qualified barrier-laminate producers commanding durable margin premiums. Watch for INVIMA's GMP harmonization pace as the inflection signal for Colombian market entry timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Form Equipment Scale-Up | Captures São Paulo hospital consortia volume requiring ICH Q1A-compliant barrier performance. |
| Backward Integration into Foil Rolling | Reduces London Metal Exchange price volatility exposure for multi-layer laminate producers. |
| ANVISA-EU-MDR Dual Certification | Eliminates separate production runs for Brazilian domestic and European export markets. |
| Direct-to-Pharmacy Distribution | Bypasses traditional wholesaler markups in Mexico City retail channel expansion. |
| Child-Resistant Lidding Development | Addresses Brazil's national health ministry pediatric safety mandate premium segment. |
Research Methodology
Desk research of ANVISA regulatory filings, COFEPRIS GMP certification databases, and pharmaceutical customs records preceded structured interviews with blister packaging procurement managers at São Paulo hospital consortia, regulatory affairs directors at Mexican generics manufacturers, and technical sales leads at multinational foil converters. Bottom-up volume estimates from equipment capacity utilization rates were triangulated against top-down pharmaceutical production data from national health ministry statistics.
Assumptions held fixed include ANVISA's ICH Q1A alignment trajectory and existing cold-form equipment installed base across the analysis window, while aluminum price volatility bands and Colombian generics penetration rates were stress-tested across scenarios. Segmentation modeling incorporated product type, end-user channel, barrier performance tier, and regional regulatory cluster dimensions. CAGRs were derived from pharmaceutical production growth correlations with packaging intensity ratios.
Stress conditions across aluminum price volatility, PVDC resin supply disruption, and ANVISA qualification timeline extensions were modeled; outcomes outside those bands fall beyond the analytical envelope. Material shifts in INVIMA's GMP harmonization pace or EU-MDR serialization mandate acceleration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Blister Packaging
Welded Blisters Market
Blister Packaging
Asia Pacific Pharmaceutical Blister Packaging Market
Blister Packaging
Pharma Blisters Packaging Market
Blister Packaging
North America Pharmaceutical Blister Packaging Market
Blister Packaging
United States Blister Packaging Market
Blister Packaging
Blister Foil Market
Blister Packaging
Carded Blister Packaging Market
Blister Packaging
North America Blister Packaging Market
Blister Packaging
Middle East and Africa Pharmaceutical Blister Packaging Market
Blister Packaging
Blister Cards Market
Blister Packaging
Sliding Blister Packaging Market
Blister Packaging
Pharma Blister Packaging Machines Market
Blister Packaging
Liquid Blister Pack Market
Blister Packaging
Alu Alu Cold Blister Films Market
Blister Packaging
Alu Alu Blister Packaging Machine Market
Blister Packaging
Blister Packaging Equipment Market