
 Asia-Pacific Biological Organic Fertilizers Market | 2026-2036
Asia-Pacific Biological Organic Fertilizers Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Biological Organic Fertilizers Market Outlook
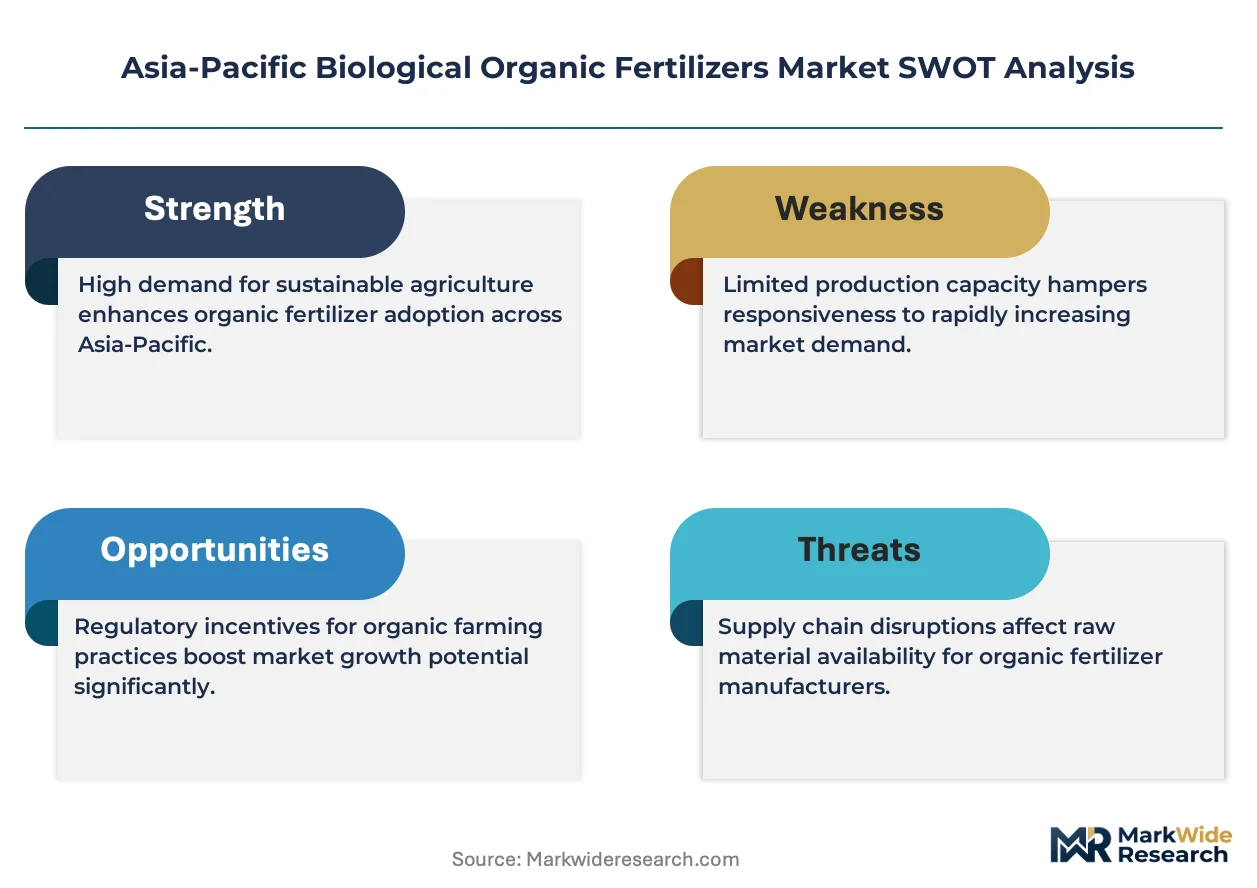
Organic certification cycles under India's Participatory Guarantee System (PGS-India) and China's organic GB standards are redrawing competitive boundaries for biological fertilizer suppliers. National Fertilizer Limited leverages its government-backed distribution network to sustain supply lines into Punjab and Haryana's wheat belts. Seek Biotechnology Co. Ltd anchors its position through specialized microbial consortia development for subtropical soil conditions. Gujarat State Fertilizers & Chemicals Ltd competes on backward integration into gujarat's port-accessible raw material corridors.
Asia-Pacific biological organic fertilizers comprise living or dormant microbial inoculants, decomposed plant or animal residues, and natural mineral amendments formulated to enhance soil fertility through nitrogen fixation, phosphate solubilization, or organic matter replenishment rather than direct chemical nutrient delivery. Manufacturing typically involves controlled aerobic composting with thermophilic microbial stages, followed by maturation, screening, and stabilization to maintain colony-forming unit viability above minimum thresholds. Vermicompost commands premium positioning among greenhouse operators due to its fine particle structure and elevated microbial diversity, while liquid formulations gain traction in precision fertigation systems across Australian horticulture clusters. Meal fertilizers occupy a mature cost-competitive tier serving broadacre cereal producers with lower per-hectare input budgets.
India's FSSAI and BIS jointly govern organic input quality thresholds, while China's SAMR enforces GB 20287 standards for microbial fertilizer registration and field efficacy documentation. Australia's TGA-equivalent agricultural regulator mandates biosecurity clearance for imported inoculant strains, adding compliance layers for cross-border suppliers. Stakeholders must track how Indonesia's nascent organic certification harmonization with ASEAN standards alters import eligibility and domestic production incentives.
Market Dynamics
India's PLI scheme for agri-input manufacturing and China's GB 20287 quality standards are compressing supplier margins while accelerating consolidation among microbial inoculant producers across the region.
Growth Catalysts
- State-level organic farming missions:Uttar Pradesh and Madhya Pradesh channel procurement toward certified biological inputs, creating guaranteed offtake corridors for domestic manufacturers.
- GB 20287 standards:China's microbial fertilizer registration requirements enforce field efficacy documentation, filtering out low-viability products and elevating technical barriers to entry.
- Compost-based biological fertilizers:Rice cultivation across Vietnam and Thailand absorbs rising volumes as farmers confront soil degradation from decades of synthetic chemical application.
Market Restraints
- Input cost volatility:Guano and rock phosphate prices fluctuate with Indonesian and Peruvian export quotas, squeezing formulation economics for mineral-amendment blends.
- Supply concentration risk:Thermophilic starter cultures for controlled composting originate from a narrow base of Japanese and Dutch strain libraries, creating biosecurity bottlenecks.
- Technical limitation:Colony-forming unit viability degrades above 35°C during Asia-Pacific monsoon transport, constraining liquid formulation shelf life.
Strategic Opportunities
- Underpenetrated geography:Indonesia's nascent organic certification harmonization with ASEAN standards alters import eligibility, opening procurement pathways for Vietnamese compost exporters.
- Regulatory tailwind:Australia's TGA-equivalent agricultural regulator mandates biosecurity clearance for imported inoculant strains, privileging domestic strain development capabilities.
- Precision fertigation convergence:Liquid biological formulations integrate with drip irrigation infrastructure across Australian horticulture clusters, displacing broadcast application methods.
Industry Challenges
- CFU enumeration skill gap:Accurate colony-forming unit counting requires microbiological expertise scarce in Vietnam's provincial extension services, compromising quality assurance.
- Certification timeline compression:India's PGS-India and BIS joint organic input approvals extend 14-18 months, locking working capital in pre-revenue product pipelines.
Report Scope
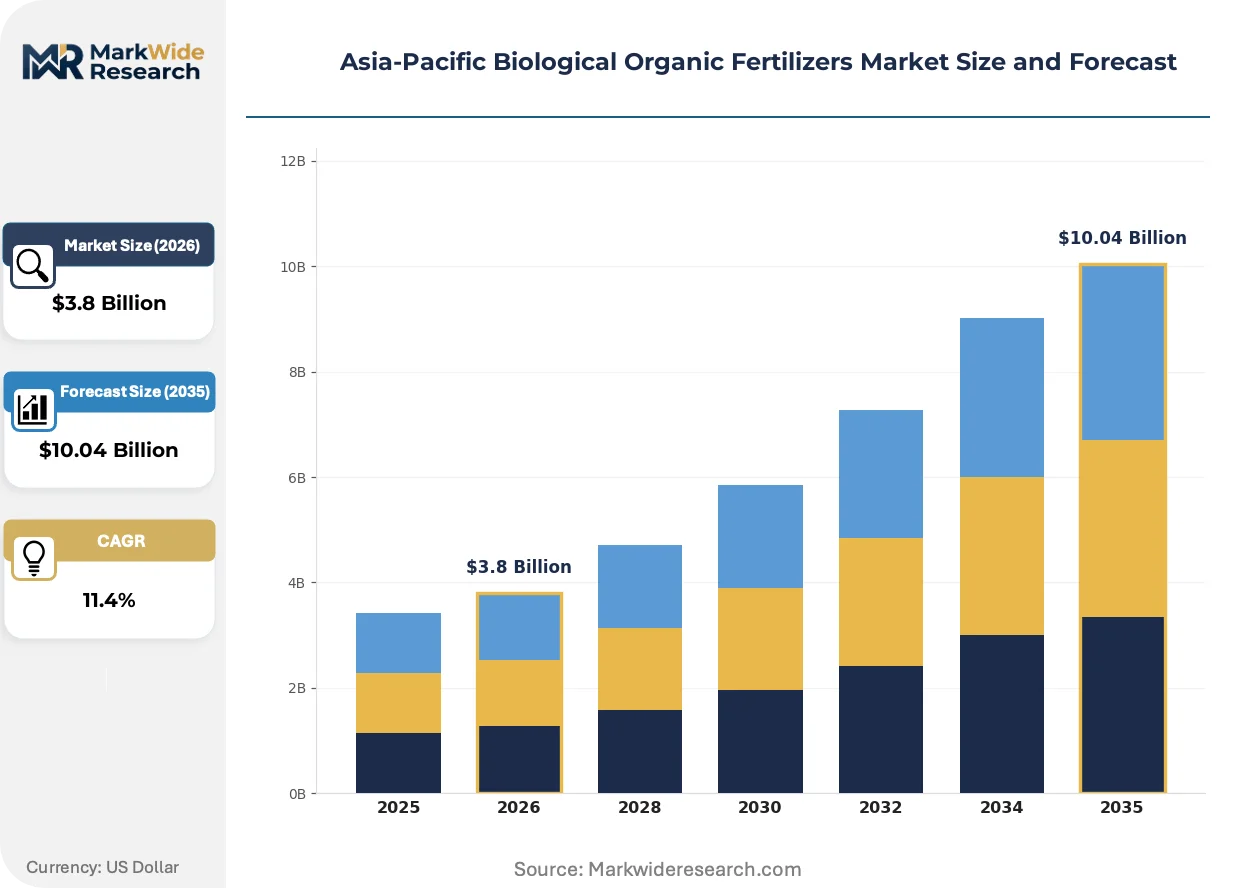
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Biological Organic Fertilizers Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compost, Vermicompost, Seaweed Extract, Meal Fertilizers End User: Agricultural Producers, Horticulturists, Greenhouse Operators, Organic Farms Form: Granular, Liquid, Powder, Pelleted Distribution Channel: Direct Sales, Online Retail, Agricultural Supply Stores, Distributors |
| Companies Covered | National Fertilizer Limited, Seek Biotechnology Co. Ltd, Gujarat State Fertilizers & Chemicals Ltd, Indian Farmers Fertiliser Cooperative Limited, AgriLife (India) Private Limited, IPL Biologicals Limited, Kiwa Biotech, Qingdao Hibong Industrial Technology Co.,Ltd., Biostadt India Limited, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Biological Organic Fertilizers Market Strategic Shifts
Microbial formulation technologies and regulatory harmonization frameworks are compressing product development cycles while fragmenting traditional distribution hierarchies across Asia-Pacific agricultural input channels.
Encapsulation technology for nitrogen-fixing rhizobia is miniaturizing delivery systems to seed-coat applications. Australian broadacre cereal producers adopt microgranular inoculants at accelerating rates, displacing peat-based carrier formats that dominated procurement for two decades. This compression enables precision placement at planting, reducing per-hectare microbial load requirements by half.
China's SAMR enforcement of GB 20287 field efficacy documentation is elevating registration costs for microbial fertilizer entrants. Domestic producers with captive research stations capture disproportionate approval velocity, while cross-border suppliers face extended dossier preparation timelines. The regulation most acutely affects consortia formulations combining multiple bacterial strains, where interaction studies multiply submission complexity.
Greenhouse operators across Thailand's Chiang Mai cluster now specify vermicompost by particle size distribution and microbial diversity indices rather than bulk organic matter content alone. This specification shift elevates supplier technical documentation burdens while compressing spot-market trading volumes. Procurement managers increasingly contract directly with vermicompost facilities, bypassing traditional agrochemical distributor networks that aggregated biological inputs as secondary product lines.
Asia-Pacific Biological Organic Fertilizers Market Segmentation
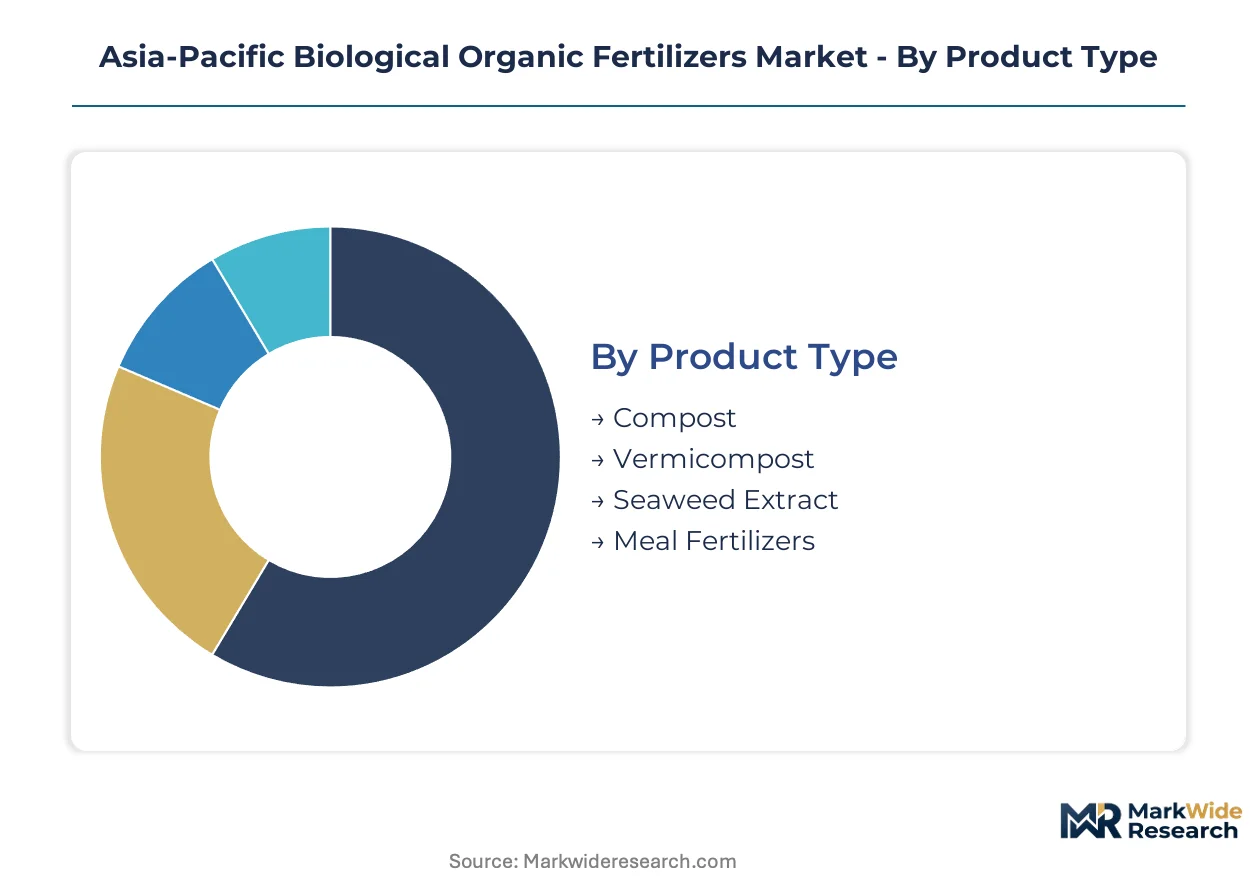
Biological organic fertilizers fragment across product chemistry, application intensity, and procurement channel. Each segment carries distinct margin profiles and regulatory exposure across Asia-Pacific agricultural markets.
Product Type:
Domestic production dominates compost and vermicompost categories across India and Vietnam, while seaweed extract and specialized meal fertilizers flow through import-dependent supply chains from Indonesian and Peruvian sources.
- Compost:Thermophilic aerobic decomposition of agricultural residues produces stabilized organic matter with documented microbial activity. Rice cultivation across Vietnam's Mekong Delta and Thailand's Central Plains absorbs rising volumes as farmers confront soil degradation from decades of synthetic chemical application. Compost holds the largest share; momentum sits with vermicompost.
- Vermicompost:Earthworm-mediated decomposition yields fine particle structure with elevated microbial diversity indices. Greenhouse operators across Thailand's Chiang Mai cluster now specify vermicompost by particle size distribution rather than bulk organic matter content alone, contracting directly with production facilities.
- Seaweed Extract:Marine biomass processing from Indonesian archipelago sources supplies bioactive compounds for foliar application.
- Meal Fertilizers:Oilseed and fish processing residues occupy mature cost-competitive tier serving broadacre cereal producers with lower per-hectare input budgets.
Compost anchors volume; vermicompost commands premium positioning through specification intensity.
End User:
Procurement scale separates segments, with agricultural producers optimizing per-ton logistics and greenhouse operators prioritizing batch consistency and microbial certification.
- Agricultural Producers:Wheat and rice farmers across India's Indo-Gangetic Plain drive bulk procurement through state-level organic farming missions in Uttar Pradesh and Madhya Pradesh.
- Horticulturists:Precision nutrient management requirements favor liquid formulations with documented colony-forming unit viability.
- Greenhouse Operators:Controlled environment agriculture demands fine-grade substrates with verified pathogen suppression properties.
- Organic Farms:Certification compliance under India's PGS-India and China's GB standards mandates chain-of-custody documentation from production to application.
Agricultural producers represent the deepest volume pool; greenhouse operators generate the steepest expansion trajectory through specification upgrading.
Form:
Physical state determines shelf-life vulnerability and application equipment compatibility across monsoon-exposed distribution networks.
- Granular:Compacted formulations enable mechanical broadcasting across broadacre cereal production. Australian broadacre producers adopt microgranular inoculants at accelerating rates, displacing peat-based carrier formats.
- Liquid:Precision fertigation integration across Australian horticulture clusters displaces broadcast application methods, though CFU viability degrades above 35°C during monsoon transport.
- Powder:Low-cost carrier for mycorrhizal inoculants in nursery propagation systems.
- Pelleted:Seed-coat compatible dimensions enable precision placement at planting, reducing per-hectare microbial load requirements.
Granular forms dominate current procurement; liquid formulations are gaining share fastest through irrigation infrastructure convergence.
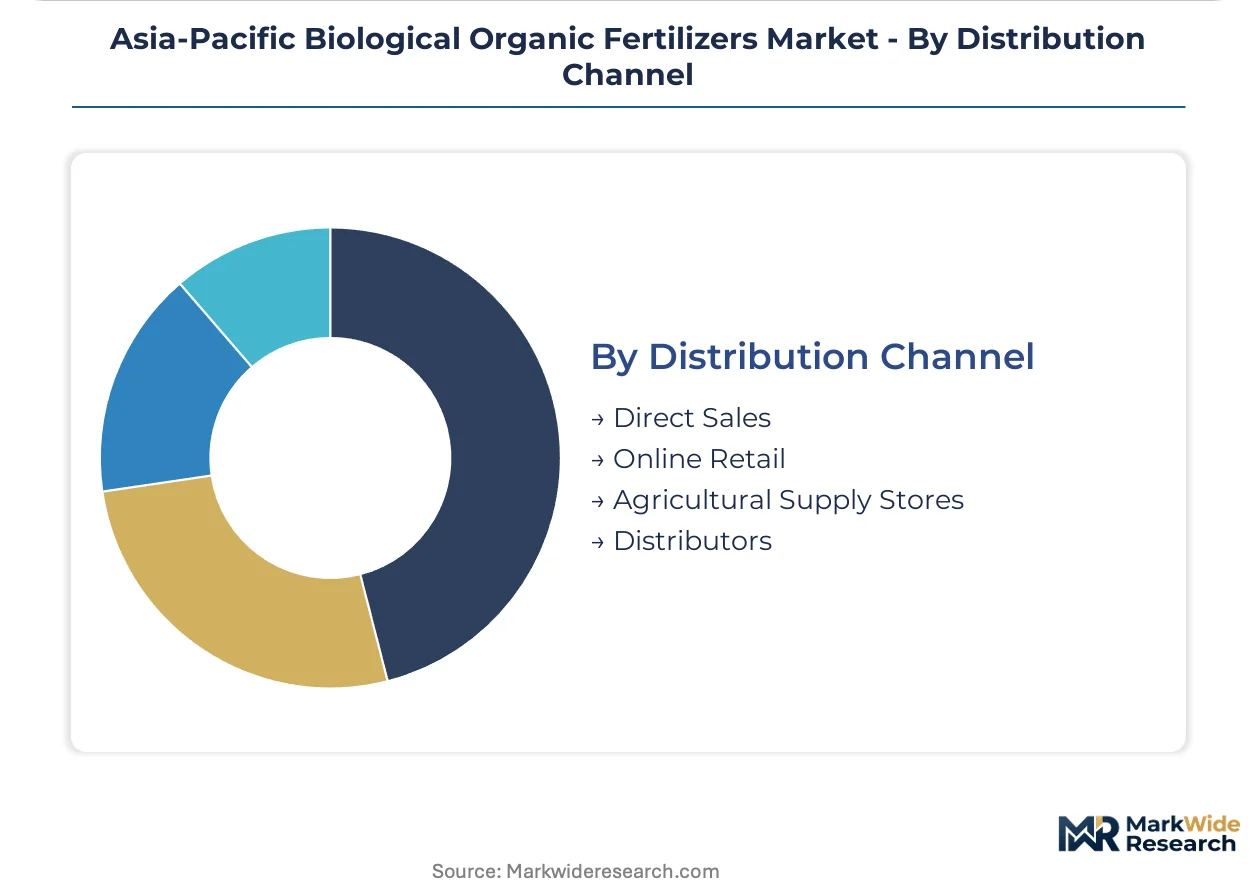
Distribution Channel:
Channel selection reflects buyer scale and technical support requirements, with direct procurement fragmenting traditional agrochemical distributor hierarchies.
- Direct Sales:Large-scale agricultural producers and greenhouse clusters bypass distributor markups through contract manufacturing arrangements with compost facilities.
- Agricultural Supply Stores:Provincial extension networks in Vietnam and India aggregate smallholder demand, though CFU enumeration skill gaps compromise quality assurance.
- Distributors:Traditional agrochemical networks aggregate biological inputs as secondary product lines, losing share to direct procurement.
- Online Retail:E-commerce platforms capture urban horticulturist demand for packaged home-garden formulations.
Direct sales channels capture the largest volume flow; online retail exhibits the most rapid expansion among non-traditional procurement pathways.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Shanghai's container throughput underwrites China's dominance in biological fertilizer ingredient imports, while Singapore's transshipment hub connects Indonesian guano exporters to Vietnamese compost manufacturers across the Mekong Delta.
India
State-level organic farming missions in Uttar Pradesh and Madhya Pradesh channel procurement toward certified biological inputs, creating guaranteed offtake corridors. India's BIS and FSSAI jointly govern organic input quality thresholds, extending certification timelines to 14-18 months. The Indo-Gangetic Plain anchors volume demand as wheat and rice farmers transition from synthetic chemicals.
China
GB 20287 standards enforce microbial fertilizer registration with field efficacy documentation, filtering low-viability products. SAMR compliance elevates technical barriers for cross-border suppliers while privileging domestic producers with captive research stations. The Yangtze River Delta concentrates manufacturing infrastructure for thermophilic starter culture production.
Vietnam
Rice cultivation across the Mekong Delta absorbs rising compost volumes as farmers confront soil degradation from decades of synthetic chemical application. Provincial extension networks aggregate smallholder demand, though CFU enumeration skill gaps compromise quality assurance. Ho Chi Minh City's port infrastructure enables direct procurement from Indonesian seaweed extract suppliers.
Australia
Precision fertigation systems across horticulture clusters displace broadcast application methods, favoring liquid biological formulations. The TGA-equivalent agricultural regulator mandates biosecurity clearance for imported inoculant strains, privileging domestic strain development capabilities. Queensland's greenhouse operators specify vermicompost by particle size distribution and microbial diversity indices.
Thailand
Greenhouse operators across Chiang Mai's cluster now contract directly with vermicompost facilities, bypassing traditional agrochemical distributor networks. Decades of intensive rice production in the Central Plains have degraded soil organic matter, accelerating compost adoption. Bangkok's logistics corridor connects domestic manufacturers to Cambodian and Laotian export markets.
Asia-Pacific Biological Organic Fertilizers Market Competitive Environment
Listed leaders compete with private specialists across distribution reach and regulatory compliance velocity. The vendor base separates into government-backed incumbents with established procurement channels, microbial technology specialists with strain library advantages, and regional cooperatives leveraging backward integration into raw material corridors. Competitive positioning depends on registration dossier preparation speed under China's GB 20287 and India's joint BIS-FSSAI frameworks. Capacity expansion and direct-to-farmer contracting represent the dominant competitive moves.
Within the government-backed tier, National Fertilizer Limited exemplifies distribution infrastructure scale, while Gujarat State Fertilizers & Chemicals Ltd occupies a position tied to port-accessible raw material corridors. Seek Biotechnology Co. Ltd represents the microbial technology specialist archetype, anchoring competitive positioning through subtropical soil condition expertise. These three entities collectively illustrate how regulatory compliance velocity and geographic raw material access determine market presence across the region.
| Leading Market Players |
|---|
| National Fertilizer Limited |
| Seek Biotechnology Co. Ltd |
| Gujarat State Fertilizers & Chemicals Ltd |
| Indian Farmers Fertiliser Cooperative Limited |
| AgriLife (India) Private Limited |
| IPL Biologicals Limited |
| Kiwa Biotech |
| Qingdao Hibong Industrial Technology Co.,Ltd. |
| Biostadt India Limited |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts between Vietnamese compost manufacturers and Thailand's greenhouse clusters lock in supply access while stabilizing unit economics against guano price volatility from Indonesian export quotas. These arrangements bundle volume commitments with quality specifications, creating price visibility that spot procurement cannot match.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates vermicompost with microbial diversity certification from bulk compost and untreated agricultural residues. Price differentiation hinges on CFU viability documentation and organic certification grade under India's PGS-India or China's GB standards. Cost compression in the economy tier is intensifying because provincial extension networks in Vietnam lack enumeration capabilities, forcing suppliers to absorb quality verification burdens. Agricultural producers across India's Indo-Gangetic Plain exhibit the highest price sensitivity, while Australian greenhouse operators prioritize batch consistency over per-ton savings.
Supply Chain Analysis
Port congestion at Shanghai and Singapore constrains container availability for Indonesian guano and Peruvian rock phosphate flowing to Vietnamese compost blenders. Raw material sourcing draws from Japanese and Dutch thermophilic strain libraries, Indonesian marine biomass corridors, and Gujarat's port-accessible organic residue networks. Single-source vulnerability concentrates in starter culture supply, where biosecurity clearance requirements fragment procurement options. Distribution runs through state-level organic farming missions in Uttar Pradesh and Madhya Pradesh, bypassing traditional agrochemical aggregators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Microbial formulation advances and regulatory harmonization under ASEAN standards are compressing product development cycles, creating a high-growth disruption window for suppliers with registration dossier velocity.
For Market Incumbents: Secure captive research station capabilities to accelerate GB 20287 and BIS-FSSAI approval timelines, as domestic Chinese and Indian producers already capture disproportionate registration velocity. Deepen backward integration into Gujarat's port-accessible raw material corridors or Vietnam's Mekong Delta residue streams to defend margin position against guano price volatility. Channel control through direct-to-farmer contracting in Thailand's Chiang Mai cluster insulates against distributor network erosion. For New Entrants and Emerging Players: Lead with liquid formulation development for Australian precision fertigation infrastructure, where irrigation convergence displaces broadcast methods and technical documentation requirements filter out commodity competitors. Target Indonesia's nascent organic certification harmonization with ASEAN standards, which alters import eligibility and opens procurement pathways for Vietnamese compost exporters. A go-to-market angle anchored to CFU viability guarantees during monsoon transport addresses a critical technical limitation that incumbent liquid suppliers have not solved. For Investors and Strategic Acquirers: Capital is best deployed toward microbial technology specialists with subtropical strain libraries and captive field efficacy documentation capabilities, as China's SAMR enforcement elevates technical barriers for cross-border entrants. The five-to-ten year viability window favors acquisition targets with established registration dossiers under multiple national frameworks. The signal to watch is GB 20287 approval velocity dispersion between domestic Chinese producers and cross-border suppliers, which indicates regulatory moat durability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Raw Material Corridors | Gujarat State Fertilizers leverages port access to stabilize guano and rock phosphate input costs. |
| Microbial Strain Library Expansion | Seek Biotechnology anchors competitive positioning through subtropical soil condition expertise. |
| Direct-to-Farmer Contracting | Thailand's greenhouse operators bypass distributor markups through vermicompost facility agreements. |
| Regulatory Dossier Acceleration | National Fertilizer Limited exploits government-backed distribution to sustain Punjab supply lines. |
| Liquid Formulation Fertigation Convergence | Australian horticulture clusters integrate biological inputs with drip irrigation infrastructure. |
Study Parameters
The analysis maps compost, vermicompost, seaweed extract, and microbial inoculant sub-sectors, each validated through compost facility operators, state agricultural department procurement officers, greenhouse managers, and regulatory affairs specialists at fertilizer registrants. Primary interviews with plant managers at thermophilic culture production sites and distribution channel partners in Vietnam's provincial networks combined with secondary validation from China's SAMR registration databases, India's BIS certification records, Australian biosecurity clearance filings, and ASEAN trade flow statistics. Bottom-up volume estimates from individual production facility capacities and top-down demand calibration from state-level organic farming mission budgets were triangulated for consistency.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled product type, end user, physical form, and distribution channel segmentation dimensions alongside regional regulatory cluster variations. CAGRs were derived from fitted growth curves incorporating input cost trajectories, certification timeline compression effects, and infrastructure penetration rates for precision fertigation systems. Industry-specific forecast inputs included monsoon seasonality impacts on CFU viability degradation and GB 20287 registration queue dynamics.
Forecasts assume regulatory continuity in China's SAMR enforcement, India's joint BIS-FSSAI framework, and Australia's TGA-equivalent agricultural biosecurity regime; material policy shifts would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bio-Agriculture
Horticulture Bioplastic Market
Bio-Agriculture
Nannochloropsis Market
Bio-Agriculture
United States Biocontrol Agents Market
Bio-Agriculture
Marine Biotechnology Market
Bio-Agriculture
Latin America Biopesticide Market
Bio-Agriculture
India Biostimulants Market
Bio-Agriculture
Bacterial Biopesticides Market
Bio-Agriculture
North America Agricultural Biologicals Market
Bio-Agriculture
Biofumigation Market
Bio-Agriculture
Silage Inoculant and Enzyme Market
Bio-Agriculture
Asia-Pacific Biocontrol Agents Market
Bio-Agriculture
Europe Plant-Based Biologics Market
Bio-Agriculture
Bionematicides Market
Bio-Agriculture
Artificial Insemination Market
Bio-Agriculture
Europe Agricultural Biologicals Market
Bio-Agriculture
Germany Biostimulants and Biopesticides Market