
 Australia Biopesticides Market | 2026-2036
Australia Biopesticides Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Biopesticides Market Outlook
Aftermarket service revenue for biological crop protection advisory is tilting toward integrated pest management program design. BASF leverages its global microbial strain library to anchor technical service contracts with Australian broadacre growers. Novozymes Australia specializes in fermentation-derived biocontrol agents that sustain premium positioning in horticultural segments. Nufarm Limited competes through distribution control across rural merchant networks, extending its reach into on-farm application guidance.
Biopesticides comprise living organisms, naturally occurring substances, and biochemical compounds formulated for pest, disease, and weed management in agricultural systems. Microbial products typically contain viable propagules of bacteria, fungi, or viruses at concentrations exceeding colony-forming unit thresholds specified for field efficacy. The primary commercial purpose centers on selective pest suppression that preserves beneficial insect populations and minimizes chemical residue in export-oriented produce. Microbial formulations occupy the dominant value share due to established manufacturing infrastructure and reproducible quality standards. Plant extracts represent the fastest-expanding category as extraction technologies improve yield consistency from native Australian botanical sources. Liquid formulations lead volume distribution through compatibility with existing spray equipment across Australian farming operations.
The Australian Pesticides and Veterinary Medicines Authority governs registration timelines and residue limits for biological active constituents entering commercial channels. APVMA streamlined assessment pathways for low-risk biological products are compressing market entry durations and redirecting R&D investment toward novel strain discovery. Organic certification standards administered by Australian Certified Organic and NASAA restrict allowable input lists, shaping product development priorities for domestic manufacturers. Stakeholders must monitor evolving export market MRL alignment between APVMA registrations and destination country standards for biological residues.
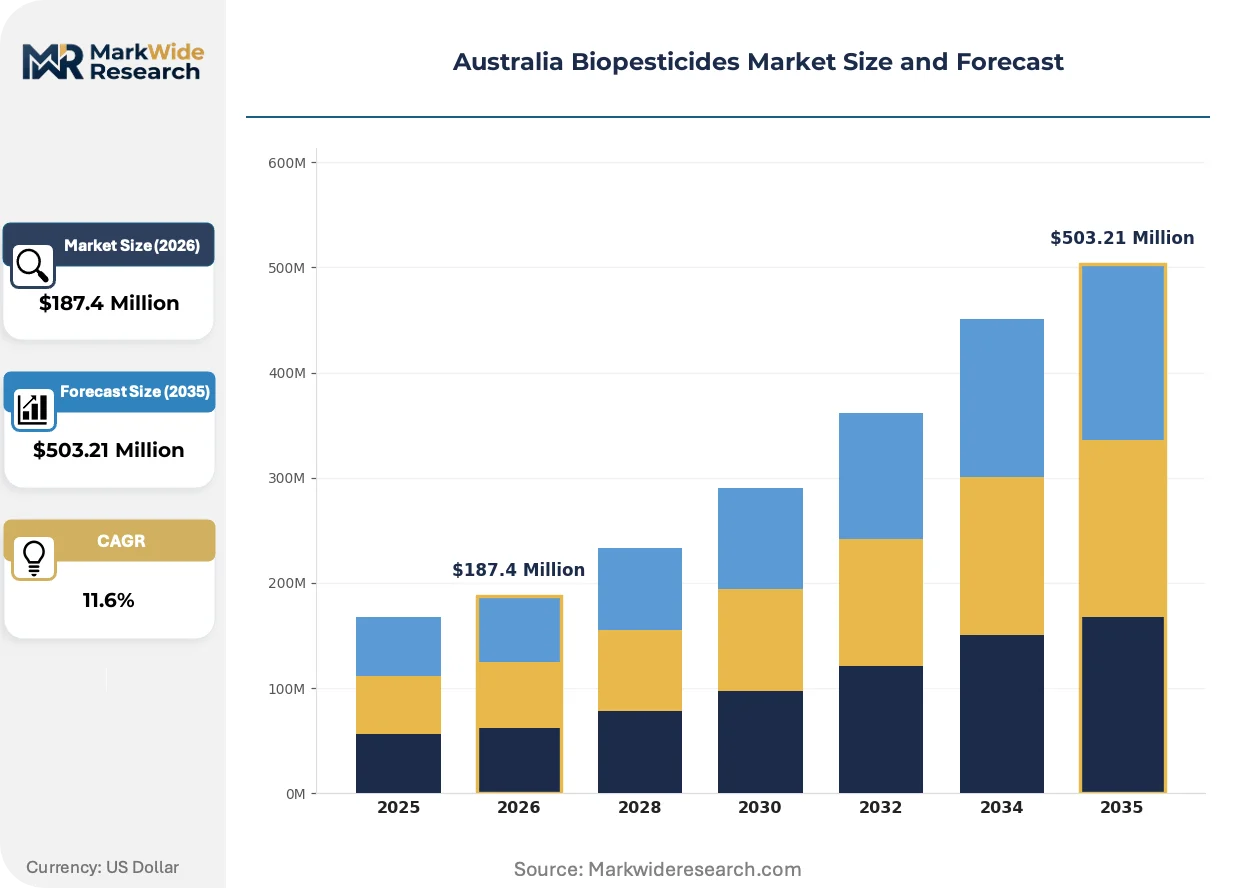
Market Dynamics
The Australian biopesticides sector pivots on APVMA's compressed assessment timelines for low-risk biological actives, which redirect manufacturer investment toward novel microbial strain discovery and away from prolonged registration delays.
Growth Catalysts
- Streamlined APVMA pathways:Low-risk biological product assessments now compress market entry durations, accelerating commercialization cycles for domestic manufacturers targeting viticulture and broadacre sectors.
- Viticulture sector pull:Export-oriented wine producers demand residue-free crop protection to satisfy European and Asian market standards, creating sustained procurement volume for microbial formulations.
- Native botanical extraction:Improved yield consistency from Australian plant sources enables plant-extract biopesticide categories to expand manufacturing scale and formulation reliability.
Market Restraints
- Fermentation input volatility:Specialized nutrient media and sterile propagation substrates for microbial production face supply concentration with limited domestic manufacturing capacity.
- Technical shelf-life limitations:Viable propagule stability in bacterial and fungal formulations constrains distribution radius and storage infrastructure requirements for rural merchant networks.
- Substitution from synthetic chemistry:Conventional pesticide price compression during commodity downturns pulls cost-sensitive broadacre growers away from biological premiums.
Strategic Opportunities
- Tasmanian organic conversion:Underpenetrated apple and berry production regions present white space for integrated pest management program expansion with certified biological inputs.
- Drone application convergence:Aerial spraying technology integration with ultra-low-volume biopesticide formulations opens precision application channels inaccessible to ground-based equipment.
- NASAA certification alignment:Organic standard harmonization across state borders reduces compliance duplication costs for manufacturers serving multi-state grower cooperatives.
Industry Challenges
- Microbial formulation expertise gap:Qualified fermentation scientists and biocontrol field specialists remain concentrated in metropolitan research institutions, limiting regional technical service capacity.
- Multi-jurisdictional residue alignment:APVMA registration outputs must synchronize with destination country maximum residue limits for biological actives, extending compliance timelines for export-focused producers.
- Legacy spray equipment incompatibility:Existing farm machinery calibrated for synthetic chemical rheology requires recalibration or replacement to handle living organism suspension properties without viability loss.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Biopesticides Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $503.21 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microbial, Plant Extracts, Biochemical, Insecticidal Application: Agricultural, Horticultural, Turf, Ornamental Formulation: Liquid, Granular, Powder, Emulsifiable Concentrate Distribution Channel: Direct Sales, Online Retail, Distributors, Agricultural Stores |
| Companies Covered | BASF, Novozymes Australia, Valent Biosciences Corp, ADAMA Australia, Certis LLC, EID Parry, Emery Oleochemicals, Nufarm Limited, Bayer CropScience, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Biopesticides Market Strategic Shifts
Biological crop protection in Australia is migrating toward precision-enabled delivery systems and fermentation-optimized actives, compressing the performance gap with synthetic chemistry while preserving ecological selectivity advantages.
Encapsulation technology for fungal spores and bacterial endospores is migrating from experimental pilot scales to commercial manufacturing lines. Broadacre growers in South Australia and Victoria adopt these stabilized formulations at accelerating pace due to extended field persistence. The technology is migrating from niche horticultural applications to mainstream cereal and oilseed programs, enabling seasonal treatment windows previously unachievable with unprotected microbial propagules.
APVMA's biological active constituent assessment reforms are compressing registration timelines from multi-year cycles to streamlined low-risk pathways. This regulatory recalibration redirects R&D expenditure toward strain discovery rather than dossier preparation. Horticultural segments with premium export exposure respond fastest, prioritizing novel Bacillus and Trichoderma formulations for residue-sensitive produce categories.
Aftermarket advisory contracts are unbundling from product supply agreements across rural merchant networks. Grower cooperatives in Queensland and Western Australia now procure standalone integrated pest management design services separate from input purchasing. This service unbundling concentrates technical expertise with manufacturers possessing global microbial strain libraries, compressing margins for distribution-only intermediaries.
Australia Biopesticides Market Segmentation
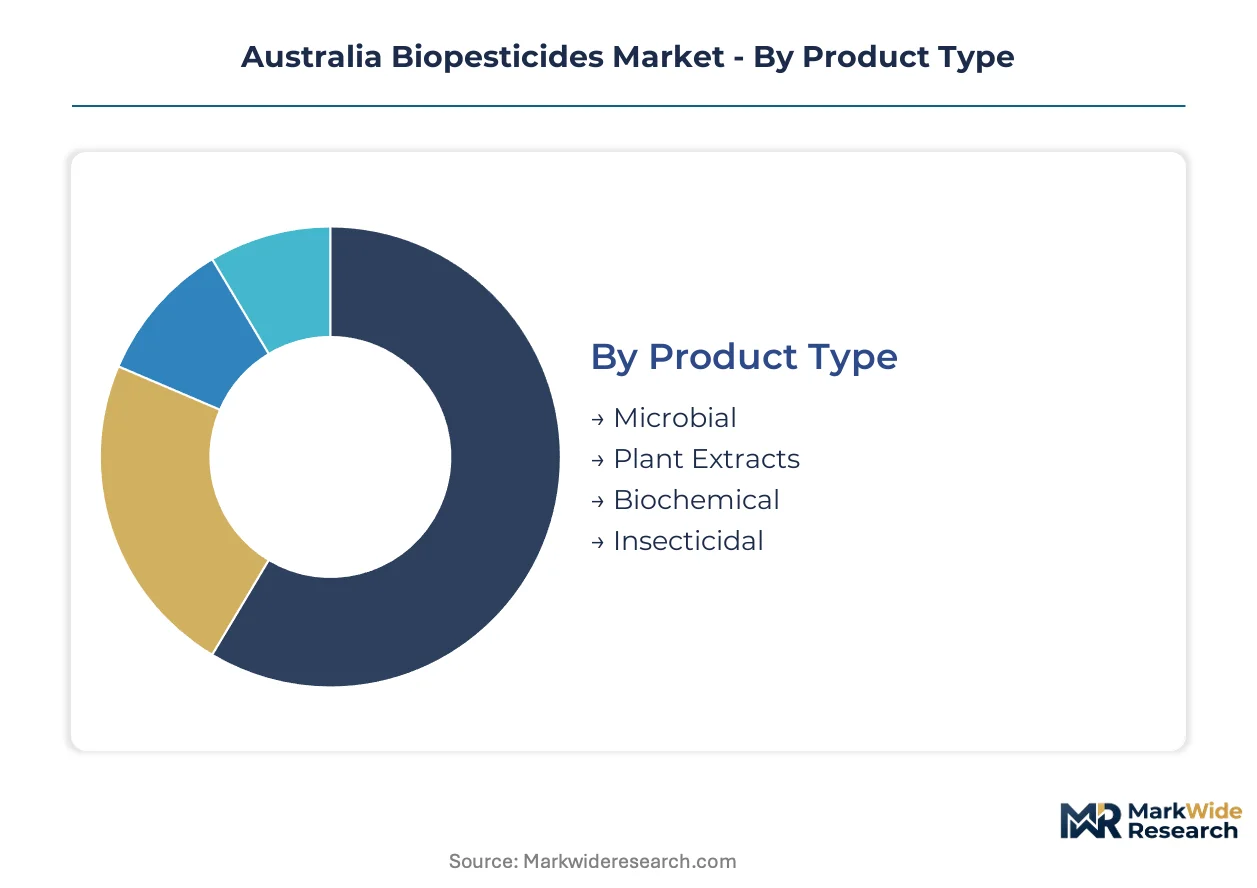
Segmentation across the Australia Biopesticides Market reveals how formulation chemistry, application context, and procurement pathways shape manufacturer positioning. Each dimension carries distinct technical requirements and regulatory implications under APVMA oversight.
Product Type:
Use cases span from broadacre soil inoculants to precision horticultural sprays, with biological complexity driving differentiation in manufacturing investment and field performance.
- Microbial:Formulations contain viable propagules of bacteria, fungi, or viruses at concentrations exceeding colony-forming unit thresholds for field efficacy. South Australian viticulture operations anchor demand for Bacillus thuringiensis and Trichoderma-based products, pressured by European export MRL compliance requirements. The dominant share belongs to Microbial, while Plant Extracts is closing the gap fastest.
- Plant Extracts:Native Australian botanical sources including eucalyptus, tea tree, and quandong deliver terpenoid and phenolic active compounds. Victoria's organic berry producers drive procurement volume as extraction yield consistency improves through supercritical CO2 processing.
- Biochemical:Naturally occurring substances including pheromones, plant growth regulators, and fatty acid derivatives disrupt pest behavior without direct toxicity. Row crop applications in Western Australia concentrate demand for mating disruption technologies.
- Insecticidal:Entomopathogenic nematodes and predatory mite formulations target specific pest complexes in protected cropping systems. Queensland greenhouse vegetable producers sustain niche procurement for Steinernema and Phytoseiulus products.
Microbial formulations command the dominant value position through established fermentation infrastructure, while plant extract categories gain manufacturing scale from improved domestic botanical sourcing.
Application:
End-use contexts range from export-oriented premium produce to amenity turf maintenance, with residue sensitivity and labor intensity shaping biological adoption rates.
- Agricultural:Broadacre cereal, oilseed, and pulse production integrates microbial seed treatments and in-furrow applications. Victoria and South Australia lead national uptake as integrated pest management adoption accelerates in wheat and canola rotations.
- Horticultural:Intensive fruit, vegetable, and nut production demands zero-residue crop protection for premium market access. Tasmania's apple and cherry sectors present underpenetrated white space for certified biological program expansion.
- Turf:Golf course and sports field managers deploy entomopathogenic nematodes against scarab larvae and fungal biocontrols for dollar spot suppression. Metropolitan Melbourne and Sydney facilities anchor procurement volume.
- Ornamental:Nursery and floriculture operations utilize microbial fungicides and insect growth regulators for aesthetic crop protection. Queensland propagation facilities concentrate demand for thrips and mite management solutions.
Agricultural applications generate the largest absolute volume, though horticultural segments sustain the steepest expansion trajectory from export market residue pressures.
Formulation:
Physical delivery formats must balance propagule viability, spray equipment compatibility, and storage stability across diverse Australian farming operations.
- Liquid:Aqueous suspensions and oil-based emulsions dominate volume distribution through compatibility with existing boom spray and airblast equipment. Compatibility with drone application systems is accelerating adoption in Queensland broadacre operations.
- Granular:Clay-carrier and polymer-based formulations protect fungal spores and bacterial endospores from desiccation and UV degradation. South Australian viticulture favors granular Trichoderma for soil incorporation at planting.
- Powder:Dry flowable and wettable powder formats reduce transport costs and extend shelf life in remote storage conditions. Western Australian grain belt merchants stock powder formulations for on-farm reconstitution.
- Emulsifiable Concentrate:Oil-phase actives with surfactant packages enhance cuticular penetration and rainfastness. Horticultural segments in Victoria specify EC formats for systemic uptake in perennial crops.
Liquid formulations lead volume distribution through equipment compatibility, while granular formats gain share from extended field persistence in dryland cropping zones.
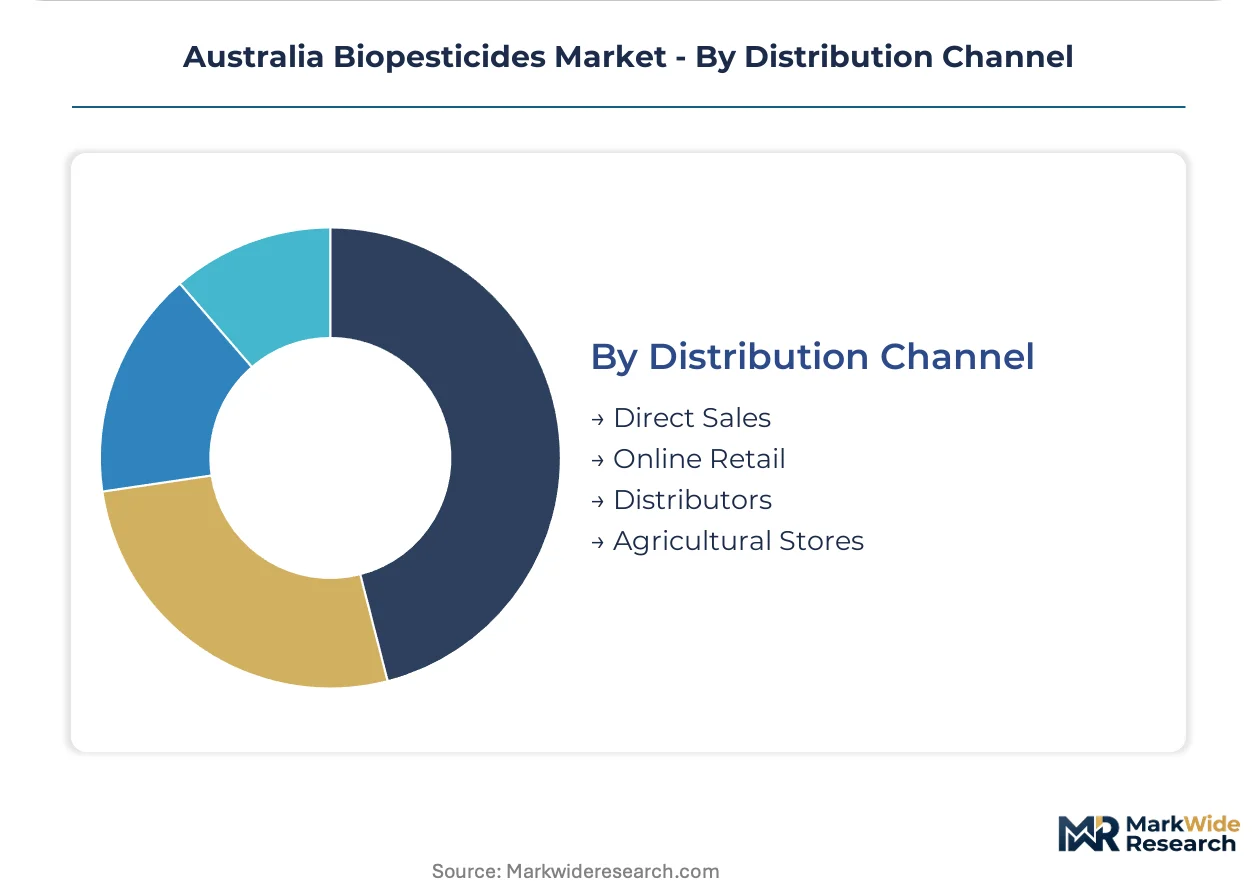
Distribution Channel:
Procurement pathways reflect the technical service intensity required for biological product success, unbundling advisory from pure product supply.
- Direct Sales:Manufacturer field teams contract directly with large-scale grower cooperatives and corporate farming operations for integrated pest management program design. BASF and Novozymes Australia anchor technical service contracts through this channel.
- Online Retail:E-commerce platforms serve smallholder and peri-urban producers with packaged consumer-grade biological products. Urban agriculture and backyard orchard segments drive transaction volume.
- Distributors:Regional merchant networks including Nufarm Limited extend reach into on-farm application guidance across rural networks. Queensland and Western Australia rely heavily on distributor technical capacity.
- Agricultural Stores:Independent rural supply stores stock fast-moving biocontrol SKUs for immediate grower procurement. Victorian and South Australian grain belts maintain dense agricultural store networks.
Distributor networks capture the dominant procurement volume, though direct sales channels are expanding fastest as manufacturers unbundle advisory services from product supply agreements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity in Australian biopesticides demand diverges sharply between export-oriented horticulture and commodity-exposed broadacre operations. Premium vineyard and berry producers absorb biological input premiums to secure residue-free certification, while wheat and canola growers retreat to synthetic chemistry during grain price troughs.
Victoria
Organic berry production and premium wine grape cultivation drive concentrated procurement of microbial formulations. APVMA registration reforms accelerate product launches for viticulture-specific applications. The Yarra Valley and Mornington Peninsula wine regions anchor technical service deployment by manufacturers with global strain libraries.
South Australia
Integrated pest management adoption in wheat-canola rotations exceeds national averages, sustaining seed treatment and in-furrow microbial demand. The state's wine export dependency enforces strict residue compliance, funneling grower expenditure toward certified biological inputs. Adelaide Plains horticulture clusters favor granular Trichoderma formulations for soil incorporation.
Queensland
Protected cropping and greenhouse vegetable production generate niche demand for entomopathogenic nematodes and predatory mite formulations. Drone application compatibility is accelerating liquid biopesticide adoption in coastal broadacre zones. Grower cooperatives in the Lockyer Valley procure standalone integrated pest management advisory separate from product supply.
Western Australia
Remote grain belt operations favor powder formulations for on-farm reconstitution and extended storage stability. The wheatbelt's sparse distribution infrastructure constrains viable propagule shelf-life requirements. Regional merchant networks extend technical guidance reach where manufacturer field teams cannot deploy economically.
Tasmania
Underpenetrated apple and cherry sectors present expansion white space for certified organic program conversion. NASAA certification alignment reduces compliance costs for manufacturers serving multi-state cooperatives. Cool-climate horticulture's export orientation mirrors Victorian residue sensitivity patterns.
Australia Biopesticides Market Competitive Environment
Capability concentration sits with multinational microbial strain libraries; scale advantage sits with distribution-anchored domestic networks. The market structures around three tiers: global agrochemical conglomerates with biological portfolios, specialized fermentation-derived biocontrol manufacturers, and regional distribution intermediaries extending technical reach. Competitive maneuvering concentrates on unbundling advisory services from product supply and compressing APVMA registration timelines through low-risk biological pathways.
Among global agrochemical conglomerates, BASF anchors technical service contracts through direct sales channels with large-scale grower cooperatives. Novozymes Australia exemplifies the fermentation-specialist archetype, occupying premium positioning in horticultural segments through biocontrol agent manufacturing. Nufarm Limited represents the distribution-integrated tier, extending reach into on-farm application guidance across rural merchant networks in Queensland and Western Australia.
| Leading Market Players |
|---|
| BASF |
| Novozymes Australia |
| Valent Biosciences Corp |
| ADAMA Australia |
| Certis LLC |
| EID Parry |
| Emery Oleochemicals |
| Nufarm Limited |
| Bayer CropScience |
| Others |
Value Chain & Pricing Dynamics
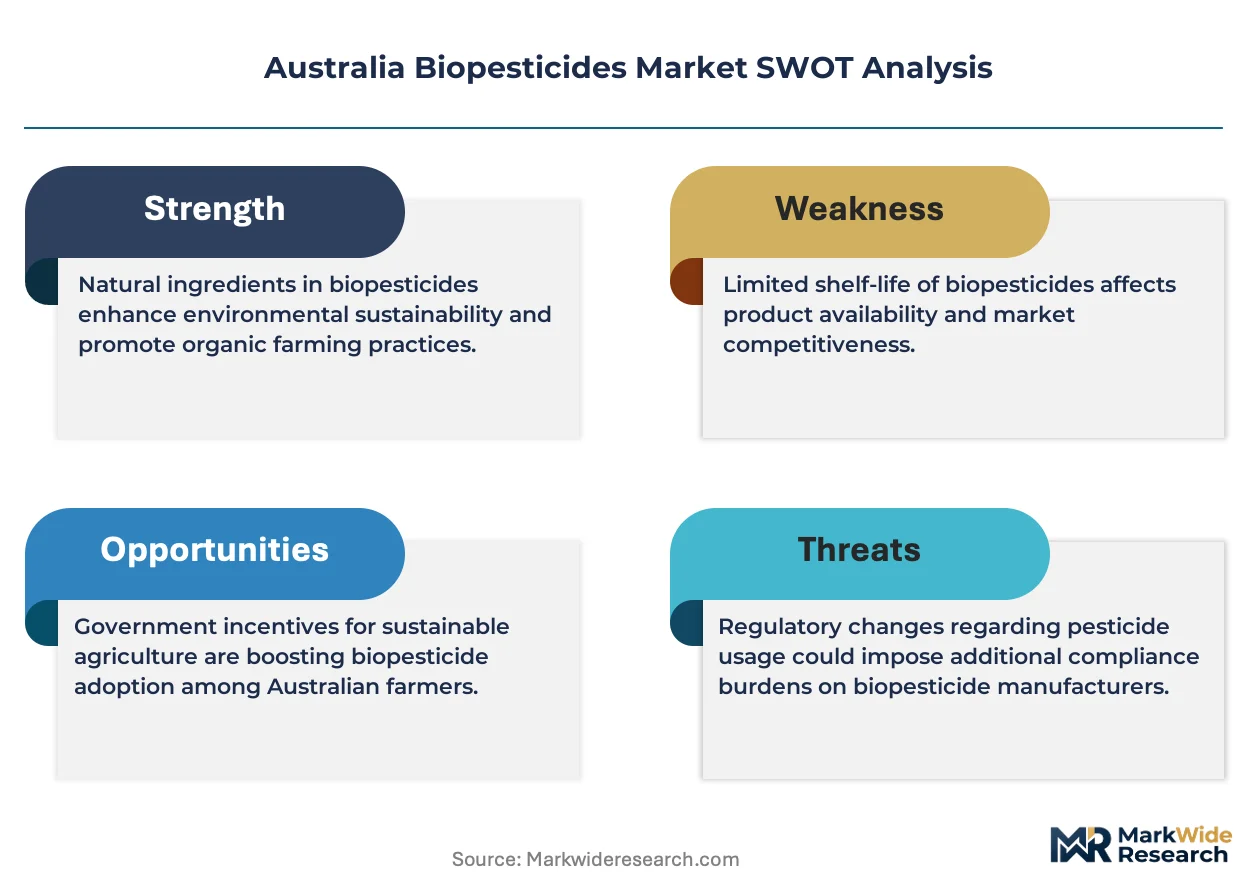
APVMA registration bottlenecks for novel microbial strains compress both pricing power for first-movers and supply chain flexibility for domestic manufacturers, forcing tiered spreads between certified organic-grade formulations and conventional biological inputs.
Pricing Analysis
Aftermarket technical service contracts for integrated pest management program design command lifetime value premiums exceeding standalone product sales. Three-tier pricing structure across premium certified-organic, standard commercial-grade, and economy generic formulations separates residue-sensitive export producers from commodity broadacre growers. Pricing pressure stems from synthetic chemistry price compression during grain price troughs, eroding biological adoption in wheat-canola rotations. Export-oriented viticulture operations in South Australia exhibit lowest price sensitivity, while Western Australian grain belt growers retreat fastest to conventional chemistry during margin squeezes.
Supply Chain Analysis
Export-control restrictions on specialized fermentation equipment from Germany and Denmark constrain domestic manufacturing scale-up for novel biocontrol strains. Active ingredient production concentrates in China, India, and the United States, with Australian formulators dependent on imported bacterial and fungal propagule concentrates. Specialized nutrient media and sterile propagation substrates face single-source vulnerability from limited domestic fermentation infrastructure. Distribution runs through Nufarm Limited's rural merchant networks and BASF's direct sales channels to large-scale grower cooperatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation creates entry niches as grower cooperatives unbundle advisory services from product supply, splintering procurement relationships and opening technical service white space for specialized fermentation manufacturers.
For Market Incumbents: Insulate market position through backward integration into fermentation infrastructure and captive supply of specialized nutrient media, countering input volatility from single-source dependencies. Deepen technical service contracts with Victorian viticulture and South Australian broadacre cooperatives to lock out distribution-only competitors. Prioritize APVMA pre-submission consultations to compress registration timelines for novel Bacillus and Trichoderma strains. For New Entrants and Emerging Players: Establish a beachhead in Tasmania's underpenetrated apple and cherry sectors through NASAA-certified organic program partnerships with cool-climate horticulture exporters. Target drone-compatible liquid formulation development for Queensland broadacre cooperatives seeking precision application channels. Deploy standalone integrated pest management advisory services to capture unbundled procurement demand from Western Australian grower cooperatives. For Investors and Strategic Acquirers: APVMA's streamlined low-risk biological assessment pathways reshape the acquisition landscape toward fermentation-specialist manufacturers with strain libraries and existing technical service deployment. Five-to-ten year viability favors targets with captive microbial propagation capacity and direct sales relationships with export-oriented horticulture segments. Monitor APVMA registration output velocity as the primary inflection signal for biological product commercialization cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Infrastructure | Captive production of bacterial propagules reduces dependency on Chinese nutrient media suppliers. |
| Drone Application Compatibility Development | Ultra-low-volume liquid formulations unlock Queensland broadacre precision spraying channels. |
| NASAA Certification Alignment Investment | Harmonized organic standards reduce compliance duplication for multi-state grower cooperatives. |
| Technical Service Contract Expansion | Unbundled advisory procurement from Victorian viticulture operations displaces distribution-only intermediaries. |
| Encapsulation Technology Scale-Up | Stabilized fungal spore formulations extend field persistence in South Australian dryland cropping zones. |
Study Parameters
Desk research of APVMA registration databases, Australian Bureau of Agricultural and Resource Economics trade statistics, and NASAA organic certification records preceded structured interviews with fermentation R&D directors, rural merchant network managers, viticulture technical officers, and broadacre grower cooperative procurement leads. Primary fieldwork with biological input manufacturers and secondary validation against customs data and industry association publications enabled bottom-up volume triangulation with top-down value estimation.
Assumptions held APVMA regulatory reform implementation and organic certification standard harmonization as fixed conditions across the projection horizon, while varying commodity grain price cycles and European export market MRL stringency. Segmentation modeling spanned product type, application context, formulation chemistry, and distribution channel dimensions. CAGRs derived from logistic adoption curves fitted to historical biological penetration rates in viticulture and broadacre rotations, calibrated against fermentation capacity expansion timelines and drone application technology diffusion patterns.
Macroeconomic conditions sit as an overlay; deviation in Australian dollar exchange rates against the euro and yen, or structural shifts in Chinese fermentation input export pricing, would shift the trajectory. Forecasts reflect these documented assumptions; material shifts in APVMA assessment pathway throughput or European MRL alignment requirements for biological residues would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bio-Agriculture
Asia-Pacific Biopesticides Market
Bio-Agriculture
Bio Rational Fungicides Market
Bio-Agriculture
Italy Biopesticides Market
Bio-Agriculture
Poultry Manure Biofertilizers Market
Bio-Agriculture
Asia-Pacific Biostimulants Market
Bio-Agriculture
Africa Biofertilizer Market
Bio-Agriculture
Brazil Biostimulants Market
Bio-Agriculture
Latin America Biopesticide Market
Bio-Agriculture
Biofertilizers Market
Bio-Agriculture
North America Biostimulants Market
Bio-Agriculture
Plant Based Biosurfactants Market
Bio-Agriculture
United States Biofertilizer Market
Bio-Agriculture
Argentina Biopesticides Market
Bio-Agriculture
South America Biological Organic Fertilizers Market
Bio-Agriculture
Transgenic Animals Market
Bio-Agriculture
Europe Feed Phytogenics Market