
 Ulva Lactuca Market | 2026-2036
Ulva Lactuca Market Size, Share, and Industry Trends Forecast 2026-2036
Ulva Lactuca Market Insights
The capital-intensity divergence between industrial-scale offshore cultivators and small-batch coastal harvesters is collapsing as automated long-line systems and AI-monitored sea farms slash unit economics for mid-tier entrants. Nordic SeaFarm leverages its integrated North Sea cultivation and processing infrastructure to supply consistent biomass volumes to European food manufacturers. Cargill Incorporated anchors its position through backward integration into Norwegian seaweed farming partnerships, securing captive supply for hydrocolloid extraction. Qingdao Haixingyuan Biotechnology Co., Ltd competes on processed powder and extract exports, dominating price-sensitive Asian nutraceutical channels.
Ulva lactuca, commonly termed sea lettuce, is a green macroalga containing approximately 15-25% protein by dry weight, rich in ulvan polysaccharides, and cultivated via suspended rope or tank-based systems for biomass harvest. Its primary commercial purpose centers on functional food ingredients, cosmetic bioactives, and sustainable protein feed additives. Dried and powder forms command the deepest margin pools due to extended shelf stability and concentrated active content for formulation industries. Extract-grade product types represent the fastest-growing category as cosmetics and nutraceutical end users prioritize standardized ulvan and bioactive peptide concentrations over raw bulk biomass.
EFSA Novel Food approvals and EU Algae Initiative funding frameworks shape market access timelines for new Ulva lactuca suppliers entering European food and supplement channels. China's SAMR and GB standards for edible algae establish quality thresholds that govern import eligibility and domestic distribution rights for processed seaweed goods. Coastal permitting regimes under Norway's Directorate of Fisheries and Ireland's Sea-Fisheries Protection Authority directly control licensed cultivation area expansion. Stakeholders must monitor regulatory divergence between jurisdictions on heavy-metal thresholds and organic certification standards to avoid supply chain disqualification.
Market Dynamics
Automated long-line cultivation systems and AI-monitored sea farms are collapsing the capital barrier between industrial offshore operators and small-batch coastal harvesters, redrawing competitive boundaries across the Ulva lactuca supply base.
Growth Catalysts
- EFSA Novel Food streamlining:Revised approval pathways under the EU Algae Initiative compress time-to-market for food-grade ulvan ingredients, accelerating supplier entry into European functional food channels.
- Marine-derived cosmetic actives:South Korean cosmetics formulators are scaling procurement of standardized Ulva lactuca extracts for bioactive peptide and ulvan polysaccharide formulations in premium skincare lines.
- Shandong aquaculture clustering:Coastal zone concentration in China's Shandong province generates economies of scale in biomass harvesting and primary processing for export-oriented dried powder production.
Market Restraints
- Heavy-metal threshold divergence:Inconsistent cadmium and lead limits between EU EFSA, China's SAMR GB standards, and other national regimes force dual-certification costs on suppliers serving multiple jurisdictions.
- Input cost volatility:Seeded rope substrate and automated monitoring hardware prices fluctuate with semiconductor and synthetic fiber supply chains, pressuring mid-tier cultivator margins.
- Protein concentrate competition:Soy and pea protein isolates maintain cost advantages in feed additive applications, limiting Ulva lactuca penetration in price-sensitive animal nutrition contracts.
Strategic Opportunities
- India nutraceutical white space:FSSAI regulatory frameworks for edible algae remain underdeveloped relative to plant-extract categories, creating first-mover positioning for compliant biomass suppliers.
- Biorefinery technology convergence:Integrated extraction platforms combining ulvan separation with protein concentration and mineral recovery are unlocking full-biomass valorization models previously uneconomical at scale.
- Direct-to-formulator channels:Cosmetics and supplement manufacturers are bypassing traditional ingredient distributors to contract directly with cultivators for traceable, certified extract supply.
Industry Challenges
- Phycologist talent scarcity:Specialized expertise in macroalgal physiology and offshore farm management concentrates in Nordic and East Asian academic institutions, constraining expansion into emerging cultivation zones.
- Organic certification timeline compression:Multi-year transition periods for wild-harvested biomass to meet EU organic aquaculture standards delay premium pricing realization for new market entrants.
- Legacy ERP integration friction:Coastal harvesters adopting automated monitoring systems face data architecture mismatches with established food manufacturer traceability platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ulva Lactuca Market |
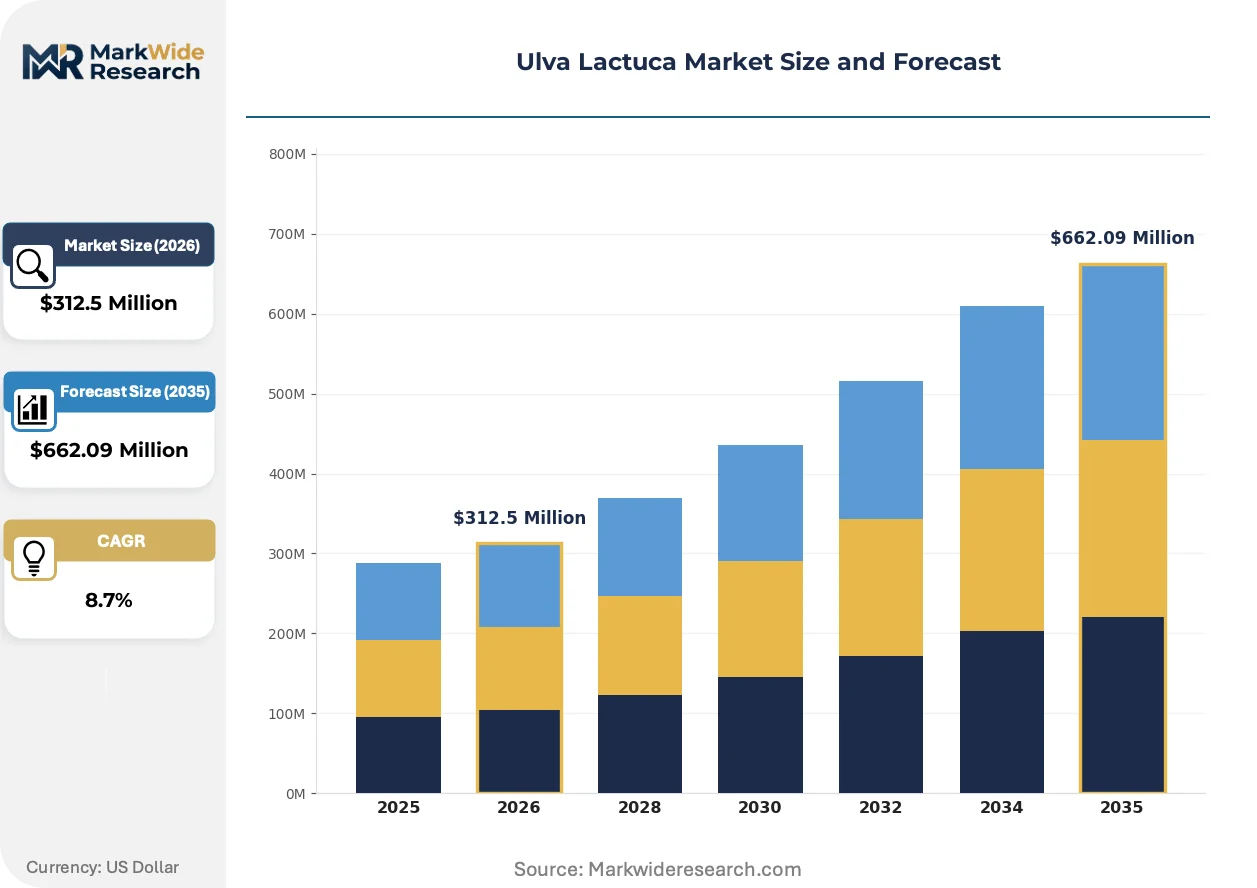
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $662.09 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fresh, Dried, Powder, Extract Application: Food Industry, Cosmetics, Nutraceuticals, Animal Feed Form: Whole Leaf, Flakes, Granules, Paste End User: Restaurants, Food Manufacturers, Retailers, Dietary Supplements |
| Companies Covered | Nordic SeaFarm, Algaia, Ocean Harvest Technology, Mara Seaweed, Cargill Incorporated, Acadian Seaplants Limited, Qingdao Haixingyuan Biotechnology Co., Ltd, CP Kelco U.S. Inc., Connemara Seaweed Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ulva Lactuca Market Trends and Innovations
Processing technology advances and regulatory harmonization efforts are converging to reshape how Ulva lactuca biomass moves from sea farms to formulated end products across food, cosmetic, and feed applications.
Photobioreactor-assisted tank cultivation is fragmenting the traditional seasonal dependence of open-water harvesting. Cosmetics laboratories in Seoul and Busan are adopting year-round contract supply of standardized ulvan concentrations. This controlled-environment approach is fragmenting regional supply monopolies held by North Atlantic wild harvesters.
REACH registration requirements for novel polysaccharide extracts are tightening purity documentation standards for EU market access. ECHA guidance on marine-derived polymer classifications is forcing reformulation of technical datasheets across extract suppliers. German and French ingredient distributors are demanding third-party ulvan molecular-weight certification before contract renewal.
Ingredient buyers are consolidating supplier rosters around vertically integrated cultivator-processors with captive extraction capability. Direct contracting replaces spot-market biomass purchasing for nutraceutical manufacturers in Oslo and Copenhagen. This concentration pattern is most visible in Norway's processed seaweed ingredient trade, where long-term offtake agreements now dominate volume planning.
Ulva Lactuca Market Segmentation
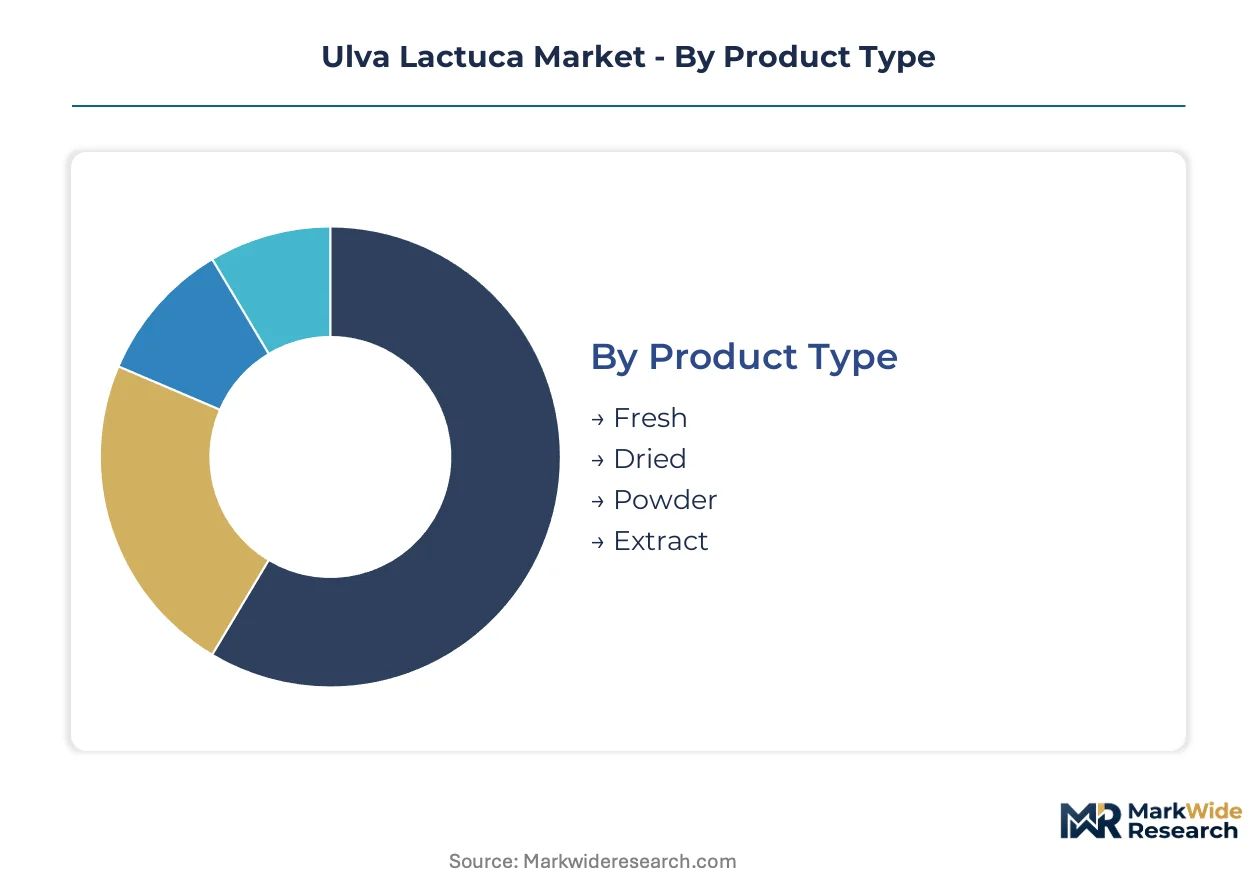
Ulva lactuca supply chains bifurcate sharply between bulk biomass commodities and refined extract value pools. Processing intensity and certification requirements determine margin capture across each segment boundary.
Product Type:
Domestic consumption clusters around perishable fresh biomass, while export channels concentrate in shelf-stable processed grades.
- Fresh:Live-harvested biomass with 85-95% moisture content requires cold-chain logistics within 72 hours of collection. Norwegian coastal restaurants and Seoul specialty retailers absorb volumes from Skagerrak and Jeju Island harvest zones. Perishability limits geographic radius and caps pricing power.
- Extract:Standardized ulvan polysaccharide and bioactive peptide concentrates command premium positioning in cosmetics and nutraceutical formulation. South Korean skincare manufacturers in Seoul and Busan are scaling procurement of certified extract grades with defined molecular weight profiles. EFSA Novel Food approval requirements filter supplier eligibility for European food-grade applications.
- Dried:Dehydrated whole thallus biomass with 8-12% residual moisture enables ocean freight economics for Asian nutraceutical processors.
- Powder:Milled particle sizes from 40-200 mesh serve ingredient blending applications in functional food manufacturing.
Dried and powder forms command the established base. The steepest expansion runs through Extract.
Application:
Cosmetics and nutraceutical end uses concentrate demand for traceable, certified supply chains with documented active compound concentrations.
- Cosmetics:Marine-derived bioactive formulations leverage ulvan's film-forming and moisture-retention properties in premium skincare. South Korean formulators specify peptide-rich extracts for anti-aging product lines. REACH registration requirements under ECHA tighten purity documentation for EU market access.
- Nutraceuticals:Capsule and tablet applications emphasize protein content and mineral bioavailability claims. Oslo and Copenhagen manufacturers contract directly with Norwegian cultivators for organic-certified biomass. China's SAMR GB standards establish heavy-metal thresholds that govern import eligibility.
- Food Industry:Functional ingredient applications span soups, salads, and novel food formulations seeking EFSA approval.
- Animal Feed:Sustainable protein additive positioning competes against soy and pea isolates in price-sensitive aquaculture and livestock nutrition contracts.
Food Industry commands the established base. The steepest expansion runs through Cosmetics.
Form:
Processing sophistication separates commodity whole-leaf exports from value-added flake and granule grades targeting specific manufacturing workflows.
- Whole Leaf:Minimally processed thallus biomass retains structural integrity for visual presentation in restaurant applications. Irish and Norwegian harvesters supply European food service distributors with wild-harvested material. Organic certification timelines under EU aquaculture standards delay premium pricing realization.
- Flakes:Dehydrated fragments rehydrate rapidly in soup and sauce formulations. Shandong processors dominate export volumes to Asian instant food manufacturers. Standardized flake dimensions enable automated dosing in manufacturing lines.
- Granules:Consistent particle sizing supports uniform dispersion in dry-mix applications.
- Paste:Stabilized aqueous preparations serve ready-to-use ingredient positioning in commercial kitchens.
Whole Leaf commands the established base. The steepest expansion runs through Flakes.
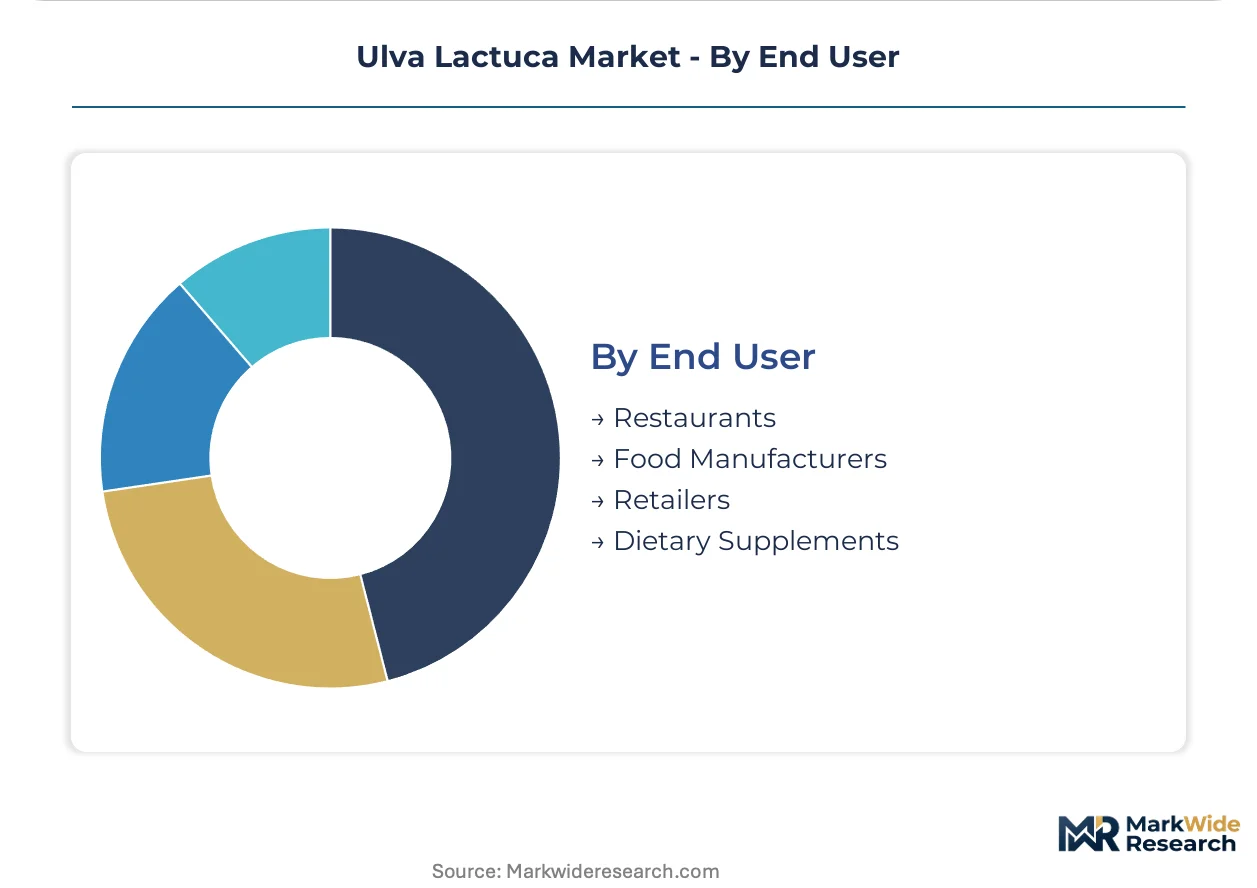
End User:
Food manufacturers and dietary supplement brands drive contract standardization, while restaurants and retailers accept greater supply variability.
- Food Manufacturers:Industrial-scale processors in Germany and France demand batch-consistent biomass with documented heavy-metal and microbiological compliance. Long-term offtake agreements with Norwegian cultivator-processors are displacing spot-market purchasing. ERP integration requirements filter supplier technical capabilities.
- Dietary Supplements:Capsule and tablet brands prioritize certified organic supply with validated active compound concentrations. Direct contracting with extraction-capable cultivators shortens traceability chains. India's FSSAI frameworks for edible algae remain underdeveloped, creating first-mover positioning opportunities.
- Restaurants:Fresh and minimally processed forms serve culinary presentation and texture applications.
- Retailers:Packaged dried and powder products reach consumer channels through specialty and health-food distribution.
Restaurants command the established base. The steepest expansion runs through Dietary Supplements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity diverges sharply across cultivation zones. European buyers absorb premium extract grades with certified traceability, while Asian processors prioritize dried biomass volumes at compressed margins.
Norway
Seaweed aquaculture licensing under the Directorate of Fisheries constrains expansion in Nordland and Trøndelag counties. The government's blue bioeconomy funding accelerates automated long-line system deployment. Bergen and Stavanger host integrated cultivator-processor clusters supplying hydrocolloid extractors.
China
Shandong province processors dominate dried powder export volumes to nutraceutical channels. SAMR GB standards for edible algae establish cadmium thresholds that filter import eligibility. Qingdao and Yantai concentration generates economies of scale in primary processing infrastructure.
South Korea
Cosmetics formulators in Seoul and Busan scale procurement of standardized ulvan extracts for marine-derived skincare actives. MFDS cosmetic ingredient regulations tighten documentation requirements for bioactive peptide concentrations. Jeju Island coastal zones supply fresh biomass to domestic specialty retailers.
Ireland
Wild-harvested organic certification under EU aquaculture standards delays premium pricing realization for Atlantic coast harvesters. The Sea-Fisheries Protection Authority controls licensed collection areas in Galway and Mayo. Connemara processors supply European food service distributors with whole-leaf grades.
United States
Specialty supplement brands in California and Oregon contract for traceable biomass with documented heavy-metal compliance. FDA dietary supplement cGMP requirements filter supplier technical capabilities. Pacific Northwest coastal research stations pilot tank-based cultivation for year-round extract supply.
Ulva Lactuca Market Competitive Landscape
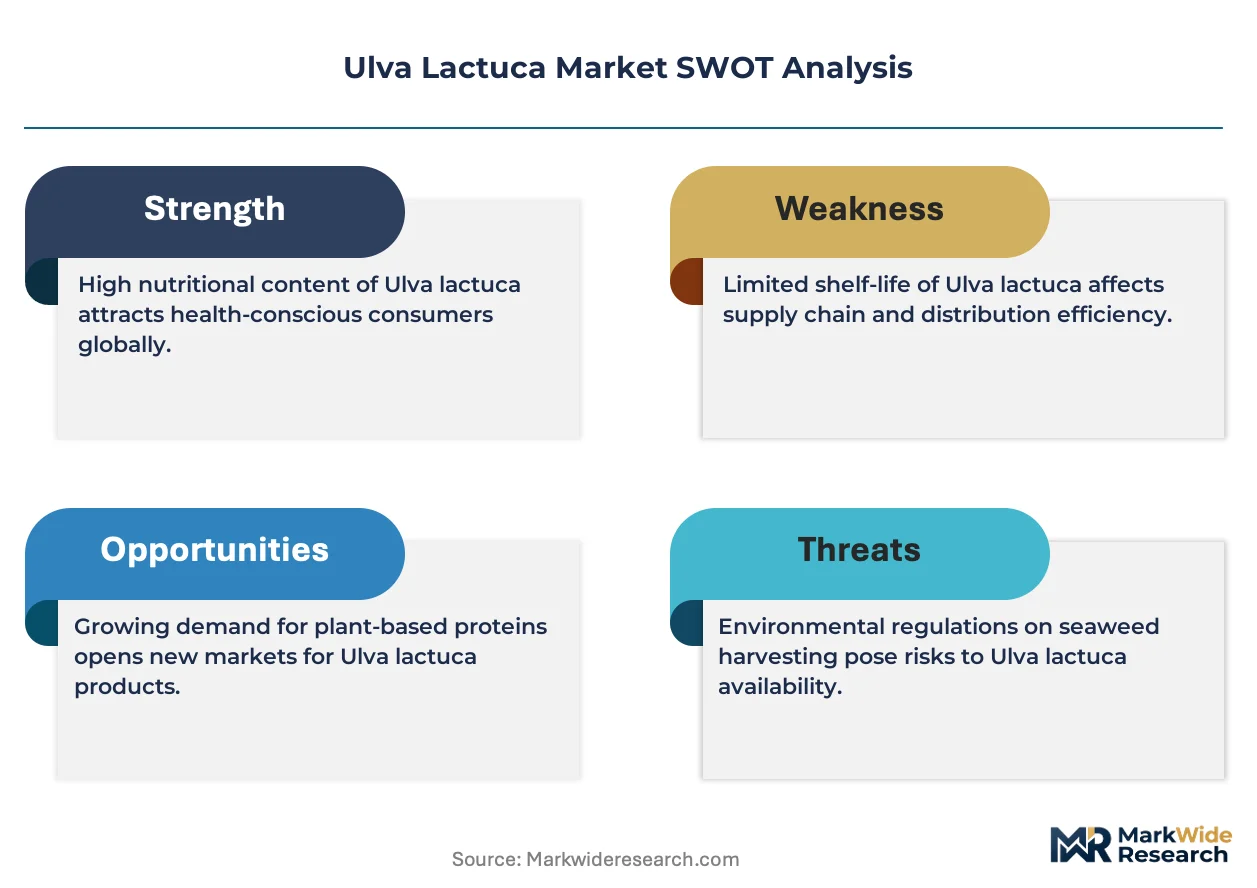
Technology leadership and cost leadership are held by different player archetypes, with automated offshore cultivators competing against price-driven dried powder exporters. The structure fragments between vertically integrated North Atlantic operators and Asian processing specialists. Three archetypes dominate: captive supply integrators, extraction-capable cultivators, and commodity biomass traders. Competitive moves concentrate on backward integration into farming partnerships and direct-to-formulator channel development.
Among Nordic integrated operators, Nordic SeaFarm and Ocean Harvest Technology occupy positions exemplifying captive cultivation-to-processing models. Cargill Incorporated anchors the multinational integrator tier through upstream control over Norwegian farming partnerships. Qingdao Haixingyuan Biotechnology Co., Ltd represents the Asian export-processing archetype competing on dried powder and extract volume shipments.
| Leading Market Players |
|---|
| Nordic SeaFarm |
| Algaia |
| Ocean Harvest Technology |
| Mara Seaweed |
| Cargill Incorporated |
| Acadian Seaplants Limited |
| Qingdao Haixingyuan Biotechnology Co., Ltd |
| CP Kelco U.S. Inc. |
| Connemara Seaweed Company |
| Others |
Pricing and Supply Chain Analysis
Seventy-two-hour cold-chain windows from harvest to formulation dictate margin capture across Ulva lactuca supply tiers, concentrating pricing power with integrated cultivator-processors who compress spoilage risk while spot-market biomass traders absorb perishability discounts. This lead-time compression rewards Norwegian and Chinese operators with captive extraction infrastructure, forcing commodity exporters into price-taking positions.
Pricing Analysis
After-sales revenue from multi-year extraction service contracts and certified biomass supply agreements drives lifetime value for integrated cultivator-processors. Three-tier pricing structure across premium, standard, and economy levels separates EFSA Novel Food-certified extracts from organic-dried grades and commodity bulk powder. Price differentiation rests on organic certification status and ulvan concentration standardization. Cost compression in commodity dried powder is intensifying because Shandong processors compete on volume exports to price-sensitive Asian nutraceutical channels. Dietary supplement manufacturers in Oslo and Copenhagen show least price sensitivity, while animal feed compounders remain most sensitive due to soy and pea protein substitute availability.
Supply Chain Analysis
Norway and China anchor biomass production, with Ireland and South Korea contributing specialized extract and fresh supply respectively. Cultivation draws from seeded rope substrates, automated monitoring hardware, and synthetic fiber long-line systems. Single-source vulnerability concentrates in semiconductor-dependent sensor equipment for AI-monitored sea farms. Distribution runs through direct-to-formulator channels for cosmetics and nutraceutical grades, while commodity dried powder moves via ingredient distributors to Asian processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market tracks a cyclical recovery anchored to EFSA Novel Food approval waves, where regulatory clearance cycles create demand pulses for certified extract supply.
For Market Incumbents: Secure backward integration into Norwegian and Chinese farming partnerships to lock captive biomass supply before automated long-line systems democratize cultivation economics. Defend margin position by accelerating EFSA and SAMR dual-certification investments, as heavy-metal threshold divergence threatens supply chain disqualification for non-compliant traders. Prioritize ERP integration capabilities to meet food manufacturer traceability requirements. For New Entrants and Emerging Players: EFSA Novel Food fast-track pathways under the EU Algae Initiative compress time-to-market for compliant suppliers entering European functional food channels. India's FSSAI regulatory frameworks for edible algae remain underdeveloped relative to plant-extract categories, creating first-mover positioning for biomass suppliers with pre-validated heavy-metal compliance. Target direct-to-formulator cosmetics contracting in Seoul and Busan, bypassing traditional ingredient distributors with traceable extract supply. For Investors and Strategic Acquirers: Carve-out targets emerge from multinational food conglomerates divesting non-core seaweed ingredient divisions amid portfolio rationalization pressures. Long-term viability over a five-to-ten year horizon favors extraction-capable cultivators with captive North Sea or Shandong cultivation infrastructure over commodity biomass traders. Watch EFSA Novel Food approval velocity as the inflection indicator for extract-grade demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cultivation Partnerships | Cargill Incorporated's Norwegian farming alliances secure captive supply for hydrocolloid extraction. |
| EFSA Novel Food Certification Investment | Accelerated approval pathways compress time-to-market for European functional food ingredient suppliers. |
| Direct-to-Formulator Channel Development | Cosmetics manufacturers in Seoul bypass distributors to contract traceable ulvan extract supply. |
| Automated Long-Line System Deployment | AI-monitored sea farms collapse capital barriers between industrial and mid-tier cultivators. |
| Biorefinery Technology Convergence | Integrated extraction platforms unlock full-biomass valorization combining ulvan, protein, and mineral recovery. |
Research Methodology
A standing panel of seaweed cultivator operations managers, cosmetics formulator procurement leads, nutraceutical quality assurance directors, and marine biotechnology R&D heads provided ongoing calibration across primary fieldwork and secondary validation cycles. Bottom-up triangulation combined trade data from Norwegian Directorate of Fisheries licensing records, Chinese customs export statistics for edible algae, EFSA Novel Food approval databases, and SAMR GB standard compliance filings with top-down reconciliation against industry association reports and academic biomass yield studies.
Consistency checks validated volume and value outputs against external benchmarks including cultivation area expansion permits, extraction capacity installations, and downstream offtake agreement disclosures across the projection horizon. Segmentation modeling spanned product type, application, form, end user, and regional regulatory cluster dimensions. CAGRs were derived from fitted growth curves incorporating EFSA approval timeline assumptions, Shandong processing capacity buildouts, and South Korean cosmetics formulation demand elasticity.
Decision-makers should treat outputs as directional under sustained EFSA streamlining and stable semiconductor supply for farm automation hardware; material deviation in regulatory velocity or input cost volatility would warrant model refresh. Recalibration cycles align with material shifts in Novel Food approval cadence and coastal aquaculture licensing expansions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bio-Agriculture
Europe Biofertilizer Market
Bio-Agriculture
Bio Rational Fungicides Market
Bio-Agriculture
Japan Biofertilizer Market
Bio-Agriculture
Horticulture Bioplastic Market
Bio-Agriculture
Bio-Based Levulinic Acid Market
Bio-Agriculture
United States Biocontrol Agents Market
Bio-Agriculture
Bovine High-Mountain Disease Market
Bio-Agriculture
South America Biological Organic Fertilizers Market
Bio-Agriculture
Hydroponics Market
Bio-Agriculture
Plant-Based Biologics Market
Bio-Agriculture
Africa Biostimulants Market
Bio-Agriculture
Aquatic Animal Vaccines Market
Bio-Agriculture
Global Biofungicides Market
Bio-Agriculture
South America Biopesticides Market
Bio-Agriculture
Biological Seed Treatment Market
Bio-Agriculture
Biofertilizers Market