
 Latin America Diaper Market | 2026-2036
Latin America Diaper Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Diaper Market Intelligence
Premium absorbent core specifications is unwinding outdated cost-engineering norms across Latin America. Kimberly-Clark Corp leverages its regional manufacturing footprint to sustain shelf presence in Mexican and Brazilian retail chains. Ontex Group BV differentiates through private-label partnerships that dominate pharmacy and supermarket channels. Hayat Kimya Sanayi AS anchors supply reliability via integrated fluff pulp sourcing into its regional operations.
A diaper constitutes a multi-layer absorbent hygiene product comprising a topsheet, acquisition distribution layer, absorbent core with superabsorbent polymers, backsheet, and elastic closures, engineered for urine and fecal containment with skin-dryness maintenance. Disposable diapers command the largest revenue pool given their convenience premium, while biodegradable variants represent the fastest-growing product type as environmental scrutiny intensifies. Adult end users generate expanding margin pools as incontinence stigma declines and senior populations rise across Colombia and Argentina.
ANVISA in Brazil and COFEPRIS in Mexico enforce absorbent hygiene product safety standards that shape formulation chemistry and labeling requirements for all market entrants. Argentina's ANMAT adds another compliance layer for imported finished goods, creating differentiated market access costs. Stakeholders must monitor regulatory divergence on biodegradability claims and chemical disclosure rules as these frameworks mature.
Market Dynamics
Superabsorbent polymer chemistry advances are compressing core thickness while maintaining retention capacity, forcing incumbent manufacturers to retool production lines or cede shelf space to specialized suppliers.
Growth Catalysts
- ANVISA safety standard harmonization:Brazil's unified absorbent hygiene regulations reduce cross-border compliance duplication for manufacturers operating in Mercosur trade zones, accelerating product registration timelines.
- Urban middle-class household formation:Concentrated demand in São Paulo and Mexico City metropolitan corridors drives volume commitments from modern trade retailers seeking category exclusivity arrangements.
- Senior incontinence normalization:Demographic aging across Colombia and Argentina reduces stigma-driven purchase hesitation, expanding the addressable user base for adult briefs and protective underwear.
Market Restraints
- Fluff pulp import dependency:Latin American diaper producers rely on North American and Scandinavian pulp suppliers, exposing margins to ocean freight volatility and currency mismatch.
- Biodegradability claim verification gaps:Absence of regionally recognized compostability certification creates consumer skepticism and regulatory enforcement inconsistency across national borders.
- Petrochemical feedstock concentration:Superabsorbent polymer production clusters in East Asia and the Middle East generate supply security concerns for regional converters.
Strategic Opportunities
- Pharmacy channel premiumization:Colombian and Chilean drugstore chains are expanding dedicated hygiene aisles, creating shelf space for higher-margin adult incontinence SKUs with clinical positioning.
- COFEPRIS expedited review pathways:Mexico's streamlined medical device classification for moderate-to-heavy adult incontinence products accelerates time-to-market for innovation-focused entrants.
- Plant-based backsheet integration:Convergence of bio-polymer extrusion technology with existing film production equipment enables partial fossil-based content substitution without line replacement.
Industry Challenges
- Polymer chemistry talent scarcity:Regional universities produce limited superabsorbent polymer formulation specialists, forcing manufacturers to recruit from European and Asian competitor pools.
- Legacy SAP-to-fluff ratio optimization:Retrofitting existing core-forming equipment for next-generation high-SAP, low-fluff configurations requires extended downtime and revalidation protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Diaper Market |
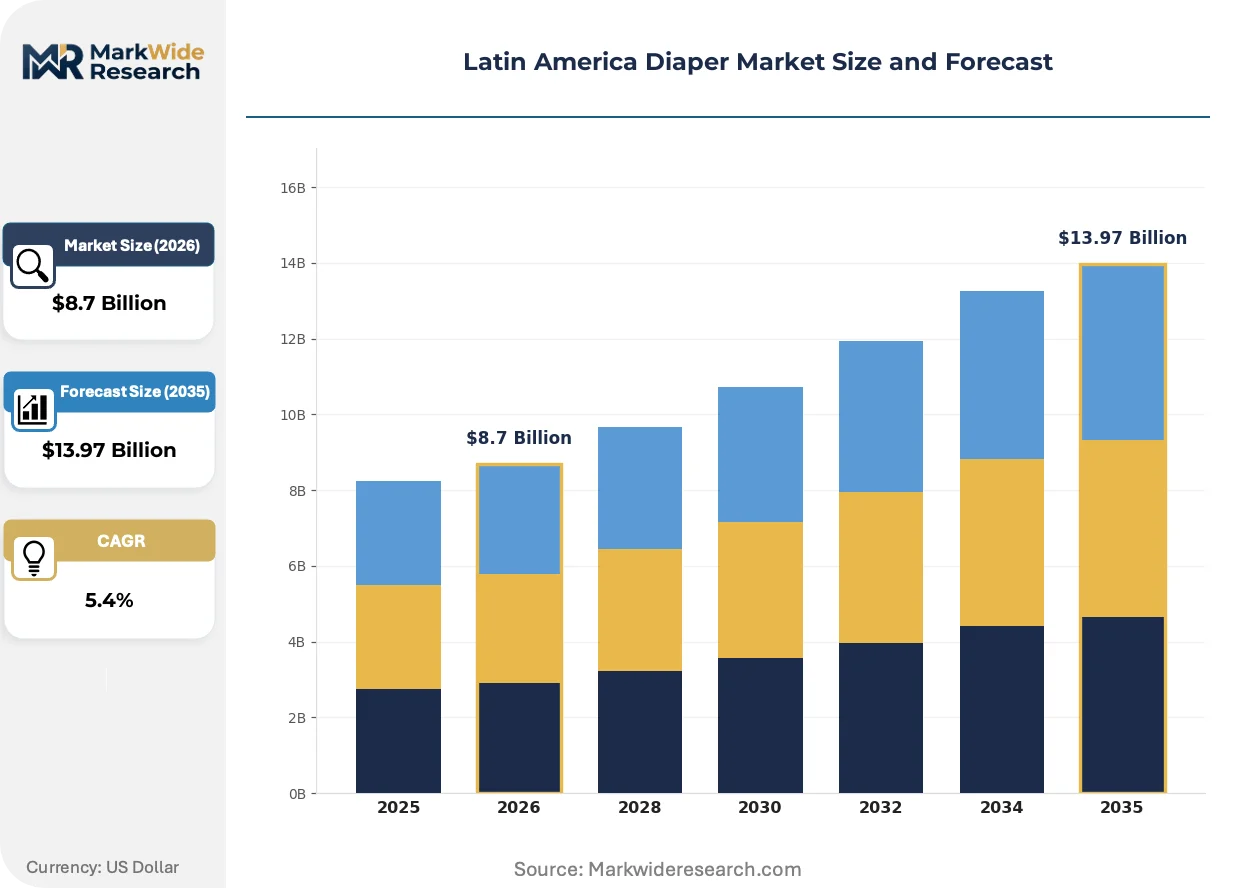
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.97 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disposable, Cloth, Biodegradable, Training Pants End User: Infants, Toddlers, Adults, Seniors Distribution Channel: Supermarkets, Pharmacies, Online Retail, Convenience Stores Price Tier: Premium, Mid-Range, Budget, Discount |
| Companies Covered | Johnson & Johnson, Drylock Technologies NV, The Procter & Gamble Co, JL Morison (India) Ltd, Tecnochemicals SA, Kimberly-Clark Corp, Ontex Group BV, Hayat Kimya Sanayi AS, Softys Brazil Ltd, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Diaper Market Strategic Shifts & Innovations
Active material science breakthroughs are redefining performance benchmarks across the Latin America diaper market. Manufacturers now compete on skin-health metrics and environmental credentials rather than absorption capacity alone.
Superabsorbent polymer core architecture is miniaturizing through gradient density layering that concentrates retention polymers toward the center while reducing bulk at peripheral zones. Pediatric dermatology clinics in Brazilian private healthcare networks are specifying these configurations for infant patients with sensitive skin conditions. The technology is miniaturizing overall product profiles while maintaining overnight capacity ratings, compressing the historical trade-off between discretion and performance.
ANVISA's 2023 updated labeling requirements mandate quantitative disclosure of fragrance content and specific superabsorbent polymer chemistry types on primary packaging. Manufacturers must reformulate scented variants or invest in translation and graphic redesign for bilingual Portuguese-Spanish labeling across Mercosur distribution. Premium infant diaper SKUs face the steepest compliance timeline pressures given their higher fragrance incidence and export volume concentration.
Subscription-based replenishment models are displacing traditional supermarket stock-up purchasing among dual-income households in Mexico City and São Paulo metropolitan zones. Direct-to-consumer platforms with predictive algorithmic sizing are capturing trial-to-conversion sequences that pharmacy and hypermarket channels previously dominated. Argentina's recurring inflation volatility makes this model most visible in Brazil and Mexico, where credit card installment integration reduces perceived monthly expenditure.
Latin America Diaper Market Segmentation
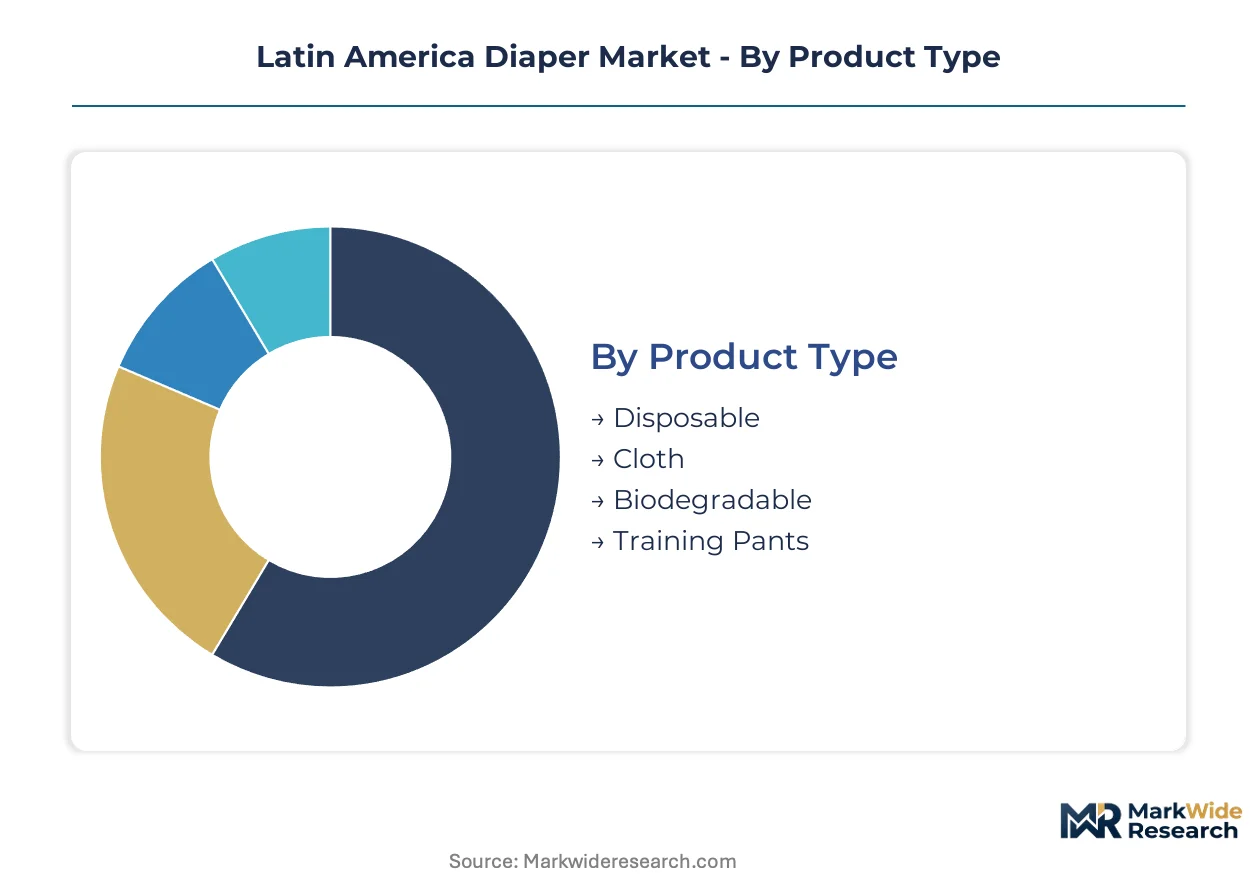
Segmentation in Latin America's diaper market reveals how purchasing behavior splits across channel access, demographic urgency, and price sensitivity. Manufacturers must align SKU architecture with these fracture lines to avoid inventory mismatches in São Paulo hypermarkets versus Colombian pharmacy chains.
Product Type:
Channel-mix dynamics vary sharply by product format, with modern trade retailers prioritizing high-velocity disposable SKUs while pharmacies and subscription platforms drive biodegradable and training pant adoption.
- Disposable:Multi-layer construction with superabsorbent polymer cores and elasticized closures dominates Brazilian and Mexican retail shelves. São Paulo supermarket chains command volume commitments through category exclusivity arrangements with manufacturers seeking shelf presence.
- Biodegradable:Plant-based backsheet materials and compostable adhesives respond to ANVISA's evolving chemical disclosure mandates. Colombian urban households show accelerating trial rates through pharmacy channels, though certification gaps create consumer skepticism.
- Cloth:Reusable cotton and bamboo blends persist in price-sensitive segments across Argentina's informal economy.
- Training Pants:Pull-up designs with tear-away sides target toddler mobility stages, concentrated in Mexican middle-class households.
By volume, disposable leads. By growth pace, biodegradable variants are climbing the fastest.
End User:
Cost tier alignment separates infant segments seeking premium skin-health positioning from adult categories where clinical efficacy commands price premiums.
- Adults:Moderate-to-heavy incontinence briefs with odor-control chemistry and discreet profiles drive margin expansion. COFEPRIS expedited medical device pathways in Mexico accelerate innovation deployment for this cohort.
- Infants:Dermatologist-specified configurations with fragrance-free topsheets and gradient-density cores concentrate in Brazilian private healthcare networks. ANVISA's updated labeling requirements force reformulation timelines for scented variants.
- Seniors:Protective underwear with breathable waistbands addresses stigma reduction in Colombia and Argentina.
- Toddlers:Daytime training products with wetness indicators align with dual-income household purchasing patterns.
Adult and senior segments together generate expanding margin pools, while infant volumes anchor manufacturer production planning.
Distribution Channel:
Volume concentration dictates supply chain configuration, with modern trade demanding pallet-scale efficiency and digital channels requiring parcel-logistics integration.
- Supermarkets:Hypermarket and supermarket chains in Mexico City and São Paulo metropolitan corridors capture stock-up purchasing with promotional bundling. Retailers seek category exclusivity arrangements that lock in manufacturer volume commitments.
- Online Retail:Subscription-based replenishment with algorithmic sizing displaces traditional pharmacy trial-to-conversion sequences among Brazilian credit-card installment users. Direct-to-consumer platforms reduce perceived monthly expenditure through recurring billing.
- Pharmacies:Colombian and Chilean drugstore chains expand dedicated hygiene aisles for clinical-positioned adult incontinence SKUs.
- Convenience Stores:Emergency purchase occasions for single-unit infant diapers concentrate in urban Brazilian bodega networks.
Supermarkets retain volume leadership. Online retail shows the steepest expansion trajectory.
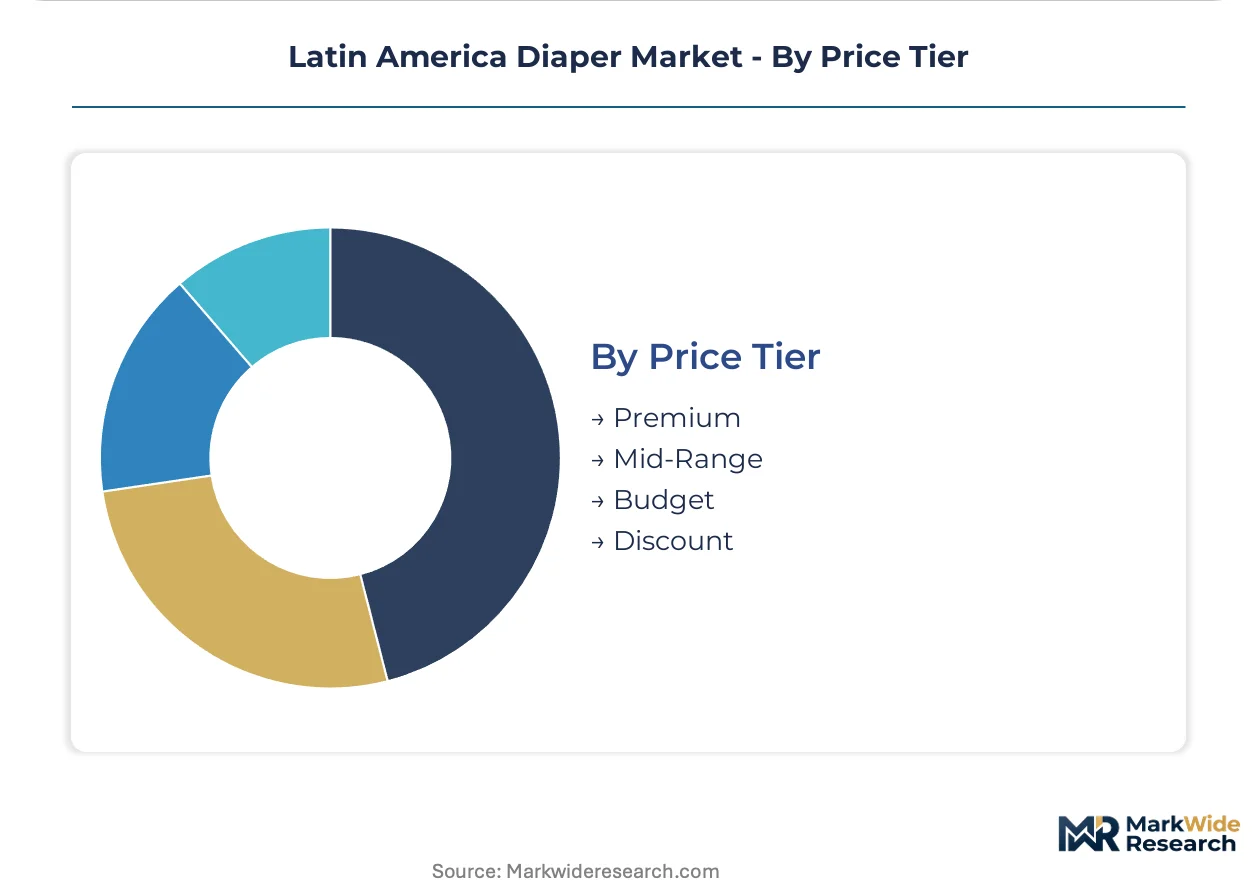
Price Tier:
Application context shapes tier selection, with clinical positioning justifying premium placement and routine replenishment driving budget-tier volume.
- Premium:Superabsorbent polymer-dense cores with dermatological certification and fragrance-free formulations target Brazilian private healthcare network specifications. ANVISA's quantitative disclosure mandates elevate compliance costs that premium pricing absorbs.
- Budget:Reduced SAP-to-fluff ratios and simplified elastic systems serve Argentina's inflation-vulnerable households through value-channel distribution.
- Mid-Range:Balanced performance specifications dominate Mexican modern trade promotional cycles.
- Discount:Minimal-feature SKUs move through informal retail in peripheral Brazilian municipalities.
Premium tier leads margin contribution. Budget tier gains share fastest in Argentina's volatile economy.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fluff pulp import flows concentrate manufacturing capacity in coastal Brazilian and Mexican industrial corridors, where port proximity offsets raw material logistics costs. ANVISA and COFEPRIS regulatory frameworks create divergent compliance cost structures that favor localized production over cross-border finished goods trade. Urban household formation in São Paulo and Mexico City metropolitan zones drives volume concentration that shapes regional supply chain configuration.
Brazil
São Paulo state's industrial belt hosts the densest absorbent hygiene manufacturing cluster in Latin America, with ANVISA's unified Mercosur regulations reducing duplicate product registration burdens for regional exporters. Brazilian private healthcare networks specify dermatologist-certified infant diaper configurations that elevate premium-tier procurement standards. The São Paulo metropolitan corridor anchors demand concentration through modern trade retailer category exclusivity arrangements.
Mexico
COFEPRIS expedited medical device classification for moderate-to-heavy adult incontinence products accelerates innovation deployment timelines for manufacturers serving aging demographics. Mexico City and Guadalajara metropolitan zones concentrate dual-income household purchasing power that sustains subscription-based replenishment platform growth. The Bajío Region's expanding manufacturing base captures nearshoring investment targeting US market access.
Argentina
ANMAT's import compliance layer for finished absorbent hygiene goods creates differentiated market access costs that protect domestic converters from price-based competition. Buenos Aires and Córdoba urban centers concentrate senior population growth that reduces incontinence stigma and expands protective underwear demand. Recurring inflation volatility compresses purchasing cycles and elevates budget-tier volume share through informal retail channels.
Colombia
Bogotá and Medellín pharmacy chains are expanding dedicated hygiene aisles that create shelf space for clinical-positioned adult incontinence SKUs with premium margin profiles. The country's national pharmaceutical regulator enforces chemical disclosure standards that align with evolving ANVISA transparency mandates. Colombian urban middle-class expansion concentrates demand in modern trade formats seeking manufacturer exclusivity commitments.
Chile
Santiago's concentrated retail landscape favors pharmacy channel premiumization for adult incontinence products with discreet positioning and odor-control chemistry. The country's national health regulator maintains stringent absorbent hygiene safety standards that exceed baseline Mercosur requirements. Chilean consumer environmental scrutiny drives trial rates for biodegradable variants despite compostability certification gaps.
Latin America Diaper Market Key Industry Players
Concentration sits with integrated multinational hygiene specialists and regional private-label converters. The market structure tiers between premium-brand incumbents with dermatological certification access and cost-optimized suppliers serving inflation-vulnerable segments. Three archetypes dominate: North American consumer goods conglomerates with Mercosur manufacturing footprints, European private-label specialists with pharmacy channel dominance, and Turkish integrated pulp-to-finished-goods producers. Competitive moves center on SAP-to-fluff ratio optimization for core-thinning and pharmacy channel shelf-space expansion for adult incontinence SKUs.
Among North American consumer goods conglomerates, Kimberly-Clark Corp and The Procter & Gamble Co exemplify scale-driven archetypes with regional manufacturing presence. European private-label positioning is occupied by Ontex Group BV. These three anchors sit within distinct strategic tiers: integrated brand ownership, retail partnership dependence, and cross-regional supply reliability.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Drylock Technologies NV |
| The Procter & Gamble Co |
| JL Morison (India) Ltd |
| Tecnochemicals SA |
| Kimberly-Clark Corp |
| Ontex Group BV |
| Hayat Kimya Sanayi AS |
| Softys Brazil Ltd |
| Others |
Cost & Logistics Intelligence
Sixty-to-ninety-day fluff pulp inventory cycles concentrate pricing power among coastal Brazilian and Mexican converters with port-adjacent warehousing, while inland Argentine producers absorb currency mismatch penalties that compress mid-range tier margins. ANVISA compliance costs for fragrance disclosure and polymer chemistry labeling feed directly into premium SKU pricing, creating tier separation that raw material volatility alone cannot explain.
Pricing Analysis
ANVISA dictates the pricing tier structure through quantitative disclosure mandates that elevate compliance burdens disproportionately for premium infant SKUs with higher fragrance incidence. Three-tier pricing structure across premium, standard, and economy levels separates dermatologist-certified configurations from value-channel offerings. Cost compression in budget tiers intensifies because Argentine inflation volatility forces informal retail channel dependence. Pharmacy channel buyers exhibit lowest price sensitivity for clinical-positioned adult incontinence products, while supermarket stock-up purchasers in São Paulo show highest elasticity to promotional bundling.
Supply Chain Analysis
Strategic stockpile preferences dominate fluff pulp procurement given ocean freight volatility and Scandinavian supplier concentration, with Brazilian coastal converters maintaining ninety-day coverage versus Mexican just-in-time exposure. Raw material sourcing draws from US and Scandinavian pulp suppliers, East Asian superabsorbent polymer producers, and Middle Eastern petrochemical feedstock clusters. Single-source vulnerability in SAP production generates supply security concerns for regional converters. Distribution runs through São Paulo and Mexico City metropolitan corridors for modern trade volume, with direct-to-consumer parcel logistics expanding for subscription replenishment platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ANVISA's 2023 labeling overhaul constitutes a regulatory inflection that compresses reformulation timelines and elevates compliance costs, accelerating market consolidation toward integrated manufacturers with in-house polymer chemistry capabilities.
For Market Incumbents: Consolidate manufacturing footprints in São Paulo state's industrial belt to capture ANVISA's unified Mercosur registration benefits, while deepening backward integration into fluff pulp sourcing to offset ocean freight volatility. Threat from Turkish integrated pulp-to-finished-goods producers with captive raw material supply demands capacity discipline and pharmacy channel exclusivity lock-ins. For New Entrants and Emerging Players: Lead with biodegradable variants through Colombian pharmacy chains where compostability certification gaps create first-mover positioning before ANVISA mandates harden. The adult incontinence segment offers most penetrable white-space given COFEPRIS expedited review pathways and stigma reduction tailwinds. Go-to-market angle should emphasize clinical efficacy positioning with odor-control chemistry differentiation. For Investors and Strategic Acquirers: Long-term, this sits as a demographic-elasticity play because aging populations across Colombia and Argentina expand addressable user bases irrespective of cyclical consumption patterns. Acquisition target archetype: regional private-label converters with pharmacy channel dominance and SAP-to-fluff optimization capabilities. Signal to watch is ANVISA enforcement consistency on biodegradability claims as proxy for regulatory maturation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluff Pulp Sourcing | Captive raw material supply insulates Brazilian manufacturers from Scandinavian pulp price volatility and freight cost spikes. |
| Pharmacy Channel Expansion for Adult Incontinence | Colombian drugstore chain partnerships unlock premium-margin shelf space with clinical positioning and discreet packaging. |
| Superabsorbent Polymer Core Thinning Investment | Gradient-density layering technology compresses product profiles while maintaining overnight capacity ratings for Brazilian private healthcare networks. |
| Direct-to-Consumer Subscription Platform Launch | Algorithmic sizing and credit-card installment integration capture trial-to-conversion sequences from Mexico City dual-income households. |
| Biodegradable Variant Certification Pursuit | ANVISA-aligned compostability standards preempt regulatory enforcement gaps that currently generate Colombian consumer skepticism. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted across primary interview programs, encompassing brand managers at multinational hygiene specialists, category buyers at São Paulo supermarket chains, procurement leads at Colombian pharmacy distributors, and plant managers at Brazilian coastal manufacturing facilities. Secondary validation drew from ANVISA regulatory filings, COFEPRIS medical device registration databases, customs trade records for fluff pulp import flows, and Nielsen retail audit data for modern trade channel velocity. Bottom-up SKU-level volume builds were triangulated against top-down demographic projections for incontinence prevalence and infant birth rates.
Across the analysis window, the forecasting framework modeled segmentation dimensions including product format, end-user demographic, distribution channel, and price tier, with additional granularity on SAP-to-fluff ratio configurations and dermatological certification status. CAGRs were derived from regression analysis against urban household formation rates and senior population growth curves. Industry-specific forecast inputs incorporated ANVISA compliance timeline assumptions and COFEPRIS expedited review pathway utilization rates for adult incontinence classifications.
Underlying assumptions cover regulatory enforcement consistency, currency stability for import-dependent inputs, and consumer stigma reduction trajectories, with deviation risk concentrated in biodegradability claim verification gaps and petrochemical feedstock supply disruptions. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Diapers
Adult Diapers Market
Baby Diapers
Australia Pant Type Adult Diaper Market
Baby Diapers
Cat Diapers Market
Baby Diapers
North America Diaper Market
Baby Diapers
Nonwoven Baby Diaper Market
Baby Diapers
United Arab Emirates Baby Diapers and Wipes Market
Baby Diapers
Global Baby Swim Pants Diaper Market
Baby Diapers
Pet Diapers Market
Baby Diapers
Smart Diaper Market
Baby Diapers
United States Diaper Market
Baby Diapers
Biodegradable Diapers Market
Baby Diapers
China Pant Type Adult Diaper Market
Baby Diapers
Middle East and Africa and Asia Pacific Baby Diaper Market
Baby Diapers
East Africa Baby Diaper Market
Baby Diapers
Dog Diapers Market
Baby Diapers
Baby Diapers Market