
 Insulated Storage Vessel Market | 2026-2036
Insulated Storage Vessel Market Size, Share, and Industry Trends Forecast 2026-2036
Insulated Storage Vessel Market Outlook
LNG terminal infrastructure is expanding as the dominant demand vector for insulated storage vessels. Chart Industries leverages cryogenic engineering depth to anchor North American project pipelines. Linde plc sustains long-term supply agreements with European energy utilities requiring large-scale horizontal tank deployments. Air Liquide competes through modular containerized solutions that reduce field installation timelines for remote gas processing sites.
Insulated storage vessels are pressure-rated enclosures employing multi-layer insulation, vacuum barriers, or high-performance foam cores to maintain temperature-stable environments for liquids, gases, and sensitive solids. Stainless steel cryogenic tanks dominate LNG and liquid hydrogen applications due to austenitic stability at minus 162 degrees Celsius, while fiberglass horizontal tanks lead chemical storage where corrosion resistance governs specification. Carbon steel vertical tanks retain mature economics in bulk food and beverage silos though polymer-insulated containers are capturing pharmaceutical cold-chain share where lightweight portability and thermal duration extension command premium positioning.
ASME Boiler and Pressure Vessel Code compliance shapes North American market access requirements while EU Pressure Equipment Directive and CE marking govern European commercialization pathways. China's GB standards and SAMR oversight enforce domestic material traceability and welding certification protocols that foreign suppliers must satisfy. Stakeholders must monitor evolving hydrogen storage pressure classifications and cross-border carbon accounting rules that will redefine vessel specification priorities and supplier qualification thresholds.
Market Dynamics
Vacuum-insulated panel technology advances are compressing thermal conductivity benchmarks by an order of magnitude, forcing incumbent foam-core manufacturers to accelerate R&D cycles or cede premium LNG and hydrogen storage contracts to specialized cryogenic engineering firms.
Growth Catalysts
- EU F-Gas Regulation phase-down:Industrial refrigeration operators face mandatory hydrofluorocarbon reduction timelines, driving retrofit demand for CO2-compatible insulated vessels with ultra-low permeability barriers.
- Modular containerization:Remote gas processing sites in Australia and the Permian Basin now specify skid-mounted cryogenic tanks that slash field welding hours and accelerate commissioning schedules.
- China's dual carbon goals:State-backed hydrogen infrastructure investments mandate liquid hydrogen storage at minus 253 degrees Celsius, creating specialized demand for double-walled vacuum vessels with activated carbon getters.
Market Restraints
- Nickel price volatility:Austenitic stainless steel 304/316 feedstock costs swing with Indonesian and Philippine ore export policies, compressing fabrication margins for cryogenic tank producers.
- ASME Section VIII certification backlog:North American pressure vessel authorizations face inspector capacity constraints, extending delivery lead times for custom horizontal tanks beyond 26 weeks.
- Composite tank substitution:Type IV carbon-fiber pressure vessels for compressed hydrogen storage erode addressable demand for liquid hydrogen cryogenic tanks in light-duty vehicle refueling stations.
Strategic Opportunities
- India's PLI scheme for cold chain:Refrigerated transport and storage subsidies create first-mover advantages for vacuum-insulated panel suppliers targeting pharmaceutical distribution networks.
- ISO 19880-1 convergence:Harmonized hydrogen fueling station standards reduce country-specific engineering overhead, enabling standardized tank platforms across Germany, Japan, and South Korea.
- Pharmaceutical serialization mandates:Temperature excursion monitoring integration creates attach-rate opportunities for smart insulation systems with embedded IoT sensors in vaccine cold-chain vessels.
Industry Challenges
- Cryogenic welding certification scarcity:Qualified GTAW operators for 9% nickel steel root passes command premium wages, constraining capacity expansion at fabrication yards.
- Multi-standard compliance overhead:Simultaneous ASME, PED, and GB 150 certification requirements force redundant design reviews, inflating engineering costs for globally active suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Insulated Storage Vessel Market |
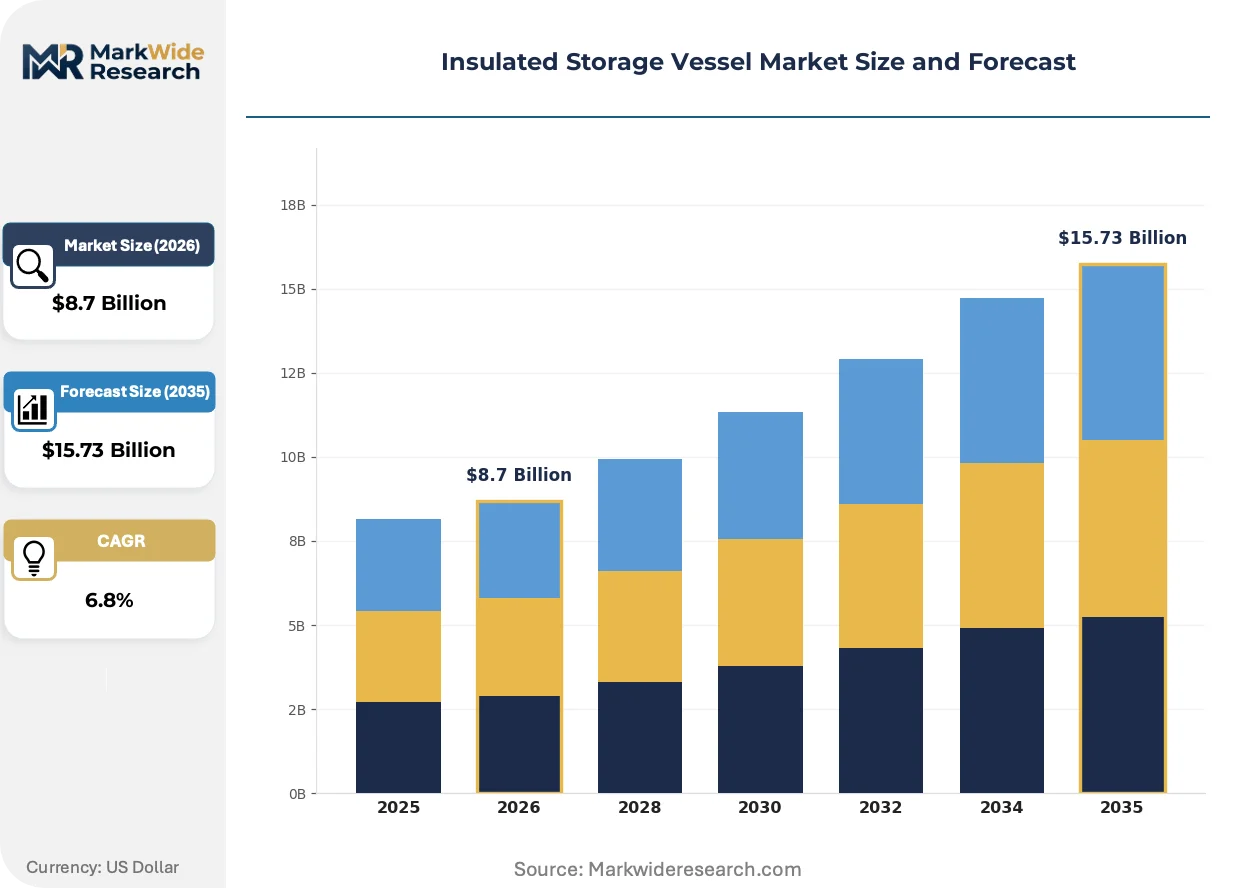
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vertical Tanks, Horizontal Tanks, Insulated Containers, Cryogenic Tanks Material: Stainless Steel, Carbon Steel, Fiberglass, Polymer Application: Food & Beverage, Pharmaceuticals, Chemicals, Energy End User: Manufacturers, Distributors, Retailers, Service Providers |
| Companies Covered | Chart Industries, Linde plc, Air Liquide, Owens Corning, Saint-Gobain, Rockwool International, Kingspan Group, Cabot Corporation, Johns Manville, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Insulated Storage Vessel Market Strategic Shifts
Aerogel composite insulation and machine-learning thermal modeling are converging to redefine performance-per-volume metrics, while regulatory pressure on embodied carbon forces material substitutions across the supply base.
Vacuum-insulated panels with fumed silica cores are overtaking polyurethane foam in LNG fuel tank applications for maritime shipping. Classification societies in Norway and Japan now specify VIP-constructed IMO Type C tanks for newbuild liquefied gas carriers. This technology compression is enabling shipyards to reduce tank wall thickness by 40% while maintaining equivalent boil-off rates, freeing cargo volume for additional revenue-generating capacity.
The EU's Carbon Border Adjustment Mechanism is reshaping sourcing decisions for stainless steel feedstock. Vessel fabricators serving European energy utilities must now document Scope 3 emissions from nickel mining through cold rolling, with non-compliant imports facing tariff adjustments from 2026. This policy friction is accelerating nearshoring of tank production to Spanish and Polish fabrication yards with verified renewable electricity supply.
Leasing models for cryogenic storage assets are displacing capital purchase in industrial gas distribution. Linde plc and Air Liquide now offer tank-as-a-service contracts in Germany and Texas, unbundling maintenance and telemetry from hardware ownership. This financing rotation is most pronounced in hydrogen refueling networks where station operators prioritize operational expenditure predictability over balance-sheet asset control.
Insulated Storage Vessel Market Segmentation
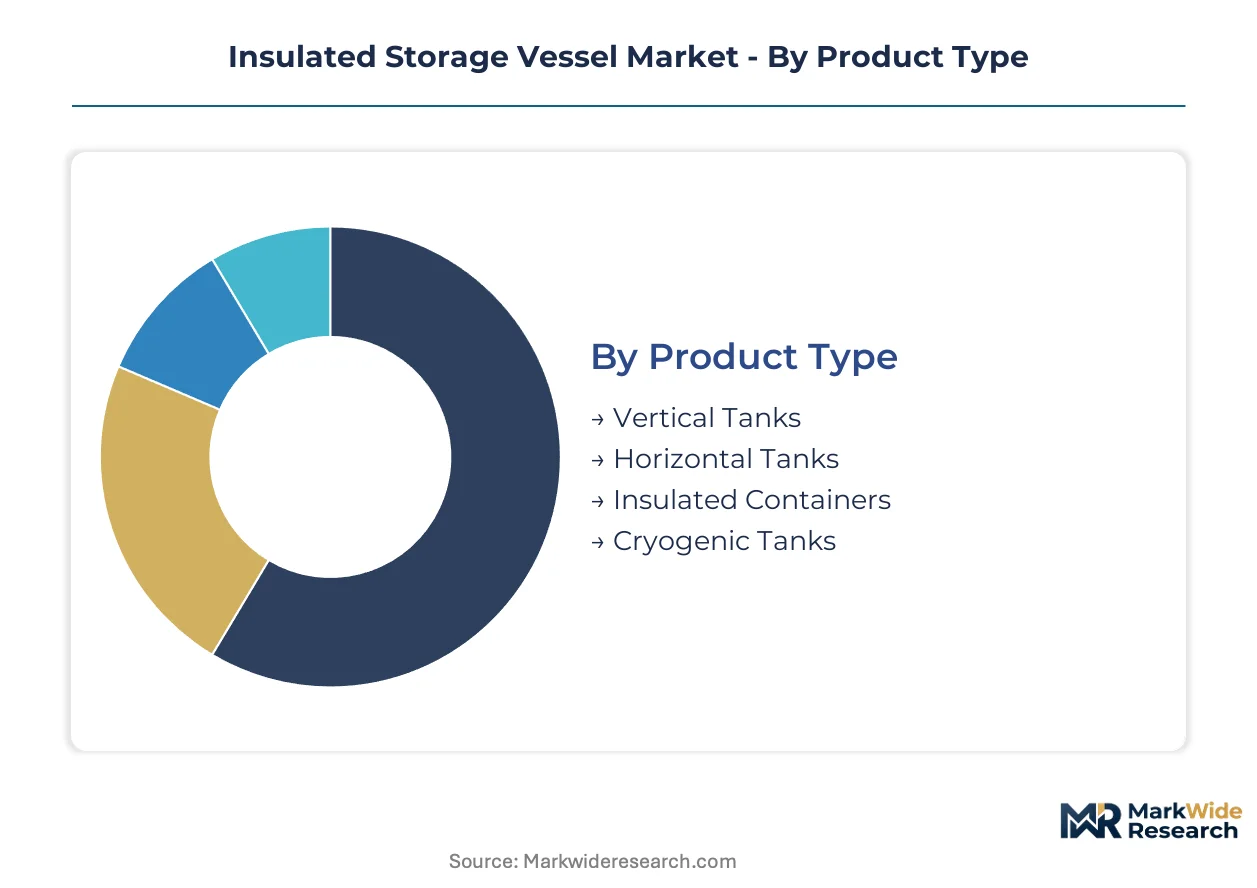
Insulated storage vessel procurement varies sharply by containment geometry, thermal duty, and regulatory exposure. Specification choices cascade through material selection, pressure rating, and lifecycle cost calculations that determine supplier qualification and project economics.
Product Type:
Supply concentration tilts toward cryogenic and horizontal tank fabricators with ASME Section VIII and PED Module H certifications, marginalizing generalist pressure vessel shops lacking specialized welding protocols.
- Cryogenic Tanks:Double-walled vacuum vessels with perlite or activated carbon getter insulation maintain temperatures below minus 150 degrees Celsius for LNG and liquid hydrogen. Demand concentrates at energy terminals in Germany and Japan where IMO Type C tank specifications govern maritime fuel gas systems. China's state-backed hydrogen infrastructure investments mandate liquid hydrogen storage at minus 253 degrees Celsius, creating specialized demand for double-walled vacuum vessels with activated carbon getters.
- Horizontal Tanks:Cylindrical vessels optimized for low-center-of-gravity transport and saddle-supported installation dominate chemical and industrial gas distribution. Procurement clusters around Permian Basin gas processing sites and Australian remote LNG operations specifying skid-mounted configurations that slash field welding hours. Leasing models from Linde plc and Air Liquide now displace capital purchase in German and Texan hydrogen refueling networks.
- Vertical Tanks:Axisymmetric pressure vessels maximize storage density in footprint-constrained terminals and bulk storage farms. Carbon steel variants retain mature economics in food and beverage silo applications.
- Insulated Containers:Portable modular units with integrated refrigeration or passive thermal mass serve pharmaceutical cold-chain and last-mile distribution requirements.
Today's leader: Cryogenic Tanks. Tomorrow's challenger: Horizontal Tanks.
Material:
Cost tier stratification separates austenitic stainless grades commanding nickel-linked premiums from fiberglass and polymer alternatives capturing corrosion-sensitive and lightweight applications.
- Stainless Steel:Austenitic 304/316 grades dominate cryogenic applications requiring stability at minus 162 degrees Celsius. Nickel price volatility tied to Indonesian and Philippine ore export policies compresses fabrication margins.
- Carbon Steel:Low-alloy grades with external insulation cladding serve bulk food, beverage, and ambient chemical storage where thermal duty permits.
- Fiberglass:Corrosion-resistant composite construction leads chemical storage specifications against aggressive media. FRP horizontal tanks capture share in coastal and high-humidity installations.
- Polymer:Lightweight insulated containers with expanded polypropylene or vacuum-insulated panel cores penetrate pharmaceutical distribution where thermal duration extension and portability command premium positioning.
Stainless Steel captures the revenue concentration. Polymer materials are gaining share fastest in cold-chain mobility applications.
Application:
Volume distribution tracks capital deployment cycles across energy infrastructure, pharmaceutical serialization mandates, and chemical processing expansions.
- Energy:LNG terminal infrastructure and hydrogen refueling networks drive the largest vessel formats. EU F-Gas Regulation phase-down timelines accelerate CO2-compatible insulated vessel retrofits among industrial refrigeration operators.
- Pharmaceuticals:Temperature excursion monitoring integration creates attach-rate opportunities for smart insulation systems with embedded IoT sensors in vaccine cold-chain vessels. India's PLI scheme for cold chain subsidizes refrigerated transport and storage infrastructure.
- Chemicals:Corrosion-resistant specifications favor fiberglass and polymer-lined steel constructions for aggressive media containment.
- Food & Beverage:Bulk silo and processed liquid storage retains carbon steel economics with polyurethane or mineral wool insulation.
Energy commands the installed base. Pharmaceuticals show the steepest expansion trajectory from serialization and biologics distribution requirements.
End User:
Customer type determines ownership structure, with manufacturers favoring capital purchase and service providers gravitating toward tank-as-a-service contracts.
- Service Providers:Industrial gas distributors and hydrogen station operators prioritize operational expenditure predictability through leasing models. Telemetry-enabled maintenance unbundling from hardware ownership dominates German and Texan hydrogen refueling networks.
- Manufacturers:Chemical and food processors specify captive storage assets with long depreciation horizons and customized integration into production lines.
- Distributors:Third-party logistics operators balance fleet standardization against route-specific thermal duration requirements.
- Retailers:Grocery and pharmacy chains specify last-mile insulated containers with passive thermal mass for home delivery compliance.
Service Providers are restructuring procurement toward operational expenditure models. Manufacturers retain the largest absolute vessel count.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting fabrication capacity toward jurisdictions with streamlined certification pathways and renewable energy verification systems. Fabricators now weigh ASME backlog delays against EU Carbon Border Adjustment Mechanism compliance costs when siting production.
United States
Permian Basin gas processing expansions and Gulf Coast LNG export terminals drive demand for skid-mounted cryogenic tanks. FERC pipeline approvals and EPA emissions frameworks shape project timelines. Houston-area fabrication yards specialize in horizontal tank configurations for remote field deployment.
Germany
Industrial hydrogen refueling networks and maritime LNG fueling infrastructure anchor vessel procurement. EU F-Gas Regulation phase-down mandates accelerate CO2-compatible storage retrofits. Hamburg and Bremen port clusters specify IMO Type C tanks for newbuild liquefied gas carriers.
China
State-backed liquid hydrogen infrastructure investments and dual carbon goals mandate minus 253 degrees Celsius storage systems. SAMR oversight and GB 150 welding certification requirements enforce domestic content rules. Yangtze River Delta fabrication yards concentrate double-walled vacuum vessel production.
India
PLI scheme subsidies for cold-chain infrastructure and pharmaceutical distribution networks create vacuum-insulated panel demand. CDSCO serialization mandates drive temperature-monitoring integration. Maharashtra and Gujarat industrial corridors attract insulated container manufacturing for vaccine logistics.
Japan
IMO-compliant LNG fuel tank specifications and hydrogen fueling station standardization anchor procurement. METI hydrogen roadmap targets and JIS certification requirements govern supplier qualification. Nagoya and Osaka industrial zones concentrate cryogenic engineering expertise for maritime applications.
Insulated Storage Vessel Market Competitive Environment
Capacity expansion dominates the current landscape as fabricators add vacuum-insulated panel production lines to capture LNG and hydrogen storage contracts. The vendor base stratifies across three tiers: integrated industrial gas majors with captive vessel production, specialized cryogenic engineering firms with ASME-PED dual certification, and regional fabrication shops serving bulk chemical and food storage. Strategic archetypes include technology licensors leveraging aerogel and VIP patents, scale operators optimizing throughput at dedicated cryogenic facilities, and service-integrated providers bundling tank-as-a-service contracts. Geographic expansion and technology licensing represent the dominant competitive moves, with players establishing satellite fabrication yards near demand clusters and cross-licensing thermal barrier innovations.
Among integrated industrial gas majors, Chart Industries, Linde plc, and Air Liquide occupy positions that exemplify the service-integrated archetype. These entities leverage captive demand from their own distribution networks while supplying third-party terminal operators. Owens Corning and Kingspan Group represent the technology-licensor tier, anchoring vacuum-insulated panel supply to vessel fabricators lacking in-house thermal engineering capabilities. This structure concentrates premium cryogenic contracts among firms with demonstrated minus 150 degrees Celsius fabrication experience while relegating ambient-temperature chemical storage to price-competitive regional shops.
| Leading Market Players |
|---|
| Chart Industries |
| Linde plc |
| Air Liquide |
| Owens Corning |
| Saint-Gobain |
| Rockwool International |
| Kingspan Group |
| Cabot Corporation |
| Johns Manville |
| Others |
Value Chain & Pricing Dynamics
Energy terminal operators and hydrogen refueling station developers concentrate procurement volumes, anchoring contract-based long-term offtake structures that favor certified fabricators with ASME-PED dual qualifications. This buyer concentration amplifies price leverage for multi-tank deployments while squeezing margins at regional shops lacking cryogenic welding protocols.
Pricing Analysis
Distributor margins for insulated vessels compress as direct-to-OEM channels capture hyperscale energy infrastructure contracts. Pricing stratifies across ASME-certified premium tiers, PED-compliant standard tiers, and uncertified economy tiers for ambient chemical storage. Cost compression in stainless steel feedstock is intensifying because nickel price volatility tied to Indonesian ore export policies erodes fabrication margins. Chemical processors and food silo operators exhibit highest price sensitivity, while LNG terminal developers prioritize thermal performance over unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for cryogenic tanks, bypassing distribution layers for energy terminal and hydrogen station deployments. Manufacturing gravity centers on China, Germany, and the United States, with Yangtze River Delta and Houston-area yards specializing in double-walled vacuum vessels. Feedstock supply draws from Indonesian nickel mines, Chinese stainless steel mills, and German specialty steel producers. Single-source vulnerability in 9% nickel steel plate creates bottlenecks for qualified GTAW fabrication. Distribution runs through industrial gas majors with captive vessel production and specialized cryogenic engineering firms serving third-party terminal operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The insulated storage vessel market represents a late-cycle quality story as vacuum-insulated panel specifications displace conventional foam-core alternatives in LNG maritime and liquid hydrogen infrastructure. Procurement committees now mandate minus 253 degrees Celsius thermal performance thresholds that eliminate uncertified fabricators from premium contract pools.
For Market Incumbents: Cement ASME-PED dual certification moats by accelerating inspector capacity investments to resolve Section VIII authorization backlogs. Backward integration into vacuum-insulated panel production reduces thermal barrier sourcing exposure to Owens Corning and Kingspan Group technology licensors. Prioritize hydrogen storage pressure classification monitoring to preempt specification shifts that could obsolete existing fabrication protocols. For New Entrants and Emerging Players: Regional cold-chain logistics operators in India and Southeast Asia represent underserved buyer archetypes with PLI-subsidized procurement budgets and limited incumbent relationships. Pharmaceutical distribution networks seeking IoT-integrated temperature monitoring create white-space entry points against legacy foam-core container suppliers. Pursue technology licensing partnerships with established VIP core manufacturers rather than greenfield thermal engineering development. For Investors and Strategic Acquirers: Industrial gas majors with captive vessel production are the most active acquirer in this space, targeting specialized cryogenic engineering firms to secure minus 150 degrees Celsius fabrication capabilities. Five-to-ten year viability hinges on hydrogen infrastructure deployment velocity and carbon border adjustment compliance positioning. Monitor EU Carbon Border Adjustment Mechanism verification system rollout as inflection indicator for nearshoring-driven fabrication capacity repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Vacuum-Insulated Panel Production Scale-Up | Captures LNG maritime and liquid hydrogen contracts from foam-core incumbents. |
| ASME-PED Dual Certification Investment | Unlocks German and North American energy terminal procurement pools. |
| Hydrogen Storage Pressure Classification R&D | Anticipates evolving ISO 19880-1 specifications for refueling station deployments. |
| India Cold-Chain Manufacturing Joint Venture | Accesses PLI scheme subsidies for pharmaceutical distribution vessel production. |
| Carbon Border Adjustment Compliance Program | Documents Scope 3 emissions for European utility contract retention. |
Study Parameters
Direct dialogue with cryogenic engineering directors, energy terminal procurement managers, industrial gas distribution executives, and vessel fabrication yard operators grounded qualitative assessments. Secondary validation drew from ASME Boiler and Pressure Vessel Code filings, EU Pressure Equipment Directive registrations, SAMR GB standards documentation, and customs trade data for stainless steel plate imports. Bottom-up project pipeline aggregation across LNG terminals and hydrogen refueling networks was triangulated against top-down industrial gas major capex disclosures.
Top-down macroeconomic drivers were cross-referenced against bottom-up vessel unit economics segmented by containment geometry, thermal duty class, material grade tier, and regional certification cluster. Modeled dimensions spanned cryogenic versus ambient temperature applications, vacuum-insulated versus foam-core thermal barriers, and service provider leasing versus manufacturer capital purchase ownership structures. CAGRs were derived from installation base expansion rates and replacement cycle timing across energy infrastructure deployment waves.
Inputs from SAMR certification databases and EU PED Module H registries were available through the study window; gaps in privately held hydrogen station commissioning schedules introduce uncertainty bands around near-term demand trajectories. Forecasts reflect assumptions regarding nickel price stability, inspector capacity expansion timelines, and cross-border carbon accounting rule convergence. Periodic stress-testing of base assumptions against F-Gas Regulation phase-down enforcement and IMO maritime fuel specifications is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Containers
Inverted Squeeze Bottle Market
Packaging Containers
Glass Vape Cartridge Market
Packaging Containers
Wrist Watch Packaging Market
Packaging Containers
Mini Refillable Spray Dispenser Market
Packaging Containers
Snap Single Dose Dispensers Market
Packaging Containers
Latin America Aerosol Cans Market
Packaging Containers
Sanitizer Bottles Market
Packaging Containers
North America Food Cans Market
Packaging Containers
Euro Box Market
Packaging Containers
Food Portion Pack Market
Packaging Containers
Self - Locking Trays Market
Packaging Containers
Logistics Packaging Market
Packaging Containers
Assembly Trays Market
Packaging Containers
Chalk Boxes Market
Packaging Containers
Child Resistant Bottles Market
Packaging Containers
Membrane Boxes Market