
 Tramadol Drug Market | 2026-2036
Tramadol Drug Market Size, Share, and Industry Trends Forecast 2026-2036
Tramadol Drug Market Analytics
Fixed-dose combination formats pairing tramadol with acetaminophen or NSAIDs is broadening prescriber choice beyond single-entity opioids. Teva Pharmaceutical Industries Ltd. leverages its generic manufacturing scale to occupy cost-sensitive hospital procurement channels. Grünenthal GmbH anchors originator-brand positioning through sustained R&D investment in extended-release formulations. Sun Pharmaceutical Industries Ltd. competes across emerging markets with localized production networks.
Tramadol hydrochloride is a centrally acting synthetic opioid analgesic with dual mechanisms—mu-opioid receptor agonism and monoamine reuptake inhibition—typically formulated as 50 mg immediate-release or 100–300 mg extended-release tablets for moderate to moderately severe pain management. The tablet segment dominates volume due to manufacturing simplicity and patient compliance, while the injectable form captures premium pricing in perioperative hospital settings. Oral delivery mode leads consumption across chronic pain and postoperative pain therapy areas, with intravenous administration reserved for acute surgical recovery where rapid onset is clinically necessary.
The FDA REMS program for extended-release and long-acting opioids shapes tramadol prescribing patterns through mandatory prescriber training and patient counseling requirements, while the DEA's Schedule IV classification imposes dispensing limits and tracking mandates. The EMA's pharmacovigilance framework for opioid medicines in Europe adds parallel reporting obligations that influence formulation development priorities. Stakeholders must monitor evolving scheduling decisions and abuse-deterrent technology standards that will determine which product configurations retain market access.
Market Dynamics
The FDA's Risk Evaluation and Mitigation Strategy for extended-release opioids is compressing prescribing freedom while simultaneously redirecting volume toward tramadol's Schedule IV status, creating a structural pull toward this lower-scheduled synthetic analgesic across hospital formularies.
Growth Catalysts
- Postoperative Protocol Expansion:Hospital systems in the United States are embedding tramadol into enhanced recovery after surgery pathways, displacing higher-schedule opioids in perioperative settings.
- Fixed-Dose Combination Formats:Pairing tramadol hydrochloride with acetaminophen or NSAIDs is broadening prescriber choice beyond single-entity opioids in chronic pain management.
- EMA Pharmacovigilance Alignment:Parallel reporting obligations for opioid medicines in Europe are normalizing tramadol's risk-benefit profile relative to traditional mu-agonists.
Market Restraints
- Active Pharmaceutical Ingredient Concentration:Synthesis of tramadol hydrochloride depends on concentrated precursor supply from Indian and Chinese bulk manufacturers, exposing formulators to import disruption.
- Abuse-Deterrent Technology Gap:Extended-release formulations lacking FDA-recognized abuse-deterrent properties face restricted access in institutional procurement channels.
- Scheduling Divergence:National narcotics boards in Saudi Arabia and the United Arab Emirates maintain stricter controls than the DEA's Schedule IV classification, fragmenting commercialization pathways.
Strategic Opportunities
- Parenteral Hospital Adoption:Injectable tramadol captures premium pricing in perioperative recovery suites where rapid onset is clinically necessary.
- India CDSCO Streamlining:India's central drug regulator is accelerating fixed-dose combination approvals, opening formulation diversification for domestic manufacturers.
- Pain Management Clinic Networks:Outpatient chronic pain centers are expanding tramadol utilization as a step-down therapy from oxycodone and hydrocodone regimens.
Industry Challenges
- Pharmacovigilance Workforce Scarcity:Manufacturers face shortage of qualified drug safety specialists capable of managing EMA and FDA parallel adverse event reporting systems.
- Legacy ERP Integration:Enterprise resource planning systems at mid-size generic houses require costly reconfiguration to track DEA Schedule IV dispensing mandates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tramadol Drug Market |
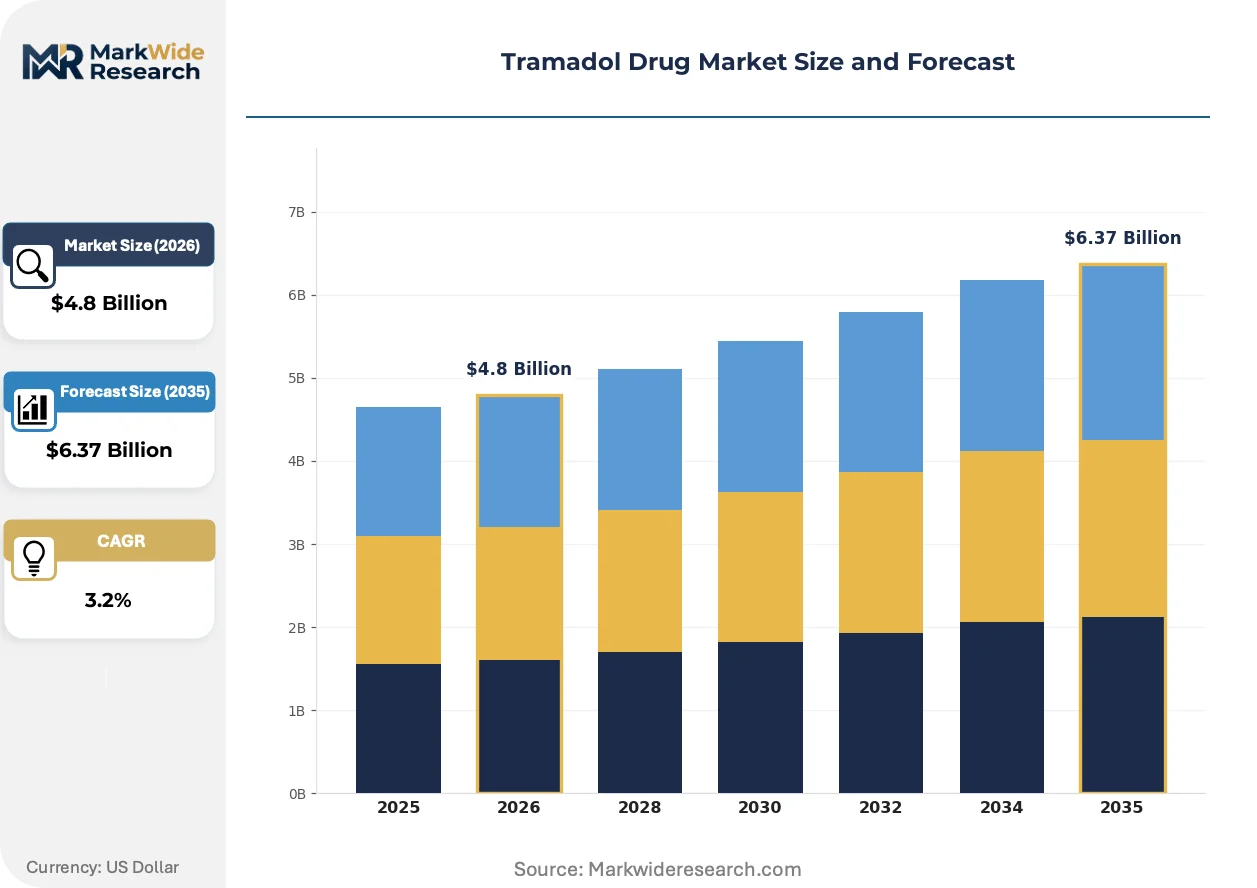
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.37 Billion |
| CAGR (2026 – 2036) | 3.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Form: Tablet, Capsule, Injectable, Oral Solution Delivery Mode: Intravenous, Oral, Subcutaneous, Intramuscular End User: Hospitals, Clinics, Home Care, Pain Management Centers Therapy Area: Chronic Pain, Postoperative Pain, Neuropathic Pain, Cancer Pain |
| Companies Covered | Aurobindo Pharma Limited, Nippon Shinyaku Co., Ltd., Teva Pharmaceutical Industries Ltd., Mundipharma, Ipca Laboratories Ltd., Sun Pharmaceutical Industries Ltd., Grünenthal GmbH, Zydus Lifesciences, Apotex Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tramadol Drug Market Evolving Landscape
Formulation science and regulatory compliance technology are converging to reshape how tramadol products reach prescriber preference lists, with three distinct vectors now determining competitive positioning.
Abuse-deterrent polymer matrix technology is expanding into extended-release tramadol tablets, creating physical barriers to crushing and dissolution that satisfy institutional pharmacy risk committees. Hospital procurement committees are prioritizing these formulations in therapeutic interchange protocols. The structural consequence is compressing market access for conventional extended-release tablets lacking such properties.
The EMA's strengthened pharmacovigilance framework for opioid medicines is mandating real-world evidence collection through patient registries and post-authorization safety studies. Marketing authorization holders must now fund longitudinal outcome tracking that was previously voluntary. Extended-release formulations in Germany and France face the steepest compliance cost escalation.
Hospital formularies are consolidating vendor relationships through single-source contracts for opioid analgesics, displacing fragmented multi-manufacturer purchasing. Integrated delivery networks in the United States are negotiating three-year supply agreements that bundle tramadol with other Schedule IV controlled substances. This concentration is most visible in the southeastern United States where hospital system mergers have accelerated.
Tramadol Drug Market Segmentation
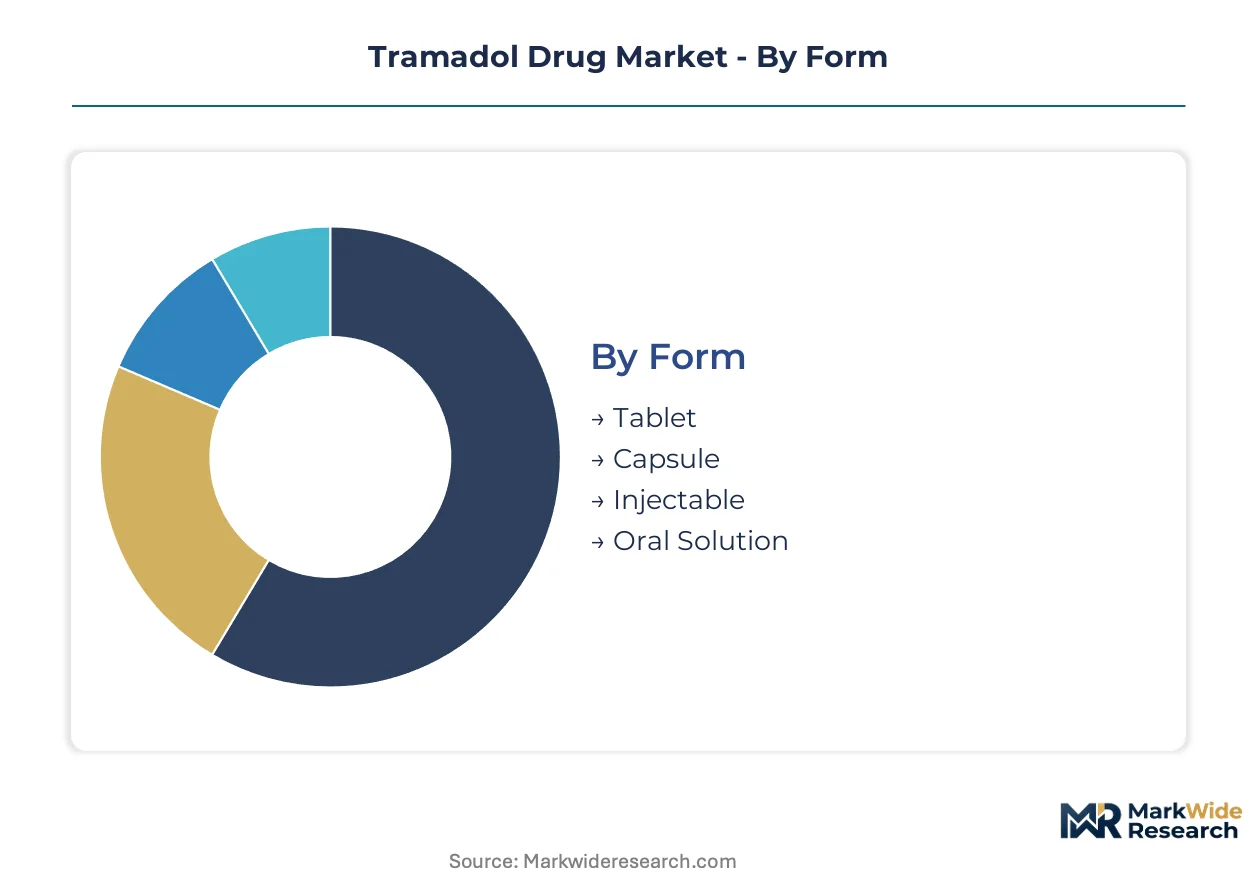
Tramadol's formulation diversity creates distinct competitive arenas where manufacturing complexity, regulatory scheduling, and clinical setting determine margin structure. Each segment category reflects a different axis of buyer priority—route of administration, care setting, or pain etiology—that shapes procurement behavior and product development investment.
Form:
Hospital procurement committees weight manufacturing reliability and abuse-deterrent properties differently than retail pharmacies serving chronic pain patients.
- Tablet:Immediate-release 50 mg and extended-release 100–300 mg formulations dominate outpatient dispensing due to dosing flexibility and stability during distribution. United States hospital formularies favor tablet procurement for step-down protocols from intravenous therapy, with DEA Schedule IV tracking requirements driving preference for unit-dose packaging.
- Injectable:Ampoule and vial presentations for intravenous or intramuscular administration command premium pricing in perioperative suites where rapid onset is clinically necessary. Saudi Arabia's national pharmaceutical regulator imposes batch-release testing requirements that extend lead times for imported sterile products.
- Capsule:Gelatin-shell formulations offer bioavailability advantages for patients with gastric sensitivity, though manufacturing depends on specialized excipient supply chains.
- Oral Solution:Liquid presentations serve pediatric and geriatric populations with swallowing difficulties, requiring stability testing under ICH guidelines for aqueous formulations.
Volume sits with Tablet; growth tilts toward Injectable as enhanced recovery after surgery protocols expand in United States health systems.
Delivery Mode:
Speed of onset and prescriber training requirements create sharp segmentation in how tramadol reaches patients.
- Oral:Swallowed tablets and capsules constitute the predominant consumption channel across chronic pain management, with patient compliance programs focusing on fixed-dose combination products pairing tramadol with acetaminophen.
- Intravenous:Direct vascular administration in hospital recovery suites enables precise titration for acute postoperative pain, with formulary placement contingent on pharmacy committee evaluation of diversion risk protocols.
- Intramuscular:Depot injection formats serve settings lacking intravenous infrastructure, particularly in Indian district hospitals where CDSCO-approved generic manufacturing supports cost-sensitive procurement.
- Subcutaneous:Continuous infusion pumps for cancer pain management in home care settings require specialized nursing support that limits penetration outside reimbursed palliative care networks.
Oral administration captures the greatest prescription volume; Intravenous delivery is expanding most quickly through United States hospital system consolidation.
End User:
Procurement sophistication and reimbursement mechanics diverge sharply across care settings.
- Hospitals:Integrated delivery networks negotiate multi-year supply agreements bundling tramadol with other Schedule IV controlled substances, with southeastern United States systems leading vendor consolidation trends.
- Pain Management Centers:Outpatient chronic pain clinics in Germany and France face EMA-mandated patient registry requirements that elevate compliance costs but normalize tramadol's risk profile relative to higher-schedule alternatives.
- Clinics:Ambulatory surgical centers embed tramadol into same-day discharge protocols, with formulary decisions influenced by group purchasing organization contracts.
- Home Care:Long-term care pharmacies serving geriatric populations prioritize blister-pack compliance aids and caregiver education materials over clinical sophistication.
Hospitals anchor current volume; Pain Management Centers are gaining share fastest as step-down therapy protocols proliferate.
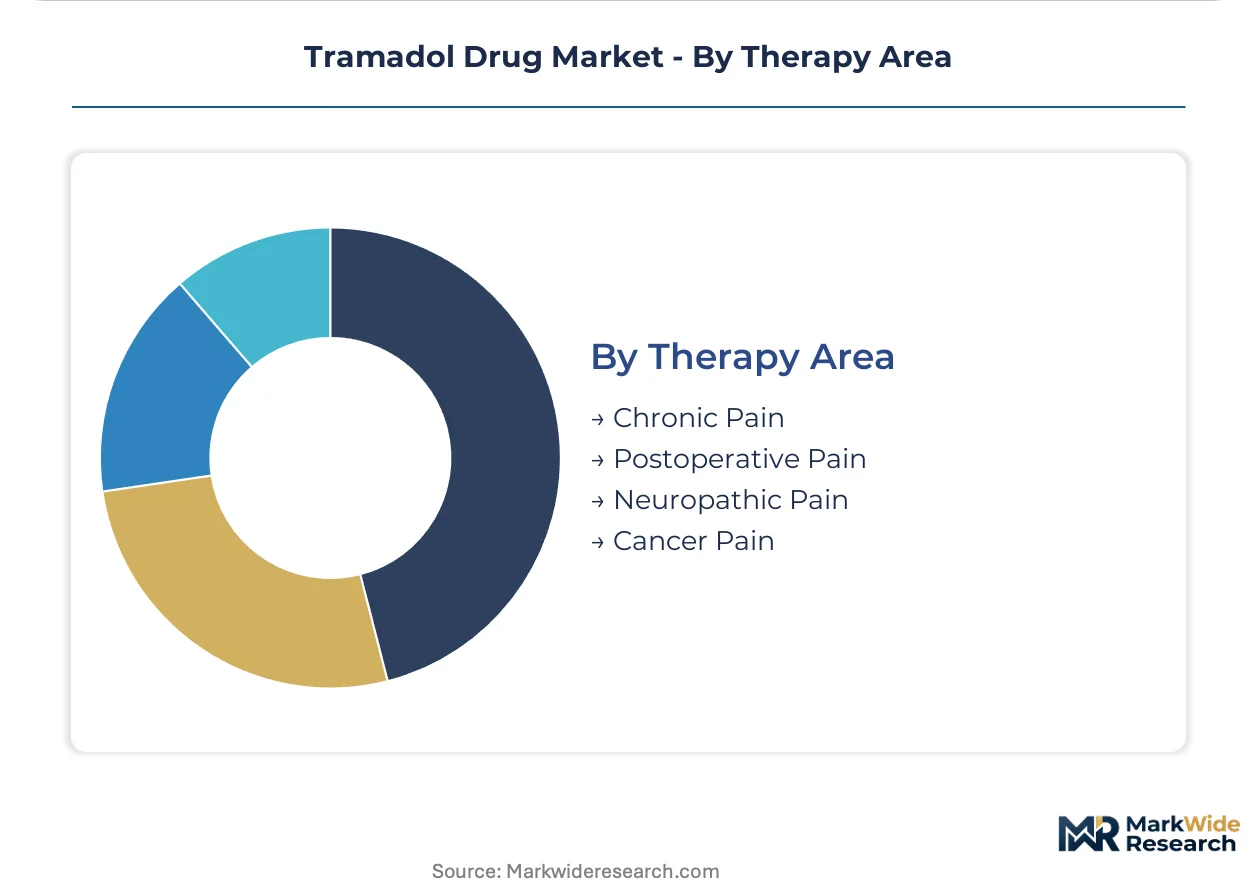
Therapy Area:
Pain etiology determines dosing duration, combination therapy requirements, and prescriber specialty.
- Postoperative Pain:Acute surgical recovery protocols in United States hospitals are displacing oxycodone and hydrocodone with tramadol in enhanced recovery pathways, with anesthesia departments driving formulary placement decisions.
- Chronic Pain:Long-term management of osteoarthritis and lower back pain sustains tablet volume through primary care prescribing, though FDA REMS training requirements for extended-release opioids influence product selection.
- Neuropathic Pain:Tramadol's monoamine reuptake inhibition provides mechanistic rationale for diabetic peripheral neuropathy and post-herpetic neuralgia, though pregabalin and duloxetine competition limits share.
- Cancer Pain:Palliative care utilization climbs the WHO analgesic ladder when non-opioid options fail, with morphine and oxycodone typically preferred for severe breakthrough pain.
Chronic Pain holds the largest patient population; Postoperative Pain shows the steepest expansion trajectory as surgical volume recovers and opioid-sparing protocols harden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tramadol consumption concentrates in mature pharmaceutical markets while manufacturing clusters in India and China supply active pharmaceutical ingredients. Hospital procurement networks in the United States absorb substantial volume through enhanced recovery protocols. European regulators impose parallel pharmacovigilance obligations that elevate compliance costs for marketing authorization holders.
United States
Chronic pain prevalence and postoperative protocol expansion drive sustained tramadol volume through hospital formularies and retail pharmacies. The FDA's Risk Evaluation and Mitigation Strategy for extended-release opioids redirects prescribing toward Schedule IV alternatives. Integrated delivery networks in the southeastern United States negotiate multi-year supply agreements that consolidate vendor relationships.
Germany
Extended-release formulations face steep compliance cost escalation under EMA-mandated patient registry requirements for opioid medicines. Grünenthal GmbH anchors originator-brand positioning through sustained R&D investment in advanced delivery systems. The Rhine-Ruhr metropolitan region hosts concentrated pharmaceutical distribution infrastructure serving central European markets.
India
Domestic manufacturers leverage localized production networks to compete across emerging markets with cost-sensitive procurement. The Central Drugs Standard Control Organization accelerates fixed-dose combination approvals, opening formulation diversification pathways. Gujarat and Maharashtra states host bulk API synthesis facilities that supply precursor materials to global formulators.
Saudi Arabia
The national pharmaceutical regulator imposes batch-release testing requirements that extend lead times for imported sterile injectable products. Stricter narcotics controls than DEA Schedule IV classification fragment commercialization pathways for extended-release formats. Riyadh's hospital procurement committees prioritize abuse-deterrent formulations in therapeutic interchange protocols.
Japan
PMDA oversight of opioid medicines maintains conservative prescribing patterns relative to Western markets. Nippon Shinyaku Co., Ltd. occupies a position within the domestic specialty pharmaceutical tier. The Kanto region around Tokyo concentrates demand through academic medical centers and pain management clinic networks.
Tramadol Drug Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across formulation and geographic vectors. The market structure tilts toward scale-driven generic manufacturers serving hospital procurement channels alongside originator-brand houses defending extended-release patent positions. Three archetypes dominate: Indian bulk-to-formulation integrators, European R&D-intensive originators, and North American generic scale players. Competitive moves concentrate on abuse-deterrent technology licensing and single-source contract consolidation with integrated delivery networks.
Within the originator-brand tier, Grünenthal GmbH exemplifies sustained investment in extended-release innovation, while Teva Pharmaceutical Industries Ltd. represents generic manufacturing scale deployed across cost-sensitive institutional channels. Sun Pharmaceutical Industries Ltd. anchors the India-based emerging market specialist position. These three companies illustrate how geographic origin and corporate structure map to divergent strategic postures—German GmbH-format R&D focus, Israeli-American generic scale, and Indian Co., Ltd. emerging market penetration.
| Leading Market Players |
|---|
| Aurobindo Pharma Limited |
| Nippon Shinyaku Co., Ltd. |
| Teva Pharmaceutical Industries Ltd. |
| Mundipharma |
| Ipca Laboratories Ltd. |
| Sun Pharmaceutical Industries Ltd. |
| Grünenthal GmbH |
| Zydus Lifesciences |
| Apotex Inc. |
| Others |
Value Network & Pricing Analysis
Precursor chemical price volatility from Indian and Chinese bulk manufacturers cascades through tramadol hydrochloride synthesis into tiered pricing structures across hospital procurement channels, retail pharmacy networks, and emerging market distributors.
Pricing Analysis
Margin tightening in generic tablet formulations reflects concentrated API sourcing from Gujarat and Maharashtra production clusters. Three-tier pricing structure across premium abuse-deterrent, standard extended-release, and economy immediate-release levels separates hospital formulary placements. Pricing pressure intensifies in injectable segments as Saudi batch-release testing extends import lead times. Cost-sensitive Indian district hospitals exhibit highest price sensitivity; United States integrated delivery networks show lowest sensitivity due to bundled contract structures.
Supply Chain Analysis
Freight cost escalation for temperature-controlled sterile shipments from India to Saudi Arabia and the United Arab Emirates compresses margins on injectable presentations. Active pharmaceutical ingredient synthesis concentrates in India and China, with formulation finishing distributed across Germany, the United States, and domestic Indian facilities. Precursor supply draws from specialized chemical manufacturers in the Yangtze River Delta and Ahmedabad chemical belts. Single-source vulnerability in extended-release polymer matrix technology creates procurement risk for abuse-deterrent formulations. Distribution runs through hospital group purchasing organizations in the southeastern United States, regional pharmaceutical distributors in Germany, and government procurement channels in Saudi Arabia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Tramadol API synthesis capacity constraints in Indian bulk manufacturing prop sustained pricing power for integrated producers, while formulation-level competition intensifies among generic houses.
For Market Incumbents: Anticipate EMA pharmacovigilance cost escalation by consolidating patient registry infrastructure across German and French marketing authorizations. Anchor hospital formulary position through abuse-deterrent technology licensing from polymer matrix specialists, defending against Teva Pharmaceutical Industries Ltd. scale advantages in cost-sensitive procurement channels. For New Entrants and Emerging Players: The mid-tier pricing gap between Grünenthal GmbH originator brands and Indian generic economy tablets offers entry space for CDSCO-approved fixed-dose combination specialists. Target parenteral hospital adoption in United States ambulatory surgical centers lacking integrated delivery network contracts. Pursue pain management clinic networks in Germany as step-down therapy volume expands under EMA registry requirements. For Investors and Strategic Acquirers: Distressed-cycle entries favor Indian bulk-to-formulation integrators with captive API supply and CDSCO regulatory relationships. Long-term viability hinges on vertical integration depth through the analysis window. Monitor DEA scheduling review signals as inflection indicators for extended-release formulation access restrictions.| Strategic Initiative | Industry Significance |
|---|---|
| Abuse-Deterrent Formulation Development | FDA REMS alignment secures hospital formulary placement against conventional extended-release competitors. |
| Fixed-Dose Combination Approval | CDSCO streamlining in India accelerates market entry for acetaminophen-tramadol pairing. |
| Parenteral Manufacturing Scale-Up | Injectable capacity captures premium pricing in United States perioperative recovery suites. |
| EMA Pharmacovigilance Integration | Patient registry funding satisfies German and French marketing authorization maintenance requirements. |
| Hospital System Contract Consolidation | Single-source agreements with southeastern United States integrated delivery networks lock multi-year volume commitments. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with formulary directors, hospital procurement managers, regulatory affairs leads, and pain management clinic administrators. FDA REMS documentation, EMA pharmacovigilance submissions, DEA controlled substance tracking data, and Indian CDSCO approval databases provided secondary validation. Bottom-up volume estimates from dosage-form consumption patterns triangulated against top-down market sizing from pharmaceutical distribution channel audits.
Granularity-level modeling operated at formulation type, delivery mode, end-user setting, and therapy area dimensions across the projection horizon. CAGRs derived from segment-level volume trajectories weighted by pricing tier evolution. Forecast inputs incorporated FDA scheduling review timelines, EMA patient registry cost assumptions, and Indian PLI scheme manufacturing capacity additions.
Inputs from hospital procurement databases and pharmaceutical customs records were available through the study window; gaps in real-time abuse-deterrent technology licensing terms introduce uncertainty bands around extended-release market share projections. Forecasts reflect documented assumptions regarding regulatory scheduling stability and API precursor supply continuity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Prescription Drugs Market
Pharmaceuticals
Global Angina Pectoris Drugs Market
Pharmaceuticals
Palonosetron Hydrochloride Market
Pharmaceuticals
Germany Opioids Market
Pharmaceuticals
Global Local Anesthesia Drugs Market
Pharmaceuticals
Diphtheria Tetanus Pertussis Vaccine Market
Pharmaceuticals
Sustained Release Drugs Market
Pharmaceuticals
Amylin Analogs Market
Pharmaceuticals
Biguanides Market
Pharmaceuticals
Lidocaine Ointment Market
Pharmaceuticals
Germany Diabetes Drugs Market
Pharmaceuticals
Radioligand Therapy (RLT) Market
Pharmaceuticals
United Kingdom (UK) Diabetes Drugs Market
Pharmaceuticals
Candidiasis Therapeutics Market
Pharmaceuticals
Global Dengue Vaccine Market
Pharmaceuticals
Global Pharmaceutical Traceability Market