
 Industrial Camera Market | 2026-2036
Industrial Camera Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Camera Market Outlook
Modular camera-lens-software bundles is realigning procurement patterns as buyers seek plug-and-play vision systems over discrete components. Basler AG leverages its broad CMOS portfolio to anchor European machine vision demand. Cognex Corporation differentiates through deep software-hardware integration in barcode and defect inspection. Teledyne Technologies extends its reach across high-performance imaging through coordinated subsidiaries including Teledyne DALSA.
An industrial camera is a ruggedized imaging device engineered for factory-floor conditions, typically operating across temperature ranges from -20°C to 60°C with IP67 sealing and GigE Vision or USB3 Vision interfaces for deterministic data transfer in automated environments. Area scan cameras dominate general-purpose quality control deployments, while line scan cameras sustain specialized applications in continuous web inspection where CMOS technology is displacing legacy CCD architectures due to faster frame rates and lower power draw. Process automation and robotics applications are capturing margin pools as end users demand embedded processing and AI-ready edge inference capabilities.
FDA quality system regulations shape camera specifications in US pharmaceutical packaging verification, while CE marking and EU Machinery Directive compliance govern product safety and electromagnetic compatibility for European deployments. ISO 9001 and ISO 14001 certifications increasingly filter supplier eligibility in automotive and electronics supply chains. Stakeholders must weigh sensor technology roadmaps against software ecosystem maturity when selecting long-term vision platform partners.
Market Dynamics
CMOS sensor maturation is compressing product lifecycles and forcing camera OEMs to recalibrate around software-defined imaging architectures rather than hardware refresh cycles.
Growth Catalysts
- East Asian semiconductor fab buildouts:Automated optical inspection lines in Taiwan and South Korea are absorbing high-frame-rate area scan cameras for wafer defect detection.
- FDA quality system regulations:Pharmaceutical packaging verification mandates in the United States are specifying vision systems with deterministic GigE Vision interfaces and full audit trails.
- Robotics end-use expansion:Collaborative robot deployments in automotive assembly are embedding AI-ready cameras with edge inference capabilities for real-time quality gates.
Market Restraints
- Image sensor supply concentration:Advanced CMOS fabrication capacity concentrates among a limited set of foundry operators in Taiwan and South Korea, creating allocation risk during demand surges.
- Specialized optical component costs:Precision lens assemblies and thermal stabilization subsystems account for disproportionate bill-of-materials inflation compared to sensor commoditization.
- CE marking compliance friction:EU Machinery Directive electromagnetic compatibility testing extends product validation timelines and requires third-party notified body involvement.
Strategic Opportunities
- India electronics manufacturing:PLI scheme incentives for mobile phone and component production are creating virgin demand for machine vision in greenfield assembly plants.
- Hyperspectral imaging convergence:Integration of spectroscopic analysis with standard industrial cameras is opening food sorting and pharmaceutical raw material inspection applications.
- EU AI Act compliance services:Risk classification requirements for automated decision systems in manufacturing vision are creating attach-rate opportunities for validation and documentation software.
Industry Challenges
- Embedded vision engineering scarcity:Cross-functional talent combining optical physics, FPGA programming, and machine learning deployment remains concentrated among a small pool of specialists.
- Multi-protocol integration complexity:Factory floors mixing GigE Vision, USB3 Vision, and proprietary camera link architectures demand costly middleware development for unified control.
- ISO 9001 certification maintenance:Automotive supply chain audits require continuous documentation of calibration traceability and supplier change management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Camera Market |
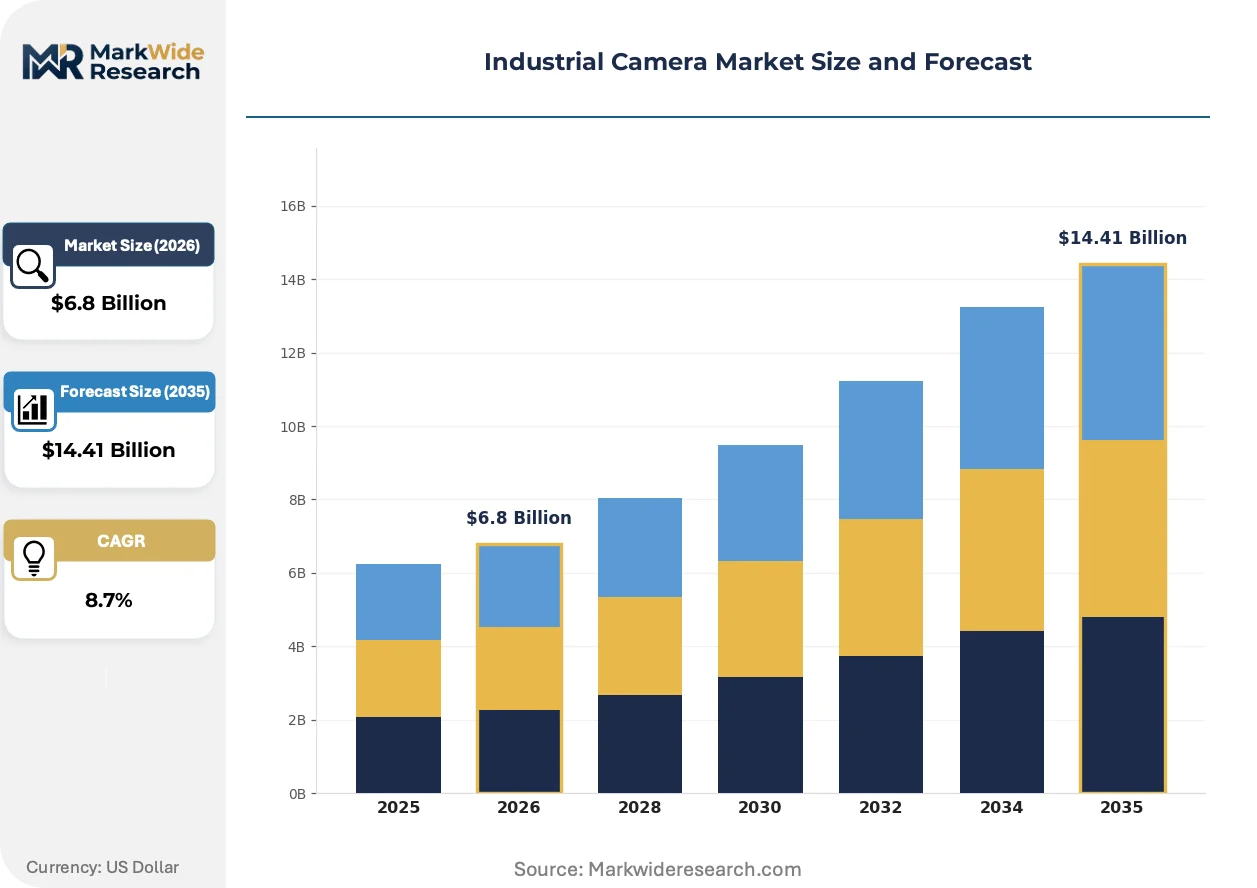
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Line Scan Cameras, Area Scan Cameras, Thermal Cameras, 3D Cameras Technology: CMOS, CCD, SLR, Machine Vision Application: Quality Control, Process Automation, Robotics, Remote Monitoring End User: Manufacturing, Aerospace, Electronics, Food & Beverage |
| Companies Covered | Keyence Corporation, Cognex Corporation, Basler AG, Teledyne Technologies, OMRON Corporation, Baumer, Teledyne DALSA, IDS Imaging Development Systems, Allied Vision Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Camera Market Strategic Shifts
Edge computing architectures are redistributing processing loads from centralized PLCs to camera-embedded inference engines, compressing latency budgets and rewiring system integration economics.
Time-of-Flight depth sensing is integrating structured light projection with standard CMOS capture to deliver sub-millimeter 3D point clouds for robotic bin-picking and dimensional verification. Automotive battery module assembly lines in Germany and China are adopting these hybrid cameras at accelerated procurement cycles. The technology is integrating collision-avoidance algorithms directly into camera firmware, reducing dependency on external processing hardware.
EU AI Act risk classification frameworks are mandating explainability documentation for vision systems performing automated quality decisions in medical device and automotive safety applications. Manufacturers must now maintain model training logs and bias audit trails alongside traditional calibration certificates. High-reliability camera suppliers serving European pharmaceutical packaging are restructuring software release processes to accommodate conformity assessment timelines.
Subscription-based firmware licensing is displacing perpetual software ownership in machine vision procurement, with camera vendors monetizing algorithm updates and cybersecurity patches as recurring revenue streams. System integrators in North American food and beverage processing are accepting this model to preserve access to continuous AI model improvements. The shift concentrates vendor switching costs and extends customer lifetime value metrics beyond hardware replacement cycles.
Industrial Camera Market Segmentation
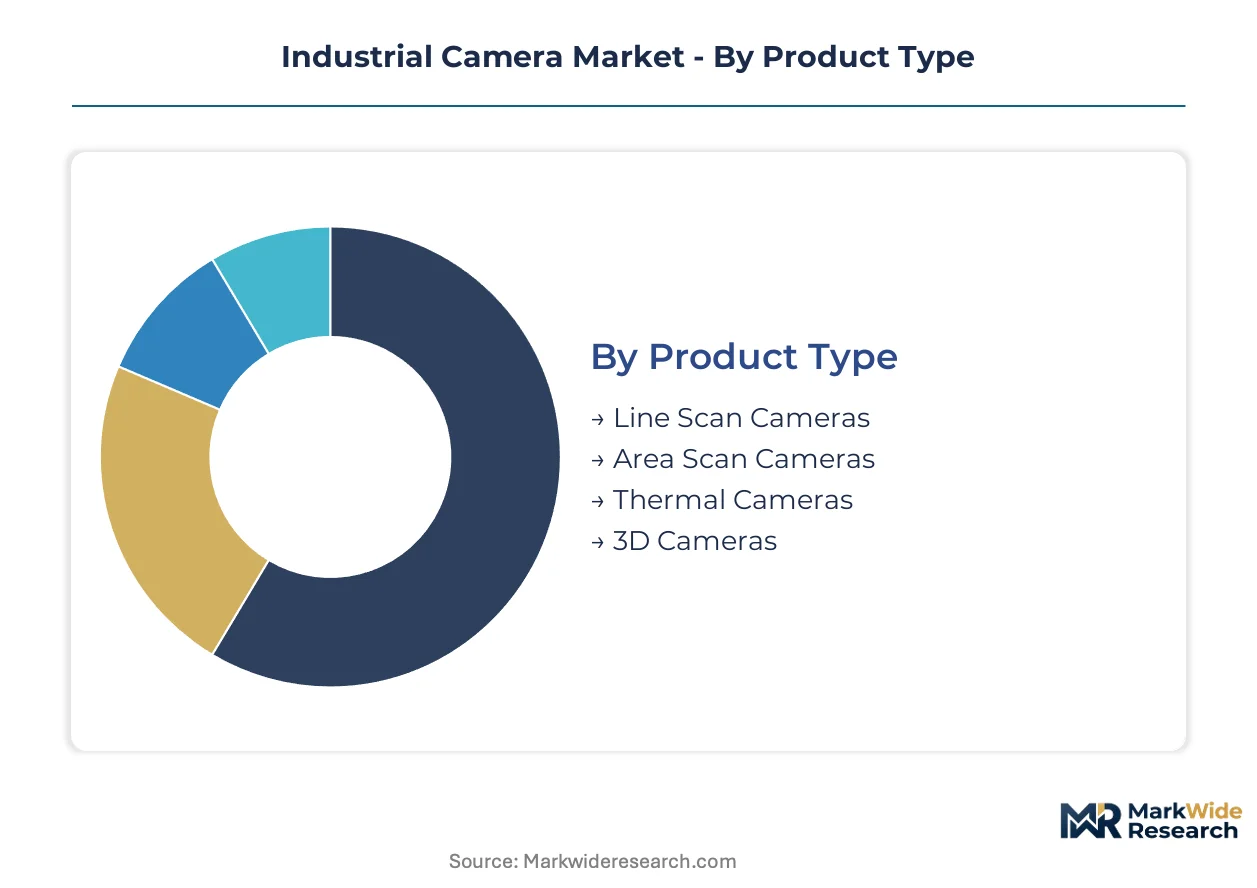
Industrial camera segmentation reveals how hardware architectures, sensor technologies, and deployment contexts fragment procurement decisions across factory automation ecosystems. Buyers navigate trade-offs between standalone imaging subsystems and deeply embedded vision modules.
Product Type:
Standalone vision systems dominate high-specification inspection stations, while embedded camera modules integrate directly into robotic end-effectors and conveyor-integrated quality gates.
- Area Scan Cameras:These devices capture full two-dimensional images in single exposures, supporting frame rates exceeding 500 fps in high-end CMOS configurations. Semiconductor wafer inspection facilities in Taiwan and South Korea specify these for defect detection on automated optical inspection lines, driven by yield-critical fab economics that demand sub-micron resolution at production speeds. Area scan cameras lead volumes today; 3D cameras are gaining share fastest.
- Line Scan Cameras:Linear sensor arrays build images progressively as objects move past the sensor plane, enabling continuous web inspection without frame rate limitations. Battery electrode manufacturing lines in Germany and China deploy these for coating uniformity verification, constrained by the mechanical precision required for consistent transport speed synchronization. Line scan cameras lead volumes today; 3D cameras are gaining share fastest.
- Thermal Cameras:Uncooled microbolometer arrays detect infrared emissions for predictive maintenance and process thermal profiling.
- 3D Cameras:Structured light and time-of-flight architectures generate depth maps for robotic bin-picking and dimensional metrology.
Area scan cameras lead volumes today; 3D cameras are gaining share fastest.
Technology:
Sensor fabrication maturity separates cost-optimized volume deployments from performance-critical specialized applications, with foundry capacity allocation shaping availability timelines.
- CMOS:Complementary metal-oxide-semiconductor sensors dominate new deployments through lower power consumption, faster readout speeds, and on-chip integration of analog-to-digital conversion. Electronics assembly lines in China's Yangtze River Delta specify CMOS-based GigE Vision cameras for PCB inspection, pressured by the region's compressed product lifecycle demands and continuous line speed upgrades. CMOS leads volumes today; machine vision is gaining share fastest.
- CCD:Charge-coupled device sensors persist in scientific imaging and legacy inspection systems requiring exceptional dynamic range and uniform pixel response.
- SLR:Single-lens reflex optical configurations appear in specialized documentation and forensic applications requiring interchangeable optics.
- Machine Vision:Dedicated imaging architectures integrate deterministic triggering, industrial protocols, and embedded processing for factory-floor deployment.
CMOS leads volumes today; machine vision is gaining share fastest.
Application:
End-use contexts determine camera specification priorities, with regulatory compliance requirements fragmenting feature sets across pharmaceutical, automotive, and electronics verticals.
- Quality Control:Defect detection and dimensional verification systems require calibrated optical chains with documented measurement uncertainty. FDA-regulated pharmaceutical packaging lines in the United States mandate vision systems with full audit trails and deterministic GigE Vision interfaces, shaped by 21 CFR Part 11 electronic records requirements. Quality control leads volumes today; robotics is gaining share fastest.
- Process Automation:In-line monitoring and feedback control applications prioritize integration speed and protocol compatibility over absolute resolution specifications.
- Robotics:Collaborative and autonomous systems embed cameras for guidance, manipulation, and safety perimeter monitoring with edge inference capabilities.
- Remote Monitoring:Distributed inspection stations and unmanned facilities require ruggedized enclosures and network resilience for intermittent connectivity.
Quality control leads volumes today; robotics is gaining share fastest.
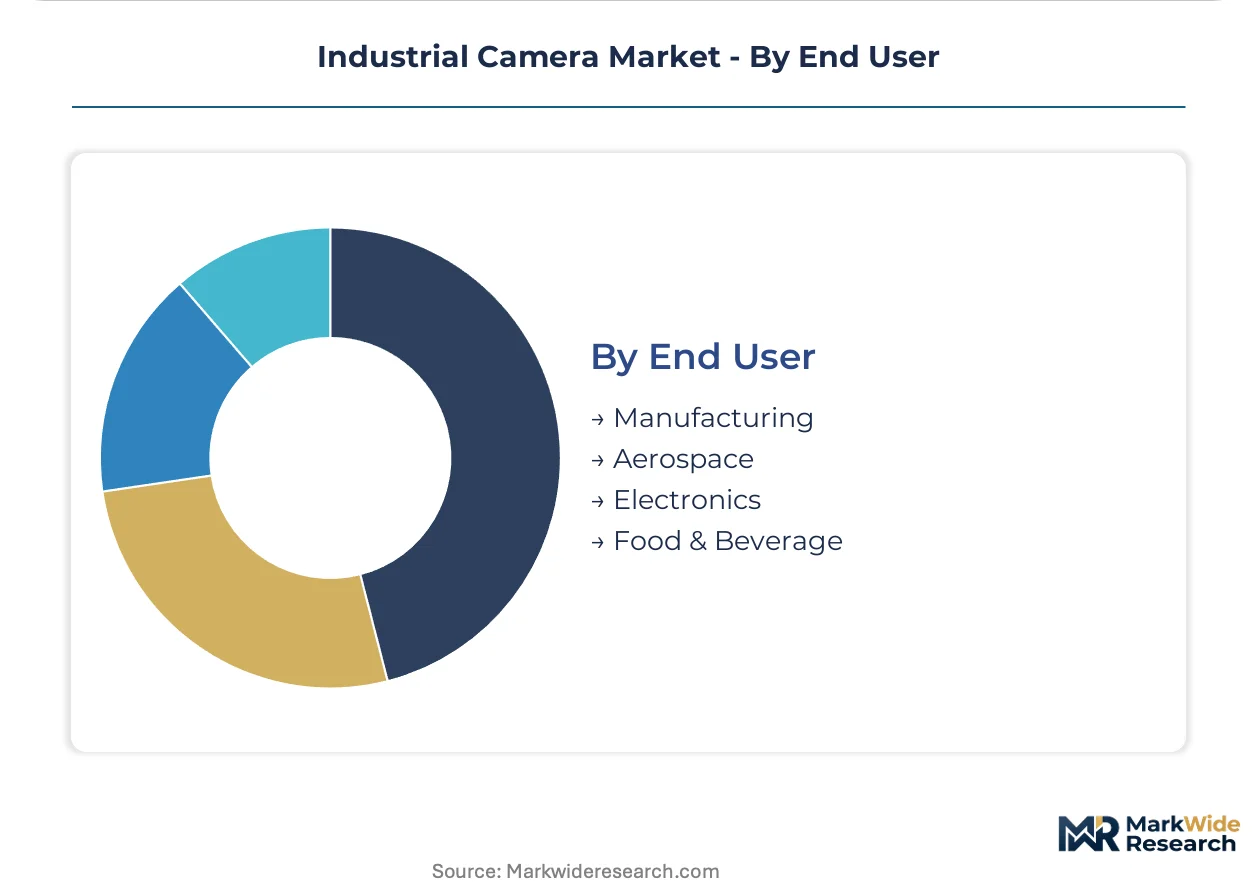
End User:
Industry-specific certification requirements and production economics drive divergent procurement patterns across manufacturing verticals, with automotive and electronics demanding the highest specification density.
- Electronics:Semiconductor fabrication and PCB assembly operations consume high-frame-rate cameras with sub-pixel measurement precision. Memory fab cleanrooms in South Korea specify vacuum-compatible camera housings and contamination-resistant cable assemblies, constrained by particle count standards that permeate equipment design decisions. Electronics leads volumes today; robotics-integrated manufacturing is gaining share fastest.
- Manufacturing:General industrial automation spans automotive assembly, metal fabrication, and packaging machinery with broad specification ranges.
- Aerospace:Precision metrology and composite inspection applications demand thermal stability and vibration resistance in camera platforms.
- Food & Beverage:Hygienic design requirements and washdown compatibility shape camera enclosure specifications for processing and packaging lines.
Electronics leads volumes today; robotics-integrated manufacturing is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany pioneered industrial machine vision integration during the 1980s automotive automation wave, establishing engineering standards that persist across European factory floors today. The sector's geographic footprint now spans precision manufacturing clusters across three continents.
China
Semiconductor fabs in Jiangsu and Zhejiang provinces are installing high-frame-rate area scan cameras for wafer defect detection. MIIT's smart manufacturing initiatives mandate vision system deployment in tier-one electronics facilities. The Yangtze River Delta electronics cluster consumes CMOS-based GigE Vision cameras for PCB inspection at compressed product lifecycle speeds.
Germany
Automotive battery module assembly lines in Bavaria and Baden-Württemberg are accelerating procurement of time-of-flight 3D cameras for robotic bin-picking. CE marking under the EU Machinery Directive governs electromagnetic compatibility validation timelines. Stuttgart's precision engineering corridor embeds AI-ready cameras with edge inference capabilities for real-time quality gates.
United States
Pharmaceutical packaging verification lines specify vision systems with deterministic GigE Vision interfaces and full audit trails. FDA quality system regulations under 21 CFR Part 11 shape electronic records requirements for camera specifications. Minnesota's medical device manufacturing corridor demands ISO 9001-certified suppliers with documented calibration traceability.
South Korea
Memory fab cleanrooms specify vacuum-compatible camera housings and contamination-resistant cable assemblies for automated optical inspection. MFDS pharmaceutical manufacturing guidelines extend to vision system validation for domestic drug packaging. Seoul Capital Area semiconductor foundries absorb high-frame-rate cameras driven by yield-critical fab economics.
India
Greenfield mobile phone assembly plants under the PLI scheme are creating virgin demand for machine vision in component production lines. BIS certification requirements filter supplier eligibility for electronics manufacturing facilities. Tamil Nadu and Karnataka electronics corridors specify plug-and-play vision systems over discrete component procurement.
Industrial Camera Market Competitive Environment
Premium-margin players sit above commodity-margin players across software-hardware integration depth, with tiered pricing separating full-stack vision platforms from sensor-only suppliers. The vendor base concentrates among European precision engineering houses, Japanese automation conglomerates, and North American imaging technology groups. Three archetypes dominate: vertically integrated automation platforms, specialized camera-lens-software bundlers, and sensor-agnostic software layer providers. M&A activity targets embedded vision engineering talent pools, while strategic partnerships secure CMOS foundry allocation during demand surges.
Within the specialized bundler tier, Basler AG and IDS Imaging Development Systems exemplify European engineering-focused positioning. Cognex Corporation anchors North American software-hardware integration approaches. These three occupy positions across the premium-to-standard spectrum without overlapping core competency claims.
| Leading Market Players |
|---|
| Keyence Corporation |
| Cognex Corporation |
| Basler AG |
| Teledyne Technologies |
| OMRON Corporation |
| Baumer |
| Teledyne DALSA |
| IDS Imaging Development Systems |
| Allied Vision Technologies |
| Others |
Value Chain & Pricing Dynamics
CMOS wafer pricing indices from Taiwan Semiconductor Manufacturing and Samsung Foundry cascade through three distinct camera tiers, compressing margins at the economy level while premium suppliers absorb volatility through software subscription bundling. Buyers in China's Yangtze River Delta electronics cluster face the steepest cost pass-through, whereas European automotive OEMs lock in multi-year contracts with thermal-stabilization subsystems.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments buyers by certification grade and embedded processing capability. Premium tiers command substantial markups for FDA-validated pharmaceutical packaging systems with deterministic GigE Vision interfaces, while economy tiers compete on frame-rate-per-dollar metrics for generic electronics inspection. Pricing pressure stems from sensor commoditization in high-volume CMOS categories, forcing mid-tier vendors toward software-defined differentiation. Contract manufacturers in India's PLI-subsidized mobile phone assembly plants exhibit the highest price sensitivity, whereas South Korean memory fabs prioritize yield-critical specifications over unit cost.
Supply Chain Analysis
ISO 9001 and CE marking compliance gates filter supplier eligibility before volume allocation, concentrating qualified component sources among established European and East Asian precision engineering houses. Advanced CMOS fabrication capacity centers on Taiwan and South Korea, with back-end packaging and lens assembly distributed across Germany, Japan, and China. Supply chains draw from specialized optical glass from Japan, precision mechanics from Germany, and CMOS dies from Taiwan foundries. Single-source vulnerability in 300mm CMOS wafer supply creates allocation risk during semiconductor demand surges. Distribution runs through authorized machine vision distributors and direct OEM relationships for high-specification deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion trajectories in industrial cameras rest on two structural forces: CMOS sensor commoditization enabling cost-down capture at the mid-tier, and subscription firmware licensing shifting revenue toward recurring software attach rates.
For Market Incumbents: Hedge against embedded vision module disintermediation by deepening software-hardware integration in robotics end-use applications. Prioritize captive supply arrangements with Taiwan foundries to secure CMOS allocation during demand surges. Defensive patent positioning around time-of-flight depth processing protects against Chinese camera module entrants. For New Entrants and Emerging Players: Enter via India's PLI-subsidized electronics manufacturing corridors, where greenfield assembly plants lack incumbent vision system relationships. Target plug-and-play vision bundles for mobile phone component inspection, bypassing discrete component procurement complexity. A software-first go-to-market with AI-ready edge inference capabilities differentiates against legacy hardware vendors. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized embedded vision engineering firms possessing FPGA programming and machine learning deployment cross-functional talent. Long-term viability favors acquisition targets with established CE marking validation records and recurring firmware revenue streams exceeding thirty percent of total sales. Watch for inflection in EU AI Act conformity assessment timelines as a signal for documentation software attach-rate expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into CMOS Foundry Allocation | Secures sensor supply for Basler AG and Teledyne DALSA during Taiwan fab capacity crunches. |
| Subscription Firmware Licensing Transition | Transforms Cognex Corporation revenue toward recurring AI model updates in North American food processing. |
| EU AI Act Compliance Documentation Services | Creates attach-rate opportunities for validation software in German automotive battery assembly lines. |
| India PLI Corridor Greenfield Partnerships | Establishes first-mover positioning in Tamil Nadu mobile phone component inspection stations. |
| Hyperspectral Imaging Module Integration | Opens pharmaceutical raw material inspection applications for OMRON Corporation in South Korean drug manufacturing. |
Study Parameters
Bottom-up electronics manufacturing modeling reconciled against top-down CMOS sensor supply tracking forms the analytical core of this study. Primary interviews with machine vision system integrators, automotive Tier 1 procurement directors, semiconductor fab equipment engineers, and pharmaceutical packaging line managers combined with secondary validation from SEC 10-K filings, MIIT smart manufacturing disclosures, EU Machinery Directive compliance databases, and customs trade data. Triangulation across these sources reconciles shipment volumes with foundry capacity allocation records.
Input-output matrices map CMOS sensor supply through camera OEM production to end-use deployment across quality control, robotics, and process automation applications. Segmentation dimensions include product architecture, sensor technology, application context, and end-user vertical. CAGRs derive from regression analysis of historical shipment data against fab capacity expansion schedules and regulatory mandate implementation timelines. Forecast inputs incorporate PLI scheme incentive disbursement rates and EU AI Act risk classification rollout pacing.
Inputs from Taiwan foundry utilization reports and German automotive production databases were available through the study window; gaps in Indian PLI scheme facility commissioning timelines introduce uncertainty bands around near-term volume projections. Forecasts reflect documented assumptions regarding CMOS technology transition pacing and robotics end-use adoption curves. A model refresh is warranted upon material change in EU AI Act enforcement timelines or Taiwan semiconductor export control configurations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Global Broadcast Cameras Market
Imaging
Global in Ceiling Camera Market
Imaging
Europe Thermal Imaging Systems Market
Imaging
X Ray Tubes Market
Imaging
Handheld Fluorescence Imaging Devices Market
Imaging
Global Automotive Imaging Market
Imaging
Micro-Magnetic Resonance Imaging Market
Imaging
Near Infra-Red Imaging Market
Imaging
PET Scanners Market
Imaging
Global Digital Photo Frame Market
Imaging
Asia Pacific IP Camera Market
Imaging
Video Microscopes Market
Imaging
EUV Mask Inspection System Market
Imaging
Europe Image Sensors Market
Imaging
Concrete Rebar Corrosion and Delamination Imaging Systems Market
Imaging
Semiconductor CD-SEM Systems Market