
 Microfluidic Devices Market | 2026-2036
Microfluidic Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Microfluidic Devices Market Intelligence
Manufacturing expansion in China and South Korea is fragmenting the supply base for polymer-based microfluidic components. Bio-Rad Laboratories leverages its established channels within life science research to distribute its cell sorting and analysis systems. Thermo Fisher Scientific differentiates through a comprehensive portfolio that integrates microfluidic consumables with its analytical instrument platforms. Meanwhile, Illumina dominates the genomics niche, with its devices optimized for high-throughput sequencing workflows.
Microfluidic devices are systems that manipulate and process minute fluid volumes, typically in the microliter to picoliter range, within channels with dimensions of tens to hundreds of micrometers. Their primary commercial purpose is to automate and miniaturize complex laboratory procedures, enabling high-throughput screening and rapid analysis. Lab-on-a-Chip technology represents the largest segment, driven by its integration capabilities for complex assays. In terms of application, point-of-care testing is the fastest-growing area, while drug discovery remains a mature and high-value segment for pharmaceutical firms.
The US FDA's 510(k) clearance pathway and Europe's CE marking under the MDR framework govern the approval of microfluidic devices for diagnostic use. In China, the NMPA sets standards for medical device registration, influencing market access for both domestic and foreign manufacturers. Navigating these varied regional compliance requirements for clinical validation and data submission is a critical decision point for device developers.
Market Dynamics
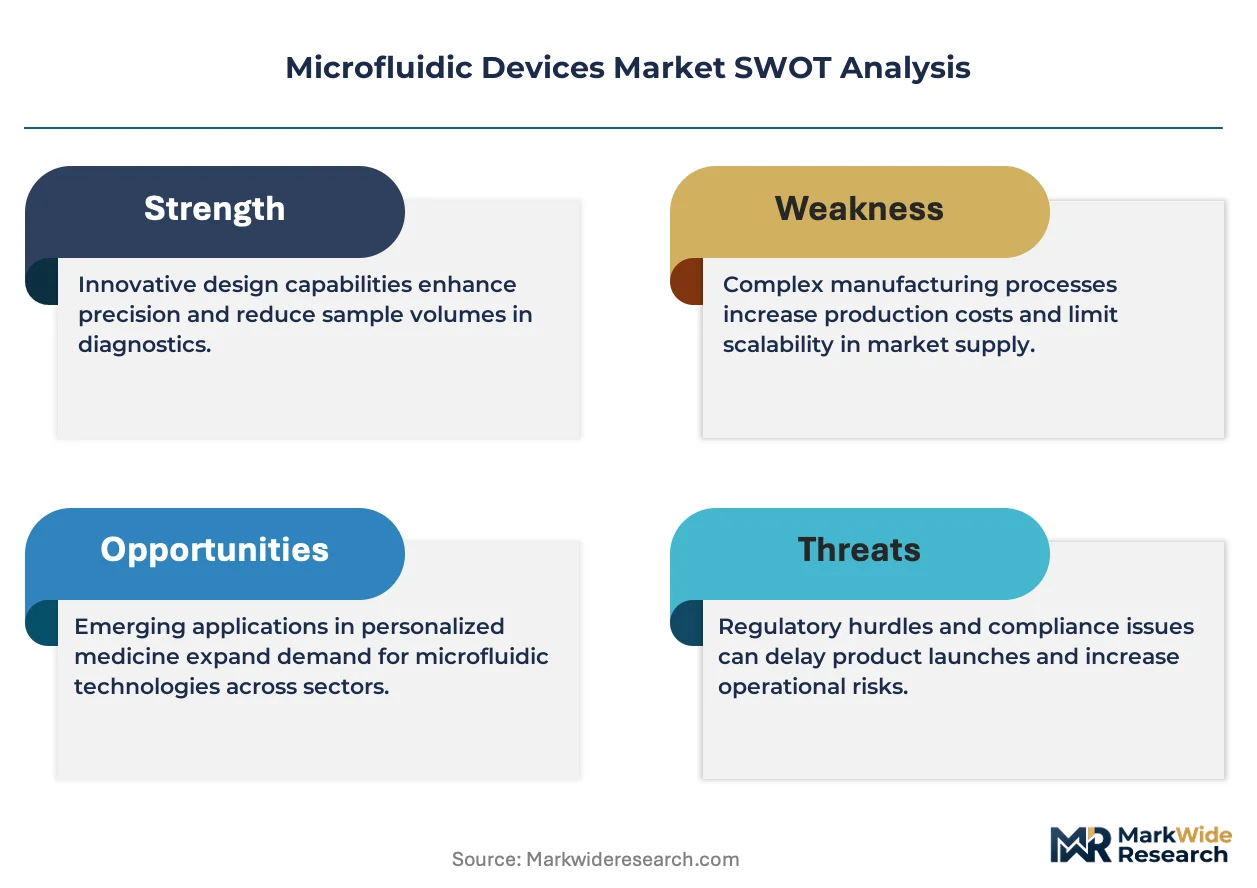
The miniaturization of complex laboratory assays into Lab-on-a-Chip formats is the central force shaping the microfluidic devices market. This drive for integration creates a structural tension between the demand for sophisticated, multi-functional devices and the manufacturing complexities involved in their mass production.
Growth Catalysts
- Point-of-Care Demand:The expansion of point-of-care testing for infectious diseases creates a primary demand source, particularly for rapid diagnostics in decentralized healthcare settings outside of traditional hospital laboratories.
- Academic Research Funding:Sustained government and private investment in biomedical research, especially within life science clusters in Germany and the United States, fuels requirements for advanced microfluidic tools for cell analysis and genomics.
- Lab-on-a-Chip Advancements:Continuous improvements in Lab-on-a-Chip technology enable greater integration of sample preparation, reaction, and detection steps onto a single device, accelerating development of complex assays for drug discovery.
Market Restraints
- High Fabrication Costs:The significant initial investment required for photolithography masks and molding tools for polymer and glass-based devices presents a cost barrier for smaller research institutions and startups.
- Lack of Standardization:The absence of universal standards for fluidic interconnects and device footprints complicates the integration of components from different manufacturers, hindering the development of modular systems.
- Material Supply Concentration:Manufacturing of high-purity polymers and specialty glass used in microfluidics is concentrated in a few suppliers, primarily in Asia-Pacific, creating potential supply chain risks for device manufacturers globally.
Strategic Opportunities
- Expansion into Agritech:The application of microfluidic devices for on-site soil nutrient analysis, water quality monitoring, and pathogen detection in food processing represents a significant new market vertical.
- Emerging Economies:Increased healthcare spending and infrastructure development in markets across Southeast Asia and Latin America create new opportunities for deploying microfluidic-based diagnostic platforms.
- On-Chip AI Integration:Incorporating machine learning algorithms directly onto microfluidic chips for real-time data analysis and decision-making can create next-generation smart diagnostic devices with enhanced accuracy.
Industry Challenges
- Regulatory Navigation:Managing the distinct and complex regulatory approval pathways for diagnostic devices, such as the FDA's 510(k) process in the US and the CE marking under MDR in Europe, requires significant specialized expertise and resources.
- Data Interoperability:A lack of standardized data formats from microfluidic instruments complicates integration with existing laboratory information management systems (LIMS) and electronic health records.
- Cross-Disciplinary Talent:A scarcity of engineers and scientists with combined expertise in microfabrication, fluid dynamics, molecular biology, and software engineering creates a bottleneck in product development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Microfluidic Devices Market |
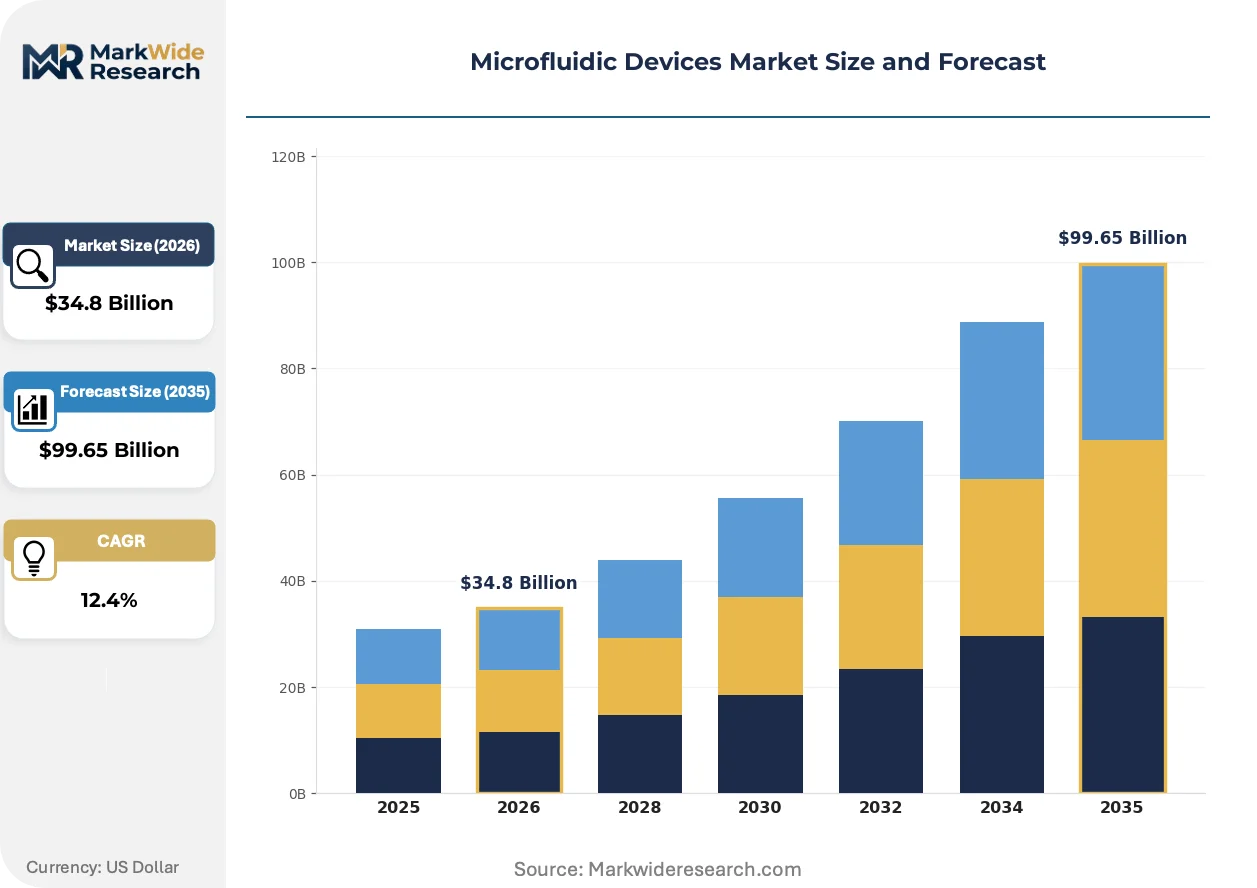
| Market Size in 2026 | $34.8 Billion |
| Market Size in 2035 | $99.65 Billion |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flow Focusing Devices, Droplet Generators, Cell Sorters, Microvalves, Micropumps Technology: Lab-on-a-Chip, Digital Microfluidics, Paper-Based, Capillary Action, Inkjet-Printed Application: Point-of-Care Testing, Drug Discovery, Environmental Monitoring, Chemical Synthesis, Food Safety Analysis End User: Biotechnology Companies, Academic Research Institutes, Pharmaceutical Firms, Environmental Agencies, Contract Research Organizations |
| Companies Covered | Bio-Rad Laboratories, F. Hoffmann-La Roche Ltd, Thermo Fisher Scientific, Standard BioTools, Illumina, Agilent Technologies, PerkinElmer, Abbott, Danaher Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Microfluidic Devices Market Strategic Shifts & Innovations
The market's evolution is defined by the push for greater automation and the integration of data analytics directly at the point of analysis. This trend moves devices from single-function tools to intelligent systems capable of performing complex, multi-step workflows with minimal human intervention.
Digital microfluidics (DMF) technology manipulates discrete droplets of fluid using electrical fields on an array of electrodes. Research laboratories in pharmaceuticals and genomics are adopting DMF to automate complex sample preparation protocols for applications like next-generation sequencing. This technology is digitizing previously manual liquid handling workflows, thereby reducing reagent volumes and minimizing the potential for human error.
Europe's In Vitro Diagnostic Regulation (IVDR) establishes a more stringent framework for the approval and post-market surveillance of diagnostic devices. The regulation elevates the requirements for clinical evidence and risk management, impacting manufacturers seeking CE marking. The point-of-care testing segment is particularly affected, as companies must now generate more comprehensive performance data to validate their devices for clinical use.
A clear shift toward decentralized research models and remote patient monitoring is altering procurement patterns for analytical instruments. This trend challenges the dominance of large, centralized laboratories by creating demand for portable, easy-to-use microfluidic systems that can be operated by non-specialists. This dynamic is most prominent in North American and European healthcare systems focused on improving patient access and reducing hospital-centric care costs.
Microfluidic Devices Market Segmentation
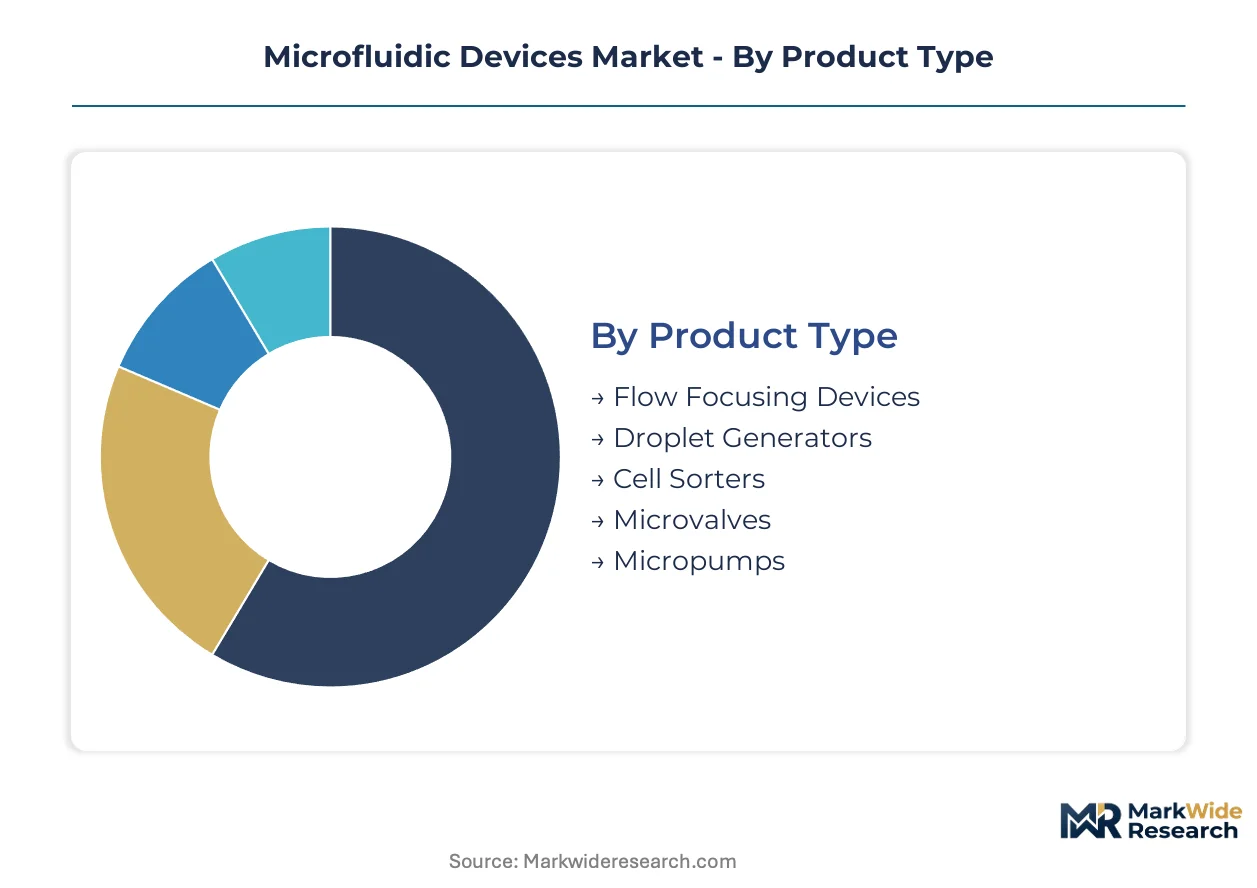
The microfluidic devices market is highly differentiated, requiring granular analysis across various dimensions to understand specific demand drivers and competitive landscapes. Segmentation highlights key areas of innovation, application growth, and end-user adoption patterns shaping market evolution.
Product Type:
The after-sales service intensity for microfluidic devices varies significantly by product type, reflecting the complexity of maintenance and calibration required for each category.
- Flow Focusing Devices:These devices precisely control the flow of two or more immiscible fluids to generate droplets or particles of uniform size, crucial for single-cell analysis and emulsion creation. Demand concentrates in advanced biological research within the United States, driven by new assay development.
- Droplet Generators:Systems designed to create discrete, reproducible picoliter to nanoliter droplets, enabling high-throughput screening and digital PCR applications. Pharmaceutical firms in Germany increasingly adopt these for drug screening, seeking enhanced assay sensitivity.
- Cell Sorters:Microfluidic components that isolate specific cell populations from heterogeneous samples based on physical or biochemical properties.
- Microvalves:Miniaturized components controlling fluid flow within microchannels, essential for automating complex liquid handling tasks in diagnostic systems.
- Micropumps:Devices that actively move small fluid volumes, critical for continuous flow systems and portable analytical instruments.
By volume, Flow Focusing Devices lead. By growth pace, Droplet Generators are ahead.
Technology:
The application focus of different microfluidic technologies dictates their market penetration, with some technologies enabling broad utility while others target niche, high-value segments.
- Lab-on-a-Chip:These integrated devices combine multiple laboratory functions onto a single chip, facilitating complex assays from sample preparation to detection. Their integration capabilities are driving adoption in point-of-care diagnostics across Europe.
- Digital Microfluidics:This technology manipulates discrete droplets using electrical fields on an array of electrodes, enabling flexible and reconfigurable liquid handling without physical channels. Genomics research in the United States leverages DMF for automated sample preparation.
- Paper-Based:Low-cost, disposable platforms utilizing paper's capillary action for fluid transport, primarily used in rapid diagnostic tests in emerging economies.
- Capillary Action:Passive fluid movement driven by surface tension and channel geometry, foundational for many point-of-care and lateral flow assays.
- Inkjet-Printed:A fabrication method that deposits functional materials in precise patterns to create microfluidic structures, offering cost-effective prototyping and mass production.
Lab-on-a-Chip technology demonstrates the broadest market penetration, while Digital Microfluidics is gaining adoption in high-throughput applications.
Application:
The customer type for microfluidic devices varies significantly across applications, influencing product design and regulatory pathways for market access.
- Point-of-Care Testing:Devices designed for rapid diagnostics outside central laboratories, often used by healthcare providers or patients directly. Demand is expanding for infectious disease diagnostics in decentralized healthcare settings.
- Drug Discovery:Microfluidic platforms used by pharmaceutical companies for high-throughput screening, cell culture, and toxicology studies during the drug development process. This remains a high-value segment for pharmaceutical firms globally.
- Environmental Monitoring:Applications include on-site detection of pollutants, water quality analysis, and pathogen identification in environmental samples.
- Chemical Synthesis:Microreactors and microfluidic systems used for controlled chemical reactions, offering advantages in yield and safety for specialized compounds.
- Food Safety Analysis:Devices for rapid detection of contaminants, allergens, and pathogens in food products, ensuring consumer protection.
Point-of-Care Testing represents a strategic investment area for device developers, while Drug Discovery remains a critical, established application for pharmaceutical R&D.
End User:
Supply concentration for microfluidic components can impact end-user procurement strategies, particularly for specialized materials or fabrication services.
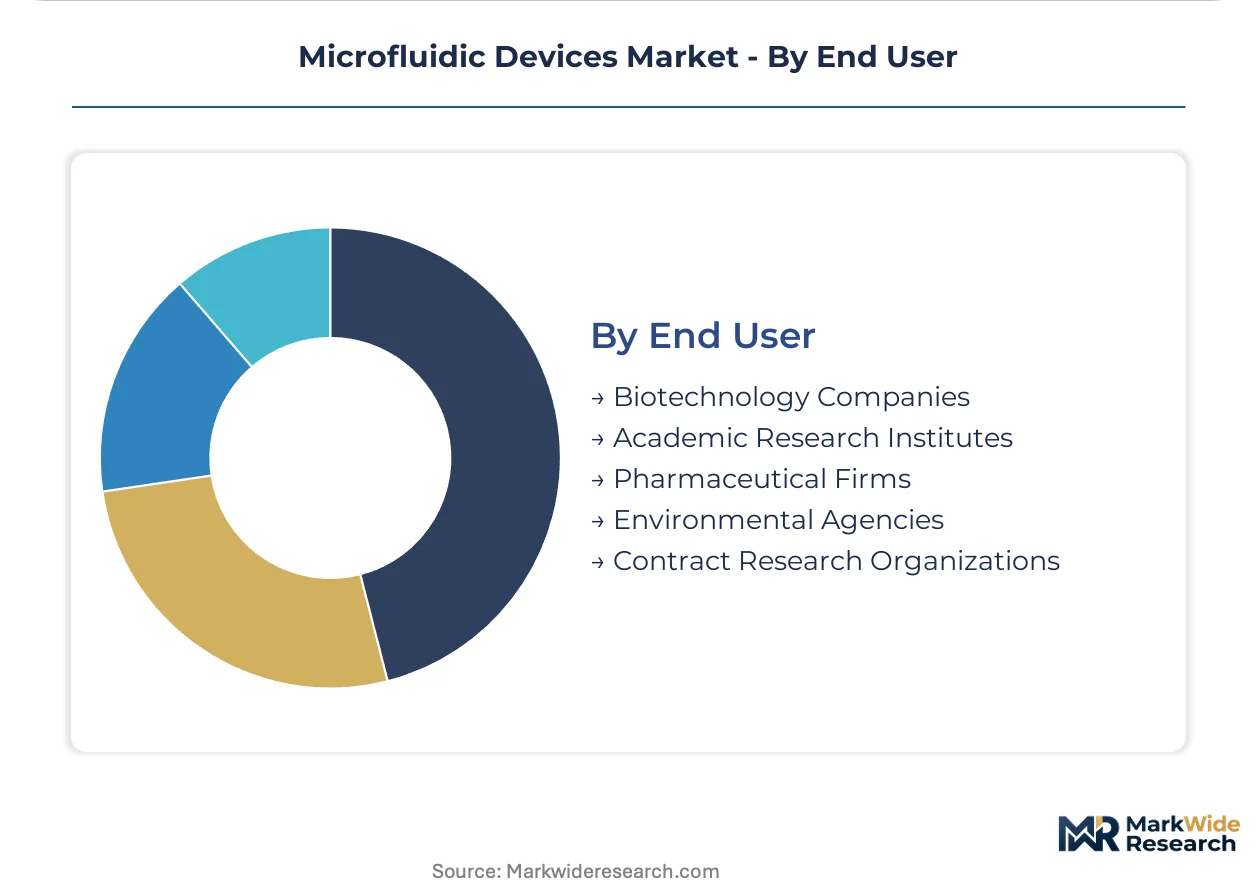
- Biotechnology Companies:These firms utilize microfluidic devices for genomics, proteomics, cell biology research, and the development of novel diagnostic assays. They frequently seek custom solutions for complex biological experiments.
- Academic Research Institutes:Universities and public research centers employ microfluidic tools for fundamental scientific discovery, assay development, and educational purposes. Significant funding in Germany and the United States supports this segment.
- Pharmaceutical Firms:Large drug developers integrate microfluidic systems into their R&D pipelines for drug screening, toxicity testing, and personalized medicine.
- Environmental Agencies:Government and private organizations using microfluidic sensors for field-based environmental analysis and public health monitoring.
- Contract Research Organizations:Companies providing outsourced research services to pharmaceutical and biotech firms, adopting microfluidics for efficiency and cost reduction.
Biotechnology Companies drive significant procurement of advanced microfluidic systems, while Academic Research Institutes influence the early adoption of new microfluidic technologies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The microfluidic devices market exhibits distinct regional dynamics, particularly concerning material supply and manufacturing. Asia-Pacific countries, notably China and South Korea, demonstrate significant concentration in the fabrication of high-purity polymers and specialty glass components. This supply base influences global distribution and device development.
United States
The United States market drives significant demand for advanced microfluidic tools in biomedical research and genomics. FDA's 510(k) clearance pathway governs diagnostic device approvals, influencing market entry. Research clusters in regions like Boston and the San Francisco Bay Area lead innovation in digital microfluidics and single-cell analysis technologies.
Germany
Germany exhibits strong demand for microfluidic devices, particularly from academic research institutes and pharmaceutical firms for drug screening applications. CE marking under the MDR framework sets stringent requirements for diagnostic devices within the country. Life science clusters around Munich and Heidelberg foster new assay development and adoption of droplet generator systems.
China
Chinese manufacturing expansion significantly influences the global supply of polymer-based microfluidic components. The NMPA sets comprehensive standards for medical device registration, impacting market access for both domestic and foreign manufacturers. Major manufacturing hubs in the Yangtze River Delta actively produce microfluidic consumables for various diagnostic applications.
South Korea
South Korea contributes substantially to the global manufacturing base for microfluidic components, particularly in polymer fabrication. The MFDS regulates medical devices, ensuring compliance for both local production and imports. Technology and biotech clusters in Seoul and Daejeon focus on developing devices optimized for high-throughput genomics and advanced diagnostics.
France
French healthcare systems drive demand for integrated Lab-on-a-Chip solutions in point-of-care diagnostics. Europe's IVDR establishes stringent frameworks for diagnostic device approval, impacting manufacturers seeking CE marking. Biomedical research centers in Paris-Saclay concentrate on developing portable microfluidic systems for rapid analysis.
Microfluidic Devices Market Key Industry Players
Integrated solution providers and specialized niche players split the microfluidic devices market, exhibiting a tiered competitive structure. Large diversified companies offer comprehensive portfolios, while smaller firms often focus on specific applications or component manufacturing. Competitive moves include strategic partnerships to expand technological capabilities and portfolio diversification to capture emerging application areas.
Among integrated solution providers, Thermo Fisher Scientific exemplifies a strategy of offering comprehensive analytical instrument platforms that integrate microfluidic consumables, catering to a broad scientific research base. Illumina, Inc. occupies a prominent position within the genomics niche, anchoring high-throughput sequencing workflows with its optimized microfluidic devices. Bio-Rad Laboratories, Inc. represents established channels within life science research, supplying cell sorting and analysis systems to academic and industrial clients. These companies collectively demonstrate the market's differentiation between broad portfolio offerings and specialized application focus.
| Leading Market Players |
|---|
| Bio-Rad Laboratories |
| F. Hoffmann-La Roche Ltd |
| Thermo Fisher Scientific |
| Standard BioTools |
| Illumina |
| Agilent Technologies |
| PerkinElmer |
| Abbott |
| Danaher Corporation |
| Others |
Cost & Logistics Intelligence
Underutilization of polymer fabrication capacity in Asia-Pacific influences global component pricing, driving competitive supplier behavior and affecting the cost structure for device manufacturers. This dynamic shapes both the final product pricing and strategic sourcing decisions across the microfluidic devices market.
Pricing Analysis
FDA's 510(k) clearance pathway dictates the pricing tier structure for diagnostic microfluidic devices, impacting market entry and perceived value. Pricing for integrated platforms follows a value-based model, reflecting advanced functionality and data analytics capabilities. Price differentiation stems from integration capabilities and comprehensive after-sales service, particularly for complex Lab-on-a-Chip systems. Downward pricing pressure emerges from increased manufacturing output in China, while academic research institutes demonstrate higher price sensitivity compared to pharmaceutical firms.
Supply Chain Analysis
Upstream feedstock for high-purity polymers and specialty glass components originates primarily from China and South Korea, forming a concentrated supply base. Device manufacturers rely on these specialized materials, including micro-electromechanical components, for fabricating advanced microfluidic systems. Single-source vulnerability for specific high-performance materials presents a structural risk for global production lines. Downstream distribution typically involves direct sales for large analytical instruments and specialized distributors for microfluidic consumables and niche components.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a high-growth disruption, driven by continuous Lab-on-a-Chip advancements and the expanding demand for point-of-care diagnostics. These technological and application inflections are reshaping strategic imperatives for all market participants.
For Market Incumbents: Harden intellectual property portfolios through strategic patenting in digital microfluidics and AI integration to counter emerging technological threats. Invest in localized manufacturing capabilities within key demand regions like the United States and Germany to mitigate supply chain risks. Strengthen established distribution channels for cell sorting and analysis systems, leveraging existing customer relationships against new market entrants. Enhance after-sales service offerings to differentiate complex analytical instrument platforms.
For New Entrants and Emerging Players: Agritech applications for on-site soil nutrient analysis and water quality monitoring represent a penetrable entry point for new microfluidic device developers. Target emerging economies in Southeast Asia with low-cost, disposable paper-based diagnostic platforms for rapid infectious disease testing. Emphasize ease-of-use and minimal infrastructure requirements as a core go-to-market angle. Focus on specific component manufacturing, like microvalves or micropumps, to establish a niche before expanding into integrated systems.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among firms providing integrated microfluidic consumables and software subscriptions for high-throughput genomics workflows. Long-term viability hinges on sustained demand from decentralized diagnostics and pharmaceutical R&D over the next decade. Acquisition targets should prioritize specialized component manufacturers or software analytics firms enhancing on-chip AI integration. The signal to watch is regulatory harmonization progress for diagnostic devices across major economic blocs.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Integrating microfluidic consumables with analytical instrument platforms enhances user workflow and strengthens customer loyalty for Thermo Fisher Scientific. |
| Geographic Expansion | Expanding manufacturing footprint into emerging economies like Southeast Asia addresses localized demand for cost-effective diagnostic solutions. |
| Regulatory Approval Pathway | Navigating the FDA's 510(k) process or Europe's CE marking is critical for market access for diagnostic device developers. |
| Strategic Partnership | Forming alliances with academic research institutes accelerates the development and commercialization of novel Lab-on-a-Chip technologies. |
| Software Companion Development | Developing software for real-time data analysis and LIMS integration improves the utility of microfluidic diagnostic devices. |
Research Approach
Findings reconcile primary fieldwork against secondary review of regulatory filings, academic journals, and company annual reports to ensure data robustness. Interviews included R&D directors, procurement managers, regulatory affairs specialists, and clinical lab heads to gather diverse perspectives. This approach incorporated both bottom-up market sizing and top-down validation. The analysis triangulates qualitative insights with quantitative market data for comprehensive understanding.
Forecast inputs considered market dynamics across the analysis window, integrating technological advancements and regulatory shifts. Segmentation dimensions modeled included product type, technology, application, end user, and the regional regulatory environment. Compound annual growth rates were derived from historical data analysis and projected future demand trends. Key forecast inputs included government research funding levels and global healthcare infrastructure development.
Practitioners should monitor new regulatory shifts, material supply disruptions, and significant technological breakthroughs for early signals of forecast revision. Forecasts reflect assumptions documented at the time of publication. Cross-checking against industry association reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Instruments
Microanalysis Sample Preparation Systems Market
Analytical Instruments
Ultraviolet (UV) Analyzer Market
Analytical Instruments
Global Handheld LCR Meters Market
Analytical Instruments
Micro Balances Market
Analytical Instruments
North America Surface Analysis Market
Analytical Instruments
Asia-Pacific Dissolved Gas Analyzer Market
Analytical Instruments
Vapor Pressure Analyzer Market
Analytical Instruments
Electron Microscope Sample Preparation Market
Analytical Instruments
Electron Probe Microanalyzers (EPMA) Market
Analytical Instruments
Global Fluorescence Spectrophotometer Market
Analytical Instruments
Scientific Instruments Market
Analytical Instruments
Global Ultrapycnometer Market
Analytical Instruments
TDLAS Moisture Analyzers Market
Analytical Instruments
Boron Analyzer Market
Analytical Instruments
ICP-MS System Market
Analytical Instruments
Gas Chromatography Systems Market