
 Microanalysis Sample Preparation Systems Market | 2026-2036
Microanalysis Sample Preparation Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Microanalysis Sample Preparation Systems Market Analytics
Automated ion milling and cryo-preparation is fragmenting the legacy manual workflow stack across electron microscopy labs. Thermo Fisher Scientific leverages its cryo-EM sample preparation portfolio to anchor high-end structural biology installations. JEOL sustains proprietary focused ion beam systems that dominate materials science departments in East Asian universities. Leica Microsystems competes through cryo-ultramicrotomy specialization, extending its installed base across European neuroscience institutes.
Microanalysis sample preparation systems encompass instruments and consumables that condition specimens—through sectioning, polishing, ion milling, or coating—to achieve electron-transparent, contamination-free surfaces suitable for electron microscopy, mass spectrometry, or spectroscopic interrogation, typically targeting thicknesses below 100 nanometers for transmission electron microscopy. Automated systems command the widest installed base in high-throughput pharmaceutical quality control, while hybrid systems represent the fastest-growing configuration as laboratories blend manual oversight with programmable repeatability for complex biological specimens. Manual systems retain durable demand in academic settings where budget constraints and pedagogical requirements favor operator-direct control over preparation parameters.
FDA 21 CFR Part 11 electronic records requirements and EPA SW-846 methods shape validation protocols for forensic and environmental laboratories selecting preparation equipment, while ISO 17025 accreditation standards drive repeatability specifications across contract research organizations. The EU MDR and REACH substance restrictions additionally constrain consumable chemistry formulations sold into European clinical and materials testing facilities. Stakeholders must weigh capital deployment between fully automated platforms and modular hybrid architectures as regulatory traceability requirements diverge across jurisdictions.
Market Dynamics
Automated ion milling and cryo-preparation systems are compressing legacy manual workflows across electron microscopy laboratories, forcing capital reallocation toward programmable repeatability and regulatory-compliant traceability.
Growth Catalysts
- FDA 21 CFR Part 11:Electronic records mandates in forensic and environmental laboratories validate investment in automated preparation platforms with audit-ready data logging.
- Pharmaceutical quality control:High-throughput screening of biologics and nanomedicines demands specimen throughput exceeding manual preparation capacity.
- German industrial research clusters:Concentrated microscopy infrastructure in Baden-Württemberg and Bavaria sustains replacement cycles for precision preparation equipment.
Market Restraints
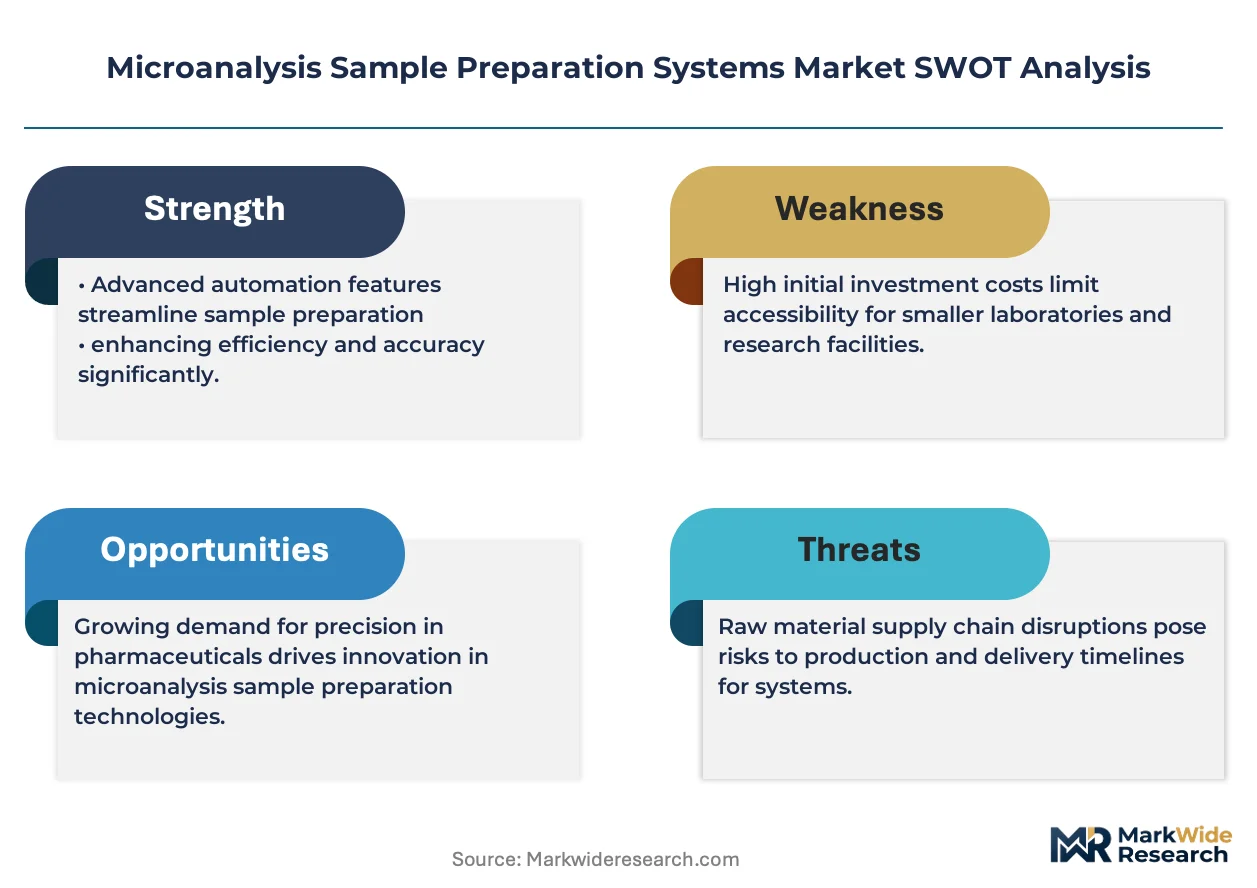
- Helium supply concentration:Focused ion beam systems depend on helium imports from Qatar and Russia, exposing operations to geopolitical disruption and price volatility.
- Technical limitation in cryo-transfer:Contamination rates during vitreous specimen transfer between preparation and imaging chambers exceed tolerances for certain structural biology applications.
- EU REACH substance restrictions:Reformulation of embedding resins and conductive coatings delays consumable certification and raises compliance costs for European facilities.
Strategic Opportunities
- India's semiconductor fabrication push:PLI scheme incentives for domestic chip manufacturing create demand for materials characterization infrastructure including sample preparation systems.
- Cryo-electron tomography expansion:Convergence of cryo-EM hardware with computational reconstruction pipelines opens clinical diagnostic applications previously confined to research.
- Service unbundling:Independent service providers now offer certified maintenance and consumable resupply outside OEM channels, lowering total cost of ownership for mid-tier laboratories.
Industry Challenges
- Cross-disciplinary technician scarcity:Operation of hybrid automated-manual systems requires simultaneous competence in materials science, electron optics, and software scripting.
- ISO 17025 accreditation timelines:Contract research organizations face 12-18 month validation periods for new preparation equipment, delaying revenue generation from installed capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Microanalysis Sample Preparation Systems Market |
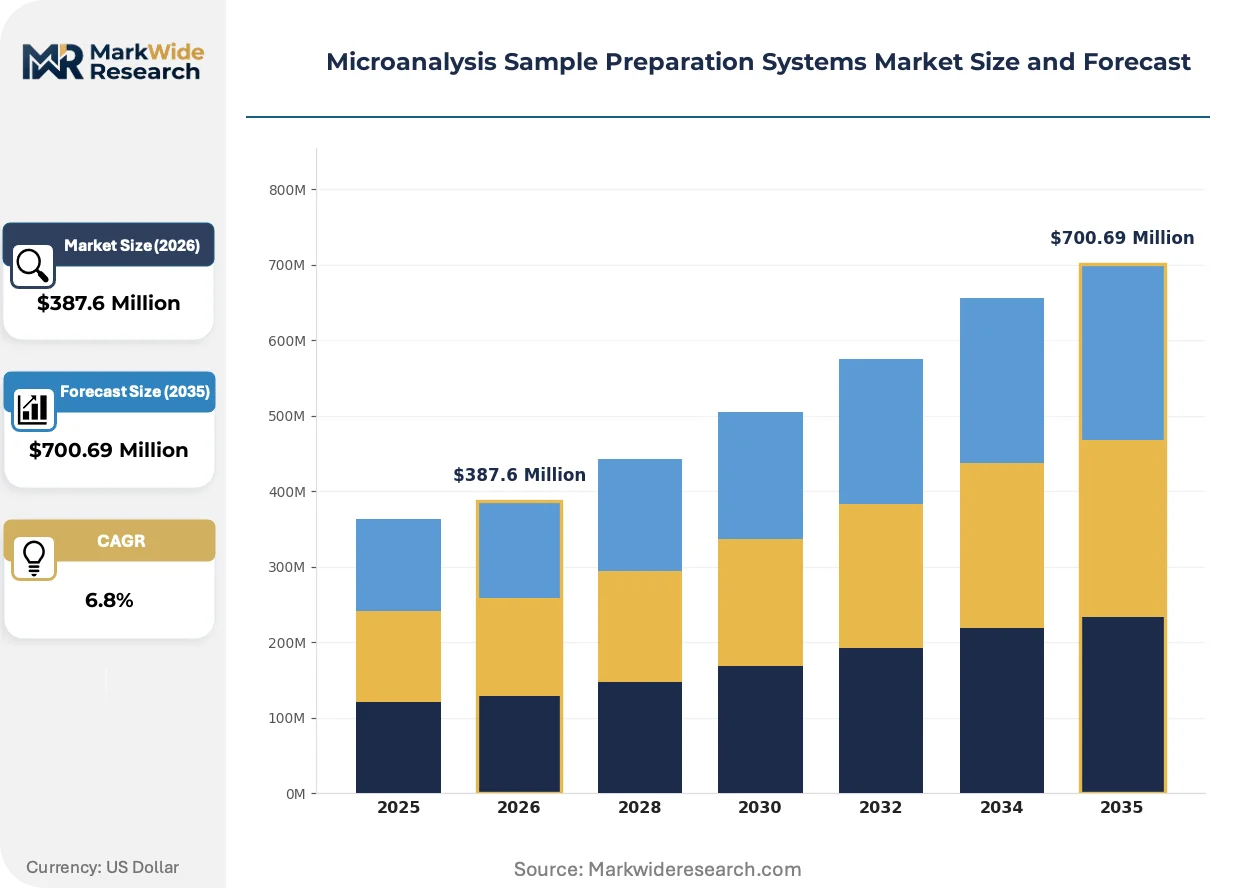
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
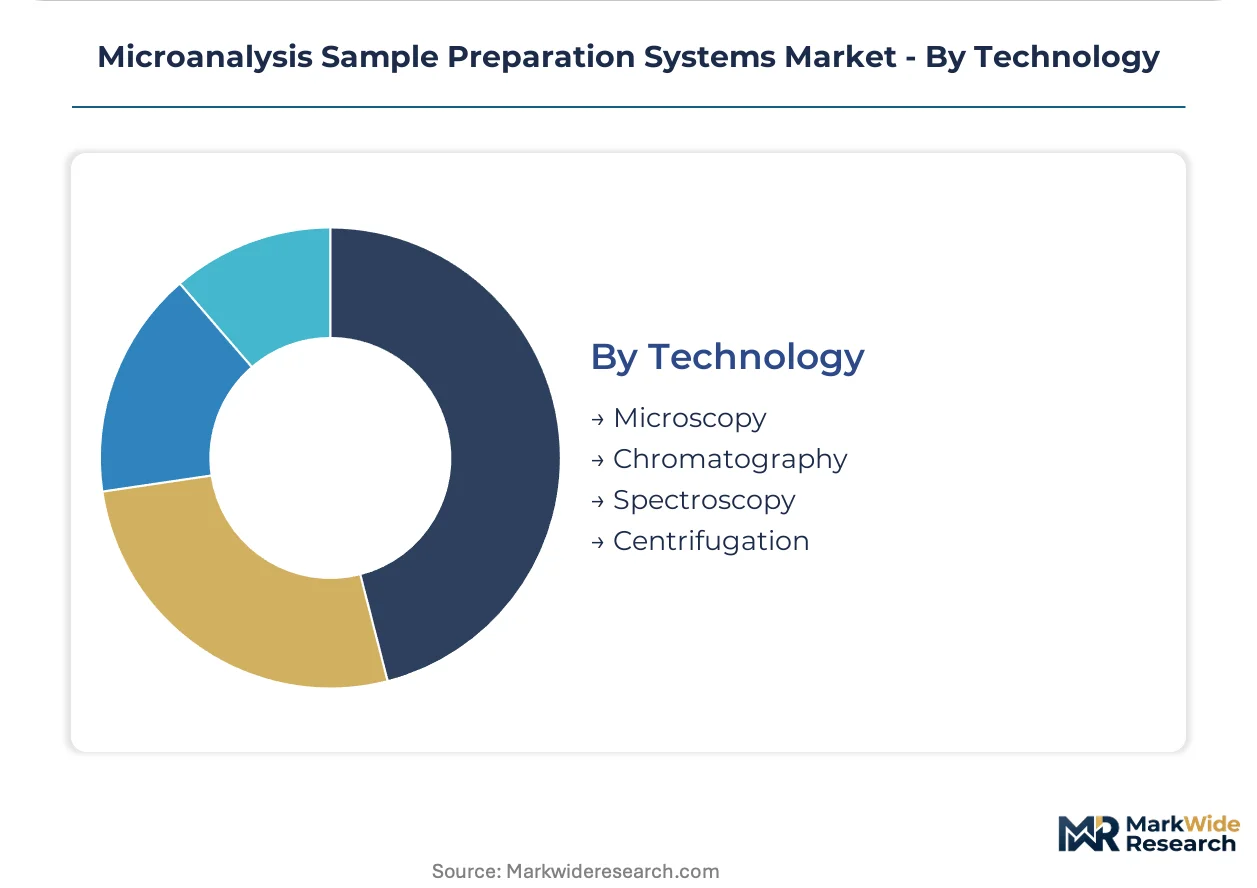
| Segmentation | Product Type: Automated Systems, Manual Systems, Semi-Automated Systems, Hybrid Systems End User: Academic Institutions, Research Laboratories, Industrial Labs, Pharmaceutical Companies Application: Material Analysis, Biological Analysis, Chemical Analysis, Forensic Analysis Technology: Microscopy, Chromatography, Spectroscopy, Centrifugation |
| Companies Covered | Thermo Fisher Scientific, JEOL, Leica Microsystems, Hitachi High-Technologies Corporation, Carl Zeiss, Gatan, Agilent Technologies, Merck KGaA, Danaher Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Microanalysis Sample Preparation Systems Market Evolving Landscape
Preparation workflows are converging with computational imaging pipelines, compressing the boundary between physical specimen conditioning and digital analysis. Three developments dominate this transition.
Correlative light-electron microscopy preparation is hybridizing fluorescence labeling with electron-transparent sectioning. Neuroscience institutes and cell biology departments adopt these integrated workflows to track dynamic processes before ultrastructural interrogation. The technology is hybridizing previously separate optical and electron microscopy capital budgets into unified procurement decisions.
EPA SW-846 method updates are tightening contamination thresholds for environmental specimen preparation. Laboratories analyzing soil and groundwater samples must demonstrate sub-part-per-billion cleanliness in grinding and polishing steps. American contract testing facilities respond by retrofitting manual stations with enclosed automated mills and positive-pressure enclosures.
Consolidated procurement by pharmaceutical central labs is displacing distributed purchasing authority at individual R&D sites. Equipment selection now flows through global capital committees prioritizing vendor interoperability and multi-site service coverage. This concentration is most visible in Switzerland and Massachusetts, where headquarters functions dominate analytical infrastructure decisions.
Microanalysis Sample Preparation Systems Market Segmentation

Segmentation in microanalysis sample preparation systems reveals distinct service lifecycle patterns. Automated platforms demand intensive calibration contracts and consumable replenishment programs. Manual and hybrid configurations shift margin toward training services and operator certification.
Product Type:
After-sales service intensity varies sharply across automation tiers, with field engineering requirements scaling directly with system complexity.
- Automated Systems:Fully programmable specimen conditioning platforms integrate ion milling, coating, and polishing sequences with minimal operator intervention. Pharmaceutical quality control labs in Switzerland and Massachusetts concentrate procurement here, driven by FDA 21 CFR Part 11 audit trail mandates for electronic records.
- Hybrid Systems:Configurations blend programmable repeatability with manual override capabilities for complex biological specimens. Neuroscience institutes across Germany and Japan favor these architectures where specimen variability exceeds pure automation tolerance.
- Manual Systems:Operator-direct control over sectioning and polishing parameters serves pedagogical requirements in academic settings.
- Semi-Automated Systems:Intermediate positioning offers programmable stage movement with manual specimen loading.
Automated systems hold the largest share; momentum sits with hybrid systems as laboratories seek flexibility without full automation capital commitment.
End User:
Customer type determines purchasing authority structure, from decentralized academic procurement to centralized pharmaceutical capital committees.
- Pharmaceutical Companies:Centralized analytical infrastructure decisions in headquarters locations prioritize vendor interoperability and multi-site service coverage. High-throughput biologics screening in Swiss and Massachusetts facilities demands specimen throughput exceeding manual preparation capacity.
- Academic Institutions:Budget-constrained environments favor manual systems where pedagogical requirements emphasize operator-direct parameter control. European neuroscience institutes represent concentrated demand for cryo-ultramicrotomy specialization.
- Research Laboratories:Contract research organizations face extended ISO 17025 accreditation timelines that delay revenue generation from new preparation equipment.
- Industrial Labs:Materials characterization facilities in German industrial clusters sustain replacement cycles for precision preparation infrastructure.
Pharmaceutical companies command the largest share; academic institutions are expanding most quickly as cryo-EM structural biology investments proliferate.
Application:
Application focus shapes regulatory compliance requirements and contamination tolerance specifications.
- Biological Analysis:Cryo-preparation workflows for structural biology and clinical diagnostics demand vitreous specimen preservation below 100 nanometers. Correlative light-electron microscopy hybridization is concentrating investment in neuroscience institutes.
- Material Analysis:Focused ion beam systems for semiconductor and advanced materials characterization depend on helium supply chains exposed to geopolitical disruption.
- Chemical Analysis:Specimen preparation for mass spectrometry and chromatographic interrogation requires contamination-free surfaces.
- Forensic Analysis:EPA SW-846 method compliance drives retrofitting of manual stations with enclosed automated mills in American contract testing facilities.
Biological analysis holds the largest share; material analysis is gaining share fastest as India's semiconductor fabrication push creates infrastructure demand.
Technology:
Technology base determines consumable chemistry requirements and capital replacement cycles.
- Microscopy:Electron microscopy preparation encompasses sectioning, polishing, ion milling, and coating to achieve electron-transparent surfaces. JEOL and Carl Zeiss anchor supply chains serving German industrial research clusters.
- Spectroscopy:Surface preparation for X-ray and electron spectroscopic interrogation demands contamination control exceeding optical microscopy tolerance.
- Chromatography:Sample conditioning for separation science emphasizes solvent compatibility and thermal stability.
- Centrifugation:Density gradient and ultracentrifugation protocols serve biological specimen fractionation prior to microscopic analysis.
Microscopy holds the largest share; spectroscopy shows the steepest expansion trajectory as environmental contamination thresholds tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision instrumentation exports flow primarily into Swiss pharmaceutical central labs and East Asian materials science departments, establishing a trade corridor that concentrates high-end system deployment in regulatory-intensive markets.
United States
FDA 21 CFR Part 11 electronic records mandates and EPA SW-846 method updates drive forensic and environmental laboratories toward automated preparation platforms with audit-ready data logging. The Boston-Cambridge biotechnology cluster sustains concentrated procurement of cryo-EM sample preparation infrastructure for structural biology applications.
Germany
Industrial research clusters in Baden-Württemberg and Bavaria anchor replacement cycles for precision preparation equipment serving materials characterization workflows. EU MDR and REACH substance restrictions constrain consumable chemistry formulations, delaying certification timelines for embedding resins and conductive coatings. JEOL and Carl Zeiss supply chains concentrate advanced microscopy infrastructure across these southern German states.
Switzerland
Swissmedic regulatory frameworks and centralized pharmaceutical capital committees prioritize vendor interoperability and multi-site service coverage in equipment selection. Basel and Zurich headquarters functions dominate analytical infrastructure decisions for global biologics screening operations. High-throughput specimen preparation demands exceed manual capacity in these concentrated R&D facilities.
Japan
METI industrial policy and PMDA quality standards shape validation protocols for electron microscopy preparation systems in pharmaceutical and materials applications. Tokyo and Osaka metropolitan areas host concentrated neuroscience institutes deploying cryo-ultramicrotomy specialization for cellular ultrastructure research. JIS standards compliance drives repeatability specifications across domestic contract research organizations.
India
PLI scheme incentives for domestic semiconductor fabrication create emerging demand for materials characterization infrastructure including focused ion beam preparation systems. Karnataka and Telangana states concentrate emerging chip manufacturing investments requiring electron-transparent specimen conditioning for process control. BIS standards adoption lags behind procurement timelines, creating validation bottlenecks for imported equipment.
Microanalysis Sample Preparation Systems Market Competitive Landscape
On the supply side, the industry is structured around three distinct capability tiers anchored by diversified life science conglomerates, specialized microscopy houses, and precision instrumentation boutiques. Diversified conglomerates leverage cross-divisional service networks and consumable recurring revenue streams. Specialized houses compete through proprietary ion beam architectures and cryogenic workflow integration. Boutique operators capture niche applications through ultramicrotomy specialization and regional service proximity. Competitive moves concentrate on strategic partnerships for software interoperability and geographic expansion through distributor networks in emerging fabrication markets.
Among diversified life science conglomerates, Thermo Fisher Scientific and Danaher Corporation represent the integrated instrumentation archetype, bundling preparation systems with adjacent analytical platforms and global service infrastructure. Within the specialized microscopy tier, JEOL exemplifies the focused ion beam technology anchor, while Leica Microsystems occupies a position in cryo-ultramicrotomy specialization for neuroscience applications. These named entities illustrate how competitive positioning stratifies across automation intensity and thermal preparation modality rather than geographic coverage alone.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| JEOL |
| Leica Microsystems |
| Hitachi High-Technologies Corporation |
| Carl Zeiss |
| Gatan |
| Agilent Technologies |
| Merck KGaA |
| Danaher Corporation |
| Others |
Value Network & Pricing Analysis
Helium refining concentration in Qatar and Russia concentrates pricing power for focused ion beam consumables in the hands of a narrow supplier tier, pushing margin capture downstream toward service-integrated vendors who bundle preparation systems with captive gas supply contracts.
Pricing Analysis
Next-generation cryo-EM preparation platforms command premiums exceeding prior-generation ion milling systems by substantial multiples, while entry-level manual polishing stations face sustained price erosion from Asian manufacturing competition. Three-tier pricing structure across premium, standard, and economy levels separates fully automated pharmaceutical-grade systems from hybrid neuroscience configurations and basic academic units. Price differentiation centers on FDA 21 CFR Part 11 compliance certification and ISO 17025 validation documentation rather than raw hardware specifications. Academic institutions exhibit highest price sensitivity due to fixed capital budgets, whereas Swiss pharmaceutical central labs prioritize interoperability premiums over unit cost.
Supply Chain Analysis
Contract manufacturing for precision ion optics concentrates in Germany, Japan, and Switzerland, with JEOL and Carl Zeiss maintaining in-house fabrication for proprietary beam columns. Critical consumables draw from specialized chemical suppliers in Belgium and the United States for embedding resins, while conductive coatings hinge on precious metal supply chains anchored in South Africa and Russia. Single-source vulnerability for helium isotope enrichment creates exposure to export restriction shocks. Distribution runs through OEM-direct service organizations in regulated markets and regional distributors in emerging fabrication economies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cross-disciplinary technician scarcity constrains laboratory throughput expansion, with simultaneous competence in electron optics, materials science, and software scripting becoming the binding constraint on automated system deployment.
For Market Incumbents: Pre-empt service unbundling threats by capturing independent maintenance providers through certified partnership programs that preserve consumable recurring revenue. Lock in pharmaceutical central labs through multi-site service coverage guarantees spanning Swiss and Massachusetts headquarters clusters. Backward integration into helium recycling technology mitigates supply disruption exposure from Qatar and Russian source concentration. For New Entrants and Emerging Players: India's semiconductor fabrication push in Karnataka and Telangana states offers the most penetrable white-space for materials characterization infrastructure, where BIS standards lag creates temporary validation flexibility for imported equipment. Cryo-electron tomography clinical diagnostic applications represent adjacent expansion territory beyond research-confined structural biology. Go-to-market positioning through independent service provider channels bypasses entrenched OEM-direct relationships in mature markets. For Investors and Strategic Acquirers: Capital is best deployed toward cryo-ultramicrotomy specialists with established installed bases in European neuroscience institutes, where replacement cycles and consumable lock-in sustain predictable cash generation. Long-term viability rests on regulatory certification breadth across FDA, EPA, and EU MDR frameworks rather than hardware performance specifications alone. The signal to watch is India's PLI scheme disbursement velocity for domestic chip manufacturing, which will indicate materials characterization infrastructure procurement timing.| Strategic Initiative | Industry Significance |
|---|---|
| Helium Recycling Technology Investment | Mitigates supply chain exposure to Qatar and Russian export restrictions for focused ion beam operations. |
| Cryo-EM Clinical Diagnostic Pathway Development | Extends structural biology hardware into regulated diagnostic applications beyond research confines. |
| Multi-Site Service Coverage Expansion | Captures pharmaceutical central lab procurement decisions in Swiss and Massachusetts headquarters clusters. |
| Independent Service Provider Certification Program | Pre-empts unbundling threats by co-opting third-party maintenance channels into OEM-controlled ecosystems. |
| India Semiconductor Infrastructure Partnership | Positions preparation systems for PLI scheme-driven demand in Karnataka and Telangana fabrication investments. |
Research Methodology
A spread of perspectives from electron microscopy lab directors, pharmaceutical analytical infrastructure managers, regulatory affairs specialists at contract research organizations, and consumable chemistry procurement leads converged on the working assumptions shaping demand trajectories. Secondary validation drew from FDA 510(k) filings for automated preparation platforms, EPA SW-846 method documentation, ISO 17025 accreditation records, and import-export trade data for ion beam system classifications. Bottom-up sizing of installed base replacement cycles and top-down cross-check against pharmaceutical R&D capital expenditure disclosures ensured analytical robustness.
Demand-supply-balance framing anchored the forecast framework, with segmentation across automation intensity tiers, end-user procurement authority structures, application-specific regulatory compliance requirements, and thermal preparation modality distinctions modeled throughout the forecast period. CAGRs were derived from replacement cycle analysis, capacity expansion announcements, and regulatory mandate implementation timelines. Industry-specific inputs included helium spot price volatility indices and cryo-EM structural biology publication volume trends as leading indicators of academic infrastructure investment.
The forecast holds incumbent behavior within observed patterns; aggressive moves by diversified life science conglomerates into cryo-ultramicrotomy specialization or by Asian manufacturing entrants into automated platform assembly would shift outcomes substantially from modeled trajectories. Quarterly review of India's PLI scheme disbursement rates, helium futures contract pricing, and FDA warning letter issuance patterns for analytical equipment validation is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Instruments
Portable Infrared Digital Thermometer Market
Analytical Instruments
Potentiometric Titrators Market
Analytical Instruments
Infrared Thermometers Market
Analytical Instruments
Discrete Analyzers Market
Analytical Instruments
Microplate Instrumentation and Systems Market
Analytical Instruments
Global Mercury Analyzer Market
Analytical Instruments
Surface Plasmon Resonance Instrument Market
Analytical Instruments
Global Terahertz and Infrared Spectroscopy Market
Analytical Instruments
Global Laboratory Electronic Balance Market
Analytical Instruments
Next Generation Mass Spectrometer Market
Analytical Instruments
Mass Spectroscopy Market
Analytical Instruments
High-Sensitivity Luminometers Market
Analytical Instruments
Trace Oxygen Analyzer Market
Analytical Instruments
Surface Plasmon Resonance Market
Analytical Instruments
Spectroscopy Software Market
Analytical Instruments
Lab-On-A-Chip Device Market