
 Electron Probe Microanalyzers (EPMA) Market | 2026-2036
Electron Probe Microanalyzers (EPMA) Market Size, Share, and Industry Trends Forecast 2026-2036
Electron Probe Microanalyzers (EPMA) Market Foresight
ISO 17025 laboratory accreditation is collapsing vendor qualification timelines for EPMA procurement across materials science and semiconductor end users. JEOL Ltd. leverages its vertically integrated electron optics manufacturing to sustain pricing power in high-resolution imaging configurations. Bruker Corporation anchors its position through software-integrated spectroscopy platforms that merge wavelength dispersive detection with automated sample handling workflows. Thermo Fisher Scientific Inc. competes by extending its service infrastructure into emerging research clusters, reducing downtime penalties that dominate total cost-of-ownership calculations for institutional buyers.
An electron probe microanalyzer directs a focused electron beam onto a solid specimen to generate characteristic X-rays for quantitative elemental analysis, typically achieving spatial resolution below one micrometer and detection limits approaching 100 parts per million for most elements. The instrument serves primary industrial and commercial purposes in materials characterization, failure analysis, and quality verification where non-destructive chemical mapping at micro scales determines product conformance. Wavelength dispersive X-ray spectroscopy commands premium positioning due to superior energy resolution for light element quantification, while energy dispersive systems occupy broader installed bases where speed outweighs spectral separation demands. Automated sample handling represents the fastest-growing technology segment as laboratories face throughput pressures from high-volume semiconductor wafer inspection and geological survey programs.
FDA device regulations for analytical instruments used in pharmaceutical quality control, EPA methods specifying elemental analysis for environmental compliance, and ISO 17025 accreditation frameworks collectively shape product development roadmaps and market access conditions for EPMA manufacturers serving North American buyers. The EU AI Act and MDR traceability requirements are beginning to influence software analysis tool validation protocols, particularly for automated spectral interpretation features that reduce operator dependency. Stakeholders must monitor how evolving accreditation standards and export control classifications for electron beam technology reshape competitive boundaries between established Japanese vendors and specialized European spectroscopy firms.
Market Dynamics
ISO 17025 accreditation timelines are compressing vendor qualification windows, forcing EPMA manufacturers to pre-certify configurations and accelerate documentation workflows for materials science laboratories.
Growth Catalysts
- Semiconductor foundry expansion:Sub-micron chemical characterization protocols in East Asian manufacturing clusters are pulling wavelength dispersive systems into high-volume wafer inspection lines.
- REACH substance identification mandates:European materials laboratories face expanded elemental disclosure requirements for alloy composition verification in automotive supply chains.
- Automated sample handling integration:Robotics-enabled throughput gains are decomposing bottlenecks in geological survey programs and failure analysis pipelines.
Market Restraints
- Electron optics supply concentration:Precision electromagnetic lens manufacturing clusters in Japan create single-source vulnerability for wavelength dispersive instrument builders.
- Helium-3 detector scarcity:Energy dispersive system producers face input cost volatility from nuclear non-proliferation export controls on neutron detection materials.
- Light element quantification ceiling:Energy dispersive spectroscopy hits resolution limits below atomic number 11, locking wavelength systems into premium pricing tiers.
Strategic Opportunities
- India BIS laboratory accreditation:Domestic testing infrastructure expansion under the National Testing and Calibration Laboratory Recognition Scheme opens procurement channels for imported EPMA systems.
- AI-assisted spectral deconvolution:Machine learning convergence with wavelength dispersive detection is compressing operator training curves for non-specialist technicians.
- Battery materials characterization:Cathode and anode microstructure mapping for solid-state electrolyte development represents an emerging application vertical.
Industry Challenges
- Electron microscopist certification pipelines:University materials science programs are failing to produce sufficient operators qualified in quantitative X-ray microanalysis protocols.
- Legacy EDS-EPMA integration friction:Mixed-instrument laboratories face data format incompatibilities when merging energy dispersive archives with wavelength dispersive workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electron Probe Microanalyzers (EPMA) Market |
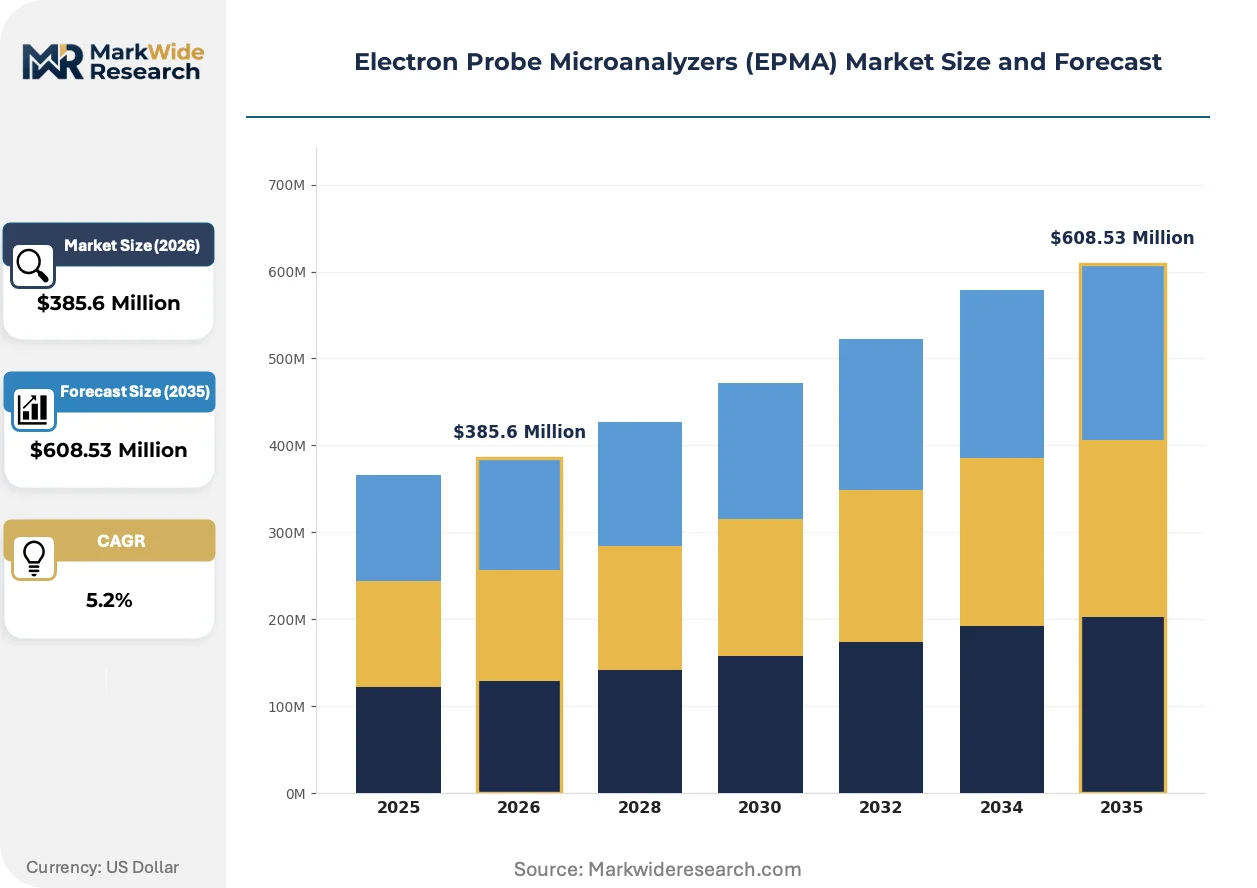
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $608.53 Million |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
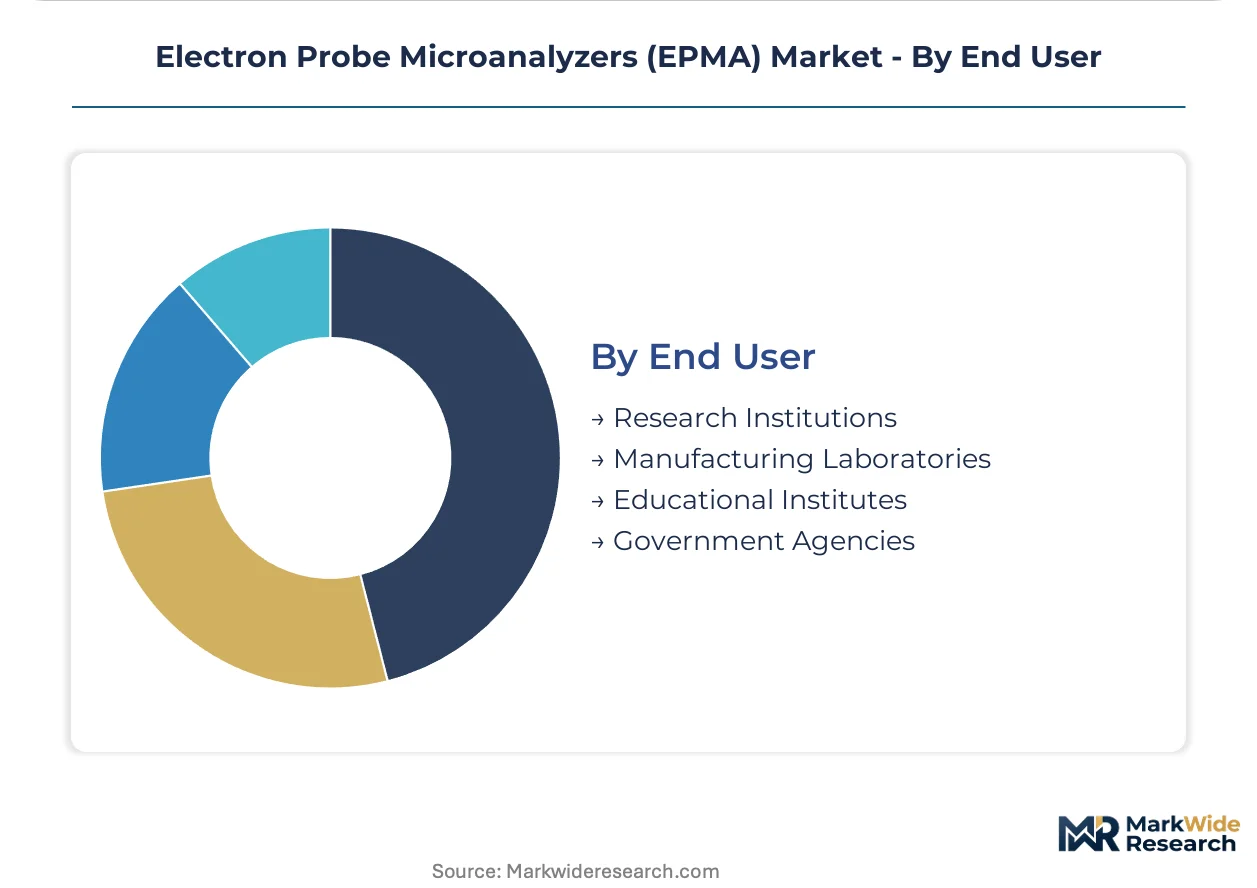
| Segmentation | Product Type: Scanning Electron Microscopes, Energy Dispersive X-ray Spectroscopy, Wavelength Dispersive X-ray Spectroscopy, Secondary Electron Imaging Technology: High-Resolution Imaging, Electron Beam Interaction, Automated Sample Handling, Software Analysis Tools Application: Materials Science, Semiconductor Analysis, Geological Research, Forensic Science End User: Research Institutions, Manufacturing Laboratories, Educational Institutes, Government Agencies |
| Companies Covered | Shimadzu Corporation, Bruker Corporation, JEOL Ltd., Horiba, Ltd., Oxford Instruments plc, Cameca SAS, Thermo Fisher Scientific Inc., Rigaku Corporation, Hitachi High-Technologies Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electron Probe Microanalyzers (EPMA) Market Shifts & Advancements
Electron probe microanalyzer architecture is fragmenting between speed-optimized configurations for production environments and resolution-maximized systems for research-grade elemental mapping.
Field-emission electron gun technology is decomposing the spatial resolution barrier that separated EPMA from scanning electron microscopy for nanoscale chemical analysis. Semiconductor failure analysis divisions in Taiwan and South Korea are adopting these configurations at accelerated replacement cycles. The technology is decomposing the traditional instrument category boundary, forcing vendors to reposition wavelength dispersive systems as complementary rather than competing modalities.
EU AI Act algorithmic transparency requirements are reshaping software validation protocols for automated spectral interpretation modules. EPMA manufacturers must now document decision pathways for machine learning-driven peak identification functions. Materials characterization laboratories in Germany and France are responding by demanding vendor-supplied conformity assessments before procurement approval.
Service contract unbundling is disrupting traditional bundled maintenance arrangements that dominated institutional procurement. Research universities in the United States are separating hardware warranty extensions from application support and operator training packages. This pattern is most visible in National Science Foundation-funded materials science facilities where grant compliance requires granular cost accounting for analytical instrument operations.
Electron Probe Microanalyzers (EPMA) Market Segmentation
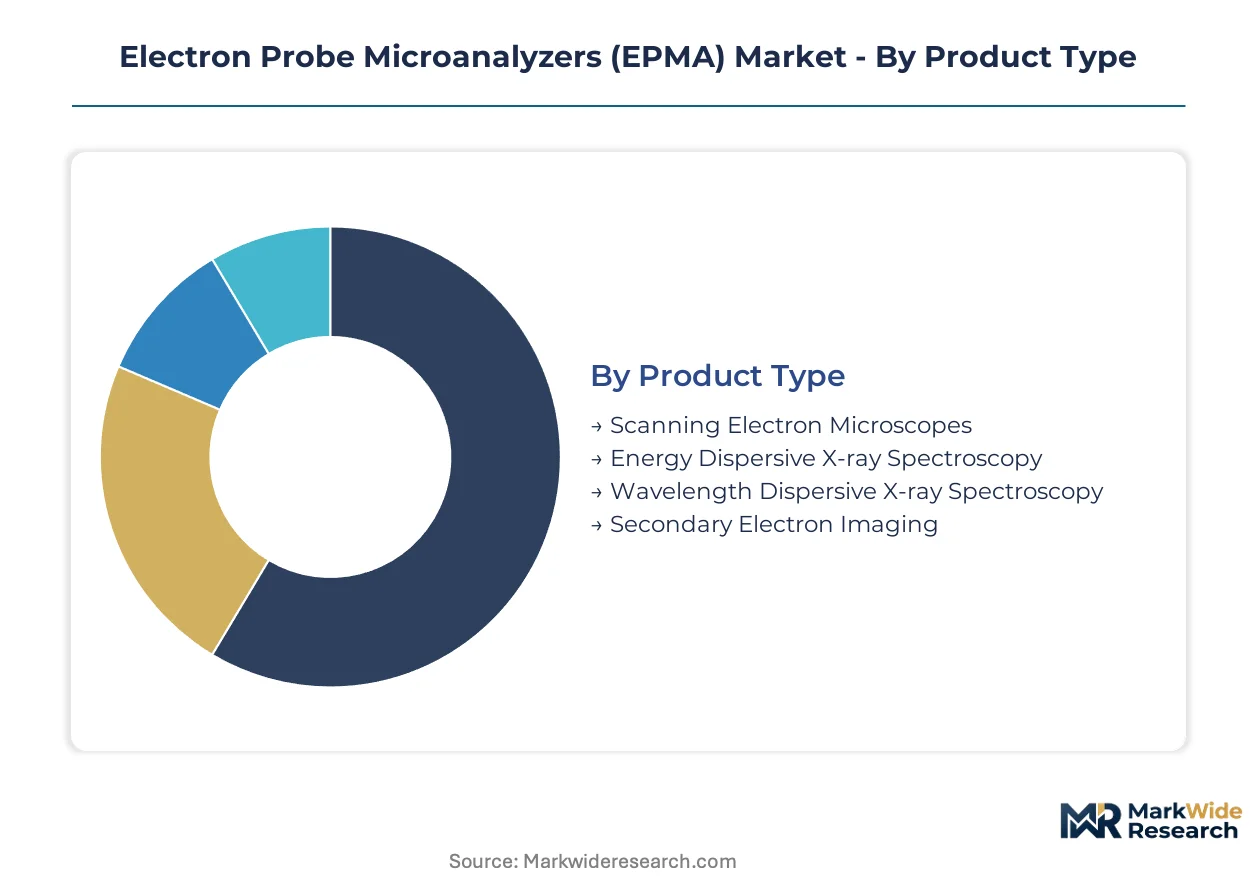
EPMA procurement patterns diverge sharply between research-grade installations requiring spectral precision and production-line deployments prioritizing throughput velocity. Segment boundaries are blurring as field-emission electron guns enable nanoscale resolution in semiconductor failure analysis, while automated handling systems penetrate geological survey programs previously served by manual workflows.
Product Type:
Domestic demand concentrates in wavelength dispersive configurations for materials science laboratories in Japan and Germany, while export markets pull energy dispersive systems into high-volume manufacturing clusters in Taiwan and South Korea.
- Wavelength Dispersive X-ray Spectroscopy:Superior energy resolution enables light element quantification below atomic number 11, critical for lithium battery cathode characterization and geological light-element mapping. Japanese materials science laboratories and German automotive materials divisions sustain premium procurement volumes despite extended qualification timelines under ISO 17025 frameworks.
- Energy Dispersive X-ray Spectroscopy:Speed-optimized detection dominates semiconductor wafer inspection lines where throughput outweighs spectral separation requirements. South Korean foundries and Taiwanese packaging houses deploy these systems at compressed replacement cycles driven by node shrink roadmaps.
- Scanning Electron Microscopes:Imaging-dominant configurations serve educational institutes and forensic laboratories where elemental mapping remains secondary to morphological documentation.
- Secondary Electron Imaging:Surface topology visualization supports failure analysis pipelines in aerospace materials divisions and archaeological conservation programs.
Wavelength dispersive systems command the established base in research-intensive installations. The steepest expansion runs through energy dispersive configurations pulled by semiconductor manufacturing scale.
Technology:
Cost tier stratification separates capital-intensive electron beam infrastructure from software-enabled capability extensions that reduce per-analysis labor overhead.
- Automated Sample Handling:Robotics integration decomposes throughput bottlenecks in high-volume geological survey programs and semiconductor wafer inspection lines. South Korean materials characterization facilities and US National Laboratory complexes are standardizing on unattended operation protocols that compress technician labor costs per sample.
- High-Resolution Imaging:Field-emission electron gun technology achieves sub-10 nanometer spatial resolution, displacing dedicated scanning electron microscopy for nanoscale chemical analysis in Taiwan semiconductor failure analysis divisions.
- Electron Beam Interaction:Precision electromagnetic lens configurations from Japanese optics manufacturers anchor instrument performance specifications.
- Software Analysis Tools:Machine learning-driven spectral deconvolution reduces operator training curves, though EU AI Act transparency requirements are reshaping validation protocols for German and French procurement approvals.
Electron beam hardware commands the established base. The steepest expansion runs through automated handling systems that compress labor intensity in production environments.
Application:
Customer maturity varies across verticals, with semiconductor analysis demanding continuous technology refresh while geological research maintains extended instrument lifecycles.
- Semiconductor Analysis:Sub-micron chemical characterization protocols at Taiwan foundries and South Korean memory manufacturers drive wavelength dispersive system adoption for dopant profiling and contamination detection. Node shrink roadmaps below 3nm are accelerating replacement cycles as spatial resolution requirements tighten.
- Materials Science:Alloy development programs at German automotive suppliers and Japanese steel producers sustain core demand for quantitative elemental mapping with trace-level sensitivity.
- Geological Research:Mineralogical survey programs in Australia and Canada deploy automated configurations for high-throughput core sample analysis.
- Forensic Science:Gunshot residue and trace evidence protocols in US federal laboratories and UK Home Office facilities require non-destructive microanalysis with chain-of-custody documentation.
Materials science commands the established base across institutional research infrastructure. The steepest expansion runs through semiconductor analysis pulled by East Asian manufacturing node transitions.
End User:
Procurement authority fragmentation separates grant-funded academic installations from capital-budget manufacturing laboratories with compressed approval cycles.
- Manufacturing Laboratories:Quality verification and failure analysis protocols at South Korean semiconductor foundries and German automotive materials divisions prioritize uptime guarantees and rapid vendor response. Service contract unbundling is disrupting traditional bundled maintenance arrangements as facilities demand granular cost accounting.
- Research Institutions:National science facilities in the United States and Max Planck Institutes in Germany sustain demand for resolution-maximized configurations, though electron microscopist certification pipelines are failing to produce sufficient qualified operators.
- Government Agencies:Environmental compliance laboratories under EPA methods and geological survey departments require standardized configurations with multi-site interoperability.
- Educational Institutes:University materials science programs in India and Southeast Asia represent emerging demand as BIS accreditation expands domestic testing infrastructure.
Research institutions command the established base in instrument-installed capacity. The steepest expansion runs through manufacturing laboratories scaling quality control automation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Materials science laboratories and semiconductor foundries concentrate procurement authority across four distinct national clusters. Each geography exhibits divergent qualification timelines, regulatory frameworks, and end-use intensity that reshape vendor access conditions.
Japan
Domestic demand for wavelength dispersive systems originates from steel producers and automotive materials divisions in the Chubu and Kansai industrial belts. METI standardization programs accelerate instrument certification for export-bound manufacturers. Tokyo and Osaka host the densest concentration of electron optics manufacturing, with JEOL Ltd. and Hitachi High-Technologies Corporation maintaining captive lens production facilities.
Germany
Automotive supply chains in Bavaria and Baden-Württemberg drive alloy verification protocols under REACH substance identification mandates. The KBA enforces traceability requirements that compress vendor documentation workflows for materials testing laboratories. Stuttgart and Munich manufacturing clusters sustain premium procurement volumes for high-resolution imaging configurations.
United States
EPA methods for environmental compliance and FDA device regulations shape analytical instrument validation for pharmaceutical quality control laboratories. National Science Foundation-funded facilities in California and Massachusetts are unbundling service contracts to satisfy grant compliance requirements. Silicon Valley semiconductor failure analysis divisions are accelerating replacement cycles for field-emission configurations.
South Korea
Memory manufacturers and foundries in the Seoul Capital Area and Busan-Ulsan corridor deploy energy dispersive systems at compressed replacement cycles driven by node shrink roadmaps below 3nm. MFDS pharmaceutical testing standards are expanding elemental analysis requirements for domestic drug production. Samsung and SK Hynix materials characterization facilities prioritize uptime guarantees in procurement specifications.
India
BIS laboratory accreditation under the National Testing and Calibration Laboratory Recognition Scheme is opening procurement channels for imported EPMA systems. Materials science programs at IIT Bombay and IISc Bangalore are failing to produce sufficient electron microscopists qualified in quantitative X-ray microanalysis. Maharashtra and Karnataka represent the emerging demand concentration as domestic testing infrastructure expands.
Electron Probe Microanalyzers (EPMA) Market Competitive Landscape
Player mix skews toward vertically integrated Japanese electron optics specialists and diversified analytical instrument conglomerates with spectroscopy software platforms. The structure concentrates around three strategic archetypes: precision electromagnetic lens fabricators, wavelength dispersive detection specialists, and service infrastructure extenders. Competitive moves center on backward integration into electron gun manufacturing and geographic expansion of application support networks to reduce downtime penalties.
Among Japanese electron optics fabricators, JEOL Ltd., Hitachi High-Technologies Corporation, and Shimadzu Corporation exemplify the vertically integrated archetype with captive lens production. Bruker Corporation and Thermo Fisher Scientific Inc. represent the diversified conglomerate model, anchoring positions through software-integrated platforms and extended service infrastructure respectively. Oxford Instruments plc and Cameca SAS occupy specialist positions in detection technology and high-resolution imaging configurations.
| Leading Market Players |
|---|
| Shimadzu Corporation |
| Bruker Corporation |
| JEOL Ltd. |
| Horiba, Ltd. |
| Oxford Instruments plc |
| Cameca SAS |
| Thermo Fisher Scientific Inc. |
| Rigaku Corporation |
| Hitachi High-Technologies Corporation |
| Others |
Supply & Pricing Matrix
ISO 17025 accreditation frameworks gate both vendor qualification timelines and price differentiation tiers for wavelength dispersive systems, compressing procurement windows while stratifying configurations by certification grade and spectral resolution capability.
Pricing Analysis
Cost-plus contracts with raw material indexation dominate procurement for precision electromagnetic lens assemblies from Japanese electron optics fabricators. Three-tier pricing structure across research-grade, production-line, and educational configurations separates wavelength dispersive systems with light-element quantification capability from energy dispersive alternatives. Cost compression in mid-tier energy dispersive segments is intensifying because semiconductor foundries in Taiwan and South Korea prioritize throughput velocity over spectral resolution. Manufacturing laboratories exhibit highest price sensitivity due to uptime penalty clauses, while research institutions absorb premium pricing for resolution-maximized field-emission configurations.
Supply Chain Analysis
Extended lead times for precision electromagnetic lens assemblies from Japanese manufacturers signal inventory tightness across the electron optics tier. Supply concentrates in Japan for electron gun and lens fabrication, in Germany for precision mechanical stages, and in the United States for detector electronics and software platforms. Raw material dependencies include high-purity copper for electromagnetic coils, specialized ceramics for electron beam chambers, and helium-3 for energy dispersive detector cooling systems. Single-source vulnerability in Japanese lens manufacturing creates supply chain risk from export control reclassifications. Distribution runs through direct vendor sales for research institutions and authorized distributors for manufacturing laboratories requiring localized service response.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electron probe microanalyzer adoption sits in early-cycle expansion as battery materials characterization protocols for solid-state electrolyte development create new application verticals beyond established semiconductor and geological survey demand.
For Market Incumbents: Consolidate captive electron optics manufacturing positions through backward integration into field-emission electron gun production, countering emerging spectroscopy specialists threatening premium wavelength dispersive margins. Deepen application support infrastructure in South Korean semiconductor clusters to reduce downtime penalties that dominate total cost-of-ownership calculations for Samsung and SK Hynix materials characterization facilities. For New Entrants and Emerging Players: Anchor in Indian educational institutes and domestic testing laboratories as BIS accreditation expands procurement channels under the National Testing and Calibration Laboratory Recognition Scheme, where electron microscopist certification gaps create demand for AI-assisted spectral interpretation modules. Target geological survey automation as the most penetrable white-space, offering robotics-integrated configurations that decompose throughput bottlenecks in Australian and Canadian core sample analysis programs. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified analytical instrument conglomerates seeking to divest non-core electron probe microanalyzer divisions amid portfolio rationalization pressures. Long-term viability hinges on software-integrated spectroscopy platforms that merge wavelength dispersive detection with machine learning-driven peak identification, with inflection signaled by EU AI Act conformity assessment completion rates among mid-tier European vendors.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Electron Gun Manufacturing | Captive field-emission source production secures resolution specifications for nanoscale semiconductor failure analysis. |
| AI-Assisted Spectral Deconvolution Development | Machine learning convergence compresses operator training curves for non-specialist technicians in high-throughput laboratories. |
| Service Contract Unbundling | Granular cost accounting satisfies National Science Foundation grant compliance for US research universities. |
| Geographic Expansion of Application Support Networks | Localized response capabilities reduce downtime penalties dominating procurement specifications at South Korean foundries. |
| Automated Sample Handling Integration | Robotics-enabled throughput gains address bottlenecks in geological survey programs and semiconductor wafer inspection lines. |
Research Methodology
A standing panel of electron microscopists, materials science laboratory directors, semiconductor failure analysis engineers, and analytical instrument procurement officers provided ongoing calibration across primary interview cycles. Bottom-up demand estimates from wavelength dispersive and energy dispersive system deployments were cross-referenced with top-down vendor shipment data from SEC filings, Japanese electron optics trade association reports, and National Science Foundation equipment expenditure disclosures. Secondary validation drew from ISO 17025 accreditation body records, EPA analytical method specifications, and EU MDR traceability requirement documentation.
Consistency checks against external benchmarks confirmed analytical framework integrity across the projection horizon. Segmentation dimensions modeled include product type, technology tier, application vertical, and end-user category with geographic production cluster overlay. CAGRs were derived from instrument replacement cycle analysis and node shrink roadmap acceleration in East Asian semiconductor manufacturing. Forecast inputs incorporated helium-3 detector supply constraints from nuclear non-proliferation export controls and electron microscopist certification pipeline shortfalls in university materials science programs.
Decision-makers should treat outputs as directional under assumptions of sustained semiconductor foundry expansion and stable ISO 17025 accreditation timelines; material deviation in electron optics supply concentration or regulatory export control reclassification would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Instruments
Gas Chromatography Systems Market
Analytical Instruments
Global Electron Microscopes Market
Analytical Instruments
North America Liquid Chromatography Devices Market
Analytical Instruments
XRF Analyzer Market
Analytical Instruments
Global Electron Microscopy and Sample Preparation Market
Analytical Instruments
Battery Testers and Analyzers Market
Analytical Instruments
Visualization Instruments for MIS Market
Analytical Instruments
Complexion Analysis System Market
Analytical Instruments
Dissolved Gas Analyzer Market
Analytical Instruments
Flame Spectrometers Market
Analytical Instruments
Asia-Pacific Handheld Spectrum Analyzer Market
Analytical Instruments
Melt Flow Meter Market
Analytical Instruments
Laser Scanning Microscopes Market
Analytical Instruments
Microfluidic Devices Market
Analytical Instruments
Surface Plasmon Resonance Instrument Market
Analytical Instruments
Spatial Mass Spectrometry Market