
 Scientific Instruments Market | 2026-2036
Scientific Instruments Market Size, Share, and Industry Trends Forecast 2026-2036
Scientific Instruments Market Intelligence
Aftermarket service revenue is narrowing as original equipment manufacturers consolidate calibration contracts and remote diagnostics under captive service arms. Thermo Fisher Scientific leverages its installed base across mass spectrometry platforms to lock in multi-year service agreements. Danaher Corporation sustains margin density through consumables tied to its liquid chromatography systems. Agilent Technologies anchors regional competitiveness with localized refurbishment centers in Asia-Pacific markets.
Scientific instruments encompass precision-engineered devices designed to measure, analyze, or manipulate physical, chemical, or biological properties with detection thresholds often reaching parts-per-billion sensitivity. These systems integrate optical gratings, ion sources, piezoelectric transducers, and vacuum chambers to serve pharmaceutical quality control, materials characterization, and environmental compliance testing. Spectrometers command substantial margin pools due to recurring consumables and software licensing attach rates. Chromatography systems occupy the fastest-expanding application layer as biopharma process analytical technology mandates intensify. Microscopes retain mature demand profiles in academic settings while industrial inspection applications drive incremental upgrade cycles.
EPA methods and FDA 21 CFR Part 11 electronic records requirements shape validation protocols for instruments deployed in regulated laboratories. ISO 17025 accreditation standards and EU REACH substance detection mandates compel manufacturers to enhance traceability and lower detection limits in new platform releases. Stakeholders must weigh captive service buildout against third-party channel partnerships as procurement committees tighten total-cost-of-ownership criteria.
Market Dynamics
Biopharma process analytical technology mandates are compressing instrument replacement cycles while tightening performance verification requirements across regulated laboratories.
Growth Catalysts
- EPA Method 525.3 compliance:Drinking water testing laboratories in the United States must upgrade mass spectrometry detection thresholds, forcing hardware refresh cycles.
- China biopharma R&D acceleration:Domestic contract research organizations are expanding chromatography procurement for monoclonal antibody process development.
- ISO 17025 accreditation expansion:Third-party testing laboratories across Germany, France, and Switzerland require traceable calibration protocols, sustaining service contract attach rates.
Market Restraints
- Helium supply concentration:Mass spectrometry and nuclear magnetic resonance systems depend on helium sourced primarily from Qatar and the United States, creating input cost volatility.
- EU REACH substance detection mandates:Per- and polyfluoroalkyl substance testing requirements impose capital-intensive detection limit upgrades without proportional revenue expansion.
- Academic budget stagnation:Public university procurement committees in Japan and South Korea extend microscope replacement timelines beyond ten years.
Strategic Opportunities
- India pharmaceutical quality control:CDSCO Schedule M compliance deadlines drive demand for high-performance liquid chromatography in generic drug manufacturing clusters around Hyderabad and Ahmedabad.
- AI-integrated spectral analysis:Machine learning algorithms trained on Raman spectroscopy datasets are enabling real-time contaminant identification in food safety applications.
- Refurbishment channel development:Certified pre-owned instrument programs address price sensitivity among mid-tier contract manufacturing organizations in Brazil and Mexico.
Industry Challenges
- Metrology technician scarcity:Vacuum system maintenance and ion source optimization require specialized training programs that outpace university output in the United States and Germany.
- Legacy data migration:FDA 21 CFR Part 11 compliance for electronic records necessitates costly software revalidation when upgrading from retired chromatography data systems.
- Multi-vendor integration complexity:Laboratories combining mass spectrometry platforms from different suppliers face interoperability gaps in data format standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Scientific Instruments Market |
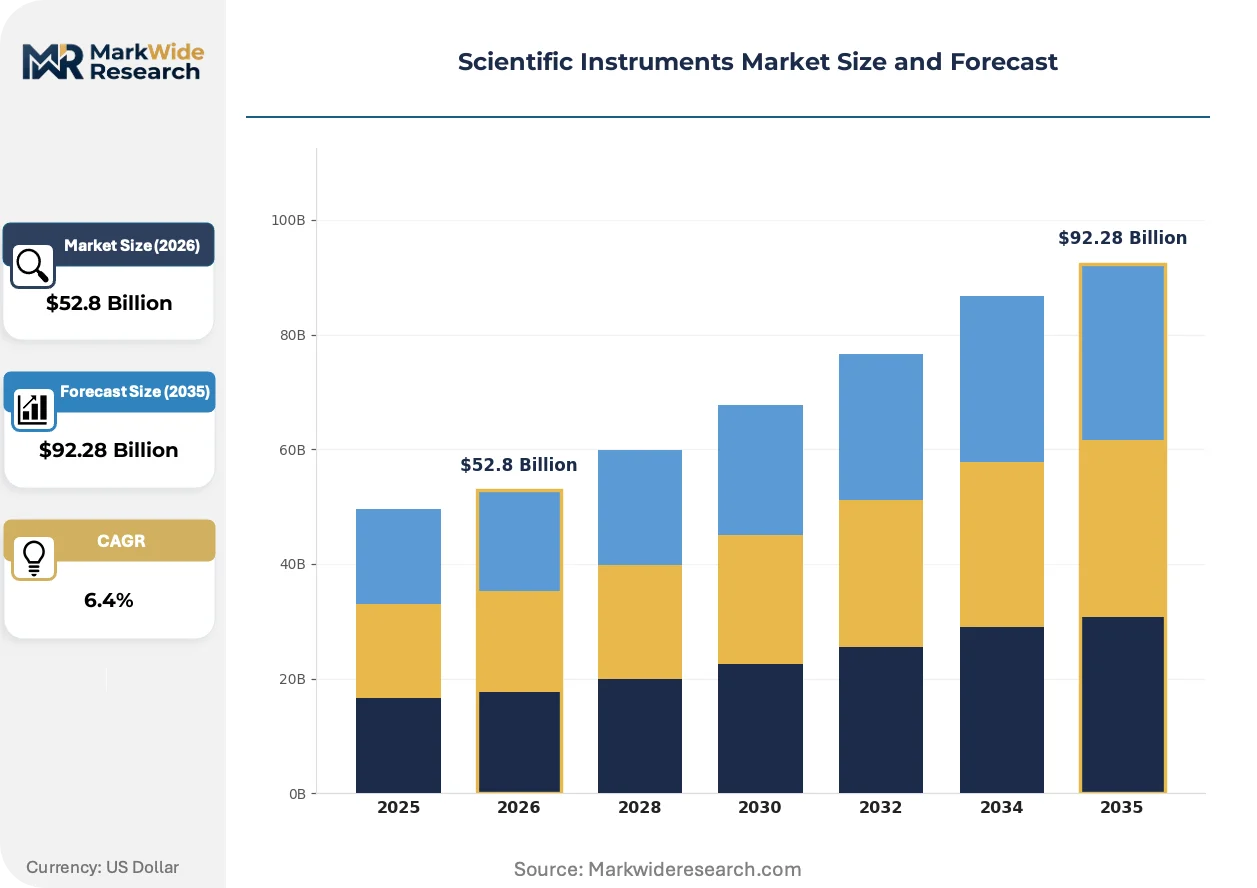
| Market Size in 2026 | $52.8 Billion |
| Market Size in 2035 | $92.28 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spectrometers, Microscopes, Chromatography Systems, Analyzers Application: Healthcare, Environmental Monitoring, Education, Research Institutions Technology: Optical, Electronic, Mechanical, Acoustic End User: Laboratories, Pharmaceutical Companies, Academic Institutions, Industrial Research |
| Companies Covered | Thermo Fisher Scientific Inc., Agilent Technologies Inc., Danaher Corporation, Shimadzu Corporation, Bruker Corporation, PerkinElmer Inc., Waters Corporation, Mettler Toledo International Inc., ZEISS Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Scientific Instruments Market Strategic Shifts & Innovations
Portable and miniaturized detection systems are penetrating field applications previously served by central laboratory infrastructure, while software-defined instrument architectures enable remote diagnostics and predictive maintenance protocols.
Quadrupole time-of-flight mass spectrometry is migrating from research-grade proteomics laboratories into routine biopharma quality control workflows. Contract manufacturing organizations in Ireland and Singapore are adopting these platforms for intact mass analysis of antibody-drug conjugates. The technology is migrating from high-resolution research applications toward standardized release testing, compressing the traditional separation between discovery and manufacturing instrumentation tiers.
EU F-Gas Regulation phase-down schedules are restricting hydrofluorocarbon refrigerants in thermal analysis equipment. Differential scanning calorimetry and thermogravimetric analyzer manufacturers must redesign cooling systems using natural refrigerants or alternative thermal management approaches. German and French laboratory equipment suppliers are accelerating hydrocarbon-based cooling platform releases ahead of 2027 quota reductions.
Consolidated procurement committees at multinational pharmaceutical headquarters are unbundling instrument purchases from service agreements. Site-level laboratory managers in China and India now negotiate hardware and maintenance contracts separately, comparing third-party calibration providers against manufacturer service arms. This behavior is most visible among generic drug manufacturers seeking to reduce total cost of ownership across multi-site quality control networks.
Scientific Instruments Market Segmentation
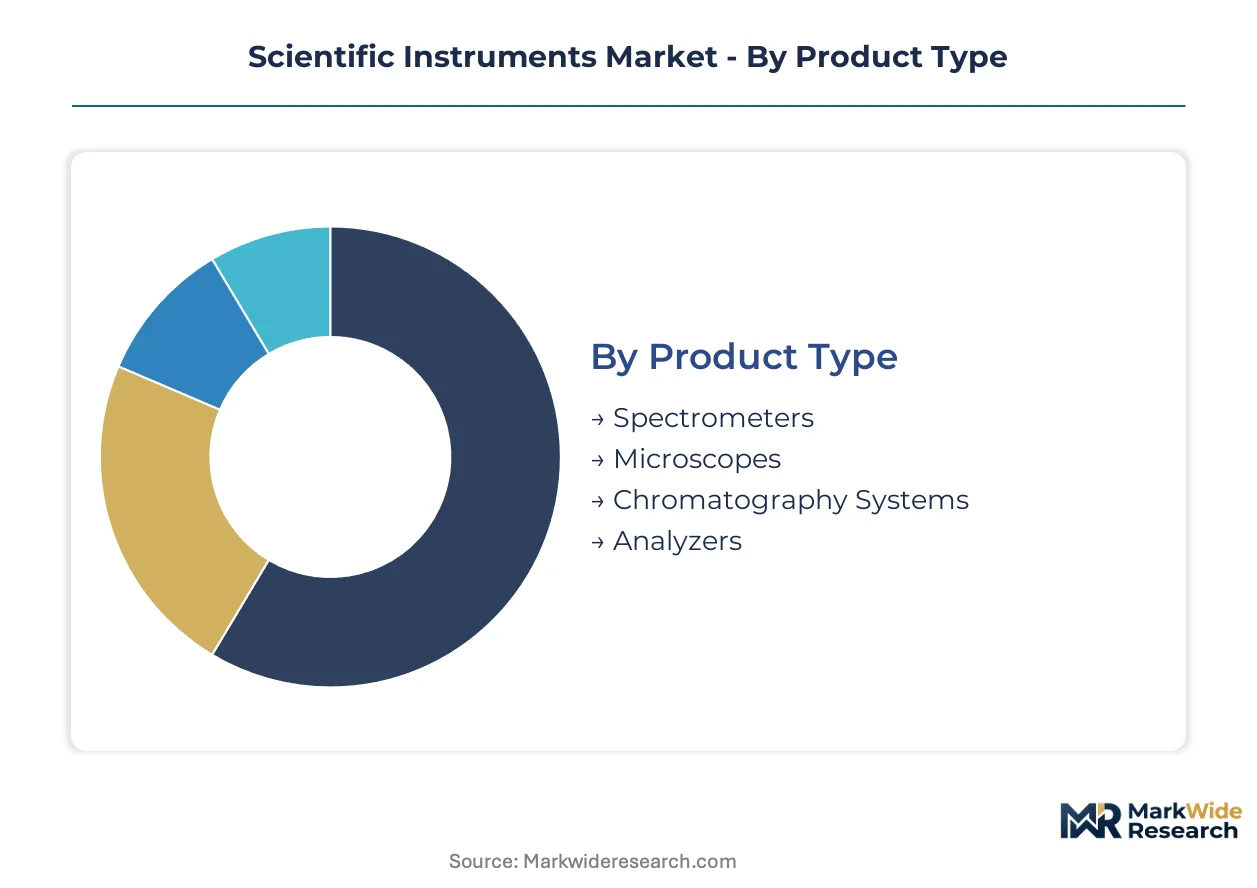
Segmentation reveals how procurement priorities diverge across regulated laboratories, academic settings, and industrial research facilities. Technical specifications, compliance requirements, and total-cost-of-ownership calculations reshape demand patterns within each slice of the market.
Product Type:
The use-case spectrum spans from routine quality control workflows requiring robust uptime to frontier research demanding parts-per-billion detection thresholds.
- Spectrometers:These systems integrate optical gratings, ion sources, and vacuum chambers to quantify molecular composition with exceptional sensitivity. Pharmaceutical quality control laboratories in Germany and Switzerland are expanding procurement of mass spectrometry platforms for impurity profiling, driven by EMA guidance on elemental impurity detection limits. The dominant share belongs to spectrometers, while chromatography systems are closing the gap fastest.
- Chromatography Systems:Liquid and gas chromatography platforms separate complex mixtures for quantitative analysis. Contract research organizations in China are accelerating HPLC procurement for monoclonal antibody process development, responding to domestic biopharma R&D investment expansion.
- Microscopes:Optical and electron microscopy systems enable materials characterization and biological imaging. Academic institutions in Japan extend replacement cycles beyond ten years amid public university budget constraints.
- Analyzers:Thermal, elemental, and particle analysis instruments support materials science and environmental compliance testing. EPA Method 525.3 compliance mandates in the United States are forcing hardware refreshes in drinking water laboratories.
Margin pools concentrate in platforms with recurring consumables and software licensing attach rates.
Application:
Cost tier differentiation separates premium regulated-laboratory deployments from price-sensitive educational procurement.
- Healthcare:Clinical diagnostics and pharmaceutical quality control demand validated systems with traceable calibration protocols. FDA 21 CFR Part 11 electronic records requirements shape instrument selection in United States hospital laboratories.
- Environmental Monitoring:EPA drinking water testing mandates and EU REACH substance detection requirements drive detection limit upgrades. Laboratories in France and Switzerland require ISO 17025 accreditation for third-party testing contracts.
- Education:Undergraduate teaching laboratories prioritize durability and simplified operation over cutting-edge specifications. Public university procurement committees in South Korea compress capital equipment budgets.
- Research Institutions:National laboratories and dedicated research centers pursue frontier detection capabilities. Helium supply concentration from Qatar and the United States creates input cost volatility for nuclear magnetic resonance installations.
Healthcare commands the largest revenue pool, though environmental monitoring is gaining share fastest on regulatory tightening.
Technology:
Volume concentration favors mature optical and electronic architectures over specialized acoustic implementations.
- Optical:Spectroscopic and imaging systems leveraging diffraction gratings, lasers, and photodetector arrays. Raman spectroscopy platforms are integrating machine learning algorithms for real-time contaminant identification in food safety applications.
- Electronic:Signal processing and sensor technologies enabling automated data acquisition. Software-defined instrument architectures are enabling remote diagnostics and predictive maintenance protocols across installed bases.
- Mechanical:Precision positioning systems and vacuum chamber technologies. Metrology technician scarcity in the United States and Germany constrains maintenance capacity for ion source optimization.
- Acoustic:Ultrasonic and acoustic emission systems for materials characterization. Industrial inspection applications in Brazil and Mexico drive incremental upgrade cycles for non-destructive testing equipment.
Optical technology retains the broadest installed base, while electronic integration is climbing the fastest on connectivity demands.
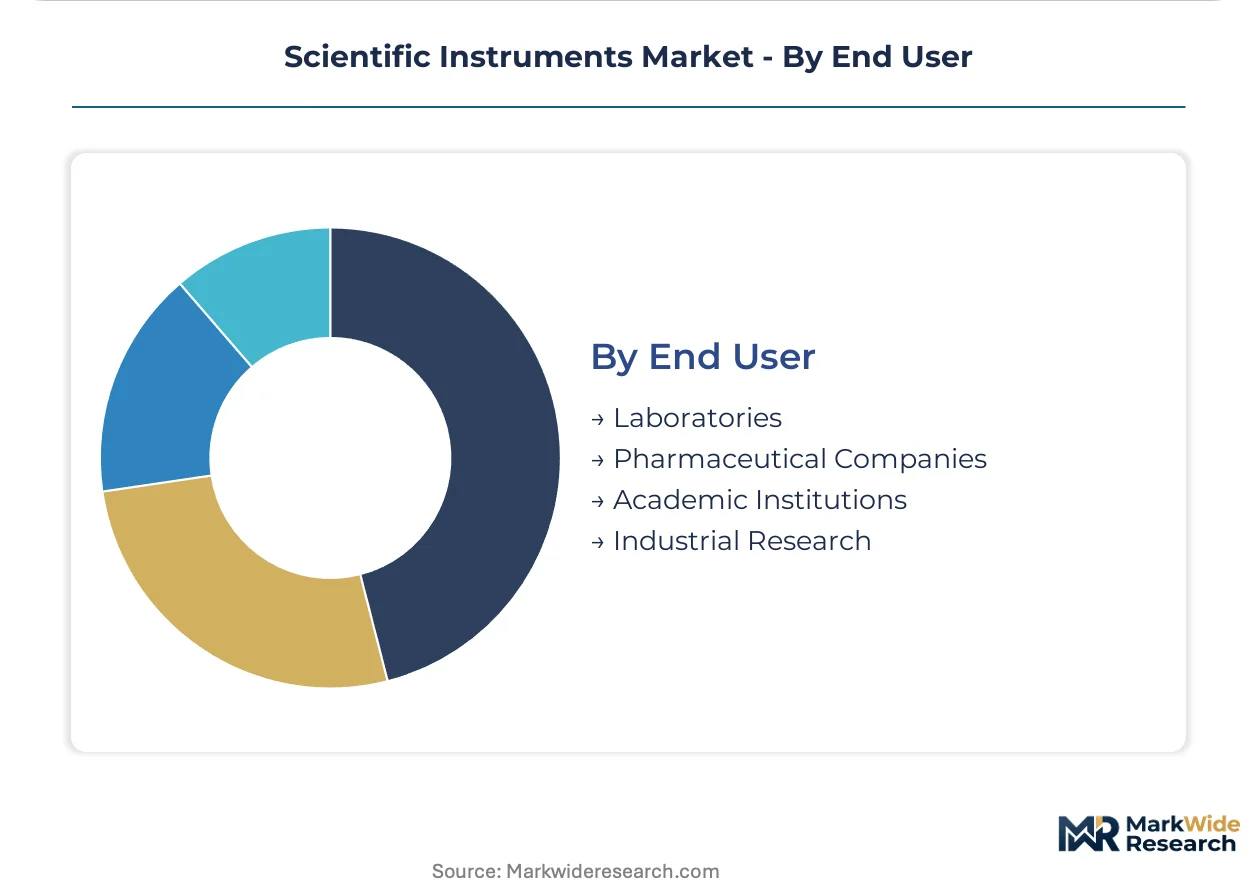
End User:
Customer type determines procurement committee structure and service contract negotiation leverage.
- Laboratories:Independent testing facilities and centralized hospital laboratories require ISO 17025 traceability. CDSCO Schedule M compliance deadlines in India are driving HPLC procurement for generic drug manufacturing clusters around Hyderabad and Ahmedabad.
- Pharmaceutical Companies:Multinational headquarters consolidate procurement while site-level managers negotiate separately. Consolidated committees in Ireland and Singapore are adopting quadrupole time-of-flight mass spectrometry for antibody-drug conjugate analysis.
- Academic Institutions:University research departments balance grant-funded frontier equipment against teaching laboratory durability. Budget stagnation in Japanese public universities extends microscope replacement timelines.
- Industrial Research:Corporate R&D centers and contract manufacturing organizations seek certified pre-owned instruments. Refurbishment programs address price sensitivity among mid-tier CMOs in Brazil and Mexico.
Laboratories represent the largest addressable base, though pharmaceutical companies are expanding procurement fastest on biopharma process analytical technology mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement elasticity varies sharply across geographies. Pharmaceutical quality control laboratories in Switzerland and Germany absorb premium pricing for validated systems, while academic institutions in Japan and South Korea compress replacement cycles to decade-plus intervals.
United States
Drinking water testing laboratories drive hardware refresh demand under EPA Method 525.3 compliance mandates. FDA 21 CFR Part 11 electronic records requirements shape validation protocols for regulated hospital laboratories. Boston-Cambridge biopharma clusters anchor mass spectrometry procurement for monoclonal antibody process development.
Germany
Third-party testing laboratories sustain service contract attach rates through ISO 17025 accreditation expansion. EU F-Gas Regulation phase-down schedules force thermal analyzer manufacturers toward hydrocarbon-based cooling redesigns. Stuttgart and Karlsruhe industrial zones concentrate differential scanning calorimetry demand from materials science R&D centers.
China
Domestic contract research organizations accelerate chromatography procurement for biopharma process analytical technology. NMPA regulatory tightening on generic drug quality standards elevates detection limit requirements. Shanghai and Suzhou biotech parks anchor monoclonal antibody development instrumentation clusters.
India
CDSCO Schedule M compliance deadlines compress HPLC procurement timelines for generic drug manufacturers. Price sensitivity among mid-tier contract manufacturing organizations sustains certified pre-owned instrument channel development. Hyderabad and Ahmedabad pharmaceutical manufacturing clusters drive quality control instrumentation demand.
Switzerland
EMA guidance on elemental impurity detection limits expands mass spectrometry procurement for pharmaceutical impurity profiling. Swissmedic regulatory standards enforce traceable calibration protocols across commercial testing laboratories. Basel pharmaceutical headquarters consolidate multi-site procurement committees while negotiating service agreements separately.
Scientific Instruments Market Key Industry Players
Capability concentration sits with diversified technology conglomerates; scale advantage sits with specialized analytical platform developers. The vendor base stratifies across three tiers: integrated life sciences conglomerates with captive consumables revenue, precision instrument specialists with regional service density, and emerging players attacking price-sensitive refurbishment channels. Dominant competitive moves include backward integration into consumables manufacturing and geographic expansion through localized refurbishment centers.
Among diversified life sciences conglomerates, Thermo Fisher Scientific Inc. and Danaher Corporation exemplify the integrated-platform archetype with recurring revenue streams from consumables and service agreements. Agilent Technologies Inc. occupies a position within the precision instrument specialist tier, anchoring regional competitiveness through Asia-Pacific service infrastructure. These three entities collectively represent the capability-scale spectrum defining competitive positioning.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Agilent Technologies Inc. |
| Danaher Corporation |
| Shimadzu Corporation |
| Bruker Corporation |
| PerkinElmer Inc. |
| Waters Corporation |
| Mettler Toledo International Inc. |
| ZEISS Group |
| Others |
Cost & Logistics Intelligence
Undercapacity in helium refining capacity across Qatar and the United States is compressing margins for mass spectrometry and nuclear magnetic resonance manufacturers while elevating input cost volatility that reshapes both supplier contracting behavior and end-user pricing posture across regulated laboratory segments.
Pricing Analysis
Long-term service contracts dominate commercial relationships, with multi-year calibration and remote diagnostics agreements locking in recurring revenue streams alongside hardware placements. Pricing stratifies across premium validated systems for FDA-regulated pharmaceutical laboratories, standard configurations for ISO 17025-accredited third-party testing facilities, and economy tiers serving price-sensitive academic institutions in Japan and South Korea. Cost compression in the economy tier is intensifying as generic drug manufacturers in India and Brazil unbundle hardware purchases from service agreements to reduce total cost of ownership across multi-site networks.
Supply Chain Analysis
Extended payment terms from original equipment manufacturers to specialized component suppliers are stabilizing working capital across the production network concentrated in Germany, the United States, and Japan. Vacuum chamber fabrication draws from precision machining clusters in Stuttgart and Boston-Cambridge, while optical grating production rests on photonics manufacturing capabilities in Jena and Rochester. Single-source vulnerability in helium supply from Qatar creates input cost volatility that distribution runs through authorized dealer networks and direct sales forces serving pharmaceutical headquarters procurement committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue from calibration contracts, consumables, and software licensing is expanding faster than hardware sales as procurement committees prioritize total-cost-of-ownership metrics over upfront capital expenditure, creating durable margin pools for vendors with installed base density.
For Market Incumbents: Entrench multi-year service agreements across mass spectrometry and chromatography installed bases before third-party calibration providers capture unbundled procurement opportunities in China and India. Deepen backward integration into consumables manufacturing to sustain margin density against emerging refurbishment channel competitors in Brazil and Mexico. For New Entrants and Emerging Players: India's CDSCO Schedule M compliance deadlines present the most penetrable geographic window for high-performance liquid chromatography systems serving generic drug manufacturing clusters around Hyderabad and Ahmedabad. Target certified pre-owned instrument programs for mid-tier contract manufacturing organizations, leveraging AI-integrated spectral analysis capabilities as a differentiated go-to-market angle for food safety applications. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across quadrupole time-of-flight mass spectrometry platforms as biopharma process analytical technology mandates compress replacement cycles. Acquisition targets should display captive consumables revenue streams and regional service density in Asia-Pacific markets; monitor helium supply contract renegotiation patterns as an inflection indicator for input cost pressure across the installed base.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Consumables | Captures recurring revenue streams from chromatography columns and ion source components tied to installed base. |
| Localized Refurbishment Center Expansion | Addresses price sensitivity among mid-tier CMOs in Brazil and Mexico through certified pre-owned programs. |
| AI-Integrated Spectral Analysis Platform Launch | Enables real-time contaminant identification for food safety laboratories adopting machine learning algorithms. |
| Multi-Year Service Agreement Lock-In | Secures calibration and remote diagnostics revenue as procurement committees unbundle hardware from maintenance contracts. |
| Hydrocarbon-Based Cooling System Redesign | Anticipates EU F-Gas Regulation quota reductions ahead of 2027 deadlines for thermal analysis equipment. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with laboratory directors, pharmaceutical quality control managers, biomedical equipment procurement officers, and aftermarket service heads across regulated testing facilities and academic institutions. Secondary validation drew from FDA 21 CFR Part 11 guidance documents, EPA Method compliance protocols, ISO 17025 accreditation databases, and SEC filings from diversified life sciences conglomerates. Bottom-up instrument shipment data triangulated against top-down pharmaceutical R&D expenditure patterns to establish market sizing across the analysis window.
Calibration against historical replacement cycle patterns and regulatory compliance deadline schedules shaped the analytical framework. Segmentation dimensions modeled include product type, application, technology, and end user, with additional granularity across biopharma process analytical technology adoption stages and environmental monitoring regulatory clusters. CAGRs were derived from elasticity-adjusted demand projections incorporating helium supply concentration effects and ISO accreditation expansion trajectories.
The forecast holds incumbent behavior within observed patterns; aggressive moves by emerging refurbishment channel competitors or accelerated AI platform development by specialized entrants would shift outcomes. Macroeconomic deviation in academic funding, regulatory acceleration in REACH substance detection mandates, or breakthrough displacement in optical detection technologies would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Instruments
Headspace Gas Analyzers Market
Analytical Instruments
Microfluidic Modulation Spectroscopy Market
Analytical Instruments
Next Generation Mass Spectrometer Market
Analytical Instruments
3D Touch Probe Market
Analytical Instruments
Digital Multichannel Analyzer Market
Analytical Instruments
Asia-Pacific Handheld Spectrum Analyzer Market
Analytical Instruments
Global Ultrapycnometer Market
Analytical Instruments
Simultaneous-Functionality Analyzers Market
Analytical Instruments
Signaling Analyzer Market
Analytical Instruments
Lab-On-A-Chip Device Market
Analytical Instruments
Trace Chemical Detector Market
Analytical Instruments
Contact Angle Measuring Instrument Market
Analytical Instruments
Atomic Force Microscopes (AFM) Market
Analytical Instruments
Kinetic Chromogenic Spectrophotometer Market
Analytical Instruments
Disintegration Analyzer Market
Analytical Instruments
Handheld Laser Measuring Instrument Market