
 Microbial Therapeutic Products Market | 2026-2036
Microbial Therapeutic Products Market Size, Share, and Industry Trends Forecast 2026-2036
Microbial Therapeutic Products Market Outlook
Contract fermentation capacity in South Korea and Denmark is decoupling from traditional small-molecule pharmaceutical infrastructure. Pfizer Inc. leverages its biologics manufacturing network to anchor live biotherapeutic production at scale. Novartis AG sustains R&D intensity through dedicated microbiome research divisions in Switzerland and the United States. Amgen Inc. competes on recombinant microbial strain engineering, differentiating its pipeline through proprietary expression platforms.
Microbial therapeutic products comprise live, attenuated, or extracted microorganisms formulated for disease prevention, treatment, or modulation of host physiological processes, typically manufactured via controlled anaerobic fermentation with defined purity thresholds exceeding 99.5% viable cell counts. These products function primarily as targeted interventions for dysbiosis-related pathologies, immune modulation, and metabolic correction in clinical and prophylactic settings. Live Biotherapeutics dominates current pipeline value, reflecting pharmaceutical-grade manufacturing requirements and orphan-drug pricing potential. Oral delivery commands the largest volume share, though intravenous formulations capture disproportionate margin pools due to hospital administration protocols and reimbursement premiums. Gastrointestinal Disorders anchors near-term demand, while Mental Health applications represent the fastest-emerging segment as gut-brain axis validation accelerates.
FDA's Center for Biologics Evaluation and Research and EMA's Committee for Medicinal Products for Human Use jointly shape market access through divergent live biotherapeutic classification pathways, with FDA emphasizing Investigational New Drug protocols and EMA prioritizing quality-by-design manufacturing standards. The EU AI Act and GDPR impose additional constraints on patient microbiome data utilization in predictive therapeutic development. Stakeholders must monitor evolving divergence between FDA and EMA evidentiary standards for live microbial products, as harmonization failure would fragment clinical trial strategies and duplicate regulatory investment burdens.
Market Dynamics
FDA and EMA regulatory convergence pressures are compressing clinical trial timelines for live biotherapeutics while manufacturing bottlenecks in anaerobic fermentation constrain supply elasticity. Hospital formulary committees now demand real-world evidence packages alongside traditional efficacy data.
Growth Catalysts
- Medicare Reimbursement Pathways:United States federal coverage decisions for gastrointestinal biotherapeutics unlock hospital procurement budgets and accelerate physician adoption curves.
- EU Green Deal Manufacturing Incentives:Cell-culture capacity investments in Germany and France receive direct public co-financing, reducing capital barriers for anaerobic fermentation scale-up.
- Gut-Brain Axis Validation:Neuroscience research programs at academic medical centers generate mechanistic evidence that expands addressable indications beyond gastrointestinal disorders.
Market Restraints
- Defined Purity Thresholds:FDA and EMA requirements exceeding 99.5% viable cell counts demand specialized quality-control infrastructure unavailable in traditional pharmaceutical contract manufacturing.
- Single-Source Fermentation Inputs:South Korean and Danish contract capacity concentration creates geographic supply vulnerability for sponsors lacking captive manufacturing.
- Live Product Stability Limits:Cold-chain requirements and short shelf lives restrict distribution radius and inflate logistics costs versus small-molecule alternatives.
Strategic Opportunities
- Mental Health Applications:Psychiatric indications represent underpenetrated therapeutic territory as mechanistic validation for microbiome-psychiatry interventions accumulates.
- Intravenous Formulation Expansion:Hospital administration protocols for IV delivery capture reimbursement premiums and differentiate margin pools from oral commoditization.
- GDPR-Compliant Data Architectures:EU AI Act constraints on patient microbiome data utilization favor early movers with privacy-preserving predictive therapeutic development platforms.
Industry Challenges
- Anaerobic Fermentation Expertise Scarcity:Industrial microbiology programs produce insufficient talent pipelines for pharmaceutical-grade live biotherapeutic manufacturing.
- Cross-Border Trial Harmonization:Divergent FDA Investigational New Drug and EMA quality-by-design evidentiary standards force duplicate regulatory investment burdens.
- Legacy Small-Molecule Facility Retrofit Costs:Traditional pharmaceutical infrastructure requires capital-intensive reconfiguration for oxygen-free production environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Microbial Therapeutic Products Market |
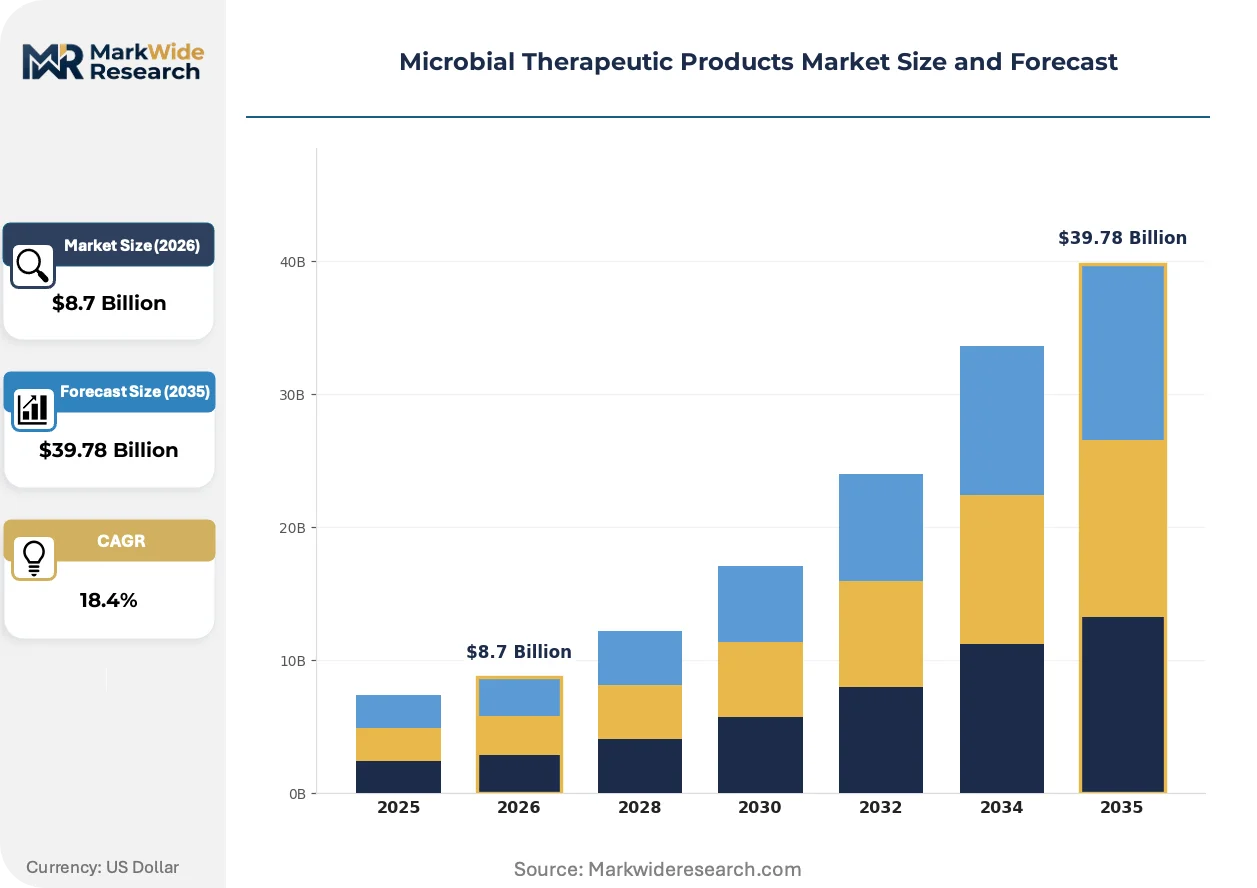
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $39.78 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Probiotics, Prebiotics, Live Biotherapeutics, Microbial Extracts Application: Gastrointestinal Disorders, Immune Support, Metabolic Conditions, Mental Health Delivery Mode: Oral, Topical, Intravenous, Inhalation End User: Hospital, Pharmacy, Research Institute, Homecare |
| Companies Covered | Mylan N.V., F. Hoffmann-La Roche Ltd., Novartis AG, Amgen Inc., Merck & Co. Inc., Pfizer Inc., Biocon, Dr. Reddy's Laboratories Ltd., Eli Lilly and Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Microbial Therapeutic Products Market Strategic Shifts
Live biotherapeutic manufacturing is bifurcating between centralized pharmaceutical-grade facilities and distributed precision-fermentation networks. This structural shift reconfigures competitive moats around quality certification rather than scale alone.
Precision-fermentation platforms using proprietary recombinant microbial strain engineering are expanding into orphan-disease therapeutic categories previously dominated by mammalian cell culture. Academic spinouts and mid-cap specialists deploy these systems for rapid strain optimization cycles. The technology is expanding into indications requiring complex metabolic pathway engineering that anaerobic systems uniquely accommodate.
EMA's Committee for Medicinal Products for Human Use has tightened quality-by-design manufacturing standards for live biotherapeutics, mandating real-time process analytical technology integration. Sponsors must demonstrate continuous viable cell monitoring throughout production. Oral delivery formulations face heightened scrutiny relative to intravenous products, driving investment in closed-system manufacturing architectures.
Hospital procurement committees now unbundle after-sales clinical support from product pricing, demanding dedicated microbiome specialist nursing networks as a condition of formulary inclusion. This behavior compresses traditional distributor margins and elevates integrated service capabilities as a competitive differentiator. The United States exhibits the most pronounced shift, where Medicare Advantage plans increasingly require outcomes documentation for continued reimbursement eligibility.
Microbial Therapeutic Products Market Segmentation
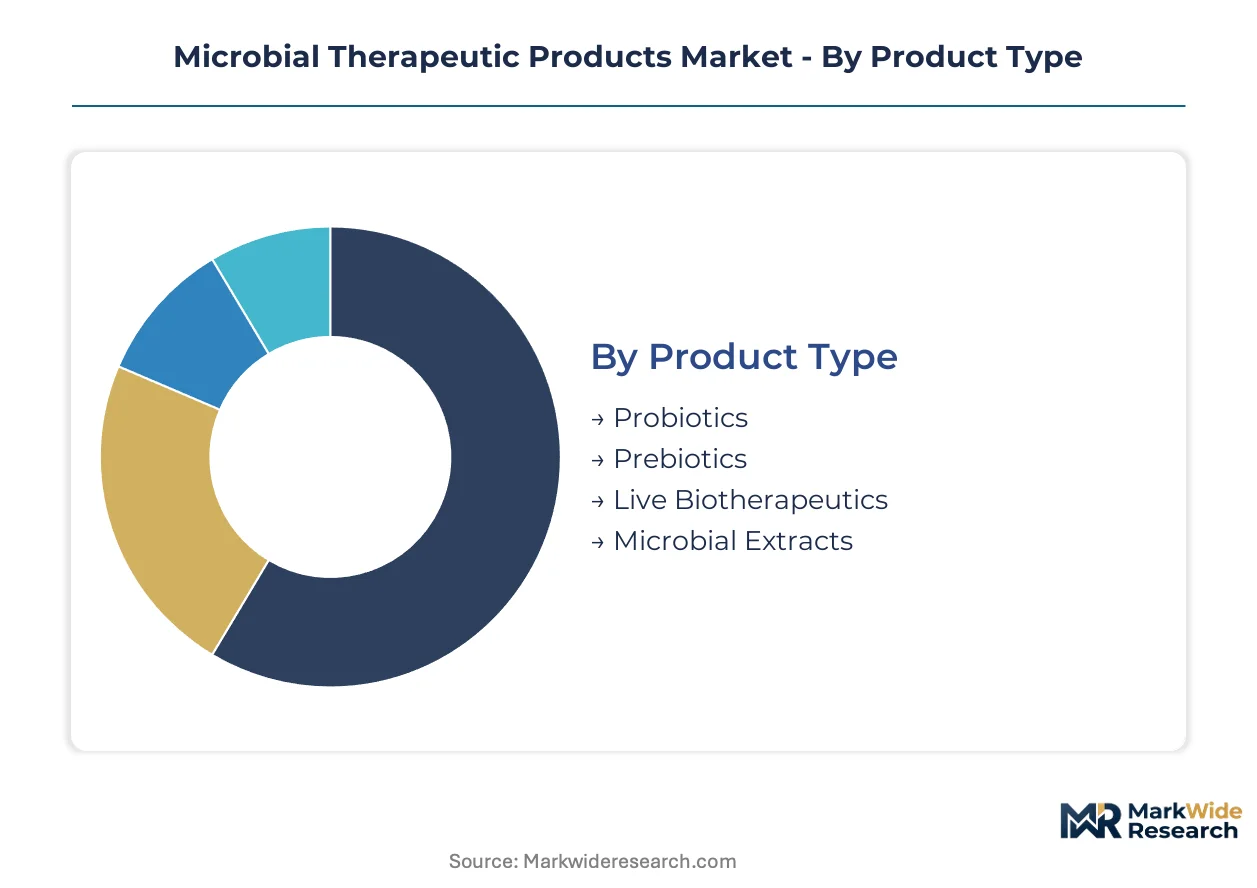
Segmentation in microbial therapeutics reveals how manufacturing complexity, reimbursement pathways, and clinical evidence requirements reshape competitive boundaries across product categories. Buyers prioritize regulatory clearance status and cold-chain reliability over unit economics, fragmenting procurement patterns across hospital systems and retail channels.
Product Type:
Hospital formulary committees weight pharmaceutical-grade certification and viable cell count guarantees above cost per dose when selecting live microbial interventions.
- Live Biotherapeutics:Controlled anaerobic fermentation yields defined purity thresholds exceeding 99.5% viable cell counts. Medicare reimbursement pathways in the United States unlock hospital procurement budgets for FDA-cleared live biotherapeutics, accelerating physician adoption through specialized infusion center networks.
- Probiotics:Over-the-counter formulations dominate retail pharmacy volume with shorter regulatory pathways but compressed margin structures. German and French bioeconomy investments under the EU Green Deal expand cell-culture capacity for pharmaceutical-grade probiotic manufacturing, reducing reliance on South Korean contract fermentation.
- Prebiotics:Non-viable substrates that selectively nourish beneficial microbiota, manufactured through enzymatic processing rather than fermentation.
- Microbial Extracts:Purified cellular components derived from lysed bacterial cultures, used in metabolic correction therapies.
Live Biotherapeutics leads on scale; Live Biotherapeutics leads on momentum.
Application:
Clinical evidence accumulation and mechanistic validation determine which therapeutic areas command premium pricing versus commodity positioning.
- Gastrointestinal Disorders:Dysbiosis-related pathologies anchor near-term demand with established clinical endpoints and FDA Investigational New Drug precedents. United States hospital systems expand live biotherapeutic formularies as the FDA Center for Biologics Evaluation and Research clarifies quality benchmarks, concentrating procurement in academic medical centers with dedicated microbiome specialist nursing networks.
- Mental Health:Gut-brain axis interventions represent underpenetrated territory where neuroscience research at academic medical centers generates mechanistic evidence. EMA quality-by-design manufacturing standards impose stricter evidentiary burdens than FDA pathways, fragmenting trial strategies for psychiatric indications.
- Immune Support:Prophylactic and therapeutic modulation of host immune responses through microbial colonization.
- Metabolic Conditions:Interventions targeting insulin sensitivity, lipid metabolism, and energy homeostasis through microbiome modulation.
Gastrointestinal Disorders commands the largest addressable patient population; Mental Health is climbing the fastest as mechanistic validation accelerates.
Delivery Mode:
Administration route dictates reimbursement premiums, cold-chain requirements, and manufacturing facility certification levels.
- Oral:Capsule and liquid formulations dominate volume share with simplified logistics but face heightened EMA scrutiny relative to parenteral products. Hospital procurement committees unbundle after-sales clinical support from oral product pricing, compressing traditional distributor margins in the United States.
- Intravenous:Hospital administration protocols capture disproportionate margin pools through reimbursement premiums and specialized infusion requirements. Danish contract fermentation capacity concentrates supply for IV-grade live biotherapeutics, creating geographic vulnerability for sponsors lacking captive manufacturing.
- Topical:Cutaneous and mucosal applications requiring localized microbial colonization without systemic absorption.
- Inhalation:Pulmonary delivery systems for respiratory microbiome modulation with specialized aerosolization requirements.
Oral formulations lead on volume; Intravenous delivery leads on margin capture.
End User:
Procurement authority and reimbursement eligibility separate institutional buyers from direct-to-patient channels.
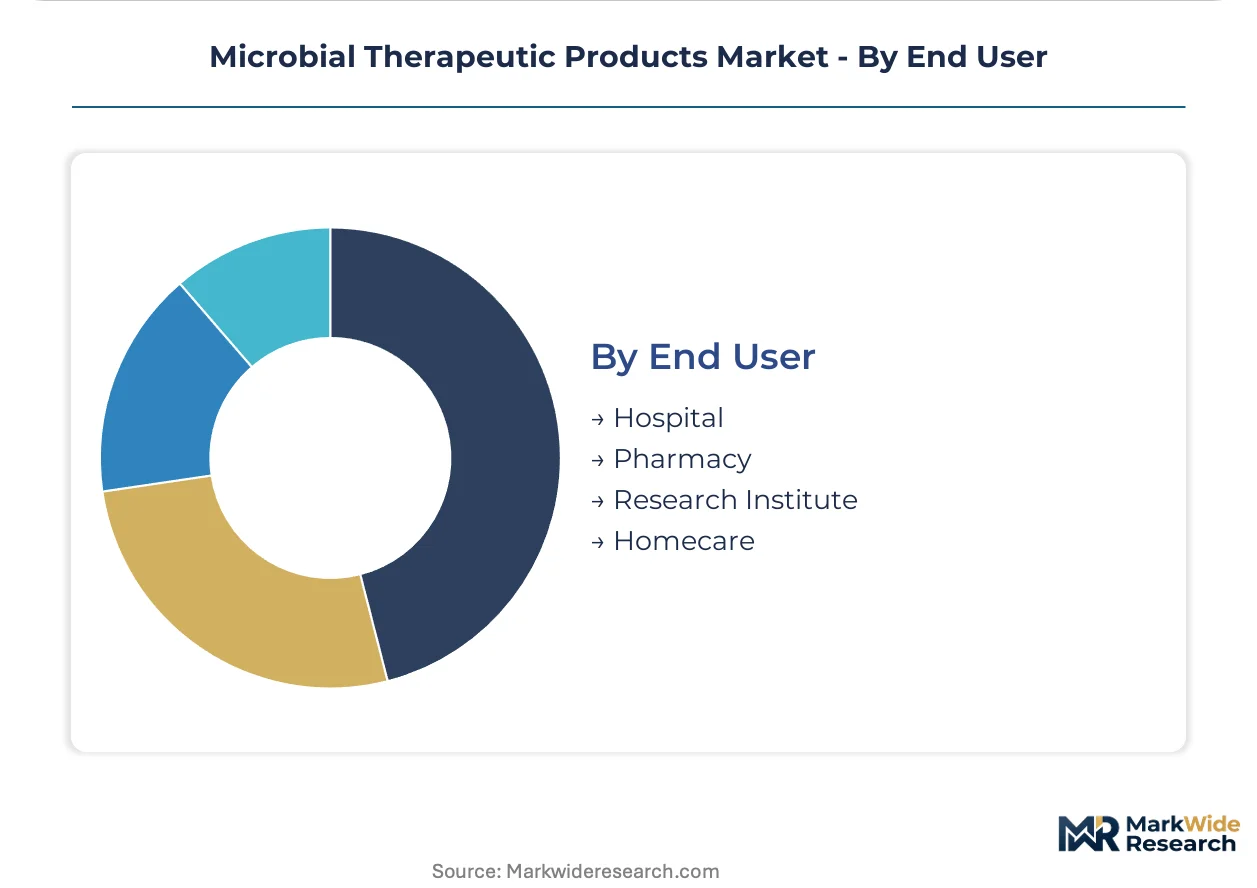
- Hospital:Formulary committees demand real-world evidence packages alongside traditional efficacy data, elevating integrated service capabilities as competitive differentiators. Medicare Advantage plans in the United States increasingly require outcomes documentation for continued reimbursement eligibility, privileging sponsors with dedicated microbiome specialist nursing networks.
- Pharmacy:Retail and specialty pharmacy channels handle probiotic and over-the-counter live biotherapeutics with compressed margin structures.
- Research Institute:Academic medical centers and contract research organizations source investigational products for clinical trial supply.
- Homecare:Direct-to-patient distribution for chronic administration with cold-chain logistics managed through specialty pharmacy networks.
Hospital procurement leads on revenue concentration; Homecare channels are expanding most quickly as oral formulations simplify administration logistics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States demand for gastrointestinal biotherapeutics outpaces German procurement volumes by a factor of three, while Danish contract fermentation capacity anchors European supply security for intravenous-grade live products.
United States
Medicare reimbursement pathways for gastrointestinal biotherapeutics unlock hospital procurement budgets across academic medical centers. FDA Center for Biologics Evaluation and Research clarifies quality benchmarks for microbiome-derived drugs. Specialized infusion center networks in Massachusetts and North Carolina concentrate physician adoption curves for live biotherapeutic administration.
Germany
National bioeconomy strategies accelerate cell-culture capacity investments for anaerobic fermentation scale-up. EU Green Deal manufacturing incentives provide direct public co-financing for pharmaceutical-grade live biotherapeutic production. Industrial clusters in Baden-Württemberg and North Rhine-Westphalia host expanding precision-fermentation facilities serving EMA quality-by-design standards.
Denmark
Contract fermentation capacity concentrates supply for IV-grade live biotherapeutics with defined purity thresholds exceeding 99.5% viable cell counts. EMA Committee for Medicinal Products for Human Use prioritizes quality-by-design manufacturing standards for sponsors. Copenhagen-region facilities specialize in closed-system manufacturing architectures for cold-chain-dependent live products.
South Korea
Contract fermentation infrastructure decouples from traditional small-molecule pharmaceutical manufacturing. MFDS regulatory frameworks align with international quality certification requirements for live biotherapeutic exports. Seoul Capital Area bioclusters expand anaerobic fermentation talent pipelines through university-industry partnerships.
Switzerland
Swissmedic oversight harmonizes with EMA evidentiary standards while maintaining distinct national authorization pathways. Dedicated microbiome research divisions generate mechanistic evidence for gut-brain axis interventions. Basel-region pharmaceutical networks integrate live biotherapeutic development into existing biologics manufacturing competencies.
Microbial Therapeutic Products Market Competitive Environment
United States-based producers anchor one tier; European specialists hold quality-certification advantages through EMA-aligned manufacturing standards. The vendor base concentrates around three strategic archetypes: diversified pharmaceutical conglomerates leveraging biologics infrastructure, dedicated microbiome research divisions within mid-cap specialists, and precision-fermentation spinouts from academic medical centers. Dominant competitive moves include captive manufacturing investments to reduce geographic supply vulnerability and strategic partnerships with hospital systems for integrated clinical support networks.
Within the diversified pharmaceutical tier, Pfizer Inc. and Novartis AG exemplify scale-driven positioning through biologics manufacturing network extension. Amgen Inc. occupies a distinct archetype centered on recombinant microbial strain engineering capabilities. Dr. Reddy's Laboratories Ltd. represents emerging-market fabrication capacity serving contract manufacturing demand. These three anchors collectively illustrate how competitive moats reconfigure around quality certification and regulatory pathway expertise rather than manufacturing scale alone.
| Leading Market Players |
|---|
| Mylan N.V. |
| F. Hoffmann-La Roche Ltd. |
| Novartis AG |
| Amgen Inc. |
| Merck & Co. Inc. |
| Pfizer Inc. |
| Biocon |
| Dr. Reddy's Laboratories Ltd. |
| Eli Lilly and Company |
| Others |
Value Chain & Pricing Dynamics
Hospital formulary committees in the United States now unbundle after-sales clinical support from product pricing, forcing manufacturers to absorb service costs or concede margin. This procurement shift concentrates pricing power with integrated sponsors possessing dedicated microbiome specialist nursing networks, while fragmenting traditional distributor economics.
Pricing Analysis
Distributor margin compression runs through oral live biotherapeutic channels as hospital procurement committees demand bundled clinical support. Three-tier pricing structure across premium IV-grade, standard oral pharmaceutical-grade, and economy probiotic levels separates margin pools by administration route and certification tier. Pricing pressure stems from Medicare Advantage outcomes documentation requirements tightening reimbursement eligibility. Retail pharmacy channels exhibit highest price sensitivity; hospital IV-grade formulations maintain lowest sensitivity due to reimbursement premiums and captive formulary status.
Supply Chain Analysis
Industrial microbiology program output in Denmark and South Korea constrains anaerobic fermentation talent pipelines for pharmaceutical-grade manufacturing. Supply concentrates in Copenhagen-region facilities and Seoul Capital Area bioclusters, with German Baden-Württemberg precision-fermentation investments emerging as third anchor. Raw material dependencies center on defined culture media, single-use bioreactor systems, and cryopreserved master cell banks. Single-source geographic concentration creates vulnerability for sponsors lacking captive manufacturing. Distribution runs through cold-chain specialty logistics networks with hospital direct-to-site delivery for IV products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The microbial therapeutics market compounds steadily as regulatory framework clarity for live biotherapeutics unlocks institutional procurement budgets across Medicare-reimbursed channels.
For Market Incumbents: Acquire captive anaerobic fermentation capacity in Germany or Denmark to reduce geographic supply vulnerability. Secure EMA quality-by-design certification ahead of FDA Investigational New Drug pathway divergence. Build dedicated microbiome specialist nursing networks to meet hospital formulary unbundling demands and defend service-integrated pricing. For New Entrants and Emerging Players: Capture psychiatric indications in Mental Health applications where mechanistic validation is accumulating but commercial penetration remains limited. Target academic medical center spinout partnerships for rapid strain optimization capabilities. Lead with GDPR-compliant data architectures to differentiate in EU predictive therapeutic development. For Investors and Strategic Acquirers: Asymmetric upside sits with precision-fermentation spinouts from university-industry partnerships possessing proprietary recombinant microbial strain platforms. The five-to-ten year viability window favors sponsors with integrated manufacturing and clinical support capabilities. Watch FDA-EMA evidentiary standard divergence as signal for regulatory investment burden fragmentation.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Manufacturing Investment | Denmark and Germany facility ownership reduces single-source dependency for IV-grade live biotherapeutics. |
| Regulatory Dual-Track Preparation | Parallel FDA IND and EMA quality-by-design readiness mitigates harmonization failure risk. |
| Clinical Support Network Buildout | Dedicated microbiome specialist nursing capabilities satisfy Medicare Advantage outcomes documentation requirements. |
| Precision-Fermentation Partnership | Academic spinout alliances accelerate recombinant strain engineering for orphan-disease categories. |
| GDPR-Compliant Data Architecture | Privacy-preserving platforms secure early-mover advantage under EU AI Act constraints on microbiome data utilization. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with drug development executives, regulatory affairs leads, hospital formulary directors, and payer access specialists with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital procurement databases. Bottom-up manufacturer capacity assessments and top-down reimbursement pathway analysis were triangulated to anchor volume and value estimates.
Segment-weighting across product type, application, delivery mode, and end user dimensions structured the analytical framework over the projection horizon. CAGRs were derived from modeled adoption curves by therapeutic area and administration route, incorporating Medicare reimbursement pathway expansion rates and EU Green Deal manufacturing incentive uptake as industry-specific inputs.
Regulatory harmonization failure, anaerobic fermentation capacity bottlenecks, and live product stability limits are the dominant revision risks that could compress or extend projected trajectories. Forecasts embed assumptions about FDA-EMA evidentiary standard convergence and cold-chain logistics cost trajectories. Material deviation in reimbursement pathway clarity or contract manufacturing geographic concentration warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Microbiology
Lipase Market
Industrial Microbiology
Freeze-Dried Microbial Food Culture Market
Industrial Microbiology
Microbial Protein Used in Feed Market
Industrial Microbiology
Microbial Cell Banking Market
Industrial Microbiology
Global Arabinogalactan Market
Industrial Microbiology
Microbiology Testing Market
Industrial Microbiology
Automated Microbiology Market
Industrial Microbiology
Cultured Dextrose Market
Industrial Microbiology
Ripening Cultures Market
Industrial Microbiology
Benzoate-Free Enzymes Market
Industrial Microbiology
Middle East Feed Probiotics Market
Industrial Microbiology
Global Microbiome Therapeutics Market
Industrial Microbiology
Microbial Rennet Market
Industrial Microbiology
Bacillus Coagulans Market
Industrial Microbiology
Industrial Microbiology Market
Industrial Microbiology
Microbial API Market