
 Medical Waste Supervision Solution Market | 2026-2036
Medical Waste Supervision Solution Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Waste Supervision Solution Market Insights
Hospital procurement departments is reorganizing their vendor relationships around full-service waste supervision platforms rather than point solutions. Stericycle, Inc. leverages its national collection network to bundle tracking software with disposal services. Veolia Environnement SA anchors its competitive position through integrated treatment facility ownership across multiple states. Daniels Sharpsmart Inc. differentiates via reusable container systems paired with digital weight and fill monitoring.
Medical waste supervision solutions encompass hardware and software systems that monitor the generation, segregation, transport, treatment, and disposal of infectious, pharmaceutical, and sharps waste, typically incorporating RFID-tagged containers, GPS-enabled transport logs, and cloud-based audit trails with retention periods exceeding three years to satisfy legal discovery requirements. Their primary purpose is to eliminate manual documentation gaps that expose healthcare generators to regulatory penalties and liability chains. Waste Stream Trackers and IoT Monitoring together command the most active R&D investment as facilities seek real-time fill-level alerts and automated manifest generation. Sharps Containers remains the most mature product category with established procurement channels, though margin pools are shifting toward Cloud Software subscriptions that lock in recurring revenue and compliance update delivery.
EPA Standards and OSHA Guidelines jointly determine product design requirements and staff training protocols for U.S. healthcare facilities, while State Regulations introduce fragmentation that vendors must navigate through jurisdiction-specific software modules. The FDA's oversight of pharmaceutical waste classification further complicates disposal routing decisions for hospital pharmacies. Stakeholders must evaluate whether their current vendor relationships can absorb the coming wave of digitized cradle-to-grave traceability mandates without forcing costly infrastructure replacements.
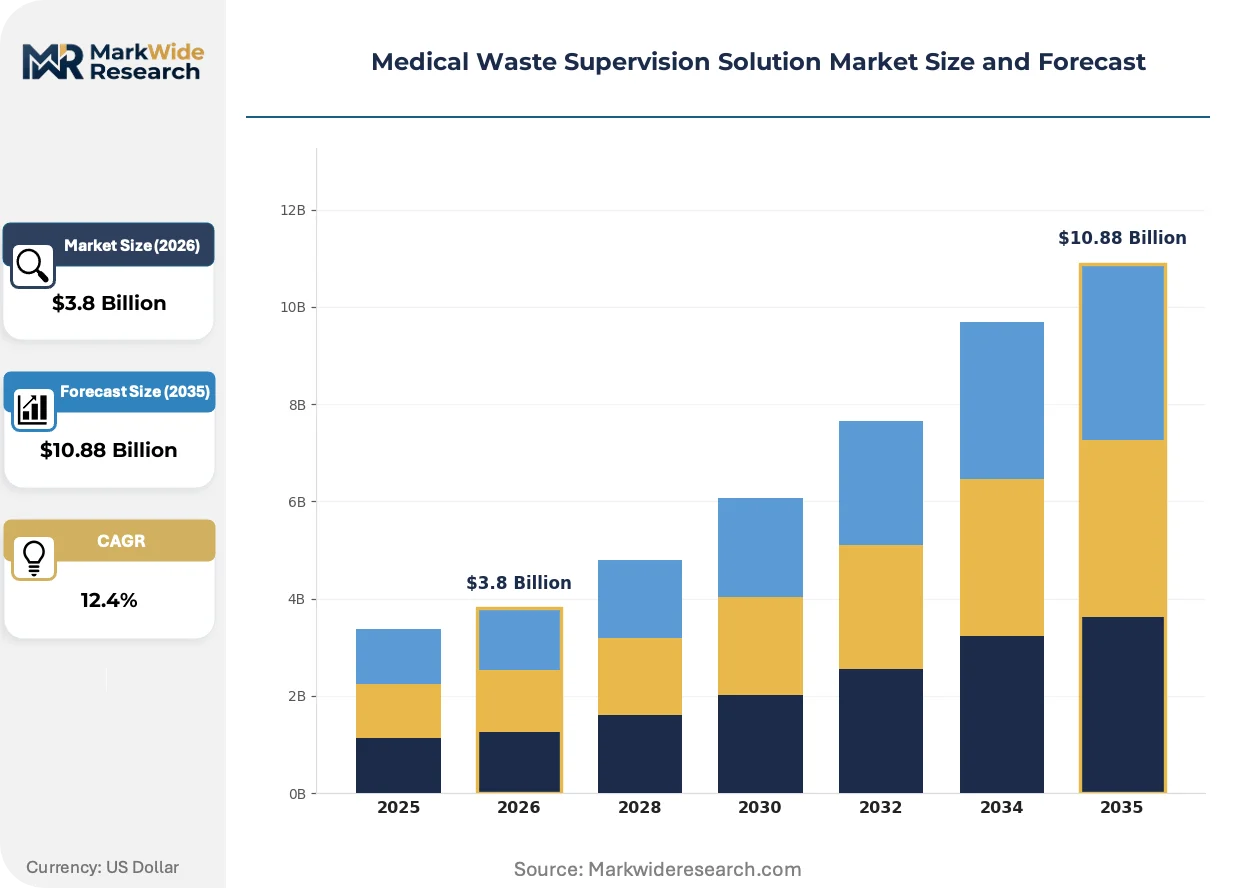
Market Dynamics
Hospital procurement departments are reorganizing their vendor relationships around full-service waste supervision platforms rather than point solutions, driven by the EPA's evolving biomedical waste rules pushing facilities toward automated compliance documentation. This structural shift concentrates demand among vendors capable of bundling hardware, software, and disposal services under unified contract structures.
Growth Catalysts
- EPA biomedical waste rule evolution:The EPA's tightening manifest documentation requirements are compelling healthcare facilities to replace paper-based tracking with RFID-tagged container systems and cloud-based audit trails.
- OSHA bloodborne pathogen exposure prevention:Sharps injury reduction mandates are accelerating hospital adoption of reusable container systems with digital weight and fill monitoring capabilities.
- United States healthcare infrastructure modernization:Federal hospital construction and renovation programs are embedding integrated waste supervision systems into new facility designs rather than retrofitting later.
Market Restraints
- Capital intensity of treatment facility ownership:Autoclave and incinerator infrastructure requires substantial upfront investment, limiting vendor expansion and creating regional supply concentration.
- State regulatory fragmentation:Jurisdiction-specific disposal routing rules force software vendors to maintain costly modular compliance engines for each state.
- Pharmaceutical waste classification complexity:The FDA's oversight of hazardous drug categorization creates routing ambiguity that delays automated disposal decision systems.
Strategic Opportunities
- Underpenetrated outpatient surgical centers:Ambulatory facilities currently rely on manual documentation but face identical liability exposure, creating expansion potential for scaled-down supervision platforms.
- IoT sensor convergence with blockchain verification:Immutable cradle-to-grave record-keeping addresses legal discovery requirements while reducing insurance premium exposure for generators.
- Cloud software subscription models:Recurring revenue streams from compliance update delivery and remote system monitoring are displacing one-time hardware sales.
Industry Challenges
- Integration complexity with legacy hospital information systems:Waste supervision platforms must interface with existing electronic health records and supply chain management software without disrupting clinical workflows.
- Certification timeline for reusable container validation:FDA and state-level approvals for novel sterilization protocols extend product development cycles and delay market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Waste Supervision Solution Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.88 Billion |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sharps Containers, Biohazard Bags, Waste Stream Trackers, Treatment Units Technology: RFID Systems, GPS Tracking, IoT Monitoring, Cloud Software End User: Hospitals, Laboratories, Clinics, Pharmaceutical Companies Regulatory Compliance: EPA Standards, OSHA Guidelines, State Regulations, International Guidelines |
| Companies Covered | Stericycle, Inc., Veolia Environnement SA, Waste Management Inc., Clean Harbors Inc., Republic Services, Inc., REMONDIS SE & Co. KG, Suez Environnement SA, Daniels Sharpsmart Inc., Triumvirate Environmental, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Waste Supervision Solution Market Trends and Innovations
Real-time waste stream visibility is displacing retrospective audit-based compliance across healthcare facilities. Vendors are embedding sensor networks and predictive analytics into container and transport infrastructure to shift risk management from reactive documentation to proactive intervention.
RFID-tagged reusable sharps containers are decomposing the dominance of single-use disposable systems in high-volume hospital settings. Major academic medical centers in the United States are deploying weight-calibrated fill sensors that trigger automated pickup scheduling. This technology is decomposing margin pools away from commodity container manufacturing toward software-enabled service contracts with multi-year retention guarantees.
The EPA's evolving biomedical waste manifest digitization requirements are forcing treatment facility operators to adopt interoperable data exchange standards. This regulatory pressure is compressing vendor differentiation around proprietary tracking formats. Small and mid-sized hospital systems in the United States are responding by consolidating vendor relationships to reduce interface complexity.
Subscription-based compliance service contracts are displacing transactional pickup-and-disposal arrangements in hospital procurement. Health system GPOs are negotiating enterprise-wide platform licenses that bundle hardware, software, and disposal across dozens of affiliated facilities. This shift is most visible in the United States, where integrated delivery networks are leveraging purchasing scale to demand real-time dashboard access for risk management officers.
Medical Waste Supervision Solution Market Segmentation
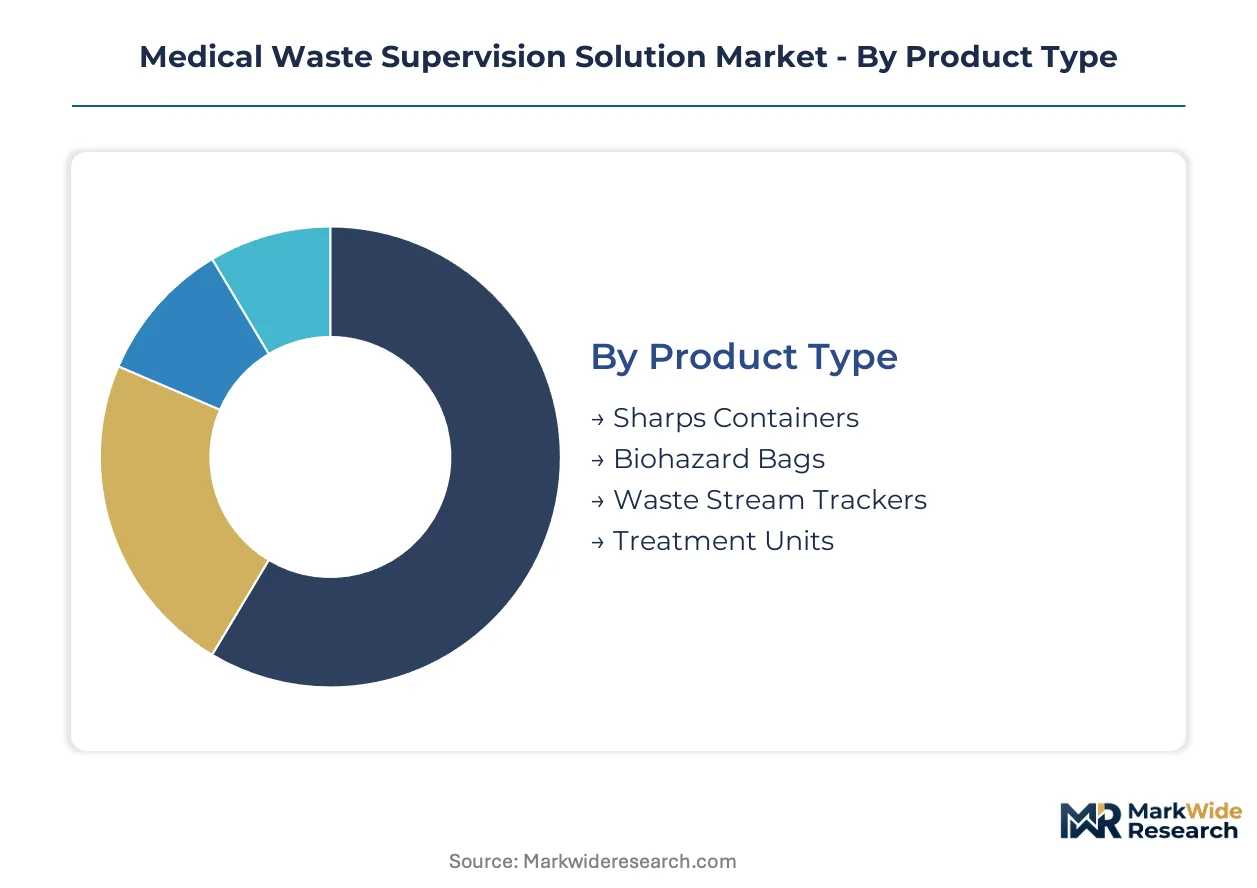
Medical waste supervision solutions fragment across hardware, software, and service layers that command distinct procurement cycles and margin structures. Hospital systems increasingly bundle these categories under unified vendor contracts to reduce integration complexity and compliance fragmentation.
Product Type:
Waste Stream Trackers and Treatment Units concentrate demand domestically within United States hospital construction programs, while Sharps Containers and Biohazard Bags retain substantial export volume to developing healthcare systems.
- Waste Stream Trackers:Digital manifest systems combining RFID-tagged containers with cloud-based audit trails for cradle-to-grave traceability. United States academic medical centers embed these into new facility designs to preempt EPA documentation mandates.
- Sharps Containers:Reusable and single-use containment systems for needles, scalpels, and lancets. OSHA bloodborne pathogen rules drive hospital procurement toward reusable variants with digital fill monitoring in high-volume United States markets.
- Biohazard Bags:Color-coded polyethylene sacks for infectious waste segregation. Clinical laboratories in India and Brazil represent expanding demand as these facilities modernize manual waste handling protocols.
- Treatment Units:Autoclaves, microwave systems, and chemical treatment stations for on-site waste decontamination. United States rural hospitals deploy these to reduce transport liability and per-ton disposal costs.
Sharps Containers holds the largest share; momentum sits with Waste Stream Trackers.
Technology:
Cloud Software subscriptions lock in recurring revenue through compliance update delivery, while RFID Systems and GPS Tracking concentrate in capital-intensive United States hospital infrastructure programs.
- Cloud Software:Browser-based platforms for manifest generation, regulatory reporting, and multi-site dashboard access. United States integrated delivery networks negotiate enterprise licenses spanning dozens of affiliated facilities.
- IoT Monitoring:Sensor networks providing real-time fill-level alerts and predictive pickup scheduling. Hospital systems in Texas and California deploy these to reduce overflow incidents and optimize collection routing.
- RFID Systems:Radio-frequency identification tags embedded in containers for automated chain-of-custody documentation. The EPA's digitization requirements accelerate replacement of barcode-based tracking in United States facilities.
- GPS Tracking:Location logging for transport vehicles to verify disposal facility delivery and transit time compliance. Waste haulers serving United States metropolitan corridors deploy these to satisfy state-level manifest verification rules.
Cloud Software commands the dominant revenue pool; IoT Monitoring is expanding most quickly.
End User:
Hospitals anchor procurement volume through GPO-negotiated platform contracts, while Pharmaceutical Companies and Laboratories represent underpenetrated segments with specialized compliance requirements.
- Hospitals:Acute care, specialty, and long-term facilities generating diverse waste streams from surgical, pharmaceutical, and laboratory operations. United States health system consolidation drives demand for standardized supervision platforms across multi-hospital networks.
- Pharmaceutical Companies:Manufacturers and compounders handling hazardous drug waste, expired inventory, and batch failure destruction. FDA pharmaceutical waste classification complexity delays automated disposal routing adoption.
- Laboratories:Clinical and research facilities processing biological specimens and chemical reagents. United States reference laboratories in North Carolina and California are retrofitting manual documentation with digital tracking systems.
- Clinics:Outpatient and ambulatory surgical centers with lower waste volumes but identical liability exposure. United States dermatology and dental clinics represent scalable entry points for scaled-down supervision platforms.
Hospitals dominate absolute volume; Clinics are gaining share fastest.
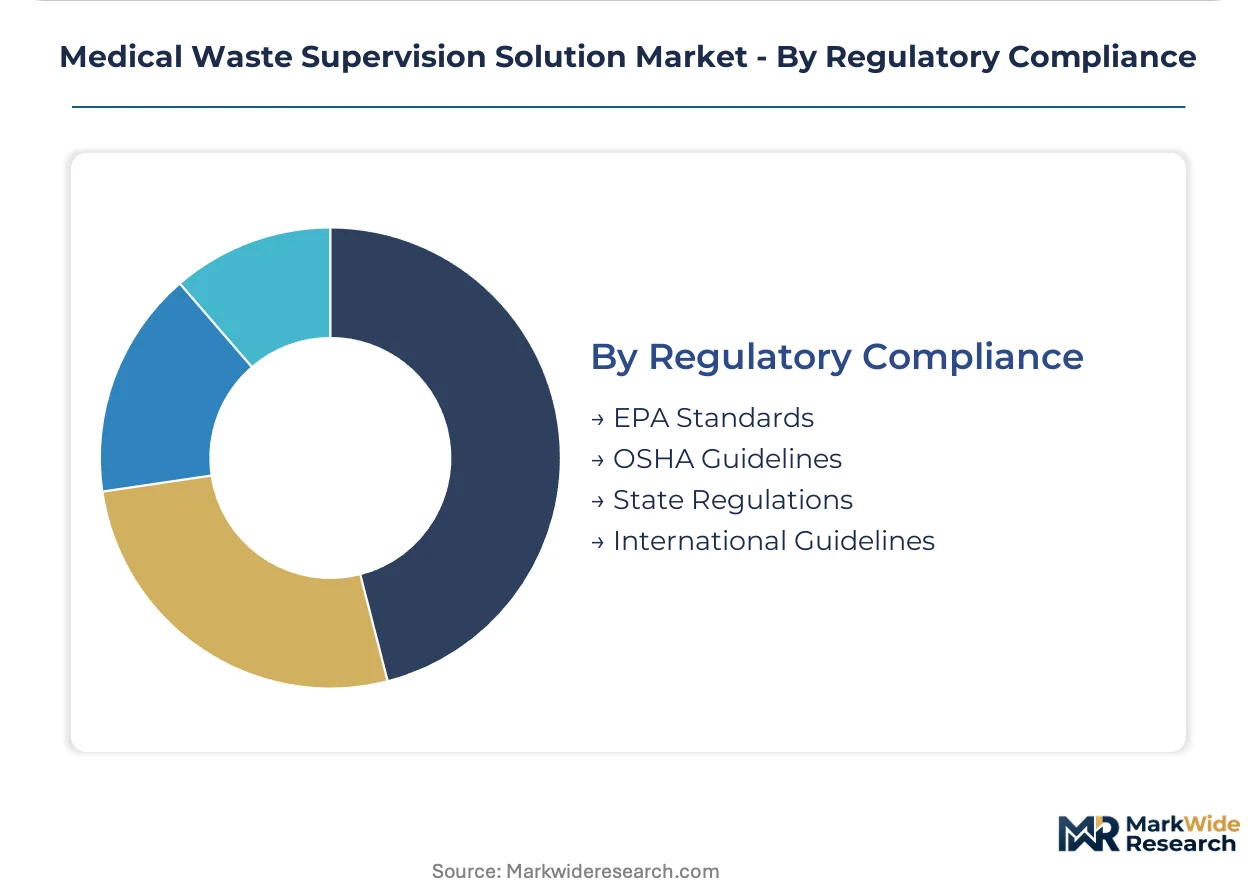
Regulatory Compliance:
United States facilities navigate EPA Standards and OSHA Guidelines as baseline requirements, while State Regulations introduce modular complexity that vendors address through jurisdiction-specific software engines.
- EPA Standards:Federal biomedical waste manifest documentation and treatment facility permitting rules. The agency's evolving digitization mandates compel healthcare generators to replace paper-based tracking with automated systems.
- State Regulations:Jurisdiction-specific disposal routing, treatment method restrictions, and record retention periods. California and New York maintain the most stringent requirements, forcing vendors to maintain costly compliance modules.
- OSHA Guidelines:Bloodborne pathogen exposure prevention protocols including sharps injury reduction and container engineering standards. These rules accelerate adoption of reusable container systems with digital monitoring.
- International Guidelines:WHO recommendations and ISO standards for healthcare waste management in non-United States markets. Export-oriented vendors align product design with these frameworks to access Latin American and Southeast Asian healthcare systems.
EPA Standards anchor procurement specifications; State Regulations are climbing the fastest as digitization mandates proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German waste technology exporters supply RFID tracking hardware to United States hospital construction programs, while French environmental services firms deliver treatment infrastructure to Saudi Arabian healthcare modernization initiatives.
United States
Academic medical centers in Texas and California deploy IoT-enabled fill sensors for automated pickup scheduling. EPA manifest digitization mandates compel rural hospitals to replace paper-based tracking with cloud-based audit trail systems. The Southeast corridor from Florida to Georgia concentrates outpatient surgical center expansion where scaled-down supervision platforms penetrate ambulatory facilities.
Germany
Industrial autoclave manufacturers supply on-site treatment units to Central European hospital networks seeking transport cost reduction. ECHA chemical classification rules intersect with biomedical waste routing protocols, complicating cross-border disposal documentation. Bavaria's medical device cluster near Munich drives demand for integrated tracking systems that interface with sterilization equipment.
China
Tier-three hospital construction in Sichuan and Shaanxi provinces creates procurement volume for basic RFID container systems. MEE hazardous waste regulations tighten treatment facility permitting, pushing generators toward vendor-managed service contracts. The Yangtze River Delta medical corridor from Shanghai to Nanjing concentrates pilot deployments of blockchain-verified disposal documentation.
Saudi Arabia
MOHAP hospital privatization programs embed waste supervision specifications into build-operate-transfer contracts for new medical cities. FDA-aligned pharmaceutical waste protocols at King Faisal Specialist Hospital drive demand for dual-stream segregation systems. The Riyadh-Eastern Province corridor concentrates treatment infrastructure investment as the kingdom reduces import dependency for medical waste services.
Brazil
ANVISA biomedical waste rules accelerate adoption of color-coded segregation systems in São Paulo's private hospital network. State-level environmental licensing in Minas Gerais and Rio de Janeiro creates modular compliance requirements that favor configurable software platforms. The Southeast industrial corridor concentrates autoclave manufacturing for domestic hospital supply and Andean export markets.
Medical Waste Supervision Solution Market Competitive Landscape
Player mix skews toward integrated environmental services conglomerates with captive treatment infrastructure. Market structure concentrates procurement influence among three to five national-scale vendors capable of bundling hardware, software, and disposal under unified contracts. Two strategic archetypes dominate: full-service platform providers owning treatment assets, and specialized technology vendors licensing tracking software to third-party haulers. Competitive moves center on GPO contract consolidation and multi-site enterprise licensing.
Within the integrated services tier, Stericycle, Inc. and Veolia Environnement SA occupy positions exemplifying the treatment-asset-plus-software-bundle model. Daniels Sharpsmart Inc. represents the specialized container-and-tracking archetype, anchoring competitive positioning around reusable hardware with embedded monitoring. These three firms collectively illustrate the structural divergence between asset-heavy disposal integration and technology-focused equipment specialization that defines vendor rivalry.
| Leading Market Players |
|---|
| Stericycle, Inc. |
| Veolia Environnement SA |
| Waste Management Inc. |
| Clean Harbors Inc. |
| Republic Services, Inc. |
| REMONDIS SE & Co. KG |
| Suez Environnement SA |
| Daniels Sharpsmart Inc. |
| Triumvirate Environmental |
| Others |
Pricing and Supply Chain Analysis
Reusable container systems replacing single-use sharps containers in United States hospitals simultaneously shift manufacturing toward domestic sterilization facilities and compress per-unit pricing through multi-year service bundling. This substitution dynamic concentrates margin capture with vendors owning treatment infrastructure while eroding commodity container manufacturers.
Pricing Analysis
Next-generation IoT-enabled waste stream trackers command subscription premiums over legacy barcode systems and basic RFID hardware. Pricing stratifies across premium, standard, and economy tiers based on EPA compliance automation depth and after-sales monitoring intensity. Cost compression in the hardware tier is intensifying because cloud software subscriptions displace capital expenditure models. Outpatient surgical centers exhibit acute price sensitivity versus academic medical centers prioritizing liability reduction.
Supply Chain Analysis
Strategic stockpiling of RFID-tagged containers dominates procurement behavior as hospitals secure supply continuity ahead of EPA digitization deadlines. Manufacturing concentrates in Germany, China, and the United States for sensor hardware, sterilization equipment, and cloud infrastructure respectively. Supply chains draw from semiconductor components, medical-grade polymers, and sterilization chemicals. Single-source vulnerability in autoclave fabrication creates bottleneck risk. Distribution runs through GPO-negotiated enterprise contracts with national hauler networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through United States health system consolidation, with integrated delivery networks leveraging multi-facility scale to demand unified platform pricing and real-time dashboard access.
For Market Incumbents: Compound defensive positioning by deepening captive treatment facility ownership in the Southeast corridor and accelerating FDA validation timelines for novel sterilization protocols. Cloud-native entrants threaten margin pools in compliance software. Priority rests on backward integration into sensor manufacturing to lock component supply. For New Entrants and Emerging Players: Lead with modular scaled-down platforms targeting dermatology and dental clinics in Texas and California where vendor consolidation has left service gaps. Ambulatory surgical centers represent the most penetrable segment. Go-to-market should emphasize rapid deployment without legacy system integration burdens. For Investors and Strategic Acquirers: The market sits at a digitization-investment phase that favors asset-heavy platform providers with EPA-compliant treatment networks. Long-term viability hinges on recurring revenue capture through multi-year retention guarantees. Acquisition targets should display GPO contract density and state-level compliance module coverage. Watch EPA manifest digitization enforcement intensity as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud Software Subscription Migration | Locks recurring revenue through EPA compliance update delivery across hospital networks. |
| Reusable Container System Expansion | Reduces per-procedure waste costs while satisfying OSHA bloodborne pathogen mandates. |
| IoT Sensor Network Deployment | Enables predictive pickup scheduling and real-time fill monitoring for overflow prevention. |
| Treatment Facility Backward Integration | Captures margin pools from disposal services and reduces transport liability exposure. |
| Blockchain Verification Pilot | Addresses legal discovery requirements while reducing insurance premium exposure for generators. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EPA enforcement databases, hospital procurement records, and GPO contract filings. Interviews with biomedical engineers, waste management directors, GPO contracts managers, and regulatory compliance officers informed demand-side validation. Secondary sources include OSHA injury surveillance data, state environmental agency permitting records, and healthcare construction pipeline databases. Bottom-up facility-level modeling triangulates against top-down market sizing.
Segmentation dimensions modeled encompass product type, technology deployment mode, end-user facility scale, and regulatory compliance tier across the analysis window. CAGRs derive from facility expansion pipelines, procurement cycle timing, and vendor contract renewal patterns. Forecast inputs incorporate EPA rulemaking timelines and health system consolidation trajectories.
Forecasts assume regulatory continuity in EPA Standards and OSHA Guidelines; material policy shifts would require re-modeling. Supply chain disruption from semiconductor shortages or sterilization chemical scarcity represents specific revision triggers. Revision becomes warranted when EPA digitization mandate enforcement crosses implementation thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Equipment
Global Hospital Asset Management Market
Healthcare Equipment
Specialty Medical Chairs Market
Healthcare Equipment
Healthcare Personal Protection Equipment Market
Healthcare Equipment
Bedpan Washer Disinfectors Market
Healthcare Equipment
North America Nurse Call Systems Market
Healthcare Equipment
Cold Plunge Tub Market
Healthcare Equipment
Middle East and Africa Ultrasound Probe Disinfection Market
Healthcare Equipment
Healthcare Cold Chain Monitoring Market
Healthcare Equipment
Microbiological Safety Cabinets Market
Healthcare Equipment
Iraq Intensive Care Unit (ICU) Beds and Surfaces Market
Healthcare Equipment
Veterinary Furniture Market
Healthcare Equipment
Clinical Mobility Market
Healthcare Equipment
US Medical Cold Storage Market
Healthcare Equipment
Ophthalmic Examination Chairs Market
Healthcare Equipment
Patient Recliner Chair Market
Healthcare Equipment
North America Healthcare Machine Vision System Market