
 Europe Dietary Supplements Market | 2026-2036
Europe Dietary Supplements Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Dietary Supplements Market Intelligence
The European Union's Green Deal and its Farm to Fork strategy is shifting consumer preference toward supplements with transparently sourced, sustainable ingredients. This places new demands on supply chain verification. Bayer AG leverages its extensive pharmaceutical R&D to develop clinically supported products. Nestlé Health Science specializes in personalized nutrition and medical nutrition segments, while Glanbia plc dominates the sports nutrition space through its control over whey protein supply chains.
Dietary supplements in Europe are legally defined as concentrated sources of nutrients or other substances with a nutritional or physiological effect. These products, often containing vitamins, minerals, or herbal extracts, are formulated in dose forms like capsules or tablets to supplement a normal diet. Within product types, vitamins and probiotics represent the fastest-growing categories, addressing consumer needs for immune and digestive health. Online retailers and pharmacies are the primary distribution channels, capturing the majority of consumer spending across the region.
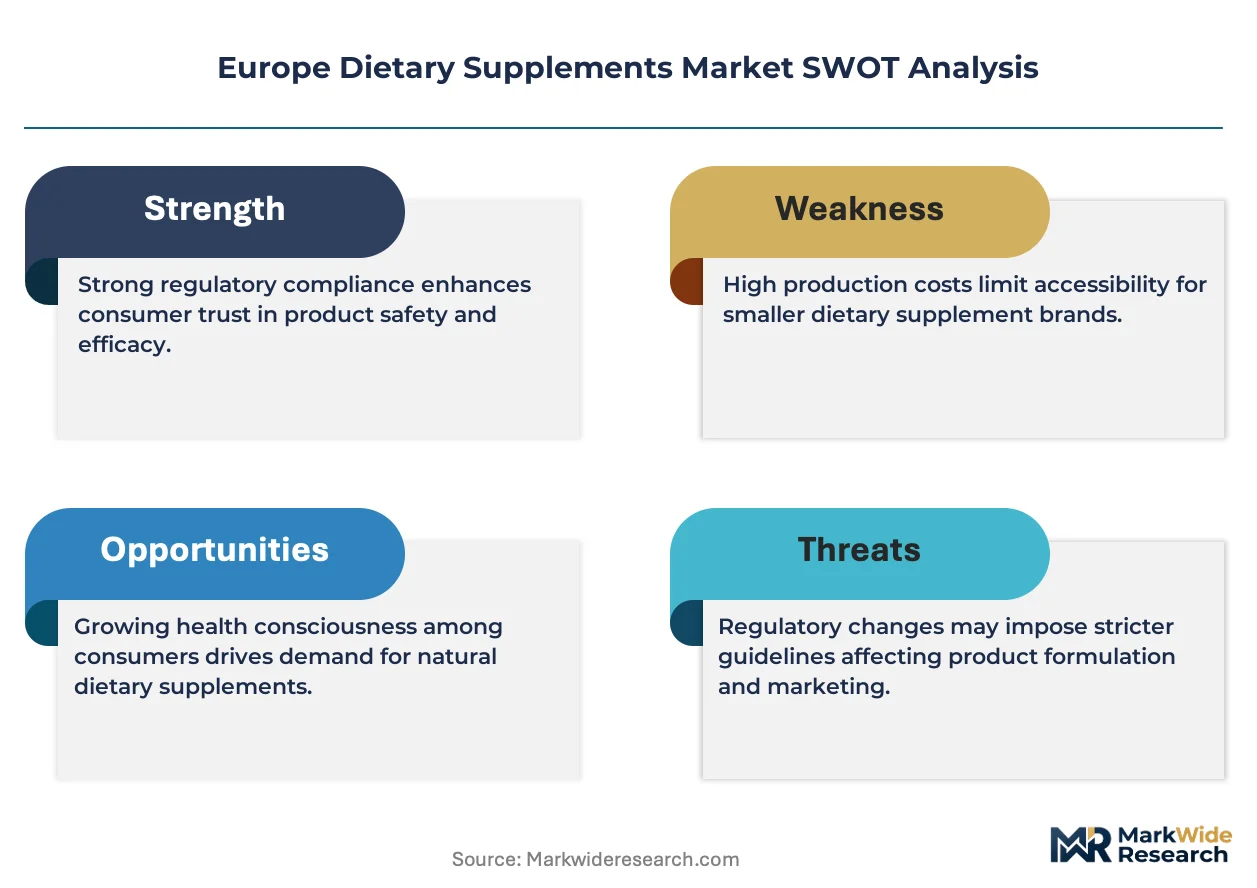
Market access in Europe is governed by the European Food Safety Authority (EFSA), which assesses the safety and health claims of supplements. Concurrently, Regulation (EU) 2015/2283 on novel foods and the CE marking for certain device-like supplements set stringent pre-market approval hurdles. Manufacturers must navigate these complex frameworks to ensure compliance and market access. The critical decision for market participants is how to balance innovation in formulation with the high burden of proof required for health claims.
Market Dynamics
The European dietary supplements market is defined by the structural tension between consumer demand for personalized, innovative health solutions and the stringent pre-market approval and health claim substantiation requirements mandated by the European Food Safety Authority.
Growth Catalysts
- Sustainable Sourcing Mandates:The EU's Farm to Fork strategy incentivizes the use of transparently sourced, sustainable ingredients, aligning with consumer values and creating a preference for certified organic and non-GMO products.
- Demographic Shifts:Europe's aging population fuels demand for supplements targeting age-related conditions, particularly in categories like cognitive function, joint health, and cardiovascular support, especially in Western European nations.
- Retail Channel Expansion:The growing dominance of online retailers and direct-to-consumer models expands market access, particularly for niche and specialized brands that bypass traditional pharmacy gatekeepers.
Market Restraints
- Regulatory Burden:The European Food Safety Authority's rigorous evaluation process for health claims creates significant R&D cost and timeline barriers, limiting the scope of marketing messages for new formulations.
- High Substantiation Costs:The expense of conducting human clinical trials required to validate a health claim is prohibitive for many small and medium-sized enterprises, concentrating innovation among larger firms.
- Threat from Fortified Foods:The proliferation of functional foods and beverages enriched with vitamins, minerals, and probiotics presents a direct substitution threat, offering convenience over traditional dose forms like capsules.
Strategic Opportunities
- Personalized Nutrition:The convergence of digital health platforms with at-home diagnostics creates significant white space for customized supplement regimens tailored to an individual's unique genetic or biomarker profile.
- Eastern Europe Penetration:Markets in Poland and the Czech Republic exhibit growing disposable incomes and health awareness, representing underpenetrated regions for market expansion beyond the saturated German and French markets.
- Plant-Based Formulations:Rising veganism and flexitarian diets across Europe open opportunities for supplements based on plant-derived proteins, omega-3s from algae, and botanical extracts, moving beyond traditional animal-based sources.
Industry Challenges
- Novel Food Approval Timelines:Navigating Regulation (EU) 2015/2283 for new ingredients, such as exotic botanical extracts or lab-grown nutrients, involves a lengthy and uncertain approval process that can delay product launches.
- Supply Chain Traceability:Implementing the digital systems required to provide full ingredient traceability from farm to capsule, as expected under the EU Green Deal, is a significant operational and capital challenge.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Dietary Supplements Market |
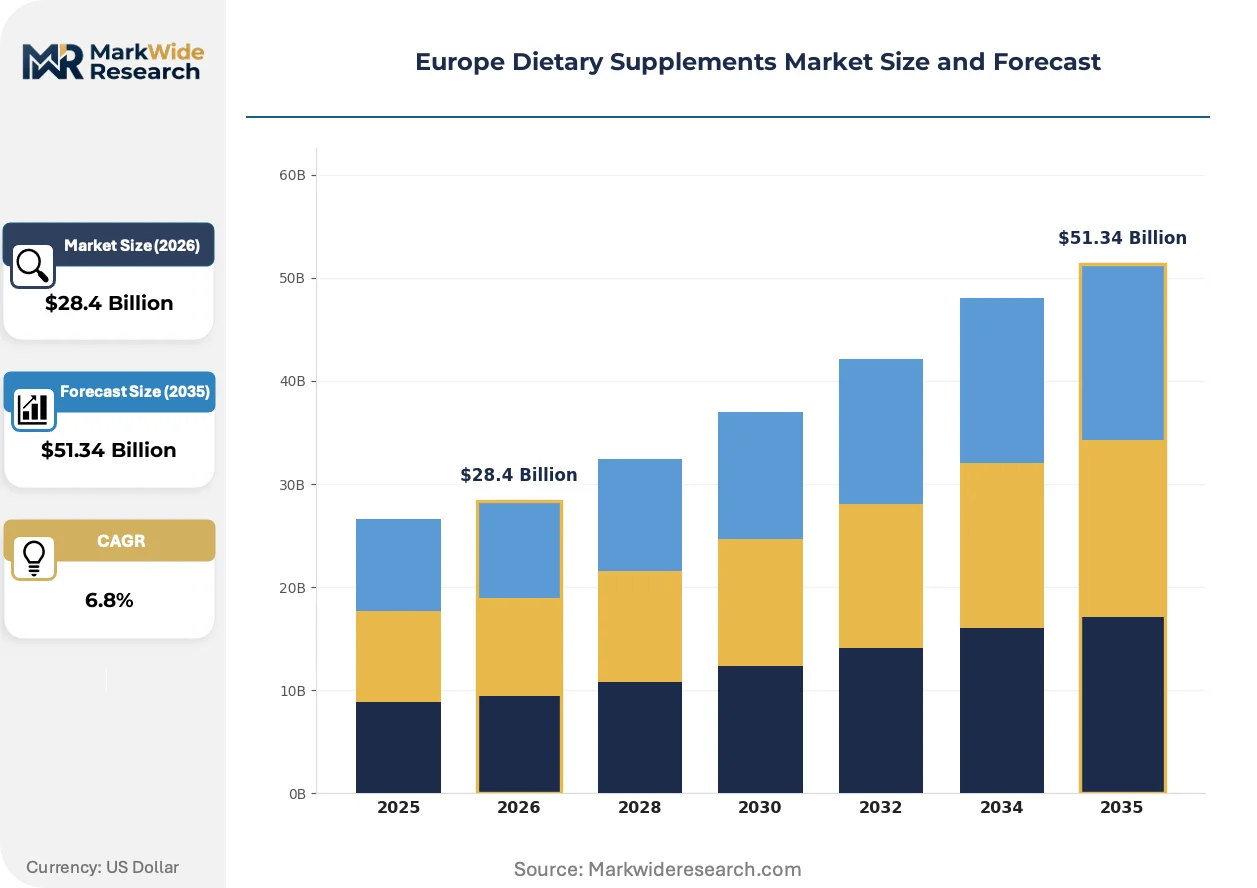
| Market Size in 2026 | $28.4 Billion |
| Market Size in 2035 | $51.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vitamins, Minerals, Herbal Extracts, Amino Acids, Enzymes, Probiotics Application: Energy & Endurance, Immune Support, Weight Management, Digestive Health, Bone & Joint Care, Cognitive Function End User: Pharmacies, Health Food Stores, Fitness Centers, Online Retailers, Wellness Clinics, Supermarkets Distribution Channel: Online Stores, Retail Pharmacies, Direct Selling, Specialty Stores, Mass Retailers, Healthcare Providers |
| Companies Covered | Bayer AG, Haleon PLC, GlaxoSmithKline plc, Nestlé Health Science, Abbott Laboratories, Glanbia plc, Herbalife Nutrition Ltd, Perrigo Co Plc, Sanofi, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Dietary Supplements Market Strategic Shifts & Innovations
A convergence of digitalization, sustainability reporting, and consumer demand for evidence-based wellness is reshaping product development and market access. This shift prioritizes verifiable data, from clinical trial results to supply chain transparency, over generic health claims.
Personalized nutrition platforms using AI to analyze biomarker data represent a key innovation. Health-conscious consumers in the UK and Scandinavia are early adopters seeking bespoke wellness plans. This technology is electrifying the market by moving it from mass-market vitamins toward hyper-customized supplement subscriptions based on individual health data.
The EU's Corporate Sustainability Reporting Directive (CSRD) extends accountability beyond financial metrics. This regulation forces manufacturers to disclose detailed environmental and social governance data, including supply chain labor practices. The botanical and herbal extracts segment is most affected, as proof of sustainable harvesting becomes a critical purchasing factor.
Consumer purchasing is shifting from pharmacies to online, direct-to-consumer (DTC) subscription models. This channel disintermediates traditional retailers, giving brands direct access to consumer data and fostering loyalty. The trend is most pronounced among urban millennials across Europe, particularly for specialized sports and beauty-from-within products.
Europe Dietary Supplements Market Segmentation
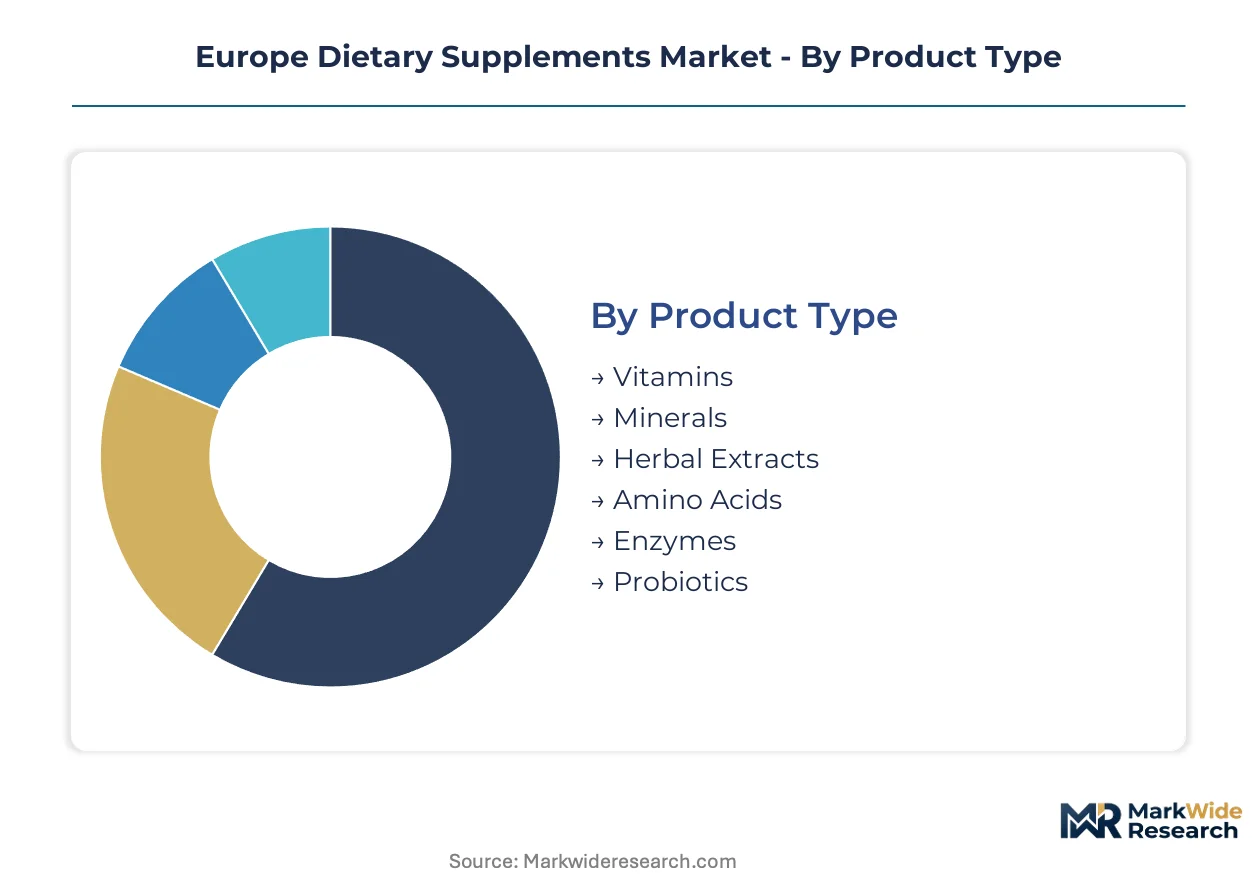
Segmentation of the Europe dietary supplements market reveals granular insights into consumer preferences and regulatory pathways. Understanding these distinct market segments is crucial for manufacturers navigating the complex landscape of health claims and ingredient approvals. This analysis delineates key product types, applications, end-users, and distribution channels.
Product Type:
The regulatory burden for dietary supplements varies significantly across product types, with certain ingredients facing stricter pre-market approval processes from the European Food Safety Authority.
- Vitamins:High consumer recognition drives demand for essential micronutrients in Germany and the UK, often requiring EFSA approval for specific health claims.
- Probiotics:These live microorganisms, gaining traction for digestive and immune health, face stringent scientific substantiation requirements for health claims under EU regulations.
- Minerals:Essential trace elements like zinc and magnesium are widely consumed across Europe, supporting various physiological functions.
- Herbal Extracts:Botanical ingredients, such as turmeric and echinacea, are popular in France and Italy, often subject to national botanical lists and safety assessments.
- Amino Acids:Products like BCAAs find strong demand within the sports nutrition segment, particularly among active consumers in Scandinavia.
- Enzymes:Digestive enzymes are utilized for gut health support, with increasing interest from an aging population in Western Europe.
Vitamins sit at the top of the volume ranking, with Probiotics climbing the fastest.
Application:
Consumer health priorities directly influence the demand trajectory for specific dietary supplement applications across European markets.
- Immune Support:This application experienced significant growth across Europe, driven by heightened health awareness and the desire to bolster natural defenses, particularly in countries like Italy and Spain.
- Digestive Health:Products targeting gut flora balance and digestive comfort are highly sought after by health-conscious consumers, with probiotics being a key ingredient for this segment in the Netherlands.
- Energy & Endurance:Athletes and active individuals in countries such as Sweden and Finland consume supplements to enhance physical performance and recovery.
- Weight Management:This category addresses consumer interest in metabolic support and satiety, with varied product forms popular in the UK.
- Bone & Joint Care:Europe's aging population drives consistent demand for supplements supporting skeletal and joint health, particularly in Germany.
- Cognitive Function:Supplements aimed at memory and focus are gaining traction among students and professionals, especially in urban centers across France.
Immune Support applications show strong market penetration, while Cognitive Function products are expanding most quickly.
End User:
The diverse end-user landscape for dietary supplements reflects varied purchasing behaviors and access points across the European region.
- Online Retailers:This channel captures a significant share of consumer spending due to convenience and broader product selection, particularly among younger demographics in the UK and Germany.
- Pharmacies:Traditional pharmacies remain a trusted source for health-related products, especially for older consumers seeking professional advice in countries like France and Italy.
- Health Food Stores:These specialized outlets cater to consumers seeking natural and organic supplements, prevalent in Scandinavia.
- Fitness Centers:Sports nutrition products are retailed directly to gym-goers and athletes, particularly in urban areas.
- Online Retailers:This channel captures a significant share of consumer spending due to convenience and broader product selection, particularly among younger demographics in the UK and Germany.
- Wellness Clinics:Personalized nutrition plans often incorporate supplements recommended through these health service providers.
- Supermarkets:Mass-market availability of basic vitamin and mineral supplements occurs through large grocery chains across Europe.
Online Retailers continue to gain market share, with Wellness Clinics representing an emerging, specialized segment.
Distribution Channel:
The market's distribution channels dictate product accessibility and brand visibility, with digital platforms rapidly expanding their reach across Europe.
- Online Stores:This channel offers unparalleled reach and convenience, facilitating direct-to-consumer models for both established brands and niche players across the entire European market.
- Retail Pharmacies:These remain critical for consumer trust and expert consultation, particularly for products requiring a degree of medical credibility in countries like Germany and Spain.
- Mass Retailers:Large supermarket chains and hypermarkets provide broad access to mainstream supplement brands for everyday consumers.
- Specialty Stores:Health food shops and sports nutrition outlets cater to specific consumer segments with curated product selections.
- Direct Selling:This model allows for personalized recommendations and community building, particularly for new and innovative product lines.
- Healthcare Providers:Physicians and nutritionists recommend specific supplements, influencing purchasing decisions through professional endorsement.
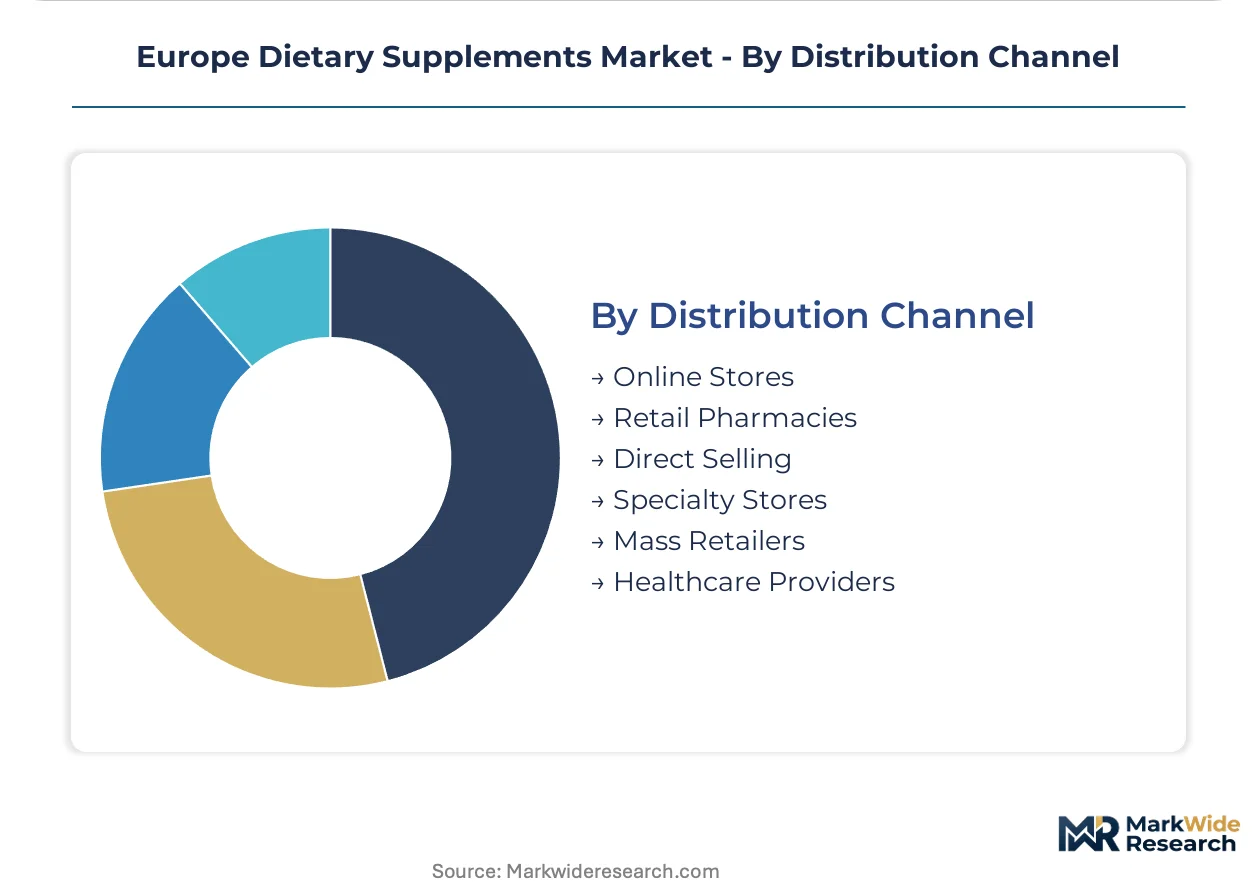
Online Stores dominate the growth trajectory, while Direct Selling models are experiencing renewed interest for personalized offerings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Europe's concentration of advanced research institutions and a highly skilled workforce in pharmaceutical and food science anchors the region's dietary supplements market. This specialized talent pool drives innovation in formulation and ingredient sourcing, particularly for evidence-backed health solutions. Regulatory bodies like the European Food Safety Authority ensure product safety and claim substantiation, fostering consumer trust across the continent.
Germany
Germany's large, health-conscious consumer base drives strong demand for vitamins and minerals, particularly for bone and joint health. The country's robust regulatory framework, influenced by EFSA guidelines, ensures high product quality. Major pharmaceutical hubs like Frankfurt and Munich are centers for dietary supplement R&D, focusing on clinically validated formulations.
United Kingdom
The UK consumer market shows high adoption of personalized nutrition platforms and direct-to-consumer supplement models, especially among urban millennials. The Food Standards Agency oversees national regulations, often aligning with EU standards for product safety. London's vibrant tech ecosystem supports innovation in digital health and customized wellness solutions.
France
French consumers prefer herbal extracts and botanical ingredients, with a cultural emphasis on natural remedies and digestive health. The Agence nationale de sécurité du médicament et des produits de santé (ANSM) regulates herbal products, maintaining a national botanical list. Paris and Lyon host research clusters exploring novel plant-based compounds for health applications.
Italy
Italian demand for immune support supplements remains strong, influenced by a greater health awareness and an aging population. The Ministry of Health sets specific national guidelines for dietary supplements, complementing EFSA regulations. Milan and Bologna are key centers for nutraceutical manufacturing and ingredient sourcing, focusing on Mediterranean-diet-aligned products.
Poland
Poland's growing disposable incomes and increasing health awareness fuel a rising demand for dietary supplements, particularly in the probiotic and vitamin categories. The Chief Sanitary Inspectorate (GIS) enforces food safety and supplement regulations. Warsaw and Krakow are experiencing investment in modern retail and online distribution channels, expanding market access.
Europe Dietary Supplements Market Key Industry Players
Capital-heavy producers compete with asset-light designers in the European dietary supplements market, creating a diversified competitive structure. Large pharmaceutical and food conglomerates leverage extensive R&D capabilities and established distribution networks. Smaller, specialized brands focus on niche formulations and agile direct-to-consumer marketing strategies. Strategic partnerships and portfolio diversification are common competitive moves among both established players and new entrants.
At the scale-driven end, Bayer AG exemplifies a pharmaceutical giant leveraging its scientific heritage for supplement development, often focusing on clinically supported products. Nestlé Health Science occupies a position in personalized nutrition and medical nutrition segments, utilizing its vast consumer health portfolio. Glanbia plc anchors the sports nutrition space, demonstrating control over key ingredient supply chains like whey protein, and serving a global athletic consumer base.
| Leading Market Players |
|---|
| Bayer AG |
| Haleon PLC |
| GlaxoSmithKline plc |
| Nestlé Health Science |
| Abbott Laboratories |
| Glanbia plc |
| Herbalife Nutrition Ltd |
| Perrigo Co Plc |
| Sanofi |
| Others |
Cost & Logistics Intelligence
The divergence between EFSA-approved, clinically-backed supplements and generic, unverified formulations creates distinct pricing tiers. This bifurcation impacts ingredient sourcing strategies and consumer willingness to pay across Europe.
Pricing Analysis
Bundled consultation services often accompany premium personalized nutrition platforms, contrasting with unbundled per-unit transactional pricing for mass-market vitamins. The dominant pricing structure is hybrid, combining per-unit sales with subscription models for customized offerings. Price differentiation stems from EFSA health claim validation and sustainable ingredient certification status. Pricing softness in generic vitamin segments stems from supermarket competition, while younger demographics are less price-sensitive for personalized solutions.
Supply Chain Analysis
Single-source vulnerability sits with specialized botanical extract suppliers for niche formulations. Geographic supply concentrates within Germany, Italy, and France for finished product manufacturing and specific ingredient sourcing. Raw material dependencies include whey protein, specialized probiotic strains, and botanical extracts, creating regulatory restriction risks from Novel Food approval timelines. Digital platforms and online direct-to-consumer models dominate downstream distribution across Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The European dietary supplements market presents a geographic-arbitrage play, leveraging lower production costs in Eastern Europe against premium pricing attainable in Western European markets due to stringent EFSA regulations.
For Market Incumbents: Extend R&D investments into clinically validated, personalized nutrition solutions to counter agile new entrant archetypes. Leverage established pharmacy distribution networks to reinforce consumer trust and professional endorsement. Invest in advanced supply chain traceability systems to meet stringent EU Green Deal mandates. This strategy defends against margin pressure from generic competition.
For New Entrants and Emerging Players: Capture white space in Eastern Europe, particularly Poland and the Czech Republic, where health awareness is rising. Target plant-based formulations and sustainable sourcing as a key go-to-market angle. Focus on direct-to-consumer models to build brand loyalty and bypass traditional distribution gatekeepers. Personalized nutrition platforms offer a penetrable segment for data-driven innovation.
For Investors and Strategic Acquirers: Consolidation pressure builds where regulatory burdens disproportionately impact small and medium-sized enterprises. The market offers long-term viability over a 5-10 year window, driven by demographic shifts and health consciousness. Acquisition targets include mid-sized firms with strong intellectual property in botanical extracts or personalized nutrition platforms. Increased EFSA approvals for novel ingredients will be a critical signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Product Portfolio Diversification | Broadens consumer appeal beyond traditional vitamins and minerals. |
| Direct-to-Consumer Channel Expansion | Enhances brand control and captures valuable consumer data directly. |
| Personalized Nutrition Platform Integration | Addresses demand for customized health solutions using biomarker data. |
| Sustainable Sourcing Certification | Meets EU Green Deal requirements and consumer preference for transparency. |
| Novel Food Approval Investment | Secures market access for innovative ingredients under strict EU regulations. |
Research Approach
Multiple input streams — primary interviews, secondary validation, and market intelligence — were reconciled to build this analysis. Primary research engaged R&D directors, regulatory affairs specialists, supply chain managers, and retail buyers across Europe. Secondary data included EFSA scientific opinions, national health ministry reports, customs data, and company annual reports. Bottom-up market sizing was triangulated with top-down industry estimations.
Data-stream reconciliation established baseline market sizing and growth rates across the analysis window. The analytical framework modeled segmentation dimensions including product type, application, end-user, distribution channel, and regional regulatory clusters. Compound annual growth rates were derived from historical trends and projected market dynamics. Key forecast inputs included demographic shifts towards an aging population and evolving consumer health awareness trends.
Unforeseen regulatory changes, economic downturns, and rapid shifts in consumer preferences are the dominant revision risks. Forecasts reflect assumptions documented in the full report, acknowledging these potential disruptions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
United States Vitamin D Supplements Market
Nutritional Supplements
Europe Meal Replacement Products Market
Nutritional Supplements
Camu Camu Extract Market
Nutritional Supplements
Olive Supplements Market
Nutritional Supplements
USA Prenatal Vitamin Supplements Market
Nutritional Supplements
Choline Market
Nutritional Supplements
Global Antioxidant Market
Nutritional Supplements
Global Hangover Rehydration Supplements Market
Nutritional Supplements
Elderberry Supplements Market
Nutritional Supplements
Whey Basic Protein Isolates Market
Nutritional Supplements
Ashwagandha Market
Nutritional Supplements
Marine Collagen Market
Nutritional Supplements
Europe Feed Prebiotics Market
Nutritional Supplements
Calcium HMB Market
Nutritional Supplements
Europe Collagen Supplements Market
Nutritional Supplements
Bypass Fat Supplement Market